
 Middle East and Africa Nurse Call Systems Market | 2026-2036
Middle East and Africa Nurse Call Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Nurse Call Systems Market Foresight
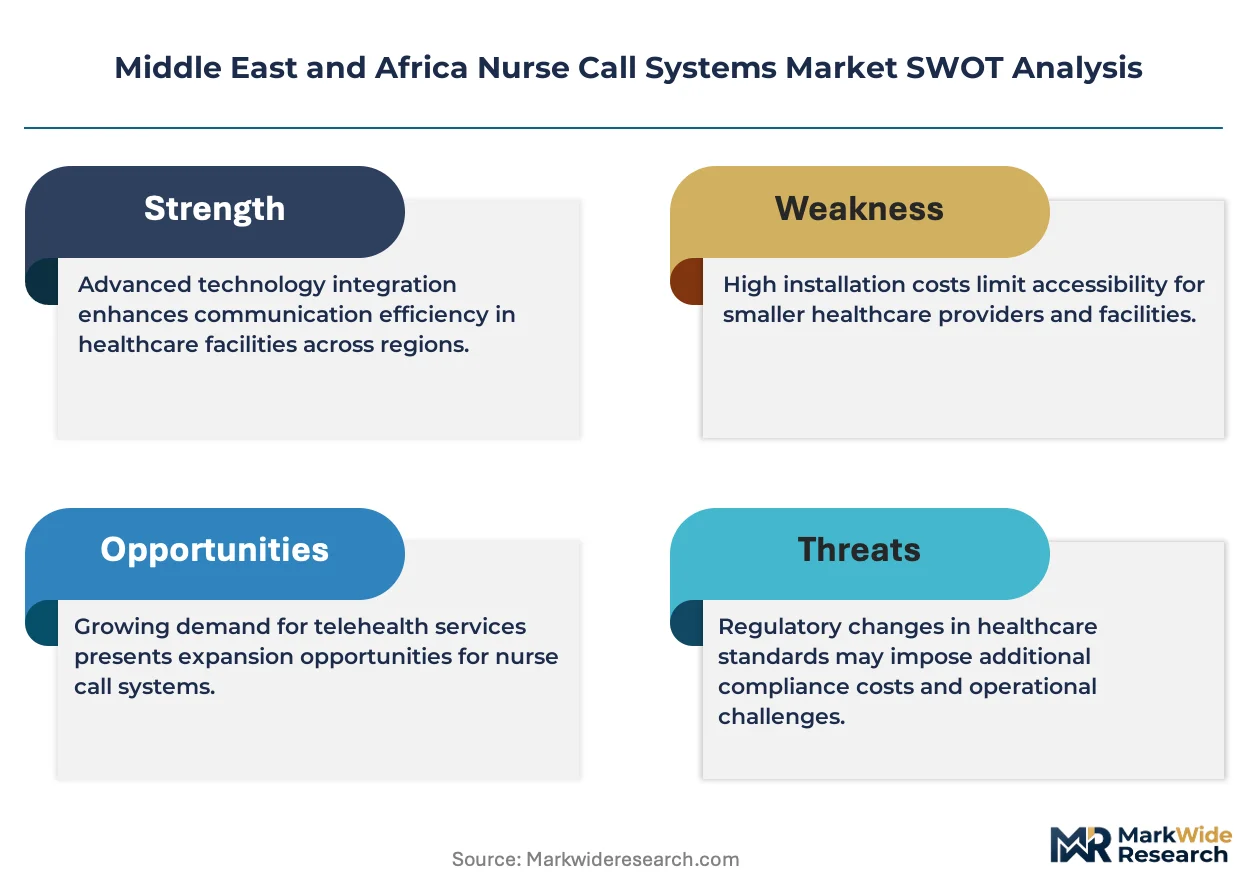
Acute care hospitals is decoupling from traditional wired installations across the Middle East and Africa, while residential care facilities and rehabilitation centers accelerate technology refresh cycles. Hill-Rom Holdings dominates premium integrated system deployments across Gulf state tertiary hospitals. Ascom Holding AG leverages its VoIP-native architecture to anchor retrofit opportunities in South Africa's public hospital network. TekTone Sound & Signal Mfg. competes on modular hardware configurations suited to phased construction timelines prevalent in Nigerian and Kenyan healthcare projects.
Nurse call systems comprise patient-initiated alarm terminals, corridor dome lights, nurse console displays, and back-end software platforms that route emergency alerts to assigned caregivers through wired or wireless communication protocols. These installations typically operate on 24-volt DC power loops with audio frequencies between 300 Hz and 3.4 kHz for clear voice transmission in clinical environments. Wireless systems lead new procurement in the Gulf Cooperation Council where hospital construction favors flexible infrastructure over fixed conduit runs. Integrated systems capture margin concentration by combining nurse call with real-time location and clinical workflow software. Retrofits represent the fastest-growing installation category across older facilities in Egypt and Morocco seeking compliance with updated patient safety standards without full infrastructure replacement.
Saudi Arabia's SFDA and the UAE's MOHAP enforce patient monitoring equipment standards that mandate traceable alarm response times and redundant communication pathways in licensed healthcare facilities. South Africa's national Department of Health has aligned public hospital procurement with IEC 60601 electromagnetic compatibility requirements for medical electrical systems. Egypt's healthcare regulator has introduced facility accreditation criteria that penalize outdated manual call bell systems. Stakeholders must monitor how Gulf state localization policies affect hardware sourcing requirements and whether East African hospital PPP frameworks specify nurse call technology in concession agreements.
Market Dynamics
Wireless infrastructure deployments are decoupling acute care hospitals from fixed conduit dependency across Gulf Cooperation Council states, while IP-native architectures compress installation timelines for greenfield construction.
Growth Catalysts
- SFDA patient monitoring mandates:Saudi Arabia's medical device regulator enforces traceable alarm response pathways in licensed facilities, compelling infrastructure upgrades.
- Greenfield hospital construction:Gulf state healthcare developments integrate nurse call platforms from architectural inception, eliminating retrofit friction.
- VoIP-native system adoption:Internet protocol architectures reduce cabling costs and enable software-defined workflow routing in tertiary facilities.
Market Restraints
- Electromagnetic compatibility certification:IEC 60601 compliance requirements extend procurement cycles for imported medical electrical systems into South Africa.
- Skilled installation labor scarcity:Certified low-voltage technicians concentrate in Gulf state urban centers, constraining rollout velocity in secondary Egyptian and Moroccan markets.
- Legacy copper infrastructure:Existing 24-volt DC power loops in older North African facilities create technical debt that delays full-platform replacements.
Strategic Opportunities
- Kenyan hospital PPP frameworks:Public-private partnership concession agreements in East Africa increasingly specify integrated clinical communication infrastructure as mandatory deliverables.
- Real-time location convergence:Nurse call platforms are integrating asset tracking and staff duress alerting, opening margin expansion in premium system configurations.
- Nigerian phased construction timelines:Modular hardware architectures align with staged healthcare facility buildouts, creating attach opportunities for expandable systems.
Industry Challenges
- Biomedical engineering talent pipeline:Facilities struggle to recruit technicians capable of maintaining IP-based platforms alongside legacy analog networks.
- Localization sourcing requirements:Gulf state domestic content policies complicate hardware procurement for multinational system vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Nurse Call Systems Market |
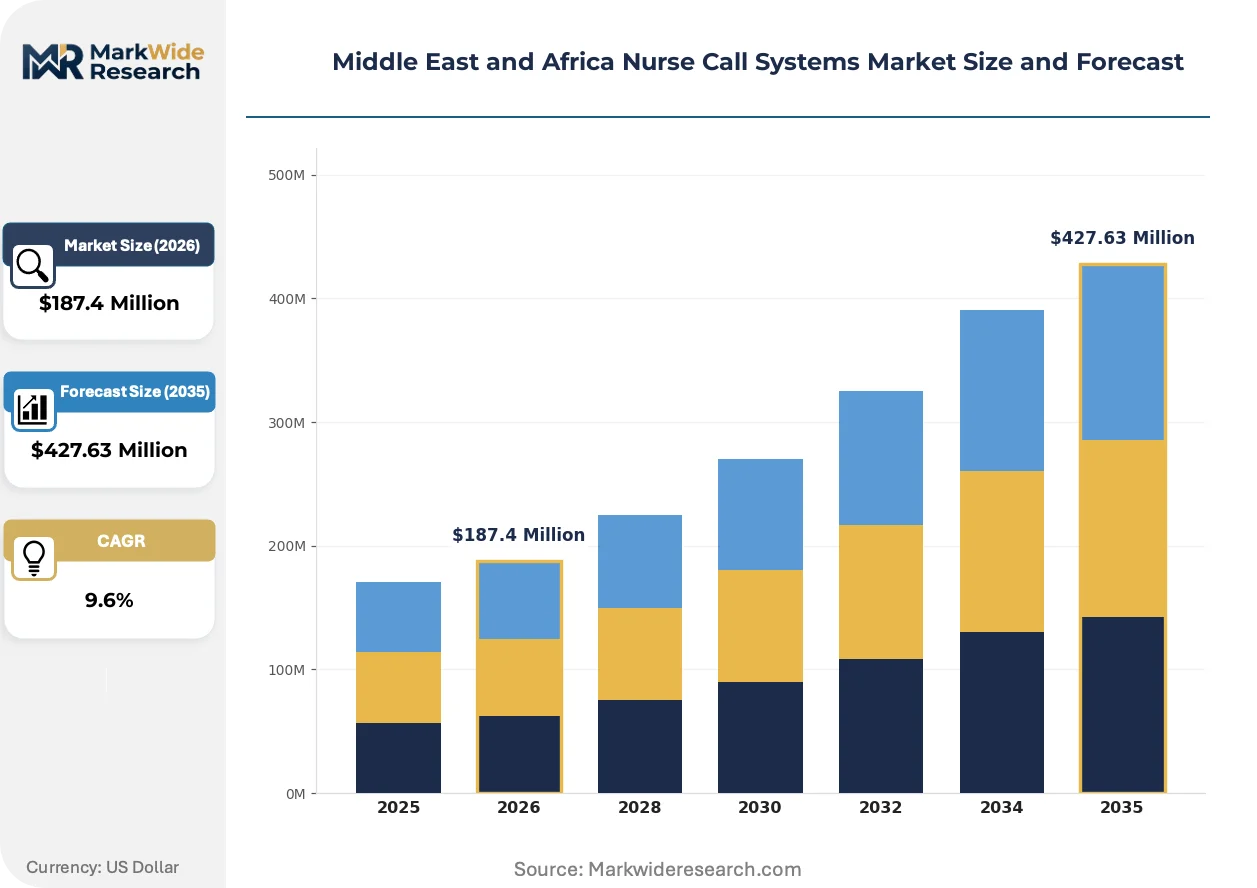
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Systems, Wired Systems, Integrated Systems, Standalone Systems End User: Hospitals, Residential Care Facilities, Assisted Living Facilities, Rehabilitation Centers Technology: Radio Frequency, Infrared, VoIP, Digital Messaging Installation Type: New Installations, Retrofits, Upgrades, Modular Systems |
| Companies Covered | Hill-Rom Holdings, Ascom Holding AG, Honeywell International, Rauland-Borg Corporation, STANLEY Healthcare, TekTone Sound & Signal Mfg., West-Com Nurse Call Systems, Critical Alert Systems, Cornell Communications, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Nurse Call Systems Market Shifts & Advancements
Clinical workflow software is embedding directly into communication infrastructure, compressing the boundary between alarm generation and care team orchestration. Three developments are restructuring competitive positioning.
Cloud-native nurse call management is integrating predictive analytics for alarm fatigue reduction. Saudi tertiary hospitals deploy these platforms to filter non-actionable alerts before they reach caregiver pagers. The technology is integrating clinical decision support layers that previously required separate software licenses.
MOHAP in the United Arab Emirates has mandated redundant communication pathways for patient monitoring equipment in licensed facilities. This regulatory pressure forces single-path analog installations toward dual-mode wired-wireless architectures. Acute care facilities in Dubai and Abu Dhabi accelerate procurement of fail-over capable systems to maintain licensure.
Service unbundling is fragmenting traditional procurement packages. South African public hospitals now separate hardware acquisition from multi-year maintenance contracts, enabling specialized regional integrators to compete against full-stack vendors. This pattern concentrates in provinces with constrained capital budgets seeking operational expenditure flexibility.
Middle East and Africa Nurse Call Systems Market Segmentation
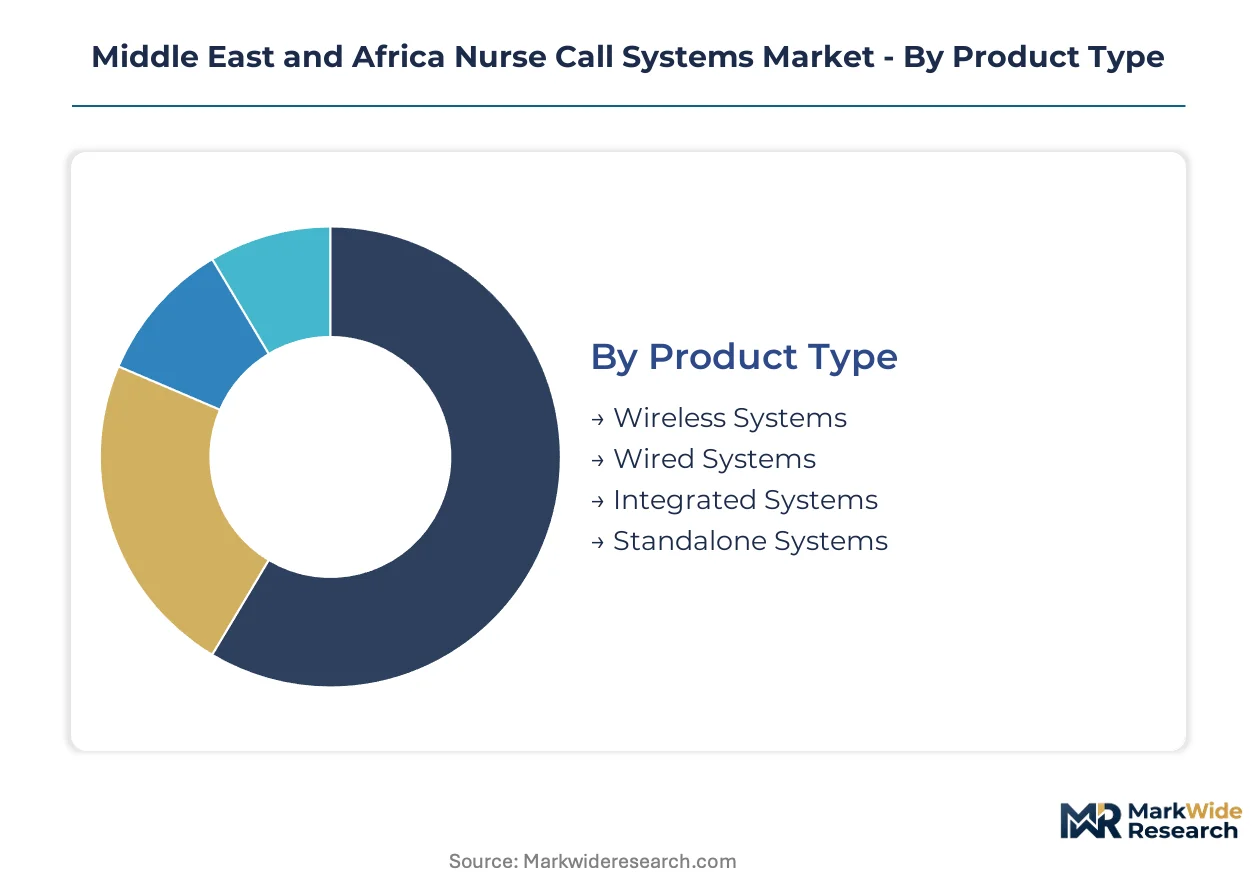
Nurse call system procurement in the Middle East and Africa fragments across infrastructure maturity levels and regulatory compliance tiers. Understanding where each segment sits on the integration spectrum reveals which configurations command premium pricing versus commodity positioning.
Product Type:
Integration depth separates standalone alarm terminals from platforms embedded with real-time location and clinical workflow layers.
- Wireless Systems:These configurations operate on 2.4 GHz or 5 GHz bands with battery-backed patient pendants and distributed access points. Demand concentrates in Saudi Arabian greenfield hospitals where MOHAP mandates redundant communication pathways and flexible infrastructure trumps fixed conduit costs. The technology eliminates 24-volt DC power loop dependency that constrains wired retrofits.
- Integrated Systems:Platforms combining nurse call with asset tracking, staff duress alerting, and clinical workflow software capture margin concentration in UAE tertiary facilities. Dubai's largest hospital operators specify these configurations from architectural inception to consolidate vendor relationships and reduce integration complexity.
- Wired Systems:Traditional 24-volt DC installations with hardwired patient stations and corridor dome lights persist in Egyptian and Moroccan facilities with legacy copper infrastructure.
- Standalone Systems:Basic patient-to-staff alerting without software integration dominates budget-constrained primary care clinics in Nigeria and Kenya.
Volume placements concentrate in wireless systems; the faster expansion belongs to integrated systems.
End User:
Acute care settings drive technology refresh cycles while long-term care facilities prioritize cost containment over feature depth.
- Hospitals:Tertiary acute care facilities across Gulf Cooperation Council states deploy IP-native architectures with predictive analytics for alarm fatigue reduction. Saudi SFDA patient monitoring mandates compel these institutions to maintain traceable alarm response pathways.
- Residential Care Facilities:Assisted living and nursing home operators in South Africa accelerate replacement of legacy manual call bells to meet tightened national health department patient safety standards.
- Assisted Living Facilities:Smaller-scale operators in Egypt and Morocco favor modular hardware configurations that permit phased capability expansion.
- Rehabilitation Centers:Post-acute facilities in Kenya's emerging hospital PPP frameworks specify integrated clinical communication infrastructure as mandatory concession deliverables.
Hospital procurement dominates absolute unit volume; rehabilitation centers are gaining share fastest as East African healthcare infrastructure expands.
Technology:
Protocol selection determines whether installations require dedicated cabling infrastructure or leverage existing network backbones.
- VoIP:Internet protocol architectures transmit voice and data over standard Ethernet infrastructure, compressing installation timelines in UAE greenfield construction. The technology enables software-defined workflow routing without proprietary hardware dependencies.
- Radio Frequency:RF-based systems using proprietary frequency bands penetrate walls and floors effectively in older South African public hospital buildings where structural constraints complicate wired retrofits.
- Infrared:Line-of-sight dependent protocols suit controlled environments like operating suites where precise location accuracy matters.
- Digital Messaging:Text-based alert routing to caregiver smartphones and pagers supplements voice communication in high-noise clinical environments.
Radio frequency retains installed base dominance; VoIP climbs the fastest as Gulf state hospital construction favors IP-native infrastructure.
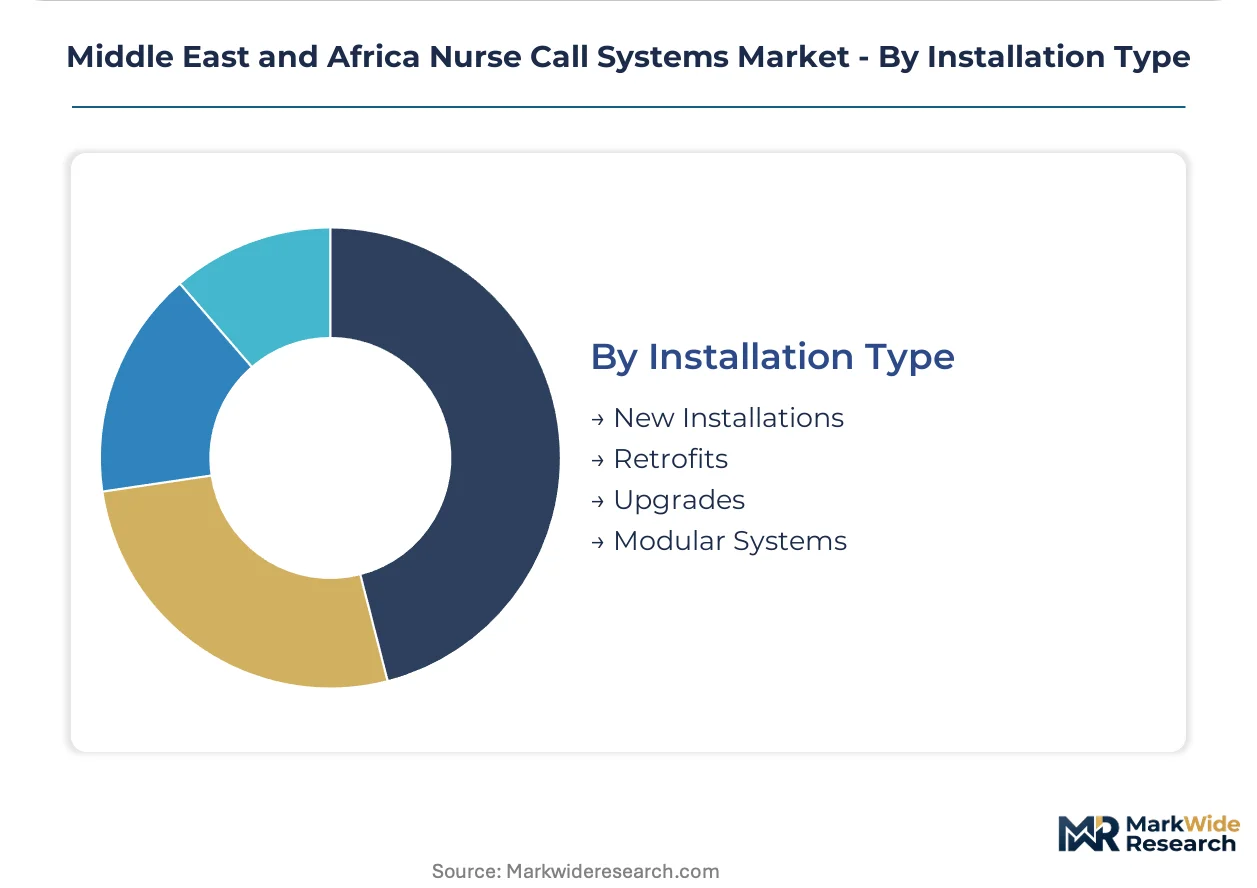
Installation Type:
Project economics bifurcate between capital-intensive new construction and operational expenditure models for existing facility upgrades.
- Retrofits:Replacement of legacy analog networks in older North African facilities represents the steepest expansion trajectory as Egypt's healthcare regulator penalizes outdated manual call bell systems through accreditation criteria.
- New Installations:Greenfield hospital construction across Gulf Cooperation Council states integrates nurse call platforms from project inception, eliminating the technical debt that constrains retrofit opportunities.
- Upgrades:Partial capability additions to existing systems allow South African public hospitals with constrained capital budgets to phase investments over multi-year cycles.
- Modular Systems:Expandable hardware architectures align with staged Nigerian healthcare facility buildouts, permitting capability growth without full platform replacement.
New installations capture the largest absolute project value; retrofits are expanding most quickly as regulatory compliance deadlines approach across North Africa.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City and Dubai Healthcare City anchor greenfield hospital construction across the Gulf, concentrating demand for IP-native nurse call infrastructure in purpose-built medical zones.
Saudi Arabia
SFDA patient monitoring mandates compel licensed facilities to maintain traceable alarm response pathways. The regulator enforces redundant communication standards that disqualify single-path analog installations. Riyadh's King Faisal Specialist Hospital and Research Centre deploys wireless infrastructure to eliminate fixed conduit dependency in new tower construction.
United Arab Emirates
MOHAP mandates dual-mode wired-wireless architectures for licensed patient monitoring equipment. Dubai Healthcare City operators specify integrated platforms from architectural inception to consolidate vendor relationships. Abu Dhabi's Cleveland Clinic Abu Dhabi anchors premium system deployments with real-time location convergence.
South Africa
The national Department of Health tightened patient safety standards compelling public hospital alarm network replacements. IEC 60601 electromagnetic compatibility requirements extend procurement cycles for imported medical electrical systems. Gauteng province's Charlotte Maxeke Johannesburg Academic Hospital accelerates VoIP-native retrofits to meet compliance deadlines.
Egypt
Healthcare regulator accreditation criteria now penalize outdated manual call bell systems. Cairo's tertiary facilities face technical debt from existing 24-volt DC copper infrastructure that delays full-platform replacements. New administrative capital hospital projects integrate modular hardware from construction phase one.
Nigeria
Phased construction timelines for emerging healthcare infrastructure create attach opportunities for expandable systems. Lagos state hospital public-private partnerships increasingly specify integrated clinical communication as mandatory deliverables. Modular hardware configurations align with staged facility buildouts in the Lekki Free Trade Zone medical cluster.
Middle East and Africa Nurse Call Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack vendors commanding premium integrated deployments while regional integrators capture retrofit service unbundling. The vendor base concentrates around three strategic archetypes: multinational healthcare technology conglomerates with integrated platform portfolios, European communication specialists with VoIP-native architectures, and modular hardware fabricators serving phased construction markets. Competitive moves center on strategic partnerships with hospital construction consortia and geographic expansion through localized maintenance networks.
Among multinational healthcare technology conglomerates, Hill-Rom Holdings exemplifies the premium integrated system archetype, while Ascom Holding AG represents VoIP-native specialists leveraging European engineering heritage. TekTone Sound & Signal Mfg. occupies a position within the modular hardware tier suited to expandable deployment timelines. These three anchors illustrate how competitive positioning fragments across infrastructure maturity levels and procurement flexibility requirements in Middle East and Africa healthcare markets.
| Leading Market Players |
|---|
| Hill-Rom Holdings |
| Ascom Holding AG |
| Honeywell International |
| Rauland-Borg Corporation |
| STANLEY Healthcare |
| TekTone Sound & Signal Mfg. |
| West-Com Nurse Call Systems |
| Critical Alert Systems |
| Cornell Communications |
| Others |
Supply & Pricing Matrix
IP-native VoIP architectures are displacing proprietary analog hardware across Gulf Cooperation Council hospital construction, simultaneously collapsing installation labor costs and concentrating procurement power with systems integrators capable of software-defined workflow routing. This technology shift feeds back into supply chain restructuring as vendors abandon component manufacturing for platform licensing models.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent greenfield deployments in Saudi Arabia from phased Nigerian construction timelines, with premium tiers commanding 40% markups for sub-90-day delivery windows. Three-tier pricing structure across premium integrated platforms, standard wireless configurations, and economy wired systems differentiates on IEC 60601 certification grade and after-sales service bundling. Pricing pressure stems from South African public hospitals unbundling hardware acquisition from maintenance contracts, squeezing full-stack vendor margins. Budget-constrained primary care clinics in Kenya exhibit highest price sensitivity; UAE tertiary facilities show least sensitivity given MOHAP-mandated redundancy requirements.
Supply Chain Analysis
Semiconductor component supply rests on Taiwanese foundries and South Korean memory producers for wireless access point chipsets and nurse console processors. Copper cabling for legacy 24-volt DC installations draws from Egyptian and Moroccan domestic wire manufacturers, while IP-native Ethernet infrastructure sources from Chinese and German networking equipment suppliers. Single-source vulnerability concentrates in radio frequency module production for patient pendants. Distribution runs through Gulf state hospital construction consortia and South African regional integrators serving public procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around full-stack platform vendors as SFDA and MOHAP regulatory mandates disqualify single-path analog specialists from licensed facility procurement. Compliance-driven obsolescence is forcing hardware-only manufacturers toward acquisition or exit.
For Market Incumbents: Extend software-defined workflow capabilities into predictive analytics layers to defend against cloud-native entrants targeting alarm fatigue reduction. Acquire certified low-voltage installation networks in secondary Egyptian and Moroccan markets to lock out regional integrators exploiting service unbundling. Anchor relationships with King Abdullah Economic City and Dubai Healthcare City construction consortia through multi-project framework agreements. For New Entrants and Emerging Players: Cloud-native alarm management platforms offer a technology-first wedge into Saudi tertiary hospital refresh cycles where incumbent legacy architectures create upgrade friction. Target South African public hospital VoIP retrofit opportunities where IEC 60601 compliance delays favor agile certification pathways. Pursue Nigerian phased construction timelines through modular hardware partnerships with regional integrators lacking expandable system expertise. For Investors and Strategic Acquirers: Re-rating potential sits with VoIP-native specialists given MOHAP redundant communication pathway mandates accelerating UAE procurement velocity. Long-term viability centers on platform vendors with recurring software revenue streams rather than transactional hardware sellers exposed to commodity input volatility. Watch Gulf state localization policy announcements as inflection indicators for hardware sourcing requirement shifts that could reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cleveland Clinic Abu Dhabi anchors integrated platform deployments consolidating vendor relationships across UAE tertiary networks. |
| Software Companion Development | Predictive analytics layers for alarm fatigue reduction embed clinical decision support previously requiring separate licensing. |
| CE Marking Pathway | IEC 60601 electromagnetic compatibility certification accelerates South African public hospital procurement cycles for European-engineered systems. |
| Strategic Partnership | Kenyan hospital PPP frameworks increasingly specify integrated clinical communication as mandatory concession deliverables. |
| Geographic Expansion | Localized maintenance networks in secondary Egyptian and Moroccan markets capture retrofit service unbundling opportunities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement committees, biomedical engineering directors, GPO contracts managers, and systems integration specialists. SFDA and MOHAP mandate documentation, IEC 60601 certification databases, and Gulf state hospital construction tender records provided demand-side validation. Bottom-up installation volume estimates triangulated against top-down healthcare infrastructure spending projections across the analysis window.
Data-stream reconciliation across product type, end user, technology protocol, and installation category dimensions generated segment-level forecasts throughout the projection horizon. CAGRs derived from regression analysis against hospital bed stock expansion, regulatory compliance deadline clustering, and wireless infrastructure penetration curves. Modeling incorporated greenfield construction pipeline tracking from King Abdullah Economic City and Dubai Healthcare City development authorities.
Several conditions sit outside the modeled scope, including currency fluctuation impacts on imported equipment costs and potential Gulf state domestic content threshold adjustments. Forecasts reflect assumptions around regulatory enforcement consistency and skilled technician availability trajectories. A small set of named triggers warrants ongoing watch: SFDA mandate expansion to residential care facilities, Nigerian PPP framework standardization, and East African hospital accreditation program adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
Healthcare AIDC Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Healthcare Ediscovery Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Prior Authorization Workflow Orchestration Market
Healthcare IT
Global Computerized Physician Order Entry (CPOE) Systems Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
Commercial Pharmaceutical Analytics Market