
 Disabled and Elderly Assistive Technologies Market | 2026-2036
Disabled and Elderly Assistive Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Disabled and Elderly Assistive Technologies Market Analysis
Home medical equipment distribution is rewriting how assistive devices reach end users, with direct-to-consumer platforms and institutional procurement channels gaining share against traditional retail. Sunrise Medical LLC leverages its European manufacturing footprint to sustain premium positioning in powered mobility. Invacare Corporation anchors North American supply through extensive dealer networks. Starkey Hearing Technologies differentiates via in-house semiconductor fabrication for custom hearing instruments.
Disabled and elderly assistive technologies encompass electromechanical and digital systems engineered to restore, augment, or substitute sensory, motor, or cognitive functions, with specifications spanning battery energy density in powered wheelchairs, signal-to-noise ratios in digital hearing aids, and torque thresholds in robotic exoskeletons. These systems serve primarily to extend independent living duration and reduce caregiver burden in aging populations. Mobility Aids and Hearing Devices command the largest installed bases, though Wearable Devices and Robotics represent the fastest-expanding technology segments where margin pools deepen through software-enabled recurring revenue. Smart Home Solutions penetration in institutional settings trails consumer adoption, creating a structural lag that Rehabilitation Centers and Hospitals are beginning to close through integrated platform contracts.
FDA premarket notification requirements for Class II medical devices shape product development timelines and clinical evidence standards in the United States, while the EU Medical Device Regulation imposes stricter post-market surveillance and unique device identification mandates across European markets. Japan's METI subsidizes elder-care robotics development under national productivity targets, directly influencing R&D allocation among manufacturers. Stakeholders must monitor convergence between software-as-a-service delivery models and traditional hardware reimbursement frameworks as payers recalibrate coverage criteria.
Market Dynamics
Home healthcare agencies are consolidating procurement authority into centralized purchasing platforms, compressing vendor margins while elevating software-integrated hardware specifications above standalone device performance.
Growth Catalysts
- Japan's METI Robotics Subsidies:National productivity targets channel public R&D funding toward elder-care automation, accelerating domestic manufacturer output and export competitiveness.
- FDA 510(k) Pathway Streamlining:Pre-market notification requirements for Class II AI-powered diagnostic wearables compress clinical evidence timelines and accelerate commercialization velocity.
- Smart Mobility Aid Procurement:Institutional buyers in post-acute care facilities specify connected wheelchairs with telemetric battery monitoring, creating pull-through demand for sensor-embedded hardware.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Battery energy density specifications for powered wheelchairs depend on cathode material flows concentrated in East Asian refining corridors, exposing manufacturers to input volatility.
- EU MDR Post-Market Surveillance:Stricter unique device identification mandates and clinical follow-up obligations extend compliance costs and documentation burdens across European distribution.
- Acoustic Amplification Substitution:Over-the-counter hearing aid categories in the United States erode prescription channel volumes for traditional audiologist-fitted instruments.
Strategic Opportunities
- Rehabilitation Center Platform Contracts:Integrated smart home solution deployments in institutional settings lag consumer adoption, creating whitespace for bundled hardware-software-service offerings.
- Software-as-a-Service Convergence:Recurring revenue attachment to wearable devices and robotic exoskeletons deepens margin pools beyond initial hardware transactions.
- German KBA Medical Device Certification:Federal Motor Transport Authority type-approval for street-legal powered mobility creates regulatory tailwind for premium European manufacturers.
Industry Challenges
- Biomechanical Engineer Talent Scarcity:Robotic exoskeleton development requires specialized expertise in torque threshold calibration and human-machine interface design that outpaces academic program output.
- Legacy Hospital IT Integration:Smart hearing instruments and diagnostic wearables face interoperability friction with entrenched electronic health record architectures, delaying enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disabled and Elderly Assistive Technologies Market |
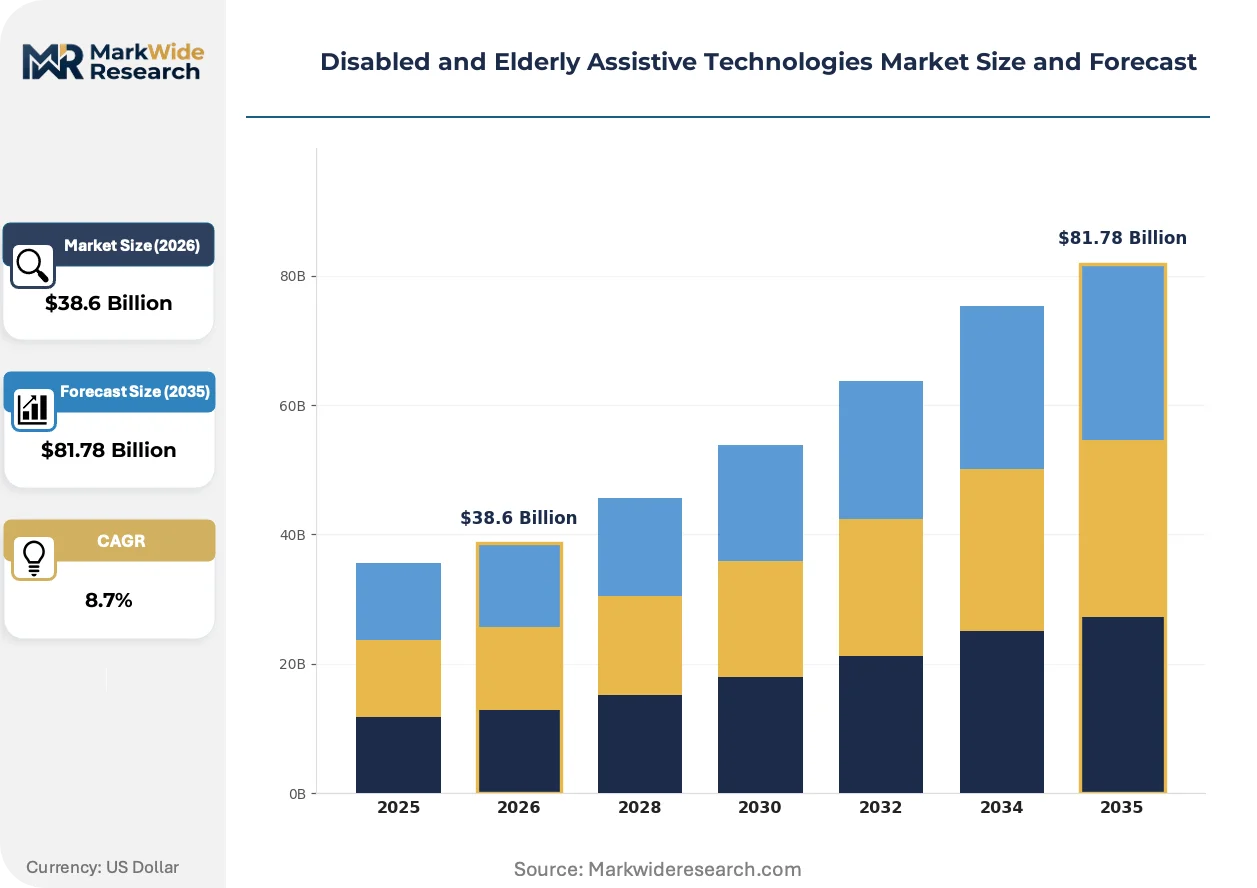
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobility Aids, Hearing Devices, Vision Aids, Daily Living Aids Technology: Smart Home Solutions, Wearable Devices, Robotics, Communication Aids End User: Individuals, Caregivers, Rehabilitation Centers, Hospitals Delivery Mode: Subscription Services, Direct Sales, Online Platforms, Retail Stores |
| Companies Covered | Sunrise Medical LLC, Invacare Corporation, Starkey Hearing Technologies, Sonova Holding AG, GN ReSound Group, Permobil AB, Drive Medical, Medline Industries, Inc., AI Squared, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disabled and Elderly Assistive Technologies Market Emerging Trajectories
Digital signal processing architectures and connected care platforms are compressing product lifecycles while elevating software capabilities to parity with hardware specifications in purchasing decisions.
Silicon-on-insulator fabrication processes for hearing instrument chipsets is migrating from discrete component assembly toward monolithic system-in-package designs. Major audiologist chains in North America and Western Europe now specify custom-programmable gain curves as standard. This migration from generic amplification toward personalized frequency response mapping compresses development timelines for mid-tier manufacturers.
The EU Medical Device Regulation's post-market clinical follow-up requirements impose systematic vigilance obligations on Class IIa and IIb assistive devices. Manufacturers must now maintain active surveillance registries for powered wheelchairs and implantable hearing systems. Rehabilitation centers in Germany and the Netherlands are responding by demanding extended warranty and remote diagnostic clauses in procurement contracts.
Institutional procurement committees are consolidating vendor relationships around integrated platform providers rather than discrete device specialists. Hospital systems and elder-care facility operators in Japan increasingly specify single-source contracts covering mobility aids, hearing devices, and environmental control systems. This concentration is most visible in metropolitan Tokyo and Osaka where METI-subsidized robotics integration mandates accelerate bundled purchasing decisions.
Disabled and Elderly Assistive Technologies Market Segmentation
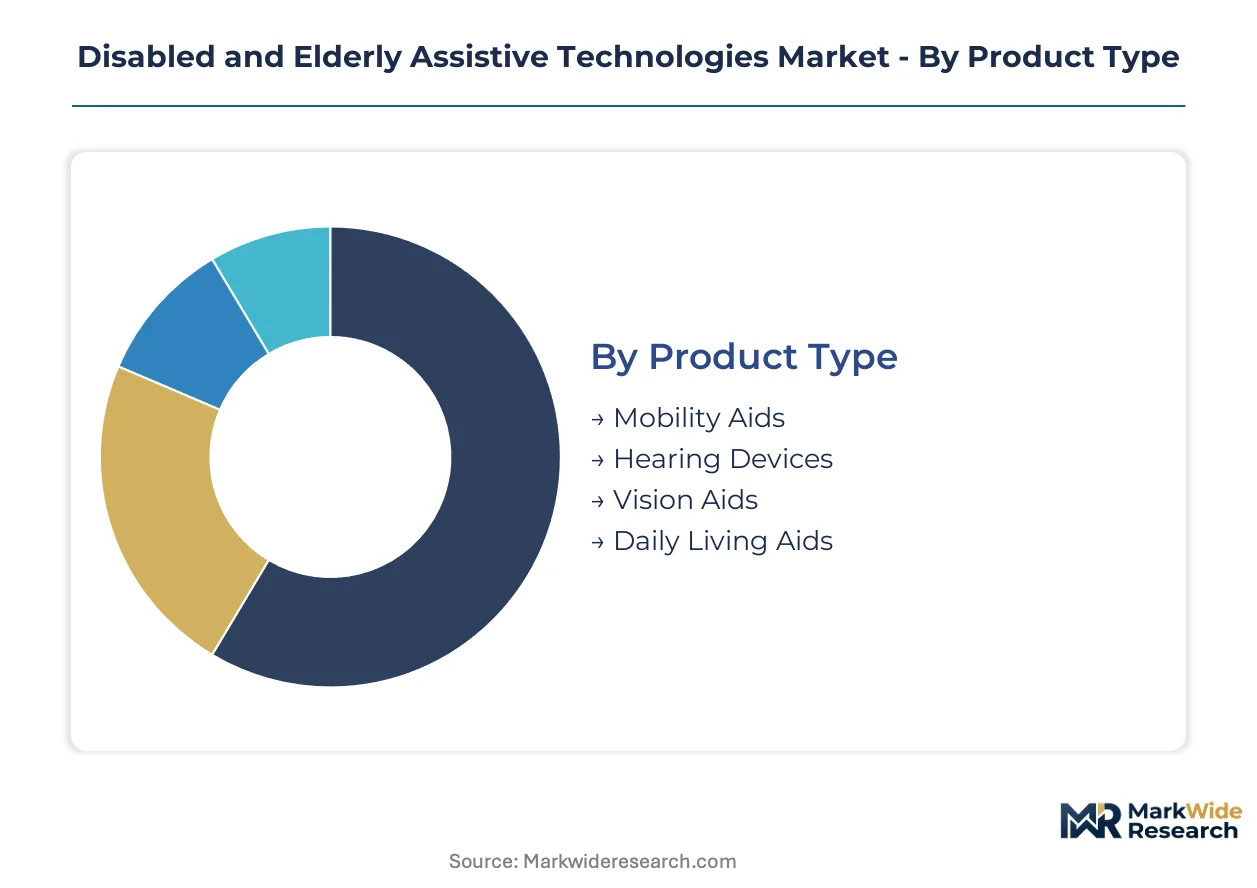
Segmentation reveals divergent service intensity across assistive technology categories. Powered mobility systems demand intensive calibration support, while disposable daily living aids operate on minimal touch models.
Product Type:
After-sales service intensity varies dramatically across product categories, with electromechanical systems requiring multi-year maintenance contracts and consumable segments relying on replacement cycles.
- Mobility Aids:Powered wheelchairs and scooters incorporate lithium-ion battery packs with telemetric monitoring systems. Rehabilitation centers in Japan specify predictive maintenance clauses under METI-subsidized robotics integration programs, elevating vendor service obligations.
- Hearing Devices:Digital signal processors with custom-programmable gain curves demand audiologist fitting and ongoing frequency adjustment. The United States over-the-counter category is compressing prescription channel service revenue, forcing traditional manufacturers toward remote programming platforms.
- Vision Aids:Screen magnifiers and electronic reading devices require periodic software updates.
- Daily Living Aids:Grab bars, reachers, and dressing aids generate minimal service attachment.
By volume, Daily Living Aids leads. By growth pace, Hearing Devices is ahead through software-enabled recurring revenue.
Technology:
Technology segments stratify by hardware-software integration depth, with robotics commanding premium pricing through torque calibration complexity and communication aids scaling through platform standardization.
- Robotics:Exoskeletons and elder-care automation systems integrate force-feedback sensors with real-time gait analysis. German KBA type-approval requirements for street-legal powered mobility create certification barriers that deepen incumbent advantage.
- Wearable Devices:Diagnostic biosensors and fall-detection pendants leverage AI-powered pattern recognition. FDA 510(k) pathway streamlining for Class II AI diagnostics is compressing evidence timelines, accelerating commercialization for algorithm-trained hardware.
- Smart Home Solutions:Environmental control systems and automated medication dispensers face legacy hospital IT integration friction.
- Communication Aids:Speech-generating devices and eye-tracking tablets standardize around platform architectures.
By installed base, Communication Aids dominates. By margin expansion, Robotics is climbing the fastest through human-machine interface specialization.
End User:
End-user segments diverge by procurement authority concentration, with institutional buyers consolidating vendor relationships around integrated platform contracts.
- Rehabilitation Centers:Post-acute facilities in Germany and the Netherlands demand bundled hardware-software-service offerings with extended warranty and remote diagnostic clauses under EU MDR post-market surveillance obligations.
- Hospitals:Acute care systems specify interoperability with electronic health record architectures, delaying enterprise sales cycles for smart hearing instruments and diagnostic wearables.
- Individuals:Direct consumers drive online platform adoption for over-the-counter categories.
- Caregivers:Family members and home health aides purchase through retail and subscription channels.
By procurement volume, Hospitals leads. By contract value growth, Rehabilitation Centers is gaining share fastest through integrated platform consolidation.
Delivery Mode:
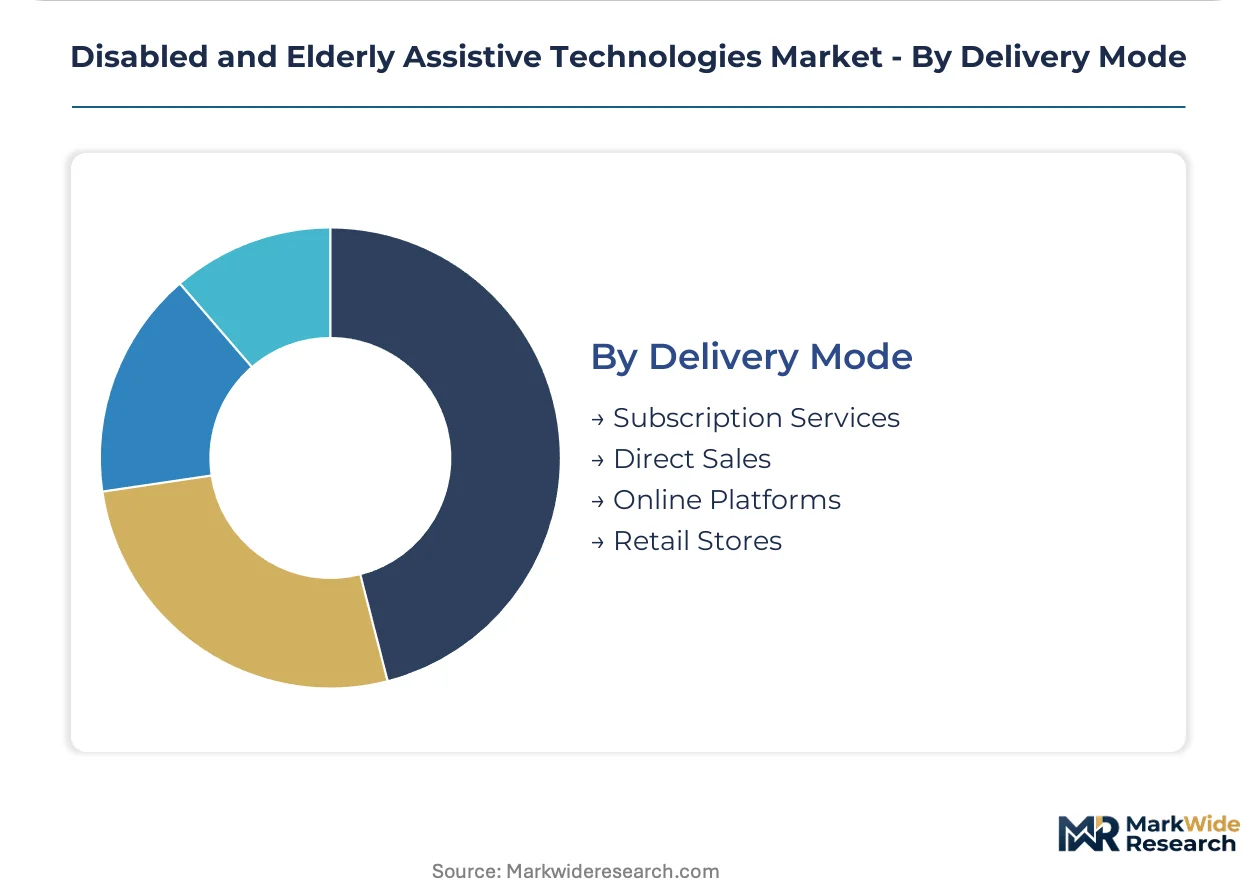
Delivery channels are restructuring around recurring revenue attachment, with subscription models deepening customer lifetime value beyond transactional hardware sales.
- Subscription Services:Software-as-a-service delivery for remote monitoring and predictive maintenance generates recurring revenue streams. Smart mobility aids with telemetric battery monitoring anchor institutional procurement specifications.
- Online Platforms:Direct-to-consumer channels capture over-the-counter hearing aid volume in the United States, eroding traditional audiologist-fitted prescription flows.
- Direct Sales:Manufacturer field forces serve high-acuity institutional accounts.
- Retail Stores:Pharmacy and medical supply outlets handle consumable and entry-level segments.
By transaction count, Retail Stores leads. By revenue per customer, Subscription Services is expanding most quickly through platform stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany and Switzerland where regulatory certification barriers protect margin structures, while volume manufacturing gravitates toward East Asian production corridors exposed to input cost volatility.
United States
Post-acute care facilities and home healthcare agencies drive institutional procurement of connected mobility systems. FDA 510(k) pathway streamlining for Class II AI-powered diagnostic wearables compresses evidence timelines and accelerates commercialization velocity. Minneapolis-St. Paul anchors hearing instrument manufacturing clusters where audiologist chains specify custom-programmable gain curves.
Germany
Rehabilitation centers in North Rhine-Westphalia and Bavaria demand bundled hardware-software-service offerings with extended warranty clauses. EU MDR post-market surveillance mandates impose systematic vigilance obligations on powered wheelchair and implantable hearing system manufacturers. Stuttgart's industrial corridor concentrates precision engineering capabilities for street-legal powered mobility under KBA type-approval frameworks.
Japan
METI subsidizes elder-care robotics development under national productivity targets, channeling public R&D funding toward domestic manufacturer output. PMDA regulatory frameworks govern software-enabled medical device approvals for diagnostic biosensors. Tokyo and Osaka metropolitan areas specify single-source platform contracts covering mobility aids, hearing devices, and environmental control systems.
Netherlands
Post-acute rehabilitation facilities in the Randstad region specify predictive maintenance clauses under integrated smart home solution deployments. EU MDR unique device identification mandates extend compliance documentation burdens across distribution networks. Eindhoven's high-tech systems cluster supports sensor-embedded hardware development for institutional procurement specifications.
China
Domestic demand for powered mobility systems expands through provincial healthcare procurement programs. NMPA regulatory pathways for Class II medical devices impose clinical evidence standards that shape product development timelines. Yangtze River Delta manufacturing corridors concentrate lithium-ion battery pack assembly for wheelchair telemetric monitoring systems.
Disabled and Elderly Assistive Technologies Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete sensors, semiconductors, and battery modules. The vendor base stratifies into three tiers: multinational conglomerates with diversified healthcare portfolios, mid-cap specialists focused on single therapeutic domains, and regional fabricators serving price-sensitive procurement channels. Two dominant competitive moves define current positioning: software-as-a-service revenue attachment deepening customer lifetime value, and integrated platform contracts consolidating vendor relationships in institutional settings.
Among European-based manufacturers, Sunrise Medical LLC and Permobil AB exemplify premium-tier positioning through regulatory certification depth and rehabilitation center channel access. Invacare Corporation anchors North American supply infrastructure through extensive dealer network coverage. Starkey Hearing Technologies occupies a distinctive position through in-house semiconductor fabrication capabilities for custom hearing instruments.
| Leading Market Players |
|---|
| Sunrise Medical LLC |
| Invacare Corporation |
| Starkey Hearing Technologies |
| Sonova Holding AG |
| GN ReSound Group |
| Permobil AB |
| Drive Medical |
| Medline Industries, Inc. |
| AI Squared |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cathode material concentration in East Asian refining corridors determines both the spread between premium powered mobility systems and economy-tier alternatives and the geographic shape of supplier networks serving wheelchair manufacturers. Battery energy density specifications tether pricing tiers to cathode chemistry grades while procurement committees in rehabilitation centers consolidate around vendors with captive cell supply.
Pricing Analysis
Configured-to-order pricing for powered wheelchairs with telemetric battery monitoring and predictive maintenance clauses commands substantial premiums over standard catalog configurations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA Class II certification depth, KBA type-approval status, and after-sales service bundling. Cost compression in economy-tier daily living aids intensifies because direct-to-consumer platforms erode retail markups. Home healthcare agencies exhibit highest price sensitivity through centralized purchasing platforms, while Japanese elder-care facilities under METI robotics integration mandates show lowest sensitivity due to subsidized procurement.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for powered mobility manufacturers dependent on lithium-ion cell assembly. Component sourcing draws from China for battery pack integration, South Korea for cathode materials, and Germany for precision drive systems. Raw material dependencies center on lithium carbonate, nickel sulfate, and rare-earth magnets for motor assemblies. Single-source vulnerability in semiconductor fabrication for hearing instrument chipsets concentrates among Taiwan-based foundries. Distribution runs through manufacturer field forces for institutional accounts, dealer networks for North American mobility aids, and direct-to-consumer platforms for over-the-counter categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through institutional procurement consolidation, with hospital systems and post-acute facilities in Japan, Germany, and the Netherlands reducing vendor panels from dozens to single-source platform contracts.
For Market Incumbents: Pre-empt margin erosion from centralized purchasing platforms by deepening software-as-a-service revenue attachment to hardware deployments. Secure backward integration into lithium-ion cell supply through long-term offtake agreements with South Korean cathode producers. Invest in FDA 510(k) pathway expertise to compress evidence timelines for AI-powered diagnostic wearables before emerging entrants accumulate clinical data assets. For New Entrants and Emerging Players: Rehabilitation centers in the Netherlands and Germany represent the most penetrable entry point, where EU MDR post-market surveillance obligations have incumbents struggling with compliance cost burdens. Mid-tier communication aids with platform-standardized architectures offer lower certification barriers than robotics or powered mobility segments. Pursue direct-to-consumer online channels for over-the-counter hearing aid categories in the United States, where prescription channel displacement creates whitespace for algorithm-trained hardware with remote programming capabilities. For Investors and Strategic Acquirers: FDA 510(k) pathway streamlining for Class II AI diagnostics reshapes the acquisition landscape toward algorithm-enabled hardware developers with compressed commercialization timelines. Long-term viability over the coming decade hinges on recurring revenue attachment rates exceeding hardware depreciation cycles. Target mid-cap specialists with integrated platform contracts in Japanese metropolitan markets. Monitor METI subsidy renewal announcements as the critical inflection signal for elder-care robotics allocation priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Remote programming platforms for hearing instruments capture recurring revenue from audiologist channel erosion. |
| Reimbursement Strategy | CMS Medicare coverage criteria for AI-powered diagnostic wearables determines commercialization velocity. |
| Hospital System Partnership | Integrated platform contracts with German rehabilitation centers lock in multi-year hardware-software-service bundles. |
| CE Marking Pathway | EU MDR unique device identification mandates create compliance barriers that deepen incumbent positioning. |
| Backward Integration | In-house semiconductor fabrication for custom hearing instrument chipsets protects margin from foundry concentration. |
Methodological Framework
Desk research of FDA 510(k) clearance databases, EU MDR vigilance registries, and METI robotics subsidy filings preceded structured interviews with biomedical engineers, rehabilitation center procurement directors, GPO contracts managers, and audiologist chain operators. Secondary validation drew from hospital procurement databases, CMS Medicare coverage determinations, and powered mobility dealer network disclosures. Bottom-up unit economics modeling triangulated against top-down spending flow analysis across institutional and consumer channels.
Fixed assumptions across the projection horizon include continued METI subsidy levels, stable FDA Class II evidentiary standards, and lithium-ion cell chemistry cost trajectories. Segmentation dimensions modeled encompass product type, technology integration depth, end-user procurement authority, and delivery mode subscription attachment. CAGRs were derived from installed base growth rates overlaid with average revenue per user expansion for software-enabled categories. Industry-specific inputs included rehabilitation center bed counts, hearing aid fitting volumes, and elder-care robotics deployment rates in subsidized Japanese facilities.
Practitioners should monitor lithium carbonate price volatility, FDA AI diagnostic guidance revisions, and METI productivity target recalibrations for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Heat Therapy Units Market
Medical Devices
US Stethoscope Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Below-The-Knee Implants Market
Medical Devices
Drug and Gene Delivery Devices Market
Medical Devices
North America Medical Device Regulatory Affairs Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Vaginal Specula Market
Medical Devices
Microneedling Cartridges Market
Medical Devices
Global Intraoral Cameras Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Prosthetic Liners Market