
 Light Therapy Market | 2026-2036
Light Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Light Therapy Market Analysis
Homecare buyers is rotating toward clinical-grade portable devices as post-pandemic self-treatment habits persist. Koninklijke Philips N.V. leverages its consumer health division to bridge prescription and over-the-counter channels. Beurer GmbH anchors the European home-use segment with CE-marked infrared lamps. Johnson & Johnson Services Inc. competes through professional wound-care protocols that integrate photobiomodulation.
Light therapy employs controlled wavelengths of visible and invisible light to stimulate cellular processes, with LED systems typically operating between 400 and 1000 nanometers to trigger photobiochemical responses. The technology serves dermatological, psychiatric, and musculoskeletal applications by modulating mitochondrial activity and circadian rhythms. LED product types dominate installed base economics due to lower heat generation and extended operational lifespans, though advanced laser systems command premium pricing in pain management. Homecare end users represent the fastest-expanding channel as direct-to-consumer portability improves, while hospital fixed systems remain a mature, replacement-driven segment with concentrated margin pools in service contracts.
The FDA regulates light therapy devices through 510(k) premarket notification and de novo classification pathways, with laser subclasses subject to additional radiation safety controls under 21 CFR 1040. The EU MDR and CE marking requirements under the Medical Devices Regulation reshape market access timelines for European distribution. Stakeholders must monitor evolving photobiomodulation dosage standards from ISO and IEC working groups as clinical evidence thresholds tighten for reimbursement eligibility.
Market Dynamics
The FDA's 510(k) clearance pathway compresses commercialization timelines for LED-based devices, while post-pandemic self-treatment habits permanently shift procurement toward clinical-grade portable systems for homecare channels.
Growth Catalysts
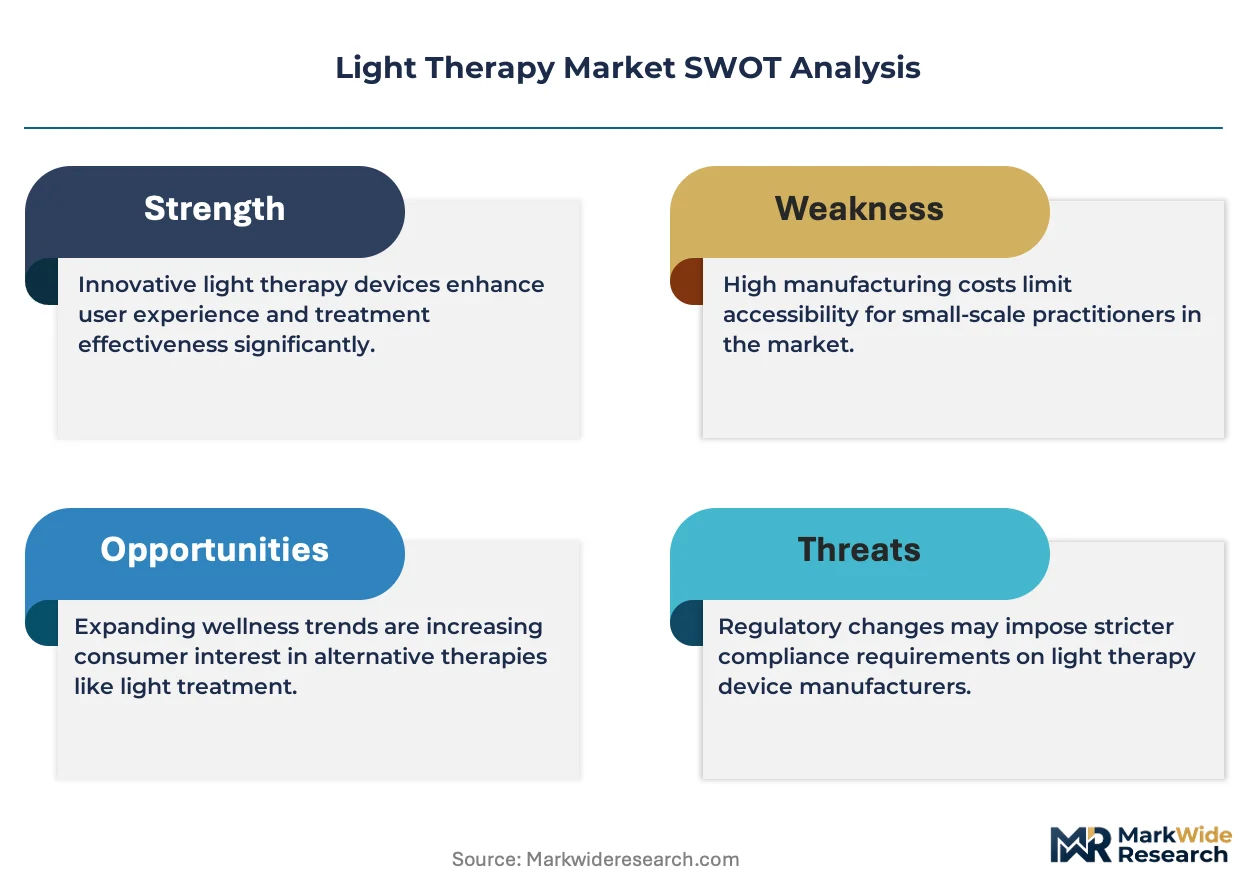
- Regulatory Streamlining:The FDA's de novo classification pathway accelerates market entry for novel photobiomodulation devices, reducing premarket notification review periods for LED systems below laser subclasses.
- Dermatology Protocol Expansion:US wellness centers are embedding infrared light systems into standardized treatment menus, creating pull-through demand for companion home-use devices.
- Photobiochemistry Validation:ISO and IEC working groups are formalizing dosage standards for mitochondrial stimulation applications, enabling clearer reimbursement pathways in wound-care protocols.
Market Restraints
- Input Cost Volatility:Precision LED chip fabrication depends on gallium nitride substrate supply concentrated in East Asian foundries, exposing device manufacturers to wafer pricing swings.
- Technical Ceiling:Heat dissipation limits constrain power density in portable form factors, capping therapeutic depth penetration versus fixed hospital installations.
- Substitution Pressure:Pharmacological circadian interventions and transcranial magnetic stimulation compete for psychiatric indication budgets, particularly seasonal affective disorder treatment allocations.
Strategic Opportunities
- Underpenetrated Musculoskeletal Segment:Germany's physiotherapy networks show low adoption of photobiomodulation for chronic pain versus dermatology, presenting white-space expansion potential.
- Technology Convergence:Integration of wearable biosensors with adaptive LED dosing algorithms enables real-time treatment personalization based on tissue oxygenation feedback.
- Channel Innovation:Direct-to-consumer subscription models for device-plus-consumable protocols bypass traditional durable medical equipment distribution, capturing lifetime value in sleep and skin verticals.
Industry Challenges
- Specialized Talent Scarcity:Photobiology expertise sits at the intersection of biomedical engineering and clinical dermatology, with limited training pipelines creating hiring bottlenecks for R&D functions.
- Certification Timeline Compression:EU MDR's tightened clinical evidence requirements for CE marking extend market access preparation by 12-18 months for novel wavelength protocols.
- Legacy System Integration:Hospital procurement of fixed light therapy systems requires compatibility with existing electronic health record workflows, complicating vendor switching decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Therapy Market |
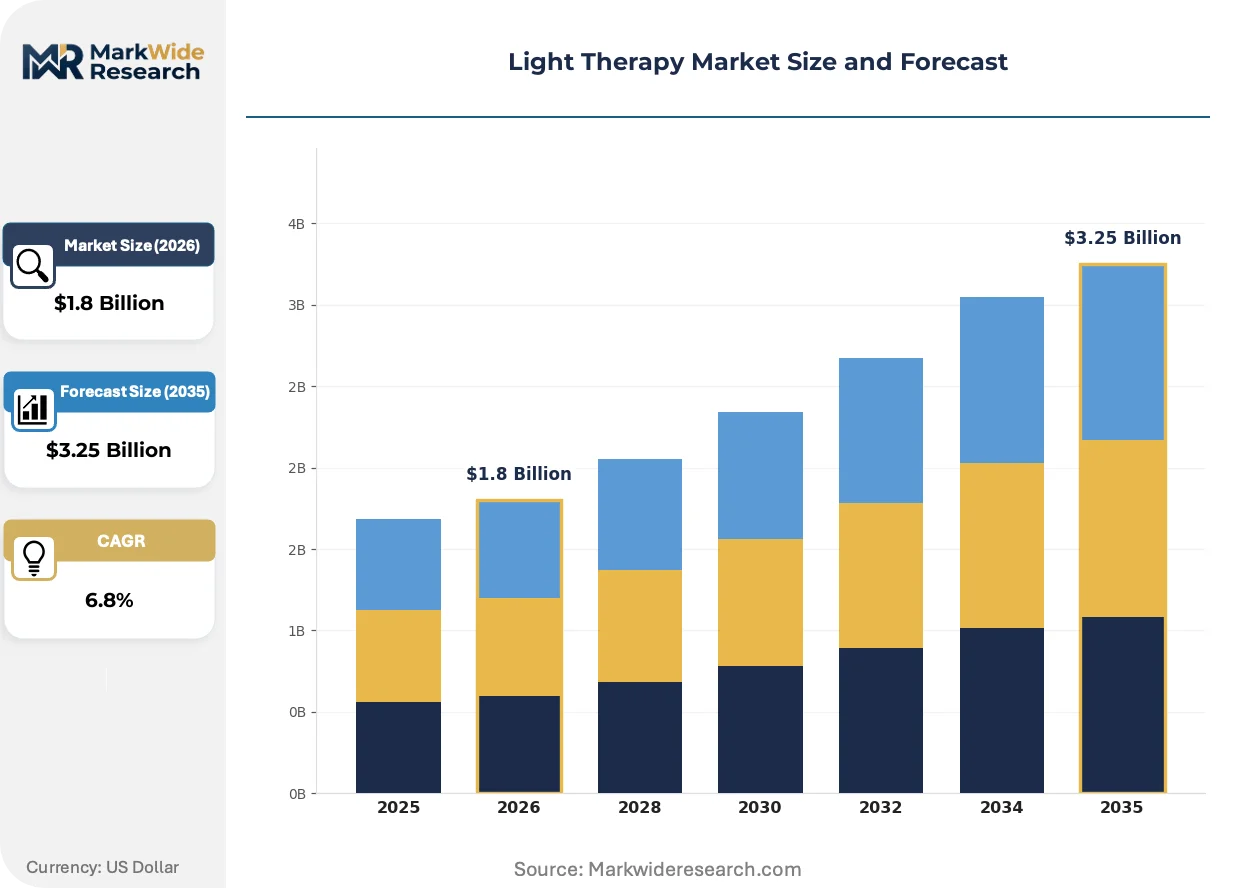
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser, Infrared, Ultraviolet Application: Chronic Pain Relief, Skin Rejuvenation, Mood Disorders, Wound Healing End User: Clinics, Homecare, Hospitals, Wellness Centers Technology: Portable Devices, Fixed Systems, Wearable Devices, Advanced Lasers |
| Companies Covered | Koninklijke Philips N.V., Beurer GmbH, Verilux Inc., Northern Light Technologies, BioPhotas, Zepter International, Lumie, Nature Bright, Johnson & Johnson Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Therapy Market Emerging Trajectories
Multi-wavelength LED arrays are displacing single-band systems as the default architecture, while regulatory frameworks on both sides of the Atlantic tighten evidence thresholds for reimbursement eligibility.
Multi-wavelength LED arrays combining red, near-infrared, and blue diodes in modular configurations are displacing fixed-spectrum devices across professional and home-use segments. Dermatology clinics in the United States are adopting these systems to address multiple indications from a single platform. The structural consequence is compressing equipment capital requirements per treatment room while extending device utilization rates across daytime and circadian applications.
The EU Medical Devices Regulation's expanded clinical evaluation requirements for active therapeutic devices are reshaping product development roadmaps for European market entry. Manufacturers must now generate post-market clinical follow-up data for CE-marked infrared lamps, extending validation timelines. Germany's notified bodies are applying the most stringent interpretations, creating a de facto regulatory filter that favors larger players with dedicated clinical affairs functions.
Direct-to-consumer buyers are consolidating purchase decisions around FDA-cleared devices with published photobiomodulation parameters, bypassing traditional physician gatekeeping for wellness applications. This certification-driven preference shift is restructuring channel economics, with e-commerce platforms capturing margin previously allocated to durable medical equipment distributors. The United States exhibits the most pronounced behavior change, where subscription bundling of devices with topical adjuncts is displacing standalone hardware sales.
Light Therapy Market Segmentation
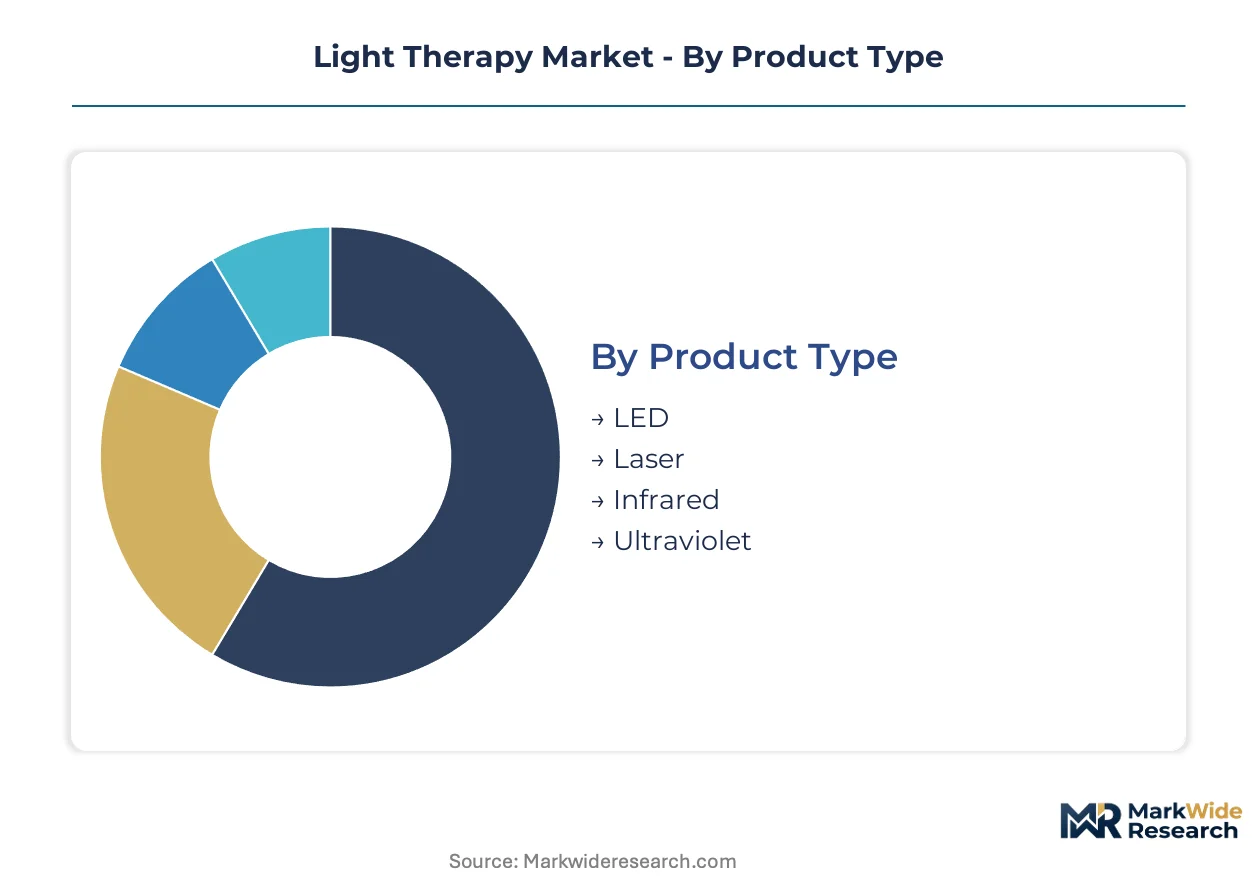
Light therapy market segmentation reveals divergent growth mechanics across hardware architectures and care settings. Understanding these fault lines enables targeted resource allocation for manufacturers navigating regulatory complexity and channel fragmentation.
Product Type:
LED systems anchor domestic production in the United States and Germany, while laser subclasses remain concentrated in Japanese and South Korean export-led supply chains.
- LED:Solid-state diodes operating between 400 and 1000 nanometers generate minimal heat and deliver extended operational lifespans. Demand concentrates in United States dermatology clinics seeking multi-wavelength platforms for standardized treatment menus, though gallium nitride substrate pricing volatility constrains margin expansion.
- Laser:Coherent light sources enable precise tissue targeting with superior penetration depth for pain management protocols. Japanese manufacturers dominate export supply for professional installations, with premium pricing sustained by clinical evidence requirements for reimbursement eligibility.
- Infrared:Thermal and non-thermal wavelengths stimulate mitochondrial activity in musculoskeletal applications. CE-marked systems from German producers anchor European homecare adoption.
- Ultraviolet:Narrowband UVB and UVA protocols address psoriasis and vitiligo under controlled clinical supervision. Deployment concentrates in hospital-based phototherapy units with strict radiation safety protocols.
LED commands the established base. The steepest expansion runs through infrared as wellness center adoption accelerates.
Application:
Cost tier stratification separates premium clinical protocols from accessible home-use solutions, with reimbursement eligibility determining effective pricing floors.
- Chronic Pain Relief:Photobiomodulation targets inflammatory cascades and nerve conduction in osteoarthritis and neuropathic conditions. German physiotherapy networks show underpenetration relative to dermatology, presenting white-space expansion potential.
- Skin Rejuvenation:Collagen stimulation and acne reduction drive the largest volume of professional treatments. United States wellness centers embed these systems into standardized menus, creating pull-through demand for companion home-use devices.
- Mood Disorders:Circadian rhythm modulation addresses seasonal affective disorder and sleep disruption. Pharmacological interventions and transcranial magnetic stimulation compete for psychiatric indication budgets.
- Wound Healing:Photobiomodulation accelerates tissue repair in diabetic ulcers and surgical sites. Johnson & Johnson Services Inc. competes through professional protocols integrating light therapy with advanced dressings.
Skin rejuvenation commands the established base. The steepest expansion runs through wound healing as ISO dosage standards formalize.
End User:
Customer type determines channel economics, with direct-to-consumer portability reshaping procurement patterns away from traditional durable medical equipment distribution.
- Clinics:Dermatology and physiotherapy practices require modular platforms supporting multiple indications per treatment room. Capital efficiency pressures favor multi-wavelength LED arrays over single-purpose installations.
- Homecare:Post-pandemic self-treatment habits persist, with buyers consolidating around FDA-cleared devices with published photobiomodulation parameters. Koninklijke Philips N.V. bridges prescription and over-the-counter channels through its consumer health division.
- Hospitals:Fixed systems for wound care and neonatal jaundice represent mature replacement demand. Procurement requires compatibility with existing electronic health record workflows, complicating vendor switching.
- Wellness Centers:United States facilities outpace other developed markets in infrared system adoption. Subscription bundling of devices with topical adjuncts displaces standalone hardware sales.
Hospitals command the established base. The steepest expansion runs through homecare as clinical-grade portability improves.
Technology:
Supply concentration in East Asian foundries for precision components shapes competitive dynamics across portable and fixed system architectures.
- Portable Devices:Battery-powered units with adaptive dosing algorithms enable treatment personalization. Heat dissipation limits constrain power density versus fixed installations.
- Fixed Systems:Hospital-grade installations deliver maximum therapeutic depth through controlled power delivery. Replacement cycles extend 7-10 years with concentrated margin pools in service contracts.
- Wearable Devices:Biosensor integration enables real-time tissue oxygenation feedback for adaptive dosing. Form factor miniaturization competes with battery life and LED array density.
- Advanced Lasers:Solid-state and fiber-coupled systems command premium pricing in interventional pain management. FDA 510(k) clearance pathways compress commercialization timelines relative to drug development.
Fixed systems command the established base. The steepest expansion runs through wearable devices as biosensor convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision LED chip fabrication concentrates in East Asian foundries, while device assembly and clinical protocol development distribute across North American and European innovation clusters. This geographic split shapes competitive access to substrate supply and regulatory clearance pathways.
United States
FDA 510(k) premarket notifications compress commercialization timelines for LED-based devices below laser subclasses. Wellness centers in California and New York Metro embed infrared systems into standardized treatment menus, creating pull-through demand for companion home-use devices. The FDA's de novo classification pathway accelerates market entry for novel photobiomodulation protocols.
Germany
Physiotherapy networks show underpenetration of photobiomodulation for chronic pain versus dermatology, presenting white-space expansion potential. EU MDR's tightened clinical evidence requirements extend CE marking preparation by 12-18 months for novel wavelength protocols. Bavaria's notified bodies apply the most stringent interpretations, creating a regulatory filter favoring larger players with dedicated clinical affairs functions.
Japan
METI standards and PMDA oversight govern laser subclass radiation safety for professional pain management installations. Japanese manufacturers dominate export supply chains for coherent light sources used in hospital-grade systems. Osaka-based production clusters sustain premium pricing through clinical evidence requirements for reimbursement eligibility.
China
NMPA medical device registration and GB standards govern domestic market access for active therapeutic devices. Yangtze River Delta foundries concentrate gallium nitride substrate supply for precision LED chip fabrication, exposing device manufacturers to wafer pricing volatility. Shanghai and Shenzhen clusters drive volume production for portable form factors.
United Kingdom
MHRA recognition of CE marking post-Brexit maintains alignment with EU MDR evidence thresholds for infrared lamp distribution. London and Southeast England wellness centers adopt multi-wavelength LED arrays for daytime and circadian applications. The country's physiotherapy networks lag German adoption rates for musculoskeletal photobiomodulation.
Light Therapy Market Vendor Landscape
Concentration sits with diversified health technology conglomerates and specialized phototherapy device manufacturers. The vendor base stratifies across three tiers: prescription-grade clinical systems, over-the-counter wellness devices, and professional wound-care protocols. Strategic archetypes include consumer health divisions bridging pharmacy and direct-to-consumer channels, European home-use specialists with CE-marked infrared portfolios, and professional medical device integrators. Dominant competitive moves encompass M&A to capture photobiology expertise and geographic expansion to bypass concentrated substrate supply.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and Johnson & Johnson Services Inc. exemplify archetypes spanning prescription and over-the-counter channels. Beurer GmbH occupies a position within the European home-use segment. These three anchors represent distinct strategic postures: consumer health bridge-building, professional protocol integration, and regional CE-marked specialization.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Beurer GmbH |
| Verilux Inc. |
| Northern Light Technologies |
| BioPhotas |
| Zepter International |
| Lumie |
| Nature Bright |
| Johnson & Johnson Services Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day gallium nitride wafer lead times concentrate pricing power with East Asian foundry operators, while FDA 510(k) clearance costs anchor premium tiers for clinical-grade devices. This temporal mismatch between substrate procurement and regulatory validation creates margin compression for mid-tier manufacturers lacking captive supply or dedicated clinical affairs functions.
Pricing Analysis
FDA 510(k) and CE marking under EU MDR dictate the pricing tier structure across the light therapy market. Three-tier pricing separates prescription-grade clinical systems from over-the-counter wellness devices and economy home-use lamps, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in the mid-tier is intensifying because gallium nitride substrate volatility erodes manufacturing margins. Homecare buyers exhibit highest price sensitivity, while hospital procurement committees prioritize interoperability over unit cost.
Supply Chain Analysis
China and Taiwan anchor precision LED chip fabrication, with South Korea and Japan supplying coherent laser sources for professional pain management installations. Device assembly draws from gallium nitride substrates, optical-grade polymers, and biosensor components. Single-source vulnerability concentrates in Yangtze River Delta foundries exposed to wafer pricing swings. Distribution runs through durable medical equipment distributors for clinical channels, while direct-to-consumer e-commerce platforms capture wellness segment margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-wavelength platform interoperability is reshaping competitive positioning around ecosystem lock-in, as dermatology clinics demand modular systems supporting daytime and circadian applications from single hardware investments.
For Market Incumbents: Fortify position through backward integration into gallium nitride substrate sourcing and dedicated clinical affairs capacity for EU MDR navigation. Philips and Johnson & Johnson Services Inc. face substitution pressure from pharmacological circadian interventions and transcranial magnetic stimulation in psychiatric indications. Priority levers include CE-marking preparation acceleration and hospital EHR workflow integration investments. For New Entrants and Emerging Players: Post-market clinical follow-up data services represent a service-layer gap where incumbents under-serve smaller manufacturers facing EU MDR compliance burdens. Germany's physiotherapy networks offer the most penetrable geography for musculoskeletal photobiomodulation expansion. Direct-to-consumer subscription bundling of devices with topical adjuncts provides the strongest go-to-market angle for wellness vertical entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified health technology conglomerates seeking to divest non-core phototherapy divisions. Long-term viability favors platforms with adaptive dosing algorithm IP and biosensor integration capabilities. The signal to watch is ISO photobiomodulation dosage standard formalization enabling clearer reimbursement pathways.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses commercialization timelines for novel LED-based photobiomodulation protocols versus laser subclasses. |
| CE Marking Pathway Investment | Extends market access preparation for EU MDR compliance, favoring players with dedicated clinical affairs functions. |
| Hospital System Partnership | Secures EHR workflow integration requirements that complicate vendor switching in fixed system procurement. |
| Software Companion Development | Enables real-time treatment personalization through wearable biosensor integration with adaptive LED dosing algorithms. |
| Reimbursement Strategy | Aligns photobiomodulation protocols with ISO dosage standards for wound-care and musculoskeletal indication coverage. |
Methodological Framework
The analysis maps LED, laser, infrared, and ultraviolet product architectures, each validated through biomedical engineers, dermatology clinic procurement managers, GPO contracts specialists, and wellness center operators. Primary interviews with device manufacturers and clinical protocol developers combined with secondary validation against FDA 510(k) filings, EU MDR notified body guidance, ISO working group documentation, and hospital procurement database extracts. Bottom-up installed base modeling and top-down expenditure flow analysis provided triangulation checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, application indication, end-user channel, and technology form factor, with CAGRs derived from slope analysis of historical trajectory and forward scenario weighting. Forecast inputs incorporated photobiomodulation dosage standard evolution, gallium nitride substrate pricing volatility assumptions, and regulatory clearance timeline distributions.
Underlying assumptions cover reimbursement pathway expansion, substrate supply stability, and clinical evidence accumulation rates, with deviation risk concentrated in EU MDR interpretation variance across notified bodies and pharmacological substitution acceleration in psychiatric indications. Recalibration cycles align with material shifts in ISO standard publication, FDA de novo classification precedent, and major foundry capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Dermatoscope Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Global Bone Cement Market
Medical Devices
Global Wearable Skin Patch Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Pulse Lavage Market
Medical Devices
External Defibrillator Market
Medical Devices
Australia General Surgical Devices Market
Medical Devices
Argentina Ultrasound Devices Market