
 Global Biopsy Needles Market | 2026-2036
Global Biopsy Needles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biopsy Needles Market Foresight
Single-use sterile specification tiers is unwinding legacy reusable needle conventions across interventional radiology departments. Medtronic plc leverages its integrated surgical navigation platforms to bundle biopsy systems with imaging workflows. Becton Dickinson anchors North American hospital supply contracts through high-volume automated manufacturing. Hologic Inc specializes in vacuum-assisted breast biopsy technologies, occupying a defensible position in women's health diagnostics.
Biopsy needles are hollow, beveled-tip instruments manufactured from surgical-grade stainless steel or nitinol alloys, designed to extract tissue specimens from solid organs or lesions under image guidance for histopathological analysis. Core needle systems penetrate tissue with coaxial cutting mechanisms to preserve architectural integrity, while vacuum-assisted devices apply continuous suction to capture larger contiguous samples during single insertions. The product type dimension shows vacuum-assisted and core needle formats commanding premium placement in oncology diagnostics, with fine needle aspiration sustaining cost-sensitive ambulatory settings. Application concentration pools within oncology diagnostics, where pulmonology and gastroenterology represent adjacent expansion corridors for minimally invasive tissue acquisition.
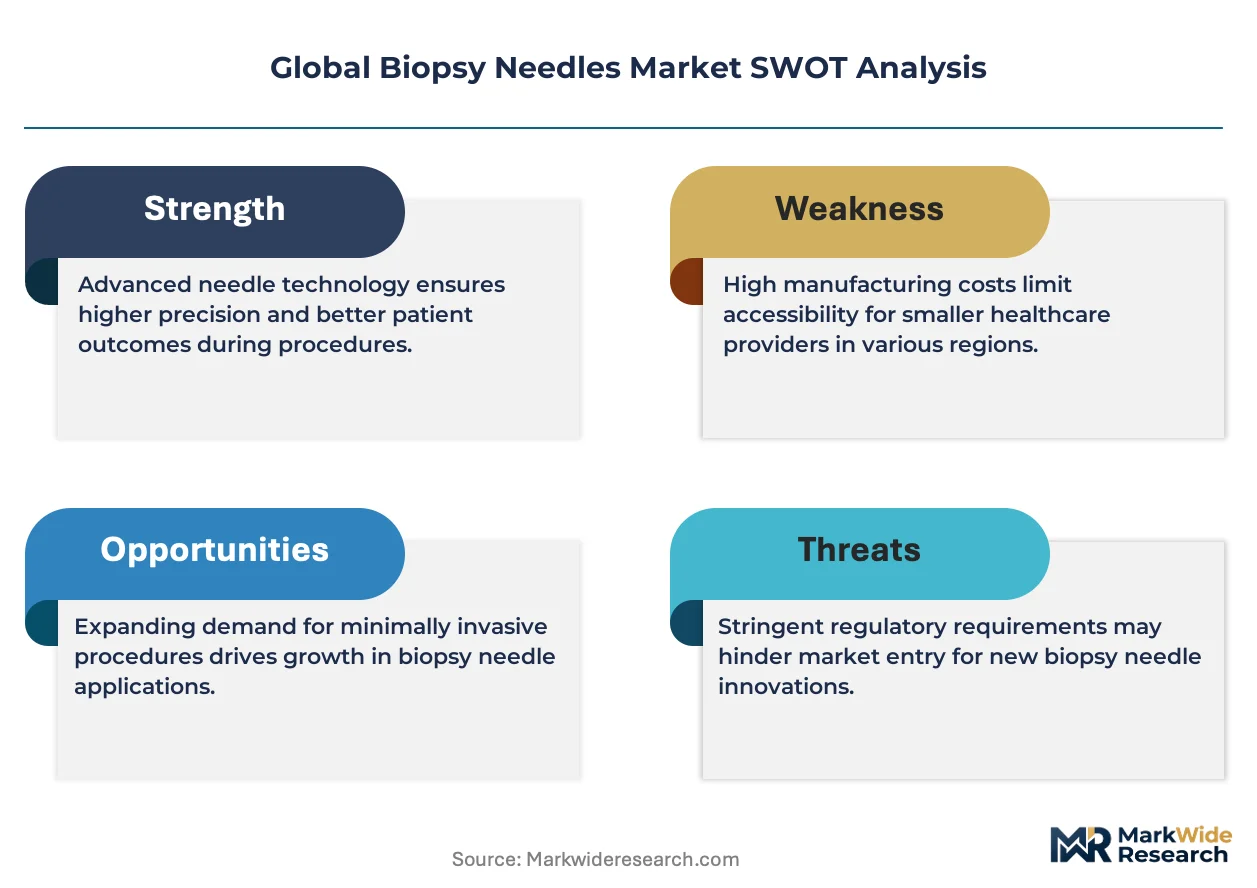
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product entry timelines and clinical evidence requirements for biopsy needle manufacturers. ISO 13485 quality management systems and sterilization validation standards govern production consistency across international supply chains. EMA post-market surveillance obligations under MDR Article 83 compel sustained vigilance on device performance reporting. Stakeholders must weigh regulatory capital intensity against the pull from ambulatory surgical centers seeking same-day biopsy capabilities.
Market Dynamics
The migration from reusable to single-use sterile biopsy needles is compressing capital equipment cycles and forcing manufacturers to reconfigure sterile packaging capacity at scale.
Growth Catalysts
- Rising cancer screening protocols:National screening programs in Germany and Japan are expanding percutaneous biopsy volumes in pulmonology and gastroenterology departments.
- EU MDR Article 83 surveillance:Enhanced post-market reporting obligations are accelerating device performance transparency and building clinical evidence repositories.
- Vacuum-assisted platform adoption:Continuous suction technology is capturing larger contiguous tissue samples, reducing repeat insertion rates in breast and prostate diagnostics.
Market Restraints
- Nitinol alloy supply concentration:Shape-memory wire production clusters in China's Zhejiang province create input vulnerability for Western manufacturers.
- FDA 510(k) documentation burdens:Premarket notification requirements for predicate device comparisons are extending clearance timelines by 8-14 months for novel tip geometries.
- Reusable needle residual demand:Cost-constrained ambulatory centers in Eastern Europe and Latin America continue sterilization cycles, limiting single-use penetration.
Strategic Opportunities
- India's oncology infrastructure buildout:Government-funded cancer hospital networks in Maharashtra and Tamil Nadu are procuring vacuum-assisted systems for tier-2 city deployment.
- Robotic navigation convergence:Integration of electromagnetic tracking with CT-guided biopsy platforms is enabling sub-centimeter lesion targeting in interventional radiology.
- Same-day ambulatory capacity:Outpatient surgical centers in Texas and Florida are unbundling biopsy services from hospital admission workflows.
Industry Challenges
- Interventional radiologist training pipelines:Fellowship programs in percutaneous tissue acquisition are not scaling with procedure volume growth in North American hospital systems.
- ISO 13485 sterilization validation:Ethylene oxide residual testing protocols are creating batch-release bottlenecks for manufacturers expanding sterile packaging lines.
- Legacy PACS integration friction:Biopsy navigation software requires custom HL7 interfacing with decade-old hospital imaging archives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biopsy Needles Market |
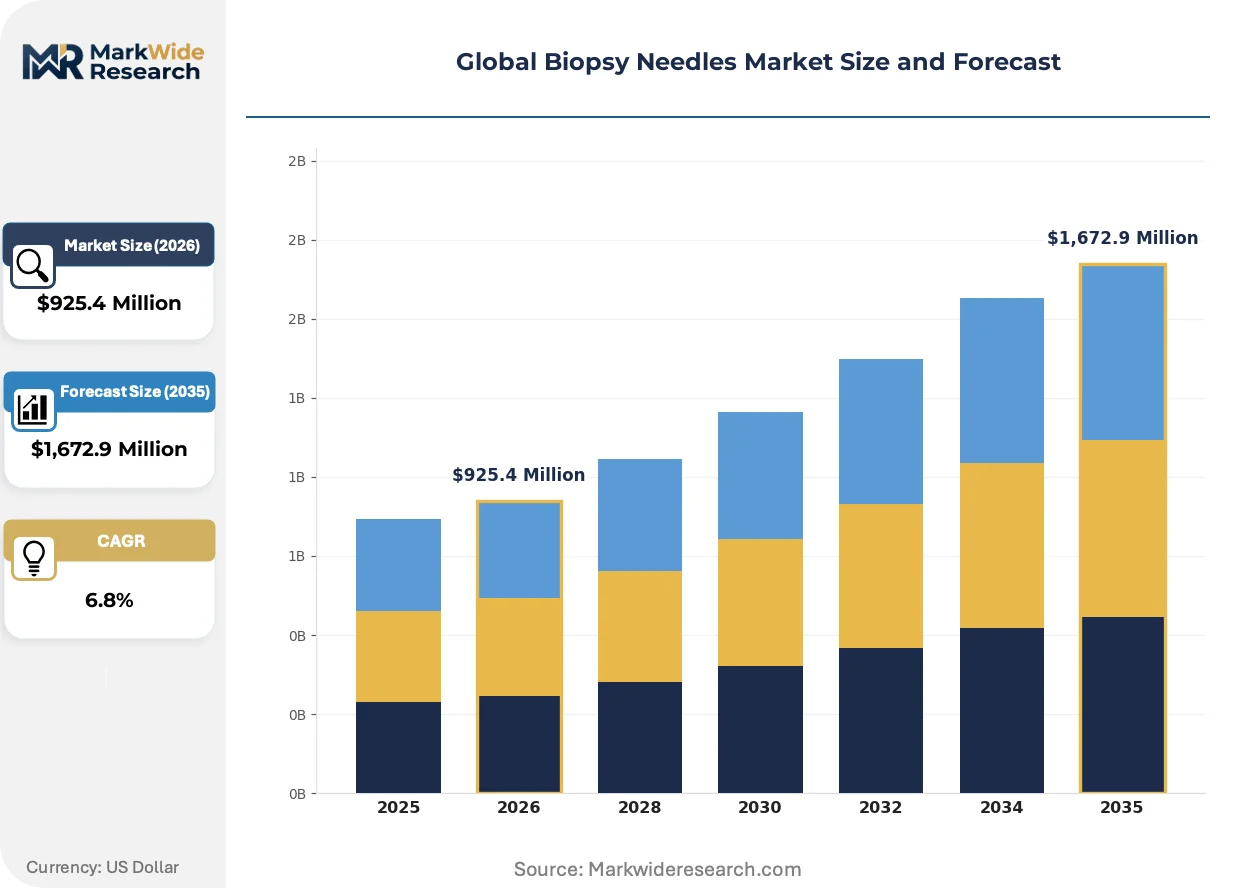
| Market Size in 2026 | $925.4 Million |
| Market Size in 2035 | $1,672.9 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Needle, Fine Needle, Vacuum-Assisted, Stereotactic, Aspiration Application: Oncology Diagnostics, Pulmonology, Gastroenterology, Dermatology, Urology End User: Medical Centers, Diagnostic Laboratories, Specialty Clinics, Ambulatory Surgical Centers Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Medical Device Wholesalers |
| Companies Covered | Medtronic plc, Becton Dickinson, Cardinal Health, Boston Scientific Corporation, Argon Medical Devices, Olympus Corporation, Hologic Inc, Devicor Medical Products, Cook Group Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biopsy Needles Market Shifts & Advancements
Disposable sterile workflows are displacing capital-intensive reprocessing infrastructure across interventional suites, while regulatory surveillance frameworks and procurement rationalization reshape competitive positioning.
Coaxial cutting mechanisms with integrated tissue preservation chambers are fragmenting the core needle segment into specialty configurations for renal, thyroid, and musculoskeletal applications. Interventional radiology departments in academic medical centers are adopting these platforms for outpatient lesion characterization. The technology is fragmenting procurement decisions away from general-purpose instruments toward procedure-specific disposable kits.
EMA post-market surveillance obligations under MDR Article 83 are compelling manufacturers to maintain active device performance registries across European hospital networks. This regulatory architecture is raising compliance capital requirements for mid-tier suppliers. Breast biopsy system vendors are responding by consolidating clinical evidence generation through multi-center prospective studies in France and Germany.
Hospital supply committees are consolidating biopsy needle procurement into multi-year framework agreements with automated replenishment triggers. Group purchasing organizations are displacing individual department buying authority in North American health systems. This concentration is most visible in integrated delivery networks across California and Pennsylvania, where standardized tip specifications now span entire hospital fleets.
Global Biopsy Needles Market Segmentation
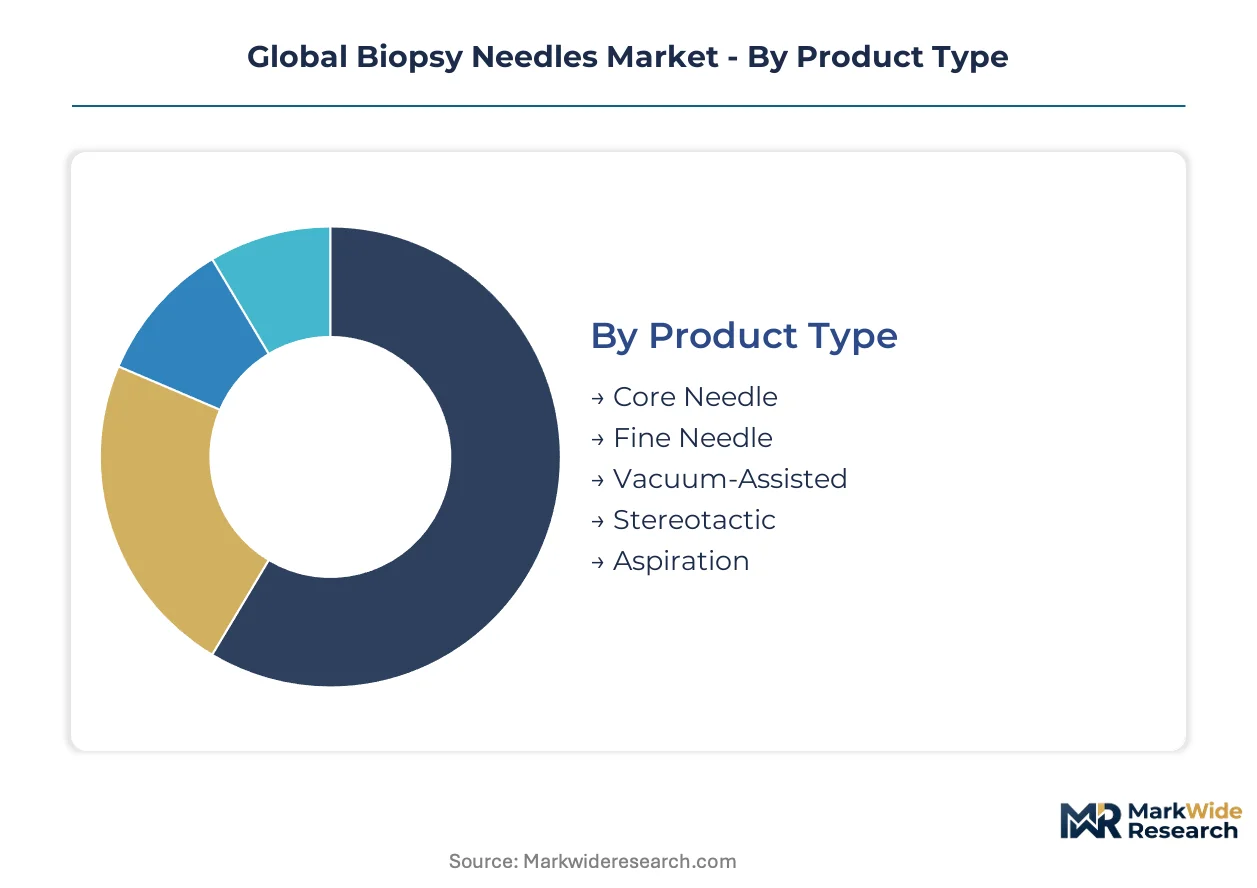
Segmentation in biopsy needles reflects divergent regulatory pathways, sterile workflow requirements, and site-of-care economics across oncology and adjacent specialties. Product configurations align with specific lesion types and imaging modalities, while distribution channels track procurement centralization trends in hospital systems.
Product Type:
FDA 510(k) clearance timelines and EU MDR conformity assessments create divergent entry barriers across needle architectures, with vacuum-assisted platforms facing heightened clinical evidence thresholds.
- Core Needle:Coaxial cutting mechanisms preserve tissue architecture through hollow-bore extraction channels. Demand concentrates in academic medical centers performing renal and musculoskeletal biopsies, constrained by interventional radiologist training pipeline bottlenecks in Germany and Japan.
- Vacuum-Assisted:Continuous suction technology captures larger contiguous samples during single insertions. Adoption is accelerating in breast and prostate diagnostics across US integrated delivery networks, though nitinol supply concentration in China's Zhejiang province creates input vulnerability.
- Fine Needle:22-25 gauge instruments for cytological sampling in thyroid and lymph node applications.
- Stereotactic:Frame-based or frameless guidance systems for sub-centimeter lesion targeting in neurosurgical and breast applications.
- Aspiration:Fluid and tissue extraction for pleural and peritoneal diagnostics in cost-sensitive settings.
Core needle configurations handle the majority of throughput across solid organ diagnostics; vacuum-assisted systems are gaining share fastest in women's health and urology segments.
Application:
Procedure reimbursement rates and screening program mandates shape volume distribution across medical specialties, with national cancer initiatives in Germany and Japan expanding percutaneous biopsy volumes.
- Oncology Diagnostics:Solid tumor characterization drives premium needle specifications in lung, liver, and pancreatic applications. Demand clusters in hospital-based interventional radiology departments across the US, constrained by EMA post-market surveillance obligations under MDR Article 83 that compel sustained device performance registries.
- Pulmonology:Transthoracic and bronchoscopic biopsy for peripheral lung lesions. Volumes are expanding in Japan's national lung cancer screening program, with electromagnetic navigation bronchoscopy integration creating technical specification requirements.
- Gastroenterology:Endoscopic ultrasound-guided fine needle aspiration for pancreatic and mediastinal lesions.
- Dermatology:Shave and punch alternatives for melanoma and non-melanoma skin cancer staging.
- Urology:Prostate and renal mass characterization in ambulatory surgical centers.
Oncology diagnostics commands the dominant procedure volume; pulmonology is climbing the fastest as screening protocols expand across East Asian markets.
End User:
Capital equipment intensity and sterile reprocessing capabilities determine site-of-care penetration, with same-day biopsy capabilities driving ambulatory migration in Texas and Florida.
- Medical Centers:Academic and community hospitals with integrated interventional radiology suites. Procurement concentrates in group purchasing organization frameworks across California and Pennsylvania health systems, with standardized tip specifications spanning entire hospital fleets.
- Diagnostic Laboratories:Independent pathology services with outsourced tissue acquisition partnerships.
- Specialty Clinics:Urology and women's health focused settings with procedure-specific disposable kit preferences.
- Ambulatory Surgical Centers:Outpatient facilities unbundling biopsy services from hospital admission workflows. Expansion is constrained by ISO 13485 sterilization validation requirements and ethylene oxide residual testing bottlenecks.
Medical centers absorb the predominant device volume; ambulatory surgical centers are expanding most quickly as payor pressure shifts site-of-care economics.
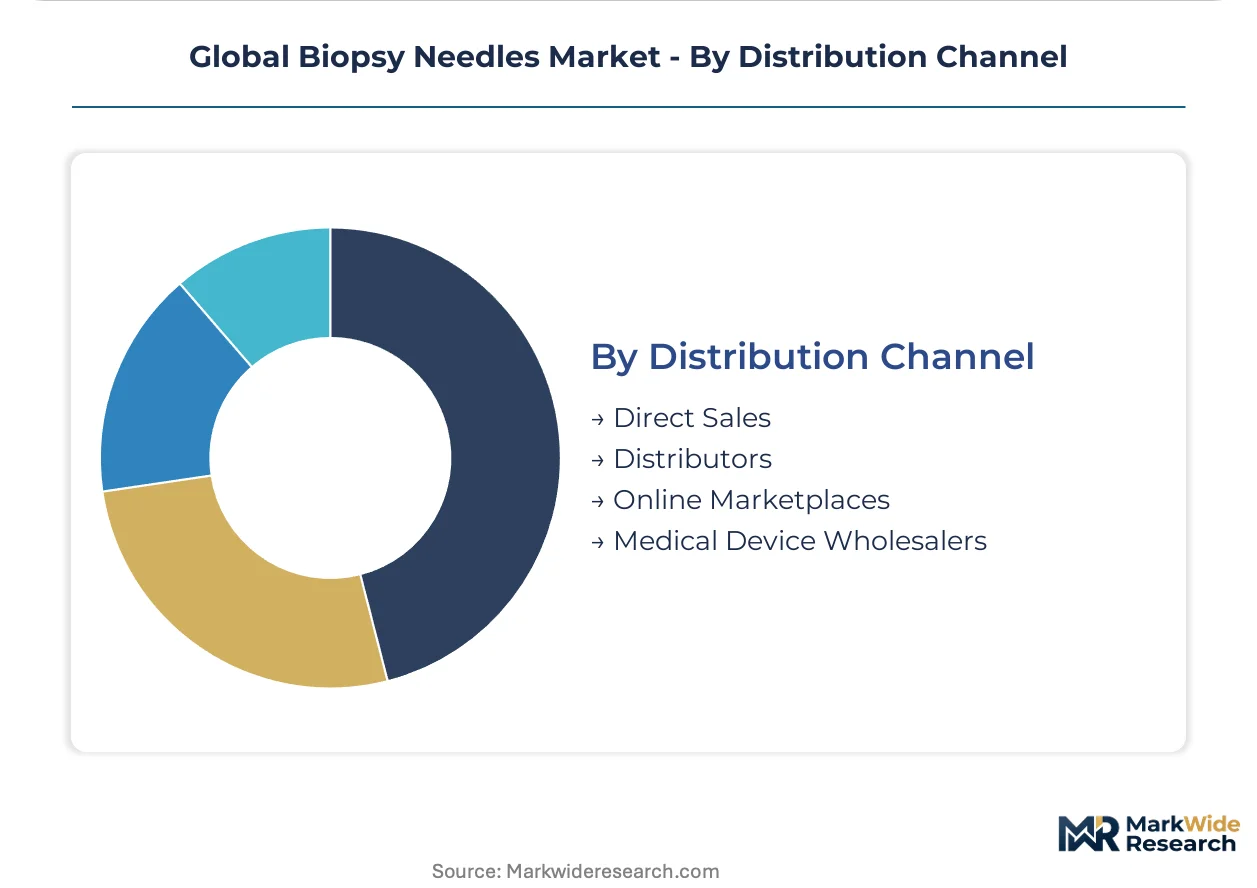
Distribution Channel:
Procurement rationalization and automated replenishment systems are compressing intermediary layers in North American supply chains.
- Direct Sales:Manufacturer field representatives negotiating multi-year framework agreements with integrated delivery networks. Relationships concentrate in high-volume automated manufacturing anchors serving hospital supply committees.
- Distributors:Regional medical device specialists with sterile logistics capabilities.
- Online Marketplaces:E-procurement platforms for standard specification needles in cost-sensitive settings.
- Medical Device Wholesalers:Broad-line distributors with consolidated warehousing across Eastern Europe and Latin America.
Direct sales channels manage the largest contract value; online marketplaces are advancing fastest as procurement digitization penetrates mid-tier health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement environments, with integrated delivery networks in the United States absorbing premium single-use specifications while cost-constrained facilities in Eastern Europe and Latin America extend reusable needle cycles.
United States
Hospital supply committees in California and Pennsylvania health systems are consolidating procurement into multi-year framework agreements with automated replenishment triggers. FDA 510(k) premarket notification requirements extend clearance timelines by 8-14 months for novel tip geometries. Boston and Houston academic medical centers are expanding percutaneous biopsy programs amid rising cancer screening volumes.
Germany
National lung cancer screening protocols are expanding percutaneous biopsy volumes in pulmonology departments across Bavaria and North Rhine-Westphalia. EMA post-market surveillance obligations under MDR Article 83 compel sustained device performance registries. The Frankfurt-Rhine-Main cluster anchors multi-center prospective studies for breast biopsy system vendors consolidating clinical evidence generation.
China
Government-funded cancer hospital networks are procuring vacuum-assisted systems for tier-2 city deployment in Jiangsu and Guangdong provinces. NMPA medical device registration pathways shape product entry timelines for domestic and foreign manufacturers. The Zhejiang province concentration of nitinol shape-memory wire production creates input vulnerability for Western manufacturers dependent on alloy supply.
India
Oncology infrastructure buildout in Maharashtra and Tamil Nadu is absorbing expanded production of vacuum-assisted and core needle systems. CDSCO medical device rules govern import registration and quality certification requirements. Mumbai and Chennai metropolitan hospital networks are scaling interventional radiology capacity faster than fellowship training pipelines can supply qualified specialists.
Japan
National lung cancer screening program expansion is driving transthoracic and bronchoscopic biopsy volumes in Kanto and Kansai regions. PMDA premarket approval processes and JIS standards govern device quality certification. The Tokyo-Osaka corridor concentrates electromagnetic navigation bronchoscopy integration creating technical specification requirements for biopsy platform vendors.
Global Biopsy Needles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated surgical navigation platforms commanding premium positioning against high-volume automated manufacturing anchors. The vendor base stratifies across three tiers: diversified medical technology conglomerates with procedure-specific disposable portfolios, mid-cap specialists with regional supply contracts, and emerging fabricators serving cost-sensitive procurement channels. Dominant competitive moves include backward integration into nitinol alloy supply chains and strategic partnerships with imaging modality manufacturers for navigation software integration.
Among diversified medical technology conglomerates, Medtronic plc and Becton Dickinson exemplify contrasting scale-driven archetypes, with the former representing integrated surgical platform bundling and the latter anchoring high-volume automated manufacturing for North American hospital supply contracts. Hologic Inc occupies a defensible specialist position within women's health diagnostics. These three entities collectively illustrate the competitive tension between full-procedure ecosystem control and focused segment depth.
| Leading Market Players |
|---|
| Medtronic plc |
| Becton Dickinson |
| Cardinal Health |
| Boston Scientific Corporation |
| Argon Medical Devices |
| Olympus Corporation |
| Hologic Inc |
| Devicor Medical Products |
| Cook Group Incorporated |
| Others |
Supply & Pricing Matrix
Single-use sterile needle adoption displacing reusable reprocessing infrastructure simultaneously concentrates sterile packaging capacity in automated manufacturing hubs and compresses margin structures for mid-tier suppliers dependent on manual assembly workflows. This substitution dynamic reshapes supply geography toward FDA-registered facilities with validated ethylene oxide sterilization lines while pricing economics bifurcate between high-volume hospital supply contracts and fragmented specialty clinic procurement.
Pricing Analysis
After-sales service contracts for navigation software maintenance and electromagnetic tracking calibration drive lifetime value beyond per-unit disposable margins. Three-tier pricing structure across premium vacuum-assisted systems, standard core needle configurations, and economy fine needle aspiration kits reflects FDA 510(k) clearance tier and sterilization validation depth. Pricing pressure stems from group purchasing organization consolidation across California and Pennsylvania health systems. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity; integrated delivery networks absorb premium specifications with automated replenishment triggers.
Supply Chain Analysis
Inventory buffers for nitinol shape-memory wire extend lead times when Zhejiang province production faces regulatory inspection backlogs. Supply concentrates in China's Zhejiang province for nitinol alloys, Germany's Baden-Württemberg region for precision grinding equipment, and Malaysia for sterile packaging films. Raw material dependencies include surgical-grade stainless steel, nickel-titanium shape-memory alloys, and ethylene oxide sterilization gases. Single-source vulnerability in Chinese nitinol supply creates input risk for Western manufacturers. Distribution runs through direct sales field representatives negotiating multi-year framework agreements with hospital supply committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biopsy needle markets are approaching a platform-economics inflection where electromagnetic navigation integration with CT-guided systems creates procedure-specific ecosystem lock-in, rewarding vendors who control both disposable hardware and imaging software interoperability layers.
For Market Incumbents: Shield market position through backward integration into nitinol alloy supply chains and captive sterile packaging capacity expansion. Defend against emerging Asian fabricators by accelerating FDA 510(k) clearance velocity for novel tip geometries. Prioritize certification investment in ISO 13485 quality management systems with ethylene oxide residual testing automation to release batch bottlenecks.
For New Entrants and Emerging Players: Lead with vacuum-assisted platform specialization for breast and prostate diagnostics in India's Maharashtra and Tamil Nadu government-funded cancer hospital networks. Target tier-2 city deployment where interventional radiologist training pipeline gaps create demand for simplified single-insertion systems. Pursue CDSCO import registration partnerships with Mumbai metropolitan distributors for regulatory pathway acceleration.
For Investors and Strategic Acquirers: EU MDR Article 83 post-market surveillance obligations reshape the acquisition landscape toward targets with active device performance registries across European hospital networks. Long-term viability favors mid-cap specialists with demonstrated clinical evidence generation capabilities in France and Germany multi-center studies. Watch for electromagnetic navigation bronchoscopy integration requirements in Japan's PMDA approval pathways as signal for platform consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Navigation Software Companion Development | Electromagnetic tracking integration with CT-guided platforms enables sub-centimeter lesion targeting in interventional radiology. |
| Hospital System Partnership | Multi-year framework agreements with California and Pennsylvania integrated delivery networks standardize tip specifications across entire fleets. |
| CE Marking Pathway | MDR Article 83 surveillance compliance builds clinical evidence repositories for European market access sustainability. |
| Backward Integration into Nitinol Supply | Captive shape-memory wire production mitigates Zhejiang province concentration risk for Western manufacturers. |
| Reimbursement Strategy | Same-day biopsy capability coding in Texas and Florida ambulatory surgical centers unbundles services from hospital admission workflows. |
Research Methodology
Operator-level perspectives from interventional radiologists, hospital purchasing committee chairs, biomedical engineers, and group purchasing organization contracts managers anchored the qualitative base. Primary fieldwork combined with secondary validation against FDA 510(k) clearance databases, EMA MDR submission records, hospital procurement databases, and CMS Medicare reimbursement files. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation established segmentation boundaries.
Sensitivity analysis across the projection horizon tested vacuum-assisted platform adoption curves and nitinol supply disruption scenarios. Segmentation dimensions modeled include product architecture, application specialty, end-user site-of-care economics, and regional regulatory cluster. CAGRs derived from procedure volume growth trajectories weighted by reimbursement rate evolution and screening program mandate expansion. Forecast inputs incorporated interventional radiologist fellowship training pipeline capacity constraints and sterile packaging line expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) clearance velocity, EU MDR surveillance compliance cost absorption, or nitinol supply chain diversification would require recalibration. Forecasts reflect documented assumptions regarding screening protocol expansion, payor site-of-care shift incentives, and electromagnetic navigation platform interoperability standardization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Italy General Surgical Devices Market
Surgical Instruments
Intraoperative Aberrometry Market
Surgical Instruments
Knotless Tissue Control Devices Market
Surgical Instruments
Global Minimally Invasive Surgery (MIS) Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Ophthalmic Handheld Surgical Instruments Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
United Arab Emirates General Surgical Devices Market
Surgical Instruments
High Flow Needle Sets Market