
 Veterinary Injectable Devices Market | 2026-2036
Veterinary Injectable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Injectable Devices Market Outlook
Veterinary technician labor availability is collapsing across North American and European companion animal practices, forcing clinics toward automatic injection systems that reduce procedural time and training burdens. Zoetis leverages its integrated animal health platform to bundle devices with pharmaceutical portfolios, while Merck Animal Health anchors its position through deep distribution networks in livestock and poultry segments. Dechra Pharmaceuticals differentiates by focusing on specialized anesthesia and pain management delivery tools for exotic and equine species.
Veterinary injectable devices comprise precision-engineered syringes, needles, automatic injectors, and associated administration systems manufactured from medical-grade polymers and stainless steel alloys, designed to deliver vaccines, therapeutics, and anesthetics with calibrated dosing accuracy and minimal tissue trauma. Syringes and needles retain the largest installed base across veterinary clinics and animal hospitals, though automatic systems are capturing the fastest growth as labor constraints intensify and safety regulations mandate sharps injury prevention. Digital solutions remain nascent but concentrate margin pools through connected dosing logs and compliance tracking for research laboratories and regulated zoo veterinary programs.
FDA Center for Veterinary Medicine oversight of device biocompatibility and USDA Animal and Plant Health Inspection Service requirements for vaccine administration tools shape product development pathways and market access conditions in the United States. ISO 13485 quality management standards and EU Medical Device Regulation conformity procedures govern European market entry, with CE marking obligations extending to reusable and single-use injection systems. Stakeholders must monitor evolving safety device mandates and digital traceability requirements as procurement criteria shift toward integrated compliance documentation.
Market Dynamics
Veterinary technician labor shortages across North American and European companion animal practices are accelerating automatic injection system deployment, compressing procedural time and reducing training dependencies for precision dosing protocols.
Growth Catalysts
- USDA APHIS vaccine administration mandates:Federal requirements for standardized biologics delivery tools drive replacement cycles in livestock and poultry operations, expanding addressable device demand.
- Medical-grade polymer advances:Cyclic olefin copolymers and lubricious coatings reduce tissue trauma and needlestick injuries, supporting safety device premiumization in specialty veterinary hospitals.
- Research laboratory procurement concentration:Regulated zoo and academic veterinary programs generate recurring revenue streams through connected dosing logs and compliance documentation requirements.
Market Restraints
- Stainless steel alloy input volatility:Medical-grade 304 and 316L stainless pricing fluctuations compress margins for needle and precision syringe manufacturers.
- Single-source polymer supply concentration:Specialized medical-grade resin production concentrates among limited European and North American chemical suppliers, creating procurement vulnerability.
- Biocompatibility testing timelines:FDA Center for Veterinary Medicine device clearance protocols extend product development cycles by 18-24 months for novel materials.
Strategic Opportunities
- Exotic and equine anesthesia specialization:Underserved species segments offer premium pricing for customized delivery tools with calibrated flow rates and ergonomic designs.
- EU Medical Device Regulation digital traceability:CE marking obligations for unique device identification create competitive differentiation for integrated compliance documentation systems.
- Telemedicine-integrated home administration:Pet owner self-injection training platforms and remote veterinary oversight open direct-to-consumer channels for chronic disease management devices.
Industry Challenges
- Veterinary technician certification bottlenecks:Accredited training program capacity constraints limit workforce expansion, forcing clinics toward automation investments.
- ISO 13485 quality management implementation:Small and mid-sized device manufacturers face capital intensity for certified cleanroom and validation infrastructure.
- Legacy practice management software integration:Connected dosing systems require API development and data standardization with entrenched veterinary clinic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Injectable Devices Market |
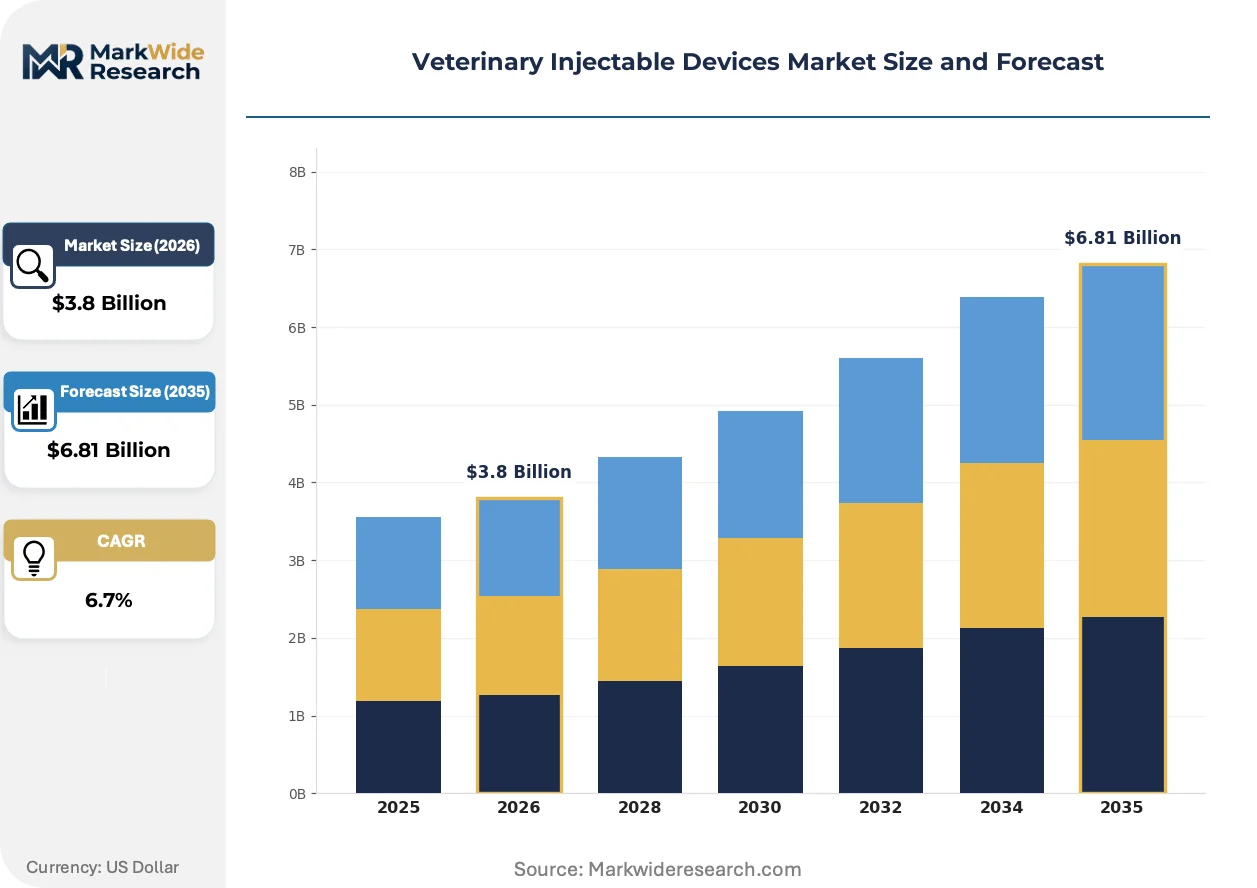
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Needles, Automatic Injectors, Injectors End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Zoos Application: Vaccination, Anesthesia, Treatment, Health Check Technology: Manual Injection, Automatic Systems, Safety Devices, Digital Solutions |
| Companies Covered | Boehringer Ingelheim, Neogen Corporation, Zoetis, Vetoquinol, Virbac, Elanco Animal Health, Ceva Santé Animale, Dechra Pharmaceuticals, Merck Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Injectable Devices Market Strategic Shifts
Device manufacturers are converging precision engineering with digital connectivity to capture margin pools in regulated environments, while safety mandates and labor constraints reshape procurement criteria across veterinary end-use segments.
Prefilled syringe systems with integrated needle safety mechanisms are displacing conventional multi-dose vial and separate needle configurations in companion animal vaccination protocols. Specialty veterinary hospital chains in the United States and Germany are standardizing these closed-system designs to reduce preparation errors and sharps injuries. The shift is compressing market share for traditional syringe-needle combinations while expanding recurring revenue models for pre-filled pharmaceutical-device bundles.
EU Medical Device Regulation conformity procedures now mandate clinical evidence and post-market surveillance for reusable injection systems, elevating documentation burdens for European market entry. Manufacturers must maintain technical files and periodic safety update reports, with notified body scrutiny intensifying for devices contacting circulating blood or cerebrospinal fluid. German and French veterinary device distributors are consolidating supplier relationships to manage compliance complexity, favoring partners with established quality management infrastructure.
Research laboratories and regulated zoo veterinary programs are unbundling after-sales service from device procurement, demanding standalone calibration contracts and predictive maintenance subscriptions. This consumption-pattern shift separates hardware margins from recurring service revenue, with academic medical centers in the United Kingdom and Netherlands leading contract restructuring. Device vendors must reconfigure sales organizations and pricing architecture to capture lifetime value across extended replacement cycles.
Veterinary Injectable Devices Market Segmentation
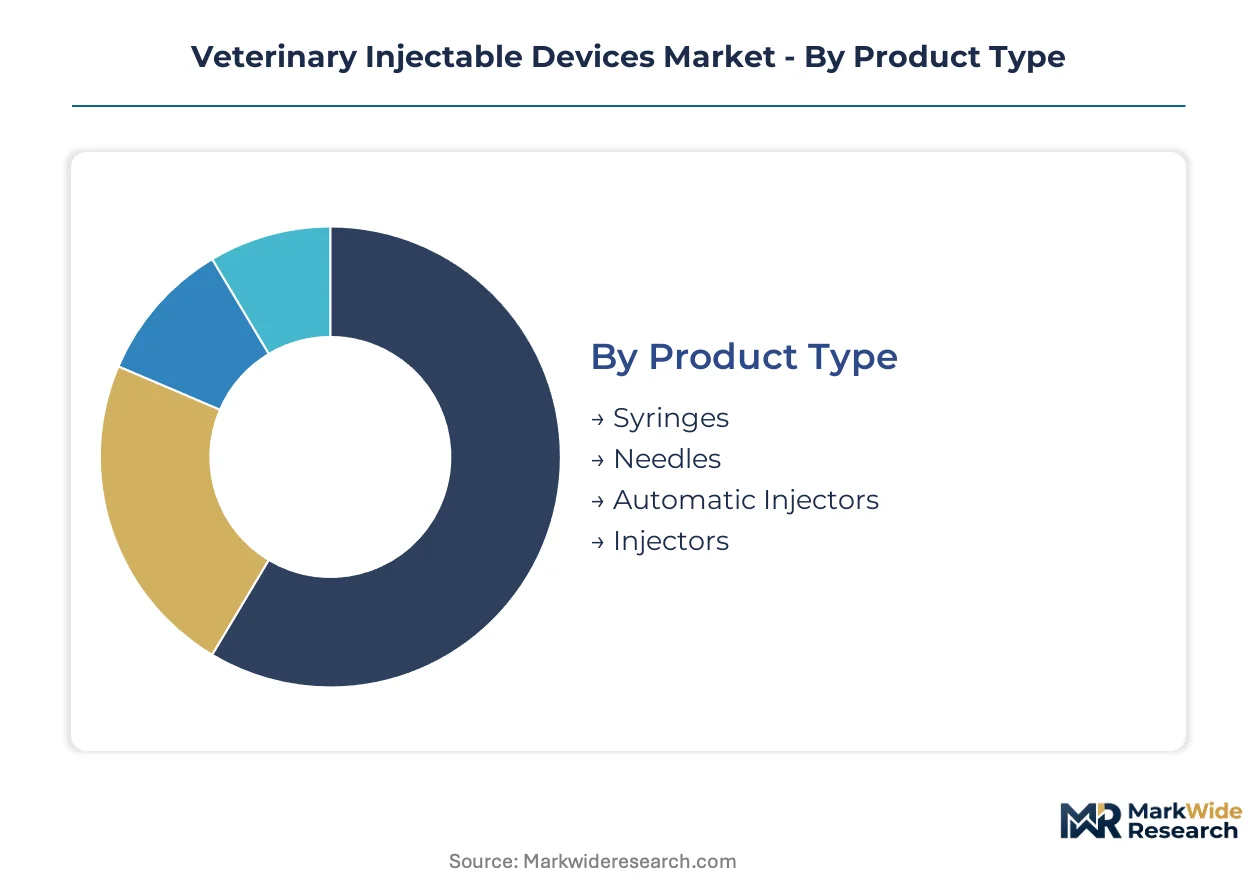
Veterinary injectable devices fragment across four critical dimensions, with product type and technology segments experiencing the sharpest substitution pressures from safety mandates and labor automation. Understanding these divides reveals where margin pools concentrate and which configurations face obsolescence.
Product Type:
Automatic injectors exert the strongest substitution pressure on conventional syringes, driven by technician shortages and sharps injury prevention mandates across companion animal practices.
- Syringes:Medical-grade polymer and glass barrel designs with Luer lock or slip-tip configurations remain the installed base standard. Demand concentrates in United States rural mixed-animal practices where cost sensitivity delays automation upgrades, though safety-retrofit attachments are displacing legacy models.
- Needles:Stainless steel 304 and 316L cannulas with bevel geometries optimized for tissue trauma reduction anchor livestock and poultry vaccination protocols. USDA APHIS biologics administration standards in United States feedlot operations drive gauge standardization and replacement cycle compression.
- Automatic Injectors:Spring-loaded or gas-powered precision dosing systems with integrated depth control.
- Injectors:Multi-dose pistol-grip devices for high-volume livestock operations.
Syringes and needles anchor the volume base while automatic injectors gain share at the steepest rate.
End User:
Cost tier stratification separates premium device procurement in research settings from price-optimized configurations in high-volume clinical environments.
- Veterinary Clinics:Companion animal primary care facilities with vaccination-heavy caseloads favor prefilled syringe systems. United States suburban clinic chains standardize closed-system designs to reduce preparation errors and technician training burdens.
- Animal Hospitals:Specialty and emergency institutions with surgical and critical care capabilities demand calibrated anesthesia delivery tools. German university-affiliated hospitals drive specifications for exotic species flow-rate precision and ergonomic handle designs.
- Research Laboratories:Regulated academic and pharmaceutical testing facilities with GLP compliance requirements.
- Zoos:Wildlife and exotic collection veterinary programs with remote chemical immobilization needs.
Veterinary clinics and animal hospitals generate the largest procurement volumes while research laboratories command the highest per-unit pricing premiums.
Application:
Volume concentration in vaccination protocols creates margin pressure, while anesthesia applications sustain premium pricing through technical complexity and species specialization requirements.
- Vaccination:Mass immunization protocols in livestock, poultry, and companion animal populations drive high-frequency disposable consumption. United States cattle feedlot operators and integrated poultry processors purchase through distributor contracts with volume-tier pricing structures.
- Anesthesia:Injectable sedative, analgesic, and general anesthetic delivery for surgical and diagnostic procedures. United Kingdom equine referral hospitals and Netherlands zoo veterinary programs specify customized delivery tools with calibrated flow rates for species-specific pharmacokinetics.
- Treatment:Therapeutic antibiotic, anti-inflammatory, and chronic disease medication administration.
- Health Check:Diagnostic sample collection and prophylactic screening procedures.
Vaccination commands the highest shipment volumes while anesthesia delivers the steepest margin expansion trajectory.
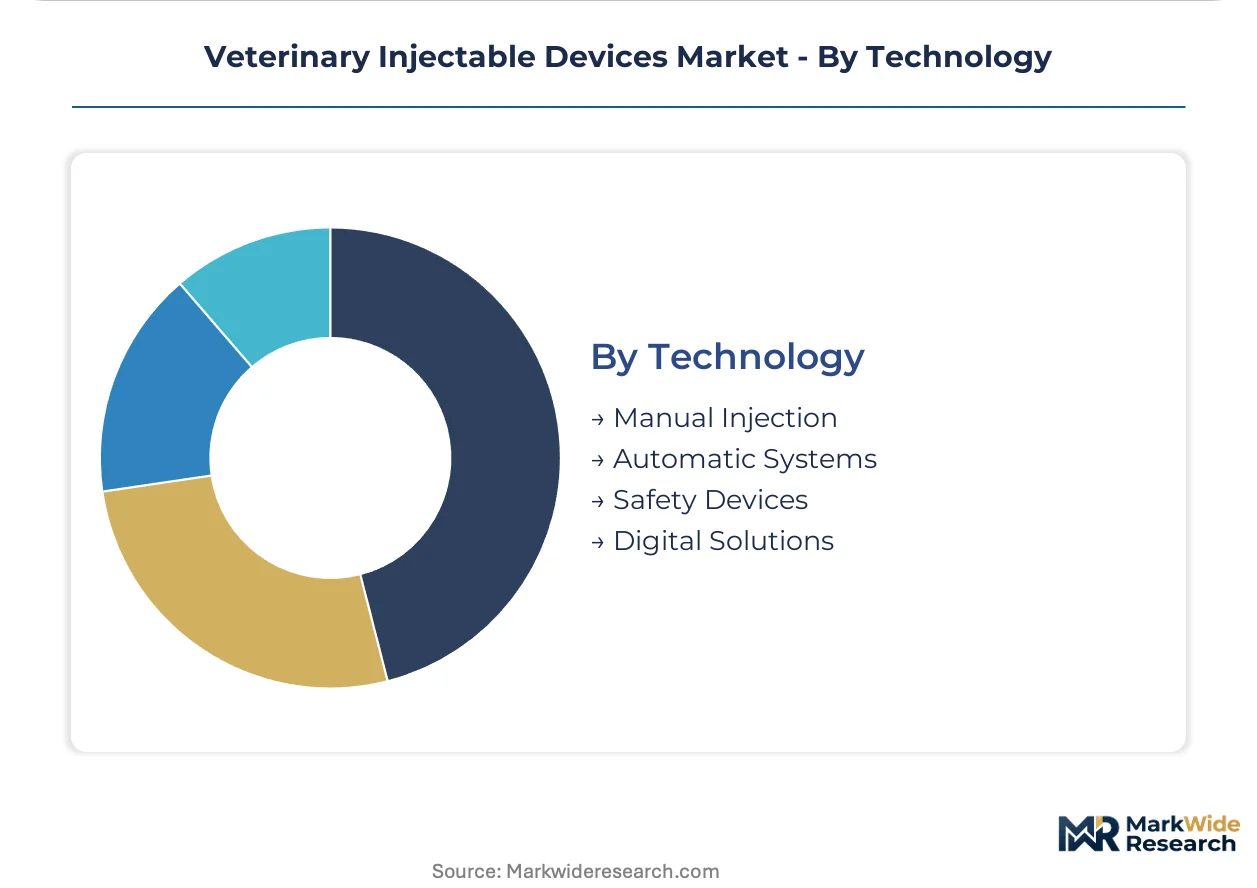
Technology:
Customer type stratification separates institutional buyers with compliance documentation requirements from independent practitioners prioritizing capital efficiency.
- Manual Injection:Conventional syringe-needle combinations with operator-controlled plunger actuation and depth placement. United States independent mixed-animal practices in rural Texas and Kansas retain these systems for economic flexibility across species.
- Automatic Systems:Motorized or spring-driven devices with fixed-dose delivery and ergonomic activation mechanisms. France and Germany specialty hospital chains deploy these to compress procedural time amid technician certification bottlenecks.
- Safety Devices:Needle shields, retractable mechanisms, and passive injury prevention engineering.
- Digital Solutions:Connected dosing logs, RFID tracking, and compliance documentation platforms.
Manual injection retains the broadest installed base while digital solutions climb the fastest despite nascent penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Companion animal clinics in the United States deploy automatic injection systems at higher penetration rates than livestock-heavy markets, while European veterinary hospitals prioritize prefilled safety devices under stricter sharps regulations. Research laboratories in the United Kingdom and Netherlands generate disproportionate per-unit pricing premiums through connected compliance documentation requirements.
United States
Specialty veterinary hospital chains and research laboratories drive premium device procurement, with suburban clinic networks standardizing closed-system prefilled syringes to reduce technician training burdens. FDA Center for Veterinary Medicine biocompatibility protocols and USDA APHIS vaccine administration mandates shape product specifications for livestock and poultry operations. Greater Boston and San Diego biotechnology corridors concentrate demand for calibrated anesthesia delivery tools in academic veterinary medical centers.
Germany
University-affiliated veterinary hospitals specify exotic species flow-rate precision and ergonomic handle designs for anesthesia applications. EU Medical Device Regulation conformity procedures and CE marking obligations elevate documentation burdens for reusable injection systems entering the market. The Baden-Württemberg and Bavaria veterinary device manufacturing clusters host quality management infrastructure serving continental European distribution networks.
United Kingdom
Equine referral hospitals and regulated zoo veterinary programs command customized delivery tools with species-specific pharmacokinetic calibration. The Medicines and Healthcare products Regulatory Agency oversees device safety standards alongside EU-UK regulatory alignment mechanisms for cross-border trade. London and Cambridge academic medical centers lead contract restructuring toward standalone calibration and predictive maintenance subscriptions.
France
Specialty hospital chains deploy automatic injection systems to compress procedural time amid veterinary technician certification bottlenecks. ANSM pharmaceutical device oversight intersects with EU MDR traceability requirements for unique device identification integration. The Lyon and Toulouse veterinary research clusters generate demand for connected dosing logs in pharmaceutical testing facilities.
Netherlands
Zoo veterinary programs with remote chemical immobilization needs source precision-engineered delivery systems for wildlife applications. Dutch healthcare regulator IGJ implements EU-aligned quality management standards for veterinary medical devices. The Utrecht veterinary science hub concentrates research laboratory procurement with GLP compliance documentation requirements.
Veterinary Injectable Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical-backed platforms leveraging distribution density against independent device manufacturers focused on species-specific niches. Market structure reflects consolidation around animal health conglomerates with captive pharmaceutical portfolios, while mid-sized specialists capture margin pools in exotic and equine anesthesia segments. Two archetypes dominate: integrated pharmaceutical-device bundlers and independent precision engineering specialists. Competitive moves concentrate on strategic partnerships for digital connectivity integration and geographic expansion through distributor consolidation.
Among pharmaceutical-integrated platforms, Zoetis and Merck Animal Health exemplify the bundling archetype, leveraging device portfolios as delivery mechanisms for therapeutic and vaccine revenue streams. Dechra Pharmaceuticals occupies a specialist position within anesthesia and pain management delivery, representing the independent precision tier focused on underserved species segments. These three anchors illustrate the competitive divergence between scale-driven platform economics and premium-priced specialization.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Neogen Corporation |
| Zoetis |
| Vetoquinol |
| Virbac |
| Elanco Animal Health |
| Ceva Santé Animale |
| Dechra Pharmaceuticals |
| Merck Animal Health |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at medical-grade polymer resin facilities in Germany and the United States shapes both supply concentration and price floors for precision syringe manufacturers, with stainless steel alloy pricing volatility transmitting directly into needle cost structures across livestock vaccination protocols.
Pricing Analysis
Long-term offtake agreements dominate procurement between United States cattle feedlot operators and needle suppliers, while spot purchasing persists among independent mixed-animal practices in rural Texas and Kansas. Three-tier pricing structure across premium, standard, and economy levels separates research laboratory calibration-contract bundles from disposable vaccination syringes, with ISO 13485 certification tier and after-sales service bundling as primary differentiation drivers. Cost compression in standard-grade manual syringes is intensifying because of stainless steel 304 input volatility, though specialty veterinary hospital chains in Germany exhibit lowest price sensitivity due to compliance documentation requirements.
Supply Chain Analysis
Inventory lead times for specialized cyclic olefin copolymers extend procurement cycles for automatic injector manufacturers, forcing buffer stock strategies among European device assemblers. Medical-grade polymer production concentrates in Germany, Belgium, and the United States, while stainless steel 316L cannula drawing feeds from Japanese and Swedish specialty metal suppliers. Single-source vulnerability in European resin supply creates exposure to notified body certification delays, with distribution running through veterinary distributor networks that consolidate supplier relationships under EU MDR compliance burdens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary injectable devices sit in early-cycle expansion as automatic injection system penetration in companion animal clinics remains below saturation thresholds despite technician labor shortages accelerating replacement demand.
For Market Incumbents: Shield market position through backward integration into medical-grade polymer compounding to offset stainless steel alloy volatility, while deepening ISO 13485 certified cleanroom capacity in Baden-Württemberg manufacturing clusters to preempt compliance documentation demands from German university-affiliated hospitals. Consolidate distributor relationships in France and the Netherlands before EU MDR traceability mandates reshape procurement criteria. For New Entrants and Emerging Players: After-sales service unbundling represents the most penetrable white-space target, with standalone calibration contracts and predictive maintenance subscriptions commanding premium pricing in United Kingdom academic medical centers and Netherlands zoo veterinary programs. Enter through telemedicine-integrated home administration platforms for chronic disease management devices, leveraging direct-to-consumer channels that bypass entrenched distributor networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent precision engineering specialists with exotic species anesthesia expertise over pharmaceutical-integrated bundlers facing margin pressure in commoditized vaccination segments. Five-to-ten year viability hinges on digital connectivity integration capabilities and GLP compliance documentation infrastructure. Monitor veterinary technician certification program expansion rates as the inflection signal for automation demand saturation versus sustained replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | Accelerates EU MDR conformity for reusable injection systems entering German and French distribution networks. |
| Hospital System Partnership | Locks in prefilled syringe standardization across United States suburban clinic chains reducing technician training burdens. |
| Software Companion Development | Enables connected dosing logs and RFID tracking for United Kingdom research laboratory GLP compliance requirements. |
| Backward Integration into Polymer Compounding | Captures margin pools and reduces single-source vulnerability in European medical-grade resin supply. |
| Reimbursement Strategy Alignment | Positions automatic injector systems for veterinary insurance coverage expansion in companion animal chronic disease management. |
Study Parameters
A spread of perspectives from veterinary device manufacturing executives, procurement managers at specialty hospital chains, biomedical engineers in academic medical centers, and distributor compliance officers converged on the working assumptions underlying this analysis. Primary interview findings were cross-referenced against FDA Center for Veterinary Medicine device clearance databases, USDA APHIS biologics administration standards, EU Medical Device Regulation technical file repositories, and ISO 13485 certification registries. Bottom-up shipment data from veterinary clinics and research laboratories was triangulated with top-down pharmaceutical-device bundle revenue estimates.
Segmentation dimensions modeled span product type, end user category, application protocol, and technology tier across the projection horizon. CAGRs were derived from replacement cycle analysis, penetration rate trajectories for automatic systems, and pricing trend extrapolation. Forecast inputs incorporated veterinary technician labor availability indices, stainless steel alloy pricing volatility bands, and EU MDR implementation timeline assumptions for notified body capacity constraints.
Underlying assumptions cover stable regulatory enforcement intensity for sharps injury prevention mandates and continued specialty veterinary hospital chain consolidation in the United States, with deviation risk concentrated in veterinary technician training program expansion rates and medical-grade polymer supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Electrosurgery Devices Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Anesthesia Laryngeal Masks Market
Medical Devices
Otorhinolaryngology Devices Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Soft Tissue Markers Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Chile Artificial Organs and Bionic Implants Market
Medical Devices
Smart Lenses Market
Medical Devices
General Surgical Devices Market
Medical Devices
Peritoneal Dialysis Solutions Market