
 Natural Gas Generator Market | 2026-2036
Natural Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Gas Generator Market Intelligence
The expansion of power-as-a-service and leasing models is reshaping competitive positioning for industrial clients. This shift allows end-users to avoid large capital outlays for standby power systems. Caterpillar leverages its extensive global dealer network to offer these financing solutions for its generator sets. Cummins, meanwhile, specializes in integrated power systems for mission-critical facilities like data centers and telecommunications hubs.
A natural gas generator is a power generation unit converting the chemical energy of natural gas into electrical energy, often via a reciprocating engine. These systems are engineered for applications requiring reliable primary, backup, or peak power. Standby generators for commercial facilities and residential backup constitute the largest application segment. Within the technology landscape, reciprocating engines dominate due to their cost-effectiveness and operational flexibility across a wide range of power outputs.
Emissions regulations from bodies like the US Environmental Protection Agency (EPA) and compliance with China's GB standards dictate engine design. European Union directives on stationary power sources further influence product development for lower NOx emissions. The central challenge for manufacturers remains engineering generators that meet these tightening environmental rules without compromising power density or operational reliability.
Market Dynamics
The natural gas generator market is defined by the tension between rising demand for reliable backup power and increasingly stringent emissions mandates. This dynamic forces manufacturers to re-engineer engine technology to meet global regulations without sacrificing performance for mission-critical end-users like data centers and hospitals.
Growth Catalysts
- Data Center Power Demand:Global data center expansion requires reliable standby power, with natural gas generators offering a cleaner alternative to diesel.
- National Fuel Switching:Policies like China's dual carbon goals promote replacing coal with natural gas, stimulating demand for compliant generator sets.
- Gas Infrastructure Growth:Extending natural gas pipelines into new industrial zones unlocks previously inaccessible markets for generator installation.
Market Restraints
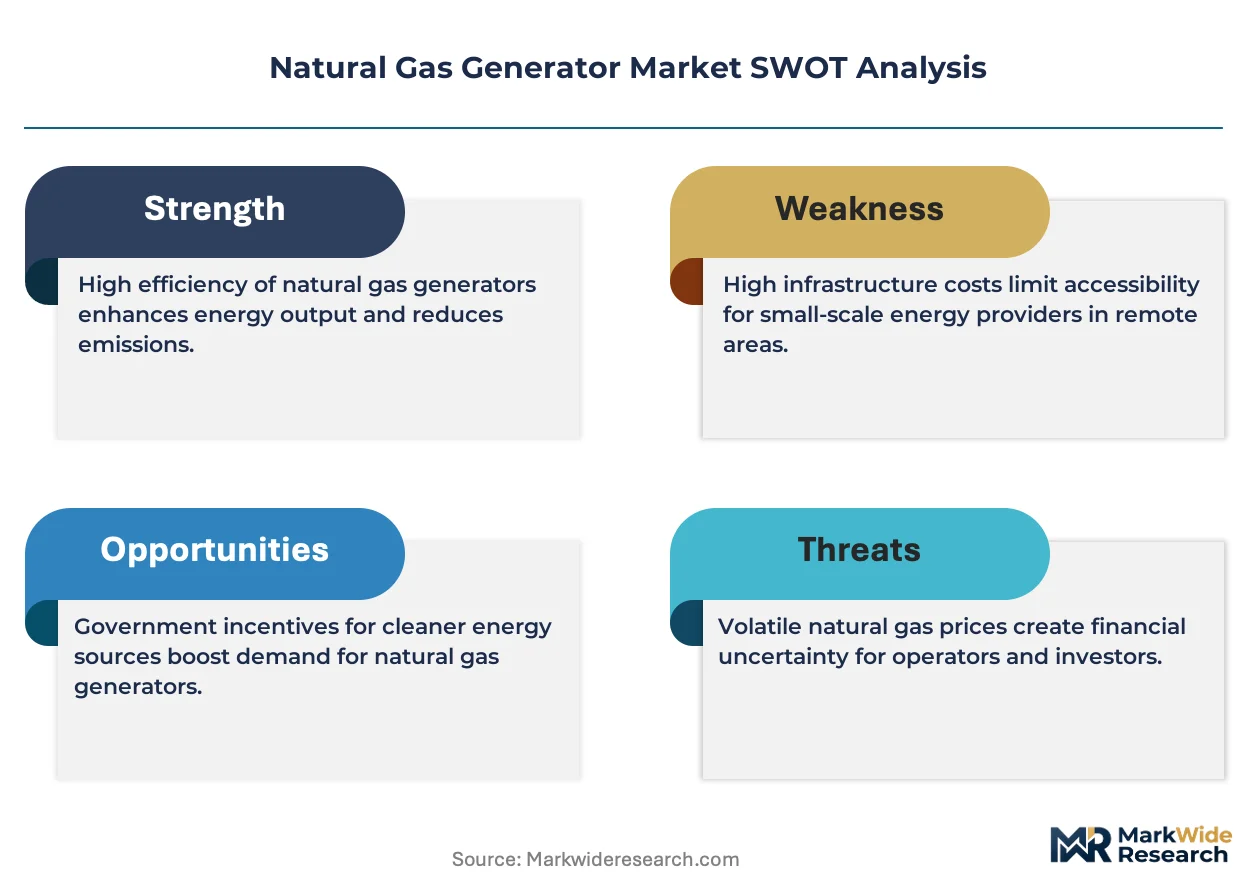
- Fuel Price Volatility:Unpredictable natural gas prices create operational cost uncertainty for end-users, complicating total cost of ownership calculations and investment decisions.
- Lower Power Density:Natural gas engines require a larger physical footprint than diesel counterparts for equivalent power output, a constraint in space-limited facilities.
- Renewable Substitution:The falling cost of solar-plus-storage solutions provides a zero-emission alternative for some standby applications, eroding the addressable market.
Strategic Opportunities
- Hybrid Generator-Storage Systems:Integrating gas generators with battery storage creates solutions with faster response times, targeting grid services and critical facilities.
- African Market Penetration:Industrial growth and unreliable grids in sub-Saharan Africa create demand for new prime and standby gas-powered generation capacity.
- Hydrogen-Ready Technology:Developing engines that operate on hydrogen blends allows manufacturers to address future fuel availability and long-term emissions reduction mandates.
Industry Challenges
- Navigating Emissions Regulations:Manufacturers face the complexity and cost of engineering engine platforms that can comply with a fragmented landscape of standards, including US EPA, EU directives, and China's GB standards.
- Component Supply Chain Risks:The supply of critical components such as advanced turbochargers, fuel injectors, and electronic control units is concentrated among a few specialized suppliers, creating potential bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Gas Generator Market |
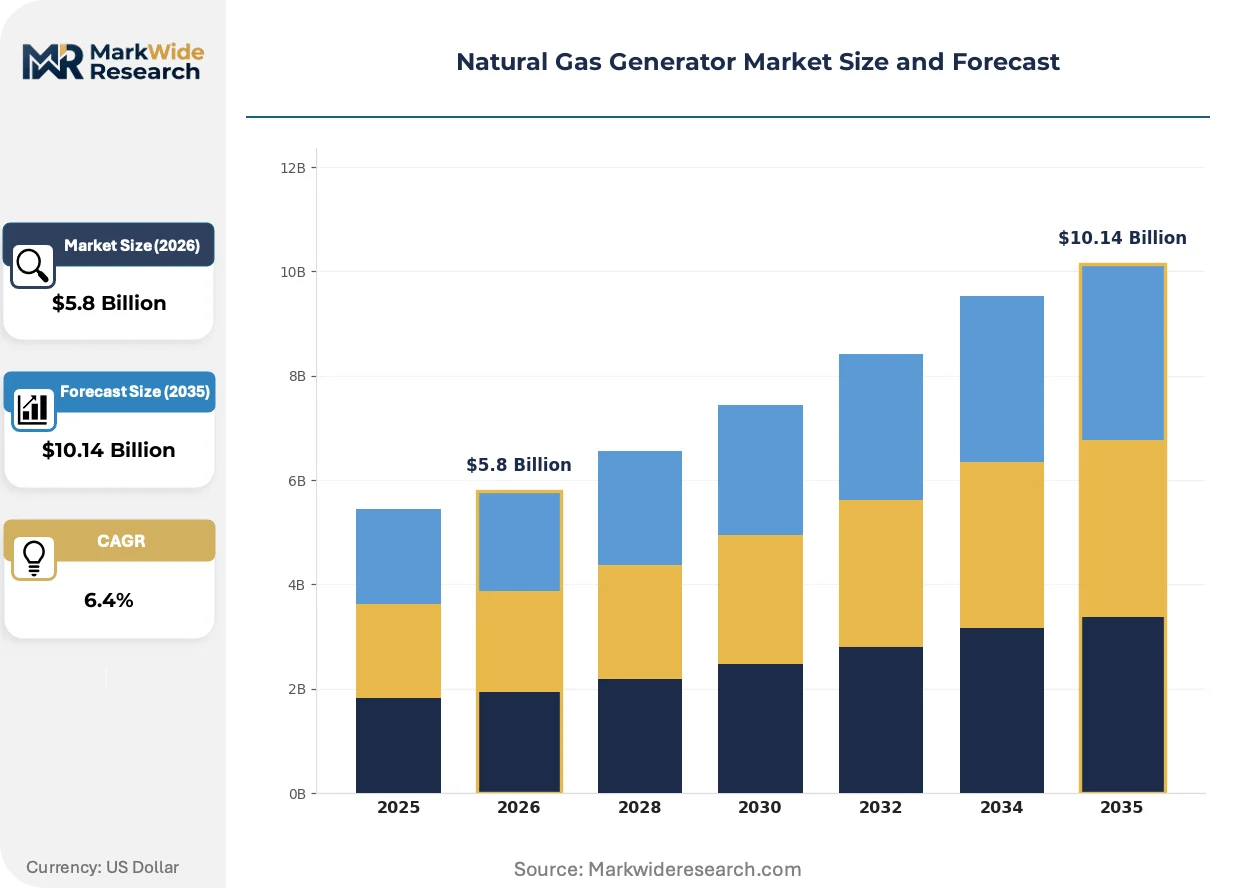
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Prime Power Generators, Continuous Power Generators, Peak Shaving Generators Technology: Reciprocating Engine, Gas Turbine, Microturbine, Combined Cycle, Stirling Engine Application: Telecommunications, Data Centers, Residential Backup, Commercial Facilities, Construction Sites, Agricultural Operations End User: Manufacturing Plants, Mining Companies, IT Companies, Educational Institutions, Municipal Facilities |
| Companies Covered | INNIO, GE Vernova, Caterpillar, MTU Onsite Energy, Kohler, Cummins, Siemens Energy, Himoinsa, Generac Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Gas Generator Market Strategic Shifts & Innovations
Technological evolution in the natural gas generator market is centered on enhancing efficiency, reducing emissions, and increasing operational flexibility. This is driving a shift from standalone hardware sales toward integrated, digitally managed power solutions.
Digital twin technology creates a dynamic, virtual replica of an in-service natural gas generator. Data center operators and industrial plant managers are adopting this for predictive maintenance and to optimize fuel consumption. This advanced modeling is virtualizing traditional asset management, enabling remote diagnostics and operational stress testing without impacting the physical unit.
The US Environmental Protection Agency's RICE NESHAP rules impose strict limits on emissions from stationary engines, including formaldehyde and carbon monoxide. This regulation mandates the use of advanced catalytic converters and after-treatment systems, increasing generator set complexity and cost. Operators in designated non-attainment areas face the most pressure, accelerating the replacement cycle for older, non-compliant equipment.
A significant shift in buyer behavior is the move from direct capital equipment purchases to power-as-a-service (PaaS) contracts. This model transfers the responsibility for maintenance, fuel management, and uptime from the end-user to the service provider, often the manufacturer or a specialized third party. The trend is most prominent among data centers and healthcare facilities, which prioritize operational reliability and predictable operating expenses over asset ownership.
Natural Gas Generator Market Segmentation
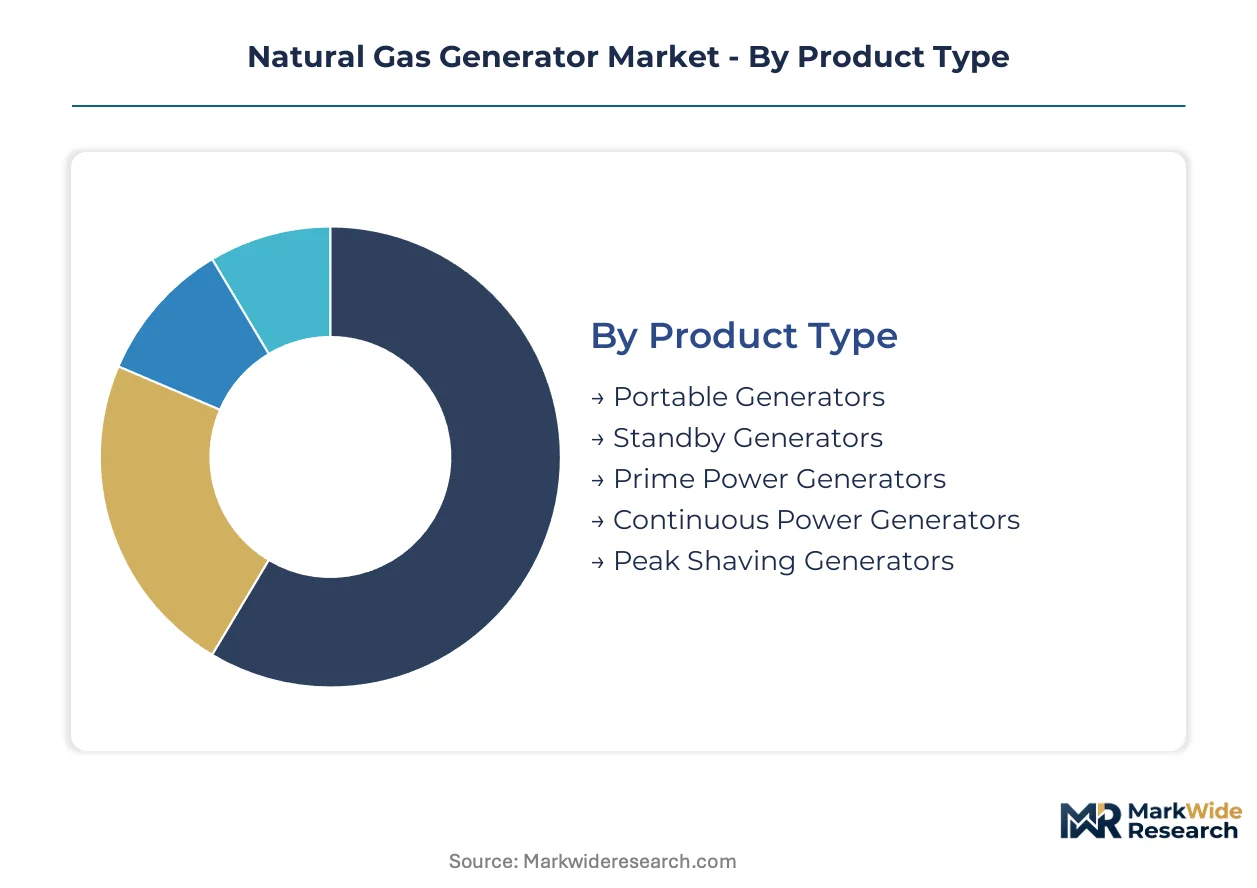
Analyzing the Natural Gas Generator Market through segmentation illuminates distinct demand patterns and technological preferences. This detailed breakdown helps identify specific growth pockets and competitive battlegrounds across various power requirements and end-use sectors. Understanding these segments is crucial for strategic product development and market entry decisions.
Product Type:
The market's product offerings span a comprehensive use-case spectrum, from intermittent backup to continuous prime power.
- Standby Generators:These units automatically activate during utility power outages, providing critical power to maintain essential operations. Demand concentrates in commercial facilities and data centers, driven by the imperative for operational reliability and continuous data processing.
- Prime Power Generators:Prime power generators supply electrical energy as the sole or primary source of power where grid infrastructure is absent or unreliable. Industrial growth and unreliable grids in sub-Saharan Africa create demand, supporting manufacturing plants and remote mining operations.
- Portable Generators:Portable generators offer flexible, temporary power solutions for smaller-scale applications like construction sites or residential emergencies.
- Continuous Power Generators:Continuous power generators provide constant, uninterrupted electrical supply for facilities requiring consistent energy availability.
- Peak Shaving Generators:Peak shaving generators operate during periods of high electricity demand, reducing utility costs for large industrial consumers.
Established volume favors Standby Generators; emerging adoption favors Prime Power Generators.
Technology:
Technological advancements differentiate offerings across various cost tiers and efficiency profiles.
- Reciprocating Engine:Reciprocating engines convert natural gas into mechanical energy via pistons, driving an alternator to produce electricity. Dominant across commercial and industrial backup applications due to their cost-effectiveness and operational flexibility across power outputs.
- Gas Turbine:Gas turbines generate power by combusting natural gas to spin a turbine, which then drives an electrical generator. Demand is strong in large-scale industrial facilities and utility peak power plants, valued for their high power output and continuous operation.
- Microturbine:Microturbines offer compact, low-emission power generation suitable for distributed energy and smaller commercial sites.
- Combined Cycle:Combined cycle systems enhance efficiency by recovering waste heat from gas turbines to generate additional electricity.
- Stirling Engine:Stirling engines utilize external heat sources to drive a closed-cycle regenerative heat engine, offering quiet and low-emission operation.
Efficiency gains are central to Combined Cycle installations while scalability defines Reciprocating Engine deployments.
Application:
The diverse application landscape dictates generator specifications based on reliability, scale, and operational environment.
- Data Centers:Natural gas generators provide critical standby power for data centers, ensuring continuous operation and data integrity during grid outages. Global data center expansion requires reliable backup solutions, with natural gas offering a cleaner alternative to diesel for mission-critical loads.
- Commercial Facilities:These applications include retail stores, office buildings, and hotels, requiring backup power for essential services and business continuity. Regulatory compliance and business interruption costs drive demand, particularly in regions with unstable grid infrastructure or high reliability expectations.
- Telecommunications:Telecommunications infrastructure relies on generators for uninterrupted power to maintain network connectivity.
- Residential Backup:Residential backup generators provide homeowners with emergency power during outages, protecting against property damage and inconvenience.
- Construction Sites:Construction sites utilize generators for temporary prime power, operating tools, lighting, and site offices in remote locations.
- Agricultural Operations:Agricultural operations employ generators for powering irrigation systems, climate control in livestock facilities, and processing equipment.
Reliability requirements are paramount for Data Centers, while operational flexibility is key for Construction Sites.
End User:
End-user segments define generator adoption based on their unique operational priorities and power consumption profiles.
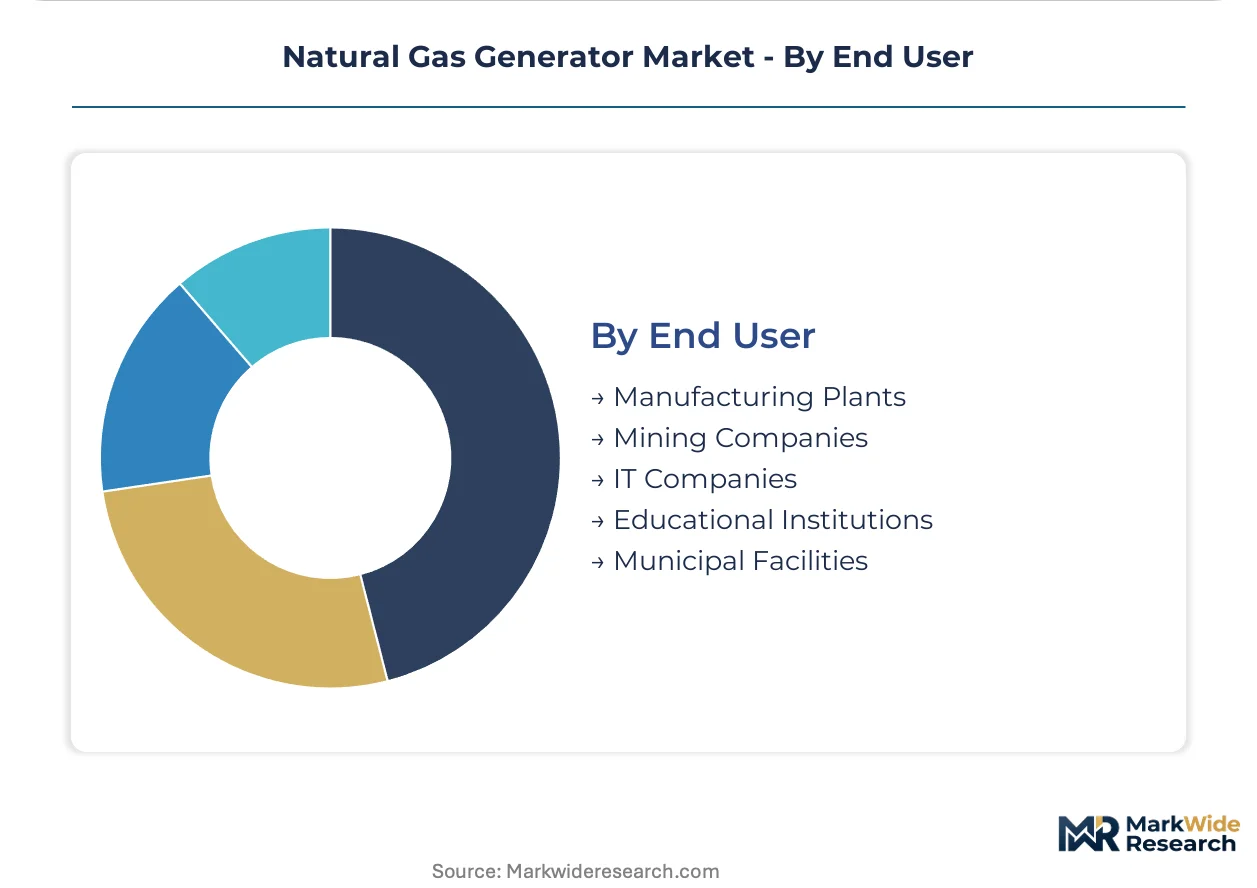
- Manufacturing Plants:These facilities require robust power systems for continuous production processes, preventing costly downtime and equipment damage. Industrial power needs in China and other rapidly industrializing economies drive demand for reliable prime and backup generation.
- IT Companies:IT companies, particularly those operating data centers, demand highly reliable and efficient power solutions to protect digital infrastructure. The expansion of cloud computing and digital services globally fuels this segment, prioritizing uptime and predictable operating expenses.
- Mining Companies:Mining companies deploy generators for remote site power, supporting extraction equipment and worker accommodations.
- Educational Institutions:Educational institutions use generators for backup power to maintain essential services like lighting, heating, and IT systems during outages.
- Municipal Facilities:Municipal facilities, including water treatment plants and emergency services, rely on generators for critical infrastructure resilience.
Investment decisions for Manufacturing Plants prioritize continuous operation, whereas Municipal Facilities focus on emergency preparedness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government policies promoting cleaner energy sources significantly influence the natural gas generator market's regional dynamics. These regulatory frameworks and national energy goals drive investment in compliant generation technologies. Demand patterns reflect localized industrial growth, grid infrastructure reliability, and environmental mandates across diverse geographies.
United States
United States demand for natural gas generators stems from expanding data center infrastructure and commercial facility backup needs. US EPA's RICE NESHAP rules impose strict emission limits on stationary engines, accelerating technology upgrades. Silicon Valley data centers and Texas industrial hubs upgrade to cleaner backup power solutions.
China
China's robust industrial power requirements and ambitious dual carbon goals stimulate significant demand for gas-fired generation. Compliance with China's GB standards dictates engine design and after-treatment systems for new installations. Yangtze River Delta manufacturing zones and Beijing's data center clusters prioritize compliant gas generation for continuous operations.
Germany
Germany's industrial sector prioritizes reliable power supply and adherence to stringent environmental performance standards. European Union directives on stationary power sources heavily influence product development for lower NOx emissions. The Ruhr Area's heavy industries and Frankfurt's financial data centers adopt efficient gas generator solutions for grid stability.
India
India's rapid infrastructure development and manufacturing plant expansion drive the need for consistent prime and backup power. The Central Electricity Authority (CEA) guides power generation policies, encouraging diverse energy sources. Maharashtra's industrial corridors and Bengaluru's IT parks install gas generators for uninterrupted production and operations.
South Africa
South Africa experiences strong demand for independent power solutions due to an unreliable national grid and industrial growth. The Department of Energy's policies encourage diversified power sources, including gas-fired generation, to enhance energy security. Gauteng province's mining operations and Cape Town's commercial facilities seek robust prime and standby power capacity.
Natural Gas Generator Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure for natural gas generators. The market sees a mix of large, integrated power solution providers and niche engine manufacturers. Strategic archetypes include global engine OEMs, regional assemblers, and service-focused providers. Competitive moves center on strategic partnerships for technology integration and portfolio diversification to capture new application segments.
Global power system manufacturers like Caterpillar and Cummins exemplify integrated solutions providers, offering extensive product lines and service networks across various power outputs. These companies often leverage their established brand presence and global dealer infrastructure to deliver comprehensive power-as-a-service models and financing solutions. Generac Power Systems, meanwhile, represents a specialized player focusing on diverse generator solutions for residential and commercial backup applications, emphasizing accessibility and ease of installation for a broader customer base. This differentiation allows players to capture distinct segments within the market, from large industrial clients to individual homeowners.
| Leading Market Players |
|---|
| INNIO |
| GE Vernova |
| Caterpillar |
| MTU Onsite Energy |
| Kohler |
| Cummins |
| Siemens Energy |
| Himoinsa |
| Generac Power Systems |
| Others |
Cost & Logistics Intelligence
Trans-oceanic shipping lanes' cost dynamics influence the natural gas generator market. These lanes connect concentrated component suppliers to global assembly points, impacting final product pricing and regional competitiveness.
Pricing Analysis
Emissions compliance certification creates the primary pricing spread in the natural gas generator market. Project-based pricing dominates, reflecting customization and installation complexity for large-scale systems. After-sales service bundling and power output scalability are significant price differentiation drivers. Pricing pressure stems from falling renewable energy costs in certain applications. Residential backup users are most price-sensitive, while data centers prioritize operational reliability over initial cost.
Supply Chain Analysis
Specialized component suppliers in Germany and Japan hold significant capacity for advanced turbochargers and fuel injectors. Geographic concentration for electronic control units also exists in China. The market depends on these critical components, including advanced turbochargers, fuel injectors, and electronic control units. Single-source vulnerability for these specialized parts presents a structural risk. Distribution primarily runs through established global dealer networks and direct OEM sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural gas generator market is a high-growth disruption, expanding significantly due to stringent global emissions regulations. This regulatory inflection demands cleaner combustion technologies and advanced after-treatment systems.
For Market Incumbents: Build a technological moat by accelerating hydrogen-ready engine development. Invest in advanced emissions control systems to meet tightening US EPA and EU directives. Expand power-as-a-service models leveraging existing global dealer networks. Renewable substitution and new entrants offering hybrid solutions threaten traditional market share.
For New Entrants and Emerging Players: Sub-Saharan Africa's underpenetrated industrial sector offers significant white-space for new entrants. Focus on prime power solutions for remote mining operations and manufacturing plants in regions with unreliable grids. Target compact microturbine applications for distributed energy. Offer integrated hybrid generator-storage systems with flexible financing.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrators of hybrid power solutions. Natural gas generators serve as a crucial bridge fuel during the energy transition, ensuring grid stability and backup power for critical infrastructure. Specialized component manufacturers for after-treatment systems or battery storage integrators represent attractive acquisition targets. The rate of adoption of power-as-a-service contracts by data centers is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Engine Development | Ensures long-term fuel flexibility and compliance with future decarbonization mandates for industrial clients. |
| Power-as-a-Service Expansion | Reduces capital outlays for end-users like data centers, shifting to predictable operational expenses. |
| African Market Expansion | Captures demand for reliable prime power in regions with developing infrastructure and unstable grids. |
| Hybrid Generator-Storage Integration | Enhances response times and efficiency, targeting critical facilities and grid service applications. |
| Advanced Emissions Control R&D | Addresses tightening US EPA and EU directives, maintaining market access for engine manufacturers. |
Research Approach
The analysis maps natural gas generator product types, technologies, and end-user applications, each validated through primary interviews with industry stakeholders. Data center operators, industrial plant managers, power utility planners, and engine component suppliers provided insights. US EPA regulations, EU directives, China's GB standards, and industry association reports informed market sizing. Bottom-up market sizing and top-down validation ensured data accuracy.
The forecast framework held regulatory environments and technological development trajectories fixed, while varying natural gas price volatility scenarios. A robust analytical framework projects market growth across the analysis window. Segmentation dimensions include product type, technology, application, end user, and regional economic growth. Compound annual growth rates derive from historical trends and projected market dynamics. Key inputs include global data center expansion rates and industrial electrification initiatives.
Practitioners should monitor shifts in global natural gas supply chains and accelerated renewable energy adoption for early signals of market revision. Forecasts reflect current assumptions regarding regulatory stability and technological readiness. Unforeseen geopolitical events or disruptive innovations could alter market trajectories. Quarterly review of energy policy changes and commodity price fluctuations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Railway Generators Market
Generators
Africa Portable Generator Market
Generators
Hand Crank Power Generator Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
Residential Gas Generator Market
Generators
Global Portable Generator Market
Generators
Southeast Asia Portable Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Marine Gensets Market
Generators
Africa Diesel Generator Market
Generators
Heat Recovery System Generator Market
Generators
Europe Diesel Generator Market
Generators
Gas Generator Sets Market
Generators
Europe Turbo Generator Market
Generators
Silent Generator Market
Generators
Construction Prime Power Generators Market