
 Industrial Solar Generator Market | 2026-2036
Industrial Solar Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Solar Generator Market Analysis
Aftermarket service revenue is narrowing toward predictive maintenance contracts and remote monitoring subscriptions as hardware margins compress. Tesla Energy leverages its vertically integrated battery supply chain to sustain cost leadership in utility-scale deployments. Caterpillar anchors its position through dealer network density and captive financing for construction and mining customers. Cummins differentiates via dual-fuel hybrid architectures that bridge diesel dependency gaps during solar intermittency.
An industrial solar generator converts photovoltaic energy into stored electrical power through lithium-ion or flow battery banks, delivering 5 kW to above 50 kW output for sites without grid access or requiring resilient backup. These systems integrate maximum power point tracking inverters with thermal management enclosures rated for dust, vibration, and temperature extremes encountered at construction sites and mining operations. Hybrid systems command the widest margin pools by combining solar generation with diesel or battery storage to guarantee continuous output during weather gaps. Portable generators represent the fastest-expanding category as telecom tower operators and emergency services prioritize rapid-deploy assets over permanent infrastructure. Fixed installations retain volume dominance across mining operations where decade-long asset lifecycles justify foundation-mounted arrays.
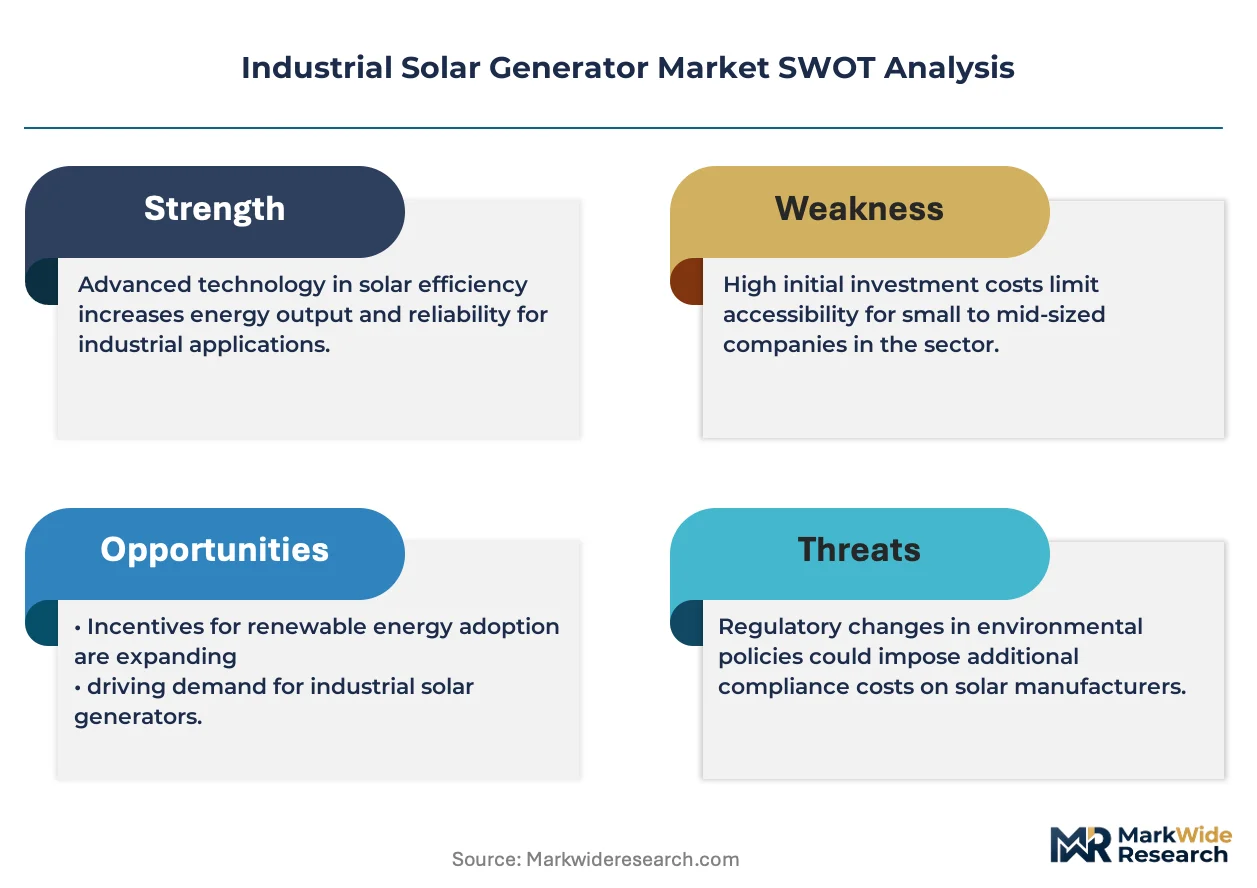
The US EPA and NHTSA coordinate emissions standards that indirectly accelerate diesel displacement at industrial facilities, while OSHA electrical safety regulations govern onsite installation protocols for temporary and permanent systems. The EU Green Deal and F-Gas Regulation constrain refrigerant choices in battery thermal management, forcing redesigns of cooling subsystems for European-bound equipment. Stakeholders must monitor how evolving grid interconnection standards in multiple jurisdictions reshape the economic case for hybrid versus standalone configurations.
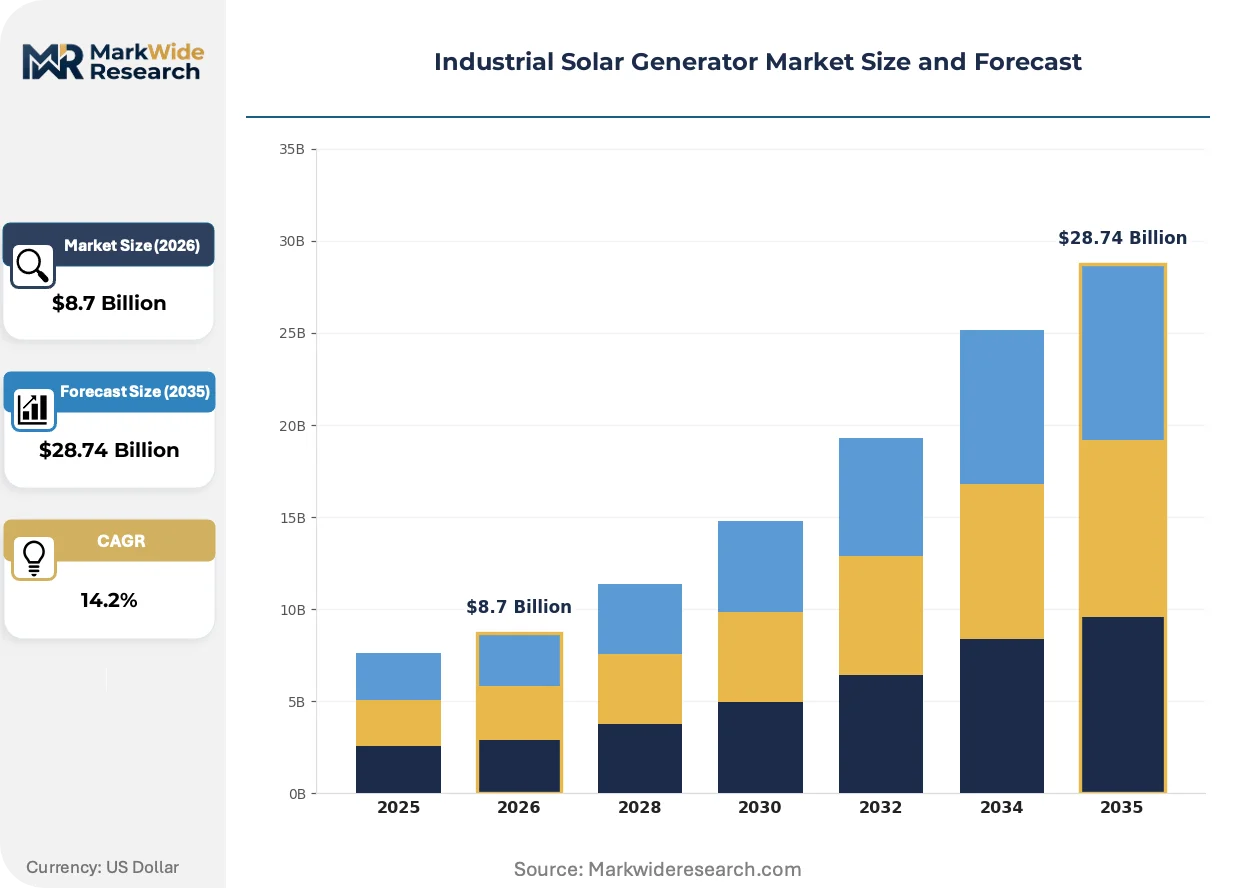
Market Dynamics
US Inflation Reduction Act production tax credits are redirecting capital toward domestic solar assembly, compressing import-dependent supply chains and reshaping competitive positioning among equipment suppliers.
Growth Catalysts
- Off-grid mining electrification:Australian extraction operations are expanding adoption of containerized solar-battery units for remote sites without transmission infrastructure.
- Factory backup power mandates:Germany's industrial Rhine-Ruhr corridor is concentrating demand for resilient generation to hedge grid instability.
- EPA-NHTSA emissions coordination:Tightening standards at US industrial facilities are accelerating diesel displacement in favor of hybrid solar configurations.
Market Restraints
- Lithium supply concentration:Battery cell production clusters in East Asia create input cost volatility and geopolitical exposure for generator manufacturers.
- F-Gas thermal management constraints:EU Green Deal refrigerant restrictions force cooling subsystem redesigns that extend European certification timelines.
- Diesel cost arbitrage:Persistently low fossil fuel prices in certain markets slow the economic case for full solar substitution at remote industrial sites.
Strategic Opportunities
- Telecom tower rapid-deploy:Portable generator categories are capturing emergency services and communications infrastructure buyers prioritizing speed over permanence.
- OSHA electrical safety compliance:Installation protocol mandates for temporary systems create certified service revenue streams for qualified deployers.
- Flow battery convergence:Vanadium redox technology paired with photovoltaic arrays opens long-duration storage applications beyond lithium-ion cycle limits.
Industry Challenges
- Grid interconnection standard fragmentation:Jurisdiction-specific technical requirements complicate hybrid system design for multi-national equipment suppliers.
- Electrical technician scarcity:Qualified installers for high-voltage DC-to-AC conversion at industrial scale remain concentrated in mature solar markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Solar Generator Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standalone Systems, Hybrid Systems, Fixed Installations End User: Construction Sites, Mining Operations, Telecommunication, Emergency Services Capacity: 5 kW, 10 kW, 20 kW, Above 50 kW Installation: Onsite, Offsite, Permanent, Temporary |
| Companies Covered | Caterpillar, Tesla Energy, Bluetti, Wärtsilä, Kohler, Jackery, Cummins, ABB, Generac Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Solar Generator Market Emerging Trajectories
Maximum power point tracking inverters with integrated thermal management are compressing system footprints. Equipment suppliers are racing to embed intelligence that anticipates load fluctuations before they occur.
Solid-state battery chemistry is rendering obsolete conventional lithium-ion thermal runaway risks in high-vibration mining environments. Australian extraction operators are piloting these systems at Pilbara iron ore sites. The technology is compressing insurance premiums and enabling underground deployment previously blocked by safety protocols.
EU F-Gas Regulation constraints on refrigerant choices are forcing battery cooling subsystem redesigns for European-bound equipment. Manufacturers must qualify alternative thermal fluids that maintain performance across Iberian summer peaks and Nordic winter troughs. German industrial buyers are accepting delivery delays of 6-9 months while suppliers recertify.
Telecom tower operators are unbundling generator procurement from long-term service contracts. Asset-heavy buyers now favor equipment-only purchases with third-party maintenance competition. This pattern is most visible across Southeast Asian markets where tower infrastructure is expanding fastest.
Industrial Solar Generator Market Segmentation
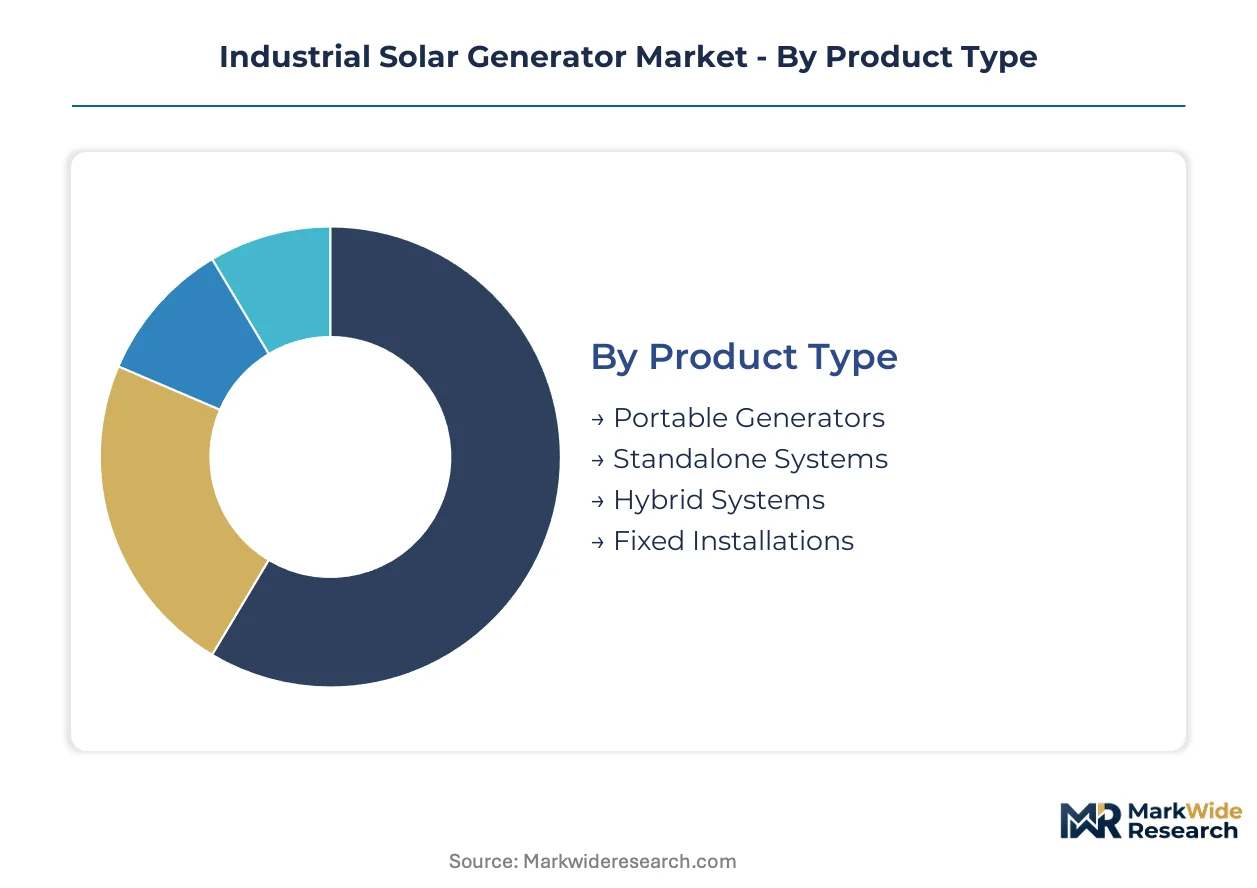
Industrial solar generator configurations span radically different operational environments, from decade-long mining deployments to emergency response scenarios measured in hours. Equipment specifications diverge sharply across these use cases, driving manufacturers toward modular platform architectures that can scale battery capacity, inverter rating, and enclosure durability without full redesign.
Product Type:
Deployment mobility defines the use-case spectrum, separating rapid-response assets from permanent infrastructure commitments.
- Hybrid Systems:These configurations combine photovoltaic arrays with diesel generation or battery storage to guarantee continuous output during weather intermittency. Mining operators in Australia's Pilbara region prioritize hybrid architectures for extraction sites where grid access remains economically unviable, accepting higher capital costs for operational certainty.
- Portable Generators:Containerized or skid-mounted units deliver 5-50 kW outputs deployable within hours without foundation work. Telecom tower operators across Southeast Asia favor these assets for rapid network expansion, unbundling procurement from long-term service contracts to enable third-party maintenance competition.
- Standalone Systems:Pure solar-battery configurations without fossil fuel backup suit sites with predictable load profiles and minimal weather risk exposure.
- Fixed Installations:Foundation-mounted arrays with decade-long asset lifecycles dominate mining operations where permanence justifies civil engineering investment.
The dominant share belongs to Fixed Installations, while Portable Generators are closing the gap fastest.
End User:
Customer archetypes cluster around tolerance for capital intensity versus urgency of deployment timelines.
- Mining Operations:Extraction companies demand 50 kW+ outputs with dust-rated enclosures and vibration-resistant battery mounting for decade-long asset cycles. Australian iron ore and lithium operations anchor volume, with OSHA electrical safety protocols governing high-voltage DC-to-AC installation at remote sites.
- Telecommunication:Tower infrastructure operators prioritize rapid-deploy units with remote monitoring capabilities for unmanned sites. Southeast Asian markets show fastest expansion as 5G rollout accelerates, with buyers accepting equipment-only purchases to enable competitive maintenance sourcing.
- Construction Sites:Temporary power needs during building phases favor rental models over ownership, compressing manufacturer margins toward service revenue.
- Emergency Services:Disaster response agencies require air-transportable units with immediate startup capability, driving specifications toward modularity over efficiency optimization.
Mining Operations command the largest revenue pool, though Telecommunication is expanding most quickly.
Capacity:
Power output tiers align with site scale and load criticality rather than simple wattage escalation.
- Above 50 kW:Utility-scale outputs serve extraction operations and industrial facilities with continuous baseload requirements. These systems integrate maximum power point tracking inverters with active thermal management, with German Rhine-Ruhr corridor factories driving demand for resilient backup against grid instability.
- 20 kW:Mid-range systems bridge commercial and light-industrial applications, often deployed as modular building blocks for scalable installations.
- 10 kW:Standard commercial outputs dominate construction site rental fleets and smaller telecom towers.
- 5 kW:Entry-level units serve emergency services and isolated instrumentation with minimal load profiles.
Above 50 kW retains volume leadership, while 20 kW configurations show steepest expansion trajectory.
Installation:
Site preparation requirements and asset permanence create distinct margin structures across deployment modes.
- Permanent:Foundation-mounted systems with grid interconnection hardware and fixed array positioning deliver lowest levelized cost over multi-decade horizons. These installations dominate mining and industrial backup applications where site control is assured.
- Temporary:Rapid-deploy configurations with minimal civil works suit construction phases and emergency response, generating higher service revenue intensity as redeployment cycles accelerate.
- Onsite:Integrated assembly at point of use reduces transport costs for oversized components but requires qualified electrical technician presence.
- Offsite:Factory-integrated containerized units minimize field labor and accelerate commissioning, preferred for remote locations with scarce technical workforce.
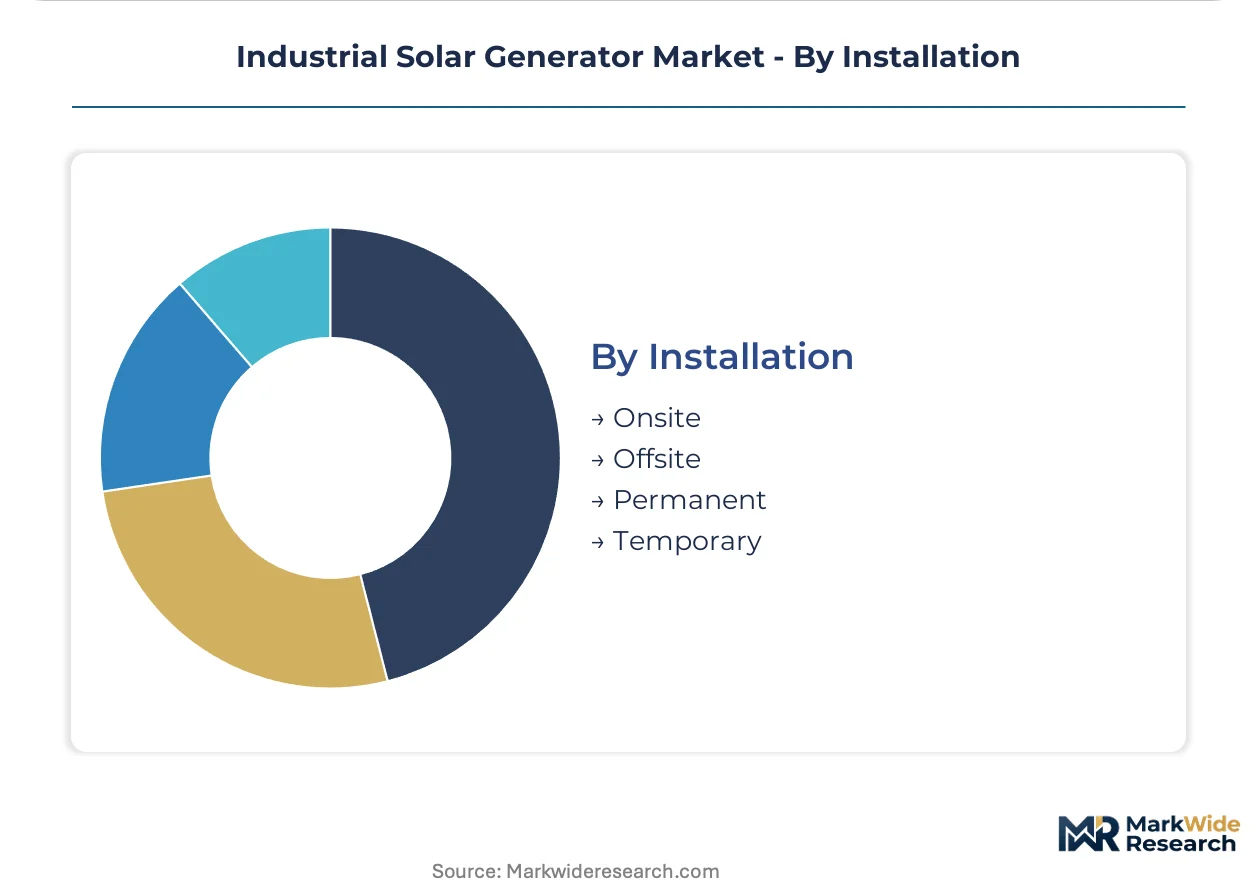
Permanent installations hold the dominant position, while Temporary deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian battery cell production clusters concentrate upstream supply for generator manufacturers, while Australian mining electrification and German industrial backup mandates anchor demand-side pull across three continents.
United States
Domestic solar assembly investments are accelerating under Inflation Reduction Act production tax credits, with EPA-NHTSA emissions coordination pressuring diesel displacement at industrial facilities. OSHA electrical safety protocols govern high-voltage DC-to-AC installation at remote construction and mining sites. Factory backup demand concentrates in Texas and California industrial corridors.
Germany
The Rhine-Ruhr industrial corridor is driving resilient generation procurement to hedge grid instability, with EU F-Gas Regulation constraints forcing battery cooling subsystem redesigns for European-bound equipment. German industrial buyers are accepting delivery delays while suppliers recertify alternative thermal fluids. Bavarian manufacturing clusters are piloting long-duration flow battery integrations.
Australia
Pilbara iron ore and lithium extraction operations are expanding containerized solar-battery adoption for off-grid sites without transmission infrastructure. Solid-state battery pilots are compressing insurance premiums and enabling underground deployment previously blocked by safety protocols. Western Australian mining camps anchor the largest fixed installation deployments.
China
Domestic dual carbon goals and MIIT industrial policy are redirecting capital toward integrated photovoltaic-battery manufacturing. GB standards for grid interconnection are reshaping hybrid system design for export-bound equipment. Yangtze River Delta production clusters supply maximum power point tracking inverters to global generator assemblers.
Industrial Solar Generator Market Vendor Landscape
Vertically integrated energy conglomerates and specialized power equipment fabricators split the market between captive supply chain control and distribution network density. The vendor base clusters around three strategic archetypes: battery-chemistry specialists leveraging upstream cell production, legacy engine manufacturers bridging diesel dependency through hybrid architectures, and industrial equipment distributors anchoring position through financing and service density. Competitive moves concentrate on backward integration into lithium supply and geographic expansion through dealer network licensing.
Among battery-chemistry specialists, Tesla Energy exemplifies vertical supply chain leverage, while Caterpillar anchors the legacy equipment fabricator tier through captive financing structures. Cummins occupies a bridging position within the hybrid-architecture segment. These three represent distinct strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Caterpillar |
| Tesla Energy |
| Bluetti |
| Wärtsilä |
| Kohler |
| Jackery |
| Cummins |
| ABB |
| Generac Holdings |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion feeds directly into landed cost spreads between containerized solar-battery units and fixed installation arrays, compressing margins for Australian mining buyers while amplifying price premiums for rapid-deploy configurations in Southeast Asian telecom markets.
Pricing Analysis
The US Inflation Reduction Act production tax credits dictate the pricing tier structure across domestic and import-dependent supply chains. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates OEM-integrated hybrid systems from dealer-assembled configurations. Pricing pressure stems from lithium cell cost volatility as East Asian production clusters adjust output. Construction site rental fleets exhibit highest price sensitivity, while German Rhine-Ruhr industrial buyers prioritize thermal management reliability over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates upstream risk calculus for generator manufacturers sourcing maximum power point tracking inverters. Battery cell production clusters in China, South Korea, and Japan anchor supply, with vanadium flow battery components drawing from Australian and South African mining operations. Single-source vulnerability concentrates in lithium hydroxide refining. Distribution runs through Caterpillar and Cummins dealer networks for mining and construction verticals, alongside direct OEM relationships for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial solar generator market represents a high-growth disruption as solid-state battery chemistry eliminates thermal runaway barriers to underground mining deployment, while EPA-NHTSA emissions coordination accelerates diesel displacement timelines.
For Market Incumbents: Pre-empt emerging solid-state specialists by securing exclusive pilot agreements with Pilbara iron ore operators before safety certification barriers fall. Deepen backward integration into lithium supply through offtake contracts with Western Australian spodumene producers. Anchor dealer financing structures against rental fleet competitors eroding construction site market share. For New Entrants and Emerging Players: Build out vanadium redox flow battery capabilities for German industrial buyers accepting delivery delays for F-Gas-compliant thermal management. Target Southeast Asian telecom tower operators unbundling procurement from service contracts. Lead with equipment-only pricing and third-party maintenance certification to bypass incumbent service density advantages. For Investors and Strategic Acquirers: Battery-chemistry specialists with captive cell production and mining safety certifications offer the strongest acquisition profile for long-term viability across the 5-10 year technology transition. Monitor OSHA electrical safety protocol expansions to temporary installations as the signal indicating service revenue inflection toward certified deployers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Supply | Secures Western Australian spodumene offtake against East Asian cell production volatility. |
| F-Gas-Compliant Thermal Redesign | Unlocks German Rhine-Ruhr corridor factory backup demand despite 6-9 month recertification delays. |
| Solid-State Battery Certification | Enables underground mining deployment previously blocked by lithium-ion thermal runaway protocols. |
| Third-Party Maintenance Certification | Captures telecom tower service revenue as Southeast Asian buyers unbundle procurement contracts. |
| Dealer Network Licensing Expansion | Replicates Caterpillar's captive financing model across emerging mining electrification markets. |
Methodological Framework
Desk research of customs trade databases, EIA power generation statistics, and FERC interconnection filings preceded structured interviews with mining operations managers, telecom infrastructure procurement leads, EPC contractors, and thermal management subsystem engineers. Primary fieldwork validated secondary assumptions through plant visits at Pilbara extraction sites and Rhine-Ruhr manufacturing facilities. Bottom-up unit economics modeling triangulated against top-down capacity installation forecasts across the analysis window.
Base-case assumptions held US Inflation Reduction Act credit levels and EU F-Gas refrigerant phase-out schedules fixed, while lithium carbonate price trajectories and grid instability frequency varied across sensitivity scenarios. Segmentation dimensions spanned product mobility tier, end-use vertical, capacity output band, and installation permanence classification. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in Australian mining electrification and German industrial backup procurement.
The forecast holds incumbent behavior within observed patterns; aggressive moves by solid-state battery specialists or vanadium flow battery integrators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
Residential Solar Generator Market
Power Generation
South Korea Combined Heat and Power Market
Power Generation
Gas Gensets Market
Power Generation
Distributed Power Generation Market
Power Generation
Commercial Gensets Market
Power Generation
Algeria Power Market
Power Generation
Europe Thermal Power Market
Power Generation
Marine Power Plant Market
Power Generation
Global Natural Gas Fired Electricity Generation Market
Power Generation
Indonesia Power Generation EPC Market
Power Generation
Asia-Pacific Distributed Power Generation Market
Power Generation
Global Electricity Ancillary Services Market
Power Generation
Global Power Grid System Market
Power Generation
Captive Power Plant Market
Power Generation
Ocean Thermal Energy Conversion Plant Market
Power Generation
Microturbine Market