
 Southeast Asia Portable Generator Market | 2026-2036
Southeast Asia Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Portable Generator Market Analytics
Indonesian manufacturing clusters is broadening the addressable base for portable power equipment. Honda Motor Co., Ltd leverages its established small-engine supply chain to dominate premium inverter segments across ASEAN distribution networks. Kirloskar Group anchors its position through diesel generator specialization tailored to construction and mining applications in the region. Atlas Copco competes on rental-service integration, bundling portable units with compressed-air systems for infrastructure contractors.
A portable generator is a self-contained internal-combustion or photovoltaic power unit, typically rated between 1 kW and 15 kW, designed to deliver alternating-current electricity at 220–240 V for off-grid or backup applications. The device serves commercial and industrial users requiring mobile, immediate power where grid connections are absent or unreliable. Gasoline-fueled conventional generators still occupy the largest revenue share due to lower first-cost barriers among price-sensitive Southeast Asian buyers. Inverter generators represent the fastest-expanding product category, as their total harmonic distortion below 3% protects sensitive electronics on construction sites and at outdoor events. Solar generators command premium positioning in remote archipelago markets where fuel logistics costs erode diesel economics.
Thailand's Pollution Control Department enforces tiered emissions certification for non-road engines, compelling manufacturers to redesign carburetion and exhaust systems for ASEAN entry. Indonesia's Ministry of Energy and Mineral Resources mandates efficiency labeling on generator imports, redirecting procurement toward certified inverter and dual-fuel models. Stakeholders must monitor how Vietnam's evolving construction safety codes specify on-site power redundancy, as this will determine fleet-upgrade cycles for rental companies and direct-purchase contractors alike.
Market Dynamics
Thailand's Pollution Control Department is tightening emissions certification for non-road engines, forcing manufacturers to redesign carburetion and exhaust systems for ASEAN entry while construction demand across Indonesia and Vietnam accelerates fleet expansion.
Growth Catalysts
- Inverter Technology Migration:Thailand's national environmental quality act mandates cleaner-burning equipment, redirecting procurement toward certified inverter models that deliver total harmonic distortion below 3% for sensitive electronics protection.
- Indonesia's Java-Bali Corridor:Persistent grid reliability gaps across industrial zones in this geographic concentration sustain baseline demand for mobile backup power among manufacturing clusters.
- Vietnam Construction Safety Codes:Evolving on-site power redundancy specifications are determining fleet-upgrade cycles for rental companies and direct-purchase contractors.
Market Restraints
- Fuel Logistics Costs:Remote archipelago markets face diesel delivery expenses that erode conventional generator economics and compress operating margins for fleet operators.
- Supply Concentration in Premium Segments:Established small-engine supply chains dominate inverter manufacturing, creating barriers for new entrants seeking ASEAN distribution access.
- First-Cost Sensitivity:Price-conscious Southeast Asian buyers continue favoring gasoline-fueled conventional generators despite higher lifetime operating costs.
Strategic Opportunities
- Solar Generator Positioning:Photovoltaic power units command premium placement in Indonesia's eastern islands where fuel logistics constraints eliminate diesel alternatives.
- Dual-Fuel Certification:Indonesia's Ministry of Energy and Mineral Resources efficiency labeling mandate redirects import flows toward certified dual-fuel models.
- Rental-Service Integration:Bundling portable units with compressed-air systems creates stickier relationships with infrastructure contractors seeking single-source equipment provisioning.
Industry Challenges
- Emissions System Redesign:Thailand's tiered certification requirements demand engineering resources for carburetion and exhaust modifications without guaranteed volume returns.
- Certification Timeline Compression:Multiple ASEAN jurisdictions operate parallel but non-harmonized efficiency and emissions standards, multiplying compliance verification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Portable Generator Market |
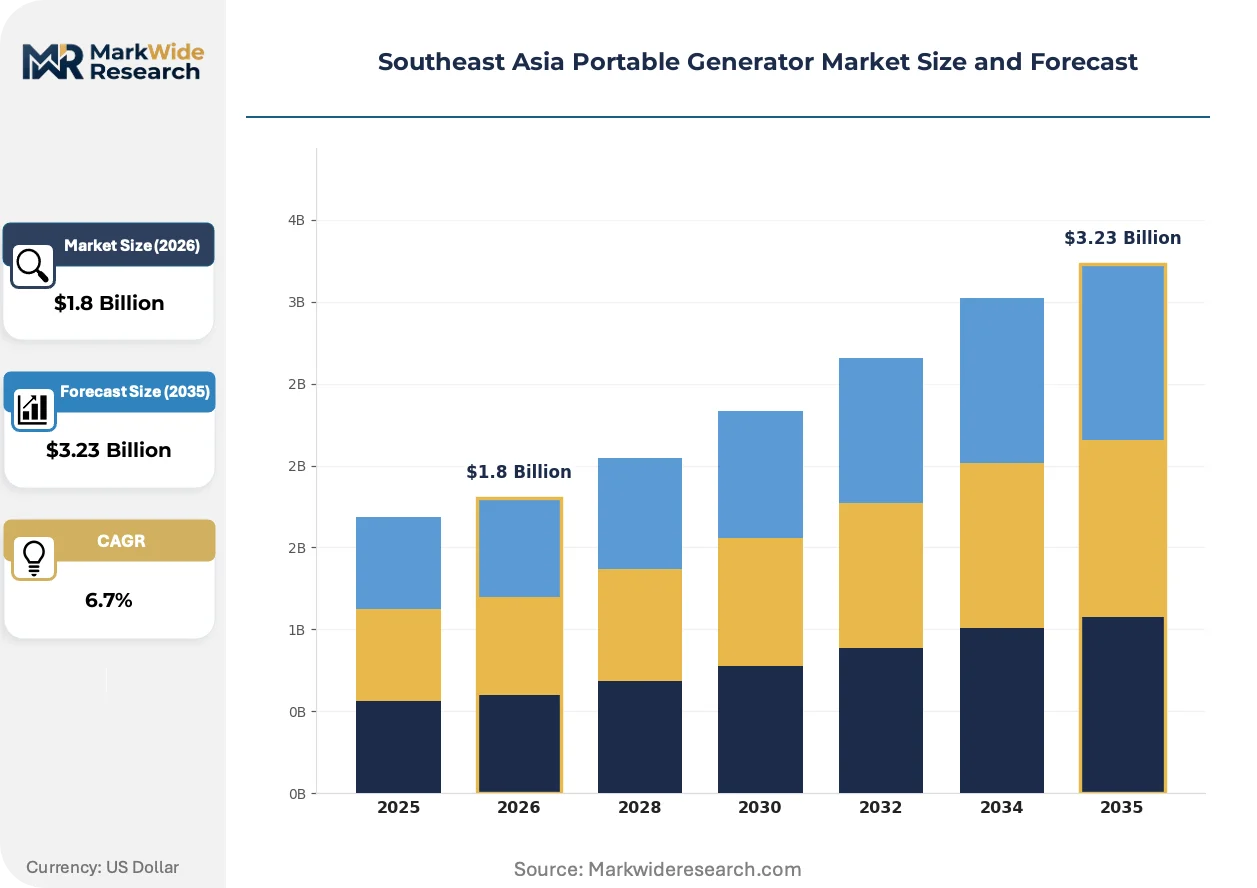
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverter Generators, Conventional Generators, Solar Generators, Dual Fuel Generators Application: Residential Use, Outdoor Events, Construction Sites, Emergency Backup Fuel Type: Gasoline, Diesel, Propane, Natural Gas End User: Households, Event Planners, Construction Companies, Emergency Services |
| Companies Covered | Honda Motor Co., Ltd, Atlas Copco, Caterpillar Inc, Kohler Power Systems, Briggs & Stratton Corporation, PRAMAC, HIMOINSA, Kirloskar Group, Generac Holdings Inc, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Portable Generator Market Evolving Landscape
Product architecture across Southeast Asia is bifurcating between legacy gasoline units serving price-sensitive segments and precision inverter systems capturing premium positioning through electronics protection capabilities.
Digital inverter control circuitry is absorbing voltage regulation functions previously handled by mechanical governors, enabling construction firms in Vietnam to deploy sensitive measurement equipment directly at remote worksites without secondary power conditioning. Equipment rental fleets are standardizing on these units to reduce customer claims from voltage spike damage. The technology is absorbing market share from conventional open-frame generators in applications below 5 kW.
Thailand's Pollution Control Department enforces tiered emissions certification for non-road engines, compelling manufacturers to redesign carburetion and exhaust systems for ASEAN entry. Industrial consequence includes accelerated phasing of uncertified inventory and redirected R&D spending toward fuel injection and catalytic after-treatment. Generator imports into Thailand now cluster in certified inverter and dual-fuel categories as uncertified conventional units face port-of-entry rejection.
Construction contractors across Indonesia are consolidating equipment procurement through rental-service providers rather than direct purchase, compressing ownership cycles and shifting maintenance responsibility upstream. Rental companies respond by expanding inverter-equipped fleets to capture safety-code-driven upgrades. This pattern concentrates most visibly in Java-Bali corridor industrial zones where grid instability coincides with concentrated infrastructure investment.
Southeast Asia Portable Generator Market Segmentation
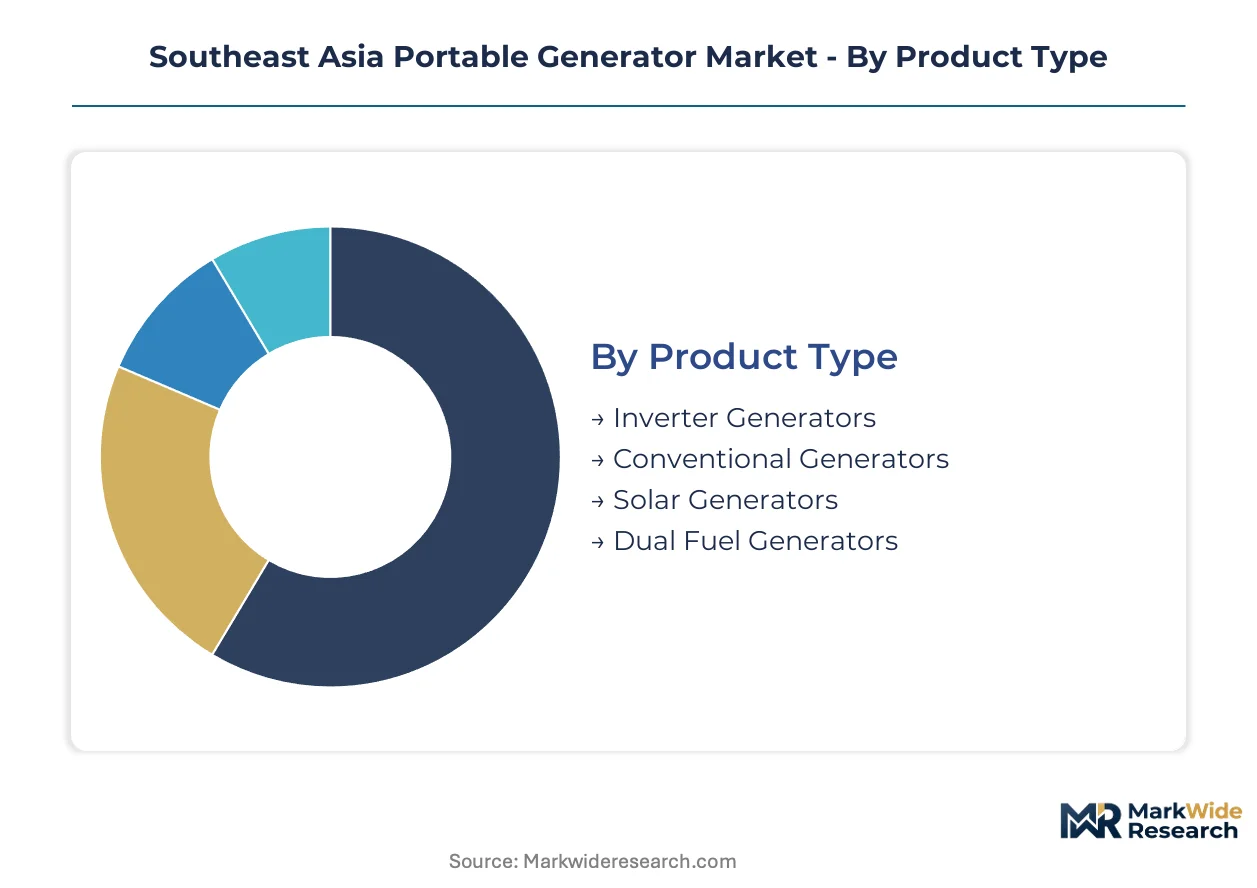
Portable generator procurement across Southeast Asia hinges on trade-offs between first-cost outlay, fuel accessibility, and emissions compliance. Buyers in Indonesia's manufacturing corridors and Thailand's regulated construction zones weigh these factors differently, fragmenting demand across distinct technical specifications and use cases.
Product Type:
Buyers prioritize harmonic distortion thresholds and emissions certification tiers when selecting portable power units for sensitive electronics or regulated job sites.
- Inverter Generators:Digital control circuitry maintains voltage stability within 3% total harmonic distortion, protecting measurement equipment deployed at remote Vietnamese construction sites. Thailand's Pollution Control Department tiered certification redirects procurement toward these cleaner-burning units across ASEAN industrial zones.
- Conventional Generators:Open-frame gasoline units deliver lower capital outlay for price-sensitive buyers, though higher lifetime operating costs erode total cost of ownership in high-utilization scenarios. Fleet operators in Indonesia's Java-Bali corridor still favor these for baseline backup power where electronics protection is secondary.
- Solar Generators:Photovoltaic power units with integrated battery storage eliminate fuel logistics entirely, commanding premium positioning in Indonesia's eastern archipelago markets where diesel delivery costs outweigh equipment price differentials.
- Dual Fuel Generators:Flexibility between gasoline and propane inputs hedges against fuel supply disruptions; Indonesia's Ministry of Energy and Mineral Resources efficiency labeling mandate accelerates import flows toward certified dual-fuel architectures.
Volume sits with conventional gasoline units; growth tilts toward inverter generators.
Application:
Site-specific power reliability requirements and regulatory exposure determine whether buyers seek intermittent backup or continuous prime power.
- Construction Sites:Vietnam's evolving safety codes specify on-site power redundancy, compelling fleet upgrades toward inverter-equipped rental units that protect sensitive instrumentation. Contractors in Indonesia's infrastructure corridors increasingly source through rental-service providers rather than direct purchase.
- Emergency Backup:Manufacturing clusters across Java-Bali deploy portable units as grid-failure insurance, with runtime duration and startup reliability outweighing fuel efficiency in procurement criteria.
- Residential Use:Urban households in grid-unstable zones prioritize compact footprint and noise suppression for backup lighting and appliance support during outages.
- Outdoor Events:Temporary power for festivals and exhibitions demands rapid deployment and low acoustic signature, favoring inverter units with enclosed casings.
Construction applications dominate absolute unit volume; emergency backup exhibits the steepest expansion trajectory as grid instability persists across industrial zones.
Fuel Type:
Logistics infrastructure density and emissions compliance horizons shape fuel selection across archipelago and mainland markets.
- Gasoline:Ubiquitous retail distribution and lower first-cost barriers sustain dominance among price-sensitive Southeast Asian buyers, particularly for intermittent residential and event applications.
- Diesel:Higher energy density and durability under continuous load attract construction and mining operators; Atlas Copco and Kirloskar Group anchor specialization in diesel generator rental fleets for heavy-duty infrastructure contracts.
- Propane:Cleaner combustion profile aligns with Thailand's tightening emissions standards, though cylinder distribution networks remain thinner than liquid fuel retail.
- Natural Gas:Pipeline-connected stationary installations in urban Thailand and Vietnam offer lowest operating cost, but portability constraints limit adoption to semi-permanent site power.
Gasoline retains the broadest addressable base; diesel concentrates in commercial fleet ownership.
End User:
Capital deployment models and technical sophistication diverge sharply between institutional procurement and individual purchase.
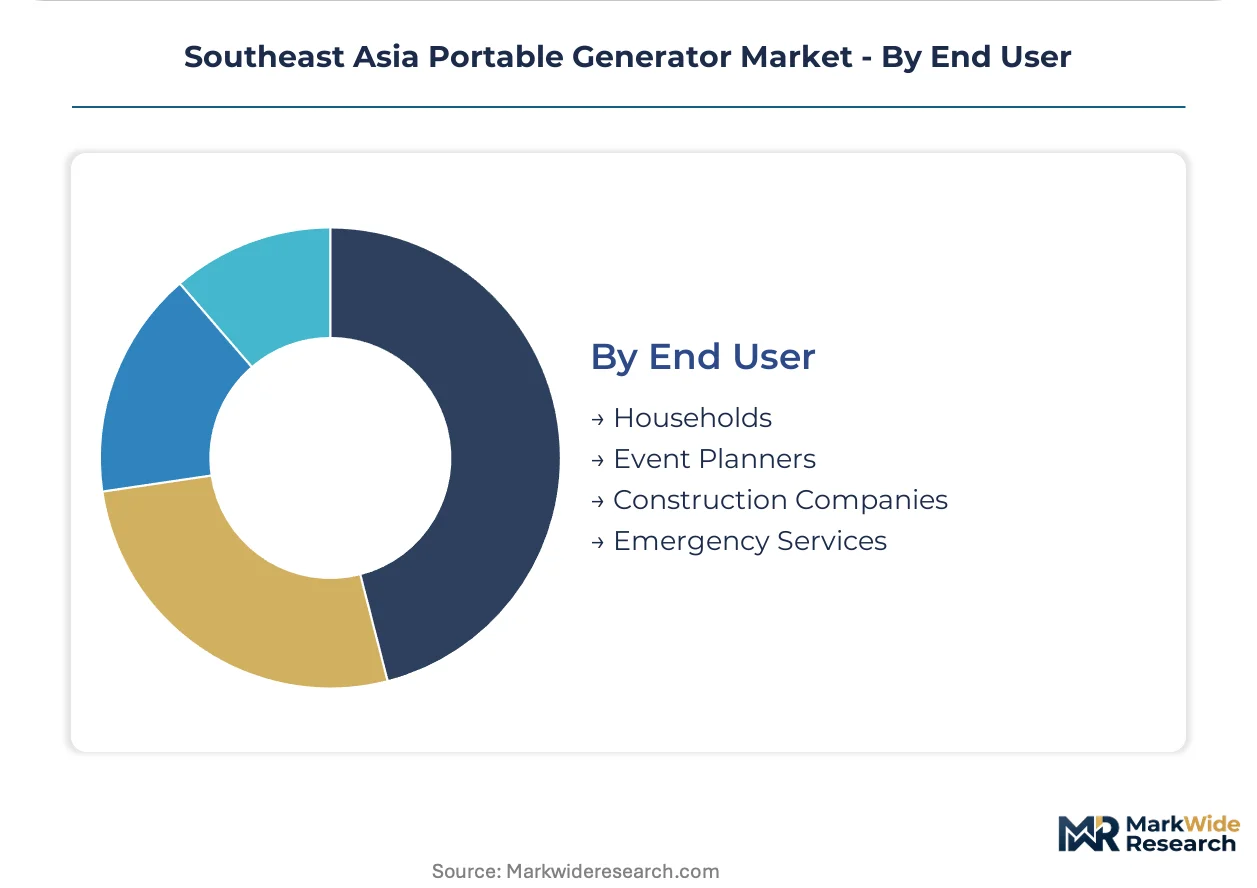
- Construction Companies:Consolidated equipment procurement through rental-service providers compresses ownership cycles and shifts maintenance responsibility upstream; fleet standardization on inverter units accelerates under safety-code pressure.
- Households:Individual buyers prioritize first-cost minimization and local service availability, sustaining conventional generator demand despite lifetime cost disadvantages.
- Event Planners:Acoustic compliance and rapid deployment requirements drive specification toward enclosed inverter units for outdoor entertainment power.
- Emergency Services:Reliability certification and instantaneous startup capability dominate procurement, with redundant fuel systems and extended runtime as mandatory specifications.
Construction companies generate the highest revenue per account; emergency services impose the most stringent technical requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's nickel processing belt and Thailand's automotive component corridors anchor portable generator demand across Southeast Asia, with fuel logistics networks and emissions enforcement creating divergent procurement patterns between archipelago and mainland markets.
Indonesia
Java-Bali manufacturing clusters sustain baseline demand for mobile backup power where grid reliability gaps persist across industrial zones. The Ministry of Energy and Mineral Resources mandates efficiency labeling on generator imports, redirecting procurement toward certified inverter and dual-fuel models. Surabaya's construction equipment rental hubs are consolidating fleet procurement through service providers rather than direct purchase.
Thailand
Construction contractors and outdoor event operators drive specification toward low-emission inverter units under tightening environmental standards. The Pollution Control Department enforces tiered emissions certification for non-road engines, compelling carburetion and exhaust system redesigns for ASEAN market entry. Bangkok's infrastructure rental companies are expanding inverter-equipped fleets to capture safety-code-driven upgrades.
Vietnam
Expanding equipment fleets support national infrastructure builds across northern and central provinces. Evolving construction safety codes specify on-site power redundancy, determining fleet-upgrade cycles for rental companies and direct-purchase contractors. Ho Chi Minh City's industrial zones exhibit concentrated demand for electronics-protecting inverter generators at remote worksites.
Philippines
Island geography and fuel logistics constraints elevate solar generator economics in remote archipelago markets. The Department of Energy promotes distributed generation alternatives through rural electrification programs. Cebu and Davao manufacturing corridors deploy portable units as grid-failure insurance against frequent outage events.
Malaysia
Peninsular industrial zones and Borneo resource extraction operations create bifurcated demand between grid-connected backup and off-grid prime power. The Sustainable Energy Development Authority incentivizes cleaner-burning equipment through efficiency certification schemes. Johor's construction corridors are standardizing procurement through rental-service integration models.
Southeast Asia Portable Generator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solar-digital hybrid positioning and rental-service bundling. The vendor base stratifies between legacy small-engine specialists and precision electronics fabricators, with technology licensing and geographic expansion as dominant competitive moves. Consolidation pressure concentrates in premium inverter segments where supply chain scale advantages create entry barriers.
Within the established-engine tier, Honda Motor Co., Ltd and Kirloskar Group exemplify divergent specialization strategies. Honda occupies a position representing premium inverter manufacturing leverage through ASEAN distribution networks. Kirloskar anchors diesel generator specialization for construction and mining applications. Atlas Copco sits within the rental-service integration archetype, bundling portable units with compressed-air systems.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd |
| Atlas Copco |
| Caterpillar Inc |
| Kohler Power Systems |
| Briggs & Stratton Corporation |
| PRAMAC |
| HIMOINSA |
| Kirloskar Group |
| Generac Holdings Inc |
| Others |
Value Network & Pricing Analysis
Construction equipment rental companies across Indonesia's Java-Bali corridor concentrate procurement volumes, forcing manufacturers toward contract-based pricing with bundled maintenance terms rather than transactional spot sales.
Pricing Analysis
Warranty and service bundling separates premium inverter offerings from unbundled conventional gasoline units. Pricing stratifies across certified inverter, dual-fuel, and open-frame economy tiers, with Thailand's emissions certification requirements driving differentiation by regulatory compliance grade. Cost compression in conventional segments intensifies as first-cost sensitivity persists among Indonesian household buyers. Fleet operators exhibit lowest price sensitivity due to total cost of ownership calculations, while individual residential purchasers prioritize capital outlay minimization.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Singapore and Bangkok as regional hub-and-spoke nodes serving archipelago markets. Manufacturing draws from China, Japan, and Thailand for small-engine components, copper windings, and electronic control modules. Single-source vulnerability in semiconductor-based inverter controllers creates exposure to foundry capacity constraints. Distribution runs through authorized dealer networks and rental-service integrators rather than direct retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's tiered emissions certification functions as a consolidation mechanism, eliminating uncertified manufacturers unable to fund carburetion and exhaust system redesigns.
For Market Incumbents: Acquire rental-service provider relationships to lock in fleet procurement channels. Honda Motor Co., Ltd and Kirloskar Group should expand inverter manufacturing capacity in Thailand to capture safety-code-driven upgrade cycles. Defensive positioning requires certification investment ahead of Vietnam's evolving construction safety codes. For New Entrants and Emerging Players: Enter via solar-digital hybrid positioning in Indonesia's eastern archipelago markets where fuel logistics costs eliminate diesel competition. Photovoltaic power units with integrated battery storage represent the most penetrable white-space segment. Go-to-market execution should prioritize direct relationships with nickel processing belt operators seeking off-grid prime power. For Investors and Strategic Acquirers: The window for entry favors vertically integrated small-engine specialists with established ASEAN distribution footprints. Long-term viability hinges on regulatory compliance capabilities across multiple jurisdictions. Watch Indonesia's Ministry of Energy and Mineral Resources efficiency labeling enforcement intensity as the inflection signal for import flow redirection toward certified architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Emissions Certification Investment | Thailand's Pollution Control Department tiered requirements determine port-of-entry acceptance for ASEAN markets. |
| Rental-Service Integration | Bundling portable generators with compressed-air systems creates stickier relationships with infrastructure contractors. |
| Inverter Manufacturing Scale-Up | Digital control circuitry production absorbs voltage regulation functions previously handled by mechanical governors. |
| Dual-Fuel Architecture Development | Indonesia's efficiency labeling mandate redirects import flows toward certified gasoline-propane flexibility. |
| Solar Generator Market Entry | Photovoltaic power units command premium positioning in remote archipelago markets where diesel logistics costs erode economics. |
Research Methodology
Multi-period observation of import certification volumes, fleet procurement patterns, and emissions compliance timelines anchored the trend analysis, supplemented by interviews with equipment rental fleet managers, construction procurement officers, aftermarket service heads, and regulatory affairs specialists at ASEAN ministries. Secondary validation drew from customs trade databases, national environmental quality act filings, efficiency labeling registries, and equipment manufacturer SEC disclosures. Bottom-up channel checks triangulated against top-down market sizing.
Segment-weighting applied product type, application, fuel category, and end-user archetype dimensions across the projection horizon. CAGRs derived from regression analysis of historical fleet expansion rates against infrastructure investment pipelines. Modeled inputs included grid reliability indices by industrial zone, construction safety code evolution timelines, and fuel logistics cost differentials across archipelago versus mainland markets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory timeline acceleration or commodity price volatility in copper and rare-earth magnet inputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Saudi Arabia Diesel Generator Market
Generators
India Generator Sets Market
Generators
Halogenerator Market
Generators
Generator Sets Market
Generators
Nuclear Turbine Generators Market
Generators
South America Gas Generator Market
Generators
Middle East Portable Generator Market
Generators
Generator (Up to 20 Kva) Market
Generators
Mobile Generators Market
Generators
India Portable Generator Market
Generators
Industrial Generator Market
Generators
United States Portable Generator Market
Generators
Gas Generator Sets Market
Generators
Dual-Fuel Generator Market
Generators
Power Generator Rental Market
Generators
United States Diesel Generator Market