
 Africa Diesel Generator Market | 2026-2036
Africa Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Diesel Generator Market Outlook
Tier-4 equivalent emission compliance is rotating demand toward higher-specification prime power units across African installations. Cummins Inc. leverages its extensive service network to sustain aftermarket revenue across East African mining corridors. Caterpillar Inc. anchors large-scale project supply through its dealer infrastructure in South Africa and Nigeria. AKSA Power Generation competes on cost-optimized manufacturing scale, positioning its Turkish production base for sub-Saharan distribution.
A diesel generator converts mechanical energy from compression-ignition engines into electrical output, typically operating at 50 Hz across African grids with power ratings spanning 5 kVA to 3,000 kVA for industrial applications. These units provide critical backup and prime power where centralized grid infrastructure remains unreliable or absent. Industrial generators dominate capital deployment across mining and manufacturing installations, while standby generators capture commercial and healthcare facilities requiring automatic transfer switch integration. Portable generators serve construction and event rental channels with lower entry costs but thinner margins. The diesel fuel type segment retains overwhelming share despite biofuel pilot programs, driven by fuel availability and energy density requirements for continuous operation.
South Africa's National Regulator for Compulsory Specifications enforces SANS standards on generator emissions and safety, while Nigeria's Standards Organisation of Nigeria mandates product conformity for import clearance. Kenya's Energy and Petroleum Regulatory Authority imposes noise and emission limits on commercial generator installations in urban zones. Stakeholders must monitor evolving carbon border adjustment discussions in European trading partner jurisdictions, as these could redirect African manufacturing investment toward cleaner on-site power solutions.
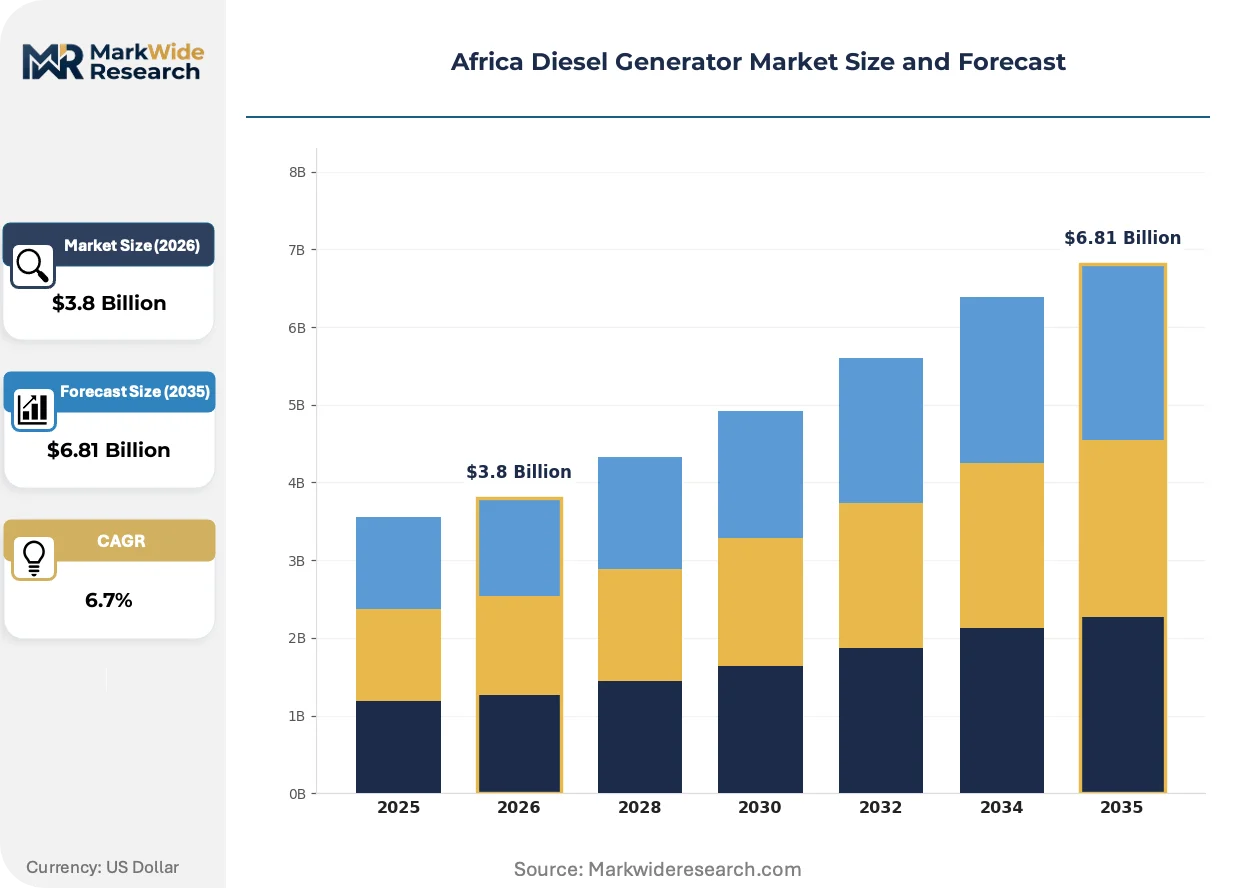
Market Dynamics
Grid instability across sub-Saharan mining belts is forcing industrial operators to treat diesel generators as primary power infrastructure rather than emergency backup, restructuring capital allocation toward higher-specification prime power units with extended duty cycles.
Growth Catalysts
- SANS Emission Standards:South Africa's enforcement of stationary engine emission limits is accelerating fleet replacement toward Tier-4 equivalent technologies, creating equipment refresh cycles across industrial estates.
- Copper-Cobalt Belt Expansion:Mining operations in Zambia and the Democratic Republic of Congo are scaling captive power installations as electrification lags behind extraction timelines.
- Hybrid Integration:Solar-diesel hybrid architectures are penetrating Nigerian manufacturing clusters, reducing fuel consumption while maintaining production continuity during grid failures.
Market Restraints
- Diesel Price Volatility:Fuel import dependencies and currency fluctuations across Nigeria and Kenya are compressing operating margins for continuous-run installations.
- Import Duty Structures:Nigeria's Standards Organisation of Nigeria conformity assessment adds clearance friction and cost layering for non-assembled generator imports.
- Grid Extension Programs:Rural electrification initiatives in Tanzania and Ethiopia are deferring commercial generator procurement in peri-urban zones.
Strategic Opportunities
- Mozambique LNG Corridor:Offshore gas development and associated infrastructure construction is generating demand for mobile and prime power units in previously underpenetrated territory.
- Rental Channel Formalization:Construction and event sectors in Ghana are shifting from informal equipment sourcing toward contracted rental providers with maintenance bundling.
- Carbon Border Adjustment Alignment:European trading partner emission protocols are incentivizing cleaner diesel technologies for export-oriented manufacturing in South Africa.
Industry Challenges
- Certification Bottlenecks:Kenya's Energy and Petroleum Regulatory Authority noise and emission testing timelines are extending deployment schedules for urban commercial installations.
- Technical Skill Scarcity:Electronic engine management and aftertreatment system maintenance expertise remains concentrated in South Africa and Nigeria, constraining service reach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Diesel Generator Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Inverter Generators, Industrial Generators End User: Residential, Commercial, Industrial, Healthcare Fuel Type: Diesel, Biofuel, Natural Gas, Others Installation: Onsite, Offsite, Semi-permanent, Temporary |
| Companies Covered | Caterpillar Inc., Cummins Inc., Atlas Copco AB, Aggreko PLC, AKSA Power Generation, Kohler Co., HIMOINSA, Wärtsilä Corporation, Perkins Engines Company Limited, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Diesel Generator Market Strategic Shifts
Digital load management and predictive maintenance platforms are reconfiguring how African operators optimize generator runtime, shifting value capture from hardware margins toward service attach rates and fuel efficiency guarantees.
Variable speed generator technology is decomposing the traditional fixed-speed diesel architecture across prime power applications. Mining operators in the Copperbelt are piloting electronically governed engines that modulate RPM against load demand. This compression of fuel consumption curves is decomposing the historical trade-off between capital cost and operating expense in large-scale installations.
Kenya's Energy and Petroleum Regulatory Authority urban noise limits are forcing acoustic enclosure redesigns and exhaust aftertreatment retrofits. Industrial facilities within Nairobi's metropolitan zone face mandatory decibel compliance inspections before operational permits renew. Healthcare and data center segments are responding by specifying factory-integrated low-noise packages rather than field-modified standard units.
Buying committees at Nigerian manufacturing conglomerates are consolidating supplier relationships and demanding outcome-based performance contracts with guaranteed uptime clauses. Long-tenured distributor networks with spare parts inventories are displacing transactional equipment brokers in the Lagos-Ibadan corridor. This concentration of procurement authority is most visible among textile and food processing clusters where production losses from power interruption carry severe contract penalty exposure.
Africa Diesel Generator Market Segmentation
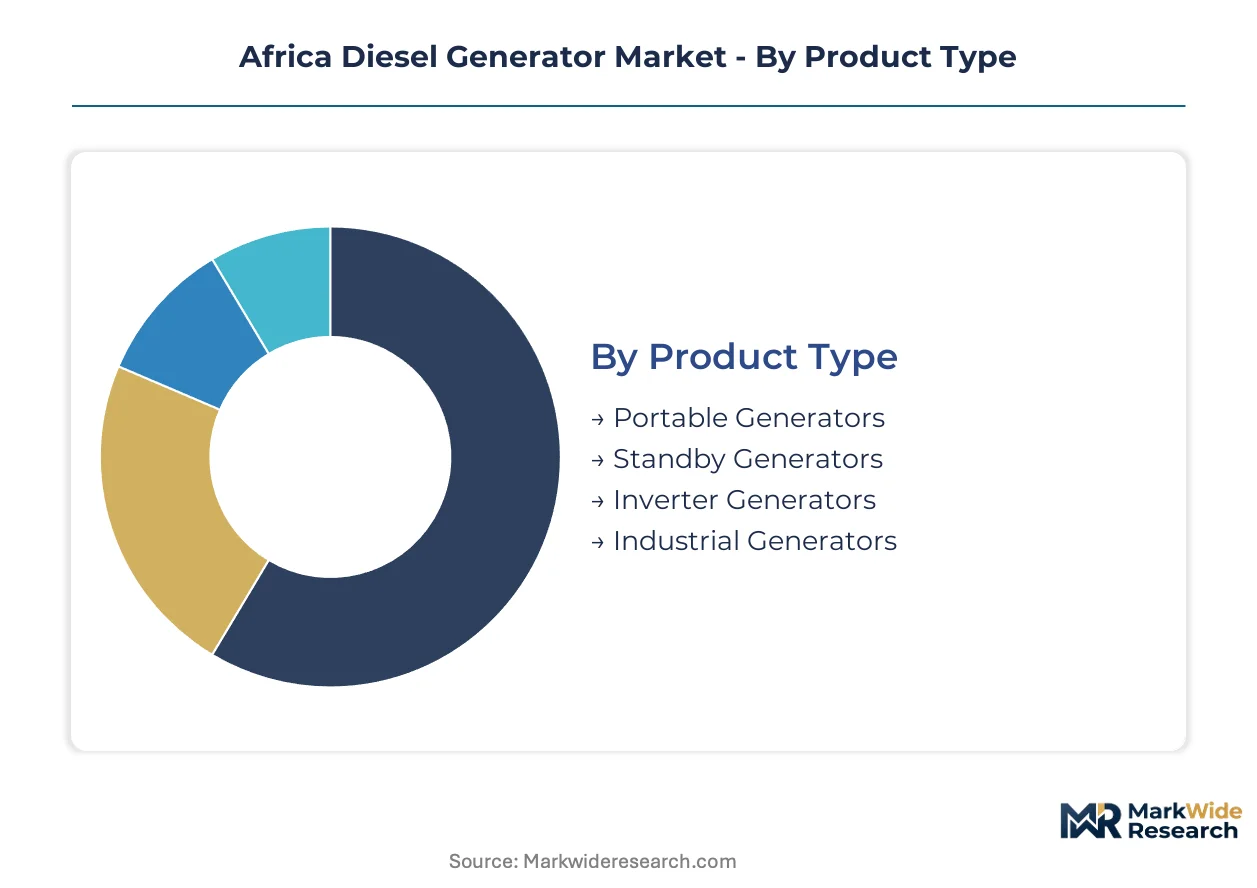
Generator procurement across Africa fragments sharply by duty cycle and capital intensity. Mining operators in the Copperbelt and manufacturing clusters in Nigeria's industrial corridor drive specification divergence that reshapes supplier positioning.
Product Type:
South Africa's SANS emission standards and Kenya's urban noise regulations are forcing specification upgrades that favor electronically governed architectures over mechanical systems.
- Industrial Generators:Compression-ignition engines rated 500 kVA to 3,000 kVA with extended duty cycles and integrated aftertreatment. Mining operations in Zambia and the Democratic Republic of Congo deploy these as prime power infrastructure where grid extension lags extraction timelines by years.
- Standby Generators:Automatic transfer switch integration enables sub-10-second failover for critical loads. Healthcare facilities in Nigeria's Lagos-Ibadan corridor and data centers in South Africa specify these for production continuity guarantees.
- Portable Generators:Construction and event rental channels in Ghana favor mobile units with lower entry costs but thinner margins.
- Inverter Generators:Electronic voltage regulation suits sensitive equipment loads in commercial installations.
Industrial generators handle the majority of throughput; inverter generators are gaining share fastest on precision power requirements.
End User:
Customer procurement authority concentrates differently across sectors — mining houses centralize fleet decisions while healthcare facilities delegate to engineering consultants.
- Industrial:Manufacturing clusters and extractive operations with 24/7 load profiles. Nigeria's textile and food processing sectors demand outcome-based performance contracts with guaranteed uptime clauses.
- Healthcare:Hospitals and clinics requiring life-safety power backup. Kenya's metropolitan facilities face mandatory decibel compliance inspections before operational permit renewal.
- Commercial:Retail and office installations with intermittent duty cycles.
- Residential:Individual households and small estates with sub-50 kVA requirements.
Industrial end users absorb the dominant share of capital deployment; healthcare represents the steepest expansion trajectory on regulatory mandates.
Fuel Type:
Energy density and supply chain reliability override sustainability preferences in procurement committees.
- Diesel:Dominates African installations due to fuel availability infrastructure and compression-ignition efficiency for continuous operation. Biofuel pilot programs in South Africa remain marginal against established supply chains.
- Natural Gas:Mozambique's offshore development creates localized opportunity for gas-fired prime power.
- Biofuel:Blending programs face cold-flow challenges in highland climates.
- Others:Dual-fuel and hybrid architectures penetrating Nigerian manufacturing clusters.
Diesel retains overwhelming share; natural gas climbs fastest where pipeline infrastructure coincides with demand.
Installation:
Deployment duration and mobility requirements determine enclosure specifications and foundation investments.
- Onsite:Permanent concrete pad installations with acoustic enclosures. Nairobi's metropolitan zone mandates factory-integrated low-noise packages rather than field modifications.
- Temporary:Mobile skid-mounted units for construction phases. Mozambique's LNG corridor generates demand in previously underpenetrated territory.
- Semi-permanent:Containerized systems with rapid redeployment capability.
- Offsite:Rental fleet positioning for emergency response.
Onsite installations anchor capital commitment; temporary deployment expands most quickly on infrastructure project cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African generator exports supply mining operations across the Copperbelt, while Turkish and UAE-based distributors channel equipment into West African industrial corridors.
South Africa
Platinum and gold mining houses in Rustenburg and Welkom deploy prime power units as grid instability forces 24/7 captive generation. The National Regulator for Compulsory Specifications enforces SANS emission standards that accelerate fleet replacement toward Tier-4 equivalent technologies. The Richards Bay industrial zone and Johannesburg manufacturing belt drive specification upgrades for electronically governed architectures.
Nigeria
Textile and food processing clusters in the Lagos-Ibadan corridor demand outcome-based performance contracts with guaranteed uptime clauses. The Standards Organisation of Nigeria mandates product conformity assessment for import clearance, adding cost layering to procurement timelines. Kano's cement plants and Port Harcourt's petrochemical facilities consolidate supplier relationships around long-tenured distributor networks with spare parts inventories.
Zambia
Copper extraction operations in the Copperbelt treat diesel generators as primary power infrastructure rather than emergency backup as electrification lags extraction timelines. The country's energy regulator imposes noise limits on commercial installations near urban centers. Kitwe and Ndola mining corridors scale captive power installations to match production expansion schedules.
Democratic Republic of Congo
Cobalt and copper mining in Kolwezi and Lubumbashi requires extended-duty-cycle prime power units for remote extraction sites. The national electricity utility's grid extension delays force industrial operators to restructure capital allocation toward higher-specification equipment. South Kivu's tin mining belt and Katanga's industrial mining zone concentrate demand for mobile and semi-permanent installations.
Kenya
Healthcare facilities and data centers in Nairobi face mandatory decibel compliance inspections before operational permit renewal. The Energy and Petroleum Regulatory Authority imposes noise and emission limits that extend deployment schedules for urban commercial installations. Mombasa's port logistics zone and Kisumu's manufacturing belt specify factory-integrated low-noise packages rather than field-modified standard units.
Africa Diesel Generator Market Competitive Environment
Listed leaders compete with private specialists across distribution infrastructure and service reach. The vendor base fragments between global engine manufacturers with captive assembly operations and regional distributors bundling maintenance contracts. Three archetypes dominate: integrated engine-generator manufacturers with African assembly presence, rental fleet operators with mobile deployment capabilities, and Turkish manufacturing specialists competing on cost-optimized production scale. Competitive moves concentrate on dealer network expansion and hybrid system integration partnerships.
Within the integrated manufacturing tier, Caterpillar Inc. and Cummins Inc. anchor supply relationships through established South African and Nigerian dealer infrastructure. AKSA Power Generation occupies a position exemplifying the cost-optimized manufacturing archetype, leveraging Turkish production proximity for sub-Saharan distribution. Aggreko PLC represents the rental fleet operator model with mobile deployment capabilities across construction and event channels.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Atlas Copco AB |
| Aggreko PLC |
| AKSA Power Generation |
| Kohler Co. |
| HIMOINSA |
| Wärtsilä Corporation |
| Perkins Engines Company Limited |
| Others |
Value Chain & Pricing Dynamics
Cummins Inc.'s East African service network density demonstrates how aftermarket scale economies compress price floors for Tier-4 equivalent prime power units while elevating barriers for non-integrated distributors. Turkish manufacturing proximity through AKSA Power Generation's production base further concentrates supply-side pricing power across sub-Saharan procurement committees.
Pricing Analysis
Mechanical-governed prior-generation units, electronically governed current-generation architectures, and variable-speed next-generation technologies command distinct price bands across African installations. Three-tier pricing structure across premium, standard, and economy levels reflects SANS emission certification status and integrated aftertreatment complexity. Cost compression in economy-tier mechanical systems is intensifying because Nigerian manufacturing clusters consolidate procurement around outcome-based performance contracts. Healthcare facilities in Kenya's metropolitan zone exhibit least price sensitivity due to mandatory decibel compliance inspections, while Ghana's construction rental channels remain most price-sensitive.
Supply Chain Analysis
Strategic stockpiling of critical engine components and acoustic enclosure materials dominates inventory strategy across African generator distributors, contrasting with just-in-time preferences in European supply bases. Manufacturing concentration in Turkey, South Africa, and the United Arab Emirates feeds sub-Saharan distribution networks. Supply chains draw from Chinese steel fabrication, German electronic engine management systems, and South African assembly integration. Single-source vulnerability in electronic aftertreatment components from European suppliers creates structural exposure. Distribution runs through long-tenured dealer networks with captive spare parts inventories rather than transactional equipment brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's SANS emission enforcement and Kenya's urban noise mandates constitute a dual regulatory inflection accelerating technology-cycle turnover across African diesel generator deployments. This disruption compresses replacement timelines while expanding addressable market for electronically governed architectures.
For Market Incumbents: Secure aftermarket revenue streams by expanding service attach rates across East African mining corridors before hybrid integration erodes pure-diesel maintenance demand. Deepen backward integration into electronic engine management system refurbishment capabilities to offset technical skill scarcity outside South Africa and Nigeria. Defensive consolidation around certified Tier-4 equivalent inventory buffers against AKSA Power Generation's cost-optimized Turkish manufacturing scale.
For New Entrants and Emerging Players: Remote diagnostics and predictive maintenance platform deployment represents a service-layer gap where incumbent distributor networks under-serve Nigerian manufacturing clusters. Mozambique's LNG corridor mobile power demand and Zambia's Copperbelt prime power expansion offer the most penetrable geographic white-space. Go-to-market execution should anchor on rental fleet formalization with maintenance bundling in Ghana's construction sector.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with African assembly presence and captive aftertreatment servicing capabilities over pure-play distributors. Long-term viability across the projection horizon rests on hybrid system integration partnerships and carbon border adjustment alignment for export-oriented South African manufacturing. The signal to watch is European trading partner emission protocol stringency crossing thresholds that redirect capital toward cleaner on-site power solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Integration Partnership | Solar-diesel architectures reduce fuel consumption while maintaining production continuity during Nigerian grid failures. |
| Tier-4 Equivalent Certification Investment | SANS emission compliance accelerates fleet replacement cycles across South African industrial estates. |
| Aftermarket Service Network Expansion | Cummins Inc.'s East African service density sustains recurring revenue against transactional equipment brokers. |
| Low-Noise Package Factory Integration | Kenya's Energy and Petroleum Regulatory Authority urban decibel mandates drive specification upgrades in Nairobi healthcare facilities. |
| Rental Fleet Formalization with Maintenance Bundling | Ghana's construction sector shifts from informal sourcing toward contracted providers with guaranteed uptime clauses. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs and trade data, Standards Organisation of Nigeria conformity assessment records, and South African National Regulator for Compulsory Specifications enforcement documentation. Primary interviews engaged maintenance directors at Zambian mining operations, plant engineers across Nigeria's Lagos-Ibadan industrial corridor, aftermarket service heads at East African distributor networks, and procurement leads at Kenyan healthcare facilities. Bottom-up unit deployment tracking across the Copperbelt and top-down macroeconomic scenario modeling were triangulated against SANS emission standard implementation timelines.
Segmentation dimensions modeled include product type tier, end-user vertical, fuel architecture, installation duration category, and regional regulatory cluster across the analysis window. CAGRs were derived from equipment refresh cycle compression under emission mandates and mining expansion timelines relative to grid extension delays. Forecast inputs incorporated diesel price volatility scenarios and currency fluctuation patterns affecting Nigerian and Kenyan operating margins.
Forecasts assume regulatory continuity in South Africa's SANS enforcement regime and Kenya's Energy and Petroleum Regulatory Authority urban noise mandates; material policy shifts would require re-modeling. Revision becomes warranted when European carbon border adjustment mechanisms cross implementation thresholds that restructure African manufacturing investment toward cleaner on-site power solutions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America and Africa Diesel Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Halogenerator Market
Generators
Heat Recovery System Generator Market
Generators
North America Gas Generator Market
Generators
Onboard Marine Gensets Market
Generators
Electric Generators Market
Generators
Global Portable Generator Market
Generators
Europe Diesel Generator Market
Generators
Digital Inverter Generator Market
Generators
Europe Gas Turbine Market
Generators
Multi Fuel Generators Market
Generators
Silent Generator Market
Generators
Nuclear Turbine Generators Market
Generators
Asia-Pacific Gas Generator Market
Generators
Gasoline Gensets Market