
 Gas Generator Sets Market | 2026-2036
Gas Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Generator Sets Market Analysis
Aftermarket service revenue is narrowing toward predictive maintenance contracts and remote monitoring subscriptions. Caterpillar Inc. leverages its global dealer network to capture long-term service agreements. Cummins Inc. anchors its position through dual-fuel technology leadership. Wärtsilä Corporation specializes in large-bore gas engines for utility-scale installations.
Gas generator sets are internal combustion engine-driven alternators that convert natural gas or biogas into electrical power, typically operating at 50 Hz or 60 Hz with thermal efficiencies ranging from 35% to 45% depending on engine class and exhaust heat recovery configuration. They serve as primary or emergency power sources for facilities requiring uninterrupted electricity. Stationary units above 250 kW dominate margin pools in industrial and data center applications, while portable 5-50 kW models compete on rental fleet turnover. Dual-fuel technology is gaining fastest in markets with volatile natural gas pricing, allowing operators to switch between gas and diesel without shutdown.
The US EPA enforces Tier 4 final emissions limits on stationary engines, compelling manufacturers to integrate selective catalytic reduction and oxidation catalysts. The EU F-Gas Regulation and CE marking requirements restrict fluorinated greenhouse gases in cooling systems and mandate conformity assessment for grid-connected equipment. India's Central Electricity Authority mandates grid code compliance for captive power plants above a threshold capacity. Stakeholders must monitor carbon intensity accounting rules for biogas certificates, as these will determine fuel cost competitiveness against battery storage alternatives.
Market Dynamics
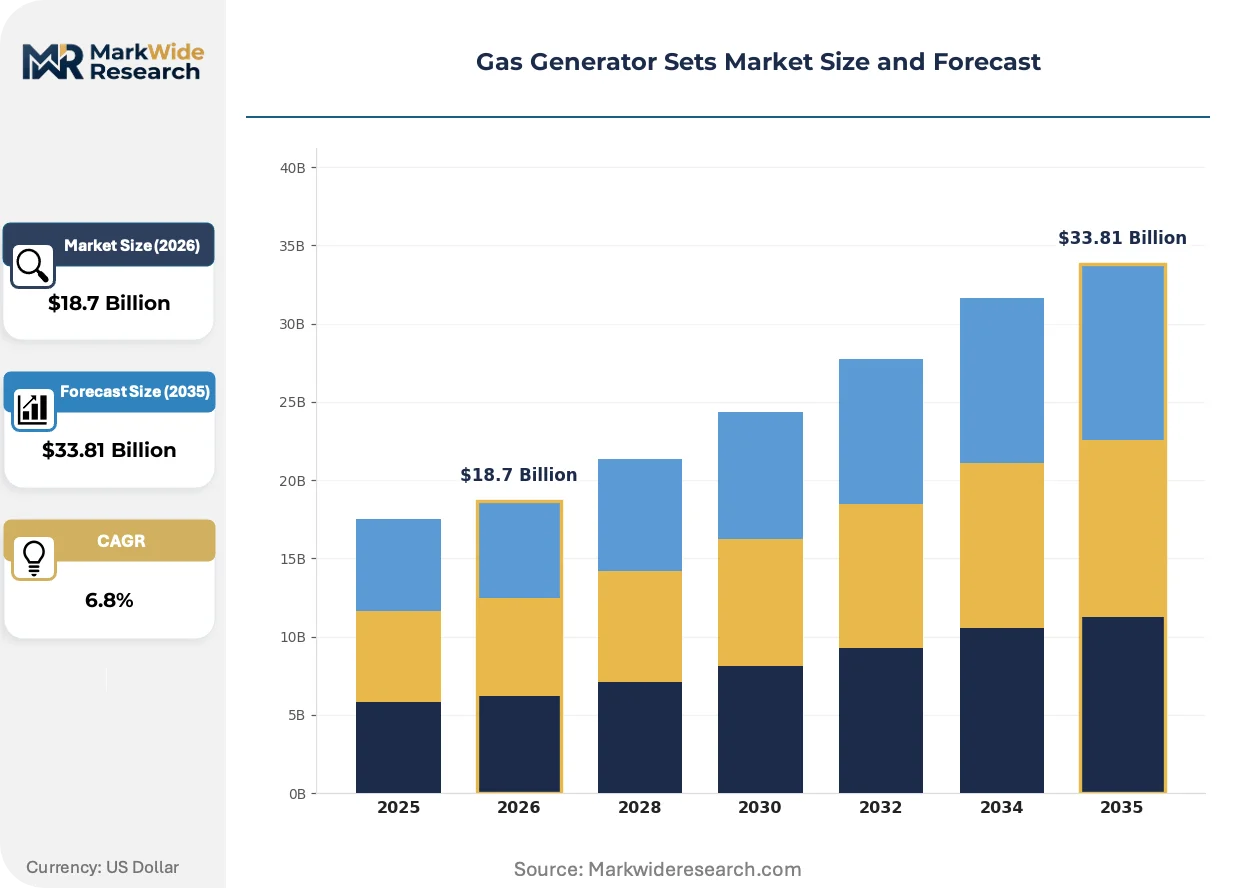
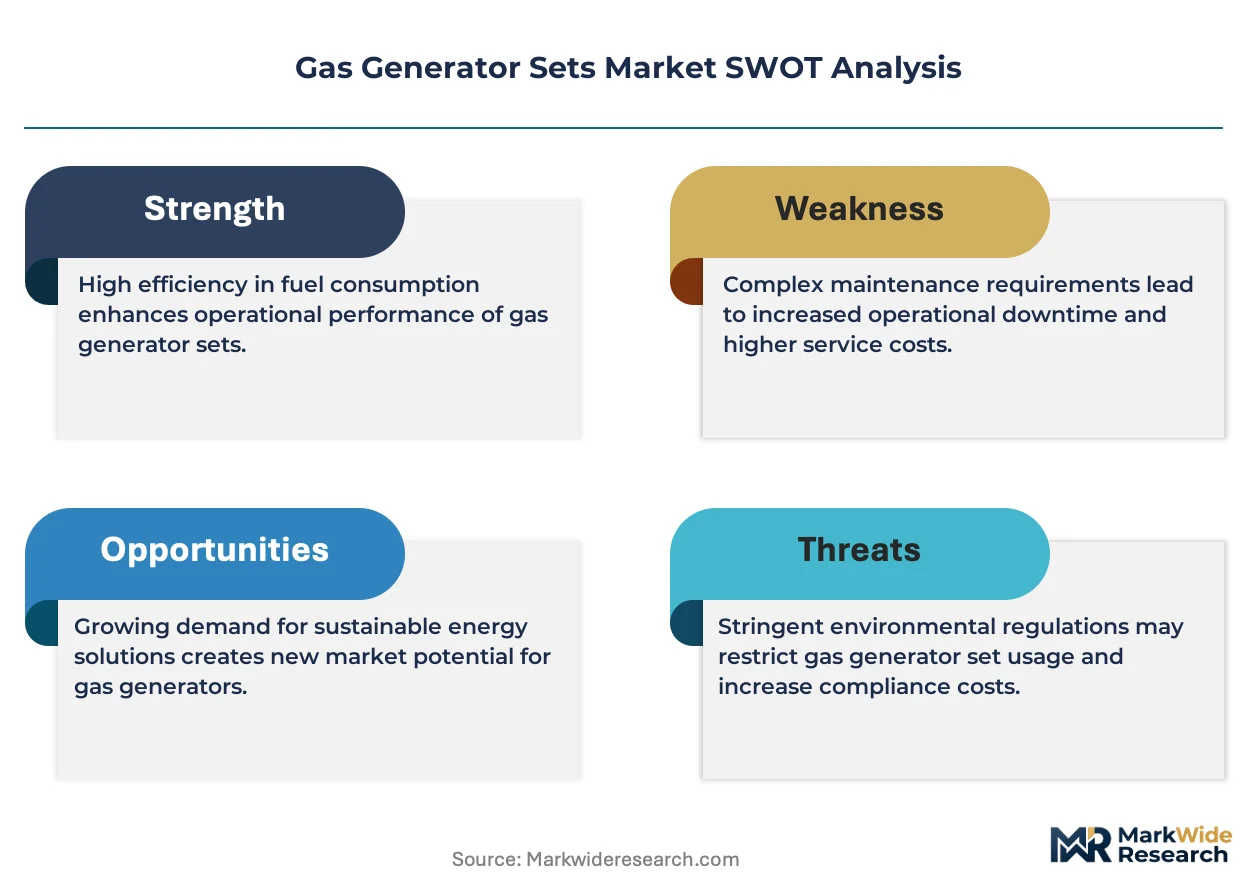
Dual-fuel engine architecture is compressing payback periods for operators exposed to volatile natural gas pricing, while EPA Tier 4 final and EU F-Gas Regulation compliance costs are redistributing margin pools toward integrated emissions control suppliers.
Growth Catalysts
- Data center load growth:Hyperscale facilities in Singapore and Jakarta are procuring 2-5 MW gas generator sets as primary backup against grid instability, with procurement cycles compressing to 18-month deployment windows.
- India's CEA grid code mandate:Captive power plants above 100 MW must maintain frequency response capability, forcing industrial clusters in Gujarat to upgrade to grid-synchronized gas engines.
- Selective catalytic reduction integration:Modular SCR systems are extending engine overhaul intervals while maintaining NOx compliance, reducing lifecycle operating costs for continuous-duty installations.
Market Restraints
- Platinum group metal cost volatility:Oxidation catalyst substrates depend on palladium and rhodium prices indexed to South African mining output, creating 15-20% quarter-to-quarter catalyst replacement cost swings.
- Biogas certificate fragmentation:Carbon intensity accounting rules vary across EU member states, German TÜV certification, and emerging Asian registries, complicating fuel cost arbitrage against lithium-ion storage.
- Large-bore engine supply concentration:Cylinder heads and crankshaft forgings for utility-scale units above 10 MW source from a limited set of European and Japanese foundries, creating 26-32 week lead time exposure.
Strategic Opportunities
- Vietnam industrial zone electrification:Northern provinces around Hai Phong lack grid capacity to match FDI manufacturing inflows, creating captive generation demand for 500 kW-2 MW modular gas units.
- Remote monitoring subscription models:Predictive maintenance platforms leveraging vibration analysis and oil particulate sensors are capturing 8-12 year service contracts, displacing transactional parts revenue.
- EU F-Gas Regulation phase-down:Restrictions on HFC refrigerants in generator set cooling systems are accelerating adoption of CO2-based heat pumps for exhaust heat recovery in combined heat and power configurations.
Industry Challenges
- Combustion calibration expertise scarcity:Optimizing air-fuel ratios across methane number variations requires specialized tuning capabilities concentrated among aging field engineers, constraining deployment velocity in biogas-heavy markets.
- CE marking conformity assessment bottlenecks:Grid code compliance testing for synchronous machines faces 4-6 month queue times at notified bodies, delaying revenue recognition for European utility-scale projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Generator Sets Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Stationary, Industrial, Residential Technology: Conventional, Inverter, Dual-Fuel, Hybrid End User: Construction, Manufacturing, Healthcare, Telecommunications Power Rating: 5-50 kW, 51-100 kW, 101-250 kW, Above 250 kW |
| Companies Covered | Caterpillar Inc., Cummins Inc., Generac Holdings Inc., Kohler Co., MTU Onsite Energy, Mitsubishi Heavy Industries, Ltd., Wärtsilä Corporation, Briggs & Stratton Corporation, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Generator Sets Market Emerging Trajectories
Engine control systems are converging with cloud-based analytics platforms, compressing the traditional separation between hardware OEMs and aftermarket service providers. Three developments are restructuring competitive positioning.
Embedded edge computing modules are digitizing real-time combustion optimization across variable methane content. Data center operators in Southeast Asia are deploying these systems at 40% of new installations. The technology is digitizing warranty risk allocation, with OEMs assuming performance guarantees conditional on continuous data streaming.
EPA enforcement of Tier 4 final standards for stationary engines above 560 kW is mandating integrated selective catalytic reduction and diesel particulate filter configurations. Manufacturers are absorbing 12-18% bill-of-materials cost increases into base pricing. The industrial rental fleet segment is responding by extending diesel asset depreciation schedules rather than retrofitting.
Power purchase agreement structures are unbundling equipment ownership from energy output risk. Data center developers in India and Singapore now procure backup capacity through 10-15 year availability contracts with guaranteed heat rate performance. This model concentrates most visibly among colocation operators seeking to offload capex intensity to specialized independent power producers.
Gas Generator Sets Market Segmentation
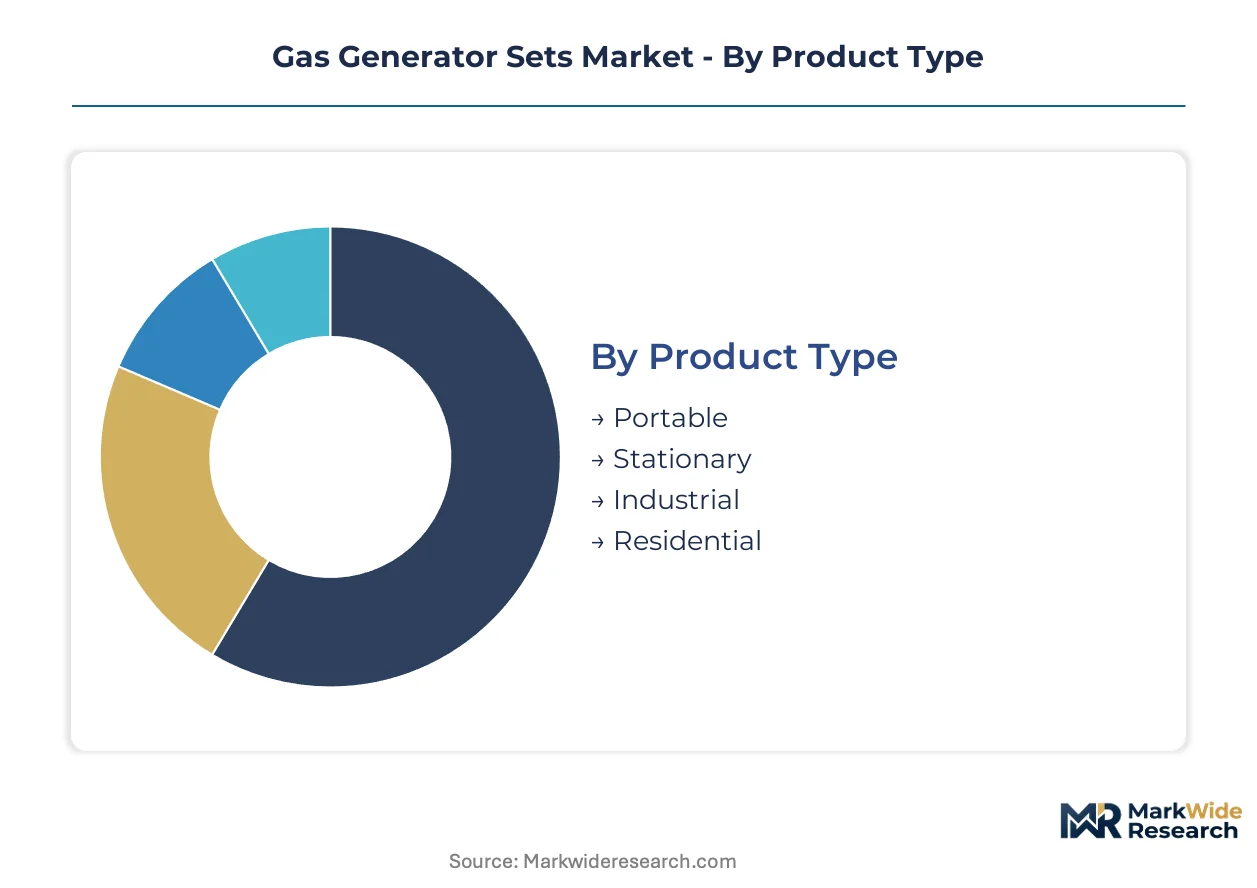
Gas generator set segmentation reveals divergent service contract structures across product tiers. Portable units generate transactional parts revenue, while stationary installations above 250 kW anchor decade-long predictive maintenance agreements.
Product Type:
After-sales service intensity varies sharply across mobility tiers, with stationary units demanding embedded technician teams and portable models relying on depot refurbishment networks.
- Stationary:Fixed-installation units above 250 kW integrate selective catalytic reduction and exhaust heat recovery systems. Data center operators in Singapore and Jakarta procure these for 18-month deployment cycles, with OEMs capturing 10-15 year service contracts tied to heat rate performance guarantees.
- Industrial:Continuous-duty engines for manufacturing clusters in Gujarat and Maharashtra operate 6,000+ hours annually. Grid code mandates from India's Central Electricity Authority force synchronization upgrades, concentrating demand among foundries with captive forging capabilities.
- Portable:Rental fleet units in the 5-50 kW range compete on turnover velocity; depot refurbishment cycles compress to 90-120 days during peak construction seasons.
- Residential:Standby units below 25 kW serve single-facility backup; service revenue concentrates on annual inspection contracts rather than predictive analytics.
Stationary holds the largest share; momentum sits with Industrial as India's CEA mandates accelerate captive power upgrades.
Technology:
Technology choice determines emissions compliance cost structures and fuel flexibility premiums across volatile natural gas markets.
- Dual-Fuel:Architecture permitting seamless diesel-to-gas switching without shutdown. Operators exposed to Henry Hub volatility in the US and TTF fluctuations in Europe compress payback periods through fuel arbitrage; modular SCR integration extends overhaul intervals while maintaining EPA Tier 4 final compliance.
- Hybrid:Battery-gas configurations emerging at hyperscale data centers; lithium-ion buffer units handle transient loads while gas engines manage sustained demand, reducing runtime hours and catalyst degradation.
- Conventional:Single-fuel gas engines dominate established utility-scale installations with stable pipeline supply contracts.
- Inverter:Variable-speed electronic governors improve part-load efficiency for residential and small commercial applications with fluctuating demand profiles.
Dual-Fuel commands the premium tier; Hybrid is climbing the fastest as data center developers unbundle capex risk through availability contracts.
End User:
End-use verticals segment by uptime requirements, with healthcare and telecommunications mandating sub-10-second transfer switches while construction tolerates longer outage windows.
- Telecommunications:Cell tower and fiber hub installations require 99.999% availability. Southeast Asian operators deploy 2-5 MW gas sets as primary backup against grid instability; remote monitoring subscriptions capture 8-12 year contracts through vibration analysis and oil particulate sensing.
- Healthcare:Hospital campuses above 500 beds require NFPA 110 Type 10 emergency power. Life safety loads mandate synchronous transfer with voltage regulation within 2%; service contracts include quarterly load bank testing.
- Manufacturing:Process industries with continuous batch operations prioritize thermal efficiency through combined heat and power configurations.
- Construction:Temporary power for infrastructure projects favors rental fleet procurement with 500-2,000 hour annual utilization targets.
Telecommunications holds the largest share; momentum sits with Healthcare as aging grid infrastructure elevates backup power to primary supply status in emerging markets.
Power Rating:
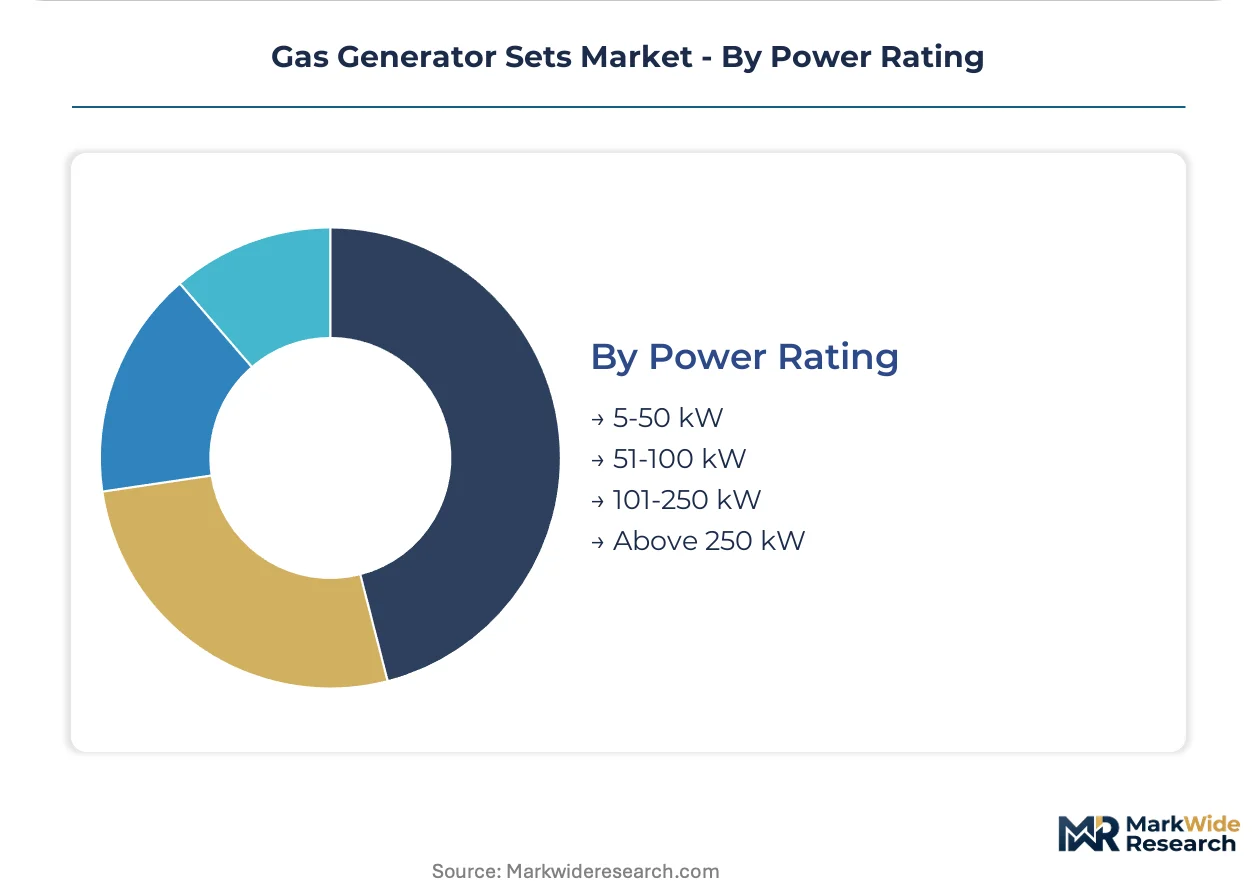
Power rating segmentation aligns with foundry capacity constraints and emissions regulatory thresholds, particularly the EPA's 560 kW Tier 4 final cutoff.
- Above 250 kW:Large-bore engines for utility-scale and industrial captive plants. Cylinder heads and crankshaft forgings source from limited European and Japanese foundries, creating 26-32 week lead time exposure; margin pools concentrate here due to technical barriers and integrated emissions control requirements.
- 101-250 kW:Mid-range units serving commercial campuses and small manufacturing facilities; CE marking conformity assessment bottlenecks at notified bodies delay European revenue recognition by 4-6 months.
- 51-100 kW:Light commercial applications with standardized enclosure designs and reduced customization.
- 5-50 kW:Portable and residential segments competing on manufacturing scale and distribution network density.
Above 250 kW holds the largest share; momentum sits with 101-250 kW as Vietnam's northern industrial zones around Hai Phong absorb FDI manufacturing inflows without matching grid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for large-bore engine components concentrates in Germany and Japan, creating 26-32 week lead times that ripple through utility-scale project schedules worldwide. This supply bottleneck shapes regional procurement strategies as data center operators and industrial captives accelerate deployment timelines.
United States
Hyperscale data centers in Northern Virginia and Dallas-Fort Worth are compressing gas generator procurement cycles to 18-month windows. EPA Tier 4 final enforcement on engines above 560 kW mandates integrated selective catalytic reduction systems. Texas industrial clusters around Houston prioritize dual-fuel architectures to hedge Henry Hub volatility.
India
Central Electricity Authority grid code mandates force captive power plants above 100 MW to upgrade frequency response capabilities. Industrial clusters in Gujarat and Maharashtra operate gas engines 6,000+ hours annually to offset utility shortages. Mumbai-Pune corridor manufacturers absorb 12-18% emissions compliance cost increases into base pricing.
Germany
EU F-Gas Regulation phase-down restricts HFC refrigerants in cooling systems, accelerating CO2-based heat pump adoption for combined heat and power. CE marking conformity assessment bottlenecks at notified bodies delay synchronous machine approvals by 4-6 months. Bavarian foundries anchor European large-bore crankshaft forging capacity.
Singapore
Data center operators procure 2-5 MW gas sets as primary backup against grid instability, with 40% of new installations embedding edge computing modules for real-time combustion optimization. Tropical humidity conditions accelerate catalyst degradation cycles. Jurong Island petrochemical complexes demand continuous-duty reliability.
Vietnam
Northern provinces around Hai Phong lack grid capacity to match FDI manufacturing inflows, creating captive generation demand for 500 kW-2 MW modular gas units. Biogas certificate fragmentation complicates fuel cost arbitrage against lithium-ion storage alternatives. Hai Phong industrial zone developers unbundle equipment ownership through 10-15 year availability contracts.
Gas Generator Sets Market Vendor Landscape
Integrated power systems conglomerates and specialized engine manufacturers split the market along project scale and service intensity lines. The vendor base organizes into three tiers: full-lifecycle solution providers capturing decade-long predictive maintenance contracts, component specialists dominating emissions control subsystems, and regional assemblers competing on rental fleet turnover velocity. Consolidation pressure concentrates among mid-scale players seeking foundry access and grid code certification capabilities. Technology licensing agreements and backward integration into cylinder head forging capacity represent the dominant competitive moves reshaping positioning.
Within the full-lifecycle tier, Caterpillar Inc. and Cummins Inc. exemplify archetypes built on global dealer networks and dual-fuel technology portfolios respectively. Wärtsilä Corporation occupies a position among large-bore utility-scale specialists, anchoring the premium segment for installations above 10 MW where European and Japanese foundry relationships determine delivery schedules. These three entities represent the structural poles around which service contract structures, emissions compliance integration, and fuel flexibility premiums organize competitive differentiation.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Generac Holdings Inc. |
| Kohler Co. |
| MTU Onsite Energy |
| Mitsubishi Heavy Industries, Ltd. |
| Wärtsilä Corporation |
| Briggs & Stratton Corporation |
| General Electric |
| Others |
Supply Flow & Price Mechanics
Platinum group metal volatility in oxidation catalyst substrates compresses pricing tier spreads while forcing supply chain restructuring toward dual-source procurement strategies. This cost vector simultaneously widens the premium attached to integrated emissions control bundles and accelerates foundry consolidation for large-bore forgings.
Pricing Analysis
EPA Tier 4 final dictates the pricing tier structure across stationary gas generator sets above 560 kW, with integrated selective catalytic reduction configurations commanding premium positioning against modular retrofit alternatives. Three-tier pricing structure across premium, standard, and economy levels separates OEM-bundled emissions systems from third-party catalyst suppliers and rental fleet depreciation schedules. Cost compression in the mid-range tier is intensifying because India's CEA grid code mandates force synchronization upgrades without corresponding fuel cost relief. Data center operators in Singapore demonstrate the lowest price sensitivity, while Vietnamese industrial zone developers pursuing availability contracts exhibit acute cost consciousness.
Supply Chain Analysis
Export controls on precision forging equipment limit capacity expansion for large-bore crankshaft production, constraining supply elasticity regardless of demand signals. Foundry capacity concentrates in Germany and Japan, with cylinder head castings drawing from specialized European facilities and precision machining anchored in Japanese industrial clusters. Palladium and rhodium sourcing rests on South African mining output, creating quarter-to-quarter catalyst cost instability. Single-source vulnerability pervades utility-scale component procurement above 10 MW. Distribution runs through OEM-authorized dealer networks for stationary installations and depot refurbishment hubs for portable rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions and remote monitoring contracts are expanding faster than hardware sales, transforming capital equipment markets into recurring revenue platforms anchored by heat rate performance guarantees.
For Market Incumbents: Insulate service contract portfolios against battery storage substitution by embedding edge computing modules that digitize warranty risk allocation. Capture foundry capacity through backward integration into cylinder head forging or exclusive supply agreements with Bavarian and Japanese specialists. Battery-gas hybrid configurations threaten pure-play gas engine positioning in hyperscale data center procurement. For New Entrants and Emerging Players: Pursue captive generation opportunities in Vietnam's northern industrial zones around Hai Phong, where grid capacity lags FDI manufacturing inflows. Target 500 kW-2 MW modular gas unit deployments through 10-15 year availability contracts that unbundle equipment ownership from energy output risk. Biogas certificate arbitrage expertise offers differentiation against established OEMs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors foundry-accessible mid-scale specialists with grid code certification capabilities. Five-to-ten year viability hinges on emissions control integration depth rather than pure engine manufacturing scale. Watch for CE marking conformity assessment queue times at notified bodies as an inflection indicator for European project revenue recognition delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Secures crankshaft supply for utility-scale engines above 10 MW amid 26-32 week lead times. |
| Predictive Maintenance Platform Launch | Captures 8-12 year service contracts through vibration analysis and oil particulate sensing subscriptions. |
| Dual-Fuel Technology Licensing | Enables fuel arbitrage across Henry Hub and TTF volatility without engine shutdown requirements. |
| CO2-Based Heat Pump Integration | Addresses EU F-Gas Regulation HFC restrictions in combined heat and power cooling systems. |
| Grid Code Certification Investment | Accelerates revenue recognition for Indian CEA-mandated frequency response upgrades in Gujarat clusters. |
Methodological Framework
The analysis maps stationary, industrial, portable, and residential product tiers, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and EPC contractors. Primary interviews with data center operators in Singapore and Jakarta, captive power managers in Gujarat, and utility-scale project developers in Germany combined with secondary validation from EPA enforcement notices, EU F-Gas Regulation amendments, Indian CEA grid code directives, and customs trade data for large-bore engine component flows. Bottom-up unit economics triangulated against top-down market sizing across power rating segments.
Assumptions held EPA Tier 4 final compliance timelines and EU F-Gas phase-down schedules fixed while varying natural gas price trajectories and biogas certificate accounting rules across the projection horizon. Segmentation dimensions modeled include mobility tier, fuel flexibility architecture, end-use vertical, power rating bracket, and regional regulatory framework. CAGRs derived from installed base turnover rates and replacement demand elasticity. Forecast inputs incorporated foundry capacity utilization rates and CE marking queue times at notified bodies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery storage specialists or hybrid system integrators would shift outcomes. Material shifts in platinum group metal pricing, South African mining output disruptions, or accelerated EU methane slip regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Middle-East and Africa Portable Generator Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
Generator Belt Market
Generators
Diesel Generator Market
Generators
Residential Gas Generator Market
Generators
Asia-Pacific Gas Generator Market
Generators
Gasoline Gensets Market
Generators
Marine Gensets Market
Generators
United States Portable Generator Market
Generators
Mobile Generators Market
Generators
Heat Recovery System Generator Market
Generators
Generator [Up to 100 Kva] Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Construction Portable Generators Market
Generators
US Generator Sales Market
Generators
Tri Fuel Generators Market