
 Europe Diesel Generator Market | 2026-2036
Europe Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Diesel Generator Market Analysis
Tier-4 final and Stage V compliance is unwinding legacy product portfolios across European rental and industrial channels. Caterpillar Inc. leverages its European manufacturing footprint to sustain localized engine production. Wärtsilä anchors large-scale stationary installations with medium-speed architecture. FG Wilson Engineering competes through channel density in the United Kingdom and Ireland.
Europe diesel generators are internal combustion engine systems converting diesel fuel into electrical energy, typically operating at 1500 RPM for 50 Hz output and incorporating turbocharged direct-injection architectures for thermal efficiency above 40 percent. Silent type enclosures dominate urban deployment where noise ordinances restrict sound levels below 75 dB at one meter, while the above 600 kVA power rating segment captures margin pools in data center and hospital applications. Oil & gas end users in the North Sea basin drive marine type demand through platform electrification requirements.
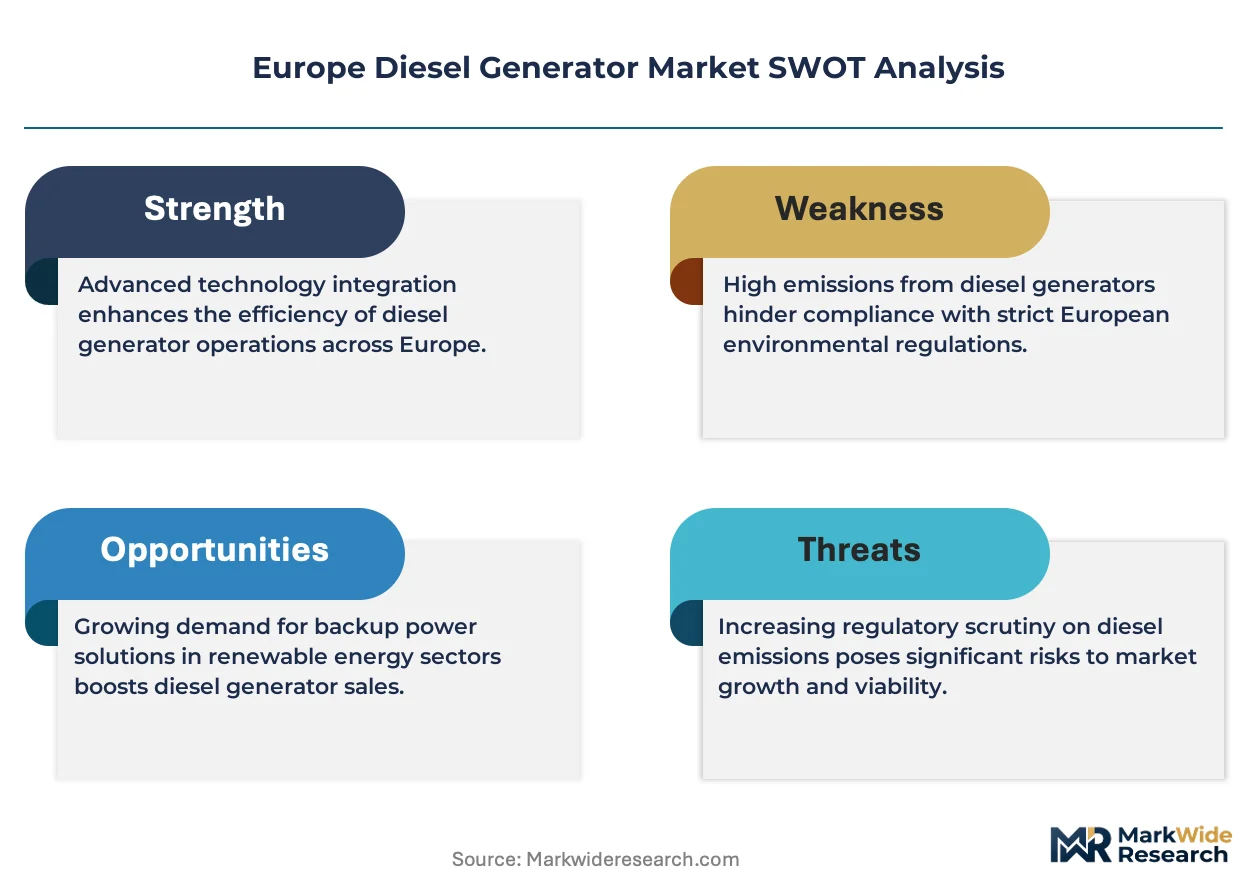
Stage V emission standards from the European Commission, CE marking directives, and national grid codes from Germany's Bundesnetzagentur collectively elevate engineering costs and certification timelines for new market entrants. The EU F-Gas Regulation further constrains cooling system design for enclosed generator sets. Stakeholders must monitor carbon border adjustment mechanisms and renewable diesel blending mandates to anticipate fuel supply restructuring and asset depreciation schedules.
Market Dynamics
Stage V emission standards are compressing product lifecycles across Europe's diesel generator installed base, forcing rental fleets and industrial operators to accelerate replacement schedules while manufacturers redesign engine architectures for compliance.
Growth Catalysts
- Data Center Electrification:Hyperscale operators in Germany and France are expanding backup power fleets to support AI compute clusters, driving demand for above 600 kVA units.
- EU Green Deal Infrastructure:Grid modernization investments are creating temporary power gaps during renewable integration, favoring mobile generator deployment.
- Nordic Remote-Grid Expansion:Mining and telecom installations across Norway and Sweden require off-grid prime power solutions where grid extension remains uneconomical.
Market Restraints
- Stage V Certification Costs:Aftertreatment systems for particulate matter and NOx compliance add 15-25% to engine bill-of-materials, squeezing margin pools in sub-100 kVA segments.
- Renewable Diesel Supply Uncertainty:Hydrotreated vegetable oil availability remains concentrated in Northwest European refining corridors, constraining fuel flexibility for inland operators.
- Electrochemical Substitution:Lithium-ion battery energy storage systems are capturing data center UPS applications below 4-hour runtime requirements.
Strategic Opportunities
- Poland Industrial Corridor:Manufacturing reshoring from Asia is expanding factory electrification needs in Silesia and Greater Poland voivodeships.
- EU F-Gas Regulation Adaptation:Cooling system redesign for enclosed generator sets creates differentiation potential for low-global-warming-potential refrigerant architectures.
- Hybrid Power Integration:Convergence of diesel gensets with solar PV and battery storage is opening microgrid contracts for construction and remote industrial camps.
Industry Challenges
- Emissions Calibration Expertise:Stage V compliance requires scarce combustion engineers capable of optimizing selective catalytic reduction dosing strategies across variable load profiles.
- Legacy Fleet Retrofit Complexity:Existing rental inventories face technical barriers to emission upgrade kits, forcing accelerated depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Diesel Generator Market |
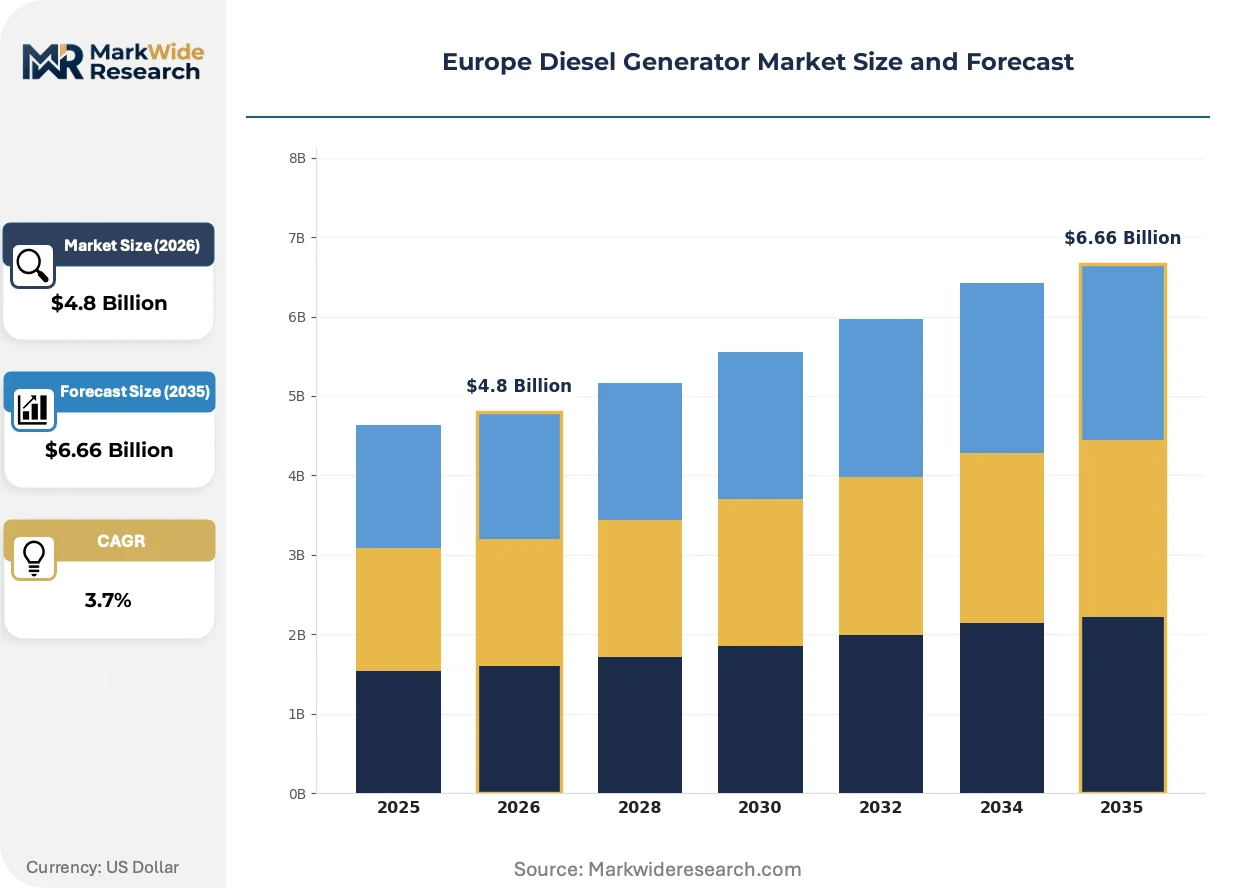
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Type, Silent Type, Marine Type, Portable Type End User: Construction, Utilities, Oil & Gas, Telecommunications Fuel Type: Biofuel, Renewable Diesel, Ultra-Low Sulfur Diesel, Others Power Rating: Below 100 kVA, 100-300 kVA, 300-600 kVA, Above 600 kVA |
| Companies Covered | Mitsubishi Heavy Industries Engine & Turbocharger, Doosan Corporation, Caterpillar Inc., Kohler Co., Generac Power Systems, Cummins Inc., Yanmar Holdings, Wärtsilä, FG Wilson Engineering, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Diesel Generator Market Emerging Trajectories
Digitalization and emission control technologies are redefining how European operators specify, monitor, and maintain diesel generator assets across rental and stationary applications.
Variable-speed generator technology is supplanting traditional fixed-speed architectures in prime power applications. Marine and offshore operators in the North Sea basin are adopting these systems to optimize fuel consumption across fluctuating platform loads. The technology is compressing operational expenditure advantages that previously favored conventional constant-speed designs.
CE marking directives combined with national grid codes from Germany's Bundesnetzagentur are elevating certification timelines for new market entrants. Manufacturers must now synchronize electromagnetic compatibility testing with grid connection compliance before market release. Data center and hospital segments are responding by consolidating supplier relationships with established certification track records.
Power-as-a-service contracting is displacing traditional capital purchase models in construction and event rental channels. Equipment lessors in the United Kingdom and Ireland are bundling fuel management, remote monitoring, and maintenance into per-kWh tariffs. This shift is most visible in urban infrastructure projects where balance-sheet treatment and emission reporting obligations favor operational expenditure structures.
Europe Diesel Generator Market Segmentation
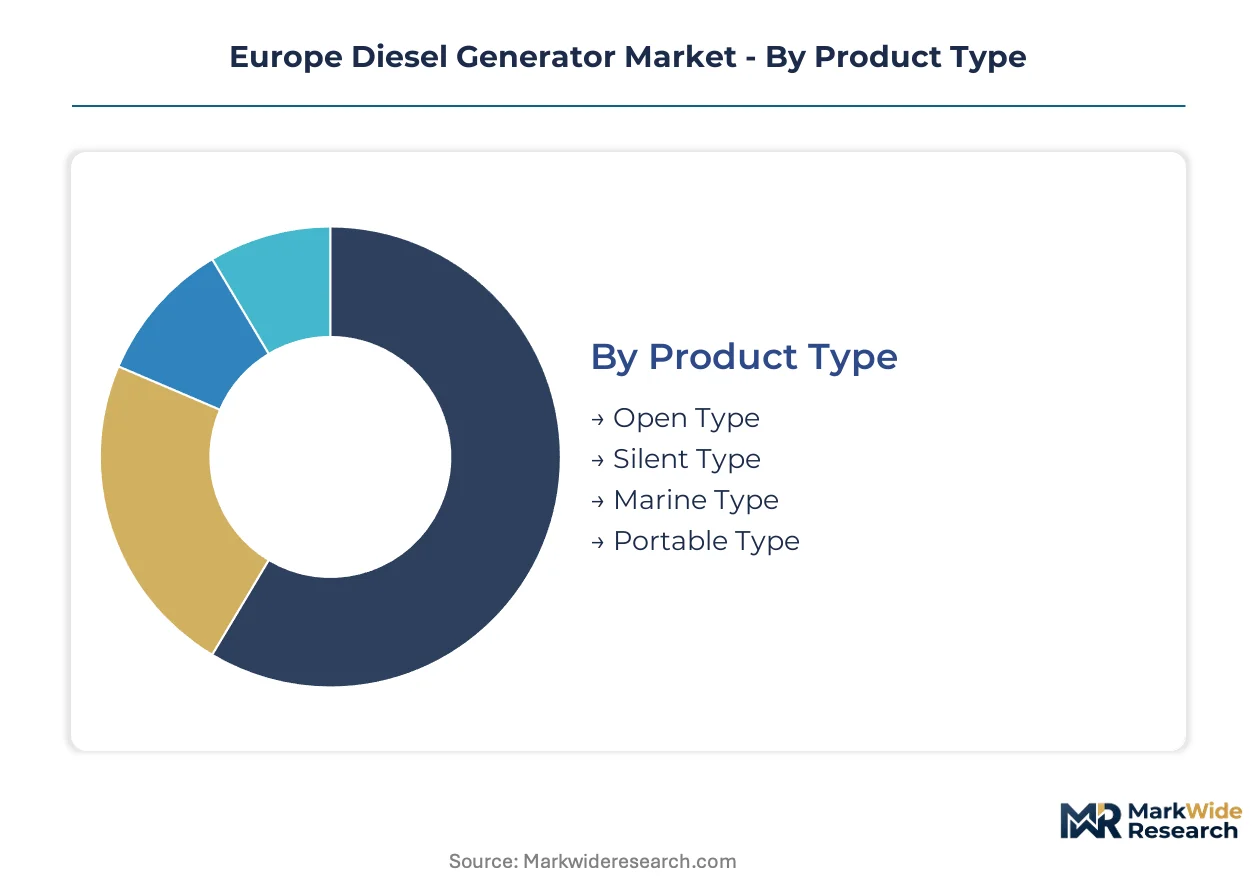
Diesel generator specification in Europe diverges sharply across deployment contexts. Channel partners in Germany and France prioritize emission-compliant architectures for data center and industrial accounts, while Nordic distributors emphasize cold-start reliability for remote installations.
Product Type:
Open type units flow through industrial procurement channels for factory and warehouse installations where acoustic containment is handled at site level. Silent type and portable type generators concentrate in rental fleet channels serving urban construction and events. Marine type supply routes through specialized offshore equipment distributors serving North Sea platform operators.
- Silent Type:Acoustic enclosures attenuate noise below 75 dB at one meter through multi-layer insulation and exhaust silencers. Demand concentrates in Germany's urban construction corridors and French hospital backup installations where municipal noise ordinances carry enforcement penalties.
- Open Type:Unenclosed radiator-cooled architectures minimize capital cost and maintenance access time. Industrial procurement teams across Poland's Silesian manufacturing belt specify these units for covered plant installations where acoustic performance is secondary to thermal efficiency and service accessibility.
- Marine Type:Salt-resistant coatings and shock-mounted gensets serve North Sea oil platform electrification requirements.
- Portable Type:Trailer-mounted or skid-based designs below 150 kVA target construction rental and emergency response channels.
Open type dominates installed base. Silent type is where expansion concentrates.
End User:
Application-driven specification creates distinct margin tiers across European demand channels. Oil and gas procurement teams prioritize redundancy certification for platform safety systems. Telecom operators emphasize remote monitoring integration for unmanned site management.
- Oil & Gas:Platform electrification and process safety systems require redundant prime power architectures with DNV or Bureau Veritas marine certification. North Sea operators in Norwegian and UK waters specify medium-speed gensets for fuel efficiency across variable drilling loads.
- Telecommunications:Unmanned base stations across Sweden and Finland require autostart capability and satellite-linked remote monitoring. Nordic operators are standardizing on hybrid diesel-battery architectures to reduce refueling frequency at Arctic Circle installations.
- Construction:Temporary power for infrastructure projects favors rental channel procurement with fuel-inclusive contracting.
- Utilities:Grid stabilization and emergency restoration services procure through national transmission operator frameworks.
Construction channels dominate transaction volume. Oil and gas represents the steepest expansion trajectory.
Fuel Type:
Supply infrastructure and regulatory pressure are restructuring fuel specification across European installed base. Northwest European refining corridor concentration limits renewable diesel availability for inland operators.
- Ultra-Low Sulfur Diesel:Maximum 10 ppm sulfur content meets Stage V emission standards through conventional aftertreatment. German industrial operators maintain strategic ULSD inventories where renewable diesel supply contracts remain unavailable.
- Renewable Diesel:Hydrotreated vegetable oil delivers identical energy density to fossil diesel with lifecycle carbon reductions. Netherlands and Belgium refiners dominate production capacity, creating supply geography that favors coastal industrial users over Central European operators.
- Biofuel:FAME blends face cold-weather gelling constraints that limit Nordic deployment.
- Others:Synthetic diesel and dual-fuel capabilities remain pilot-scale for data center applications.
Ultra-low sulfur diesel dominates installed base. Renewable diesel is where expansion concentrates.
Power Rating:
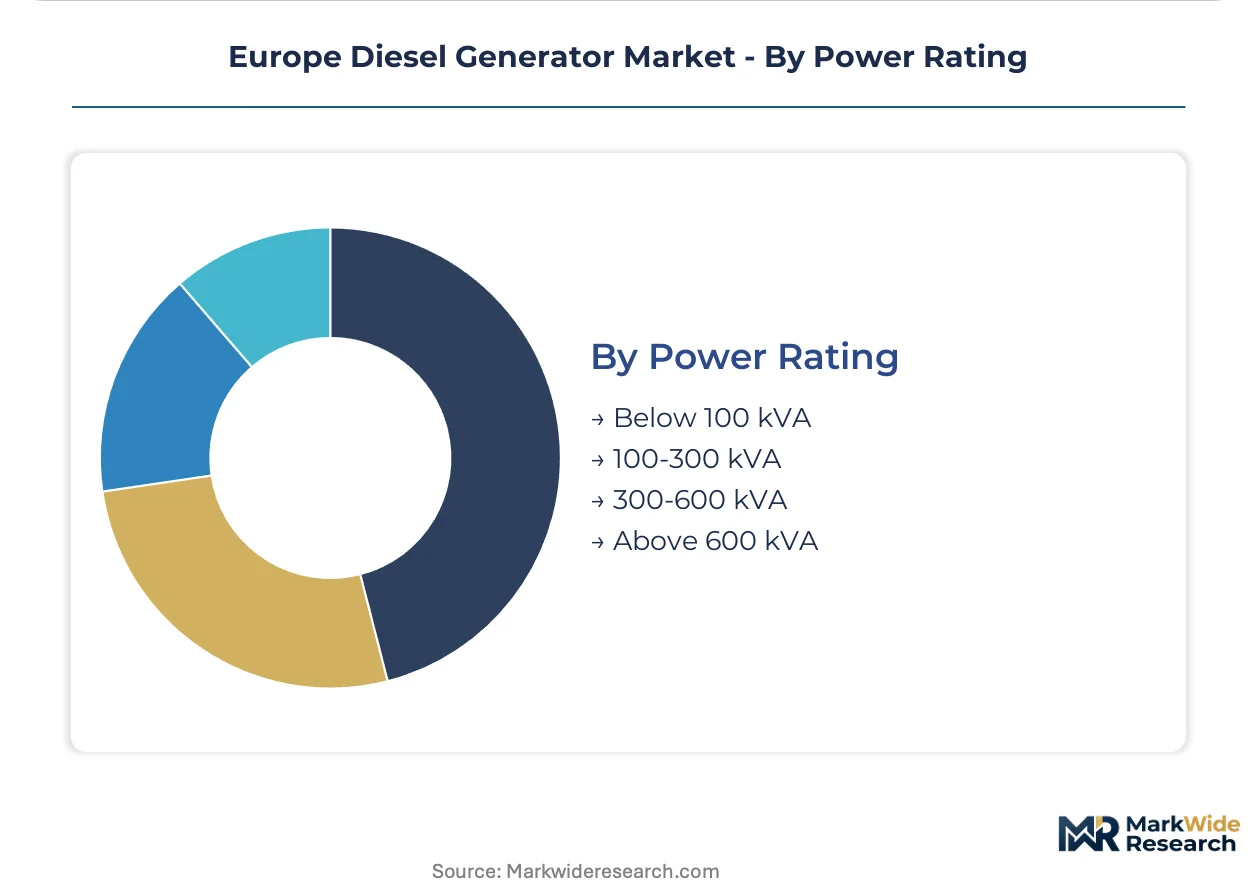
Unit scale determines channel access and service infrastructure requirements. Sub-100 kVA segments compete through distributor density, while above-600 kVA contracts require manufacturer-direct engineering support.
- Above 600 kVA:Medium-speed engine architectures with optimized thermal efficiency serve hyperscale data center backup requirements. Frankfurt and Paris metro area operators are expanding fleets to support AI training cluster power density.
- Below 100 kVA:High-speed single-cylinder or small multi-cylinder designs target residential and small commercial standby. Price compression from Stage V aftertreatment costs is forcing supplier consolidation in this segment.
- 100-300 kVA:Construction rental and light industrial standby represent core demand.
- 300-600 kVA:Hospital and manufacturing facility backup applications require synchronized paralleling capability.
Below 100 kVA dominates installed base. Above 600 kVA is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European diesel generator trade flows reflect a net import position for specialized high-kVA units, with domestic manufacturing concentrated in Germany and the UK serving intra-regional demand while standardized smaller units arrive from Asian production bases.
Germany
Hyperscale data center construction in Frankfurt and Berlin drives demand for above-600 kVA backup systems. Bundesnetzagentur grid codes mandate synchronized paralleling capability for utility-interconnected installations. Bavaria's industrial corridor hosts manufacturing facilities supplying Stage V-compliant engines across Central Europe.
United Kingdom
North Sea oil platform electrification sustains marine-type generator procurement through Aberdeen and Great Yarmouth supply bases. Health and Safety Executive offshore regulations require redundant prime power architectures with DNV certification. London's urban construction sector specifies silent-type units below 75 dB for compliance with municipal noise ordinances.
France
Hospital backup power upgrades and nuclear grid stabilization contracts expand demand in Île-de-France and Lyon metropolitan areas. ANSM safety standards for healthcare critical power systems elevate certification requirements. Auvergne-Rhône-Alpes hosts testing facilities for Stage V emission validation before EU-wide deployment.
Poland
Manufacturing reshoring from Asia accelerates factory electrification in Silesia and Greater Poland voivodeships. National grid modernization creates temporary power gaps during renewable integration phases. The Baltic Sea corridor positions Gdansk-area distributors for renewable diesel supply from Northwest European refiners.
Norway
Arctic Circle mining and telecom installations require cold-start reliable prime power for unmanned remote sites. Norwegian Maritime Authority regulations govern offshore platform generator certification. Troms and Finnmark counties standardize on hybrid diesel-battery architectures to reduce refueling frequency at isolated base stations.
Europe Diesel Generator Market Vendor Landscape
Listed leaders compete with private specialists across emission compliance capabilities, with publicly traded multinationals leveraging capital markets for Stage V R&D while family-owned fabricators defend regional service relationships. The vendor base concentrates around engine manufacturers with captive generator set assembly, rental fleet operators with captive maintenance infrastructure, and independent assemblers sourcing powertrains from third-party suppliers. Strategic moves center on portfolio diversification into hybrid power systems and geographic expansion through distributor acquisition.
Within the multinational engine-manufacturer tier, Caterpillar Inc., Cummins Inc., and Wärtsilä occupy positions defined by thermal efficiency architecture and speed-class specialization. Caterpillar represents the high-speed integrated-system archetype with European manufacturing footprint advantages. Cummins exemplifies the modular powertrain supplier model enabling third-party assembly partnerships. Wärtsilä anchors the medium-speed stationary segment for large-scale industrial and marine applications.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Engine & Turbocharger |
| Doosan Corporation |
| Caterpillar Inc. |
| Kohler Co. |
| Generac Power Systems |
| Cummins Inc. |
| Yanmar Holdings |
| Wärtsilä |
| FG Wilson Engineering |
| Others |
Supply Flow & Price Mechanics
Stage V emission certification gates both supplier qualification and price differentiation simultaneously, as aftertreatment system integration costs stratify manufacturers by compliance capability while rental fleet operators absorb premium pricing for certified units.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on emission certification tier and geographic delivery cost, with Stage V-compliant units commanding substantial premiums over legacy inventory. Pricing pressure stems from aftertreatment component cost inflation in sub-100 kVA segments. Construction rental channels exhibit highest price sensitivity, while data center operators demonstrate lowest sensitivity due to uptime guarantee requirements.
Supply Chain Analysis
Germany and the United Kingdom anchor engine manufacturing and generator set assembly for European demand. Powertrain components draw from Italy for high-pressure fuel injection systems and Japan for turbocharger assemblies. Single-source vulnerability concentrates in selective catalytic reduction dosing module supply. Distribution runs through captive rental fleet operators and independent industrial distributors with regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity, with power-as-a-service contracting and remote monitoring subscriptions expanding faster than hardware unit sales across European rental channels.
For Market Incumbents: Secure captive maintenance infrastructure through distributor acquisition in Poland's industrial corridor, insulating against lithium-ion battery substitution in sub-4-hour UPS applications. Deepen backward integration into aftertreatment system production to defend margin position against component cost inflation. For New Entrants and Emerging Players: Lead with hybrid diesel-battery architectures for Nordic Arctic Circle telecom installations, where refueling logistics create the most penetrable white space. Target power-as-a-service contracting models for urban construction rental channels in France and Germany. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across above-600 kVA stationary segments due to synchronized paralleling engineering requirements. Acquisition candidates include regional assemblers with Bundesnetzagentur certification track records. The signal to watch is carbon border adjustment mechanism implementation affecting renewable diesel supply economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Power System Integration | Converges diesel gensets with solar PV and battery storage for microgrid contracts. |
| Stage V Certification Investment | Unlocks German and French data center procurement frameworks requiring compliant architectures. |
| Power-as-a-Service Platform Launch | Captures construction rental demand shifting from capital purchase to per-kWh operational expenditure. |
| Regional Distributor Acquisition | Secures maintenance infrastructure density in Poland's Silesian manufacturing belt. |
| Low-GWP Cooling System Redesign | Differentiates enclosed generator sets under EU F-Gas Regulation constraints. |
Methodological Framework
Desk research of EU regulatory filings, national grid code documentation, and emission certification databases preceded structured interviews with rental fleet procurement directors, data center facility engineers, and aftermarket service heads. Primary fieldwork with Stage V engine calibration specialists and industrial distributor principals combined with secondary validation through Bundesnetzagentur interconnection standards and CE marking directives. Bottom-up unit shipment estimates triangulated against top-down power capacity deployment data.
Variance decomposition across power rating tiers, product type configurations, and end-use applications shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling incorporating data center construction pipelines and North Sea platform electrification schedules. Forecast inputs included renewable diesel supply corridor expansion and lithium-ion battery cost curves for electrochemical substitution assessment.
The analysis sits within stated boundaries; outcomes outside sustained Stage V enforcement intensity or accelerated grid modernization timelines would require recalibration. Forecasts reflect documented assumptions regarding emission regulation implementation and hyperscale data center power density trajectories. Recalibration cycles align with material shifts in EU Green Deal infrastructure allocation and carbon border adjustment mechanism scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Heat Recovery System Generator Market
Generators
Generator Sets Market
Generators
South America Diesel Generator Market
Generators
Commercial Standby Generator Sets Market
Generators
Africa Diesel Generator Market
Generators
Emergency Power Generators Sales Market
Generators
Africa Portable Generator Market
Generators
Portugal Gas Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
Global Portable Generator Market
Generators
South America Gas Generator Market
Generators
Mobile Generators Market
Generators
Asia-Pacific Portable Generator Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Tri Fuel Generators Market
Generators
North America Gas Generator Market