
 Construction Prime Power Generators Market | 2026-2036
Construction Prime Power Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Prime Power Generators Market Insights
Tier 4 Final and Stage V compliance-grade prime power packages is rotating through the product mix as construction fleets replace legacy diesel assets. Caterpillar leverages its integrated engine-generator manufacturing footprint to control certification costs across North American and European job sites. Cummins sustains competitive positioning through modular power node architectures that simplify transport between remote infrastructure locations.
Construction prime power generators are engine-driven electrical generation systems rated for unlimited hours of variable load operation, typically delivering 50 kW to 3,000 kW with sustained output capability rather than emergency standby duty. Diesel generators still occupy the largest installed base due to fuel availability and torque response, though natural gas generators and dual fuel generators are capturing incremental share where pipeline access exists at permanent construction campuses. Prime-rated technology configurations dominate mining operations and oilfield sites where grid connection remains impractical, while load management systems gain traction in civil engineering applications seeking fuel optimization.
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by national type-approval authorities limit diesel particulate emissions from non-road engines, compelling OEMs to integrate selective catalytic reduction and diesel exhaust fluid systems. India's CEA grid reliability mandates and BIS fuel quality standards shape import requirements for foreign generator suppliers bidding on public works contracts. Stakeholders must monitor how carbon border adjustment mechanisms and evolving NOx thresholds rebalance the total cost of ownership between conventional diesel and gaseous-fuel prime power platforms.
Market Dynamics
Emissions compliance deadlines are compressing diesel generator margins while accelerating natural gas and dual-fuel technology transitions across construction fleets. The shift from intermittent standby to continuous-duty prime-rated configurations is redrawing equipment procurement specifications for multi-year infrastructure builds.
Growth Catalysts
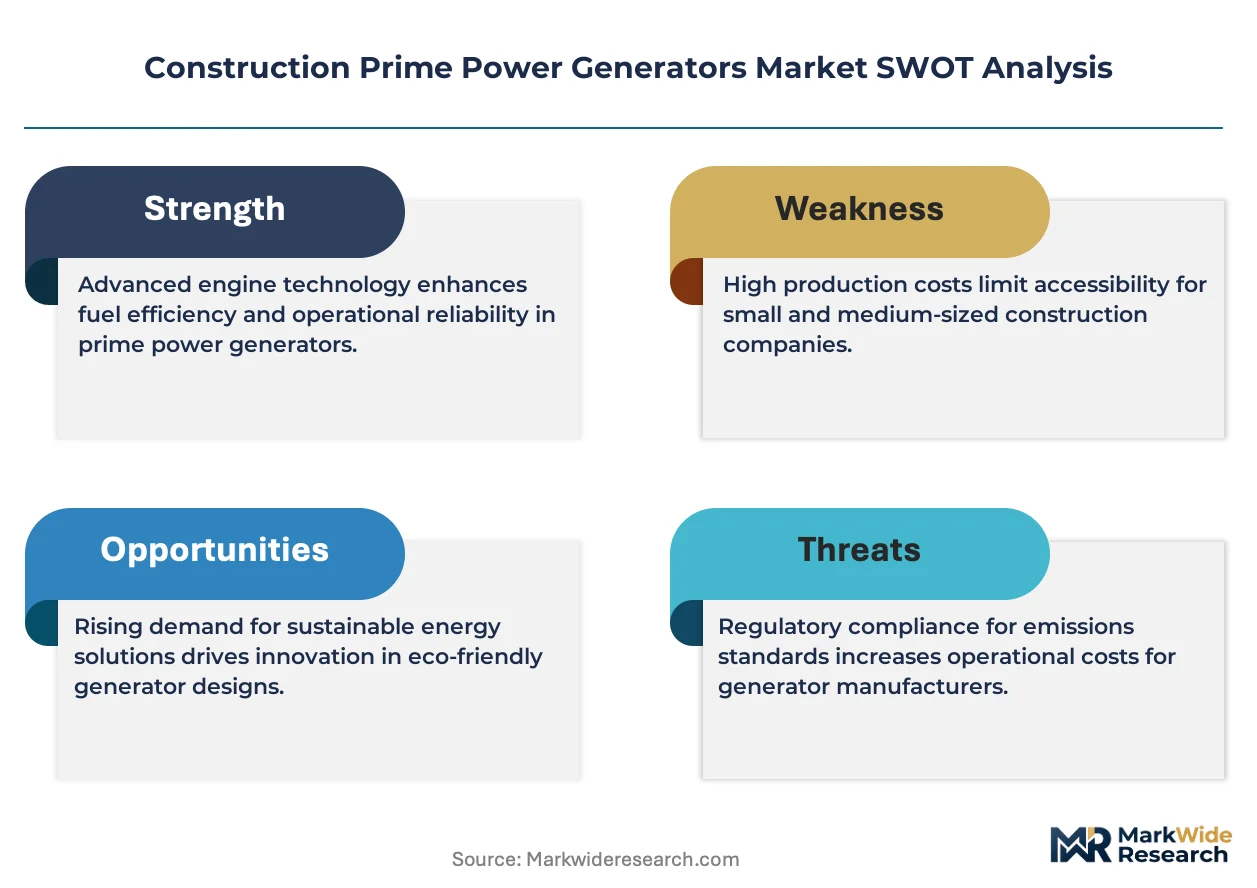
- EPA Tier 4 Final mandates:North American contractors face phased compliance deadlines that force fleet turnover toward certified prime power packages, sustaining replacement demand through the forecast window.
- India's national highway expansion:The National Highways Authority of India requires reliable off-grid power for remote construction camps spanning multi-year build phases, concentrating genset procurement in this geography.
- Dual-fuel engine technology:Natural gas-diesel blending systems enable fuel arbitrage where pipeline infrastructure exists, attracting mining operators and oilfield developers seeking operating cost flexibility.
Market Restraints
- Steel and copper input volatility:Generator enclosures and winding materials expose OEMs to commodity price swings that compress manufacturing margins without corresponding pricing power.
- Emissions aftertreatment complexity:Selective catalytic reduction and diesel exhaust fluid systems add capital cost and maintenance burden, lengthening payback periods for contractor fleets.
- Grid extension in mature markets:Utility electrification of construction corridors in Western Europe reduces addressable market for prime-rated mobile power.
Strategic Opportunities
- Southeast Asia megaproject corridors:Indonesia's new capital development and Vietnam's expressway networks create demand for continuous-duty power at permanent construction campuses lacking grid access.
- CEA grid reliability mandates:India's Central Electricity Authority standards for backup power at critical infrastructure sites create a compliance-driven procurement channel distinct from commercial construction.
- Hybrid battery-genset architectures:Lithium-ion buffer systems paired with prime-rated engines enable load leveling and fuel optimization, opening premium pricing tiers for technology-integrated suppliers.
Industry Challenges
- Emissions certification timelines:EPA and EU type-approval processes for new engine platforms extend 18-24 months, delaying product launches and freezing R&D capital.
- Aftertreatment technician scarcity:SCR and DEF system diagnostics require specialized training that construction equipment service networks lack, extending downtime and eroding customer satisfaction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Prime Power Generators Market |
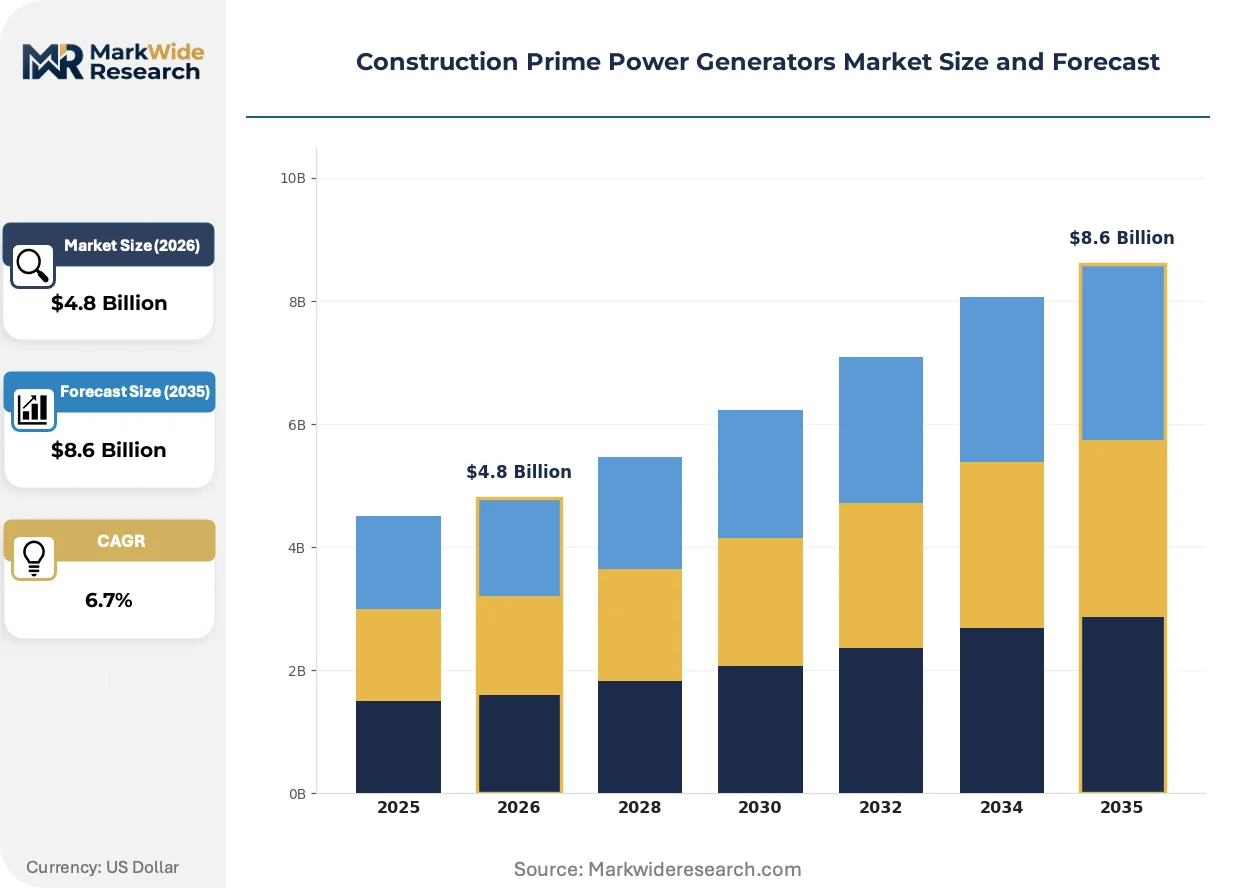
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gasoline Generators, Natural Gas Generators, Dual Fuel Generators, Bi-Fuel Generators Technology: Standby, Continuous, Prime, Peak Shaving, Load Management Application: Construction Sites, Mining Operations, Infrastructure Projects, Remote Worksites, Oilfield Sites End User Industry: General Contracting, Heavy Equipment Rental, Earthworks, Civil Engineering, Utilities Maintenance |
| Companies Covered | Caterpillar, Cummins, Generac Power Systems, Kohler, Atlas Copco, Mitsubishi Heavy Industries, MTU Onsite Energy, FG Wilson, Himoinsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Prime Power Generators Market Trends and Innovations
Prime power generator technology is pivoting from standalone diesel engines toward integrated power nodes that blend combustion assets with energy storage and digital load management. This convergence is compressing the traditional specification gap between construction-site mobility and permanent-installation efficiency.
Modular natural gas gensets is supplanting conventional diesel packages in pipeline-accessible construction corridors. Mining operators in Australia and oilfield developers in the Permian Basin are specifying these units for 24/7 duty cycles. The technology is supplanting diesel's historical dominance in continuous-load applications where fuel logistics favor gaseous infrastructure.
EU Stage V standards enforced by national type-approval authorities are mandating particulate number limits that diesel engines can only meet through complex aftertreatment. Equipment lessors in Germany and France are accelerating fleet turnover to avoid stranded assets. Contractors are responding by extending lease terms on pre-Stage V units in non-regulated export markets while staging capital for compliant replacements.
Rental channel consolidation is reshaping how construction fleets access prime power. National equipment lessors are unbundling maintenance from base rental rates, forcing OEMs to compete on lifecycle cost transparency rather than upfront capital. This pattern is most visible in the United States, where United Rentals and Sunbelt Rentals dictate specification standards that flow back to manufacturer R&D priorities.
Construction Prime Power Generators Market Segmentation
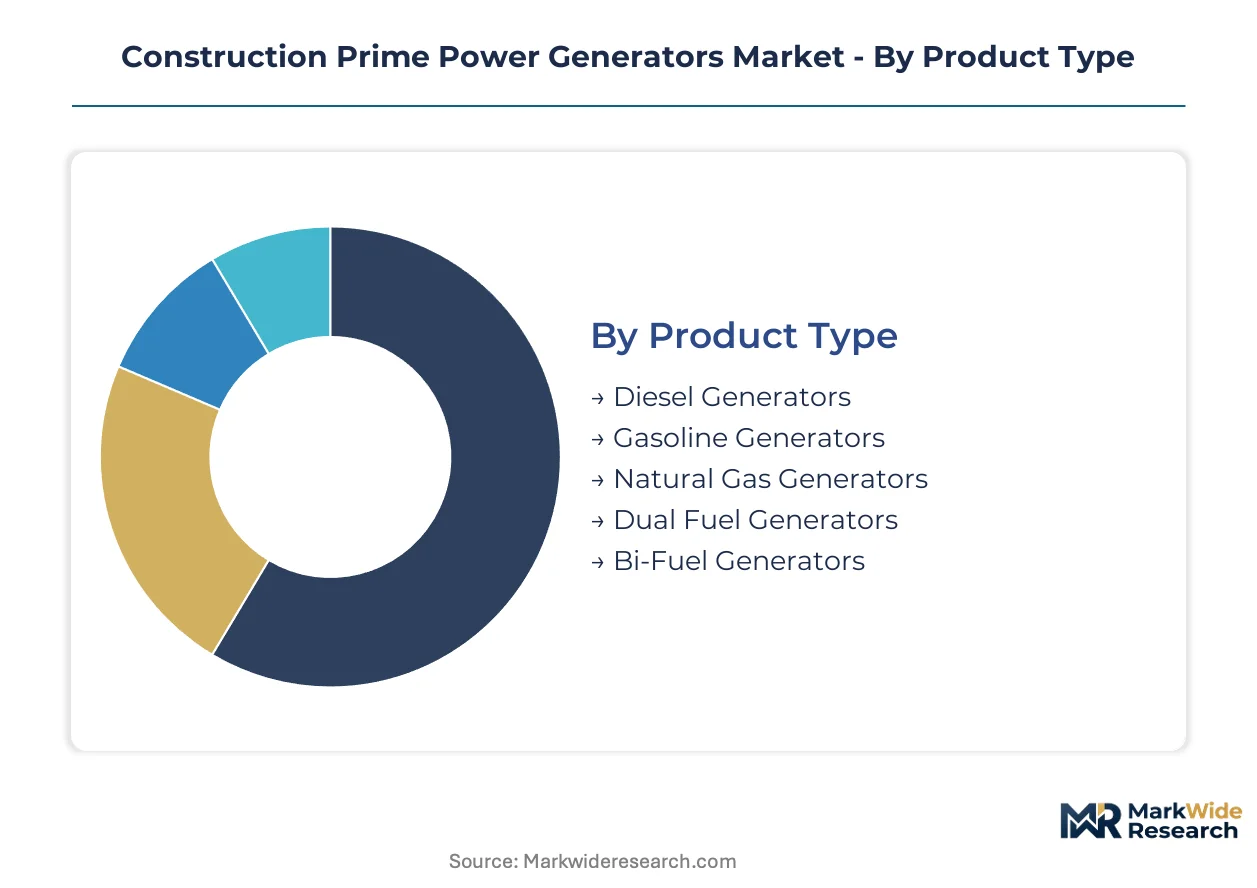
Segmentation in the construction prime power generators market reveals how equipment specifications diverge across duty cycles, fuel access, and project duration. Procurement patterns vary sharply between intermittent standby deployments and continuous-duty mining operations, reshaping manufacturer product roadmaps and rental fleet composition.
Product Type:
Margin pools concentrate in emission-compliant diesel platforms and dual-fuel systems that command premium pricing for regulatory flexibility.
- Diesel Generators:Compression-ignition engines delivering 50 kW to 3,000 kW with sustained torque response for heavy starting loads. Demand clusters in India's national highway corridors where fuel logistics favor established distribution networks and BIS fuel standards ensure supply reliability. EPA Tier 4 Final aftertreatment adds capital cost but sustains fleet eligibility for public works contracts.
- Dual Fuel Generators:Blending architectures that substitute 30-70% diesel with natural gas through fumigation or port injection, enabling arbitrage where pipeline infrastructure exists. Mining operators in Australia's Pilbara region specify these units for 24/7 duty cycles, attracted by operating cost flexibility against volatile diesel pricing. The technology is gaining traction fastest in oilfield developments with captive gas supplies.
- Natural Gas Generators:Spark-ignition units requiring pipeline or compressed gas logistics, prevalent in permanent construction campuses with stationary fueling infrastructure.
- Gasoline Generators:Portage-scale units under 50 kW for light-duty tool power and temporary lighting, common in residential construction sub-markets.
- Bi-Fuel Generators:Switchable systems operating independently on either fuel type rather than simultaneous blend, offering operational redundancy for remote worksites.
The dominant share belongs to diesel generators, while dual fuel generators are closing the gap fastest.
Technology:
Application requirements dictate technology selection, with continuous and prime-rated configurations capturing the highest equipment value per kilowatt.
- Prime:Engine-generator packages rated for unlimited hours of variable load operation without time restrictions, specified for multi-year infrastructure builds lacking grid connection. India's smart city developments and Indonesia's new capital construction rely on prime-rated fleets for sustained power availability. These configurations command rental premiums over standby equivalents due to heavier-duty cooling and lubrication systems.
- Continuous:Fixed-load operation at constant output, typical of base-load mining camps and oilfield facilities where demand profiles remain stable. Australian iron ore operations specify continuous-rated units for processing plant power, prioritizing fuel efficiency over load-following capability. The segment attracts long-term lease structures spanning equipment depreciation cycles.
- Standby:Emergency backup duty with limited annual operating hours, common in grid-connected construction offices and temporary facilities.
- Peak Shaving:Grid-parallel operation reducing demand charges during utility peak periods, emerging in electrified construction corridors with time-of-use pricing.
- Load Management:Digital control systems optimizing multiple genset dispatch against variable demand, penetrating civil engineering applications seeking fuel optimization.
Prime-rated technology holds the largest revenue share, with continuous-rated configurations expanding most quickly in resource extraction sectors.
Application:
Project duration and grid proximity determine equipment specification intensity across construction deployment scenarios.
- Mining Operations:Isolated extraction sites requiring 24/7 power for crushing, processing, and camp facilities over decade-long mine life cycles. Western Australia's gold and iron ore belts represent concentrated demand for 1,000+ kW prime-rated installations with modular scalability. Diesel and dual-fuel dominance persists due to remoteness from pipeline infrastructure.
- Infrastructure Projects:Multi-year civil works including highways, bridges, and urban rail with phased power requirements evolving from construction to commissioning. Vietnam's expressway networks and India's dedicated freight corridors drive procurement of transportable 200-500 kW units with rapid redeployment capability. Rental channel penetration is highest in this segment.
- Construction Sites:General building activity with shorter-duration power needs, typically served by rental fleet standby and prime packages under 300 kW.
- Oilfield Sites:Exploration and production facilities with explosive atmosphere requirements and harsh environmental specifications.
- Remote Worksites:Scientific, military, or telecommunications installations with extreme logistics constraints and low equipment density.
Mining operations command the highest absolute equipment value, though infrastructure projects are gaining share fastest as public capital deployment accelerates across Southeast Asia.
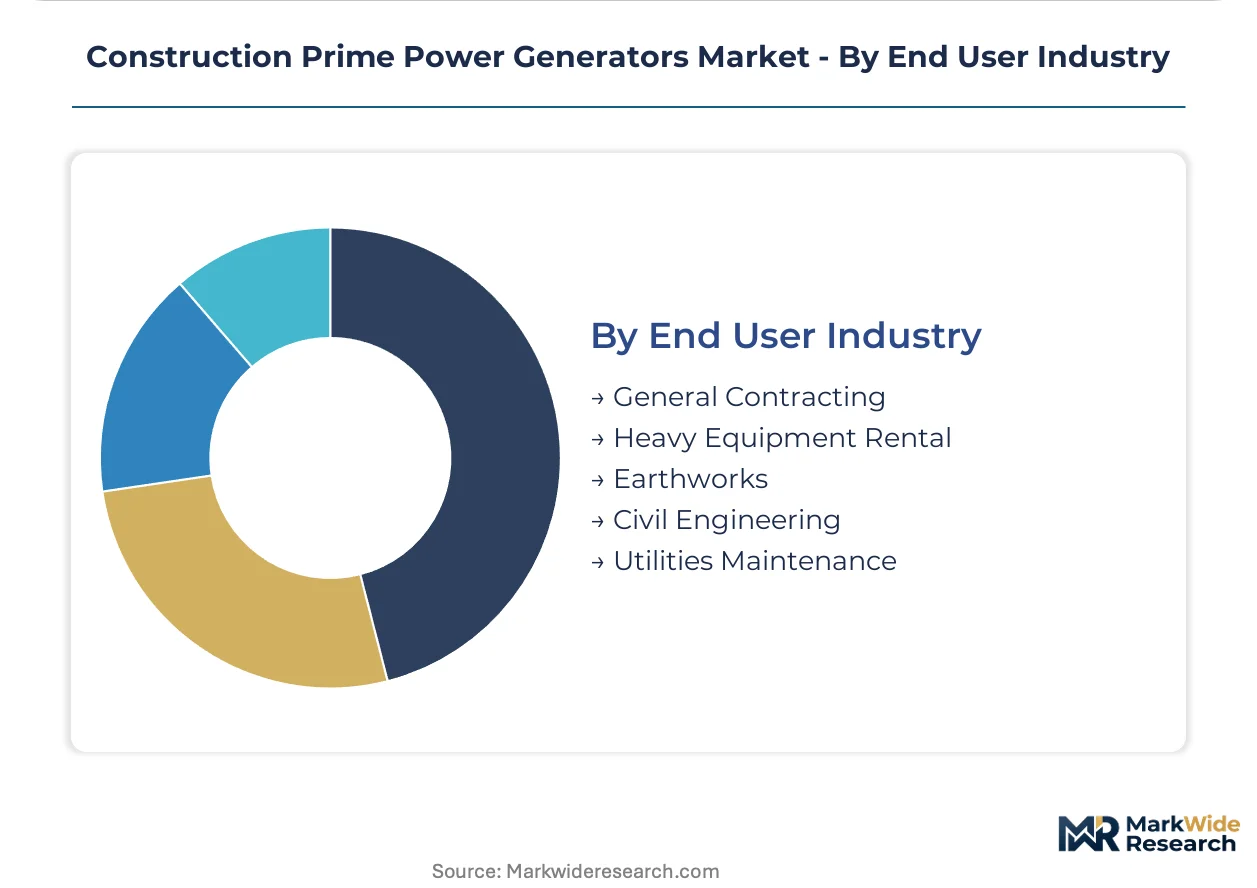
End User Industry:
Customer sophistication and fleet scale differentiate procurement behavior across contractor categories.
- Heavy Equipment Rental:National lessors including United Rentals and Sunbelt Rentals aggregating demand across fragmented contractor bases, dictating manufacturer specification standards through volume purchasing. These entities prioritize lifecycle cost transparency and telematics integration over upfront capital, compressing OEM margins while capturing aftermarket service revenue.
- Civil Engineering:Specialized contractors executing dams, tunnels, and water treatment facilities with extended project horizons and complex load profiles. German and French civil engineering firms face EU Stage V compliance deadlines that accelerate fleet turnover toward certified prime power packages, with equipment lessors staging capital for compliant replacements.
- General Contracting:Diverse residential and commercial builders with intermittent, short-duration power needs typically served through rental channels.
- Earthworks:Site preparation and excavation specialists with high-torque starting requirements favoring diesel generator torque response.
- Utilities Maintenance:Grid infrastructure contractors requiring portable power for transmission line work and substation construction, often with live-line safety specifications.
Heavy equipment rental commands the dominant procurement volume, while civil engineering is climbing the fastest as megaproject scale concentrates demand with specialized contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction prime power generator trade flows tilt toward import dependence in infrastructure-heavy economies while manufacturing-scale exporters consolidate supply positions. Equipment procurement concentrates where megaproject pipelines outstrip domestic production capacity, reshaping regional competitive dynamics.
United States
Highway modernization and data center construction drive sustained demand for EPA Tier 4 Final certified units. Contractors face phased compliance deadlines that accelerate fleet turnover toward aftertreatment-equipped packages. Equipment lessors in Texas and California dictate specification standards through volume purchasing agreements with manufacturers.
Germany
EU Stage V type-approval requirements compress diesel generator margins while accelerating rental channel consolidation. Civil engineering firms in Bavaria and North Rhine-Westphalia stage capital for compliant replacements to avoid stranded assets. National equipment lessors unbundle maintenance from base rental rates, forcing OEM competition on lifecycle cost transparency.
India
National highway expansion and smart city investments concentrate genset procurement in Maharashtra and Gujarat. CEA grid reliability mandates create compliance-driven procurement channels distinct from commercial construction. BIS fuel quality standards shape import requirements for foreign suppliers bidding on public works contracts.
Australia
Mining operations in Western Australia's Pilbara region specify 1,000+ kW prime-rated installations with modular scalability. Dual-fuel technology captures share where captive gas supplies exist at oilfield developments. Continuous-duty configurations attract long-term lease structures spanning equipment depreciation cycles.
Indonesia
New capital development in East Kalimantan creates demand for continuous-duty power at permanent construction campuses lacking grid access. Infrastructure corridors spanning the Java-Sumatra axis require transportable units with rapid redeployment capability. National type-approval processes for imported equipment extend procurement timelines for foreign OEMs.
Construction Prime Power Generators Market Competitive Landscape
Concentration sits with integrated engine-generator manufacturers and national equipment lessors who aggregate fragmented contractor demand. The vendor base stratifies across three tiers: full-system OEMs controlling certification costs, modular architecture specialists optimizing transport logistics, and regional fabricators serving price-sensitive procurement channels. Dominant competitive moves include rental channel consolidation through maintenance unbundling and hybrid battery-genset technology licensing for premium positioning.
Within the full-system OEM tier, Caterpillar and Cummins occupy positions that exemplify divergent strategic approaches to emissions compliance and fleet mobility. Caterpillar leverages integrated manufacturing footprints to manage EPA and EU certification costs across North American and European job sites. Cummins sustains positioning through modular power node architectures that simplify transport between remote infrastructure locations. Both represent how scale-driven manufacturers respond to rental channel consolidation that compresses upfront equipment margins while capturing aftermarket service revenue.
| Leading Market Players |
|---|
| Caterpillar |
| Cummins |
| Generac Power Systems |
| Kohler |
| Atlas Copco |
| Mitsubishi Heavy Industries |
| MTU Onsite Energy |
| FG Wilson |
| Himoinsa |
| Others |
Pricing and Supply Chain Analysis
Engine-generator manufacturing scale in India and China anchors global cost floors for prime-rated gensets, compressing margins for regional fabricators while concentrating procurement leverage with national equipment lessors. This scale dynamic simultaneously shapes supply geography and pricing power distribution across EPA Tier 4 Final and EU Stage V compliance tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across prime power procurement, with rental fleet operators capturing volume discounts against spot-market contractors. Price differentiation separates EPA-certified premium tiers from pre-compliance economy units, while steel and copper input volatility intensifies cost compression in standard-grade manufacturing. Price sensitivity concentrates among general contractors with intermittent project pipelines, whereas mining operators with decade-long camp power requirements absorb certification premiums for reliability assurance.
Supply Chain Analysis
China, India, and Germany anchor engine block casting and alternator winding production for construction prime power generators. Manufacturing draws from steel enclosures, copper windings, and emissions aftertreatment catalysts sourced through specialized tier-2 suppliers. Single-source vulnerability concentrates in selective catalytic reduction substrate supply, where limited qualified vendors extend procurement timelines. Distribution runs through national equipment lessor networks that aggregate fragmented contractor demand across North American and European job sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent generator OEMs face substitution pressure from hybrid battery-genset architectures and grid extension in mature markets, requiring defensive repositioning around service revenue capture and emissions compliance leadership.
For Market Incumbents: Compound aftermarket service attachment rates through predictive maintenance telemetry and SCR/DEF system lifecycle contracts. Defend against stranded asset risk by accelerating EU Stage V fleet turnover in Germany and France while extending lease terms on pre-compliant units to export markets. Prioritize certification investment in dual-fuel engine platforms to capture mining operator procurement in Australia's Pilbara region.
For New Entrants and Emerging Players: Differentiate on modular transportability and rapid deployment capability for Southeast Asia megaproject corridors. Target Indonesia's new capital development and Vietnam's expressway networks where grid absence sustains continuous-duty demand. Penetrate through equipment leasing partnerships with regional contractors lacking capital for fleet ownership.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among national equipment lessors with maintenance-unbundled rental structures and telematics-enabled service contracts. Long-term viability favors targets with EPA and EU type-approval capabilities spanning 500-2,000 kW prime-rated configurations. Watch hybrid battery-genset technology licensing activity as inflection signal for technology-integrated premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engine Certification | Captures mining operator procurement in Australia's Pilbara and Permian Basin oilfield developments. |
| Hybrid Battery-Genset Integration | Opens premium pricing tiers through lithium-ion load leveling and fuel optimization capabilities. |
| Telematics-Enabled Service Contracts | Transforms transactional equipment sales into recurring revenue streams with predictive maintenance. |
| Southeast Asia Distribution Partnership | Secures access to Indonesia's new capital and Vietnam's expressway megaproject pipelines. |
| Emissions Aftertreatment Vertical Integration | Reduces SCR/DEF system cost exposure and accelerates EPA Tier 4 Final certification timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors at national equipment lessors, maintenance managers at mining operations, project engineers at civil engineering contractors, and aftermarket service heads at OEM distribution networks. Secondary validation drew from EPA engine certification databases, EU type-approval registries, customs trade data for genset imports, and BIS fuel quality standards documentation. Bottom-up equipment shipment estimates triangulated against top-down infrastructure investment projections across the analysis window.
Across the projection horizon, forecasts modeled segmentation by fuel type, technology rating, application intensity, and end-user procurement channel. CAGRs derived from equipment replacement cycles tied to emissions compliance deadlines and megaproject pipeline visibility. Industry-specific inputs included India's CEA grid reliability mandate enforcement patterns and rental fleet utilization rates reported by national lessors.
Decision-makers should treat outputs as directional under sustained infrastructure capital deployment and stable emissions regulatory trajectories; material deviation in commodity input costs or compliance deadline extensions would warrant model refresh. Recalibration cycles align with material shifts in mining investment sentiment and Southeast Asian public works procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Asia-Pacific Diesel Generator Market
Generators
Telecom Generator Market
Generators
Mobile Generators Market
Generators
Dual-Fuel Generator Market
Generators
Commercial Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Digital Inverter Generator Market
Generators
Nuclear Turbine Generators Market
Generators
Global Diesel Gensets Market
Generators
Gasoline Generator Market
Generators
Construction Portable Generators Market
Generators
Multi Fuel Generators Market
Generators
South Africa Diesel Generator Market
Generators
Wind Turbine Alternator Market
Generators
Emergency Power Generators Sales Market
Generators
Generator Belt Market