
 Europe Turbo Generator Market | 2026-2036
Europe Turbo Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Turbo Generator Market Foresight
Ultra-high efficiency specifications above 60 percent combined-cycle thermal efficiency are redrawing competitive boundaries in the Europe Turbo Generator Market. Siemens AG leverages its hydrogen-ready turbine portfolio to anchor German industrial demand. Ansaldo Energia SpA specializes in heavy-duty gas turbine retrofits, sustaining its position across Italian power plants. General Electric Company competes through advanced air-cooled generator technology, extending its reach into Eastern European combined-cycle installations.
A turbo generator converts mechanical energy from a turbine into electrical energy through electromagnetic induction, typically operating at synchronous speeds with power outputs ranging from tens of megawatts to over one gigawatt and employing hydrogen or air cooling for thermal management. Steam turbines dominate base-load power generation across established European nuclear and coal fleets, while gas turbines capture expanding load-following roles as renewable penetration rises. Combined cycle configurations concentrate the highest margin pools by maximizing fuel efficiency, whereas hydroelectric turbines occupy mature, regulated segments with limited new site availability.
CE marking under the EU Machinery Directive governs equipment safety and market access, while the EU Green Deal and F-Gas Regulation mandate progressive decarbonization and refrigerant phase-downs that reshape turbine cooling system specifications. EMA guidelines on industrial emissions and REACH chemical compliance further constrain material selection and lubricant chemistry for original equipment manufacturers. Stakeholders must monitor hydrogen blending mandates and carbon border adjustments to calibrate R&D spending and supply chain sourcing ahead of regulatory tightening.
Market Dynamics
Hydrogen-readiness mandates under the EU Green Deal are forcing turbine OEMs to redesign combustion systems and cooling architectures ahead of binding blending targets, compressing R&D timelines and supplier qualification windows across the European supply base.
Growth Catalysts
- Grid Balancing Demand:Renewable intermittency in Germany and Spain is pulling gas turbines into mid-merit dispatch roles, expanding unit operating hours and replacement part consumption.
- F-Gas Phase-Down:The EU F-Gas Regulation is accelerating conversion from fluorinated refrigerants to hydrogen-based cooling in generator stator windings, creating retrofit demand across existing French and Italian installations.
- Industrial CHP Expansion:Chemical and refining clusters in the Netherlands and Belgium are deploying large-frame turbines for captive power and steam cogeneration, anchoring order books for heavy-duty equipment.
Market Restraints
- Specialized Forging Capacity:Rotor forging for large gas turbines concentrates among a handful of European and Japanese suppliers, creating multi-year lead time bottlenecks for new unit deliveries.
- Copper and Rare Earth Volatility:Stator winding copper and permanent magnet materials face price swings that compress generator margin pools and complicate long-term project contracting.
- Nuclear Decommissioning Drag:Scheduled closures of French and German nuclear baseload are reducing steam turbine overhaul volumes faster than gas turbine growth can offset.
Strategic Opportunities
- Hydrogen Hub Alignment:Poland and Romania are emerging as priority markets where EU hydrogen valley funding can anchor first-mover turbine deployments for industrial off-takers.
- Digital Twin Services:Remote monitoring and predictive maintenance subscriptions are opening recurring revenue streams independent of new equipment sales cycles.
- Biomass and Waste-to-Energy Retrofit:Existing steam turbine fleets in Nordic district heating networks present conversion opportunities for sustainable fuel integration.
Industry Challenges
- Turbomachinery Engineering Talent:Retirement waves among European designers fluent in aeromechanical analysis and combustion physics are narrowing the pipeline for complex turbine development programs.
- Hydrogen Combustion Certification:Validating flame stability and emissions performance across variable hydrogen blends requires extended test campaigns that delay product launches and customer commitments.
- Legacy Control System Integration:Modern digital turbine controllers must interface with decades-old plant DCS architectures, stretching commissioning timelines and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Turbo Generator Market |
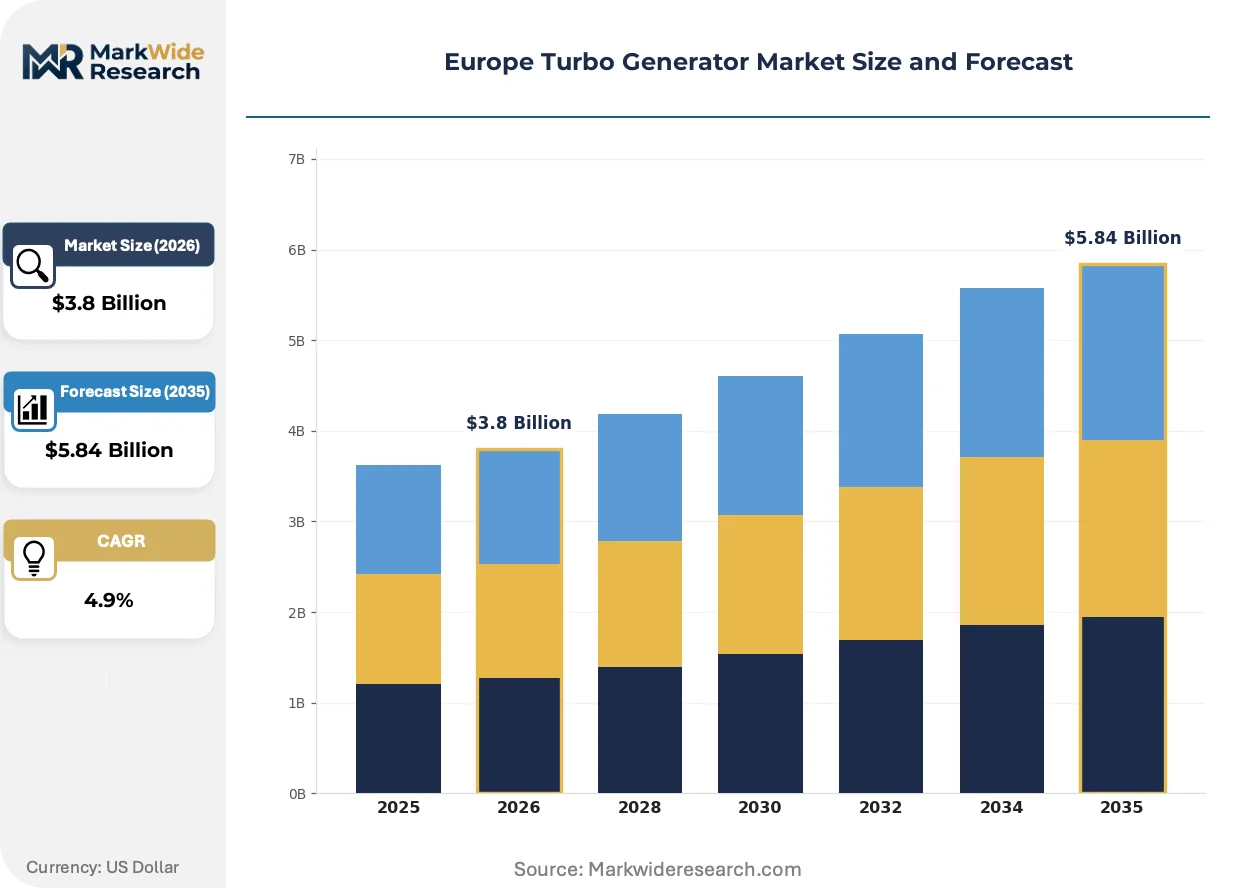
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Turbines, Gas Turbines, Hydroelectric Turbines, Combined Cycle Turbines End User: Power Generation, Oil & Gas, Marine, Industrial Application: Base Load, Load Following, Peaking, Combined Heat and Power Installation: Onshore, Offshore, Industrial Sites, Power Plants |
| Companies Covered | Andritz AG, Ansaldo Energia SpA, Siemens AG, Centrax Gas Turbines Limited, Kawasaki Heavy Industries Ltd, Toshiba Corporation, Mitsubishi Heavy Industries Ltd, MAN Energy Solutions, General Electric Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Turbo Generator Market Shifts & Advancements
Turbine technology trajectories are diverging between efficiency-maximizing combined-cycle designs and flexibility-optimized units for renewable balancing, with cooling system chemistry and combustion architecture as the primary pivot points.
Advanced air-cooled generator technology is bifurcating the high-capacity segment. Hydrogen-cooled units above 500 MW retain efficiency advantages for baseload combined-cycle plants in Germany and France, while air-cooled designs below 300 MW capture distributed generation and industrial CHP applications where simplified maintenance and eliminated hydrogen infrastructure outweigh thermal performance trade-offs. European utilities are segmenting procurement portfolios across both tracks.
REACH compliance and the EU F-Gas Regulation are reshaping material specifications for stator insulation and rotor cooling systems. Restrictions on perfluorinated compounds are forcing reformulation of generator sealants and bearing lubricants, with OEMs qualifying bio-based alternatives through accelerated aging protocols. Italian and Spanish operators face compressed retrofit windows as 2027 phase-down deadlines approach.
Power purchase agreement structures are fragmenting traditional equipment procurement. European independent power producers now unbundle turbine supply from long-term service agreements, selecting OEMs on capital cost while negotiating aftermarket support with third-party specialists or in-house engineering teams. This pattern concentrates in British and Nordic markets where merchant exposure and renewable cannibalization risk have shifted buyer preference toward capital discipline over lifecycle bundling.
Europe Turbo Generator Market Segmentation
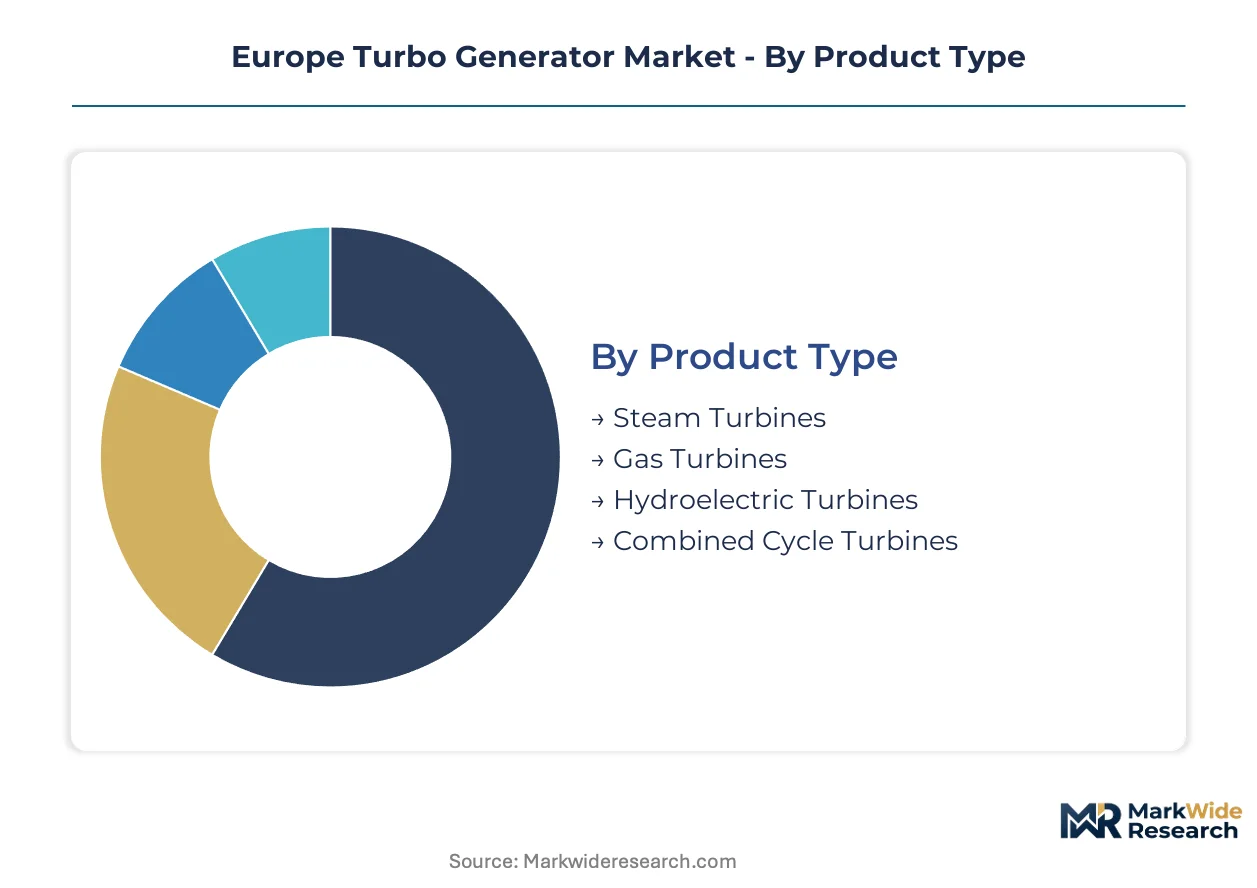
Turbo generator procurement patterns diverge sharply across product architectures and duty cycles. CE marking requirements and EU Green Deal compliance timelines create distinct qualification burdens that reshape segment economics.
Product Type:
Regulatory differentiation under the EU F-Gas Regulation and hydrogen-readiness mandates splits procurement priorities across cooling architectures and fuel flexibility specifications.
- Steam Turbines:These units convert thermal energy from high-pressure steam into rotational mechanical energy through multi-stage blade configurations, typically achieving thermal efficiencies above 40 percent in modern reheat cycles. German and French nuclear baseload fleets anchor overhaul demand, though scheduled decommissioning compresses long-term service contract values. Established volume favors Steam Turbines; emerging adoption favors Combined Cycle Turbines.
- Gas Turbines:Aeroderivative and heavy-frame designs combust natural gas or hydrogen blends to drive axial compressors and power turbines, with output flexibility spanning 50-400 MW for grid balancing roles. Spanish and German utilities are pulling these units into mid-merit dispatch as renewable penetration rises, extending operating hours and consumables demand.
- Hydroelectric Turbines:Francis, Kaplan, and Pelton runners extract energy from water head and flow, operating at synchronous speeds with minimal emissions. Nordic district heating networks and Alpine run-of-river sites concentrate remaining installation activity where environmental permitting allows.
- Combined Cycle Turbines:Integrated gas and steam turbine configurations recover exhaust heat through heat recovery steam generators, pushing thermal efficiency above 60 percent. Netherlands and Belgian chemical clusters are deploying large-frame units for captive power and process steam.
Established volume favors Steam Turbines; emerging adoption favors Combined Cycle Turbines.
End User:
Cost tier differentiation separates utility-scale procurement with long amortization horizons from industrial buyers prioritizing operational flexibility over capital efficiency.
- Power Generation:Grid-connected utilities and independent power producers operate units across baseload, intermediate, and peaking duty cycles with regulatory-mandated availability requirements. German transmission system operators specify hydrogen-ready equipment for future blending compatibility.
- Oil & Gas:Upstream platforms and downstream refineries deploy turbines for mechanical drive, power generation, and process heat in remote or hazardous environments. North Sea installations drive offshore specification demand.
- Marine:Naval vessels and commercial shipping integrate turbo generators for propulsion and auxiliary power, with classification society rules governing shock resistance and redundancy. Italian and Greek ferry operators are retrofitting for emissions compliance.
- Industrial:Chemical, cement, and steel facilities deploy captive generation for electricity and steam cogeneration, optimizing around thermal demand profiles rather than grid dispatch signals. Rotterdam and Antwerp port clusters anchor heavy-duty orders.
Power Generation captures the dominant installed base; Industrial end-use is climbing the fastest on CHP expansion.
Application:
Application segmentation tracks duty cycle intensity and revenue model structure, from regulated capacity payments to merchant energy sales.
- Base Load:Continuous operation at rated capacity maximizes capacity factor and energy sales, requiring designs optimized for thermal efficiency and maintenance interval extension. French nuclear steam turbines and German lignite units historically dominated this category.
- Load Following:Variable output tracking demand curves and renewable generation ramps stresses thermal cycling and startup frequency, favoring aeroderivative gas turbines with fast ramp rates. Iberian utilities are procuring specifically for this duty.
- Peaking:Infrequent high-output operation during demand spikes or supply shortfalls prioritizes startup reliability over fuel efficiency, with oil-fired units retaining niche roles. British capacity market auctions sustain limited procurement.
- Combined Heat and Power:Simultaneous electricity and useful heat production elevates total system efficiency above 80 percent, with district heating networks in Denmark and Finland representing mature deployment.
Base Load retains the largest operating hour base; Load Following is gaining share fastest on renewable integration mandates.
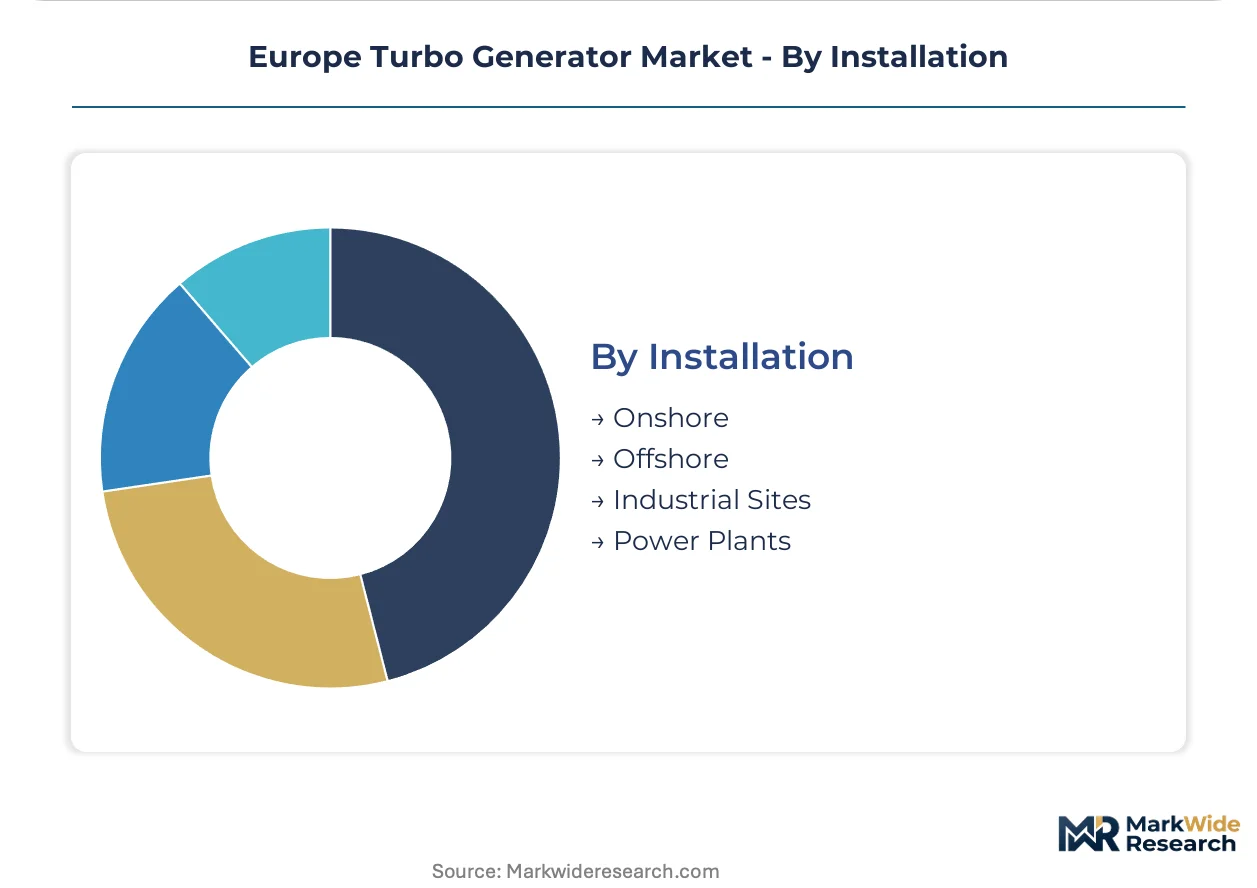
Installation:
Installation environment dictates enclosure specifications, foundation requirements, and logistics complexity, with offshore and industrial site categories commanding specialized engineering.
- Onshore:Ground-mounted installations at dedicated power plant sites with established grid interconnection and fuel supply infrastructure. Polish and Romanian greenfield developments are concentrating new capacity.
- Offshore:Platform-mounted or floating installations exposed to marine corrosion, vibration, and limited maintenance access windows. North Sea oil and gas decommissioning is reducing this segment's growth trajectory.
- Industrial Sites:Integration within existing process facilities requiring steam extraction, noise mitigation, and space-constrained layouts. Benelux chemical corridors dominate European demand.
- Power Plants:Purpose-built generation facilities with optimized thermal cycles, cooling water systems, and emissions control equipment. German combined-cycle replacements are sustaining order flow.
Power Plants anchor the replacement cycle; Industrial Sites show the steepest expansion trajectory on captive generation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Benelux chemical corridors show the lowest price elasticity, prioritizing thermal efficiency and hydrogen readiness over capital cost, while Polish and Romanian utilities remain acutely sensitive to upfront equipment pricing amid constrained balance sheets.
Germany
Transmission system operators specify hydrogen-ready combined-cycle units for grid balancing as renewable penetration exceeds 50 percent of generation mix. The EU Green Deal mandates progressive hydrogen blending targets that compress OEM qualification timelines. Industrial clusters in North Rhine-Westphalia anchor heavy-duty turbine deployments for captive power and process steam cogeneration.
France
Scheduled nuclear baseload closures are reducing steam turbine overhaul volumes while gas turbine retrofits accelerate for mid-merit dispatch roles. EMA industrial emissions guidelines constrain lubricant chemistry and material selection for generator rebuilds. The Dunkirk and Fos-sur-Mer port corridors concentrate hydrogen hub development tied to turbine offtake agreements.
Italy
Ageing gas turbine fleets across the Po Valley and Lombardy industrial belt drive heavy-frame retrofit demand as operators seek F-Gas Regulation compliance before 2027 phase-down deadlines. Ansaldo Energia SpA anchors domestic supply capacity for combustion system upgrades. REACH chemical compliance is forcing reformulation of stator insulation materials across existing installations.
Netherlands
Rotterdam and Antwerp port clusters deploy large-frame combined-cycle units for chemical sector captive generation, prioritizing total system efficiency above 80 percent through heat recovery steam generators. The EU F-Gas Regulation accelerates conversion from fluorinated refrigerants to hydrogen-based cooling in generator stator windings. Grid balancing contracts pull aeroderivative turbines into peaking and load-following service.
Poland
EU hydrogen valley funding is anchoring first-mover turbine deployments for industrial off-takers in the Silesian and Łódź manufacturing basins. CE marking under the EU Machinery Directive governs equipment safety and market access for greenfield installations. Utilities balance capital cost sensitivity against long-term fuel flexibility requirements as coal phase-out accelerates.
Europe Turbo Generator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated industrial conglomerates dominating high-efficiency combined-cycle development while specialized turbomachinery firms capture retrofit and service niches. The vendor base concentrates among European and Japanese engineering groups with captive forging capacity and combustion test facilities. Three archetypes define competitive positioning: full-stack OEMs with hydrogen-ready portfolios, heavy-duty retrofit specialists, and aeroderivative-focused technology licensors. Capacity expansion into hydrogen combustion certification and strategic partnerships for digital twin services represent the dominant competitive moves reshaping alliance structures.
Among German industrial conglomerates, Siemens AG exemplifies the full-stack archetype through integrated turbine-generator offerings, while General Electric Company occupies a position bridging European and North American technology streams. Ansaldo Energia SpA represents the heavy-duty retrofit specialist model, anchoring service-intensive relationships across Mediterranean installed bases. These three firms collectively illustrate how geographic origin and corporate structure shape strategic positioning without converging on identical capability profiles.
| Leading Market Players |
|---|
| Andritz AG |
| Ansaldo Energia SpA |
| Siemens AG |
| Centrax Gas Turbines Limited |
| Kawasaki Heavy Industries Ltd |
| Toshiba Corporation |
| Mitsubishi Heavy Industries Ltd |
| MAN Energy Solutions |
| General Electric Company |
| Others |
Supply & Pricing Matrix
Rotor forging scale economies concentrate among European and Japanese suppliers, compressing price floors for large gas turbine units while elevating bargaining power for qualified vendors serving German and French utilities. This concentration cascades through generator stator winding costs and hydrogen-ready combustion system premiums, with CE marking compliance and F-Gas phase-down timelines layering qualification costs onto delivered equipment pricing.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across hydrogen-cooled and air-cooled generator architectures. Pricing stratifies across premium hydrogen-ready combined-cycle systems, standard air-cooled distributed generation units, and economy-tier retrofit packages for existing steam turbine fleets. Cost compression in the standard tier is intensifying because copper and rare earth magnet volatility compresses generator margin pools. Industrial buyers in Benelux chemical corridors show the lowest price sensitivity, prioritizing thermal efficiency and hydrogen readiness, while Polish utilities remain acutely sensitive to upfront capital cost.
Supply Chain Analysis
Germany and Japan anchor specialized forging capacity for large gas turbine rotors, with Italy and France concentrating precision machining for combustion system components. The European supply chain draws from copper stator windings sourced through global commodity markets, rare earth permanent magnets centered on Asian processing facilities, and hydrogen-ready alloy formulations qualified under REACH compliance protocols. Single-source vulnerability concentrates in rotor forging, where multi-year lead times create bottleneck exposure for new unit deliveries. Distribution runs through EPC contractors and OEM direct sales channels into utility and industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward European utilities consolidating procurement through unbundled turbine supply and third-party service agreements, fragmenting traditional OEM lifecycle bundling.
For Market Incumbents: Compound hydrogen combustion certification investments to preempt regulatory tightening under EU Green Deal blending mandates. Secure captive forging capacity through backward integration into Japanese or European supplier relationships. Defend against independent service specialists by embedding digital twin subscriptions that create switching costs for utility fleet operators. For New Entrants and Emerging Players: CE marking fast-track services for hydrogen-ready retrofits open white-space entry into Italian and Spanish F-Gas compliance deadlines. Target Polish and Romanian hydrogen valley deployments where EU funding reduces customer capital constraints. Enter through aeroderivative gas turbine niches for load-following applications, leveraging modular designs that bypass heavy-frame forging bottlenecks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital twin and predictive maintenance platforms over pure equipment manufacturing. Long-term viability hinges on recurring revenue streams decoupled from new equipment sales cyclicality. Monitor hydrogen hub offtake agreement velocity as the inflection signal for turbine deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Combustion Certification | EU Green Deal mandates validate flame stability across variable hydrogen blends ahead of binding targets. |
| Digital Twin Platform Launch | Siemens AG and GE extend recurring revenue through remote monitoring subscriptions independent of equipment sales. |
| Rotor Forging Capacity Expansion | Japanese and European suppliers compress multi-year lead times bottlenecking German utility procurement. |
| CE Marking Fast-Track Services | Ansaldo Energia SpA captures Italian retrofit demand ahead of 2027 F-Gas phase-down deadlines. |
| Industrial CHP Joint Venture | Benelux chemical clusters anchor combined-cycle deployments exceeding 80 percent total system efficiency. |
Research Methodology
Desk research of EU regulatory filings, EPC project databases, and OEM technical documentation preceded structured interviews with utility planning officers, IPP project developers, turbine aftermarket service heads, and grid operators across Germany, France, Italy, and Poland. Secondary validation drew from CE marking registries, F-Gas compliance tracking, and hydrogen hub funding disclosures. Bottom-up unit deployment tracking and top-down capacity addition estimates were triangulated against manufacturer order book patterns.
Variance decomposition across fuel source, generation capacity tier, cooling architecture, and regional regulatory framework shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated hydrogen blending mandate trajectories, nuclear decommissioning schedules, and industrial CHP deployment economics specific to European chemical corridor demand.
Underlying assumptions cover hydrogen combustion certification timelines, rotor forging capacity availability, and EU funding continuity for hydrogen valleys, with deviation risk concentrated in regulatory acceleration or commodity price spikes. Recalibration cycles align with material shifts in EU Green Deal implementation pace and hydrogen hub offtake agreement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
North America Gas Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
China Gas Generator Market
Generators
Middle-East and Africa Diesel Generator Market
Generators
South America and Africa Diesel Generator Market
Generators
Generator Belt Market
Generators
Asia-Pacific Portable Generator Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Middle East and Africa Gas Generator Market
Generators
Electric Generators Market
Generators
US Generator Sales Market
Generators
Onboard Marine Gensets Market
Generators
Generator Sets Market
Generators
Railway Generators Market
Generators
Asia Pacific Electric Generators Market
Generators
China Generator Sets Market