
 Cold Climate Air Source Heat Pump Market | 2026-2036
Cold Climate Air Source Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Climate Air Source Heat Pump Market Analytics
Premium cold-climate heat pump performance is decoupling from commodity-grade equipment as coefficient-of-performance thresholds diverge at sub-zero temperatures. Daikin Industries leverages inverter-driven compressors to sustain heating capacity at minus twenty-five degrees Celsius, while Mitsubishi Electric anchors its position through proprietary flash-injection cycle technology. Carrier competes on integrated controls and North American distribution density.
Cold climate air source heat pumps are electrically powered vapor-compression systems engineered to deliver usable heat at ambient temperatures below minus fifteen degrees Celsius, typically employing enhanced vapor injection or two-stage compression to maintain thermal output when conventional units fail. Split systems dominate residential retrofits where existing ductwork is absent, while dual-fuel configurations capture the fastest growth in markets with volatile electricity pricing or extreme cold snaps. Inverter technology leads on efficiency metrics and now occupies the primary margin pool as utilities tie rebates to variable-speed performance thresholds.
FERC grid-interconnection rules, EPA refrigerant phase-down mandates under the AIM Act, and Canada's EnerGuide cold-climate performance standard collectively reshape product certification requirements and utility incentive structures. These frameworks push manufacturers toward lower-global-warming-potential refrigerants and demand-response-ready controls as baseline market access conditions. Stakeholders must monitor how building electrification mandates interact with winter peak-load constraints to determine deployment pacing and infrastructure investment priorities.
Market Dynamics
Building electrification mandates in cold-climate jurisdictions are forcing heating infrastructure decisions years ahead of equipment end-of-life, compressing replacement cycles and rewiring utility incentive structures around variable-speed performance thresholds.
Growth Catalysts
- Canada's EnerGuide cold-climate performance standard:Federal labeling requirements now distinguish sub-zero heating capacity, directing consumer choice toward certified equipment and accelerating stock turnover in provinces with fossil fuel phase-out timelines.
- Scandinavian building energy code tightening:Norway, Sweden, and Finland now prohibit fossil fuel heating in new construction and major renovations, eliminating boiler-centric infrastructure planning and normalizing heat pump-first mechanical system design.
- Inverter-driven compressor technology maturation:Variable-speed modulation enables sustained thermal output at minus twenty-five degrees Celsius without auxiliary resistance heating, collapsing the historical performance gap between air-source and geothermal systems in extreme cold.
Market Restraints
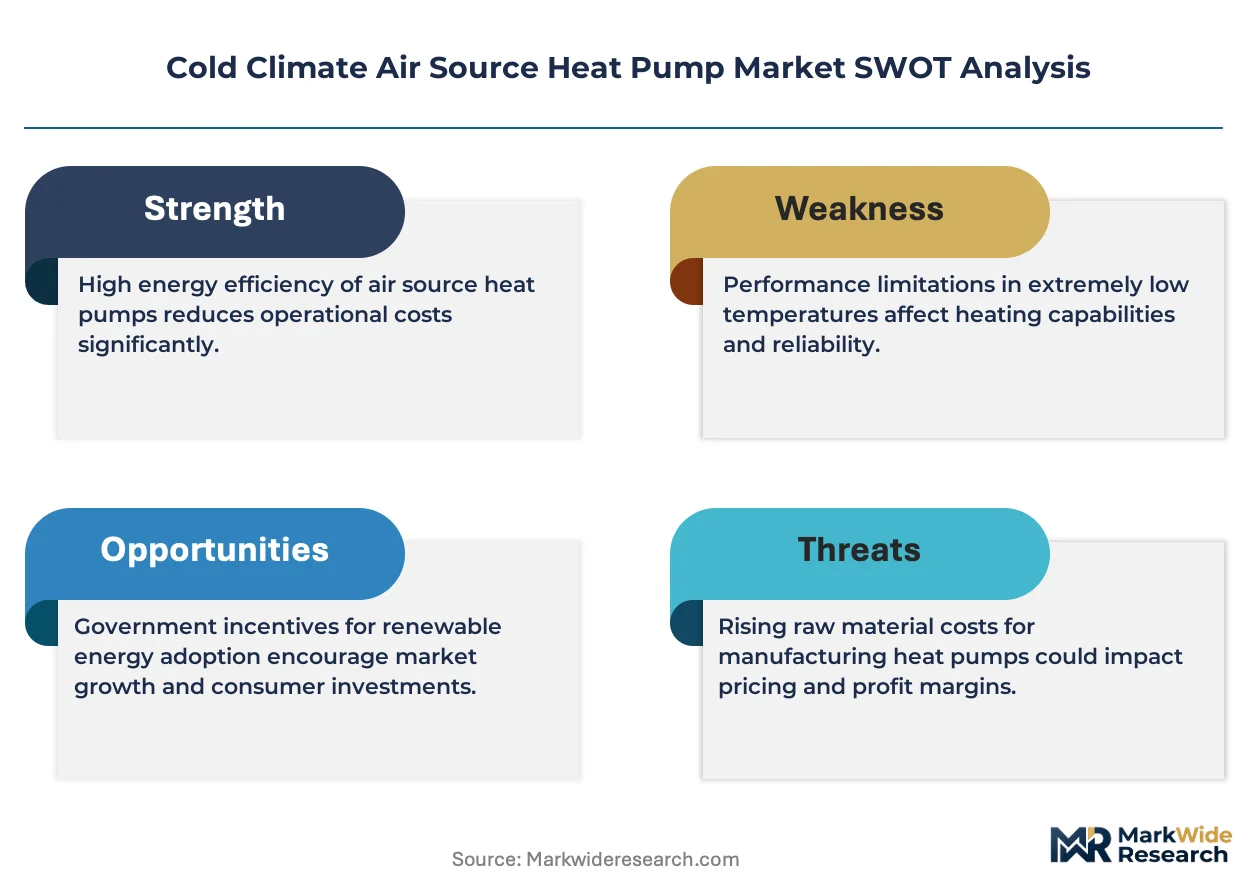
- Copper and rare-earth magnet cost volatility:Compressor manufacturing depends on neodymium supply concentrated in Chinese processing facilities, exposing margin structures to export quota fluctuations and geopolitical supply disruptions.
- Refrigerant supply chain concentration:Lower-global-warming-potential alternatives to R-410A remain captive to limited production capacity in European and Japanese chemical facilities, constraining manufacturer volume scaling.
- Winter peak-load grid infrastructure:Rural and suburban distribution networks in northern climates lack the transformer capacity and circuit redundancy to absorb mass residential electrification without multi-year utility capital programs.
Strategic Opportunities
- Dual-fuel configuration penetration in volatile electricity markets:Hybrid systems pairing heat pumps with existing fossil fuel furnaces capture retrofits where grid reliability concerns or time-of-use pricing spikes deter full electrification, particularly in the northern United States.
- Demand-response-ready control integration:Utility-managed load curtailment capabilities unlock enhanced rebate tiers and create recurring revenue streams through grid services contracts, differentiating equipment beyond efficiency metrics.
- Flash-injection cycle technology licensing:Proprietary two-stage compression architectures enable performance premiums in minus thirty degrees Celsius conditions, opening addressable markets in interior Alaska, northern Canada, and Siberian Russia previously reserved for ground-source systems.
Industry Challenges
- Refrigerant handling certification complexity:EPA Section 608 technician requirements and evolving AIM Act phase-down schedules create compliance friction for HVAC contractor networks already facing workforce shortages.
- Legacy thermostat and control integration:Smart home ecosystems and proprietary utility demand-response protocols fragment control compatibility, forcing manufacturers to maintain multiple firmware branches and certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Climate Air Source Heat Pump Market |
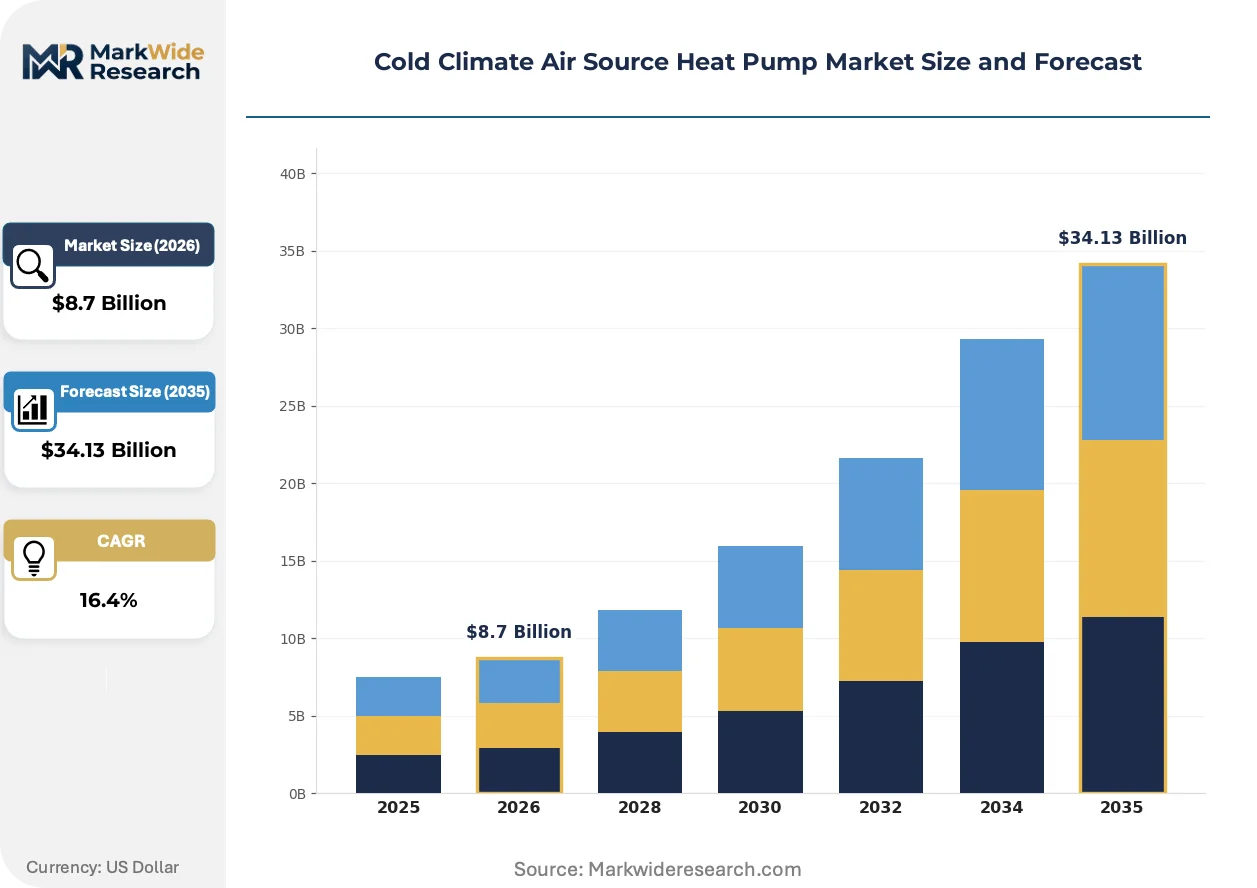
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split Systems, Multi-Zone Systems, Packaged Systems, Dual-Fuel Systems Technology: Inverter Technology, Traditional Compressors, Variable Speed, Heat Recovery Installation: Residential, Commercial, Industrial, New Construction End User: Homeowners, Contractors, Builders, Government |
| Companies Covered | Daikin Industries, Mitsubishi Electric, Carrier, LG Electronics, Panasonic Holdings Corporation, Fujitsu General, Lennox International, Johnson Controls, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Climate Air Source Heat Pump Market Evolving Landscape
Cold-climate heat pump engineering is converging around three vectors: compressor architecture advances that sustain capacity at extreme temperatures, regulatory frameworks that monetize grid flexibility, and procurement models that unbundle equipment from installation financing.
Enhanced vapor injection is electrifying residential heating in sub-Arctic conditions by injecting intermediate-pressure refrigerant into the compression cycle, boosting mass flow without proportional power draw. Alaska Housing Finance Corporation pilot programs demonstrate sustained heating at minus thirty-five degrees Celsius, collapsing the historical geographic boundary where air-source systems required backup. This thermal performance envelope expansion is electrifying market segments previously reserved for fuel oil and propane heating in rural northern communities.
The EPA's refrigerant phase-down mandates under the AIM Act are compressing R-410A availability and accelerating manufacturer migration to R-32 and R-454B alternatives with lower global warming potential. Equipment redesign cycles must synchronize with chemical supply transitions, forcing compressed product development timelines. North American manufacturers face the steepest compliance curve given historical R-410A dependency and limited domestic low-GWP refrigerant production capacity.
Utility-managed installation programs are displacing traditional contractor-led sales in markets with aggressive electrification targets. Massachusetts, Vermont, and British Columbia now route consumer incentives through pre-qualified installer networks that aggregate equipment procurement and standardize commissioning protocols. This channel consolidation compresses price transparency and shifts manufacturer go-to-market investment toward utility relationship management rather than traditional distribution incentives.
Cold Climate Air Source Heat Pump Market Segmentation
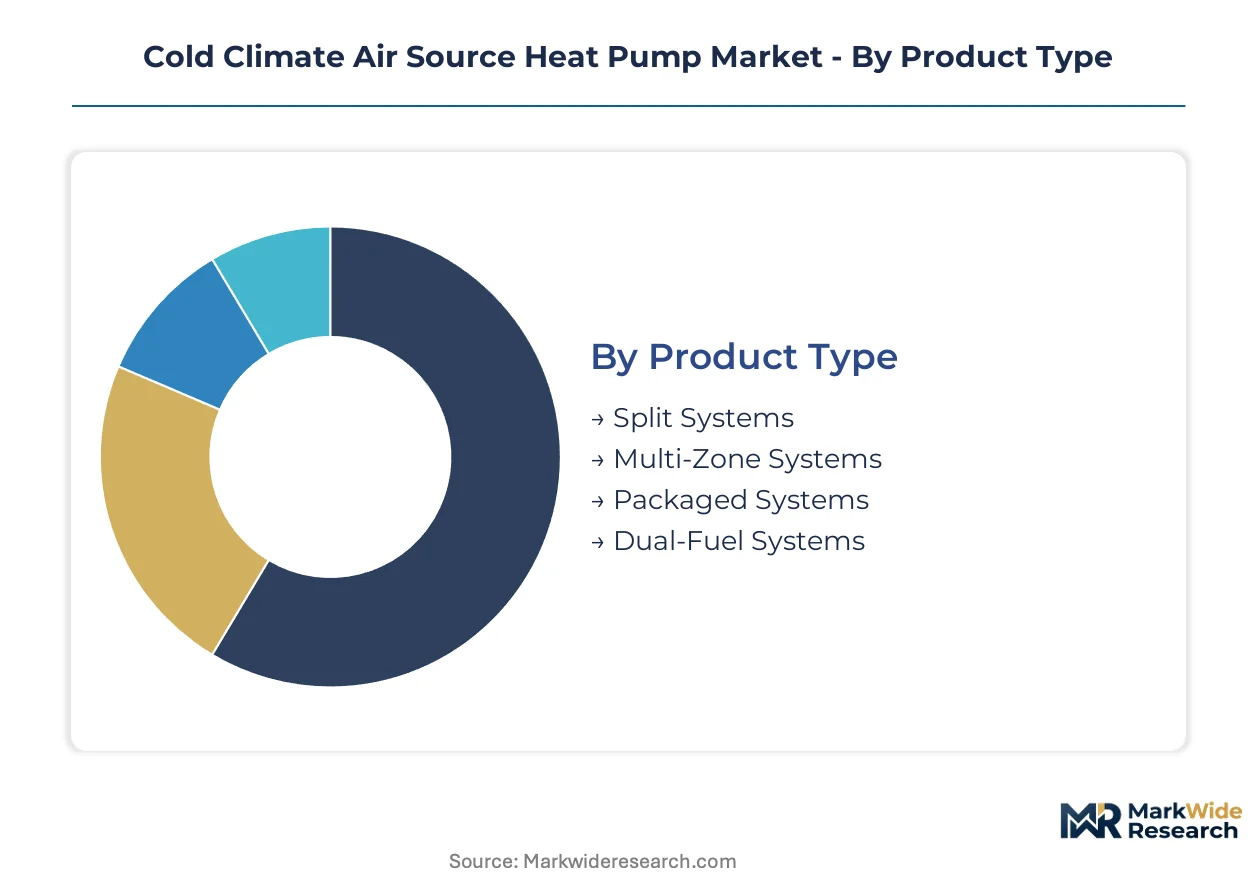
Cold climate heat pump procurement decisions hinge on thermal performance thresholds, installation constraints, and regulatory incentive alignment. Segmentation reveals where technology premiums command pricing power versus where commodity configurations dominate.
Product Type:
Retrofit compatibility and existing infrastructure drive product selection, with ductwork presence and auxiliary heating requirements determining system architecture.
- Split Systems:Ductless configurations pair outdoor condensing units with wall-mounted or ceiling-cassette indoor handlers. Demand concentrates in Scandinavian and Canadian residential retrofits where legacy hydronic or forced-air distribution is absent, with EnerGuide certification requirements directing specification toward variable-capacity models.
- Dual-Fuel Systems:Hybrid architectures integrate heat pumps with existing fossil fuel furnaces, switching to combustion below temperature setpoints. Installations are climbing fastest in Minnesota, Wisconsin, and Alberta where time-of-use electricity pricing and grid reliability concerns deter full electrification.
- Multi-Zone Systems:Single outdoor units serve multiple indoor zones through refrigerant distribution manifolds.
- Packaged Systems:Self-contained rooftop or ground-level units with integrated air handling.
Split systems lead on scale; dual-fuel systems lead on momentum.
Technology:
Utility rebate structures now tie incentive tiers to compressor modulation capabilities, reshaping manufacturer R&D allocation and procurement specifications.
- Inverter Technology:Variable-frequency drives modulate compressor speed to match thermal load, sustaining coefficient-of-performance above 2.0 at minus twenty-five degrees Celsius. Deployment dominates in Norway, Sweden, and Finland where building codes prohibit resistance backup and demand-response integration unlocks enhanced rebate tiers.
- Variable Speed:Multi-stage compressors operate across partial-load conditions without full modulation range.
- Traditional Compressors:Fixed-speed on/off cycling with reduced efficiency at part-load conditions.
- Heat Recovery:Simultaneous heating and cooling operation through refrigerant flow reversal.
Inverter technology leads on scale; heat recovery leads on momentum.
Installation:
Construction cycle timing and regulatory compliance windows create divergent demand patterns across installation contexts.
- Residential:Single-family and multifamily retrofits and replacements.
- Commercial:Offices, retail, and institutional buildings with centralized mechanical systems.
- New Construction:Projects subject to electrification mandates and performance-based building codes.
- Industrial:Process heating and warehouse applications with high ventilation loads.
Residential leads on scale; new construction leads on momentum.
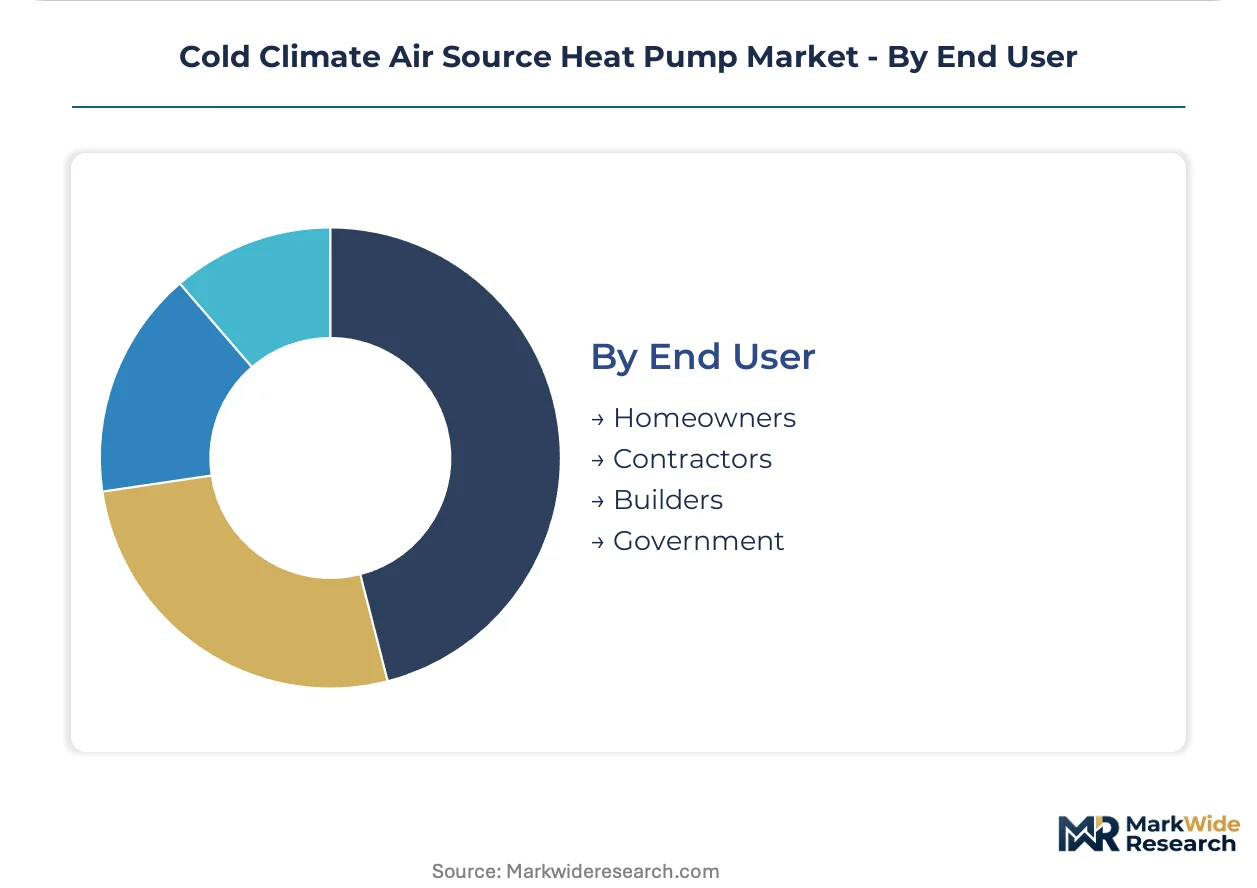
End User:
Decision authority and financing access separate consumer-driven from project-driven procurement channels.
- Homeowners:Individual purchasers responding to equipment failure or incentive program marketing.
- Contractors:HVAC installation firms specifying equipment for client projects.
- Builders:Production and custom home developers integrating systems at construction phase.
- Government:Public housing authorities, military installations, and municipal building portfolios.
Contractors lead on scale; government leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified HVAC technicians concentrate in northern manufacturing belts where electrification mandates compress installation timelines and utility incentive programs reshape contractor economics.
United States
State-level building electrification mandates in Massachusetts, Vermont, and California accelerate residential retrofit demand. The EPA's AIM Act refrigerant phase-down compresses equipment redesign cycles while FERC grid-interconnection rules reshape utility rebate structures. Minnesota and Wisconsin contractors specialize in dual-fuel configurations where volatile electricity pricing deters full electrification.
Canada
Natural Resources Canada's EnerGuide cold-climate performance standard directs consumer choice toward certified variable-capacity equipment. Federal fossil fuel phase-out timelines in British Columbia and Quebec compress replacement cycles ahead of equipment end-of-life. Alberta's Calgary-Edmonton corridor anchors hybrid system adoption where grid reliability concerns persist.
Norway
The national ban on fossil fuel heating in new construction eliminates boiler-centric infrastructure planning. Building energy codes in Oslo, Bergen, and Trondheim normalize heat pump-first mechanical system design. Tromsø sub-Arctic installations demonstrate sustained heating at minus thirty-five degrees Celsius through enhanced vapor injection pilots.
Sweden
Bostadsrätter housing cooperatives drive multi-zone system specifications in Stockholm and Gothenburg retrofits. The Swedish Energy Agency's demand-response rebate tiers tie incentives to variable-speed performance thresholds. Malmö's Øresund cluster integrates heat recovery systems in mixed-use developments with simultaneous heating and cooling loads.
Finland
Remote rural electrification programs displace fuel oil and propane heating in Lapland communities previously reserved for ground-source systems. VTT Technical Research Centre certification protocols validate equipment performance at extreme temperatures. Helsinki metropolitan area contractors concentrate inverter-driven compressor installations where building codes prohibit resistance backup.
Cold Climate Air Source Heat Pump Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across compressor architecture and control system integration. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive refrigerant supply, specialized climate-control engineering houses with proprietary cycle technology, and regional HVAC assemblers with dense service networks. Consolidation pressures concentrate among mid-scale manufacturers lacking inverter-driven compressor sourcing agreements. Technology licensing and utility partnership programs represent the dominant competitive moves as regulatory compliance costs rise.
Within the diversified industrial tier, Daikin Industries and Mitsubishi Electric anchor competitive positioning through proprietary flash-injection and enhanced vapor injection architectures respectively. Carrier occupies a position among North American building systems integrators where distribution density and control platform integration differentiate procurement specifications. These three exemplify how compressor technology leadership and utility relationship management separate premium-tier positioning from commodity-grade competition.
| Leading Market Players |
|---|
| Daikin Industries |
| Mitsubishi Electric |
| Carrier |
| LG Electronics |
| Panasonic Holdings Corporation |
| Fujitsu General |
| Lennox International |
| Johnson Controls |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
Canada's EnerGuide cold-climate performance standard gates qualified supply and premium-tier pricing access by mandating certified variable-capacity equipment for federal incentive eligibility, compressing margins for uncertified manufacturers while rewarding inverter-driven compressor suppliers with pricing power in retrofit-heavy provinces.
Pricing Analysis
The bundled-vs-unbundled service split separates utility-managed installation programs from traditional contractor-led sales, with Massachusetts and British Columbia standardizing procurement through pre-qualified installer networks. Price differentiation hinges on EnerGuide certification tier and demand-response control integration, with certified inverter systems commanding premiums over fixed-speed alternatives. Cost compression in entry-level equipment is intensifying because of copper and rare-earth magnet volatility. Residential homeowners in rural northern climates exhibit highest price sensitivity, while government housing authorities prioritize performance over cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing facilities that anchor rare-earth magnet supply for compressor manufacturing. Component sourcing draws from Japan for inverter drives, China for heat exchanger aluminum, and Germany for precision valves. Tariff exposure on processed rare-earth compounds threatens margin structures. Distribution runs through utility-managed installer networks in electrification-mandate jurisdictions and traditional HVAC wholesaler channels elsewhere.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Canada's federal fossil fuel phase-out timelines and the EPA's AIM Act refrigerant mandates continuously expand certified equipment demand.
For Market Incumbents: Deploy demand-response control integration as the primary lever to defend utility rebate tier positioning against emerging Asian manufacturers with lower-cost inverter platforms. Deepen captive sourcing agreements for neodymium magnets to offset Chinese export quota volatility. Secure exclusive distribution terms with Massachusetts Clean Energy Center and BC Hydro installer networks before channel consolidation hardens. For New Entrants and Emerging Players: Rural Alaskan and Siberian interior communities underserved by ground-source geothermal contractors represent the most penetrable white-space target for flash-injection cycle technology licensing. Alberta's Calgary-Edmonton corridor offers hybrid system retrofit opportunity where grid reliability concerns deter full electrification. Pursue white-label manufacturing partnerships with established compressor architecture licensors to bypass R&D capital barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional HVAC assemblers with dense service networks because utility incentive program consolidation is displacing fragmented contractor markets. Target mid-scale manufacturers lacking inverter-driven compressor sourcing agreements as acquisition candidates. Monitor FERC grid-interconnection rulemaking progress as the inflection signal for demand-response-ready control valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Vapor Injection Licensing | Alaska Housing Finance Corporation pilots validate minus thirty-five degrees Celsius performance, expanding addressable markets. |
| Demand-Response Control Integration | Swedish Energy Agency rebate tiers tie incentives to variable-speed thresholds, differentiating procurement specifications. |
| Refrigerant Supply Agreement | R-32 and R-454B alternatives with lower global warming potential remain captive to limited European and Japanese chemical capacity. |
| Utility Partnership Program | Massachusetts, Vermont, and British Columbia route consumer incentives through pre-qualified installer networks, consolidating channel access. |
| Dual-Fuel Configuration Expansion | Minnesota and Wisconsin contractors specialize in hybrid architectures where volatile electricity pricing deters full electrification. |
Research Methodology
Multiple input streams — regulatory filing analysis, equipment shipment databases, and utility incentive program records — were reconciled against primary interviews with HVAC contractor network managers, utility demand-response program officers, compressor manufacturing procurement leads, and building code enforcement officials. Secondary validation drew from Natural Resources Canada EnerGuide certification databases, EPA AIM Act implementation schedules, FERC grid-interconnection dockets, and Scandinavian building energy code amendments. Bottom-up equipment deployment estimates and top-down market sizing were triangulated to constrain variance.
Historical installation data cross-referenced against panel input from equipment manufacturers and utility program administrators shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, compressor technology tier, installation context, and end-user decision authority. CAGRs were derived from slope analysis of certified equipment deployment curves and incentive budget trajectories. Forecast inputs incorporated building electrification mandate adoption timelines and refrigerant phase-down compliance schedules.
Underlying measurement precision varies by segment; inverter technology and utility-managed installation channels carry tighter precision than traditional compressor and contractor-led sales categories. Forecasts reflect assumptions regarding regulatory enforcement consistency and rare-earth supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Solar Cold Room Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Solar Cooling Market
Cooling Systems
Dry Cooler Market
Cooling Systems
Air to Air Heat Pumps Sales Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Cold Trap Market
Cooling Systems
Radiant Cooling Systems Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Middle East and Africa Cooling Systems Market
Cooling Systems
Solar Air Conditioning Market