
 Residential Gas Generator Market | 2026-2036
Residential Gas Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Gas Generator Market Analysis
Modular product bundling is shifting buyer choice in the residential gas generator space, with manufacturers pairing standby units with smart transfer switches and remote monitoring subscriptions. Generac Power Systems leverages its captive dealer network to control installation quality and recurring service revenue. Kohler Co. anchors its positioning through premium whole-home coverage systems that compete on brand heritage and engineering depth. Cummins Inc. differentiates via industrial-derived engine platforms that extend durability claims into the residential segment.
Residential gas generators are internal-combustion engine systems designed to convert gaseous fuel—primarily natural gas or propane—into electrical output ranging from roughly 1 kW to 20 kW for domestic use, with automatic standby units featuring permanently installed transfer switches that activate within seconds of grid failure. Standby generators dominate value capture due to permanent installation requirements and higher unit economics, while inverter generators represent the fastest-growing configuration as noise-sensitive suburban buyers prioritize harmonic distortion below 5 percent. Natural gas fuel type holds the largest installed base where utility pipeline access exists, though propane retains structural importance in rural locations beyond municipal gas distribution.
EPA certifies emissions compliance under 40 CFR Part 60 for stationary spark-ignition engines, while California Air Resources Board imposes supplemental standards that effectively gate market access for non-compliant products. OSHA noise exposure limits influence enclosure design and siting requirements for contractor-grade portable units. Stakeholders must monitor evolving state-level building codes that increasingly mandate carbon monoxide shutoff sensors and minimum setback distances from residential structures.
Market Dynamics
Grid instability across hurricane-prone coastal zones is compressing purchase cycles and forcing manufacturers to pre-position inventory near storm corridors, fundamentally altering working capital requirements and distribution topology.
Growth Catalysts
- EPA Tier 4 Final standards:Stringent emissions ceilings for stationary spark-ignition engines are accelerating R&D investment in stoichiometric combustion controls and three-way catalyst integration.
- Propane infrastructure expansion:Rural homeowners beyond natural gas pipeline networks are driving demand for dual-fuel conversion kits and dedicated propane standby systems.
- Smart load management:AI-driven priority load shedding is automating generator sizing optimization, reducing unit overspecification and expanding addressable middle-income households.
Market Restraints
- Steel and copper price volatility:Enclosure fabrication and winding materials face input cost swings that compress gross margins on sub-10 kW units.
- CARB certification backlog:California's supplemental testing protocols create 6-12 month approval delays that freeze product launches for the nation's largest state economy.
- Solar-plus-storage substitution:Declining lithium-ion battery costs and net metering incentives are capturing incremental backup power demand in sunbelt jurisdictions.
Strategic Opportunities
- Texas ERCOT instability:Repeated grid failures in the state's deregulated market are creating first-time buyer pools in suburban Dallas-Fort Worth and Houston corridors.
- Virtual power plant aggregation:Utility-controlled dispatch of residential standby units is emerging as a grid services revenue stream in ISO-New England territories.
- Voice-activated monitoring:Integration with Alexa and Google Home ecosystems is opening channel partnerships with smart home installers and security system providers.
Industry Challenges
- Certified electrician scarcity:NEC 702.12 transfer switch installation requirements face bottlenecks from aging electrical trades workforce and limited apprenticeship pipelines.
- Legacy panel integration:Service entrance rated automatic transfer switches require coordination with outdated residential load centers that lack modern busbar configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Gas Generator Market |
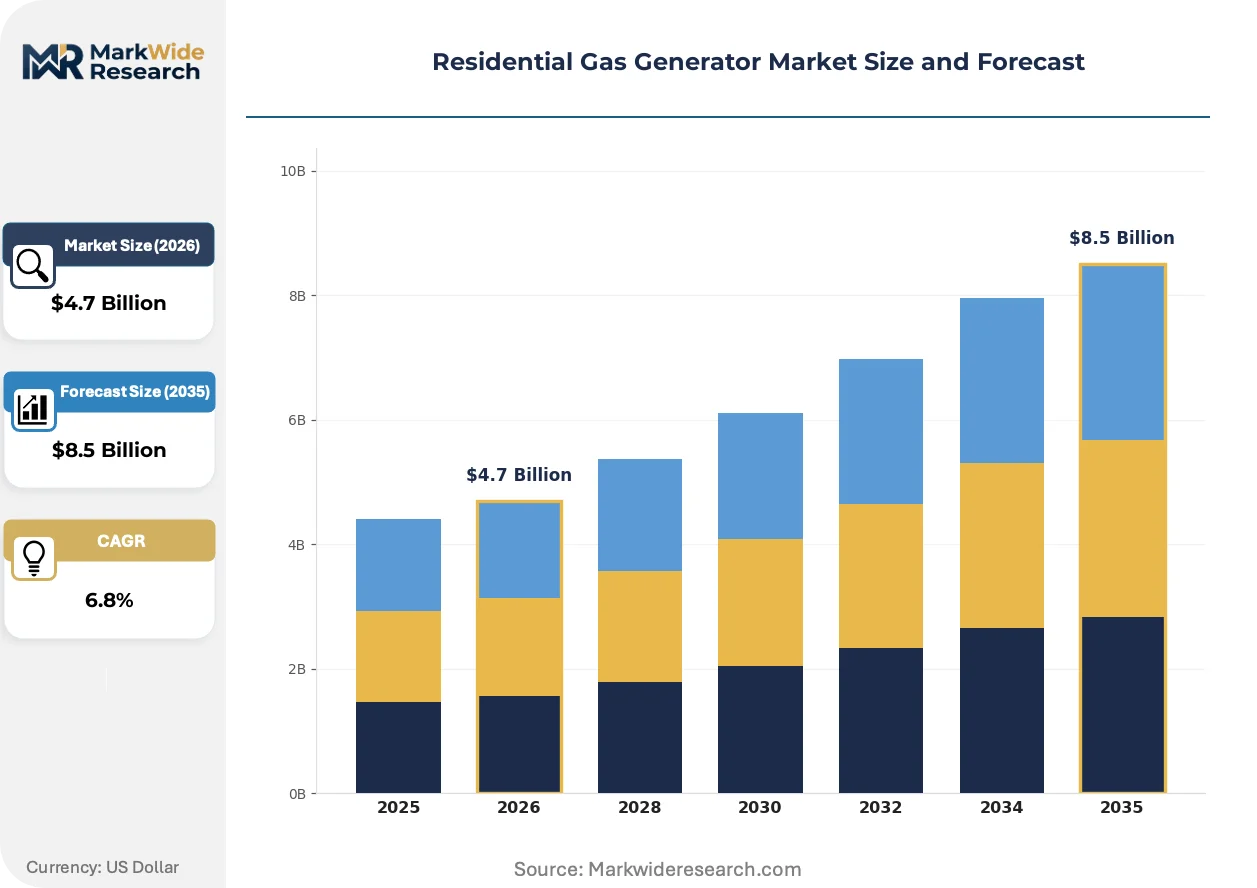
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Inverter Generators, Dual Fuel Generators Fuel Type: Natural Gas, Propane, Biogas, Others Power Rating: 1-5 kW, 6-10 kW, 11-15 kW, 16-20 kW End User: Homeowners, Contractors, Emergency Services, Outdoor Enthusiasts |
| Companies Covered | Generac Power Systems, Kohler Co., Cummins Inc., Caterpillar Inc., Briggs & Stratton Corporation, Honda Motor Co. Ltd., Aggreko PLC, F.G. Wilson, Himoinsa S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Gas Generator Market Emerging Trajectories
Digitalization of power management is collapsing the distinction between standby generation and grid-interactive assets, with firmware updates now extending product lifecycles and reshaping service monetization.
Load-shedding controllers with cellular connectivity are automating generator operation based on real-time utility pricing signals and homeowner-defined priority circuits. Suburban buyers in storm-exposed counties are specifying these modules at accelerating rates, shifting competitive differentiation from kW rating to software sophistication and integration depth.
OSHA noise exposure limits for contractor-grade portable units are forcing enclosure redesigns with composite baffling and air-cooled exhaust routing. Manufacturers serving the rental and construction channel are absorbing NRTL certification costs for 65 dB(A) compliance, while residential standby lines pursue voluntary Quiet Zone branding to capture noise-sensitive suburban infill markets.
Subscription-based monitoring is displacing traditional break-fix service contracts across the dealer channel. Generac's Mobile Link platform and competitor equivalents are capturing recurring revenue from homeowners in Florida and the Carolinas who prioritize proactive maintenance alerts over reactive troubleshooting, compressing independent service provider margins and consolidating aftermarket control under factory-authorized networks.
Residential Gas Generator Market Segmentation
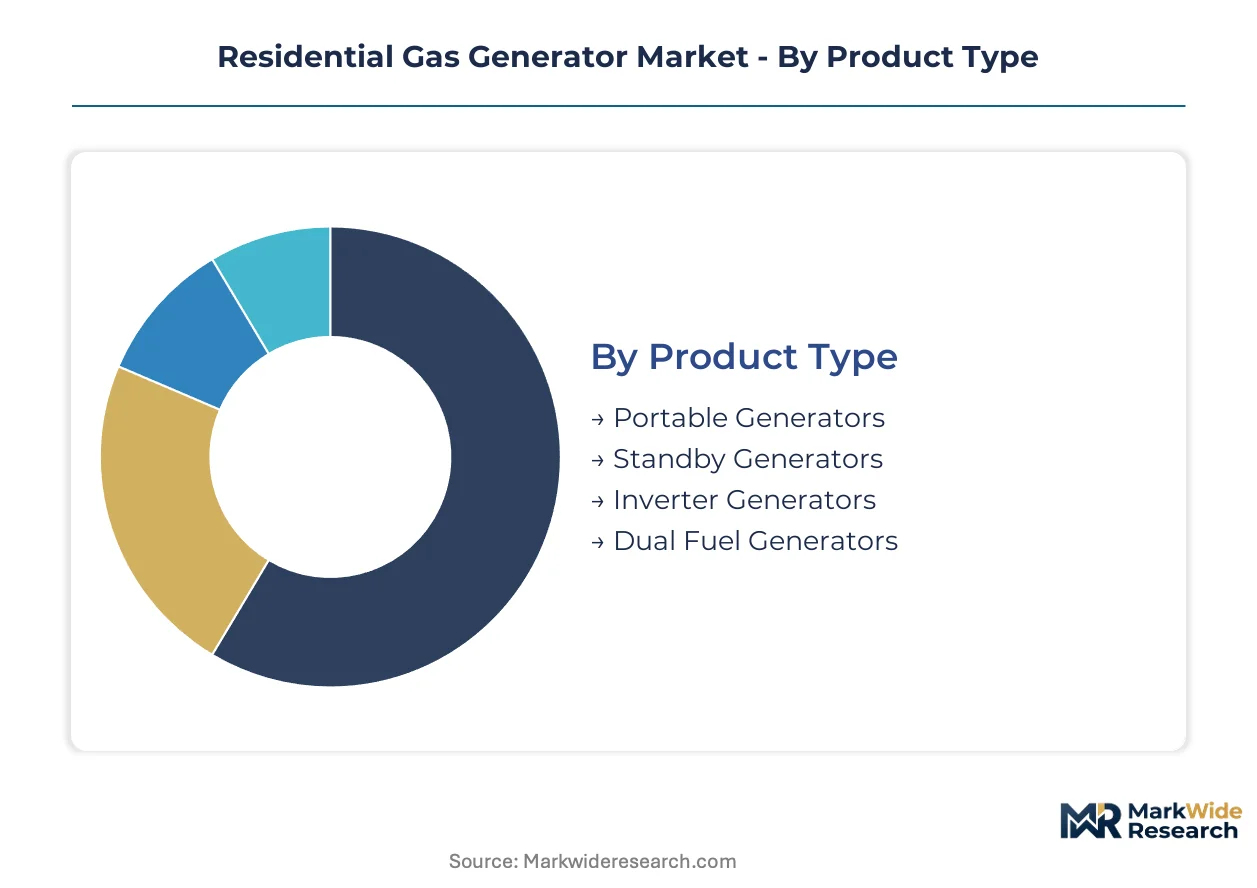
Residential gas generator segmentation reveals distinct upgrade pathways as homeowners migrate from portable units toward permanently installed standby systems. Product type and fuel configuration choices increasingly lock buyers into long-term service relationships and fuel supply dependencies.
Product Type:
Upgrade cycles in this market compress as storm exposure intensifies and smart home integration becomes standard, with replacement decisions now triggered by connectivity gaps rather than mechanical failure alone.
- Portable Generators:Mobile units with manual start mechanisms and temporary connection via extension cords or inlet boxes. Demand concentrates with contractors in Gulf Coast states facing OSHA noise compliance mandates and emergency services requiring rapid deployment capabilities.
- Standby Generators:Permanently installed automatic systems with utility-grade transfer switches. Southeast Florida and coastal North Carolina homeowners drive volume as hurricane frequency and grid aging create persistent backup power requirements.
- Inverter Generators:Compact units with electronic load matching and harmonic distortion below 5 percent.
- Dual Fuel Generators:Convertible systems accepting both natural gas and propane via field-installed kits.
Standby generators sit at the top of the volume ranking, with inverter generators climbing the fastest.
Fuel Type:
Cost tier differentiation separates segments by infrastructure requirements and ongoing fuel economics, with pipeline access determining viable options for suburban versus rural buyers.
- Natural Gas:Pipeline-delivered methane fueling permanently connected standby units. Suburban Houston and Dallas-Fort Worth corridors anchor demand as Texas ERCOT instability drives first-time installations.
- Propane:Stored liquid petroleum serving rural properties beyond municipal gas distribution. Appalachian and Rocky Mountain regions rely on this segment where pipeline extension remains economically unviable.
- Biogas:Methane captured from anaerobic digestion or landfill sources.
- Others:Synthetic methane and hydrogen-blended pilot programs.
Natural gas holds the largest installed base, though propane gains share fastest in exurban expansion zones.
Power Rating:
Application-driven sizing decisions now incorporate AI load-shedding controllers that reduce unit overspecification, expanding addressable middle-income households previously priced out of whole-home coverage.
- 1-5 kW:Essential circuit coverage for refrigeration, lighting, and medical devices. Coastal South Carolina retirees prioritize this tier for targeted backup without whole-home premiums.
- 6-10 kW:Partial home coverage with automatic load management. Suburban Atlanta and Tampa Bay buyers favor this segment as entry-level standby with smart transfer switch compatibility.
- 11-15 kW:Whole-home coverage for residences under 3,000 square feet.
- 16-20 kW:Maximum residential capacity for large estates and luxury construction.
The 6-10 kW range dominates unit shipments, with 11-15 kW systems expanding most quickly as smart load management reduces perceived oversizing risk.
End User:
Customer type segmentation separates transactional portable purchases from relationship-driven standby installations, with lifetime value diverging dramatically across channels.
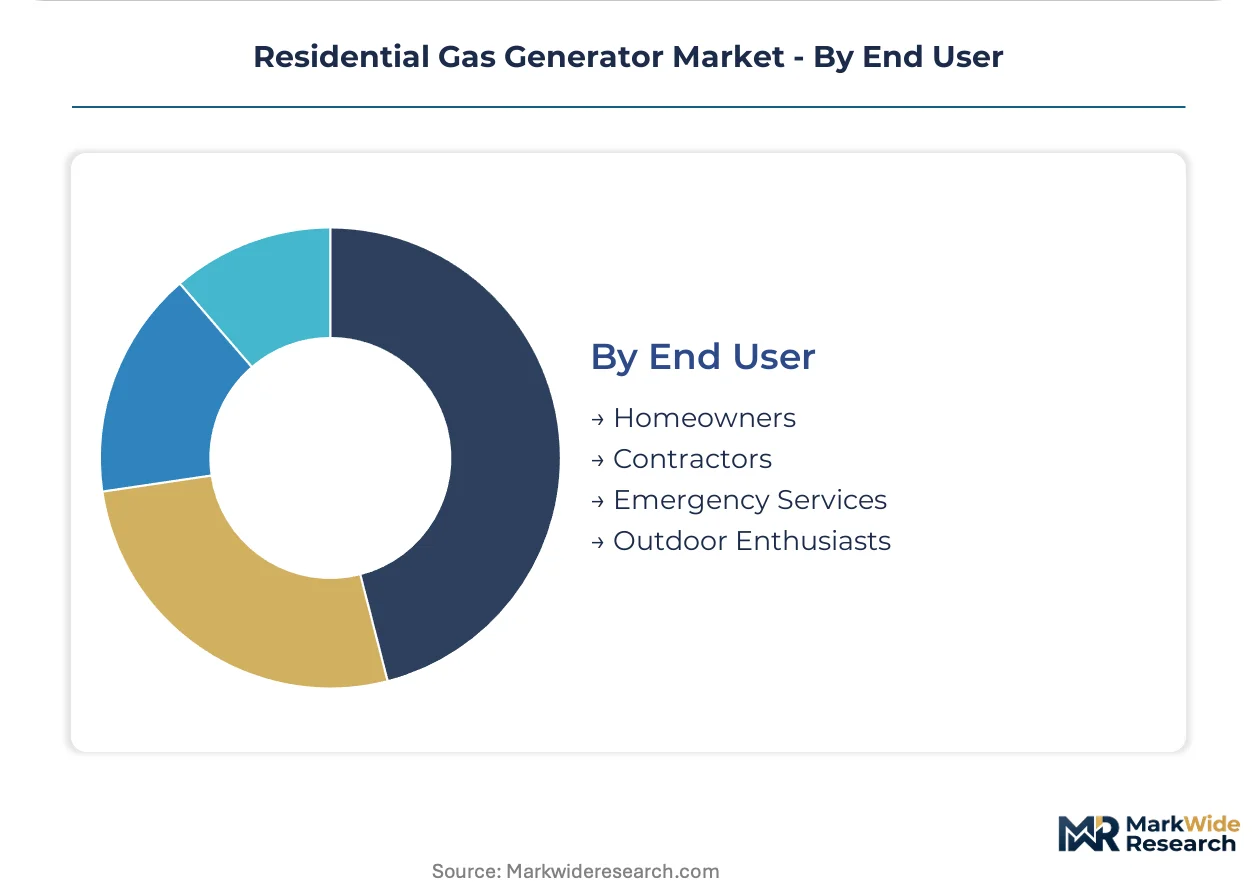
- Homeowners:Permanent installation buyers seeking automatic backup for family residences. Hurricane-prone Florida counties and Texas ERCOT corridors generate concentrated demand for factory-authorized dealer networks.
- Contractors:Construction and rental channel purchasers prioritizing durability and rapid service turnaround. OSHA 65 dB(A) compliance requirements reshape enclosure specifications for this segment.
- Emergency Services:Municipal and hospital auxiliary power procurement.
- Outdoor Enthusiasts:Recreational vehicle and camping applications.
Homeowners generate the highest revenue concentration, with emergency services posting the steepest expansion trajectory as disaster preparedness budgets increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The residential gas generator industry traces its commercial scale to post-war suburban expansion in the United States, where permanent standby systems first penetrated hurricane-exposed coastal markets before diffusing to other storm-prone geographies worldwide.
United States
Hurricane frequency along the Gulf and Atlantic coasts compresses purchase cycles, while Texas ERCOT grid failures generate first-time buyer pools in Dallas-Fort Worth and Houston suburbs. EPA Tier 4 Final emissions standards and CARB supplemental protocols govern product certification, creating 6-12 month approval delays for California market entry. Southeast Florida and coastal North Carolina concentrate installation activity, where factory-authorized dealer networks pre-position inventory ahead of storm seasons.
Germany
Grid stability concerns following Russian gas supply disruptions accelerate residential backup power planning in Bavaria and Baden-Württemberg. The EU Green Deal and national building efficiency regulations (EnEV) shape permissible fuel types and installation standards. Industrial clusters around Stuttgart and Munich host engineering-focused distributors emphasizing CHP-compatible standby systems for high-efficiency homes.
Japan
Seismic resilience requirements and aging grid infrastructure drive standby generator adoption in Tokyo and Osaka metropolitan corridors. METI energy security directives prioritize distributed generation assets for critical facilities, with residential applications following institutional procurement patterns. Chubu region manufacturers supply compact natural gas units optimized for dense urban siting constraints.
Australia
Bushfire-related grid isolation events expand addressable markets beyond traditional storm exposure, particularly in New South Wales and Victoria. State-level building codes mandate carbon monoxide detection and minimum setback distances, while federal energy market reforms incentivize behind-the-meter resilience investments. Queensland coastal communities represent emerging demand concentration as cyclone intensity increases.
Canada
Ice storm frequency in Ontario and Quebec drives seasonal demand spikes for automatic standby systems, with propane retaining structural importance in Prairie provinces beyond pipeline networks. Natural Resources Canada efficiency standards and provincial electrical safety codes govern installation contractor licensing. Greater Toronto and Vancouver metropolitan areas concentrate premium-tier product uptake among luxury construction segments.
Residential Gas Generator Market Vendor Landscape
Premium-margin players sit above commodity-margin players across installation complexity and service bundling dimensions, with factory-authorized networks capturing recurring revenue streams that independent distributors cannot replicate. The vendor base organizes into three strategic archetypes: integrated power equipment conglomerates with industrial-derived engine platforms, dedicated residential standby specialists with captive dealer networks, and diversified engine manufacturers leveraging brand heritage across consumer and commercial segments. Dominant competitive moves include vertical integration into installation services and smart home ecosystem partnerships that lock in replacement cycles through firmware-dependent feature roadmaps.
Among North American-anchored specialists, Generac Power Systems and Kohler Co. exemplify divergent paths within the premium service tier, while Cummins Inc. represents industrial-platform adaptation into residential applications. Generac occupies a position defined by dealer network density and subscription monitoring revenue, Kohler anchors brand heritage positioning in whole-home coverage systems, and Cummins sits within durability-focused engineering differentiation. These three patterns—network control, brand equity leverage, and industrial technology transfer—structure competitive rivalry across price-performance segments.
| Leading Market Players |
|---|
| Generac Power Systems |
| Kohler Co. |
| Cummins Inc. |
| Caterpillar Inc. |
| Briggs & Stratton Corporation |
| Honda Motor Co. Ltd. |
| Aggreko PLC |
| F.G. Wilson |
| Himoinsa S.L. |
| Others |
Supply Flow & Price Mechanics
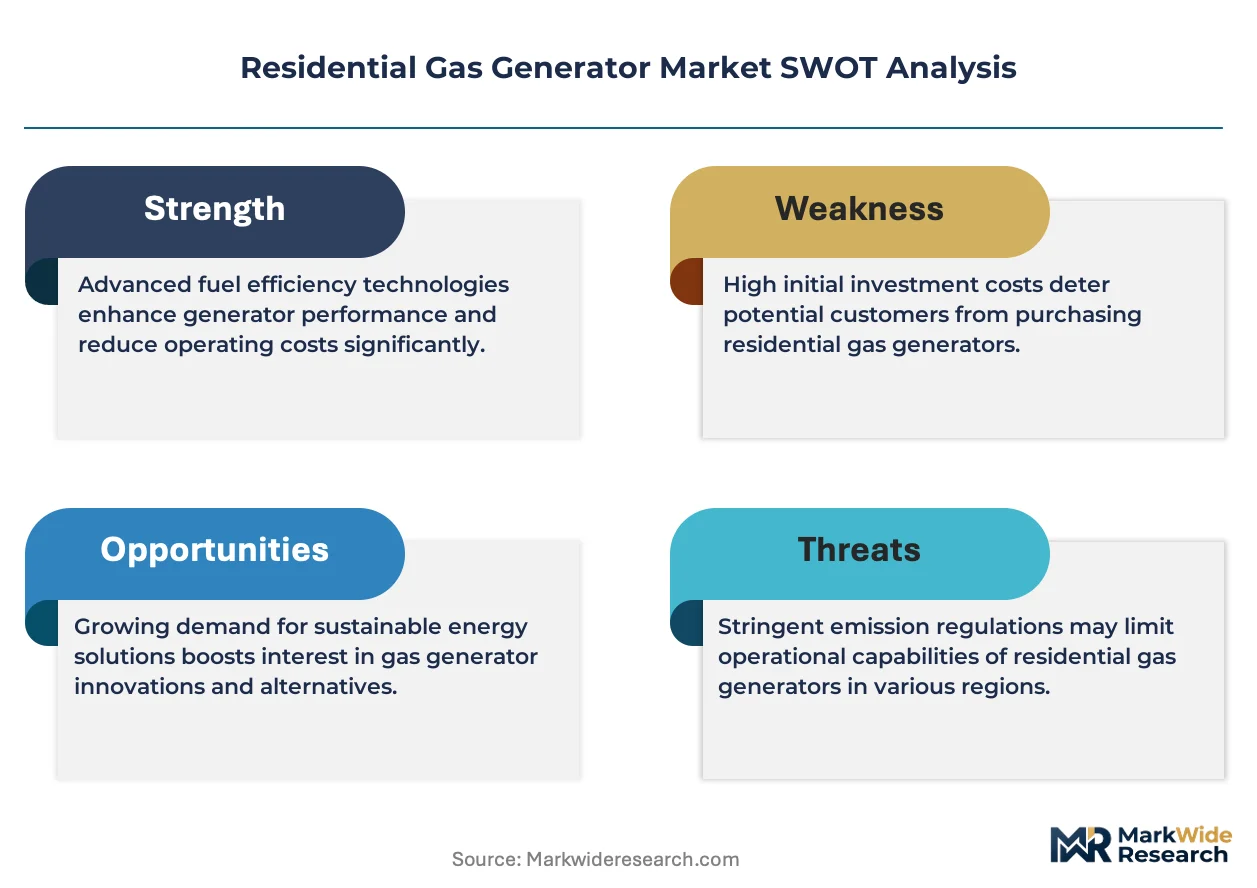
Stoichiometric combustion control integration is compressing cost curves for Tier 4 Final compliant engines while simultaneously concentrating engine block casting capacity among suppliers with EPA certification infrastructure. This dual effect amplifies pricing power for certified manufacturers while squeezing margins on sub-10 kW units facing copper and steel volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates factory-authorized dealer networks from independent installers from big-box retail channels. Price differentiation rests on certification grade—EPA Tier 4 Final and CARB compliance command 15-20% premiums—and after-sales service bundling including remote monitoring subscriptions. Pricing pressure stems from solar-plus-storage substitution in sunbelt jurisdictions capturing incremental backup demand. Contractor-grade portable buyers exhibit highest price sensitivity, while whole-home standby purchasers prioritize brand heritage and installation quality over unit economics.
Supply Chain Analysis
Domestic-content requirements under Buy American provisions for federal procurement are reshaping sourcing toward domestic engine block foundries and enclosure fabricators. Manufacturing concentrates in the United States, Mexico, and China, with engine platforms drawing from industrial power equipment supply bases. Critical inputs include copper windings, steel enclosures, and three-way catalyst substrates. Single-source vulnerability runs through specialized catalyst suppliers serving EPA Tier 4 Final compliance. Distribution runs through factory-authorized dealer networks controlling installation quality and recurring service revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Texas ERCOT corridor demand expansion and California CARB certification bottlenecks that freeze product launches for 6-12 months.
For Market Incumbents: Cement dealer network density in hurricane-prone Florida and coastal North Carolina counties to lock in installation capacity ahead of storm seasons. Deepen backward integration into transfer switch manufacturing to capture margin from NEC 702.12 compliance requirements. Solar-plus-storage substitution in sunbelt jurisdictions represents the primary threat to standby generator replacement cycles. For New Entrants and Emerging Players: Begin with AI-driven load-shedding controller modules as a standalone attach product for existing installed bases, bypassing capital-intensive engine manufacturing. Texas ERCOT instability in suburban Dallas-Fort Worth corridors offers the most penetrable first-time buyer geography. Partner with smart home security system providers for channel access to noise-sensitive suburban infill markets. For Investors and Strategic Acquirers: Valuations sit cheapest among independent service providers facing margin compression from factory-authorized network expansion. The 5-10 year viability window favors captive dealer networks with recurring monitoring revenue over transactional portable distributors. Watch virtual power plant aggregation pilots in ISO-New England territories as the signal indicating grid services revenue materialization.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Expansion | Factory-authorized installation capacity in Florida and Carolinas captures storm-driven demand spikes and recurring service revenue. |
| Smart Load Management Integration | AI-driven priority load shedding reduces unit overspecification and expands addressable middle-income household segments. |
| Dual-Fuel Platform Development | Propane conversion kits unlock rural markets beyond natural gas pipeline infrastructure in Appalachian and Rocky Mountain regions. |
| Virtual Power Plant Enrollment | Utility-controlled dispatch of residential standby units creates grid services revenue streams in deregulated ISO territories. |
| Voice-Activated Monitoring Partnership | Integration with Alexa and Google Home ecosystems opens channel access through smart home installer networks. |
Methodological Framework
Coverage spans the United States, Germany, Japan, Australia, and Canada, with primary inputs from each market's dealer network operators and regulatory compliance officers. The analysis combines structured interviews with factory-authorized service managers, electrical contractor licensing boards, and utility demand-side management directors with secondary validation against EPA certification databases, EIA residential energy consumption surveys, and state-level building code repositories. Bottom-up unit shipment tallies triangulate against top-down spending estimates from utility rebate program disclosures.
Granularity-level modeling disaggregates volume and value across product type, fuel configuration, power rating tier, and end-user segment throughout the forecast period. CAGRs derive from regression analysis against historical storm frequency data, grid reliability indices, and fuel price differentials. Industry-specific forecast inputs include hurricane landfall probability models and ERCOT outage event databases.
Caveats apply where lithium-ion battery cost curves or net metering policy revisions could materially shift the outlook for standby generator substitution risk. Forecasts reflect assumptions about EPA enforcement continuity and electrical trades workforce availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Africa Portable Generator Market
Generators
Europe Portable Generator Market
Generators
Wind Turbine Alternator Market
Generators
Middle-East and Africa Diesel Generator Market
Generators
Gasoline Gensets Market
Generators
United States Portable Generator Market
Generators
Middle East Portable Generator Market
Generators
Construction Generator Sets Market
Generators
China Diesel Generator Market
Generators
US Generator Sales Market
Generators
Reciprocating Power Generating Engine Market
Generators
Hand Crank Power Generator Market
Generators
North West Europe Diesel Generator Market
Generators
Commercial Standby Generator Sets Market
Generators
South America Portable Generator Market
Generators
Electric Generators Market