
 Global Portable Generator Market | 2026-2036
Global Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Portable Generator Market Outlook
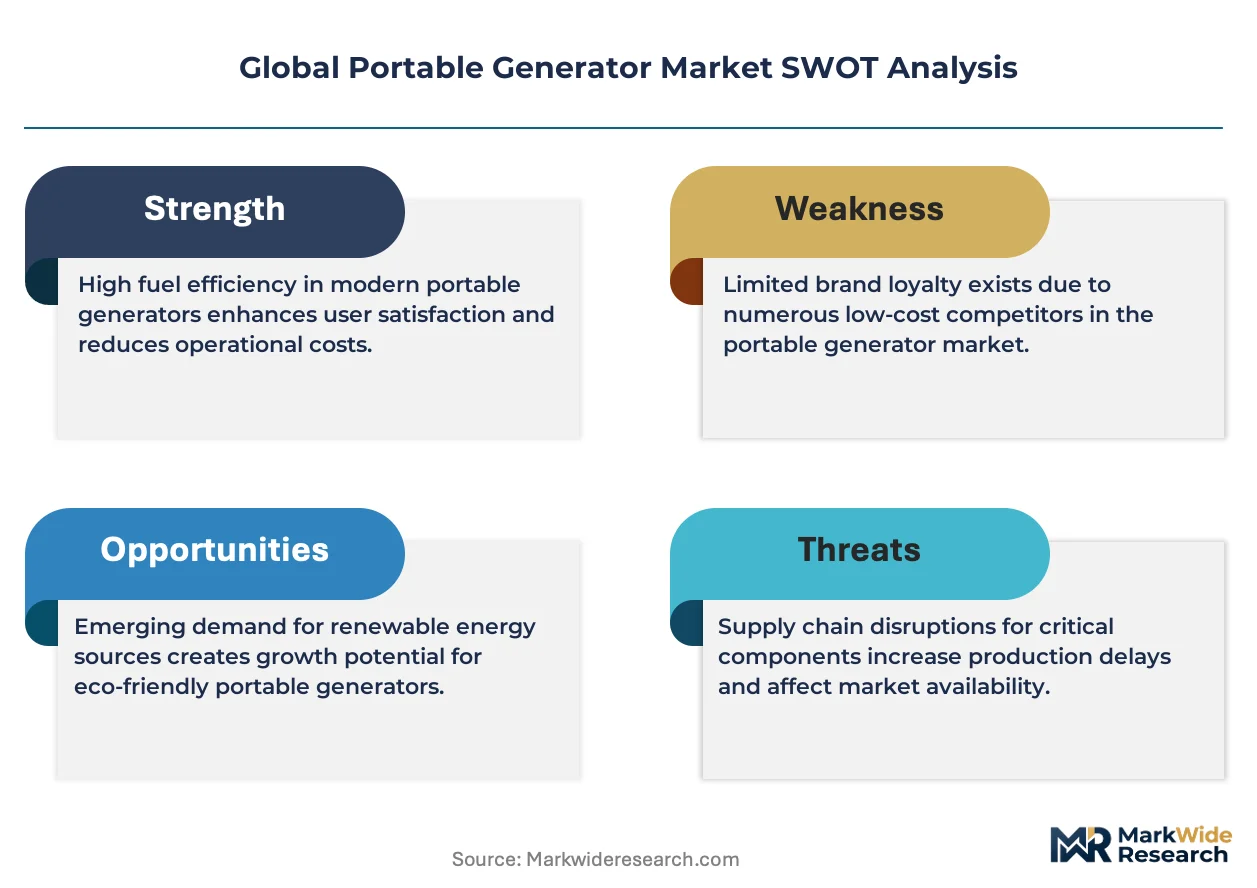
EPA Tier 4 Final certification is collapsing the competitive field for conventional gasoline generators in the United States. Champion Power Equipment leverages its vertical integration across engine manufacturing and assembly to sustain cost leadership in the inverter segment. Generac Power Systems anchors its position through deep channel control in residential backup, while Honda Power Equipment differentiates via proprietary noise-reduction technology and fuel-efficiency leadership.
A portable generator is a self-contained internal combustion or battery-based power unit, typically rated between 1 kW and 15 kW, designed to supply alternating current electricity at standard voltage and frequency for locations without grid access or during utility interruption. Its primary commercial purpose spans emergency resilience, construction site electrification, and outdoor recreational power supply. Inverter generators command premium positioning due to clean sine-wave output essential for sensitive electronics, while dual fuel generators gain traction from operational flexibility across propane and gasoline. Solar generators remain niche but occupy the fastest-expanding margin pool among outdoor enthusiasts and environmentally regulated jurisdictions.
The EPA regulates exhaust emissions and noise thresholds for gasoline-powered units sold in the United States, while the EU Green Deal and Stage V standards constrain diesel generator deployment across European member states. CARB certification in California creates a de facto national benchmark that manufacturers must meet for access to the largest state economy. Stakeholders must monitor battery-energy-storage substitution curves and inverter-cost decline trajectories to calibrate R&D allocation between combustion architectures and electrochemical alternatives.
Market Dynamics
EPA Tier 4 Final and EU Stage V emissions standards are compressing the addressable market for conventional gasoline and diesel architectures while accelerating capital reallocation toward inverter and battery-electric platforms.
Growth Catalysts
- Grid Reliability Deficits:Chronic outages across Texas, California, and Uttar Pradesh are pushing homeowners and small commercial facilities toward on-site backup procurement. Residential emergency adoption now outpaces construction-site demand in volume terms.
- Outdoor Recreation Expenditure:Camping and RV ownership expansion in the United States and Australia is creating pull-through for sub-3 kW inverter units. Noise-sensitive environments favor sine-wave output specifications.
- REACH and RoHS Convergence:European chemical compliance is forcing material substitutions that incidentally improve thermal efficiency in engine housings. Manufacturers serving EU markets gain certification advantages transferable to other jurisdictions.
Market Restraints
- Steel and Aluminum Input Volatility:Engine block and enclosure fabrication costs swing with commodity indexes, compressing margin visibility for assembly-heavy producers.
- Carburetor Supply Concentration:Precision fuel-system components concentrate among Japanese and Chinese suppliers, exposing non-integrated manufacturers to lead-time extension risks.
- Battery-Energy-Storage Substitution:Lithium-ion power stations from Goal Zero, Jackery, and EcoFlow are capturing sub-2 kW recreational demand with zero-emission positioning.
Strategic Opportunities
- India Electrification Gaps:Rural commercial and agricultural segments remain underserved by grid infrastructure, creating white space for 5-10 kW diesel and dual-fuel deployment.
- EU Green Deal Subsidies:Member-state incentives for low-emission backup power are opening procurement channels for propane and solar-hybrid configurations.
- Telematics Integration:Remote monitoring and predictive maintenance capabilities are converging with inverter platforms to create subscription-enabled revenue streams.
Industry Challenges
- EPA Certification Timeline Compression:Tier 4 Final testing protocols require 18-24 month validation cycles, freezing product pipelines for smaller engineering teams.
- Inverter Firmware Integration:Sine-wave generation algorithms and parallel-operation capability demand embedded systems expertise scarce among legacy engine manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Portable Generator Market |
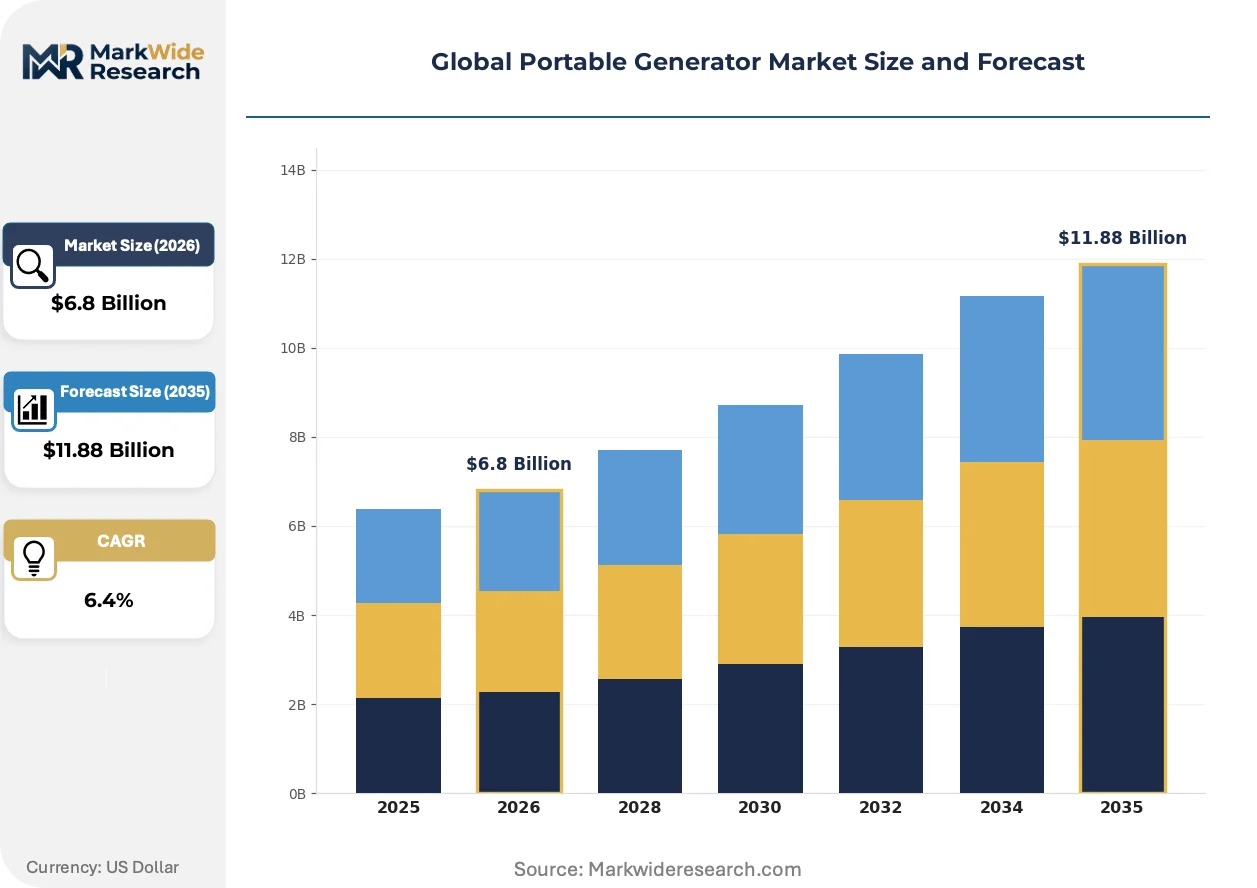
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverter Generators, Conventional Generators, Dual Fuel Generators, Solar Generators Fuel Type: Gasoline, Propane, Diesel, Natural Gas Application: Residential, Commercial, Construction, Emergency Backup End User: Homeowners, Contractors, Event Organizers, Outdoor Enthusiasts |
| Companies Covered | Champion Power Equipment, Westinghouse Outdoor Power Equipment, Generac Power Systems, Kohler Co., DuroMax Power Equipment, Honda Power Equipment, Briggs & Stratton, Hyundai Power Products, Yamaha Generators, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Portable Generator Market Strategic Shifts
Inverter architecture is capturing share from conventional alternator designs as electronics-laden loads proliferate across residential, commercial, and recreational end-uses. Three developments are restructuring competitive positioning.
Silicon-carbide power electronics are decomposing the cost premium between inverter and conventional generator platforms. SiC MOSFETs enable higher switching frequencies with reduced thermal losses, shrinking inverter chassis dimensions and material content. Residential buyers in noise-restricted suburbs and RV parks are adopting these units at replacement-cycle acceleration, compressing the addressable market for open-frame gasoline alternatives.
EU Stage V particulate limits and EPA Tier 4 Final hydrocarbon caps are forcing selective catalytic reduction and diesel particulate filter adoption on mid-size diesel units. Aftertreatment hardware adds weight, cost, and maintenance burden, pushing commercial renters toward gasoline and propane alternatives where duty cycles permit. European construction fleet operators are responding with hybrid solar-diesel configurations to minimize runtime under load.
Direct-to-consumer channel expansion is fragmenting traditional dealer and rental-yard dominance. E-commerce platforms and manufacturer-owned sites now capture substantial recreational and light-commercial volume, disintermediating regional distributors. This shift is most visible in the United States, where Amazon and Home Depot online are reshaping brand discovery and price transparency for sub-5 kW segments.
Global Portable Generator Market Segmentation
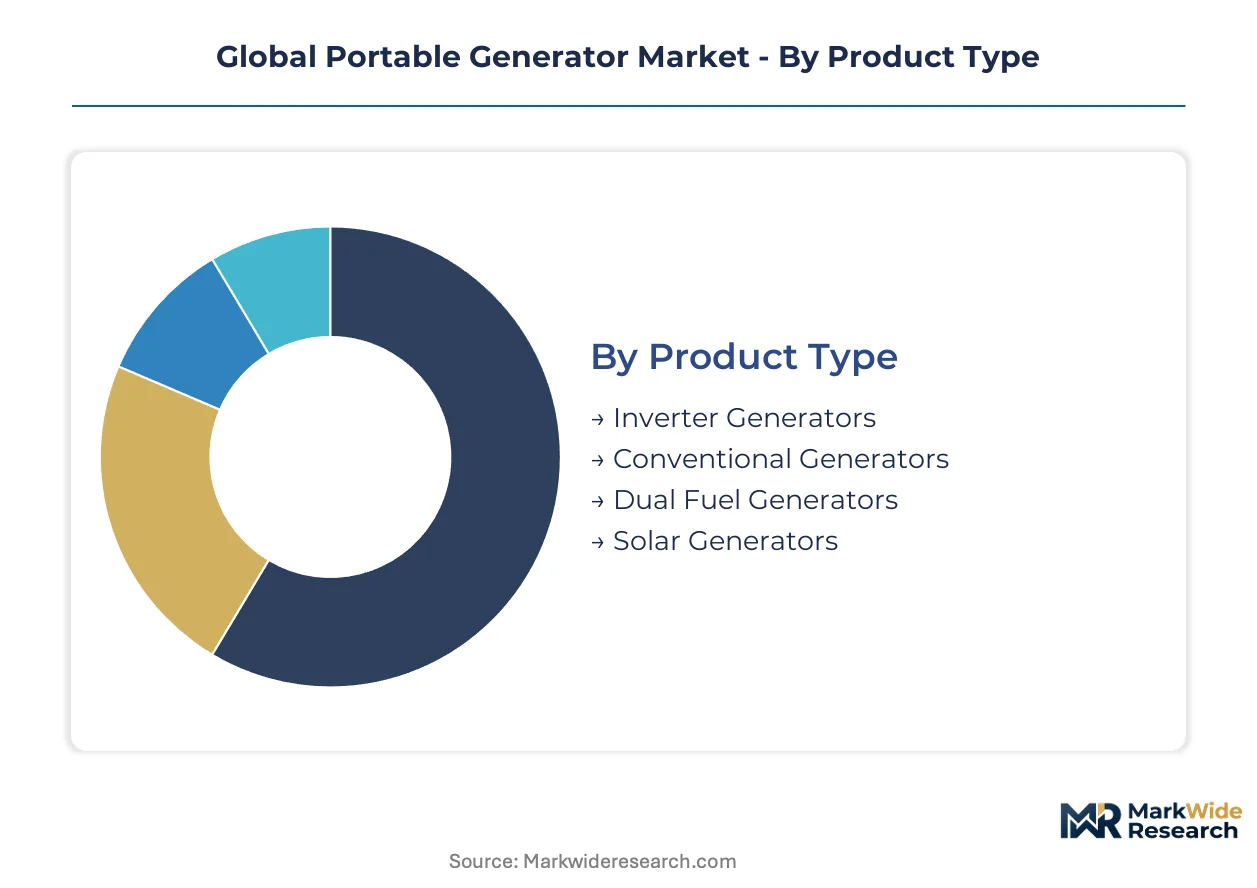
Segmentation in the portable generator market reveals divergent margin structures across power electronics, fuel systems, and end-use applications. Each category carries distinct certification burdens and channel requirements that reshape competitive positioning.
Product Type:
Margin pools concentrate in inverter architectures where silicon-carbide power electronics justify premium positioning against conventional alternatives.
- Inverter Generators:These units deploy high-frequency switching circuits to produce clean sine-wave output suitable for sensitive electronics. Demand clusters among RV owners in the United States and suburban homeowners in noise-restricted municipalities where EPA Tier 4 Final compliance adds cost barriers to conventional units.
- Conventional Generators:Open-frame alternator designs dominate construction site deployment due to lower capital cost and simpler maintenance protocols. Volume concentrates in India and Southeast Asia where diesel and gasoline variants serve agricultural pumping and small commercial electrification needs.
- Dual Fuel Generators:Propane-gasoline flexibility addresses fuel availability volatility during extended outages.
- Solar Generators:Battery-based units from Chinese and US manufacturers capture zero-emission positioning among outdoor enthusiasts.
Conventional generators hold installed capacity. Solar generators are rotating up the share rankings.
Fuel Type:
Volume leadership sits with gasoline systems, though regulatory pressure is compressing their addressable market in jurisdictions with tightening emissions protocols.
- Gasoline:Carbureted and fuel-injected small engines power the majority of sub-5 kW recreational and residential units. CARB certification requirements in California create a de facto national standard that elevates engineering costs for US-bound products.
- Diesel:Compression-ignition architectures dominate 5-15 kW commercial and construction segments where runtime durability outweighs first cost. EU Stage V particulate limits and EPA Tier 4 Final aftertreatment mandates are pushing fleet operators toward hybrid solar-diesel configurations.
- Propane:Cleaner combustion profile aligns with EU Green Deal subsidies for low-emission backup power.
- Natural Gas:Pipeline-connected standby units serve fixed commercial installations with predictable duty cycles.
Gasoline maintains volume dominance. Propane is climbing the fastest as dual-fuel flexibility gains procurement preference.
Application:
Revenue concentration has shifted toward residential emergency backup as grid reliability deficits intensify across multiple continents.
- Residential:Homeowners in Texas, California, and Uttar Pradesh are accelerating procurement of sub-10 kW units following chronic outage events. Channel control through home improvement retailers and direct-to-consumer platforms is fragmenting traditional dealer networks.
- Emergency Backup:Critical facility requirements span healthcare clinics, data centers, and telecommunications infrastructure where sine-wave quality and automatic transfer capability command specification priority.
- Commercial:Small retail and food service operations require mobile power for seasonal demand spikes and equipment redundancy.
- Construction:Rental yard fleets favor conventional gasoline and diesel units for durability under abrasive site conditions.
Construction holds the legacy installed base. Residential emergency is gaining share fastest as outage frequency reshapes buyer urgency.
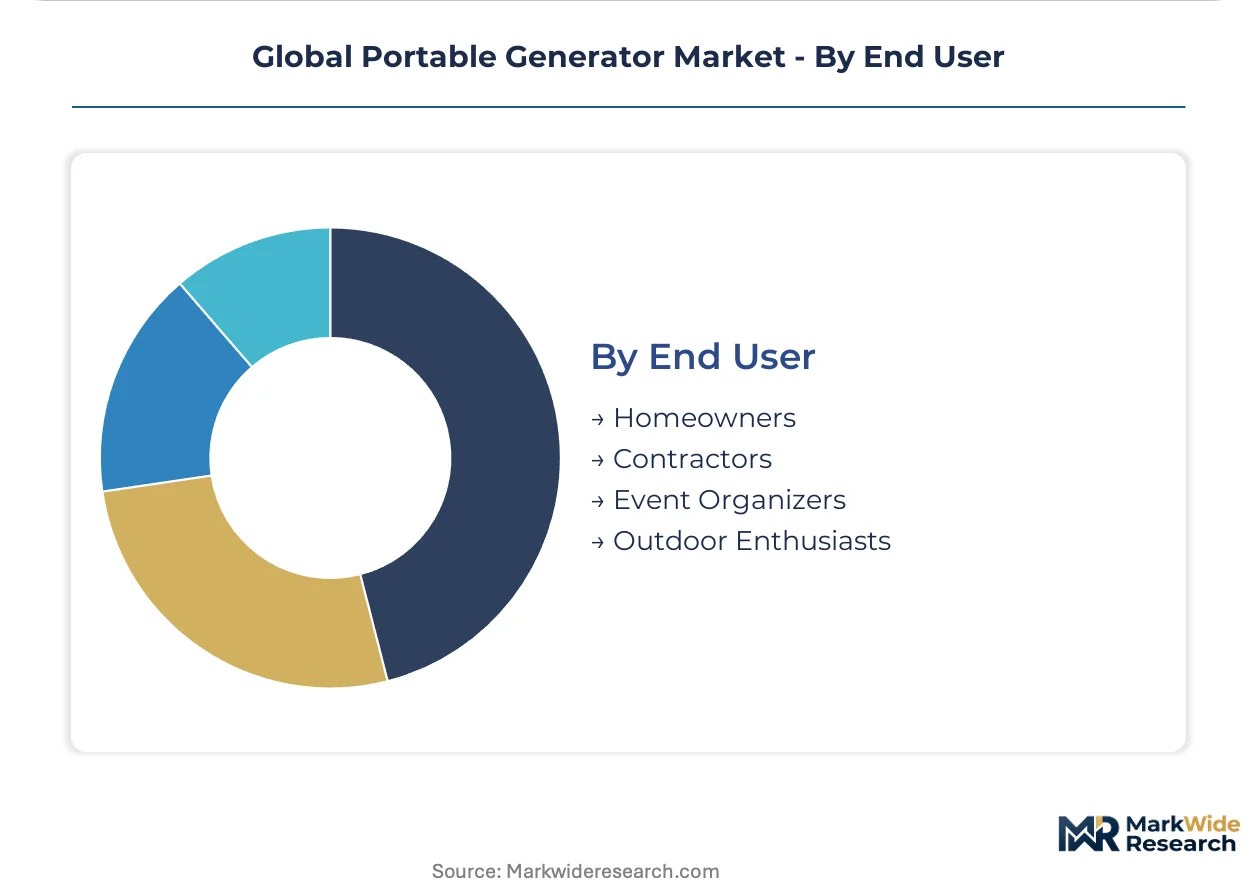
End User:
Procurement authority fragments across price-sensitive homeowners, specification-driven contractors, and experience-weighted outdoor enthusiasts with divergent technical requirements.
- Homeowners:First-time buyers prioritize decibel ratings and EPA certification badges over technical specifications. E-commerce discovery through Amazon and manufacturer direct sites is displacing regional dealer relationships for sub-3 kW recreational purchases.
- Contractors:Professional construction and maintenance crews demand runtime durability, service parts availability, and parallel operation capability for equipment scaling.
- Outdoor Enthusiasts:Camping and overlanding participants weight portability and noise suppression above raw output capacity.
- Event Organizers:Temporary power for festivals and outdoor gatherings requires rapid deployment and emissions compliance in regulated venues.
Contractors retain equipment loyalty through service relationships. Outdoor enthusiasts are expanding most quickly as recreation expenditure outpaces infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA tax credits and state-level resilience incentives are accelerating residential backup procurement across multiple jurisdictions. EPA Tier 4 Final enforcement is compressing the addressable market for conventional gasoline units in the United States. Grid reliability deficits in Texas, California, and Uttar Pradesh are pushing homeowners toward on-site power solutions.
United States
Texas and California homeowners are accelerating sub-10 kW emergency backup purchases following chronic outage events. EPA Tier 4 Final certification creates 18-24 month validation cycles that freeze product pipelines for smaller engineering teams. The Southeast manufacturing corridor spanning Tennessee and South Carolina hosts assembly operations serving both residential and commercial segments.
China
Export-oriented fabricators are scaling inverter generator output for North American and European recreational markets. MIIT efficiency standards and GB emissions protocols constrain domestic gasoline generator deployment in urban zones. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates precision carburetor and power electronics component supply.
Germany
Construction fleet operators are adopting hybrid solar-diesel configurations to minimize runtime under EU Stage V particulate limits. The EU Green Deal subsidies for low-emission backup power are opening procurement channels for propane and battery-electric alternatives. The Baden-Württemberg industrial region anchors diesel generator engineering and aftertreatment system development.
India
Rural commercial and agricultural segments in Uttar Pradesh and Maharashtra remain underserved by grid infrastructure, creating white space for 5-10 kW diesel deployment. BIS certification requirements and state-level electrification gaps sustain demand for conventional gasoline and dual-fuel architectures. The Gujarat manufacturing belt hosts assembly operations serving domestic demand and export markets across South Asia and Africa.
Australia
Camping and RV ownership expansion is creating pull-through for sub-3 kW inverter units in noise-sensitive environments. The country's national emissions regulator enforces standards that favor clean-burning propane and battery-electric alternatives in regulated venues. The Queensland and New South Wales coastal corridors concentrate recreational demand and distribution infrastructure for outdoor power equipment.
Global Portable Generator Market Competitive Environment
Listed leaders compete with private specialists across certification capability and channel control. The vendor base stratifies into three tiers: integrated engine manufacturers with captive supply chains, assembly-focused brands dependent on component sourcing, and emerging battery-electric specialists. Strategic archetypes include vertical integrators defending cost positions, premium differentiators leveraging noise-reduction IP, and direct-to-consumer disruptors fragmenting traditional dealer networks. Capacity expansion and geographic licensing agreements represent the dominant competitive moves.
Within the integrated manufacturing tier, Champion Power Equipment and Generac Power Systems exemplify archetypes of cost leadership and residential channel dominance respectively. Honda Power Equipment occupies a position as the premium-tier anchor for noise-sensitive applications. Among private specialists, DuroMax Power Equipment and Westinghouse Outdoor Power Equipment represent the assembly-heavy model competing on price accessibility and rapid product iteration.
| Leading Market Players |
|---|
| Champion Power Equipment |
| Westinghouse Outdoor Power Equipment |
| Generac Power Systems |
| Kohler Co. |
| DuroMax Power Equipment |
| Honda Power Equipment |
| Briggs & Stratton |
| Hyundai Power Products |
| Yamaha Generators |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion battery pack substitution for conventional engine blocks is redrawing procurement geography while compressing margin structures across assembly tiers. This input shift simultaneously elevates Chinese cell manufacturing centrality and erodes pricing power for carburetor-dependent producers in legacy supply corridors.
Pricing Analysis
Certification level creates the primary spread between inverter premium tiers and conventional economy positioning. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Tier 4 Final compliance burden and sine-wave output quality. Cost compression in the economy tier intensifies because commodity steel and aluminum volatility feeds directly into open-frame generator fabrication. Contractors exhibit highest price sensitivity due to rental-yard procurement protocols, while outdoor enthusiasts accept substantial premiums for decibel-rated inverter units.
Supply Chain Analysis
China and Japan anchor precision carburetor and silicon-carbide power electronics manufacturing for inverter architectures. Engine block casting draws from Indian and Vietnamese metalworking clusters, while aftertreatment system assembly rests on German and US Tier 1 suppliers. Single-source vulnerability concentrates in Japanese fuel-system component providers serving non-integrated brands. Distribution runs through direct-to-consumer platforms and home improvement retail chains, displacing regional dealer networks for sub-5 kW recreational segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable generator procurement is shifting toward platform-economics logic as telematics-enabled inverter units create subscription revenue streams and ecosystem lock-in. Interoperability between battery-electric power stations and solar panel arrays is restructuring buyer expectations around modular expandability.
For Market Incumbents: Shield core inverter margins by deepening backward integration into engine manufacturing and silicon-carbide power electronics sourcing. Battery-energy-storage substitution from Goal Zero and EcoFlow threatens sub-2 kW recreational positioning. Channel control through home improvement retail partnerships and predictive maintenance subscription tiers represents the priority defensive lever.
For New Entrants and Emerging Players: EPA Tier 4 Final certification fast-track through third-party testing laboratory partnerships opens white-space entry. Rural commercial segments in Uttar Pradesh and Maharashtra present the most penetrable geography given grid reliability deficits and limited incumbent service presence. Direct-to-consumer launch via Amazon and manufacturer-owned sites bypasses dealer network capital requirements.
For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors vertically integrated specialists with captive engine supply. Five-to-ten year viability hinges on R&D allocation between combustion architectures and electrochemical alternatives. Telematics integration penetration rates signal the inflection point where hardware margins commoditize and software-enabled recurring revenue separates winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engine Manufacturing | Captive supply of EPA Tier 4 Final certified engines insulates Champion Power Equipment from carburetor supplier concentration risk. |
| Telematics Platform Development | Remote monitoring subscriptions transform Generac Power Systems from transactional hardware sales toward recurring revenue models. |
| Direct-to-Consumer Channel Expansion | Amazon and manufacturer-owned sites fragment traditional dealer networks for sub-3 kW recreational inverter procurement. |
| Hybrid Solar-Diesel Configuration Launch | EU Stage V compliance through runtime minimization opens German construction fleet procurement to dual-fuel alternatives. |
| Silicon-Carbide Power Electronics Adoption | SiC MOSFET integration shrinks inverter chassis dimensions while improving thermal efficiency for Honda Power Equipment premium positioning. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Plant managers at assembly operations, procurement leads at rental yard fleets, aftermarket service heads, and regulatory compliance officers provided operational perspective. EPA certification databases, CARB executive orders, EU Stage V type-approval records, and customs trade data furnished secondary validation. Bottom-up unit shipment estimates and top-down market value reconstruction triangulate across data sources.
Sensitivity analysis around steel price trajectories and battery cost decline curves stress-tests projection robustness across the analysis window. Segmentation dimensions span product architecture, fuel system, application vertical, and end-user procurement authority. CAGRs derive from logistic adoption curve fitting and replacement cycle modeling. Forecast inputs incorporate grid reliability indices by state and province, plus outdoor recreation expenditure trends from national statistical agencies.
Underlying assumptions cover EPA enforcement continuity and lithium-ion cell cost trajectories, with deviation risk concentrated in battery substitution velocity and emissions standard delay scenarios. Recalibration cycles align with material shifts in regulatory enforcement timelines and commodity input volatility regimes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Reciprocating Power Generating Engine Market
Generators
Global Diesel Gensets Market
Generators
Commercial Generator Market
Generators
Digital Inverter Generator Market
Generators
Power Generator Rental Market
Generators
Diesel Generator Market
Generators
Onboard Marine Gensets Market
Generators
Nuclear Turbine Generators Market
Generators
Turbo Generator Market
Generators
Hand Crank Power Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
Power Generator for Military Market
Generators
China Generator Sets Market
Generators
Africa Diesel Generator Market
Generators
Industrial Generator Sets Market
Generators
Southeast Asia Portable Generator Market