
 Nano Positioning System Market | 2026-2036
Nano Positioning System Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Positioning System Market Intelligence
Multi-source procurement for precision motion subsystems is rebalancing toward vertically integrated domestic suppliers in key manufacturing economies. Physik Instrumente anchors European demand through captive piezoelectric actuator production. Newport Corporation leverages its Newport and Spectra-Physics heritage to control photonics-aligned positioning channels. SmarAct GmbH specializes in compact stick-slip drives that occupy space-constrained quantum research setups.
A nano positioning system integrates actuators, sensors, and controllers to achieve repeatable motion resolution below 100 nanometers, typically employing piezoelectric or capacitive feedback loops for closed-loop stability in vacuum and ambient environments. Stage systems command the highest unit values where multi-axis vacuum compatibility determines qualification for semiconductor metrology. Piezoelectric technology leads installed base because solid-state actuation eliminates mechanical play and enables sub-nanometer step resolution. Capacitive sensing segments grow fastest as fabs demand direct position feedback immune to thermal drift in EUV tool environments.
FDA 21 CFR Part 820 quality system requirements shape biomedical nano positioning adoption where optical coherence tomography systems require validated motion repeatability. ISO 17025 calibration standards and NIST traceability protocols determine supplier qualification for defense and aerospace contracting. Semiconductor end users in Germany and Japan additionally navigate REACH substance restrictions and METI energy efficiency directives affecting piezo driver electronics. Stakeholders must monitor how export control expansions around dual-use precision motion components redraw eligible customer geographies.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are consolidating supplier qualification around closed-loop piezoelectric architectures that satisfy EUV lithography alignment tolerances, compressing vendor selection cycles and favoring vertically integrated motion subsystem providers.
Growth Catalysts
- EUV Lithography Alignment Demands:Sub-7nm node production requires picometer-scale stage stability, pulling investment into capacitive feedback loops and thermal compensation algorithms for photolithography tools.
- ISO 17025 Calibration Mandates:Defense and aerospace contracting now requires NIST-traceable position verification, disqualifying open-loop systems and expanding addressable market for certified closed-loop vendors.
- Quantum Research Infrastructure Buildout:National laboratories in Germany, Japan, and the United States are procuring compact multi-axis stages for trapped-ion and superconducting qubit manipulation.
Market Restraints
- PZT Ceramic Supply Concentration:High-purity lead zirconate titanate feedstock is concentrated among Japanese and Chinese suppliers, exposing stage manufacturers to export licensing delays and price volatility.
- Vacuum-Compatible Electronics Cost:Outgassing-rated drivers and position sensors carry 3-5x cost premiums over ambient equivalents, constraining adoption in cost-sensitive industrial automation.
- REACH Substance Restrictions:European semiconductor tool builders face compliance complexity for piezo driver electronics containing restricted substances, lengthening qualification timelines.
Strategic Opportunities
- Biomedical Imaging Integration:Optical coherence tomography and super-resolution microscopy in the United States and Germany are creating validated motion repeatability requirements that premium positioning suppliers can capture.
- Modular Stick-Slip Architectures:Space-constrained quantum computing testbeds favor compact linear drives that combine nanometer resolution with centimeter travel range, displacing traditional stacked stage configurations.
- India PLI Scheme Alignment:Domestic semiconductor packaging investments under India's production-linked incentive framework are generating first-time demand for precision alignment stages among new fab entrants.
Industry Challenges
- Mechatronics Talent Scarcity:The intersection of piezoelectric physics, control systems engineering, and vacuum engineering is producing acute hiring constraints for stage manufacturers expanding production.
- Multi-Axis Integration Complexity:Semiconductor metrology tools require six-degree-of-freedom stages with crosstalk compensation below 1 nanometer, demanding extended customer co-development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Positioning System Market |
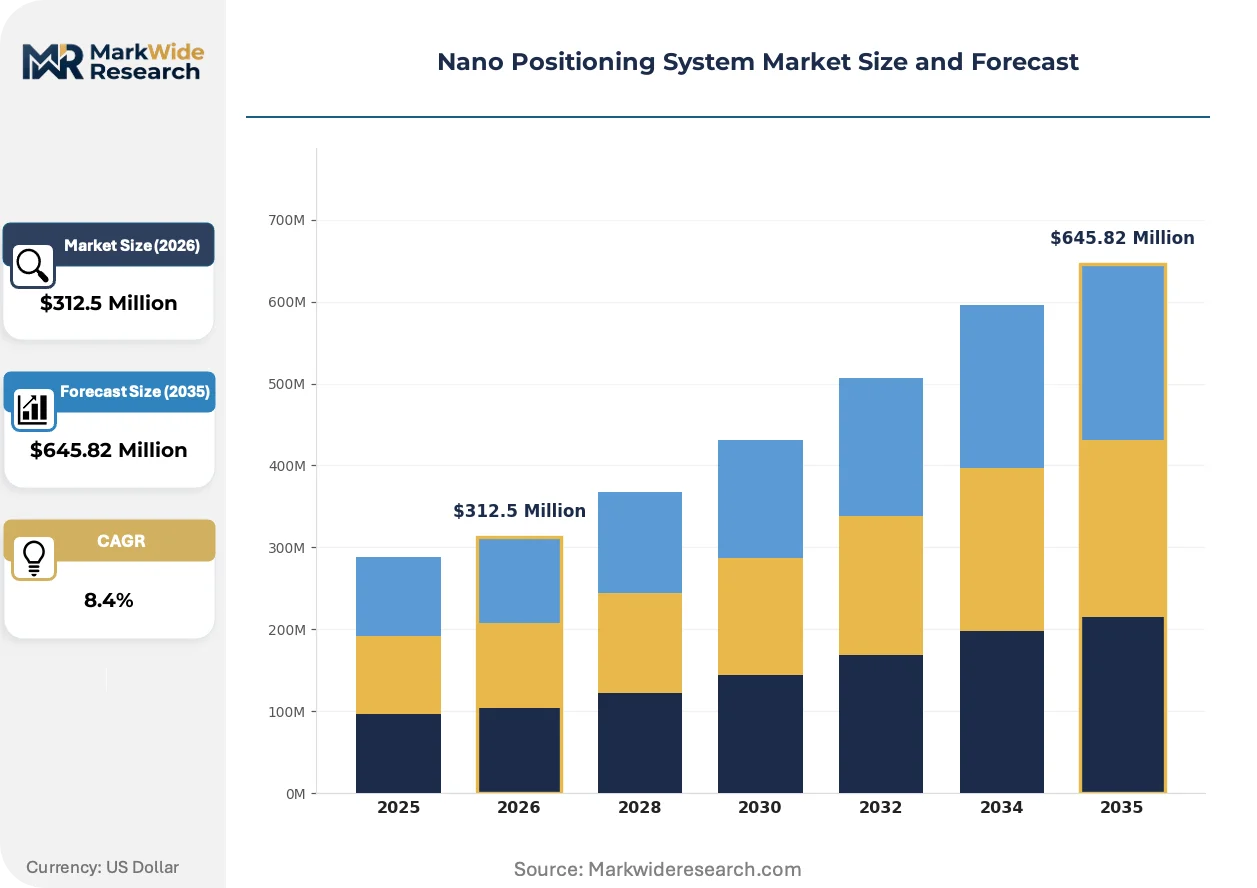
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Actuators, Controllers, Sensors, Stage Systems Technology: Optical, Magnetic, Piezoelectric, Capacitive End User: Semiconductors, Biotechnology, Aerospace, Research Institutions Application: Optical Coherence Tomography, Metrology, Micro-manipulation, Scanning Probe Microscopy |
| Companies Covered | Newport Corporation, Attocube Systems AG, Physik Instrumente (PI) GmbH & Co. KG, SmarAct GmbH, Piezosystem Jena GmbH, Aerotech Inc., Mad City Labs Inc., Nanotion Ltd., Thorlabs Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Positioning System Market Strategic Shifts & Innovations
Precision motion architectures are fragmenting into application-optimized configurations as end-users reject universal platforms in favor of purpose-built subsystems. Three developments are compressing product development cycles and redrawing competitive boundaries.
Capacitive sensing technology is decentralizing position feedback authority away from centralized controller architectures. Fabs in Taiwan and South Korea are embedding direct position sensors at each actuator node, eliminating thermal drift errors that accumulate in serial kinematic chains. This distributed sensing topology is compressing alignment cycle times in EUV tools by enabling parallel rather than sequential axis settling.
Japan's METI energy efficiency directives are forcing piezo driver electronics redesigns that reduce standby power consumption in semiconductor manufacturing environments. Equipment suppliers must now qualify new amplifier architectures that maintain sub-nanometer stability while cutting thermal dissipation. German and Japanese tool builders are responding by co-developing driver-stage integrated thermal management with positioning vendors.
Buyers in advanced node semiconductor manufacturing are consolidating stage procurement under multi-year lifecycle service agreements that unbundle hardware from calibration and refurbishment. This contractual shift is displacing transactional component sales in favor of guaranteed uptime models. The transition is most visible in South Korea, where memory fabs are negotiating total cost-of-ownership contracts spanning 10-year tool lifecycles.
Nano Positioning System Market Segmentation
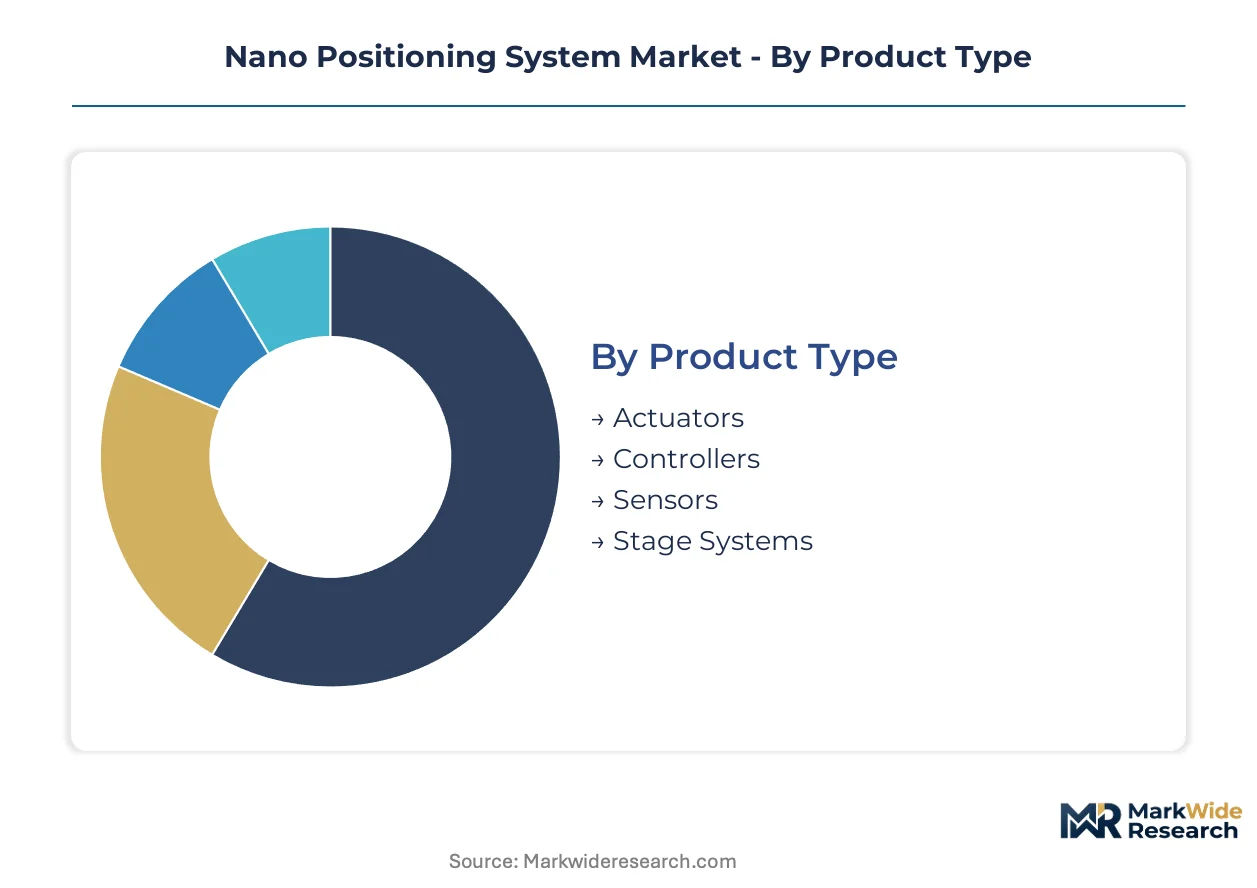
Precision motion requirements diverge sharply across nano positioning applications, with semiconductor fabs demanding vacuum-compatible multi-axis stages while biomedical researchers prioritize compact single-axis modules. Supplier portfolios must align technical specifications to end-use constraints rather than forcing universal platform adoption.
Product Type:
Capital allocation decisions hinge on whether buyers seek discrete components for integration or complete subsystems for faster deployment.
- Stage Systems:Multi-axis platforms integrate actuators, sensors, and structural elements into vacuum-rated assemblies for EUV lithography alignment. Taiwan and South Korea fabs consolidate procurement around these high-unit-value configurations where thermal stability and crosstalk compensation determine tool qualification.
- Actuators:Solid-state piezoelectric stacks deliver sub-nanometer step resolution without mechanical play, forming the motion foundation for semiconductor metrology and quantum research setups. Demand concentrates among vertically integrated stage manufacturers and specialized OEMs building custom instrumentation.
- Sensors:Capacitive and optical feedback devices provide direct position verification for closed-loop architectures.
- Controllers:Digital signal processors and amplifier electronics execute closed-loop algorithms with microsecond latency.
Volume sits with Actuators; growth tilts toward Stage Systems.
Technology:
Performance specifications and environmental constraints dictate sensing and actuation modality selection across end-use verticals.
- Capacitive:Non-contact position sensing delivers immunity to thermal drift and electromagnetic interference, making these sensors essential for EUV tool environments where picometer stability is mandatory. Fabs in Taiwan and South Korea are embedding capacitive feedback at each actuator node to enable parallel axis settling.
- Piezoelectric:Lead zirconate titanate ceramics enable solid-state actuation with nanometer resolution and microsecond response times. Japanese and Chinese suppliers control high-purity PZT feedstock, exposing stage manufacturers to supply concentration risk.
- Optical:Laser interferometry and encoder systems provide traceable position verification for calibration laboratories.
- Magnetic:Linear motor and voice coil architectures serve applications requiring centimeter travel ranges with moderate precision.
Revenue concentrates in Piezoelectric; Capacitive is climbing the fastest.
End User:
Regulatory requirements and procurement cycles vary dramatically across buyer categories, from defense contracting protocols to research grant funding mechanisms.
- Semiconductors:Memory and logic fabs in Taiwan, South Korea, and Germany drive demand for vacuum-compatible multi-axis stages with NIST-traceable calibration. EUV lithography alignment tolerances below 7nm nodes require picometer-scale stability and thermal compensation algorithms.
- Research Institutions:National laboratories in Germany, Japan, and the United States procure compact stages for trapped-ion quantum computing and superconducting qubit manipulation. Stick-slip drive architectures from specialized vendors occupy space-constrained cryogenic setups.
- Biotechnology:Optical coherence tomography system builders require FDA-validated motion repeatability under 21 CFR Part 820 quality systems.
- Aerospace:Defense contractors specify ISO 17025 calibrated positioning for satellite optical assembly and precision pointing mechanisms.
Spending dominance belongs to Semiconductors; Research Institutions show the steepest expansion trajectory.
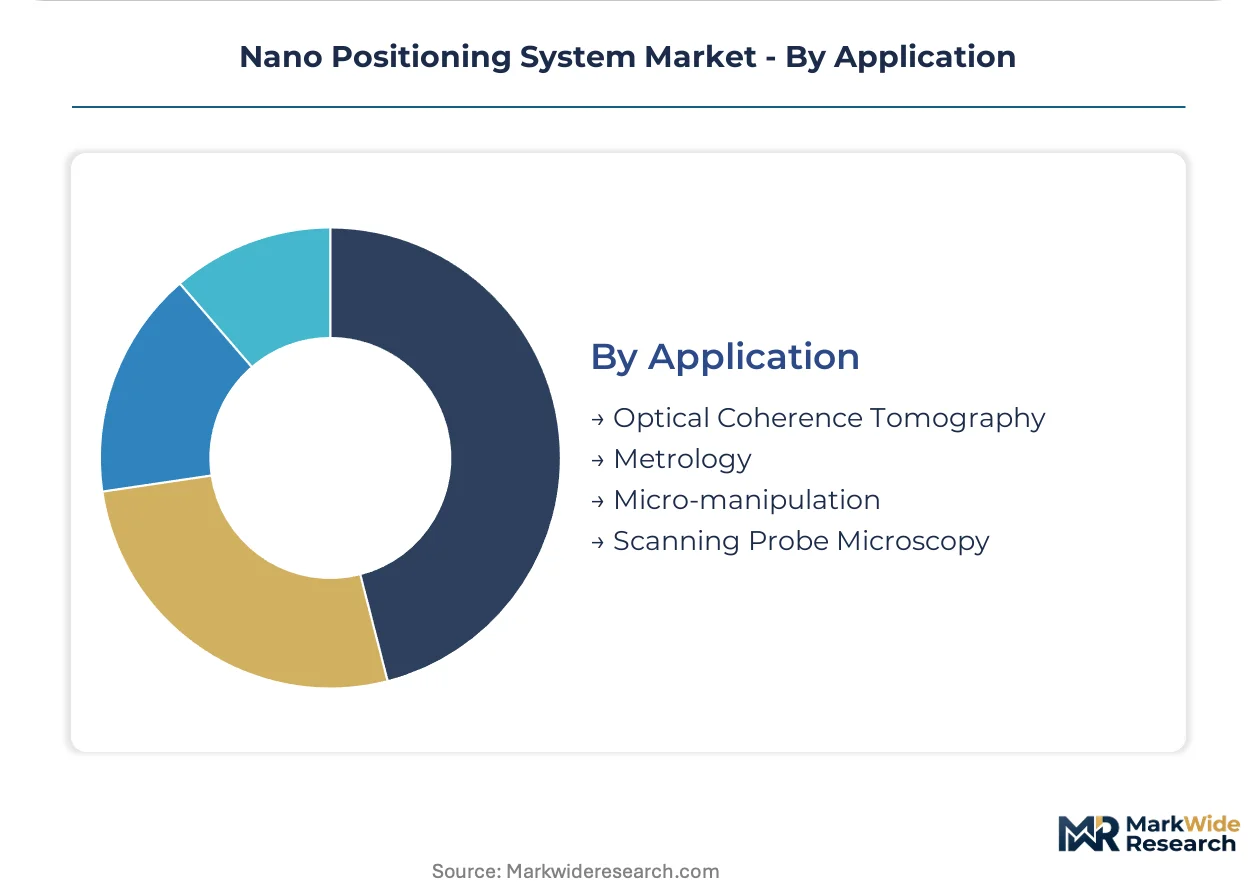
Application:
Use-case specific performance envelopes determine whether buyers prioritize speed, precision, or environmental compatibility.
- Metrology:Coordinate measuring machines and wafer inspection systems require six-degree-of-freedom stages with crosstalk compensation below 1 nanometer. Semiconductor tool builders in Germany and Japan co-develop thermal management with positioning vendors to satisfy METI energy efficiency directives.
- Optical Coherence Tomography:Biomedical imaging systems demand validated motion repeatability for micron-scale tissue scanning. FDA quality system requirements shape supplier qualification and extend development cycles for this segment.
- Scanning Probe Microscopy:Atomic force microscopy and related techniques need vibration-isolated stages with sub-angstrom resolution.
- Micro-manipulation:Cell biology and materials science applications combine optical microscopy with precision positioning for sample manipulation.
Installed base favors Metrology; Optical Coherence Tomography is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabs in Taiwan and South Korea concentrate the most acute demand for precision positioning systems, with quantum research infrastructure in Germany and Japan adding secondary volume centers. These four countries anchor procurement for EUV lithography alignment stages and cryogenic positioning setups.
Taiwan
Memory and logic foundries in Hsinchu and Tainan Science Parks drive procurement of vacuum-compatible multi-axis stages for sub-7nm node production. The National Science and Technology Council coordinates domestic supplier qualification programs under the Semiconductor Industry Development Framework. TSMC and United Microelectronics cluster their EUV tool installations in the Central Taiwan Science Park, compressing vendor selection cycles around closed-loop piezoelectric architectures.
South Korea
Samsung Electronics and SK Hynix fabs in Giheung and Pyeongtaek consolidate stage procurement under 10-year lifecycle service agreements. The Ministry of Trade, Industry and Energy enforces METI-aligned energy efficiency standards for piezo driver electronics through K-REACH substance monitoring. Memory production clusters in Icheon and Cheongju are negotiating total cost-of-ownership contracts that unbundle hardware from calibration services.
Germany
Fraunhofer Institutes and Max Planck Society laboratories in Munich and Stuttgart procure compact stick-slip drives for trapped-ion quantum computing testbeds. The Federal Ministry of Education and Research funds national quantum infrastructure through the Quantum Technologies Programme. Precision motion vendors in Baden-Württemberg co-develop thermal management solutions with tool builders to satisfy ISO 17025 calibration mandates for defense contracting.
Japan
RIKEN and Osaka University research groups in Kansai and Kanto regions source cryogenic-compatible positioning for superconducting qubit manipulation. METI energy efficiency directives force redesigns of piezo driver electronics to reduce standby power consumption in semiconductor manufacturing. Tokyo Electron and Nikon cluster their metrology tool development in Nagoya and Kumamoto, pulling in captive supply relationships with domestic stage manufacturers.
United States
National laboratories in Livermore, Argonne, and Oak Ridge procure multi-axis stages for quantum research and satellite optical assembly. FDA 21 CFR Part 820 quality systems shape biomedical positioning adoption where optical coherence tomography builders require validated motion repeatability. NIST traceability protocols determine supplier qualification for Department of Defense precision motion contracting.
Nano Positioning System Market Key Industry Players
Multi-year lifecycle service agreements dominate the current landscape as memory fabs in South Korea and Taiwan unbundle hardware from calibration and refurbishment. The vendor base organizes around vertically integrated motion subsystem providers, specialized compact drive manufacturers, and photonics-aligned positioning channels. Three archetypes anchor competitive positioning: captive piezoelectric actuator producers, stick-slip drive specialists for space-constrained setups, and heritage photonics brands controlling metrology-aligned distribution. Technology licensing and backward integration into high-purity PZT ceramics represent the dominant competitive moves.
Among European heritage positioning houses, Physik Instrumente (PI) GmbH & Co. KG and Attocube Systems AG exemplify the vertically integrated archetype through captive piezoelectric production. Newport Corporation occupies a position within photonics-aligned channels, leveraging its Newport and Spectra-Physics heritage. SmarAct GmbH represents the compact specialization vector with stick-slip drive architectures for quantum research setups. These three companies anchor the competitive structure without exhausting the vendor map.
| Leading Market Players |
|---|
| Newport Corporation |
| Attocube Systems AG |
| Physik Instrumente (PI) GmbH & Co. KG |
| SmarAct GmbH |
| Piezosystem Jena GmbH |
| Aerotech Inc. |
| Mad City Labs Inc. |
| Nanotion Ltd. |
| Thorlabs Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in precision motion control anchor pricing discipline through captive piezoelectric actuator production, insulating margin structures from raw material volatility while semiconductor fabs in Taiwan and South Korea consolidate procurement around long-term service agreements that compress transactional pricing flexibility.
Pricing Analysis
High-unit-value stage systems capture margin premiums against commoditized actuator components. Pricing stratifies across NIST-traceable certified tiers, vacuum-compatible configurations, and standard ambient-rated modules. Cost compression in entry-level actuators intensifies as Chinese suppliers expand piezoelectric stack capacity. Research institutions exhibit highest price sensitivity; EUV tool builders prioritize total cost-of-ownership guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from defense contractors and semiconductor fabs mandate qualified secondary suppliers for critical motion subsystems. High-purity lead zirconate titanate feedstock concentrates in Japan and China, with driver electronics sourcing anchored in Germany and the United States. Single-source vulnerability around Japanese PZT ceramics exposes stage manufacturers to export licensing delays. Distribution runs through direct OEM relationships and specialized photonics distributors serving metrology channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as ISO 17025 calibration mandates disqualify open-loop vendors, forcing sub-scale competitors toward exit or acquisition by vertically integrated motion subsystem providers.
For Market Incumbents: Anchor defensive positioning through backward integration into high-purity PZT ceramics and captive driver electronics production. Expand calibration service infrastructure in Taiwan and South Korea to capture lifecycle revenue under 10-year tool agreements. Threat substitution from compact stick-slip architectures in quantum research demands R&D investment in modular linear drive portfolios. For New Entrants and Emerging Players: Capacitive sensing modules for EUV tool retrofit represent the most penetrable white-space target. Target India's PLI-funded semiconductor packaging entrants with cost-optimized alignment stages for first-time fab buyers. Go-to-market leverage rests on co-development partnerships with domestic tool builders seeking import substitution. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European positioning houses with captive piezo production and dormant quantum research channel relationships. Long-term viability hinges on 5-10 year service contract attach rates exceeding hardware margins. Watch South Korean memory fab capex announcements as inflection indicators for stage procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PZT Ceramics | Japanese and Chinese feedstock control insulates margin structures from supply shocks. |
| Lifecycle Service Agreement Expansion | South Korean fabs unbundle hardware from calibration under 10-year uptime contracts. |
| Capacitive Sensing Module Launch | Taiwan EUV tool retrofits demand embedded position feedback immune to thermal drift. |
| Quantum Research Channel Partnership | German national laboratories procure compact stick-slip drives for cryogenic setups. |
| India PLI Scheme Alignment | Domestic packaging investments generate first-time demand from new fab entrants. |
Research Approach
Multi-period observation of EUV tool installation rates, PZT ceramic trade flows, and quantum research grant allocations anchored the trend analysis, supplemented by interviews with semiconductor tool procurement directors, precision motion R&D leads, calibration laboratory managers, and photonics distribution channel heads. Secondary validation drew from SEC filings of listed equipment suppliers, METI energy efficiency directive documentation, NIST calibration protocol releases, and customs records for piezoelectric component trade. Bottom-up stage shipment estimates triangulated against top-down fab capex allocations.
Segment-weighting across product type, technology modality, end-user vertical, and application use-case shaped the analytical framework. Modeled dimensions included vacuum compatibility tier, axis configuration complexity, and regional regulatory cluster. CAGRs derived from installed base evolution and replacement cycle analysis. Forecast inputs incorporated EUV lithography node transition timelines and national quantum infrastructure buildout schedules.
Several conditions sit outside the modeled scope, including speculative export control expansions around dual-use precision motion components and unannounced REACH substance restriction amendments affecting piezo driver electronics. Forecasts reflect documented assumptions regarding semiconductor fab utilization rates and research grant continuity. Deviation in PZT ceramic export licensing protocols would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Piezoelectric Accelerometer Market