
 Off-Highway Machine Position and Angle Sensor Components Market | 2026-2036
Off-Highway Machine Position and Angle Sensor Components Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Highway Machine Position and Angle Sensor Components Market Insights
Contactless Hall Effect sensing is tilting the technology stack away from mechanical potentiometers toward solid-state architectures with higher mean time between failures. Bosch Rexroth leverages in-house semiconductor fabrication to control sensor-to-hydraulic-valve integration. TE Connectivity anchors North American supply relationships through its ruggedized connector-sensor bundles. Pepperl+Fuchs specializes in intrinsically safe variants for mining and oil-and-gas off-highway deployments.
Off-highway machine position and angle sensor components are electromechanical devices that translate mechanical displacement or rotational position into electrical signals, typically operating across temperature ranges from minus forty to one hundred twenty-five degrees Celsius and sealing ratings of IP6K9K for exposure to dust, pressure washing, and vibration. Their primary purpose is enabling closed-loop control of booms, buckets, steering axes, and implement hitch positions in vehicles that lack on-road homologation. Rotary sensors and inclinometers lead unit volume because every articulated chassis and boom assembly requires angular feedback, while magnetostrictive sensors capture the fastest expansion as long-stroke hydraulic cylinders displace legacy cable-extension transducers in excavators and wheel loaders. Hall Effect technology dominates cost-optimized construction and agricultural machinery, whereas optical encoders retain premium positioning in autonomous guidance systems where resolution requirements exceed sixteen bits.
EPA Tier 4 Final and EU Stage V emissions regulations compel engine and aftertreatment control strategies that depend on precise throttle, EGR valve, and DEF dosing position feedback, directly expanding sensor counts per machine. ISO 15026 functional-safety standards and OSHA machinery directives shape product validation requirements, forcing suppliers to document failure modes and diagnostic coverage for safety-critical steering and braking position loops. Stakeholders must monitor how autonomous off-highway pilot programs in Australian mining and Canadian oil sands translate from demonstration fleets into production sensor specifications with hardened cybersecurity architectures.
Market Dynamics
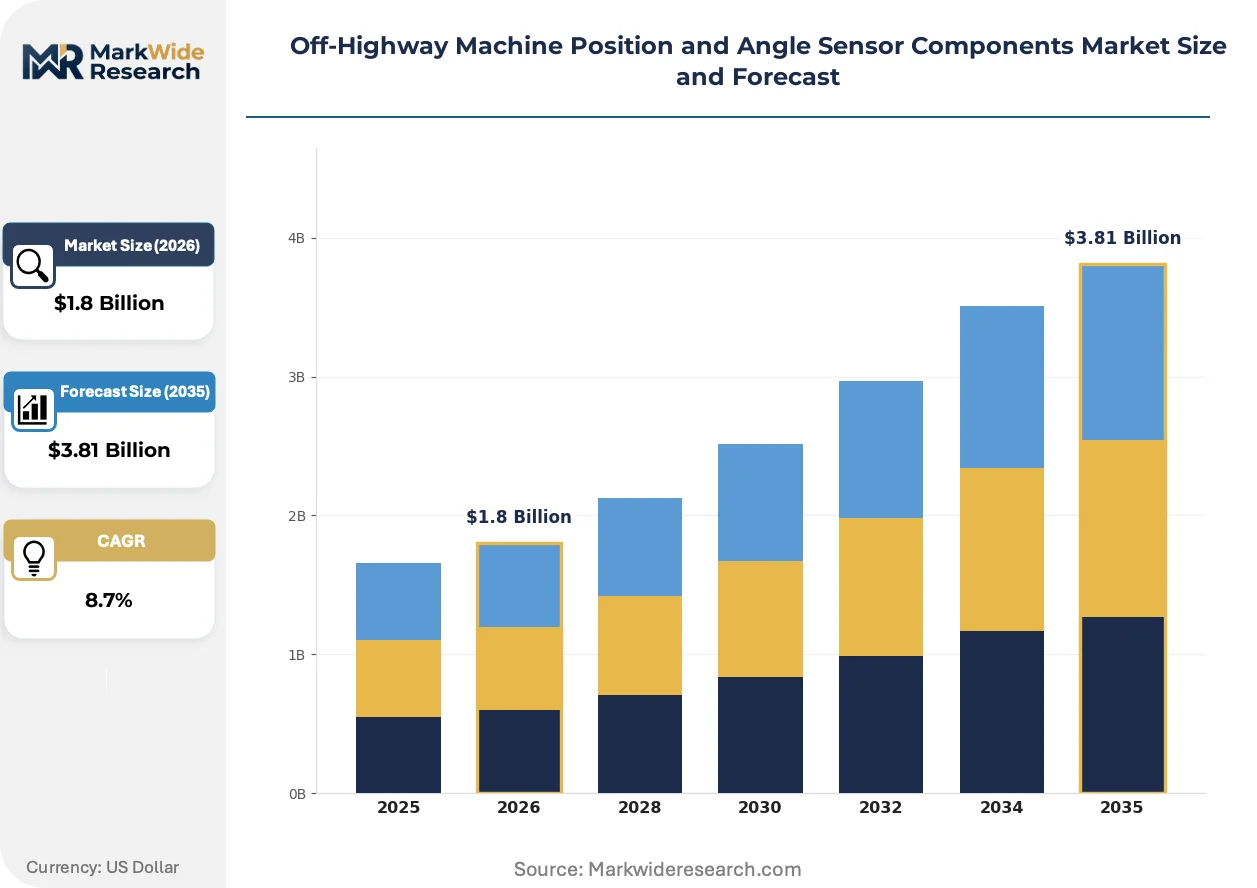
Contactless Hall Effect architectures are compressing replacement cycles and forcing mechanical potentiometer suppliers to retool fabs or exit, while EU Stage V and EPA Tier 4 Final emissions rules embed sensors deeper into engine control loops.
Growth Catalysts
- EU Green Deal machinery standards:The EU Green Deal's emissions mandates force engine and hydraulic optimization, embedding position feedback into every throttle valve and DEF dosing system across European construction fleets.
- Autonomous mining pilots:Australian and Canadian oil sands operators are specifying hardened cybersecurity architectures for demonstration fleets, translating into production sensor requirements with functional safety certification.
- Hall Effect cost curves:Solid-state semiconductor fabrication advances have collapsed per-unit costs, enabling two-sensor redundancy in mid-tier agricultural tractors previously limited to single mechanical units.
Market Restraints
- Neodymium price volatility:Rare-earth magnet supply concentration in Chinese processing facilities exposes Hall Effect sensor margins to input cost swings that mechanical alternatives avoid.
- ISO 15026 validation burden:Functional safety documentation requirements for steering and braking position loops extend development timelines and lock out uncertified entrants from safety-critical applications.
- Optical encoder substitution ceiling:Autonomous guidance systems demanding sixteen-bit resolution maintain optical architectures that cap Hall Effect penetration in premium positioning segments.
Strategic Opportunities
- Indian construction mechanization:The country's national infrastructure regulator is accelerating highway and rail projects, creating first-time demand for precision boom control in domestic equipment fleets.
- Sensor-to-valve integration:Convergence of MEMS fabrication with hydraulic manifold design enables single-supplier bundles that capture value previously split between component vendors.
- CSRD supply chain disclosure:The EU's corporate sustainability reporting directive rewards sensor suppliers with documented lifecycle data, creating preference premiums in European OEM sourcing decisions.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 and ISO 15026 certified firmware developers command salary premiums that strain mid-tier sensor houses competing for talent against automotive suppliers.
- Legacy CAN bus integration:Decades-old machine communication protocols resist real-time position data throughput, forcing gateway hardware investments that erode solid-state sensor margin advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Highway Machine Position and Angle Sensor Components Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Sensors, Linear Sensors, Inclinometers, Gyroscopic Sensors, Magnetostrictive Sensors Technology: Capacitive, Inductive, Optical, Ultrasonic, Hall Effect Application: Construction Equipment, Agricultural Machinery, Mining Tools, Forestry Equipment, Material Handling End User: Equipment Manufacturers, Component Suppliers, Rental Companies, Government Contractors |
| Companies Covered | FORVIA HELLA, Baumer, ifm electronic, Bosch Rexroth, HYDAC, Novotechnik, TE Connectivity, Pepperl+Fuchs, SICK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Highway Machine Position and Angle Sensor Components Market Trends and Innovations
Magnetostrictive position sensing is hybridizing with wireless telemetry to eliminate cable fatigue failures in long-stroke cylinders, while procurement departments consolidate supplier panels around safety-certified bundles.
Magnetostrictive waveguide technology measures piston position in hydraulic cylinders by detecting the intersection of magnetic fields with mechanical strain pulses. Mining OEMs in Western Australia and oil sands operators in Alberta are adopting these sensors at replacement-cycle pace for boom and bucket cylinders. The technology is hybridizing with Bluetooth Low Energy transmitters to replace braided cable harnesses that fail under constant flexing and abrasion.
EPA Tier 4 Final and EU Stage V regulations mandate closed-loop control of exhaust gas recirculation valves and selective catalytic reduction dosing modules. Engine manufacturers must embed redundant position feedback into every emissions-critical actuator, expanding sensor counts per powertrain. Agricultural equipment in the US Corn Belt and construction machinery in Germany's industrial corridor show the steepest compliance-driven specification upgrades.
Equipment finance departments now bundle sensor health monitoring into lease residual value calculations. OEM captive finance arms in Japan and Germany are displacing third-party lessors by guaranteeing uptime through predictive position-sensor replacement schedules. This preference shift concentrates procurement authority at headquarters level, compressing the distributor channel that historically sold replacement sensors to fleet maintenance shops.
Off-Highway Machine Position and Angle Sensor Components Market Segmentation
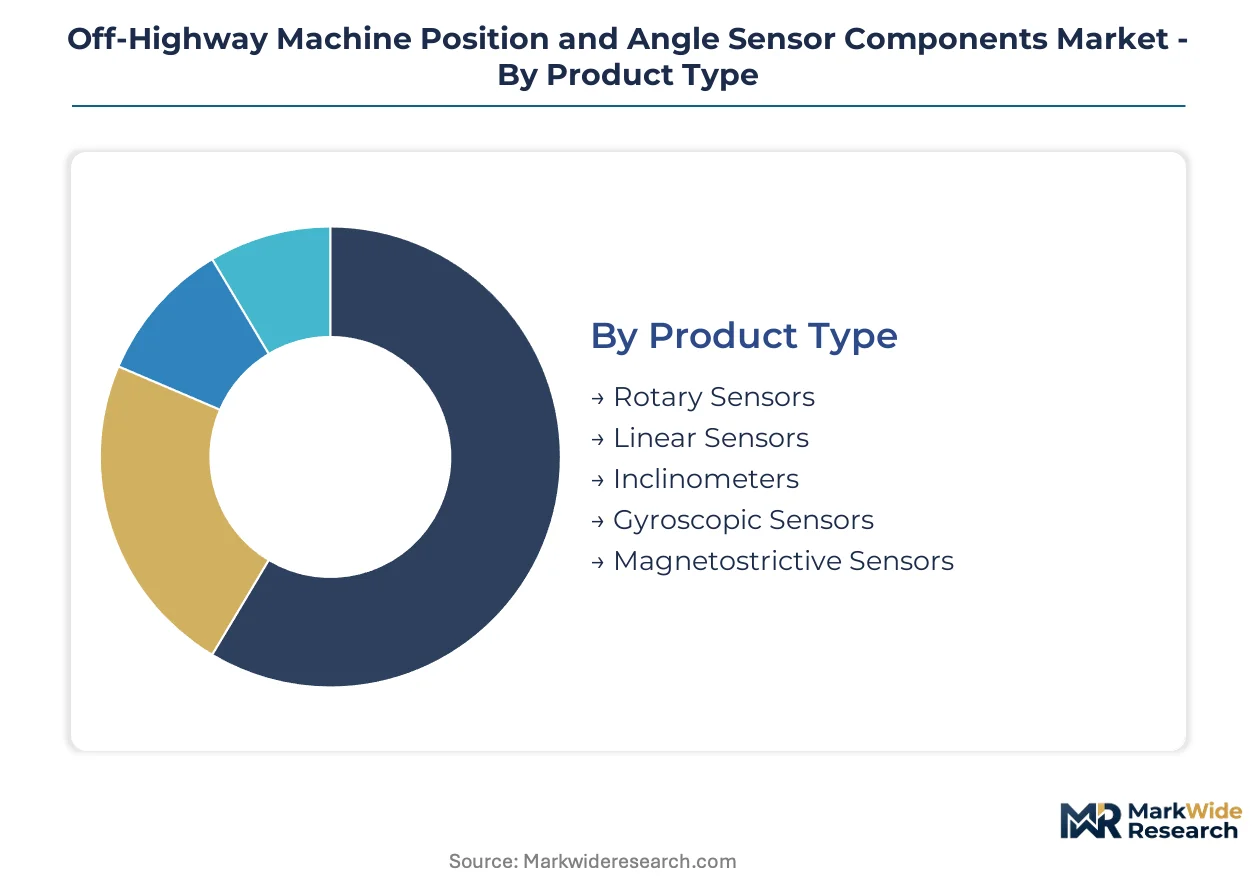
Segmentation reveals how replacement cycles, technology transitions, and regulatory compliance reshape procurement patterns across off-highway equipment fleets. Understanding these divides exposes where sensor suppliers capture margin versus where they compete on unit cost.
Product Type:
Rotary sensors and inclinometers turn over fastest on articulated chassis with constant boom motion, while gyroscopic units persist longest in stabilized guidance platforms.
- Rotary Sensors:Electromechanical devices measuring angular displacement through conductive plastic or Hall Effect elements, typically sealed to IP6K9K. Demand concentrates in German construction equipment where EU Stage V compliance mandates redundant steering position feedback.
- Inclinometers:Solid-state MEMS devices detecting gravitational tilt for bucket and blade leveling. Australian mining fleets specify these for autonomous haul truck navigation, with replacement cycles accelerated by shock loading in rough-terrain operations.
- Linear Sensors:Potentiometric or magnetostrictive architectures translating straight-line displacement into voltage or pulse signals.
- Gyroscopic Sensors:MEMS-based angular rate sensors for stability control and GPS-denied navigation in forestry and underground mining.
- Magnetostrictive Sensors:Waveguide technology measuring piston position via sonic pulse timing in hydraulic cylinders.
Rotary sensors anchor the volume base while magnetostrictive sensors gain share at the steepest rate.
Technology:
Cost tiers separate premium optical architectures from mass-market Hall Effect implementations, with inductive and capacitive variants occupying intermediate positioning.
- Hall Effect:Semiconductor-based magnetic field detection offering contactless operation and solid-state reliability. Agricultural machinery OEMs in the US Corn Belt specify these for throttle and EGR valve position due to collapsed per-unit costs from fabrication advances.
- Optical:Encoder disks with photodetector arrays delivering sub-arcminute resolution. Canadian oil sands autonomous fleets require these for sixteen-bit positioning in dragline and shovel guidance systems.
- Capacitive:Dielectric sensing for short-stroke applications with immunity to magnetic interference.
- Inductive:Eddy-current principles for harsh environments with metallic contamination.
- Ultrasonic:Time-of-flight measurement for non-contact distance sensing in material handling.
Hall Effect technology commands the highest shipment volumes whereas optical encoders capture the premium tier.
Application:
Equipment utilization intensity determines sensor specification grade, with mining and construction demanding hardened variants against agricultural and forestry applications.
- Construction Equipment:Excavators, wheel loaders, and dozers requiring boom, bucket, and blade position feedback. German OEMs embed redundant sensors to satisfy EU Green Deal machinery emissions standards for engine and hydraulic optimization.
- Mining Tools:Surface and underground equipment with extreme vibration, shock, and temperature exposure. Western Australian iron ore operators specify magnetostrictive cylinder sensors with Bluetooth Low Energy telemetry to eliminate cable fatigue.
- Agricultural Machinery:Tractors, combines, and implements with seasonal duty cycles and cost-sensitive specification.
- Forestry Equipment:Harvesters and forwarders with moisture ingress and mechanical impact challenges.
- Material Handling:Forklifts and telehandlers with repetitive motion and safety-critical load positioning.
Construction equipment anchors the volume base while mining tools expand most quickly through autonomous fleet conversion.
End User:
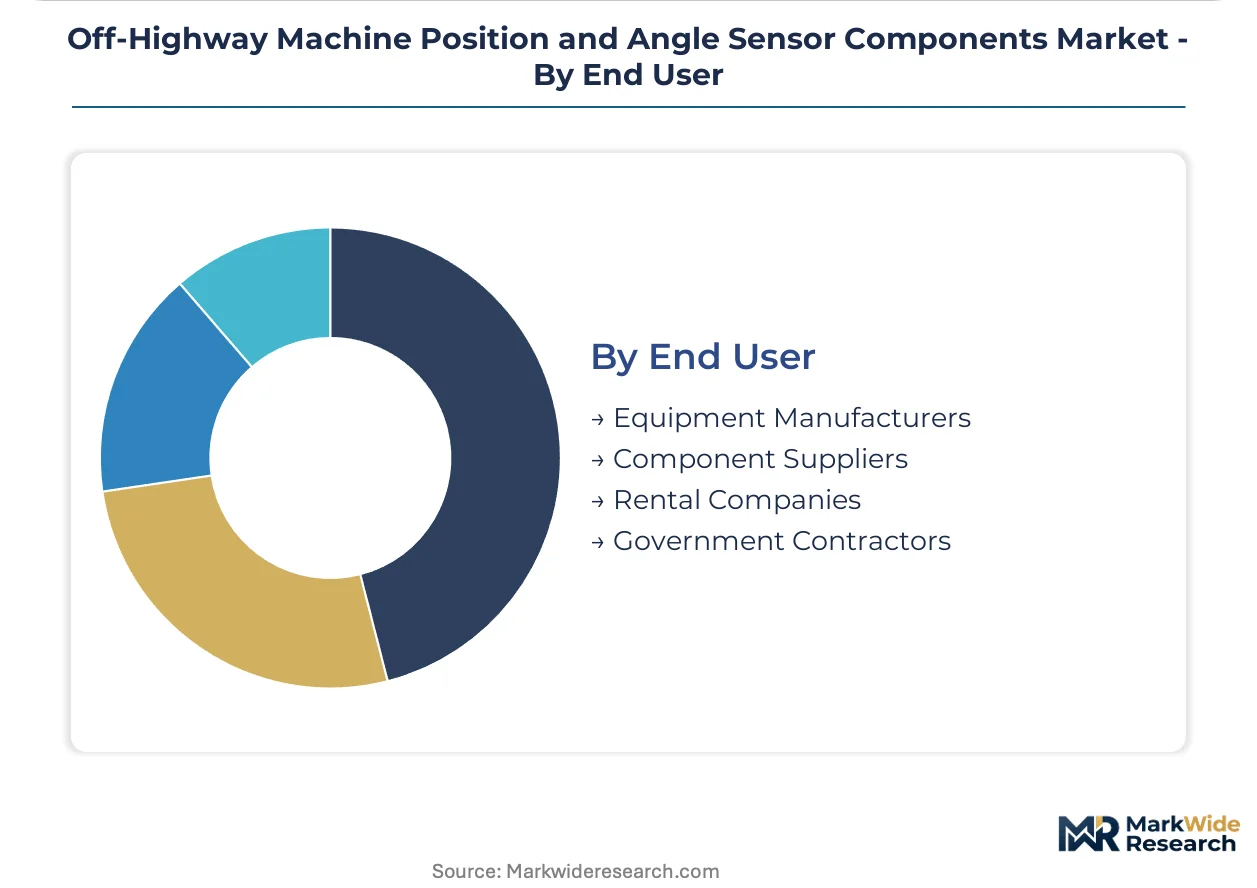
Procurement authority concentrates at equipment manufacturers and component suppliers, with rental companies and government contractors representing fragmented secondary demand.
- Equipment Manufacturers:OEMs integrating sensors at original assembly with multi-year supply agreements. Japanese and German captive finance arms now bundle sensor health monitoring into lease residual calculations, tightening procurement centralization.
- Component Suppliers:Tier-1 and Tier-2 hydraulic and powertrain system integrators specifying sensor-to-valve bundles. Bosch Rexroth controls semiconductor fabrication for captive sensor production.
- Rental Companies:Fleet operators with aftermarket replacement demand and uptime-focused maintenance schedules.
- Government Contractors:Defense and infrastructure projects with certified supplier requirements and extended validation timelines.
Equipment manufacturers anchor the volume base while component suppliers climb the fastest through integrated system bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor exports flow to Australian mining fleets and North American construction OEMs, establishing a trade corridor that concentrates R&D investment in Bavaria and Baden-Württemberg while pulling volume through Perth and Edmonton distribution nodes.
Germany
EU Stage V emissions mandates from the EU Green Deal force redundant position feedback into every EGR valve and DEF dosing system across construction equipment. Baumer and SICK anchor sensor R&D clusters in Bavaria's industrial corridor, with captive semiconductor fabrication lines expanding near Munich.
United States
EPA Tier 4 Final regulations embed sensors deeper into engine control loops for agricultural tractors and construction machinery. TE Connectivity leverages ruggedized connector-sensor bundles through Midwest distribution hubs serving the Corn Belt equipment OEMs.
Australia
Autonomous mining pilot programs in Western Australia's iron ore operations specify hardened cybersecurity architectures for position feedback systems. Perth-based fleet operators adopt magnetostrictive cylinder sensors with Bluetooth Low Energy telemetry to eliminate cable fatigue failures.
Canada
Oil sands operators in Alberta demand sixteen-bit resolution optical encoders for dragline and shovel guidance systems. Edmonton serves as the procurement hub where autonomous fleet specifications translate into production sensor requirements with functional safety certification.
China
Domestic construction equipment OEMs accelerate precision guidance system adoption for highway and rail infrastructure projects. Rare-earth magnet processing concentration exposes Hall Effect sensor supply chains to input cost volatility from northern mining regions.
Off-Highway Machine Position and Angle Sensor Components Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three tiers: diversified industrial conglomerates with captive semiconductor fabrication, mid-tier sensor houses with safety-certified portfolios, and regional distributors serving aftermarket replacement cycles. Consolidation pressure intensifies as ISO 15026 validation requirements lock out uncertified entrants from safety-critical steering and braking applications. Dominant competitive moves include backward integration into MEMS fabrication and strategic bundling of sensor-to-valve integration packages.
Among German-based sensor specialists, SICK and Baumer occupy positions within the safety-certified tier, exemplifying the archetype of mid-cap houses competing for ISO 26262 certified firmware talent against automotive suppliers. FORVIA HELLA represents the diversified conglomerate vector with cross-sectoral sensor portfolios spanning automotive and off-highway applications. TE Connectivity anchors the North American supply relationship tier through bundled connector-sensor offerings.
| Leading Market Players |
|---|
| FORVIA HELLA |
| Baumer |
| ifm electronic |
| Bosch Rexroth |
| HYDAC |
| Novotechnik |
| TE Connectivity |
| Pepperl+Fuchs |
| SICK |
| Others |
Pricing and Supply Chain Analysis
Neodymium price volatility in Chinese rare-earth processing facilities compresses Hall Effect sensor margins while simultaneously widening the cost spread between magnetic-field architectures and legacy mechanical alternatives, forcing procurement departments to dual-source across magnetostrictive and optical encoder tiers to hedge input exposure.
Pricing Analysis
The technology-generation pricing gap between Hall Effect solid-state architectures, legacy potentiometric designs, and emerging magnetostrictive hybrids anchors market stratification. Three-tier pricing structure across premium optical encoders, standard Hall Effect units, and economy potentiometric variants reflects ISO 15026 functional-safety certification levels and resolution specifications. Cost compression in mid-tier agricultural machinery intensifies as semiconductor fabrication advances collapse per-unit Hall Effect costs, enabling two-sensor redundancy previously limited to premium construction equipment. Rental fleet operators exhibit highest price sensitivity due to uptime-focused maintenance budgets, whereas autonomous mining OEMs prioritize cybersecurity-hardened specifications over unit cost.
Supply Chain Analysis
Extended payment terms from German construction equipment OEMs now stretch to 120 days, forcing mid-tier sensor houses to access supply-chain finance facilities or cede share to diversified conglomerates with captive working capital. Semiconductor fabrication concentrates in Germany, Taiwan, and the United States, with Bosch Rexroth and SICK anchoring captive production near Munich. Rare-earth magnet supply draws from Chinese processing facilities, while precision optical components source from Japanese and South Korean specialist manufacturers. Single-source vulnerability in neodymium supply exposes margin stability to northern Chinese mining region output fluctuations. Distribution runs through OEM captive procurement departments consolidating supplier panels around safety-certified bundles, compressing traditional distributor channels serving aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The convergence of sensor-to-valve integration with functional-safety certification requirements creates platform-economics dynamics where ISO 15026-compliant suppliers capture ecosystem lock-in through hydraulic manifold design partnerships.
For Market Incumbents: Insulate market position by deepening backward integration into MEMS fabrication to control semiconductor supply during rare-earth price spikes, and anchor procurement relationships through predictive sensor health monitoring bundled into OEM captive finance lease structures. Hall Effect cost curve acceleration threatens premium positioning unless incumbents embed cybersecurity architectures ahead of autonomous fleet production specifications. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian construction equipment precision guidance systems, where national infrastructure acceleration creates first-time demand for boom control sensors without entrenched incumbent relationships. Target magnetostrictive sensor-to-telemetry bundles for Western Australian mining replacement cycles, leveraging Bluetooth Low Energy integration as a differentiated go-to-market angle against legacy cable-harness suppliers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors mid-cap safety-certified specialists with ISO 15026 documentation capabilities and captive semiconductor fabrication assets. Long-term viability hinges on regulatory compliance depth rather than unit cost optimization, positioning functional-safety engineering talent pools as scarce acquisition targets. Watch Australian autonomous mining pilot conversions to production fleet specifications as the inflection signal for cybersecurity-hardened sensor demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Bosch Rexroth's captive semiconductor lines control sensor-to-hydraulic-valve integration timing and cost. |
| Functional Safety Certification Investment | ISO 15026 documentation unlocks safety-critical steering and braking position loop procurement access. |
| Sensor-to-Valve Bundle Development | Converged hydraulic manifold designs capture value previously split between component vendors. |
| Cybersecurity Architecture Hardening | Autonomous mining fleets in Alberta and Western Australia specify production-grade security protocols. |
| Predictive Health Monitoring Service | Japanese and German OEM finance arms guarantee uptime through sensor replacement scheduling. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with sensor procurement managers at German construction OEMs, hydraulic system engineers at Australian mining operators, and aftermarket service directors at North American rental fleets; and secondary validation through EU Stage V regulatory filings, EPA Tier 4 Final compliance documentation, SEC 10-K disclosures from diversified industrial conglomerates, and customs trade data on rare-earth magnet flows. Bottom-up unit shipment estimates triangulated against top-down equipment production forecasts from agricultural and construction machinery databases.
Forecast inputs considered technology substitution rates between Hall Effect and optical architectures, regulatory compliance timelines across EU and North American emissions standards, and autonomous fleet conversion trajectories in mining applications. Segmentation modeling spanned product type, technology generation, application intensity, and end-user procurement authority dimensions. CAGRs derived from equipment replacement cycle analysis, semiconductor cost curve projections, and functional-safety certification adoption curves.
Macroeconomic conditions sit as an overlay; deviation in neodymium commodity prices, semiconductor foundry capacity allocation, or EU Green Deal implementation pacing would shift the trajectory. Forecasts reflect documented assumptions on technology transition speeds and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
France Digital Thermometer Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
Torque Transducer Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Vision Sensor Market