
 Exhaust Sensors Market | 2026-2036
Exhaust Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Exhaust Sensors Market Analysis
Commercial vehicle fleet operators is reorganizing procurement priorities toward predictive maintenance and real-time emission monitoring, pulling demand away from traditional passenger car OEM channels. Robert Bosch GmbH leverages its integrated electronics foundry network to dominate NOx sensor module production. Continental AG anchors European supply through captive ceramic substrate manufacturing in Germany. DENSO Corporation specializes in high-temperature thermistor arrays for heavy-duty diesel applications across Asia-Pacific markets.
Exhaust sensors are electrochemical or solid-state transducers that measure gas composition, thermal profiles, or pressure differentials in engine effluent streams, typically operating between 600°C and 900°C to ensure signal fidelity in corrosive thermal environments. Their primary commercial purpose is to enable closed-loop feedback for catalytic converter efficiency and onboard diagnostic fault detection. Oxygen sensors occupy the largest installed base due to universal gasoline and diesel powertrain requirements, while NOx sensors command premium positioning as Euro 7 and EPA Tier 3 regulations proliferate. Aftermarket providers represent the fastest-growing channel as aging vehicle parc and extended service intervals expand replacement demand beyond factory-installed units.
The EPA enforces Tier 3 emission standards that mandate precise NOx and particulate measurement, compelling sensor calibration to single-digit ppm resolution. EMA's Euro 7 framework extends real-driving emission monitoring requirements, directly expanding sensor count per vehicle platform. China's MIIT implements GB VI standards with remote OBD verification, creating localized certification barriers for non-domestic suppliers. Stakeholders must monitor regulatory divergence between testing protocols to avoid platform fragmentation costs.
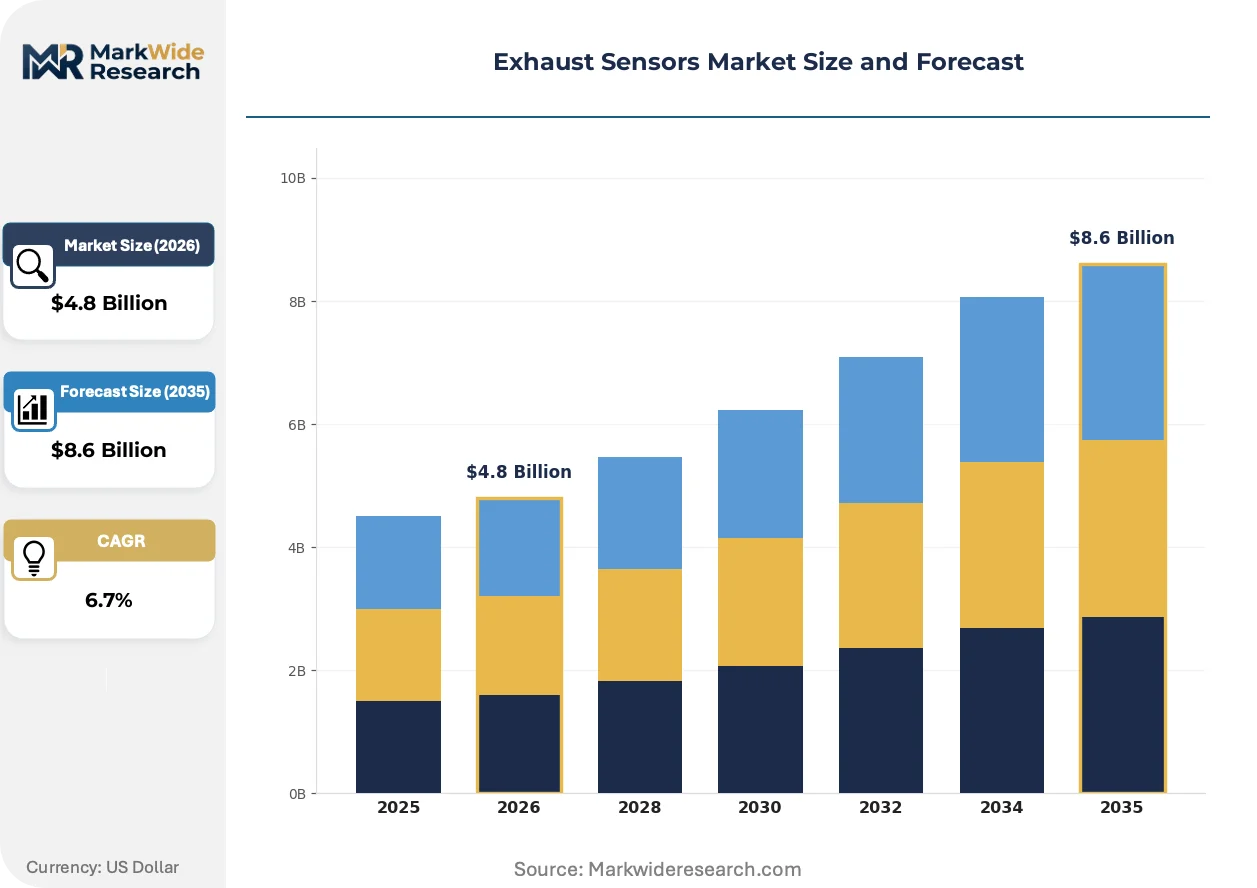
Market Dynamics
The exhaust sensors market is undergoing fundamental restructuring as Euro 7 and EPA Tier 3 regulations force simultaneous hardware upgrades across gasoline, diesel, and emerging hydrogen combustion platforms. This regulatory compression is collapsing traditional sensor procurement cycles and concentrating volume with suppliers capable of certifying multi-platform compatibility.
Growth Catalysts
- Euro 7 Real-Driving Emissions:EMA's expanded RDE testing protocols mandate continuous NOx monitoring under dynamic load conditions, doubling sensor count per heavy-duty vehicle platform.
- China GB VI Remote OBD:MIIT's telematics verification requirements create captive demand for domestically certified sensor modules with embedded cellular transmitters.
- Hydrogen Combustion R&D:OEM development of H2-ICE powertrains requires novel ammonia slip sensors for aftertreatment systems, opening adjacent sensor categories.
Market Restraints
- Palladium Supply Concentration:Russia and South Africa control 75% of global palladium refining, exposing sensor electrode costs to geopolitical supply shocks.
- Ceramic Substrate Oligopoly:German and Japanese suppliers dominate yttria-stabilized zirconia production, limiting second-source qualification options for tier-2 module assemblers.
- Electrochemical Drift Limitations:Solid-state NOx sensors suffer baseline drift above 800°C, constraining placement proximity to turbocharger outlets.
Strategic Opportunities
- Indian Commercial Vehicle Parc:BS VI Phase 2 implementation creates 40 million unit retrofit opportunity as aging trucks require aftermarket sensor replacement.
- Sensor-as-a-Service Models:Fleet operators in Germany are piloting subscription-based emission monitoring with integrated predictive maintenance analytics.
- Silicon Carbide MEMS Convergence:Integration of wide-bandgap semiconductor substrates with microelectromechanical structures enables multi-gas detection in single packages.
Industry Challenges
- Calibration Engineer Scarcity:Specialized expertise in ppm-level NOx signal processing across temperature transients commands 40% salary premiums in Stuttgart and Detroit labor markets.
- Platform Fragmentation Costs:Divergent EPA, EMA, and MIIT test protocols force sensor suppliers to maintain three distinct firmware calibrations per hardware variant.
- Legacy CAN Bus Integration:Older commercial vehicle fleets lack bandwidth for real-time emission data streaming, requiring gateway hardware retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exhaust Sensors Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Oxygen Sensors, Temperature Sensors, Pressure Sensors, NOx Sensors Application: Emission Control, Engine Management, Fuel Economy, Diagnostics End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Vehicle Type: Passenger Cars, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Sensata Technologies, ZF Friedrichshafen AG, NGK Spark Plug, BorgWarner Inc., Faurecia, HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exhaust Sensors Market Emerging Trajectories
Sensor architecture is fragmenting along temperature-grade and communication-protocol axes as powertrain electrification diversifies thermal environments. Manufacturers are repositioning R&D spend toward solid-state platforms that eliminate noble metal dependencies.
Wide-bandgap semiconductor materials are decomposing the traditional platinum-palladium-rhodium electrode stack in high-temperature oxygen sensors. Heavy-duty diesel OEMs in Germany and the United States are accelerating qualification timelines for silicon carbide-based lambda probes. This material transition is decomposing cost structures in the premium sensor tier while compressing margins for electrochemical specialists.
EPA Tier 3 and California LEV IV standards are tightening particulate number limits below 10^12 per kilometer, forcing gasoline direct injection engines to adopt gasoline particulate filters with integrated differential pressure sensors. The industrial consequence is sensor module consolidation, combining pressure, temperature, and oxygen sensing in single housing units. Passenger car platforms targeting 2027 model year compliance are absorbing 15-20% sensor unit cost increases to meet calibration precision requirements.
Fleet procurement departments are unbundling sensor replacement from full exhaust system service contracts, creating direct commercial relationships with module suppliers. Independent repair chains in the United States and aftermarket distributors in Poland are capturing this disintermediated volume through private-label sensor programs. This channel shift is most visible in Class 8 truck segments where extended warranty periods compress OEM captive parts revenue.
Exhaust Sensors Market Segmentation
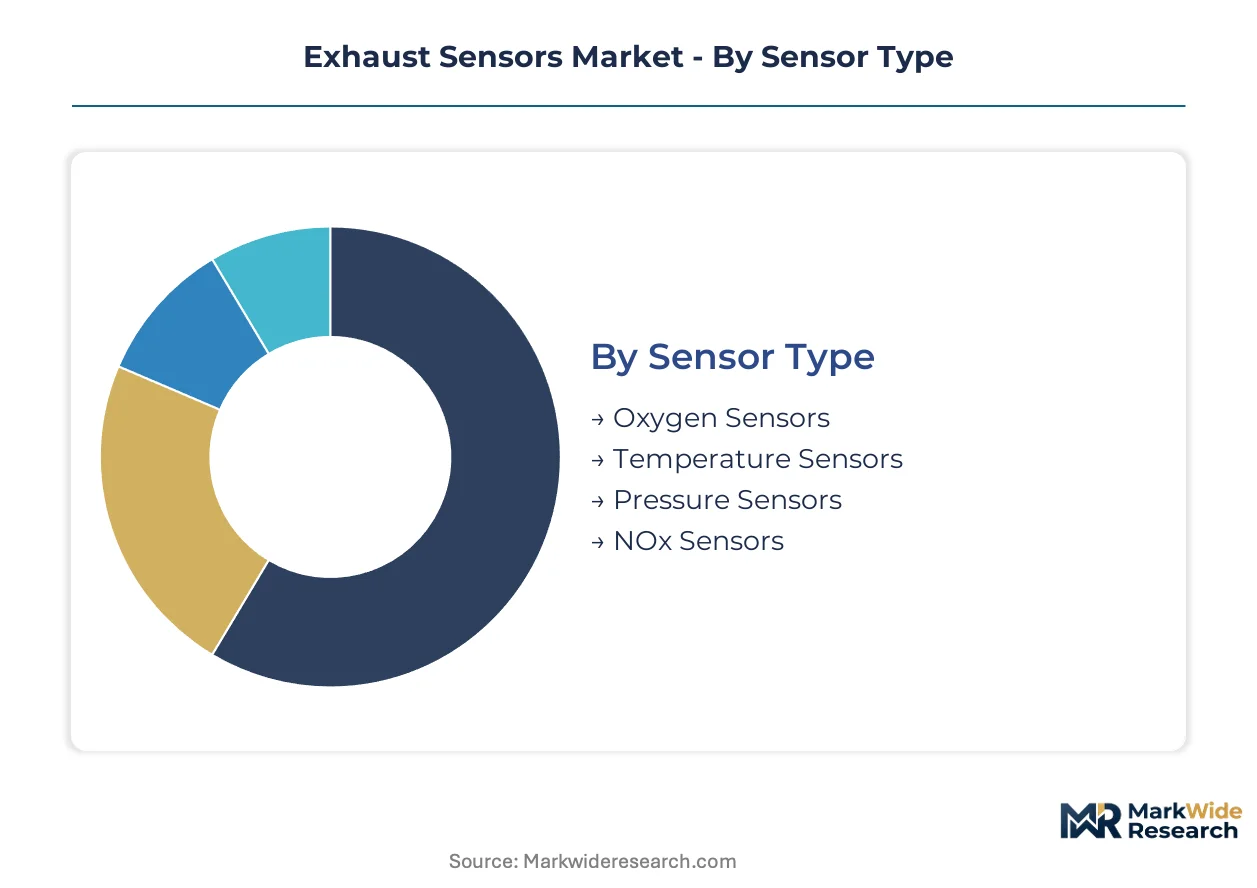
Exhaust sensor procurement splits sharply across regulatory compliance tiers, with Euro 7 and EPA Tier 3 forcing divergent technical specifications by application and vehicle class. Suppliers must maintain parallel certification tracks to serve fragmented OEM and aftermarket channels without platform standardization.
Sensor Type:
EMA's Euro 7 real-driving emission mandates and EPA Tier 3 calibration requirements create divergent performance thresholds across electrochemical and solid-state architectures.
- Oxygen Sensors:Zirconia-based lambda probes measure air-fuel ratios through voltage potential across platinum electrodes, operating between 300°C and 900°C. Gasoline powertrains in Germany and the United States consume the largest volumes as closed-loop fuel trimming remains mandatory for LEV IV compliance. Ceramic heater elements dominate cost structures in this mature segment.
- NOx Sensors:Solid-state electrochemical cells with yttria-stabilized zirconia electrolytes detect nitrogen oxide concentrations below 10 ppm resolution. Heavy-duty diesel platforms across European Union member states require dual-sensor configurations per vehicle under expanded RDE testing protocols, compressing procurement cycles for module suppliers.
- Temperature Sensors:Thermistor arrays monitor exhaust gas thermal profiles upstream and downstream of catalytic converters. K-type thermocouples serve cost-sensitive motorcycle applications in India.
- Pressure Sensors:Piezoresistive or capacitive differential pressure transducers measure filter loading in gasoline particulate filter systems. Silicon MEMS variants are penetrating passenger car platforms in Japan.
Oxygen sensors handle the majority of throughput; NOx sensors are gaining share fastest as regulatory thresholds tighten across multiple geographies.
Application:
Cost tier differentiation separates premium calibration-grade modules from standard diagnostic units across fleet procurement portfolios.
- Emission Control:Closed-loop feedback systems for catalytic converter efficiency optimization require sub-ppm measurement precision. Euro 7 real-driving emission testing in European Union markets mandates continuous monitoring under dynamic load conditions, expanding sensor count per platform.
- Engine Management:Lambda sensor input governs fuel injection timing and ignition advance in port-injected gasoline architectures. Brazil's flex-fuel vehicle parc demands ethanol-compatible sensor chemistries.
- Fuel Economy:Wide-band oxygen sensors enable lean-burn combustion strategies in hybrid powertrains. Japanese OEMs prioritize this application for next-generation thermal efficiency targets.
- Diagnostics:Onboard diagnostic fault detection triggers malfunction indicator lamps for catalyst degradation or sensor drift. United States aftermarket channels capture replacement volume as vehicles age beyond warranty periods.
Emission control absorbs the largest procurement spend; diagnostics is expanding most quickly as fleet telematics integration accelerates.
End User:
Volume concentration shifts toward direct fleet relationships as predictive maintenance contracts disintermediate traditional distribution channels.
- OEMs:Original equipment manufacturers specify sensor modules during powertrain development, locking in multi-year supply agreements. German passenger car producers dominate premium sensor procurement through captive electronics divisions.
- Aftermarket Providers:Independent distributors and repair chains source replacement sensors for aging vehicle parc. Polish distributors are capturing disintermediated volume through private-label programs.
- Fleet Operators:Commercial vehicle fleets in Germany pilot subscription-based emission monitoring with integrated predictive maintenance analytics. Direct procurement bypasses traditional parts distribution networks.
- Research Institutions:Universities and national laboratories characterize novel sensor chemistries for hydrogen combustion applications. South Korean government-funded institutes lead ammonia slip sensor development.
OEMs command the dominant share of new-vehicle sensor volume; fleet operators are climbing the fastest as service contracts restructure procurement relationships.
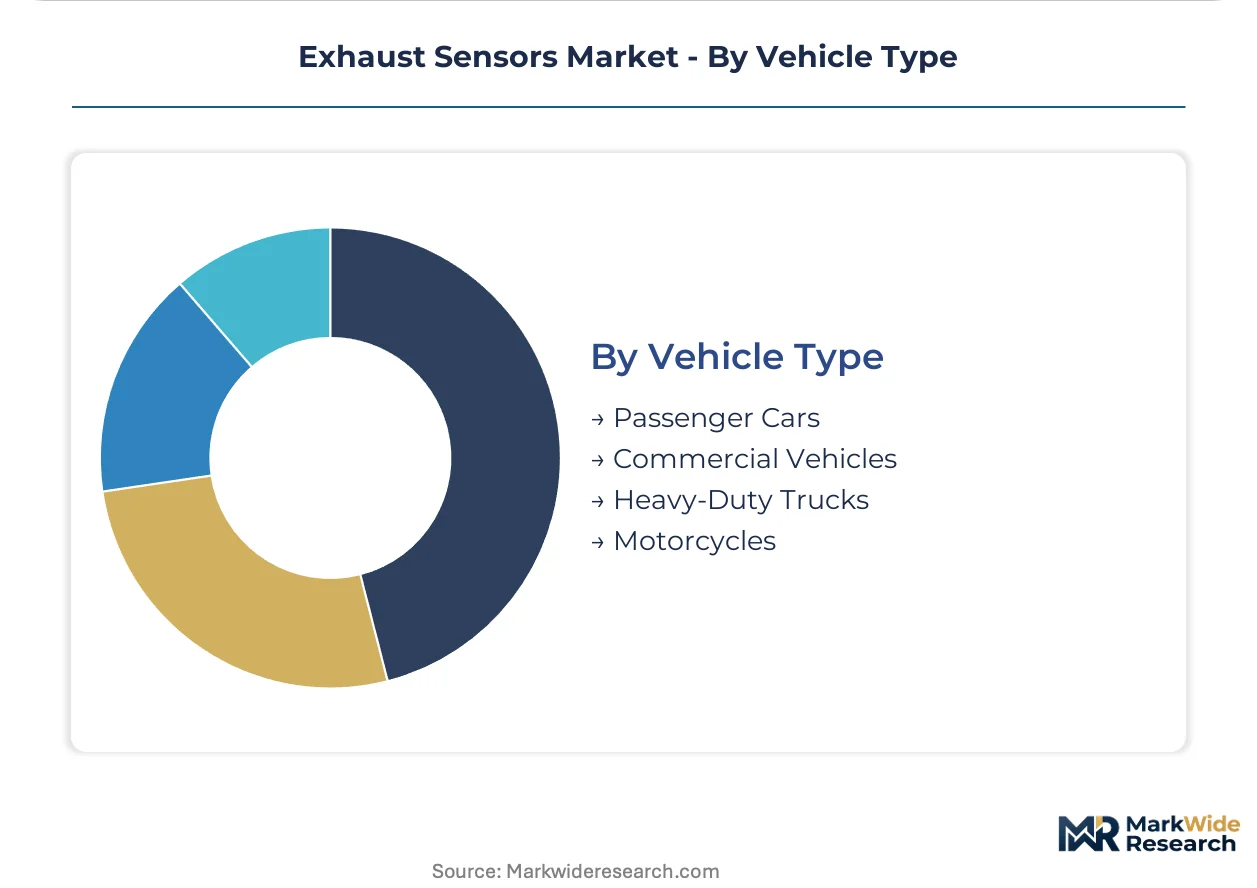
Vehicle Type:
Margin structures diverge sharply between high-unit passenger car platforms and low-volume heavy-duty applications requiring extended temperature durability.
- Commercial Vehicles:Heavy-duty diesel trucks require NOx and particulate sensors certified for 1.2 million kilometer service life. Euro 7 mandates in European Union member states double sensor count per platform versus predecessor regulations.
- Passenger Cars:Gasoline direct injection architectures integrate combined pressure-temperature-oxygen modules for particulate filter management. United States and Chinese OEMs absorb 15-20% unit cost increases for calibration precision.
- Heavy-Duty Trucks:Class 8 long-haul segments in North America demand sensors rated for 900°C continuous operation. Extended warranty periods compress OEM captive parts revenue.
- Motorcycles:Cost-optimized lambda sensors serve two-wheeler emission compliance in India and Southeast Asia. BS VI Phase 2 implementation creates retrofit demand for 40 million unit parc.
Commercial vehicles carry the highest sensor content per platform; motorcycles are expanding most quickly as emerging market emission standards proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports sensor modules to commercial vehicle OEMs in the United States and China, establishing the primary trade corridor for exhaust sensor technology. This flow concentrates procurement power with German suppliers while creating localized certification requirements in destination markets.
United States
EPA Tier 3 standards mandate single-digit ppm NOx resolution for heavy-duty diesel certification. California's LEV IV rules extend particulate number limits below 10^12 per kilometer, forcing gasoline direct injection architectures to adopt integrated pressure-temperature-oxygen modules. Detroit anchors North American sensor procurement through captive relationships with Class 8 truck manufacturers.
Germany
EMA's Euro 7 framework doubles sensor count per heavy-duty platform through expanded real-driving emission testing protocols. Stuttgart labor markets command 40% salary premiums for calibration engineers specializing in ppm-level NOx signal processing. Bavaria concentrates yttria-stabilized zirconia ceramic substrate production, limiting second-source options for tier-2 module assemblers.
China
MIIT implements GB VI standards with remote OBD verification, creating captive demand for domestically certified sensor modules with embedded cellular transmitters. The Yangtze River Delta hosts telematics integration facilities serving state-owned commercial vehicle producers. Shanghai-based fleet operators pilot subscription-based emission monitoring with predictive maintenance analytics.
India
BS VI Phase 2 implementation creates 40 million unit retrofit opportunity as aging trucks require aftermarket sensor replacement. The central automotive regulator mandates ethanol-compatible sensor chemistries for flex-fuel vehicle parc expansion. Maharashtra and Tamil Nadu concentrate two-wheeler lambda sensor production for cost-optimized motorcycle emission compliance.
Japan
METI prioritizes wide-band oxygen sensors for lean-burn combustion strategies in next-generation hybrid powertrains. Kansai region suppliers specialize in silicon MEMS pressure sensors for gasoline particulate filter management. Nagoya-based OEMs absorb 15-20% unit cost increases to meet 2027 model year calibration precision requirements.
Exhaust Sensors Market Vendor Landscape
Listed leaders compete with private specialists across certification bandwidth and ceramic substrate supply security. The vendor base organizes into three tiers: integrated electronics conglomerates with captive foundry networks, European automotive suppliers with backward integration into ceramic materials, and Asia-Pacific specialists in high-temperature thermistor arrays. Consolidation pressure intensifies as Euro 7 and EPA Tier 3 regulations collapse traditional procurement cycles. Dominant competitive moves include strategic partnerships for multi-platform firmware development and geographic expansion to capture aftermarket retrofit volume.
Within the integrated electronics tier, Robert Bosch GmbH exemplifies scale-driven positioning through its foundry network dominance. Continental AG and DENSO Corporation occupy distinct archetype positions: the former anchors European supply through German ceramic substrate manufacturing, while the latter represents Asia-Pacific specialization in heavy-duty diesel applications. These three entities collectively illustrate how regulatory compression favors suppliers with parallel certification tracks across EPA, EMA, and MIIT protocols.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Sensata Technologies |
| ZF Friedrichshafen AG |
| NGK Spark Plug |
| BorgWarner Inc. |
| Faurecia |
| HELLA GmbH & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Bosch's Reutlingen foundry and Continental's ceramic substrate lines in Bavaria shapes price floors across the NOx sensor tier. Scale economies in yttria-stabilized zirconia production concentrate bargaining power with German suppliers, while Chinese module assemblers absorb margin compression through volume offtake commitments.
Pricing Analysis
Next-generation silicon carbide MEMS platforms command 40-60% premiums over incumbent electrochemical architectures, while legacy zirconia lambda probes trade at commodity price points. Three-tier pricing structure across premium calibration-grade, standard diagnostic, and economy retrofit levels stratifies by certification precision and thermal durability ratings. Cost compression in the standard tier intensifies as Indian aftermarket distributors and Polish private-label programs disintermediate OEM captive channels. Fleet operators exhibit lowest price sensitivity due to subscription-based emission monitoring contracts, whereas motorcycle OEMs in Southeast Asia prioritize unit cost minimization over precision specifications.
Supply Chain Analysis
Palladium refining concentration in Russia and South Africa exposes electrode cost structures to geopolitical supply shocks. German and Japanese suppliers dominate yttria-stabilized zirconia ceramic substrate production, while Chinese telematics module integrators in the Yangtze River Delta embed cellular transmitters for GB VI compliance. Single-source vulnerability concentrates in noble metal electrode supply, with 75% of global palladium refining capacity concentrated in two jurisdictions. Distribution runs through captive OEM supply agreements for new-vehicle platforms, shifting toward direct fleet procurement and independent aftermarket channels for replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The exhaust sensors market sits in early-cycle expansion as Euro 7 and EPA Tier 3 regulations force hardware refresh across 40 million commercial vehicle platforms. Hydrogen combustion R&D opens adjacent ammonia slip sensor categories with limited incumbent qualification.
For Market Incumbents: Secure backward integration into ceramic substrate production to defend against German-Japanese supply oligopoly leverage. Lock multi-year palladium supply hedges through offtake agreements with South African refiners. Prioritize firmware certification investment across EPA-EMA-MIIT protocol divergence to prevent platform fragmentation cost multiplication. For New Entrants and Emerging Players: Predictive maintenance analytics under-service by integrated electronics conglomerates creates white-space for specialized fleet software vendors. Target Indian BS VI Phase 2 retrofit segment through ethanol-compatible lambda sensor distribution partnerships with Maharashtra-based distributors. Pursue silicon carbide MEMS qualification with German heavy-duty diesel OEMs as material transition accelerates. For Investors and Strategic Acquirers: Ceramic substrate specialists with captive yttria-stabilized zirconia production represent priority acquisition archetypes for supply security positioning. Frame long-term viability around 5-10 year regulatory compliance hardware refresh cycles rather than single-platform sensor content. Monitor hydrogen combustion prototype announcements from South Korean national laboratories as inflection signal for ammonia slip sensor category formation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Platform Firmware Certification | EMA, EPA, and MIIT protocol alignment reduces variant maintenance costs for module suppliers. |
| Ceramic Substrate Backward Integration | Captive yttria-stabilized zirconia production insulates against German-Japanese supply concentration. |
| Fleet Telematics Partnership | Direct subscription relationships with German commercial operators disintermediate traditional distribution channels. |
| Silicon Carbide MEMS Qualification | Wide-bandgap semiconductor transition decomposes noble metal dependencies in high-temperature oxygen sensing. |
| Indian Aftermarket Distribution Buildout | BS VI Phase 2 retrofit demand in Maharashtra and Tamil Nadu captures 40 million unit replacement opportunity. |
Methodological Framework
Desk research of regulatory filings from EPA, EMA, and MIIT preceded structured interviews with OEM platform engineers, Tier 1 sensor module procurement leads, aftermarket distributors in Poland and India, and fleet telematics operators in Germany. Secondary validation drew from vehicle production databases, customs trade records for ceramic substrate flows, and SEC disclosures from listed automotive suppliers. Bottom-up sensor unit forecasts triangulated against top-down emission compliance hardware spend estimates.
Variance-decomposition across sensor type, vehicle class, and regional regulatory cluster anchored the analytical framework. Modeled dimensions included oxygen/NOx/temperature/pressure sensor architectures, commercial versus passenger vehicle applications, and OEM versus aftermarket versus fleet direct procurement channels. CAGRs derived from unit volume trajectories and content-per-vehicle escalation under Euro 7 and EPA Tier 3 mandates. Hydrogen combustion prototype timelines and palladium price volatility scenarios informed sensitivity bands.
Underlying assumptions cover sustained enforcement of Euro 7 real-driving emission protocols and EPA Tier 3 calibration precision requirements, with deviation risk concentrated in regulatory delay or palladium supply disruption. Forecasts reflect these conditions without claiming predictive certainty. Practitioners should keep alternative scenarios live as hydrogen combustion commercialization timelines and China GB VI telematics verification scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Smart Dust Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market