
 Precision Positioning Equipment Market | 2026-2036
Precision Positioning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Positioning Equipment Market Analysis
Aftermarket service revenue is fragmenting across precision positioning vendors as end-users extend equipment lifecycles rather than replace capital-intensive stages. Trimble Inc. leverages its GNSS calibration infrastructure to capture recurring positioning accuracy contracts in geospatial surveying. Physik Instrumente (PI) anchors its margin structure through proprietary piezoelectric controller firmware that locks in replacement part demand. Hexagon AB competes by integrating metrology software with hardware service tiers, blurring the boundary between product and subscription revenue.
Precision positioning equipment encompasses electromechanical and piezoelectric systems engineered to achieve sub-micron repeatability, typically operating at resolutions below 100 nanometers with closed-loop feedback architectures. These systems translate electrical signals into mechanical displacement for semiconductor lithography, photonics alignment, and automated microscopy workflows. Linear stages and controllers command the dominant share of product-type revenue, reflecting their ubiquity across multi-axis robotic cells and wafer-handling platforms. Piezoelectric technology leads growth velocity in semiconductor and photonics applications where nanometer-scale settling times determine throughput. Electromechanical actuators retain maturity in automotive and general manufacturing end uses where micrometer precision satisfies tolerance requirements at lower cost points.
FDA device manufacturing regulations, ISO 230-2 motion accuracy standards, and EU machinery directives collectively elevate compliance costs for positioning equipment deployed in medical device and semiconductor cleanroom environments. REACH substance restrictions on lead-based piezoelectric ceramics are accelerating material substitution programs among European and Asian component suppliers. Stakeholders must monitor how export control expansions on high-precision motion systems reshape accessible customer bases and qualification pathways for cross-border sales.
Market Dynamics
Semiconductor foundries in Taiwan and South Korea are compressing lithography stage replacement cycles from seven years to four, forcing vendors to engineer modular upgrade paths rather than full-system replacements.
Growth Catalysts
- Sub-7nm Lithography Ramp:Advanced node migration at TSMC and Samsung Foundry demands multi-axis piezoelectric stages with sub-nanometer stability. Equipment vendors are qualifying new ceramic formulations to meet thermal drift specifications.
- EU Green Deal Industrial Emissions Mandate:REACH substance restrictions on lead-based piezoelectric ceramics are accelerating material substitution programs. European component suppliers are retooling production lines toward compliant formulations.
- Photonics Packaging Automation:Silicon photonics module assembly requires active optical alignment with nanometer precision. Contract manufacturers in Germany and Japan are deploying dedicated positioning cells for transceiver production.
Market Restraints
- Raw Material Concentration:High-purity lead zirconate titanate ceramics concentrate among Japanese and Chinese specialty ceramic producers. Supply disruptions at any major furnace operation propagate through controller and stage lead times.
- Export Control Friction:EU dual-use regulations on high-precision motion systems are redirecting supply chains toward qualified domestic producers. Cross-border sales now require extended end-user verification timelines.
- Technical Ceiling at Atomic Scale:Thermal noise and quantum uncertainty impose fundamental limits on open-loop positioning accuracy below 50 picometers. Research applications are hitting this barrier before commercial demand.
Strategic Opportunities
- Quantum Computing Testbeds:Trapped-ion and superconducting qubit systems require cryogenic positioning with picometer stability. National laboratories in the US and Germany are funding prototype stage development.
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor assembly and test are attracting positioning equipment vendors to establish local calibration facilities. Domestic qualification pathways are shortening import dependency.
- AI-Assisted Motion Control:Machine learning algorithms are converging with traditional PID architectures to predict thermal drift and compensate in real time. This hybrid approach is opening retrofit markets for installed base upgrades.
Industry Challenges
- Mechatronics Talent Scarcity:The intersection of precision mechanical design, control theory, and embedded firmware requires specialized expertise. Universities in Germany and Switzerland are the primary training pipelines, creating geographic hiring bottlenecks.
- Cleanroom Certification Timelines:ISO 14644 and SEMI S2 compliance for semiconductor-grade positioning systems extends qualification cycles. Each design iteration requires redundant testing protocols that compress development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Positioning Equipment Market |
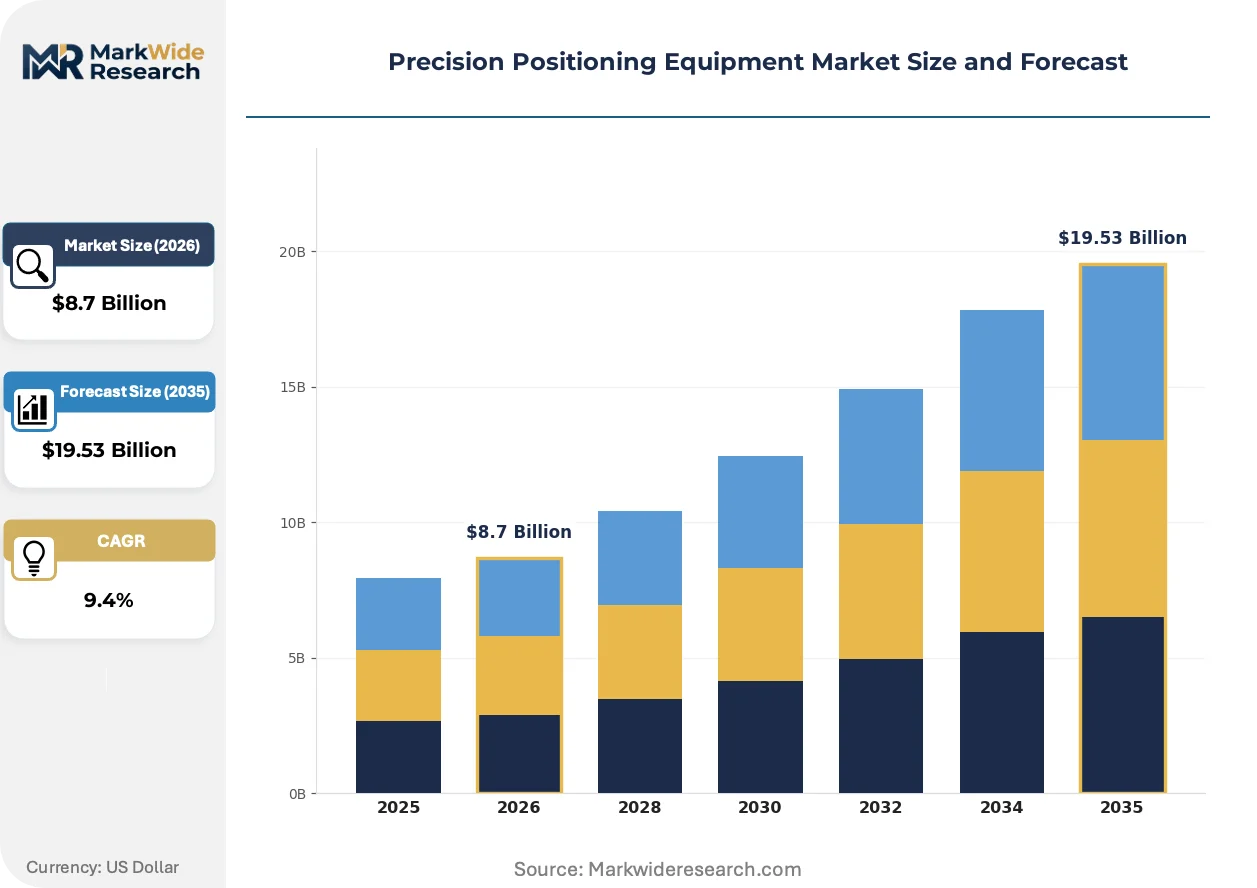
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Stages, Controllers End User: Aerospace, Automotive, Electronics, Manufacturing Technology: Magnetic, Electromechanical, Piezoelectric, Hydraulic Application: Robotics, Semiconductor, Photonics, Laboratory |
| Companies Covered | Trimble Inc., Topcon Corporation, Physik Instrumente (PI), Thorlabs, Inc., Parker Hannifin Corporation, Aerotech, Inc., Hexagon AB, Zaber Technologies Inc., Newport Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Positioning Equipment Market Emerging Trajectories
Digital twin architectures are reshaping how positioning systems are commissioned, diagnosed, and upgraded in the field. Vendors are embedding sensor networks and edge computing to enable predictive maintenance and remote calibration.
Capacitive sensing technology is digitizing closed-loop feedback architectures in semiconductor lithography stages. ASML and Nikon lithography tool divisions are adopting multi-channel capacitive probes for wafer-level alignment. This displacement of traditional laser interferometry is digitizing metrology integration, compressing stage footprints while maintaining sub-nanometer resolution.
REACH substance restrictions on lead-based piezoelectric ceramics are forcing material science investments across European supply chains. ECHA authorization requirements are blocking imports of non-compliant actuators into EU manufacturing facilities. German and French precision ceramics producers are accelerating sodium potassium niobate formulations to maintain market access.
Aftermarket service contracts are unbundling from hardware sales as foundries extend equipment lifecycles. Semiconductor manufacturers in Taiwan and South Korea are negotiating standalone calibration and controller firmware update agreements. This service separation is most visible in East Asian manufacturing corridors where capital expenditure scrutiny has intensified.
Precision Positioning Equipment Market Segmentation
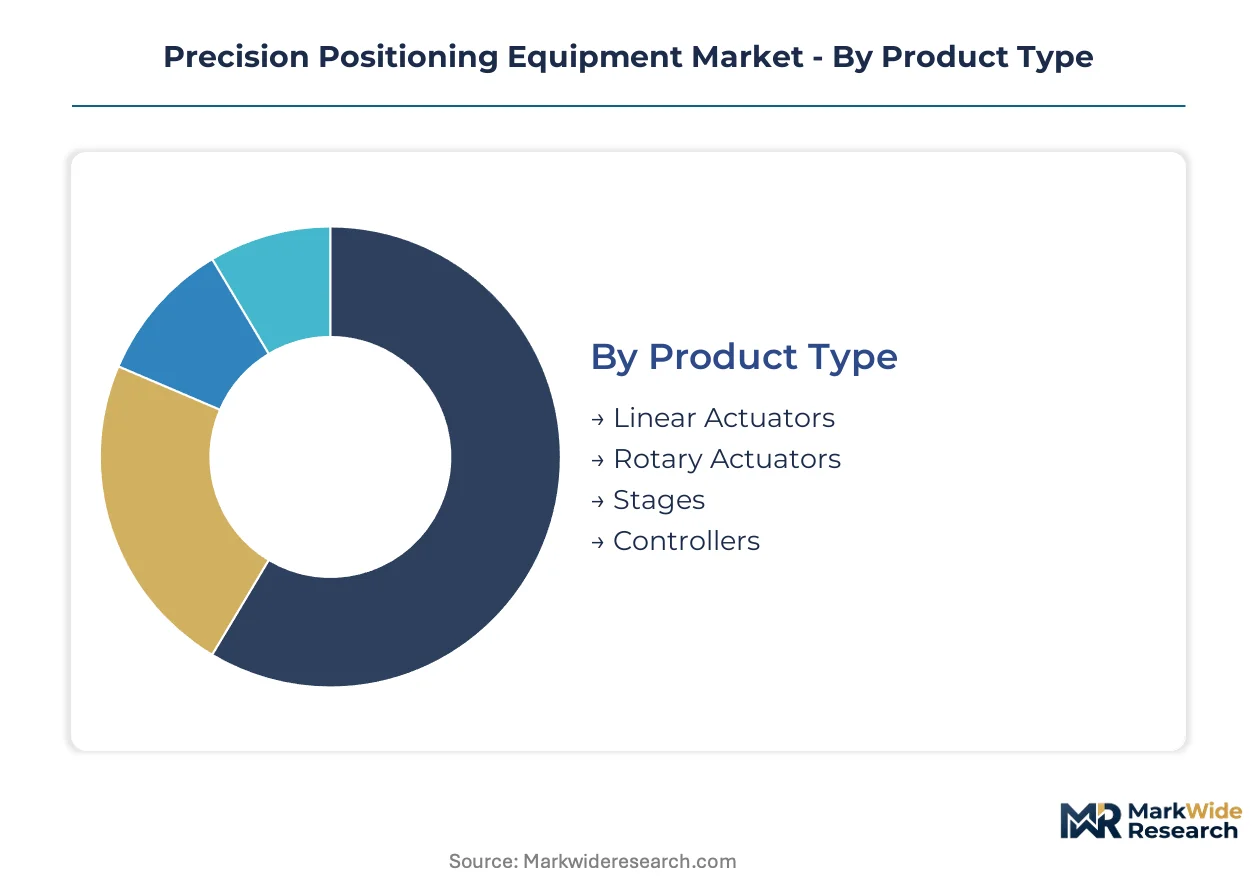
Precision positioning equipment fragments across four structural dimensions that determine procurement priorities and vendor competitive intensity. Product type and technology choices lock in performance ceilings and lifecycle cost structures, while end-user concentration in East Asian electronics corridors and application-specific thermal drift requirements reshape supply chain configurations.
Product Type:
Mature electromechanical platforms coexist with emerging piezoelectric architectures across this category, creating divergent margin profiles and replacement cycle dynamics.
- Linear Actuators:Ball-screw and linear motor configurations deliver micrometer to sub-micron positioning across multi-axis robotic cells. Demand concentrates in German automotive assembly lines where tolerance requirements sit between cost-sensitive and precision-critical thresholds.
- Stages:Multi-axis positioning platforms integrate mechanical bearings, linear motors, or air bearings with closed-loop feedback for lithography and wafer handling. TSMC and Samsung Foundry in Taiwan and South Korea absorb the dominant share of high-precision stage output for sub-7nm node production.
- Rotary Actuators:Direct-drive torque motors and gear-driven systems enable angular positioning for inspection and metrology workflows.
- Controllers:Motion control hardware and firmware architectures manage trajectory generation, servo loops, and error compensation across multi-axis configurations.
Stages retain volume leadership; controllers hold the steepest expansion curve as firmware unbundling accelerates service revenue separation from hardware sales.
End User:
Customer type segmentation tracks capital intensity cycles and cleanroom certification requirements that compress or extend vendor sales timelines.
- Electronics:Semiconductor foundries and contract manufacturers in Taiwan, South Korea, and Germany deploy precision positioning for lithography, inspection, and advanced packaging. Node migration below 7nm is forcing replacement cycle compression from seven years to four.
- Manufacturing:General industrial automation employs electromechanical positioning for assembly, test, and material handling where micrometer precision satisfies tolerance windows at lower cost points than piezoelectric alternatives.
- Aerospace:Satellite component alignment and optical bench stabilization require thermal stability across temperature extremes.
- Automotive:Battery cell assembly and electric drivetrain testing drive demand for mid-precision linear motion in German and Chinese production facilities.
Electronics commands the dominant revenue share; manufacturing offers the broadest installed base for retrofit and upgrade services.
Technology:
Cost tier stratification separates commodity electromechanical solutions from premium piezoelectric platforms where material science investments determine market access.
- Piezoelectric:Lead zirconate titanate and emerging sodium potassium niobate ceramics translate electrical fields into nanometer-scale mechanical displacement. REACH substance restrictions on lead-based formulations are accelerating material substitution programs among European suppliers.
- Electromechanical:Servo motors coupled with ball screws, belt drives, or linear motors dominate automotive and general manufacturing applications where micrometer precision satisfies requirements at lower capital cost.
- Magnetic:Linear and rotary magnetic drives eliminate mechanical contact for contamination-sensitive environments.
- Hydraulic:Fluid power actuation retains niche deployment for high-force positioning in heavy manufacturing contexts.
Electromechanical platforms retain shipment volume leadership; piezoelectric systems are climbing the fastest as semiconductor node advancement demands sub-nanometer stability.
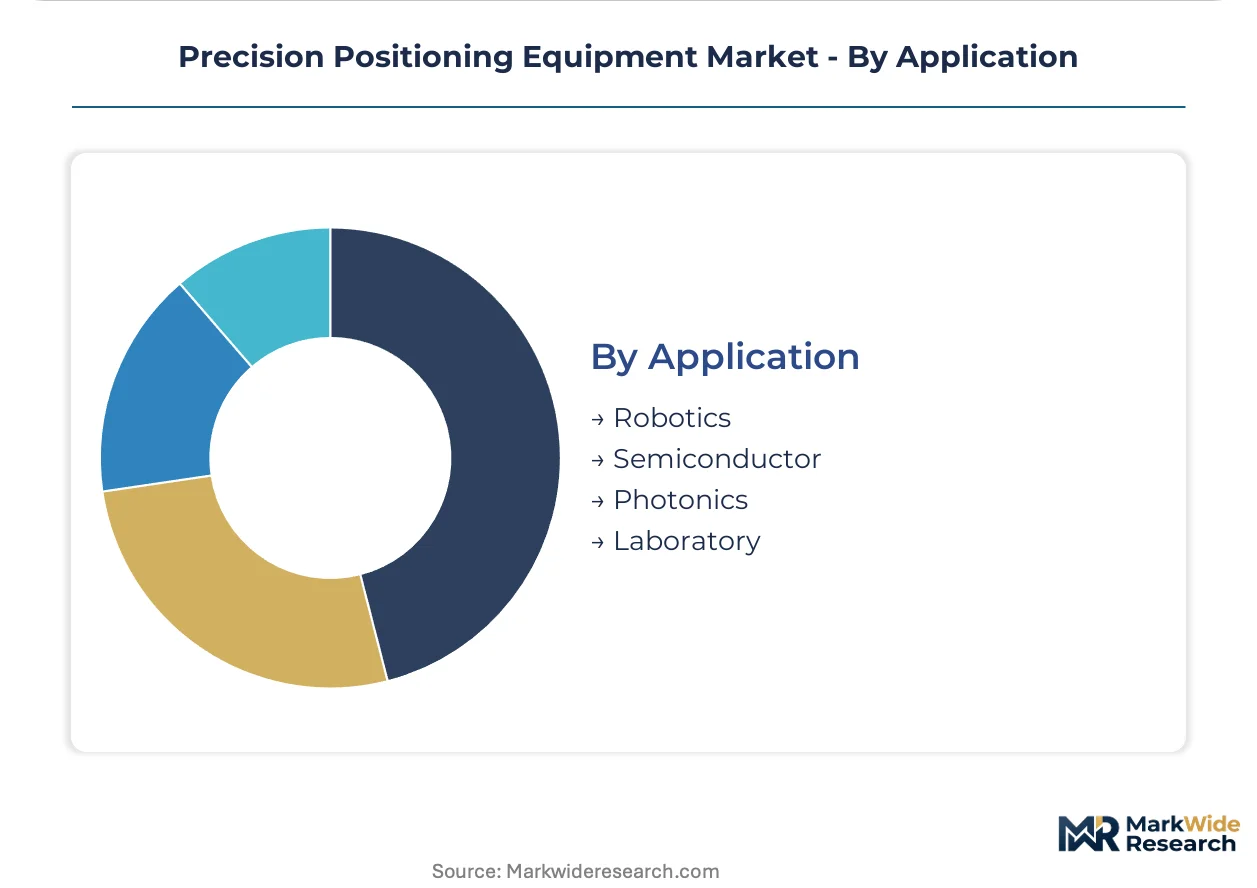
Application:
Geographic clustering of demand varies sharply across application types, with semiconductor and photonics concentrating in East Asian manufacturing corridors while laboratory equipment distributes across German, Swiss, and North American research institutions.
- Semiconductor:Lithography stages, wafer handlers, and inspection systems require closed-loop architectures with sub-nanometer repeatability. Taiwan and South Korea foundries absorb the dominant share of advanced positioning equipment output.
- Photonics:Silicon photonics module assembly demands active optical alignment with nanometer precision for transceiver production. Contract manufacturers in Germany and Japan are deploying dedicated positioning cells.
- Robotics:Multi-axis Cartesian and SCARA configurations integrate linear and rotary positioning for pick-and-place and assembly automation.
- Laboratory:Automated microscopy and sample handling systems require vibration isolation and thermal stability for life sciences research.
Semiconductor applications anchor revenue concentration; photonics is gaining share fastest as data center transceiver volumes accelerate packaging automation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan consumes precision positioning equipment as lithography infrastructure, while Germany deploys identical hardware for photonics packaging—revealing how geography dictates application intensity rather than technology choice.
Taiwan
TSMC and United Microelectronics Corporation operate the densest concentration of sub-7nm lithography stages worldwide. The National Science and Technology Council funds domestic positioning equipment qualification programs to reduce import dependency. Hsinchu Science Park hosts calibration facilities where vendors compress stage replacement cycles from seven years to four.
Germany
Siemens and Bosch drive demand for electromechanical positioning in battery cell assembly and electric drivetrain testing. ECHA REACH restrictions on lead-based piezoelectric ceramics force material substitution toward sodium potassium niobate formulations. Dresden and Jena clusters concentrate photonics packaging cells for silicon photonics transceiver production.
South Korea
Samsung Foundry and SK Hynix absorb multi-axis piezoelectric stages for advanced node migration. MFDS medical device regulations elevate cleanroom certification requirements for positioning equipment deployed in diagnostic imaging manufacturing. Pyeongtaek and Hwaseong industrial corridors host dedicated lithography stage maintenance facilities.
United States
National laboratories fund cryogenic positioning prototypes for trapped-ion quantum computing testbeds. FDA device manufacturing regulations extend qualification timelines for cleanroom-grade positioning systems. Boulder and Albuquerque research clusters concentrate picometer-stability stage development programs.
Japan
METI production-linked incentives attract positioning equipment vendors to establish local calibration facilities for semiconductor assembly. JIS standards govern motion accuracy specifications for industrial automation deployments. Kyoto and Osaka ceramic producers concentrate high-purity lead zirconate titanate furnace operations.
Precision Positioning Equipment Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player tiers: precision specialists commanding sub-nanometer specifications, diversified industrial conglomerates leveraging manufacturing scale, and regional fabricators competing on delivery velocity. Strategic moves cluster toward modular upgrade path engineering and firmware unbundling from hardware sales. M&A activity targets calibration infrastructure and controller firmware assets rather than stage manufacturing capacity.
Among precision specialists, Physik Instrumente (PI) and Aerotech, Inc. exemplify the capability-driven archetype through proprietary controller architectures. Hexagon AB occupies a position spanning metrology software integration with hardware service tiers. These three anchors demonstrate how competitive positioning separates through firmware lock-in and recurring revenue separation from capital equipment sales.
| Leading Market Players |
|---|
| Trimble Inc. |
| Topcon Corporation |
| Physik Instrumente (PI) |
| Thorlabs, Inc. |
| Parker Hannifin Corporation |
| Aerotech, Inc. |
| Hexagon AB |
| Zaber Technologies Inc. |
| Newport Corporation |
| Others |
Supply Flow & Price Mechanics
Kyoto's ceramic furnace concentration shapes downstream pricing power for piezoelectric actuators, as Japanese and Chinese specialty producers command premium terms for high-purity lead zirconate titanate formulations that semiconductor lithography stages require.
Pricing Analysis
Long-term offtake contracts dominate procurement between foundries and stage vendors, with TSMC and Samsung Foundry locking in multi-year agreements for sub-7nm lithography platforms. Three-tier pricing structure across premium, standard, and economy levels separates sub-nanometer piezoelectric systems from micrometer-grade electromechanical alternatives, with ISO 14644 cleanroom certification tiering the premium band. Cost compression in mid-precision electromechanical segments is intensifying because automotive battery assembly lines in Germany and China are standardizing on commodity linear motor configurations. Contract manufacturers in Taiwan exhibit the highest price sensitivity, while national laboratories in the US and Germany show minimal elasticity for cryogenic positioning prototypes.
Supply Chain Analysis
High-purity lead zirconate titanate ceramics draw from Japanese and Chinese specialty furnace operations, with sodium potassium niobate alternatives emerging from German and French retooling programs. Controller firmware architectures rest on embedded processor supply from Taiwan and South Korea, while precision bearing components source from Swiss and German machining clusters. Single-source vulnerability concentrates in Japanese ceramic producers operating legacy furnace assets. Distribution runs through direct vendor-foundry relationships for semiconductor-grade equipment, with regional calibration facilities in Hsinchu, Dresden, and Pyeongtaek shortening service lead times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision positioning equipment sits in early-cycle expansion as sub-7nm lithography migration forces replacement cycle compression from seven years to four, accelerating upgrade revenue separation from new equipment sales.
For Market Incumbents: Pre-empt modular upgrade path engineering to capture extended lifecycle revenue from installed base stages, while accelerating sodium potassium niobate qualification to defend against REACH-driven material substitution threats. Backward integration into controller firmware development locks in recurring calibration contract capture. For New Entrants and Emerging Players: Pursue AI-assisted motion control retrofit opportunities in general manufacturing segments where electromechanical installed base exceeds piezoelectric penetration, targeting German automotive battery assembly facilities with hybrid PID-machine learning controller offerings. Partner with established calibration infrastructure providers to bypass cleanroom certification timeline barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among controller firmware specialists with proprietary piezoelectric driver architectures, positioning these assets for sustained cash flow quality across the next decade. Acquisition focus should center on calibration facility networks in East Asian manufacturing corridors. Watch for ECHA authorization timeline acceleration as an inflection signal for material substitution investment urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Upgrade Path Engineering | TSMC and Samsung Foundry replacement cycle compression creates captive upgrade revenue streams. |
| Material Substitution Program | Sodium potassium niobate qualification defends EU market access against REACH lead restrictions. |
| AI-Assisted Motion Control Development | Hybrid PID-ML architectures open retrofit markets in German automotive battery assembly. |
| Calibration Infrastructure Expansion | Hsinchu and Pyeongtaek facilities shorten service lead times for East Asian foundry clusters. |
| Controller Firmware Unbundling | Standalone firmware update agreements separate recurring revenue from hardware sales cycles. |
Methodological Framework
The analysis maps piezoelectric stage architectures, electromechanical platforms, controller firmware tiers, and calibration service networks, each validated through precision equipment procurement directors, cleanroom facility managers, and aftermarket service heads. Primary interviews with semiconductor foundry engineers, photonics packaging specialists, and national laboratory researchers combined with secondary validation against SEMI industry filings, ECHA substance restriction databases, and ISO motion accuracy standards. Bottom-up shipment data triangulated against top-down capital expenditure disclosures from TSMC, Samsung Foundry, and Intel.
Assumptions held fixed include REACH substance restriction timelines and EU dual-use export control scope, while semiconductor node migration pace and AI-assisted control adoption rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, technology tier, end-user industry, application workflow, and geographic manufacturing cluster. CAGRs derived from equipment replacement cycle dynamics and foundry capacity expansion announcements, with thermal drift specification tightening and cleanroom certification timeline compression as industry-specific forecast inputs.
Sensitivities concentrate around ECHA authorization acceleration, Japanese ceramic supply disruptions, and quantum computing testbed funding volatility. Forecasts reflect documented assumptions on lithography stage demand elasticity and material substitution cost curves. Cross-checking against SEMI capital equipment shipment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Glass Washer Market
Industrial Equipment
Digital Tube Roller Market
Industrial Equipment
COG Bonder Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Asia Pacific Industrial Embedded Systems Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Precision Machine Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Long-Range Acoustic Device Market
Industrial Equipment
Battery Spot Welder Market