
 Photoelectric Sensor Market | 2026-2036
Photoelectric Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Photoelectric Sensor Market Analysis
A capital-intensity divergence between players is bifurcating the competitive landscape. Pepperl+Fuchs leverages deep vertical integration in intrinsic safety barriers to dominate hazardous-environment applications. Keyence Corporation sustains premium positioning through direct sales channels and rapid custom sensor turnaround. SICK AG anchors its European installed base with comprehensive machine-vision-to-sensor integration.
Photoelectric sensors detect object presence, absence, or distance by emitting modulated light and measuring reflected or interrupted beam intensity, typically operating at response times under one millisecond for high-speed manufacturing lines. Their primary purpose is non-contact position and object verification across automated production, material handling, and quality control systems. Laser technology leads in precision measurement segments where micron-level accuracy commands price premiums, while infrared variants capture volume in general factory automation due to ambient-light immunity. Industrial automation applications absorb the dominant share of unit demand, though safety-system deployments are expanding fastest as functional-safety certifications become mandatory on new machinery.
FDA oversight of manufacturing equipment in pharmaceutical and food processing environments shapes sensor material and washdown-rating requirements. The EU Machinery Directive and CE marking framework mandate documented reliability for safety-critical sensor installations, creating compliance-driven replacement cycles. OSHA machine-guarding standards in the United States pressure facilities to upgrade legacy mechanical interlocks to electronic presence-sensing devices. Stakeholders must weigh certification investment against the margin compression from unbranded Asian suppliers penetrating standard-factory-automation tiers.
Market Dynamics
Factory digitization is compressing sensor replacement cycles as automotive OEMs mandate real-time position feedback for adaptive manufacturing lines. The shift from mechanical limit switches to photoelectric detection is restructuring component sourcing priorities across Tier-1 suppliers.
Growth Catalysts
- EU Machinery Directive:CE marking requirements for safety-rated sensors are forcing machinery OEMs to upgrade legacy installations, creating certified-product demand across German and Italian automation corridors.
- Laser triangulation:Micron-level distance measurement is penetrating battery cell assembly lines where electrode alignment tolerances now require sub-millimeter verification.
- OSHA machine-guarding enforcement:US facilities face citation pressure to replace mechanical interlocks with electronic presence-sensing devices on press brakes and robotic cells.
Market Restraints
- Optoelectronic component concentration:Laser diode supply chains cluster in East Asian foundries, exposing European sensor assemblers to single-source vulnerability.
- Inductive proximity substitution:Weld-slag environments in heavy fabrication favor magnetic sensors over photoelectric units, capping penetration in steel processing.
- REACH substance restrictions:RoHS compliance costs for lead-free solder and restricted coatings compress margins on standard-factory-automation sensor tiers.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are drawing sensor module assembly to Gujarat and Tamil Nadu industrial zones.
- Time-of-flight convergence:3D vision integration with photoelectric arrays is opening bin-picking and cobot guidance applications in logistics automation.
- Direct-to-machine-builder channels:Bypassing distributor markup through embedded sensor specification in CAD libraries is capturing margin in mid-volume automation.
Industry Challenges
- Functional safety certification timelines:TÜV and UL approval cycles for SIL-rated sensors extend eighteen to twenty-four months, delaying new product revenue.
- Optical calibration expertise:Field service teams lack laser alignment training for precision measurement installations, forcing vendor-dependent maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoelectric Sensor Market |
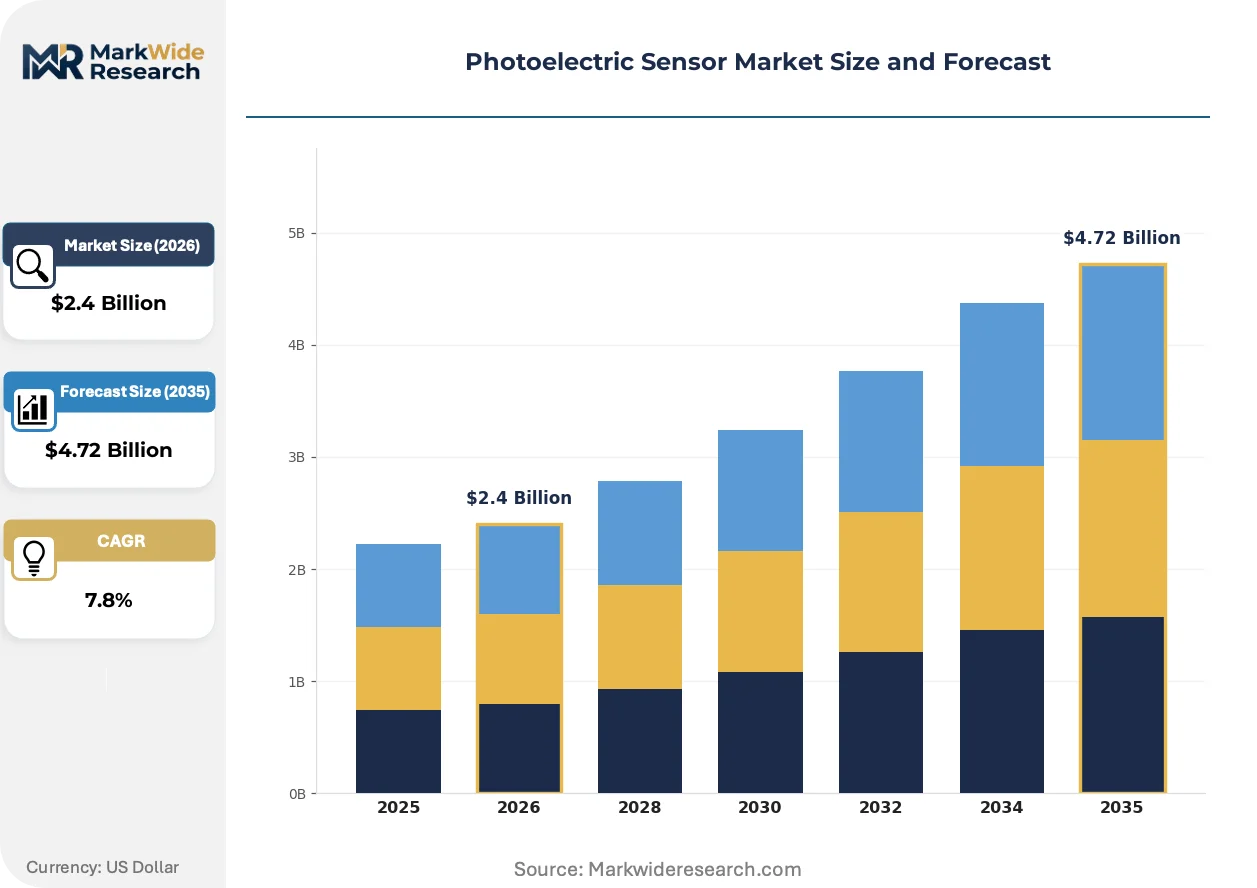
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Active, Passive, Proximity, Retroreflex Technology: Laser, Infrared, Visible Light, Ultraviolet Application: Industrial Automation, Safety Systems, Consumer Electronics, Packaging End User: Manufacturing, Automotive, Healthcare, Food & Beverage |
| Companies Covered | Pepperl+Fuchs, Rockwell Automation Inc., SICK AG, Banner Engineering Corp, Schneider Electric SE, Keyence Corporation, Autonics Corporation, Panasonic Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoelectric Sensor Market Emerging Trajectories
Photoelectric sensing is fragmenting into application-specific variants as end-users reject one-size-fits-all specifications. The convergence of optical hardware with embedded processing is enabling edge-level decision making without controller dependency.
Time-of-flight photoelectric sensors are supplanting ultrasonic distance measurement in high-bay warehouse applications where dust and temperature gradients degrade acoustic performance. Amazon and Alibaba fulfillment centers are specifying TOF units for pallet dimensioning at conveyor speeds exceeding two meters per second. The technology is compressing ultrasonic sensor share in logistics automation while opening new volume in outdoor yard management systems.
REACH substance restrictions on cadmium and lead in optical coatings are forcing reformulation of emitter housings and lens assemblies. Sensor manufacturers must requalify washdown-rated products for food-contact environments under EFSA migration limits. German packaging machinery builders are absorbing these compliance costs fastest, while Southern European OEMs lag in supply chain requalification.
Machine builders now embed photoelectric sensor CAD models directly into digital twin libraries, bypassing traditional distributor specification channels. This specification-capture model is displacing component distributor influence in automotive body-in-white projects. The shift is most visible in Stuttgart and Wolfsburg industrial clusters, where Siemens and Bosch automation teams pre-validate sensor performance in virtual commissioning environments.
Photoelectric Sensor Market Segmentation
Photoelectric sensor procurement channels diverge sharply by segment. Industrial buyers source through machine-builder CAD libraries, while safety-rated variants flow through certified systems integrators. Component distributors retain grip on replacement volumes in legacy factory floors.
Type:
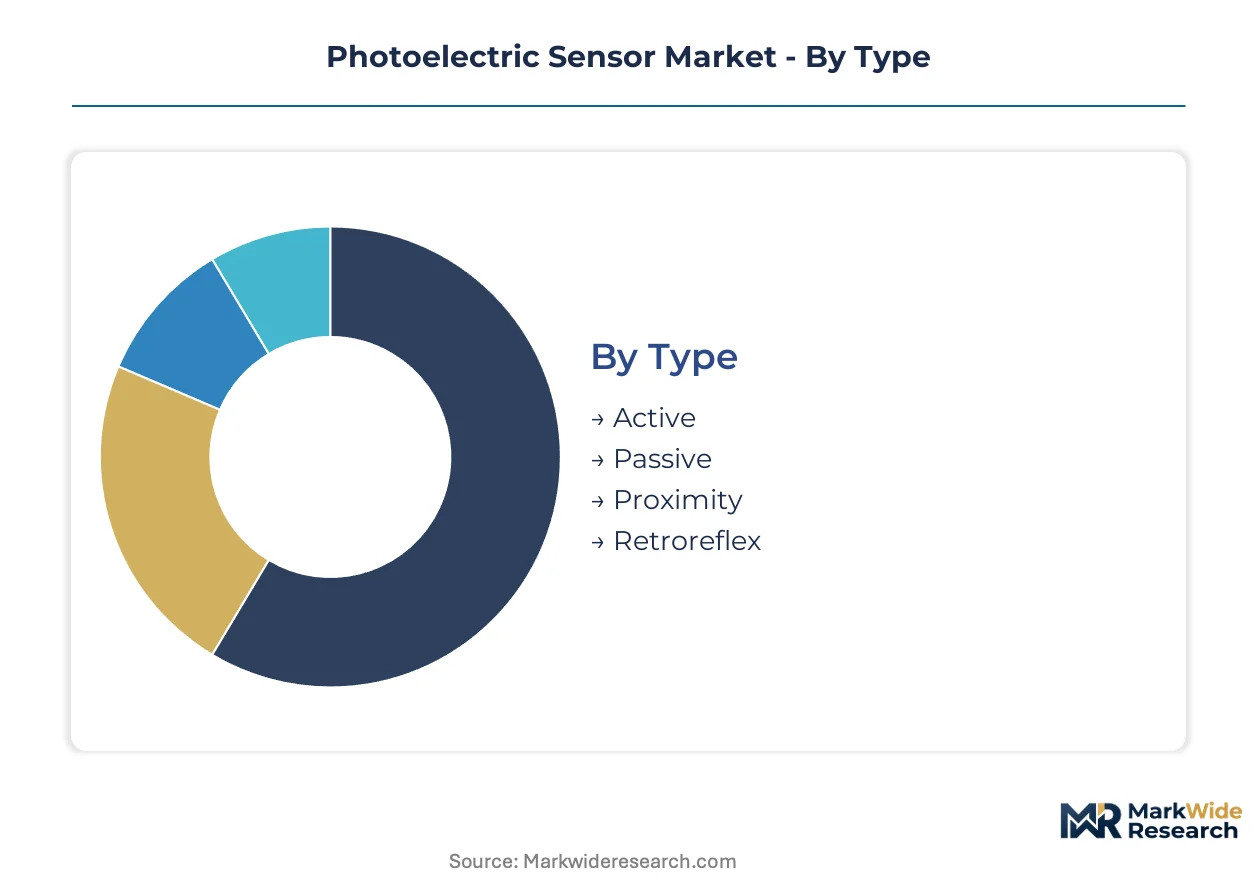
Active sensors move through direct OEM specification channels. Passive variants circulate through maintenance-repair-operations distributors. Proximity and retroflex units split between system integrators and catalog distributors based on application complexity.
- Active:Emit modulated light beams with integrated amplifiers for long-range detection. Demand concentrates in German automotive body-in-white lines where weld-spark immunity and millisecond response times are mandatory for adaptive manufacturing cells.
- Passive:Rely on ambient light detection without dedicated emitters, reducing component count. Italian packaging machinery builders specify these for cost-sensitive carton-feeding applications where controlled lighting environments eliminate active-emitter premiums.
- Proximity:Detect objects within fixed sensing windows through diffuse reflection principles. Food processing lines in Spain deploy these for conveyor bottle counting under EFSA washdown compliance.
- Retroreflex:Use corner-cube reflectors to return emitted beams for reliable medium-range detection. Logistics automation in Netherlands distribution centers favors these for pallet presence verification across temperature-variable warehouse zones.
By volume, retroreflex leads in factory automation deployments. By growth pace, active variants are expanding most quickly through Industry 4.0 retrofit programs.
Technology:
Cost tiers separate these technologies. Laser commands premium pricing for precision measurement. Infrared captures mid-market factory automation. Visible light and ultraviolet occupy specialized niches with distinct margin profiles.
- Laser:Delivers micron-level distance resolution through time-of-flight or triangulation principles. Battery cell assembly in South Korea demands these for electrode alignment verification where sub-millimeter tolerances prevent thermal runaway risks.
- Infrared:Operates at 850-950nm wavelengths with superior ambient-light rejection. General manufacturing across Poland and Czech Republic absorbs these for conveyor line object detection in uncontrolled lighting conditions.
- Visible Light:Employs red or green LED emitters for alignment visibility and color-contrast sensing. Pharmaceutical packaging in Ireland uses these for tablet blister verification where operator visual confirmation aids setup.
- Ultraviolet:Excites fluorescent materials for specialized mark and code detection. Security printing applications in Switzerland specify these for currency authentication and high-value document verification.
Laser technology commands the highest unit margins. Infrared variants show the steepest volume expansion as standard factory automation penetrates Eastern European manufacturing corridors.
Application:
Application segments map to distinct customer maturity levels. Industrial automation buyers specify sensors in digital twin environments. Safety systems procurement requires certified vendor relationships. Consumer electronics and packaging serve volume markets with compressed lead times.
- Industrial Automation:Encompasses position feedback, object detection, and quality verification across production lines. German machine builders integrate these directly into TIA Portal and TwinCAT engineering environments, bypassing traditional distributor specification.
- Safety Systems:Mandates SIL-rated and PL-certified variants for personnel protection applications. French press brake manufacturers face ANSII enforcement pressure to replace mechanical interlocks with electronic presence-sensing devices.
- Consumer Electronics:Absorbs miniature photoelectric arrays for gesture recognition and ambient light adjustment. Assembly plants in Hungary supply these for smartphone and tablet manufacturing under CE marking requirements.
- Packaging:Deploys sensors for fill-level detection, label verification, and carton presence. Italian OEMs lead in integrating these into continuous-motion form-fill-seal machinery for food and pharmaceutical clients.
Industrial automation generates the largest revenue base. Safety systems are climbing the fastest as Machinery Directive compliance deadlines approach across EU member states.
End User:
End-user concentration determines channel strategy. Automotive and manufacturing favor direct specification relationships. Healthcare and food processing require regulatory-compliant supply chains with documented material certifications.
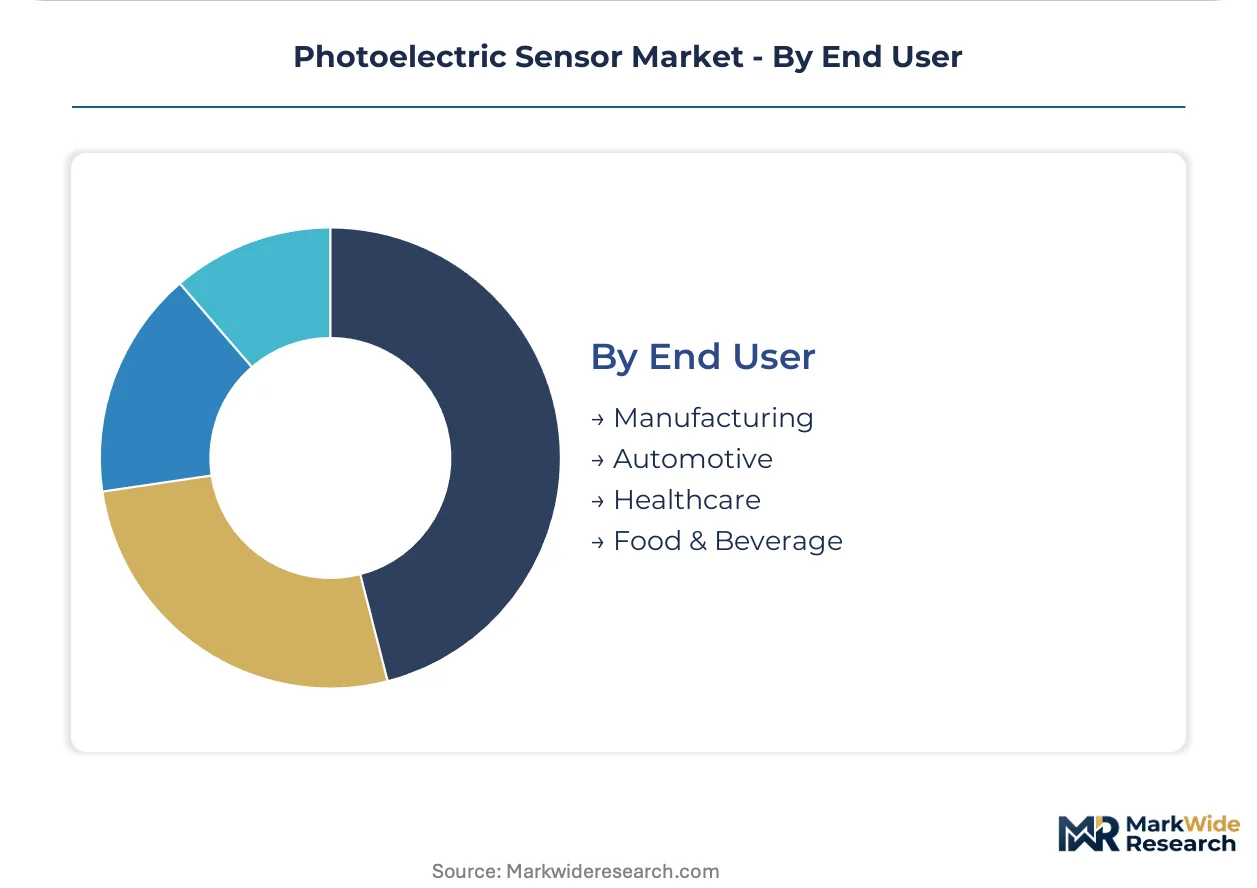
- Manufacturing:Spans discrete and process industries with broad sensor deployment. Czech automotive suppliers specify photoelectric arrays for robotic cell interlocking and adaptive conveyor routing.
- Automotive:Demands the highest reliability grades for body-in-white, paint shop, and powertrain applications. Stuttgart and Wolfsburg industrial clusters specify sensors validated through virtual commissioning before physical installation.
- Healthcare:Requires FDA and MDR-compliant materials for equipment manufacturing. German diagnostic device makers specify washdown-rated sensors for automated sample handling systems.
- Food & Beverage:Mandates EFSA-compliant materials and IP69K ratings for hygienic design. Dutch dairy processing lines specify stainless-steel housings with crevice-free construction for CIP/SIP compatibility.
Manufacturing absorbs the greatest unit volumes. Healthcare represents the most rapid expansion trajectory as medical device automation accelerates under MDR quality system requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's automotive belt show minimal price elasticity for certified safety-rated sensors, while packaging machinery OEMs in Southern Europe prioritize cost containment over certification premiums. This demand-elasticity contrast shapes regional procurement patterns across the forecast window.
Germany
Machine builders in Stuttgart and Wolfsburg specify SIL-rated photoelectric arrays for body-in-white automation, absorbing premium pricing for TÜV-certified variants. The EU Machinery Directive and CE marking framework mandate documented reliability for safety-critical installations. Bavarian packaging OEMs integrate sensors directly into digital twin libraries, bypassing traditional distributor channels.
United States
Automotive OEMs in Michigan and Ohio mandate real-time position feedback for adaptive manufacturing lines, compressing replacement cycles. OSHA machine-guarding enforcement pressures facilities to upgrade mechanical interlocks to electronic presence-sensing devices. Detroit-area Tier-1 suppliers specify photoelectric detection for robotic cell interlocking.
China
Battery cell assembly lines in the Yangtze River Delta demand laser triangulation sensors for electrode alignment verification at sub-millimeter tolerances. MIIT industrial automation standards accelerate factory digitization mandates. Shenzhen electronics assemblers specify miniature photoelectric arrays for consumer device manufacturing.
South Korea
Semiconductor and display manufacturing in Gyeonggi Province absorbs infrared variants for ambient-light-immune conveyor detection. KOSHA occupational safety regulations drive press brake modernization with electronic guarding. Busan-Ulsan industrial clusters specify high-reliability sensing for shipbuilding automation.
India
Automotive suppliers in Tamil Nadu and Gujarat deploy photoelectric sensors for robotic cell integration under PLI scheme manufacturing incentives. BIS certification requirements shape sensor material specifications for domestic assembly. Pune industrial corridors absorb standard-factory-automation tiers from unbranded Asian suppliers.
Photoelectric Sensor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with differentiation anchored in certification depth and channel control. The upper tier commands pricing power through captive safety technology and direct machine-builder relationships. Mid-scale specialists compete on application-specific customization and regional service density. Dominant competitive moves include backward integration into emitter component supply and embedded specification through CAD library partnerships.
Within the integrated safety tier, Pepperl+Fuchs and SICK AG exemplify archetypes leveraging hazardous-environment certification and European installed-base anchoring respectively. Keyence Corporation occupies a position representing premium direct-sales positioning with rapid custom turnaround capabilities. These three entities collectively illustrate how certification investment, channel architecture, and vertical control over critical subsystems separate pricing power from margin compression.
| Leading Market Players |
|---|
| Pepperl+Fuchs |
| Rockwell Automation Inc. |
| SICK AG |
| Banner Engineering Corp |
| Schneider Electric SE |
| Keyence Corporation |
| Autonics Corporation |
| Panasonic Corporation |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
CE marking requirements under the EU Machinery Directive simultaneously gate supplier qualification and stratify price tiers, forcing unbranded Asian assemblers to absorb certification costs or retreat to non-safety applications. This regulatory threshold bifurcates the market into certified-premium and uncertified-economy bands with minimal overlap in buyer procurement patterns.
Pricing Analysis
After-sales service contracts and field calibration subscriptions now generate lifetime value exceeding original hardware margins for integrated vendors. Three-tier pricing structure across premium, standard, and economy levels separates TÜV-certified safety arrays from general-factory infrared units and unbranded proximity sensors. Cost compression in standard tiers intensifies because unbranded Asian suppliers flood Eastern European replacement channels. Automotive OEMs in Stuttgart and Wolfsburg show minimal price sensitivity for SIL-rated variants, while Italian packaging machinery builders prioritize acquisition cost over certification premiums.
Supply Chain Analysis
Inbound logistics costs from East Asian ports through Rotterdam and Hamburg have compressed assembler margins as container availability fluctuates on Asia-Europe trade lanes. Laser diode foundries cluster in Taiwan, Japan, and South Korea, drawing European sensor houses into single-source dependencies for precision emitters. Supply chains rest on gallium arsenide substrates, molded polycarbonate lenses, and lead-free solder alloys vulnerable to REACH substance restrictions. Tariff exposure on optoelectronic components threatens cost structures for German machine builders. Distribution runs through machine-builder CAD library partnerships, certified systems integrators, and maintenance-repair-operations catalog channels in descending margin order.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor vendors must recalibrate toward service-attach revenue as calibration subscriptions and predictive maintenance contracts expand faster than hardware unit growth. Recurring revenue layers now determine enterprise valuation multiples more than production volume.
For Market Incumbents: Compound defensive moats by embedding sensor specifications directly into Siemens TIA Portal and Beckhoff TwinCAT engineering libraries, capturing specification lock-in before distributor involvement. Deepen backward integration into laser diode supply through foundry partnerships in Taiwan and Japan, reducing single-source vulnerability. Prioritize SIL certification investment over price competition with unbranded Asian suppliers penetrating Czech and Polish replacement markets.
For New Entrants and Emerging Players: Differentiate on rapid custom turnaround for battery cell assembly applications where electrode alignment tolerances require application-specific laser triangulation variants. Target India's Tamil Nadu and Gujarat industrial corridors under PLI scheme incentives, where domestic assembly requirements create procurement preference for local sensor module production. Pursue direct-to-machine-builder channels through embedded CAD library partnerships rather than distributor markup capture.
For Investors and Strategic Acquirers: EU Machinery Directive compliance deadlines reshaping the acquisition landscape favor targets with TÜV-certified product portfolios and established automotive OEM relationships. Five-to-ten year viability hinges on regulatory certification depth rather than manufacturing scale alone. Monitor BIS certification progress in India as an inflection indicator for production-linked incentive capture and domestic market access.
| Strategic Initiative | Industry Significance |
|---|---|
| CAD Library Partnership | Embedded specification in Siemens and Beckhoff engineering environments captures procurement influence before distributor involvement. |
| Backward Integration | Foundry partnerships in Taiwan and Japan reduce laser diode single-source exposure for precision measurement tiers. |
| SIL Certification Investment | TÜV approval cycles for safety-rated variants create eighteen-to-twenty-four month competitive moats against unbranded entrants. |
| Service Contract Expansion | Field calibration and predictive maintenance subscriptions generate recurring revenue exceeding original hardware margins. |
| PLI Scheme Localization | Tamil Nadu and Gujarat assembly operations under Indian production-linked incentives capture domestic procurement preference. |
Methodological Framework
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and machine-builder specification leads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across German automotive clusters, Dutch logistics automation centers, and Indian PLI scheme manufacturing zones with secondary validation from EU Machinery Directive compliance databases, OSHA enforcement records, BIS certification filings, and SEC 10-K disclosures from listed sensor vendors. Bottom-up unit demand modeling triangulated against top-down industrial automation capex forecasts.
Sensitivity analysis tested forecast robustness across alternative regulatory enforcement scenarios and supply chain disruption assumptions. The analytical framework segmented demand by sensor type, technology wavelength, application vertical, and end-user industry across the projection horizon. CAGRs derived from regression analysis against industrial production indices, automotive output forecasts, and battery cell manufacturing capacity expansion plans. Time-of-flight adoption curves and safety-system replacement cycles served as industry-specific demand drivers.
Material uncertainties — tariff escalation on optoelectronic components, REACH substance restriction expansion, and single-source laser diode supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and supply chain continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Thermistor Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Area Sensor Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
North America Water Detection Sensors Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Electro-Pneumatic Transducers Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Temperature Monitoring System Market