
 Millimeter Wave Sensors and Modules Market | 2026-2036
Millimeter Wave Sensors and Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Millimeter Wave Sensors and Modules Market Intelligence
The shift toward integrated Antenna-in-Package (AiP) modules is recalibrating buyer preferences away from discrete components, simplifying design for OEMs. Infineon Technologies AG specializes in radar solutions for advanced driver-assistance systems. NXP Semiconductors N.V. leverages its extensive RF portfolio to compete across multiple end-user segments. Texas Instruments sustains its position through large-scale production of cost-optimized CMOS-based sensors.
Millimeter wave sensors and modules are electronic devices that operate in the 30 GHz to 300 GHz frequency spectrum. They function by transmitting short-wavelength electromagnetic waves to detect objects, measure distance, and determine velocity with high precision. Within applications, automotive safety systems represent the most significant area of development, particularly for in-cabin monitoring and collision avoidance. The technology landscape shows a clear migration towards CMOS for cost-sensitive applications and GaN for high-power communication modules.
Spectrum allocation and device certification are governed by national and regional bodies. The US Federal Communications Commission (FCC) and the European Telecommunications Standards Institute (ETSI) set critical standards for frequency use in the 60 GHz and 77 GHz bands. These regulations directly influence product design and market access for manufacturers. The key strategic decision for component suppliers involves balancing investment between maturing CMOS platforms and emerging GaN technologies to meet diverse performance and cost targets.
Market Dynamics
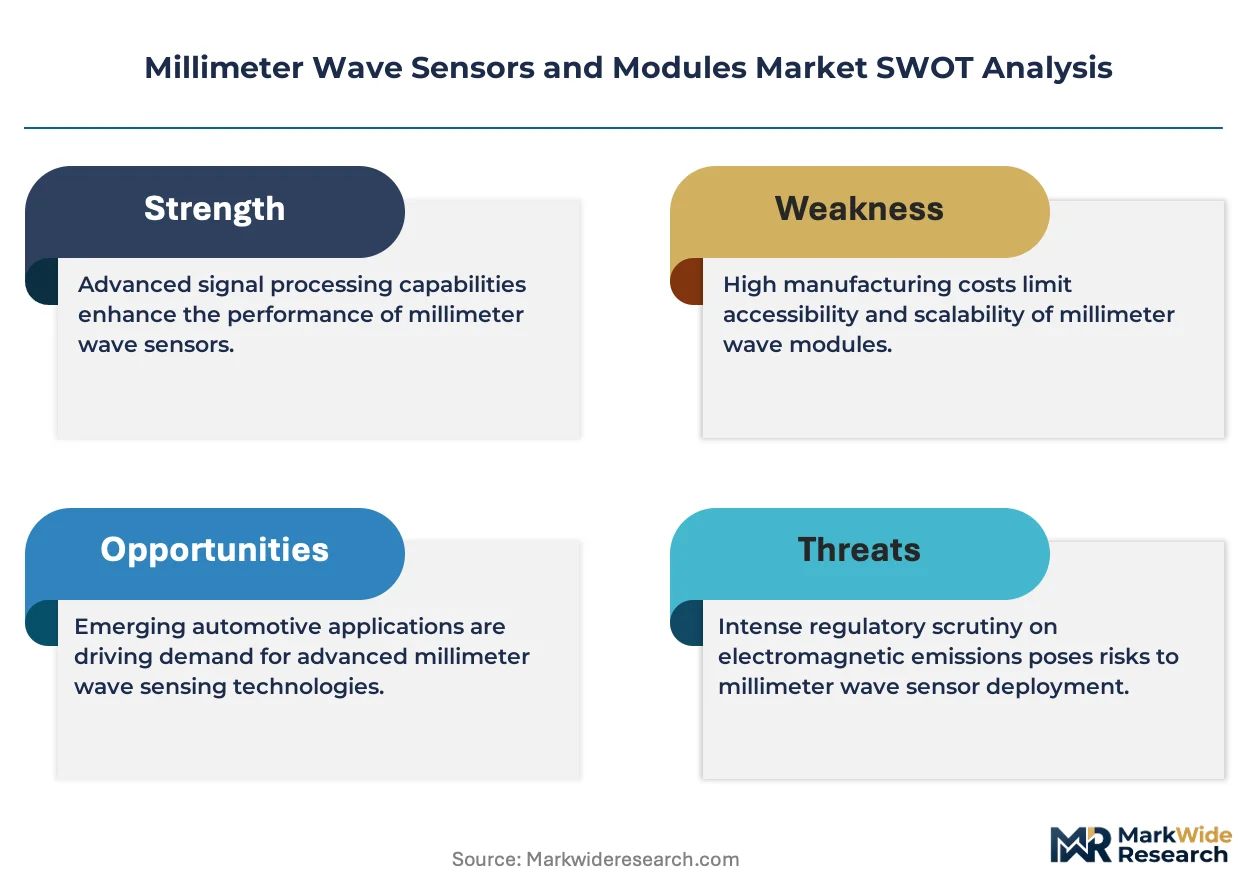
The central structural force shaping the market is the shift from discrete components to highly integrated Antenna-in-Package modules. This integration simplifies OEM design cycles and accelerates adoption in cost-sensitive, high-volume automotive and consumer electronics applications.
Growth Catalysts
- 5G Infrastructure Expansion:The global deployment of 5G networks necessitates high-frequency backhaul and fronthaul communication links, creating sustained demand for mmWave modules in telecommunications infrastructure.
- Automotive Safety Mandates:Regulations from bodies like Germany's KBA and the US NHTSA promoting advanced driver-assistance systems (ADAS) directly stimulate demand for 77 GHz radar sensors for collision avoidance.
- Industrial Automation:The adoption of Industry 4.0 principles is expanding the use of mmWave sensors for high-precision robotics, machine monitoring, and factory logistics, where reliable object detection is critical.
Market Restraints
- Material Cost Structure:The high cost of Gallium Nitride (GaN) substrates compared to silicon (CMOS) presents a significant barrier to adoption in price-sensitive consumer applications, limiting its use to high-performance segments.
- Signal Propagation Limits:Millimeter waves suffer from high atmospheric attenuation and are easily blocked by obstacles, limiting their effective range and reliability in non-line-of-sight scenarios without complex compensation techniques.
- Spectrum Fragmentation:Divergent spectrum allocation policies between regions, such as those managed by the FCC in the US and ETSI in Europe, create design complexity and increase certification costs for global manufacturers.
Strategic Opportunities
- In-Cabin Sensing Systems:The development of 60 GHz radar for automotive in-cabin monitoring offers a new application frontier for detecting child presence, driver drowsiness, and occupant biometrics for enhanced safety.
- AI and Sensor Fusion:Integrating mmWave sensor data with machine learning algorithms enables superior object classification and environmental mapping, creating opportunities for more intelligent and autonomous systems in various end-uses.
- Industrial IoT in Emerging Economies:Underpenetrated industrial sectors in India and Brazil present an opportunity for deploying mmWave sensors for process control and asset tracking as smart factory initiatives gain government support.
Industry Challenges
- RF Engineering Talent Scarcity:The design and integration of high-frequency mmWave systems require specialized radio frequency engineering skills, and a shortage of qualified talent constrains product development capacity across the industry.
- Thermal Management Complexity:The high power density and operational frequencies of compact GaN and AiP modules generate significant heat, demanding sophisticated thermal management solutions that add to design complexity and cost.
- Standardization and Interoperability:A lack of universal standards for communication protocols and data formats between different vendors' modules hinders interoperability, slowing large-scale deployment in multi-vendor environments like smart cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Millimeter Wave Sensors and Modules Market |
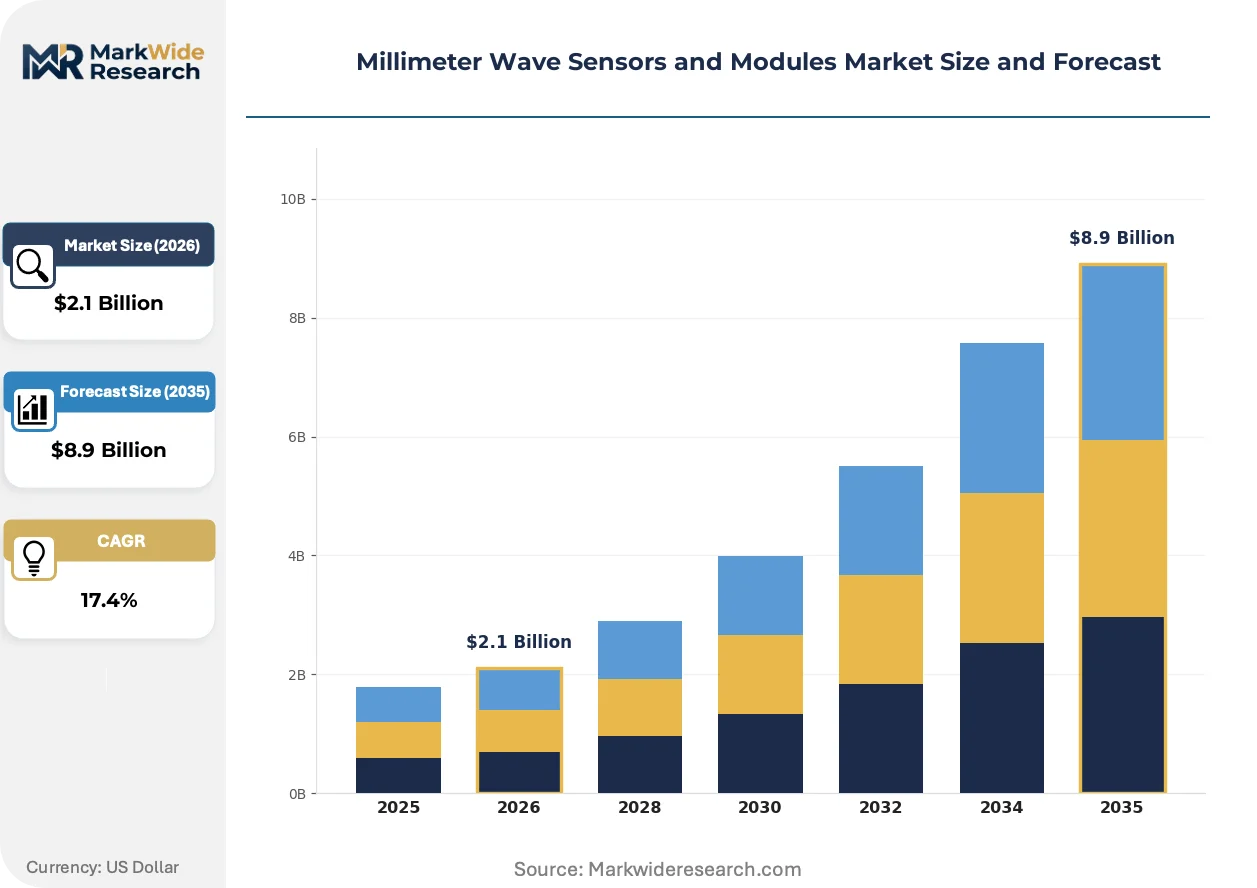
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.9 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radars, Imaging Sensors, Communication Modules, Transmitters Application: Traffic Monitoring, Security Surveillance, Industrial Automation, Automotive Safety End User: Aerospace, Defense, Healthcare, Telecommunications Technology: Solid State, Hybrid, CMOS, GaN |
| Companies Covered | Infineon Technologies AG, Qualcomm Technologies, Inc., NXP Semiconductors N.V., Texas Instruments, Keysight Technologies, Aviat Networks, Inc., NEC Corporation, Ceragon Networks Ltd., Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Millimeter Wave Sensors and Modules Market Strategic Shifts & Innovations
The market's evolution is defined by a technological push towards silicon-based integration and cost reduction. This transition enables the expansion of mmWave technology from specialized, high-performance niches into mainstream automotive and consumer applications, fundamentally altering the competitive landscape.
CMOS-based sensor technology provides a pathway to cost-effective, large-scale production through established semiconductor fabrication processes. Automotive and consumer electronics OEMs are rapidly adopting these silicon solutions to manage system costs. This highly integrated, silicon-based approach is overtaking discrete Gallium Arsenide (GaAs) components in high-volume, cost-sensitive applications where performance-per-dollar is the primary metric.
Harmonization efforts by regulators such as the US Federal Communications Commission (FCC) and the European Telecommunications Standards Institute (ETSI) are standardizing the 77 GHz frequency band for automotive radar applications. This regulatory alignment simplifies product development and reduces market access friction for component suppliers. The automotive sector is most affected, as suppliers can now develop single radar platforms for deployment across multiple key geographic markets.
A clear preference shift among original equipment manufacturers toward fully integrated Antenna-in-Package (AiP) modules is apparent. This move away from the procurement of discrete components simplifies the RF design-in process and accelerates development timelines for end-product manufacturers. The trend is most pronounced within the advanced driver-assistance systems ecosystem in Germany and in the high-volume consumer electronics supply chains centered in South Korea.
Millimeter Wave Sensors and Modules Market Segmentation
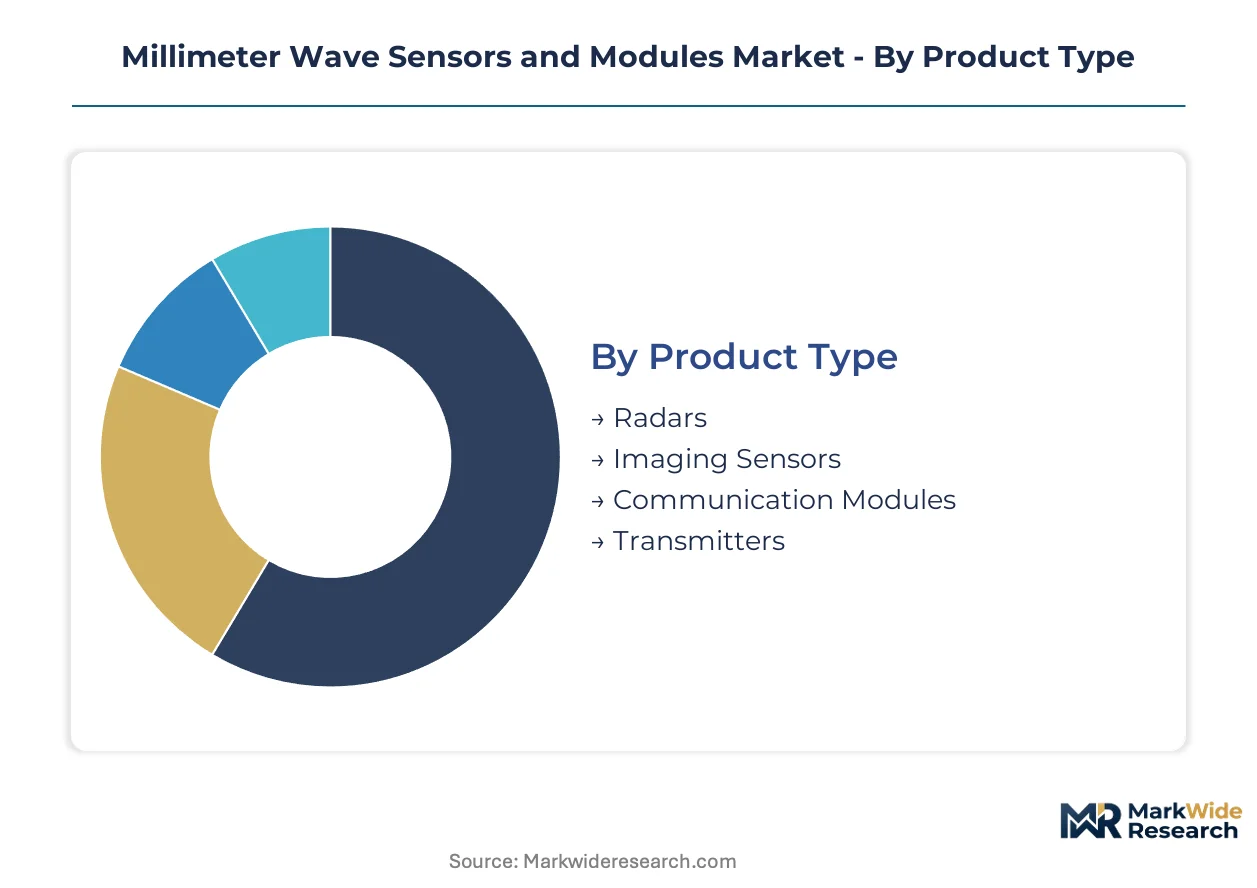
Millimeter wave sensor and module market segmentation provides a granular view of diverse product capabilities and application areas. This breakdown highlights where specific technological advancements are concentrated and how various end-user requirements shape product development. Understanding these segments is crucial for identifying precise growth opportunities and strategic investment areas within the market.
Product Type:
The capital outlay for millimeter wave product development varies significantly across different device types.
- Radars:These sensors transmit and receive radio waves to detect objects, measure distance, and determine velocity with high precision. Demand concentrates in automotive safety systems, particularly for advanced driver-assistance systems (ADAS) in Germany, driven by regulatory mandates.
- Communication Modules:These modules facilitate high-bandwidth data transmission over short distances, critical for next-generation wireless networks. The global rollout of 5G infrastructure in countries like the US and China drives demand for these modules in backhaul and fronthaul links.
- Imaging Sensors:These devices create high-resolution images of objects, often used in security screening and industrial quality control. Object detection capabilities are critical for factory logistics.
- Transmitters:These components generate the millimeter wave signals for various applications, including radar and communication systems. Their performance is fundamental to overall system efficacy.
Most installed capacity flows through Radars. Expansion is steepest in Communication Modules.
Application:
Application scope and precision requirements dictate the specific millimeter wave sensor configurations deployed.
- Automotive Safety:This segment involves sensors for collision avoidance, blind spot detection, and in-cabin monitoring, enhancing vehicle occupant protection. Regulatory bodies like the US NHTSA and Germany's KBA mandate ADAS features, fueling demand for 77 GHz radar sensors.
- Industrial Automation:Millimeter wave sensors enable precise object detection, ranging, and level sensing in harsh industrial environments. Industry 4.0 initiatives in countries like Japan and South Korea integrate these sensors for robotics and machine monitoring.
- Traffic Monitoring:These systems monitor vehicle flow, speed, and occupancy for intelligent transportation systems. Urban centers globally utilize this technology to optimize traffic management.
- Security Surveillance:Millimeter wave technology provides non-invasive detection of concealed objects, primarily in airport security and public venue screening. High-resolution capabilities are essential.
Demand for Automotive Safety dominates, while Industrial Automation exhibits rapid expansion.
End User:
End-user regulatory environments and performance demands critically influence the adoption of millimeter wave technologies.
- Telecommunications:This sector utilizes millimeter wave modules for high-capacity wireless backhaul, fronthaul, and fixed wireless access in 5G networks. The global buildout of 5G infrastructure, especially in the US and China, drives significant market volume.
- Defense:High-frequency sensors are deployed in military radar, missile guidance, and surveillance systems, requiring robust performance in challenging conditions. Government spending on advanced defense capabilities in countries like the US supports this segment.
- Aerospace:Millimeter wave sensors are used for aircraft navigation, weather radar, and satellite communication systems. Precision and reliability are paramount for aerospace applications.
- Healthcare:Emerging applications include non-invasive vital sign monitoring, remote diagnostics, and medical imaging. In-cabin sensing for occupant biometrics represents a new frontier.
The largest volume of millimeter wave deployments serves Telecommunications. Emerging growth concentrates in Healthcare.
Technology:
Material science and manufacturing scalability differentiate millimeter wave technologies across the market.
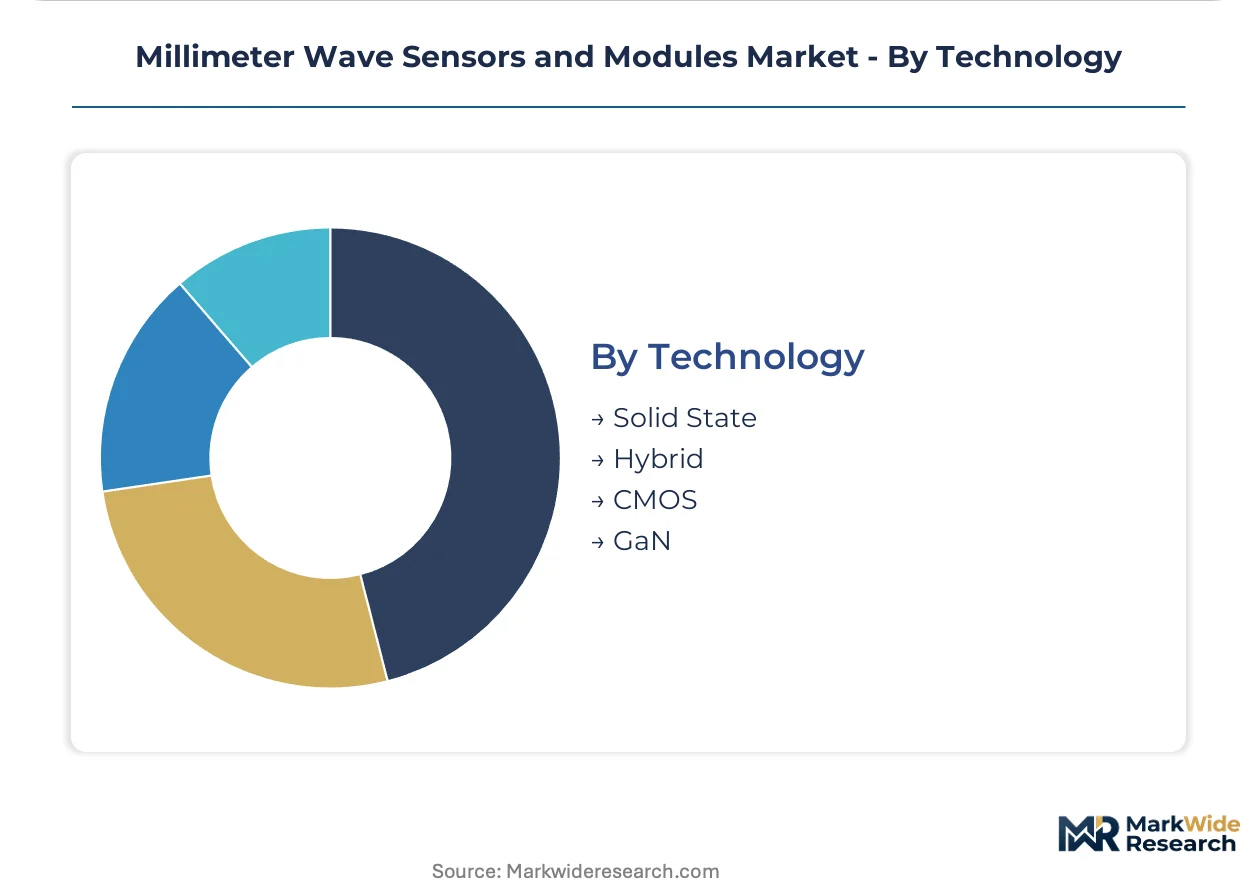
- CMOS:Complementary Metal-Oxide-Semiconductor technology offers cost-effective, highly integrated solutions suitable for high-volume consumer and automotive applications. Texas Instruments excels in large-scale production of these cost-optimized sensors.
- GaN:Gallium Nitride technology provides high power density and superior efficiency at millimeter wave frequencies, ideal for high-performance communication modules and defense applications. Its high material cost limits adoption in price-sensitive segments.
- Solid State:This technology refers to circuits built entirely from solid materials, offering reliability and compact form factors. Solid state designs are foundational for modern integrated circuits.
- Hybrid:Hybrid approaches combine different semiconductor materials or packaging techniques to optimize performance and cost. This allows for customized solutions.
CMOS technology forms the foundation for most cost-optimized solutions. GaN solutions are capturing high-performance niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The millimeter wave sensor and module market initially scaled through specialized defense applications and early telecommunications infrastructure. Its evolution accelerated with the advent of high-frequency radar for automotive safety systems. This technology now forms the bedrock for advanced sensing in diverse global industries.
Germany
Germany's automotive industry drives substantial demand for millimeter wave radar sensors, particularly for advanced safety features. The KBA mandates for driver-assistance systems directly stimulate this market. The automotive manufacturing ecosystem in Bavaria and Baden-Württemberg concentrates development of high-resolution sensing solutions.
United States
The United States experiences robust demand from its extensive 5G network buildout and evolving automotive safety standards. The FCC regulates frequency bands for communication modules, while the NHTSA influences ADAS adoption. Technology hubs in California and Texas lead innovation in both telecommunications and automotive sensor integration.
China
China's aggressive 5G deployment strategy generates significant demand for millimeter wave communication modules. National industrial policies, including Industry 4.0 initiatives, also expand sensor applications in manufacturing. Major technology centers in the Yangtze River Delta and Pearl River Delta are key development hubs.
Japan
Japan's advanced manufacturing sector fuels demand for millimeter wave sensors in industrial automation and robotics. The METI supports Industry 4.0 principles, integrating these sensors for precise machine monitoring. Industrial clusters around Tokyo and Nagoya focus on high-precision object detection for factory logistics.
South Korea
South Korea shows strong demand from its leading consumer electronics industry and expanding automotive ADAS ecosystem. Government initiatives promoting smart mobility and advanced manufacturing influence technology adoption. The Seoul Capital Area remains a center for integrated AiP module development and consumer device innovation.
Millimeter Wave Sensors and Modules Market Key Industry Players
Premium-margin players sit above commodity-margin players across the millimeter wave sensor and module value chain, influencing market dynamics. The industry structure is tiered, featuring highly specialized RF component manufacturers alongside diversified semiconductor conglomerates. Strategic archetypes include dedicated radar sensor specialists, broad-spectrum communication module providers, and integrated system solution developers targeting specific performance or cost points. Competitive positioning often involves strategic alliances for advanced technology co-development and targeted portfolio expansion into high-growth application areas like in-cabin sensing.
Within the integrated semiconductor solutions archetype, Infineon Technologies AG and NXP Semiconductors N.V. exemplify companies leveraging extensive RF portfolios to address diverse end-user segments. These European-based corporations occupy positions providing radar solutions for advanced driver-assistance systems and broader connectivity applications. Texas Instruments, a US-based entity, represents the scale-driven manufacturing segment, anchoring its market presence through large-scale production of cost-optimized CMOS-based sensors. These entities collectively demonstrate the varied approaches to delivering millimeter wave technology.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Qualcomm Technologies, Inc. |
| NXP Semiconductors N.V. |
| Texas Instruments |
| Keysight Technologies |
| Aviat Networks, Inc. |
| NEC Corporation |
| Ceragon Networks Ltd. |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Publicly traded semiconductor conglomerates drive the millimeter wave market, influencing both supply-side capacity and pricing discipline. Their extensive R&D investments shape advanced technology availability and cost structures for integrated modules.
Pricing Analysis
Tiered pricing stratifies across premium, standard, and economy levels in the millimeter wave market. Price differentiation stems from technology choice, such as high-performance GaN versus cost-optimized CMOS, and specific regulatory certifications required for frequency bands like 77 GHz radar. Pricing softness reflects intense competition for high-volume automotive and consumer electronics applications, where cost-per-unit is paramount. Defense and specialized telecommunications sectors exhibit lower price sensitivity due to stringent performance requirements.
Supply Chain Analysis
Specialized RF engineering talent availability in Germany, South Korea, and the United States underpins the millimeter wave supply chain. Production relies heavily on silicon and Gallium Nitride substrates, with manufacturing concentrated in regions supporting major automotive and consumer electronics OEMs. A significant supply chain risk is the scarcity of qualified RF engineering talent, constraining product development capacity across the industry. Distribution runs through direct channels to original equipment manufacturers, especially for integrated Antenna-in-Package modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Millimeter Wave Sensors and Modules market presents a margin-expansion story, driven by the shift towards cost-effective CMOS-based integration. This transition allows for broader application penetration and optimized production scaling.
For Market Incumbents: Lock in intellectual property around integrated Antenna-in-Package (AiP) modules to maintain a competitive edge against emerging component suppliers. Deepen in-house production of cost-optimized CMOS solutions to counter margin pressure from high-volume automotive and consumer electronics segments. Invest in advanced thermal management R&D, addressing a key challenge for compact, high-power GaN modules. Strengthen relationships with regulatory bodies like the FCC and ETSI to influence standardization efforts, simplifying market access.
For New Entrants and Emerging Players: Capture white space opportunities in emerging applications like 60 GHz in-cabin sensing for occupant biometrics, leveraging new automotive safety mandates. Target underpenetrated industrial sectors in India and Brazil, deploying mmWave sensors for process control as smart factory initiatives gain support. Develop AI and sensor fusion capabilities to offer superior object classification, creating intelligent systems for diverse end-uses. Focus on highly integrated, cost-effective CMOS solutions for rapid market penetration.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized RF component manufacturers offering niche capabilities in thermal management or antenna design. The market offers long-term growth potential, particularly with the continued expansion of 5G infrastructure and ADAS mandates. Identify integrated system solution developers with strong IP in sensor fusion and AI algorithms as prime acquisition targets. The signal to watch is the harmonization of communication protocols and data formats, which will accelerate large-scale deployments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Developing common 77 GHz radar platforms for automotive applications reduces market access friction across global geographies. |
| Integrated Module Development | Focusing on Antenna-in-Package (AiP) modules simplifies design cycles for automotive and consumer electronics OEMs. |
| Advanced Material R&D | Investing in Gallium Nitride (GaN) substrate alternatives can lower costs for high-power communication modules. |
| Sensor Fusion Investment | Integrating millimeter wave data with machine learning enables superior object classification for autonomous systems. |
| Geographic Manufacturing Footprint | Establishing production capabilities in Germany supports demand from its robust automotive safety sector. |
Research Approach
Direct dialogue with OEM procurement managers, RF system engineers, ADAS developers, and telecommunications infrastructure planners formed the primary data foundation. This primary research was rigorously validated against secondary sources including FCC filings, ETSI standards documents, automotive industry reports, and 5G deployment statistics. The analysis then employed both bottom-up and top-down triangulation to ensure comprehensive data accuracy and market sizing.
A bottom-up analytical lens, cross-referenced with top-down market validation, underpinned the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end user, technology, and regional regulatory environments. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected adoption rates. Key industry-specific inputs included anticipated 5G network buildout rates and ADAS feature penetration in major automotive markets.
Regulatory shifts, material cost volatility, and RF engineering talent availability are the dominant revision risks for these forecasts. The projections reflect current market dynamics and technological trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Fingerprint Sensor Market