
 PID Controller Market | 2026-2036
PID Controller Market Size, Share, and Industry Trends Forecast 2026-2036
PID Controller Market Outlook
Asset-light leasing models for automation hardware are tilting competitive dynamics toward system integrators that previously faced high capital barriers. Siemens leverages its captive financing arm to place multi-loop controllers into mid-tier manufacturing sites without upfront purchase requirements. Yokogawa Electric anchors its position in oil and gas through long-term service contracts bundled with distributed control architecture. Honeywell International competes by extending predictive maintenance software subscriptions alongside its hardware installations.
A proportional-integral-derivative controller continuously calculates an error value as the difference between a desired setpoint and a measured process variable, then applies a correction based on proportional, integral, and derivative terms tuned to specific loop response characteristics. Its primary purpose is to maintain stable process conditions in industrial automation where precise temperature, pressure, flow, or level control determines product quality and operational safety. Smart controllers now lead product type dynamics as embedded edge computing enables autonomous tuning algorithms that reduce commissioning time. Digital technology segments capture expanding margin pools as plants replace aging analog installations with Ethernet-connected variants that feed plant-wide analytics platforms.
FDA validation requirements for pharmaceutical batch control and EPA emissions monitoring standards for combustion processes both mandate documented control loop performance, directly expanding demand for certified PID implementations. CE marking under the EU Machinery Directive and IEC 61508 functional safety standards further constrain market access to suppliers with proven SIL-rated product lines. Stakeholders must weigh the pace of wireless protocol standardization against the reliability guarantees that hardwired digital loops still provide in critical applications.
Market Dynamics
Smart PID controllers with embedded edge computing are compressing commissioning cycles and displacing analog loop architectures across process industries, while EFSA hygiene automation standards in Germany and MIIT digital mandates in China reshape procurement specifications.
Growth Catalysts
- EFSA Hygiene Automation Standards:Food processing facilities in Germany face mandatory automation upgrades for sanitary compliance, expanding certified controller deployments in dairy and meat processing lines.
- MIIT Digital Manufacturing Mandates:China's Ministry of Industry and Information Technology requires digital control system integration across industrial clusters, forcing replacement of pneumatic and analog installations.
- Edge Computing Integration:Autonomous tuning algorithms embedded in smart controllers reduce field commissioning from weeks to days, accelerating replacement cycles in chemical and pharmaceutical plants.
Market Restraints
- SIL Certification Concentration:IEC 61508 functional safety certification remains limited to established suppliers, blocking mid-tier Asian manufacturers from safety-critical oil and gas applications.
- Semiconductor Input Volatility:Industrial-grade microcontrollers and analog-to-digital converters face supply allocation constraints from automotive and consumer electronics demand.
- Wireless Protocol Fragmentation:Competing industrial wireless standards (WirelessHART, ISA100, 5G-URLLC) create interoperability deadlocks that hardwired 4-20mA loops still resolve reliably.
Strategic Opportunities
- India PLI Manufacturing Incentives:Production-linked incentive schemes for electronics and pharmaceuticals drive greenfield automation investments in Gujarat and Tamil Nadu industrial corridors.
- FDA Process Analytical Technology:Pharmaceutical batch control mandates create demand for validated PID loops with electronic batch record integration in continuous manufacturing lines.
- Predictive Maintenance Convergence:Controller-integrated vibration and temperature analytics bundled with cloud platforms open recurring revenue streams in rotating equipment monitoring.
Industry Challenges
- Control Loop Tuning Expertise Scarcity:Retiring instrumentation engineers leave gaps in PID parameter optimization for complex multi-variable processes, forcing reliance on vendor field service.
- Legacy DCS Integration Complexity:Proprietary communication protocols in aging distributed control systems obstruct seamless smart controller retrofit without costly gateway infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PID Controller Market |
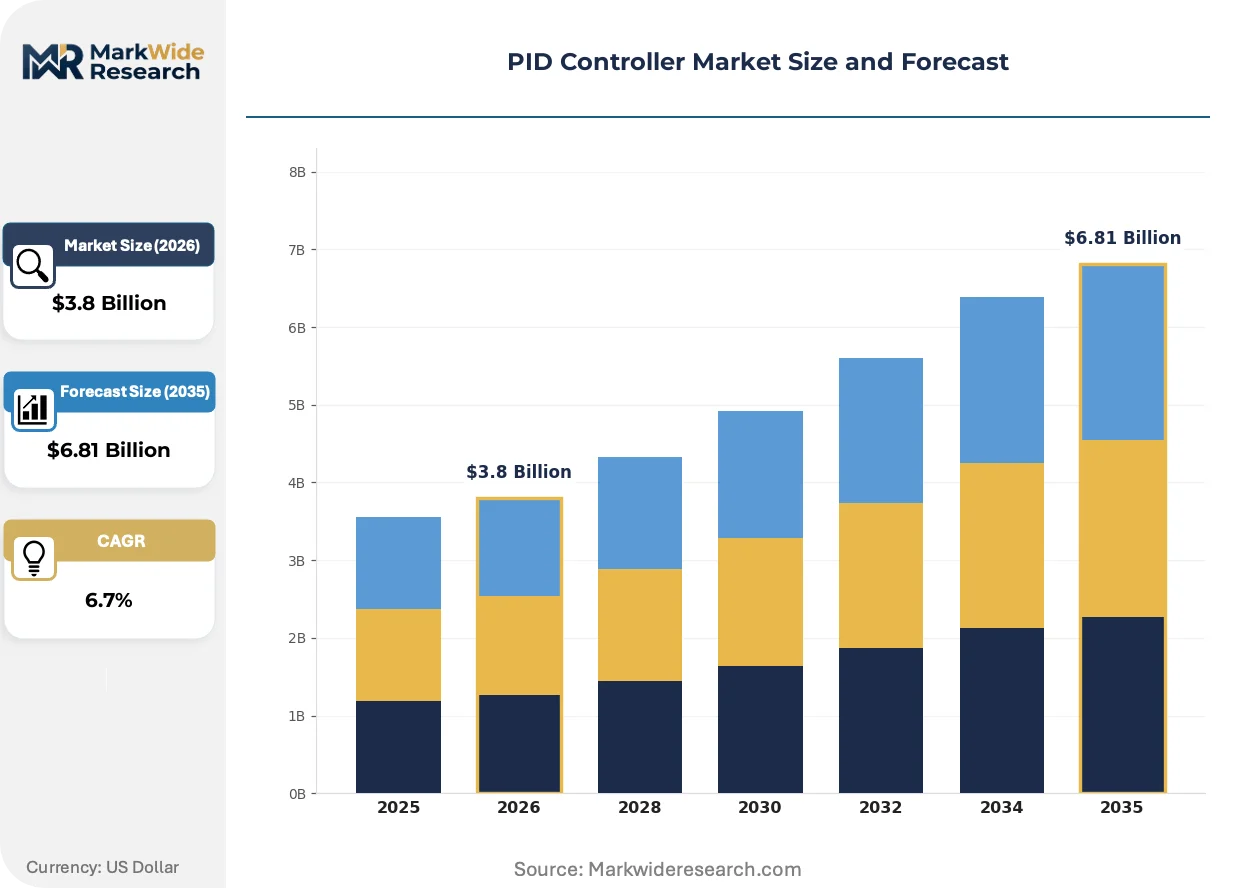
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-loop, Multi-loop, Distributed, Smart End User: Manufacturing, Oil & Gas, Aerospace, Food & Beverage Technology: Analog, Digital, Hybrid, Wireless Application: Temperature Control, Pressure Control, Flow Control, Level Control |
| Companies Covered | Emerson Electric, Honeywell International, Rockwell Automation, Siemens, ABB, Schneider Electric, Yokogawa Electric, Omron, Azbil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PID Controller Market Strategic Shifts
Model predictive control algorithms and adaptive tuning methods are compressing the performance gap between traditional PID and advanced process control, reshaping how mid-tier plants justify automation investments.
Self-tuning PID algorithms with embedded process identification are rendering obsolete manual commissioning procedures that required specialized instrumentation technicians on-site for weeks. Chemical batch manufacturers in the US Gulf Coast and specialty polymer producers in Rotterdam are deploying these controllers to reduce startup time and minimize off-spec production. The technology is compressing the total installed cost gap between basic and advanced control strategies, forcing DCS vendors to unbundle software licensing.
EPA emissions monitoring standards for combustion processes now mandate documented control loop performance with continuous data logging, compelling power generation and refining operators to replace pneumatic controllers with digital variants. The regulation requires certified SIL-rated implementations for safety shutdown loops, restricting supplier selection to vendors with proven functional safety track records. Natural gas combined cycle plants in Texas and Pennsylvania are accelerating digital retrofit timelines to meet compliance deadlines.
Asset-light leasing arrangements for automation hardware are displacing traditional capital purchase models in mid-tier manufacturing. System integrators in China's Yangtze River Delta and India's Pune-Ahmedabad belt now bundle controller hardware with multi-year service contracts, transferring obsolescence risk from plant operators to integration firms. This shift concentrates procurement authority with engineering contractors rather than end-user maintenance departments, altering vendor sales channel strategies.
PID Controller Market Segmentation
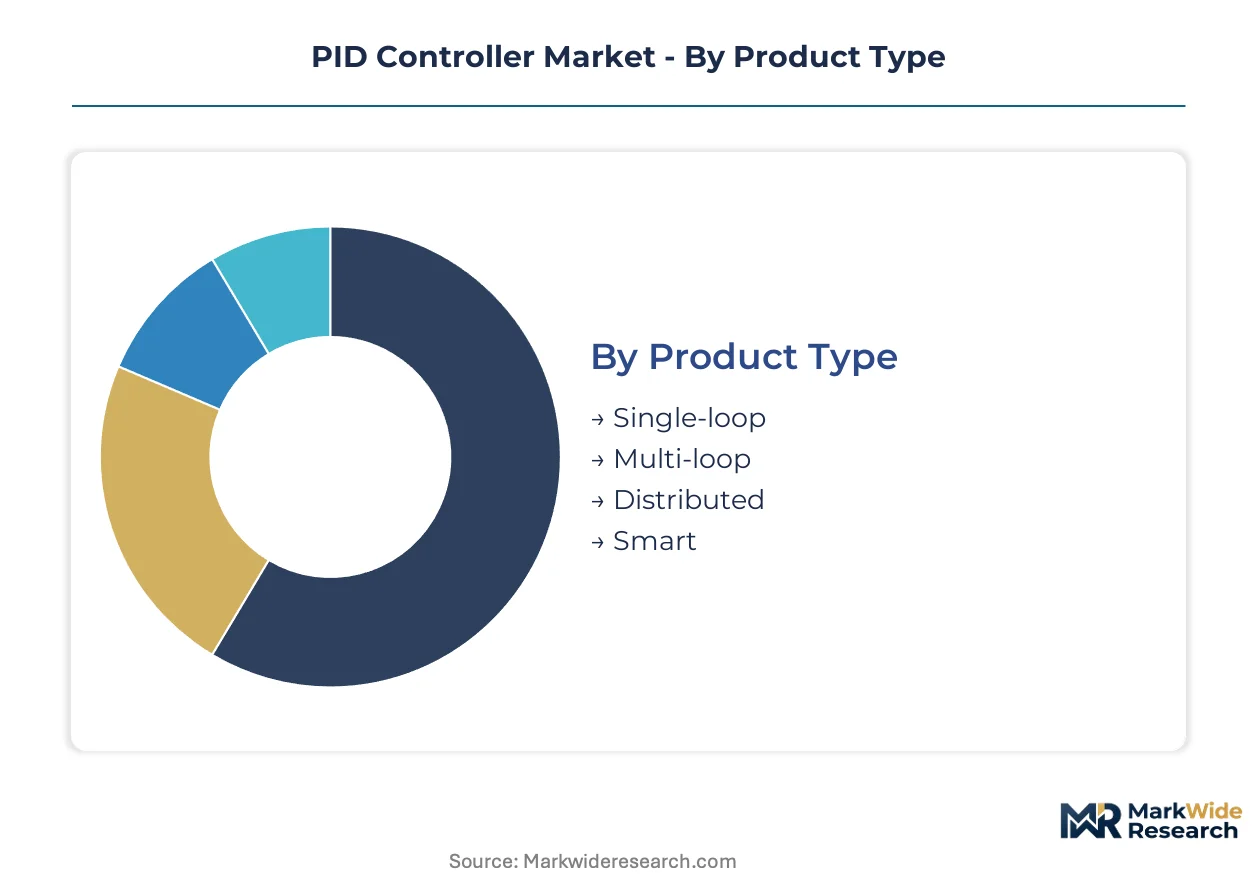
PID controller procurement patterns diverge sharply across hardware configurations, end-use environments, and communication architectures. Service contract attachment rates and recalibration frequency vary by segment, directly shaping lifetime revenue per installation for suppliers.
Product Type:
After-sales service intensity climbs with controller complexity, as embedded diagnostics and remote monitoring capabilities expand vendor field service obligations.
- Single-loop:Standalone units manage one process variable with dedicated I/O channels, typically deployed in isolated heating or cooling skids. Demand concentrates in Germany's food processing facilities upgrading to EFSA hygiene automation standards, where sanitary washdown requirements mandate frequent recalibration services.
- Multi-loop:Integrated chassis house multiple control channels sharing power and communication backplanes, reducing panel space and wiring density. Chemical batch manufacturers in China's Yangtze River Delta favor these for reactor train coordination under MIIT digital mandates, though commissioning complexity extends vendor service engagements.
- Distributed:Field-mounted modules communicate over plant networks, separating control logic from operator interfaces. These installations generate recurring revenue through firmware update subscriptions and redundancy validation testing.
- Smart:Edge-computing-enabled variants with autonomous tuning algorithms and embedded analytics. Predictive maintenance bundling creates the highest service contract attachment rates in this category.
By volume, Single-loop leads. By growth pace, Smart controllers are expanding most quickly.
End User:
Cost tier stratification separates capital-intensive process industries from discrete manufacturing, with certification requirements and safety integrity levels driving pricing spreads.
- Manufacturing:Discrete automation lines in automotive stamping and electronics assembly deploy controllers for thermal management of tooling and curing ovens. India's PLI manufacturing incentives in Gujarat and Tamil Nadu corridors are accelerating greenfield controller procurement.
- Oil & Gas:Upstream production and downstream refining demand SIL-rated implementations for safety shutdown loops. EPA emissions monitoring standards mandate digital retrofit timelines at natural gas combined cycle plants in Texas and Pennsylvania.
- Aerospace:Test stand and propulsion system applications require traceable calibration chains and extended temperature specifications. This segment commands premium pricing for documentation and failure analysis services.
- Food & Beverage:Dairy and meat processing lines in Germany face mandatory automation upgrades for EFSA sanitary compliance, expanding certified controller deployments with hygienic enclosure ratings.
Manufacturing captures the largest installation base. Aerospace delivers the steepest margin expansion trajectory.
Technology:
Application environment dictates communication architecture selection, with hazardous area classification and electromagnetic interference tolerance filtering viable options.
- Analog:4-20mA current loop signaling persists in safety-critical applications where deterministic response overrides connectivity benefits. Aging pneumatic-to-electronic conversions in legacy plants sustain replacement demand.
- Digital:Ethernet-connected variants feed plant-wide analytics platforms and enable centralized parameter management. These are displacing analog installations across China's industrial clusters under MIIT integration requirements.
- Hybrid:Mixed-signal designs bridge legacy analog field devices with digital control networks, easing transition risk for brownfield retrofits. Gateway infrastructure costs concentrate procurement authority with system integrators.
- Wireless:Battery-powered or energy-harvesting units eliminate conduit and cable tray installation. Competing standards fragmentation between WirelessHART, ISA100, and 5G-URLLC creates interoperability deadlocks that constrain deployment.
Digital technology dominates new installations. Wireless is gaining share fastest despite protocol uncertainty.
Application:
Customer type segmentation separates batch process operators from continuous manufacturing, with tuning expertise requirements and setpoint volatility shaping controller specification.
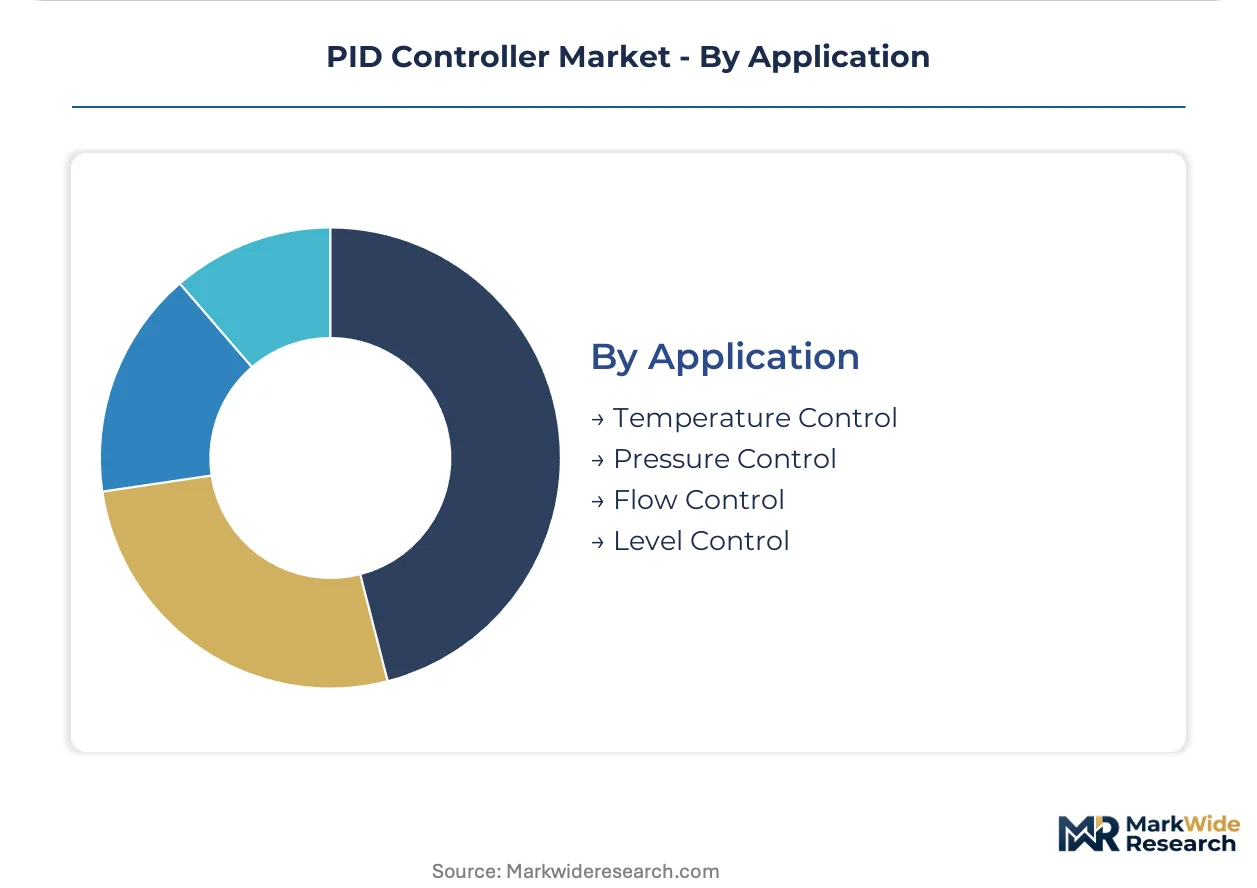
- Temperature Control:Thermal regulation in reactors, distillation columns, and heat exchangers demands tight setpoint tracking to prevent thermal runaway or product degradation. Pharmaceutical batch manufacturers require FDA-validated loops with electronic batch record integration.
- Pressure Control:Compressor anti-surge and vessel pressure protection applications prioritize response speed over precision. Safety shutdown loops in oil and gas require certified SIL-rated implementations.
- Flow Control:Ratio control and cascade configurations manage reactant addition and product blending. Custody transfer metering in hydrocarbon pipelines demands traceable calibration documentation.
- Level Control:Inventory management and pump protection applications tolerate wider deadbands than other loops. Radar and guided-wave sensors increasingly embed self-tuning algorithms that reduce commissioning scope.
Temperature Control maintains the broadest cross-industry footprint. Level Control is climbing the fastest as solids and slurry applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT digital mandates in China and EFSA hygiene standards in Germany are redirecting procurement flows toward certified smart controllers, while India's PLI schemes and US EPA emissions rules create parallel demand vectors across industrial clusters.
China
Yangtze River Delta chemical manufacturers are replacing pneumatic loops with Ethernet-connected digital controllers under MIIT integration requirements. The ministry's digital manufacturing mandates force brownfield upgrades across 15 industrial clusters. Shanghai and Suzhou process plants now specify smart controllers with autonomous tuning to compress commissioning cycles.
Germany
Dairy and meat processing lines in Bavaria and Lower Saxony face mandatory EFSA hygiene automation standards requiring sanitary-rated controller enclosures. The EU Machinery Directive's CE marking constraints limit supplier selection to proven SIL-rated product lines. Stuttgart-area automotive stamping plants deploy multi-loop controllers for thermal management of curing ovens.
United States
Texas and Pennsylvania natural gas combined cycle plants accelerate digital retrofit timelines to meet EPA emissions monitoring standards for combustion processes. FDA validation requirements for pharmaceutical batch control expand certified PID deployments in New Jersey and Massachusetts biotech corridors. Gulf Coast chemical manufacturers adopt self-tuning algorithms to minimize off-spec production.
India
Gujarat and Tamil Nadu industrial corridors attract greenfield automation investments through PLI manufacturing incentives for electronics and pharmaceuticals. BIS certification requirements for industrial control equipment filter supplier selection toward established vendors. Pune-Ahmedabad system integrators bundle controller hardware with multi-year service contracts, transferring obsolescence risk from plant operators.
Japan
Chubu region automotive and machinery producers specify traceable calibration chains for test stand applications under METI industrial standards. JIS certification requirements constrain market access to suppliers with documented functional safety track records. Osaka-area specialty chemical manufacturers deploy edge-computing-enabled controllers for reactor train coordination.
PID Controller Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Vertically integrated conglomerates with captive financing arms leverage asset-light leasing to displace upfront purchase requirements in mid-tier manufacturing. System integrators with regional installation density capture procurement authority from end-user maintenance departments. The dominant competitive moves involve bundling predictive maintenance software subscriptions with hardware installations and anchoring positions through long-term service contracts tied to distributed control architecture.
Among diversified industrial conglomerates, Siemens and Honeywell International exemplify the financing-integrated archetype, while Yokogawa Electric occupies a position within the process-specialist tier focused on oil and gas safety applications. These three companies represent distinct strategic postures: captive financing deployment, software-subscription bundling, and long-term service contract anchoring respectively.
| Leading Market Players |
|---|
| Emerson Electric |
| Honeywell International |
| Rockwell Automation |
| Siemens |
| ABB |
| Schneider Electric |
| Yokogawa Electric |
| Omron |
| Azbil |
| Others |
Value Chain & Pricing Dynamics
Shanghai and Suzhou industrial clusters anchor microcontroller and analog-to-digital converter capacity for PID controller assembly, concentrating upstream pricing power among semiconductor foundries serving automation OEMs. MIIT digital mandates across China's Yangtze River Delta force volume procurement commitments that compress margins for mid-tier controller manufacturers lacking captive silicon supply.
Pricing Analysis
Certification level creates the primary spread, with IEC 61508 SIL-rated implementations commanding substantial premiums over standard industrial variants. Three-tier pricing structure across premium certified, standard digital, and economy analog levels reflects differential compliance burdens. Cost compression in economy analog tiers is intensifying because automotive and consumer electronics demand diverts semiconductor allocation toward higher-margin customers. Discrete manufacturing buyers in India's PLI corridors exhibit highest price sensitivity, while oil and gas operators prioritize safety integrity over unit economics.
Supply Chain Analysis
Export-control regimes restricting advanced microcontroller technology flows constrain supply elasticity for edge-computing-enabled smart controllers. Controller assembly draws from China, Germany, and Japan for precision manufacturing, with industrial-grade microcontrollers and ADCs sourced from Taiwan, South Korea, and USA fabrication facilities. Single-source vulnerability concentrates in automotive-qualified semiconductor allocation, where demand spikes trigger supply rationing. Distribution runs through system integrators in China's Yangtze River Delta and India's Pune-Ahmedabad belt, transferring procurement authority from end-user maintenance departments to engineering contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Model predictive control algorithms threaten traditional PID architectures in mid-tier chemical and pharmaceutical applications, forcing incumbents to defend installed base through service contract anchoring and predictive maintenance bundling.
For Market Incumbents: Harden defensive positions by embedding autonomous tuning algorithms that compress commissioning cycles and raise switching costs for chemical batch manufacturers. Deepen backward integration into industrial-grade microcontroller supply through long-term foundry commitments, insulating against automotive demand allocation shocks. Anchor customer relationships through predictive maintenance software subscriptions that capture recurring revenue streams and obscure hardware substitution economics. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Tamil Nadu industrial corridors, where PLI manufacturing incentives accelerate greenfield automation investments and BIS certification requirements filter less agile competitors. Target food and beverage hygiene automation upgrades in Germany's Bavaria and Lower Saxony processing belts, where EFSA mandates force certified controller procurement without entrenched supplier relationships. Pursue system integrator partnerships rather than direct end-user sales, concentrating limited resources on channel control rather than field service buildout. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart controller vendors with predictive maintenance bundling and firmware update subscriptions, positioning these archetypes for premium valuation multiples. Target acquisition profiles center on edge-computing specialists with embedded process identification algorithms and established SIL certification track records. The signal to watch is EPA emissions monitoring enforcement intensity at Texas and Pennsylvania natural gas combined cycle plants, where compliance acceleration would force compressed digital retrofit timelines and concentrate demand among certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Tuning Algorithm Development | Compresses commissioning cycles from weeks to days for chemical manufacturers under MIIT mandates. |
| Predictive Maintenance Platform Integration | Bundles controller hardware with vibration analytics, capturing recurring revenue in rotating equipment monitoring. |
| SIL Certification Investment | Unlocks safety-critical oil and gas applications where IEC 61508 compliance blocks mid-tier Asian competitors. |
| System Integrator Channel Partnership | Concentrates procurement authority with engineering contractors in India's Pune-Ahmedabad belt. |
| Backward Integration into Semiconductor Supply | Insulates against automotive demand allocation shocks affecting industrial-grade microcontroller availability. |
Study Parameters
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and system integration specialists anchored the qualitative base for this analysis. Primary interviews across Germany's food processing belt, China's Yangtze River Delta chemical clusters, and India's PLI corridor manufacturing sites combined with secondary validation from IEC certification databases, MIIT policy circulars, EPA emissions enforcement records, and SEC filings from listed automation vendors. Bottom-up installation counts triangulated against top-down industrial automation spending estimates across the projection horizon.
Scenario-bracketing around MIIT mandate implementation pace, EPA enforcement intensity, and semiconductor allocation volatility framed the analytical envelope. Segmentation dimensions modeled include product type complexity, end-use safety integrity requirements, communication architecture generation, and regional regulatory cluster stringency. CAGRs derived from installation volume trajectories, replacement cycle compression, and service contract attachment rate evolution, with specific weighting for edge-computing adoption curves in pharmaceutical batch manufacturing.
Stress conditions across semiconductor supply disruption, wireless protocol standardization deadlock, and instrumentation engineer retirement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology substitution elasticity. Material shifts in EPA emissions monitoring timelines or MIIT digital mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Europe Nano Radiation Sensors Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market