
 Asia-Pacific Water Detection Sensors Market | 2026-2036
Asia-Pacific Water Detection Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Water Detection Sensors Market Outlook
Municipal utilities are unwinding decades of reliance on manual inspection regimes across the Asia-Pacific region. Yokogawa Electric Corporation leverages its process automation heritage to dominate industrial water quality monitoring in Japan and Australia. Emerson Electric Co. sustains competitive positioning through backward integration into sensor calibration services. HORIBA, Ltd. anchors its regional presence with specialized optical detection platforms for semiconductor fabs.
Water detection sensors are electromechanical or photonic devices that transduce liquid presence, level, or chemical composition into processable signals, typically operating across conductivity ranges from ultrapure water to high-salinity brine with response thresholds measured in parts per billion. Their primary purpose spans pipeline integrity assurance, flood early warning, and regulatory compliance in water-stressed industrial zones. Capacitive and ultrasonic sensor types command premium positioning where non-contact measurement eliminates corrosion risk in chemical processing environments. IoT-enabled and smart systems architectures are capturing disproportionate investment as utilities demand cloud-integrated analytics for predictive maintenance of distribution infrastructure.
Japan's Ministry of Economy, Trade and Industry promotes sensor miniaturization through its national IoT acceleration framework, while India's Bureau of Indian Standards enforces electromagnetic compatibility and ingress protection ratings for municipal deployment tenders. China's Ministry of Ecology and Environment ties wastewater discharge permits to real-time monitoring mandates, forcing industrial facilities toward certified detection systems. Stakeholders must weigh the trade-off between localized manufacturing for tariff compliance and technology licensing for advanced optical and capacitive platforms.
Market Dynamics
Asia-Pacific water utilities are abandoning reactive maintenance schedules in favor of continuous monitoring architectures, with cloud-native analytics platforms compressing replacement cycles for electromechanical sensors across municipal and industrial procurement channels.
Growth Catalysts
- China's MEE wastewater mandates:Real-time discharge monitoring requirements for semiconductor and chemical plants are mandating certified optical detection systems, forcing facility upgrades.
- India's smart city infrastructure:Municipal corporations in Delhi, Mumbai, and Bangalore are bundling leak detection sensors with AMR water meter deployments under urban renewal frameworks.
- Capacitive non-contact measurement:Corrosion elimination in chemical processing environments is accelerating sensor replacement in Japan's petrochemical corridors and Australia's mining water treatment facilities.
Market Restraints
- Optical component import dependence:Photodiode and laser diode supply concentrates in East Asian contract manufacturers, exposing downstream sensor assemblers to geopolitical logistics friction.
- Calibration service scarcity:Certified metrology laboratories capable of traceable ppb-level validation remain limited to Tokyo, Singapore, and Sydney, extending commissioning timelines for remote deployments.
- Legacy 4-20mA protocol entrenchment:Existing SCADA infrastructure in Southeast Asian utilities resists digital retrofit, slowing IO-Link and wireless adoption despite superior diagnostic capability.
Strategic Opportunities
- Vietnam's industrial corridor expansion:Northern provinces surrounding Hanoi are attracting foreign electronics manufacturing, creating greenfield demand for ultrapure water monitoring in fabs.
- Edge AI inference integration:On-sensor anomaly detection algorithms are converging with low-power LoRaWAN transmission, enabling predictive maintenance without cloud dependency in bandwidth-constrained regions.
- Indonesia's national water loss reduction program:Presidential directives targeting 20% non-revenue water are unlocking municipal tender volume for acoustic and pressure-based leak detection networks.
Industry Challenges
- Cross-domain firmware expertise shortage:Engineers capable of integrating chemical sensing membranes with embedded wireless stacks command premium compensation, constraining product development velocity.
- BIS electromagnetic compatibility testing backlog:India's certification queue for smart water meters extends 14-18 weeks, delaying commercial launches and freezing working capital.
- Retrofit integration complexity:Aging cast-iron distribution networks in Philippine and Thai municipalities resist standard sensor mounting, requiring custom fabrication that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Water Detection Sensors Market |
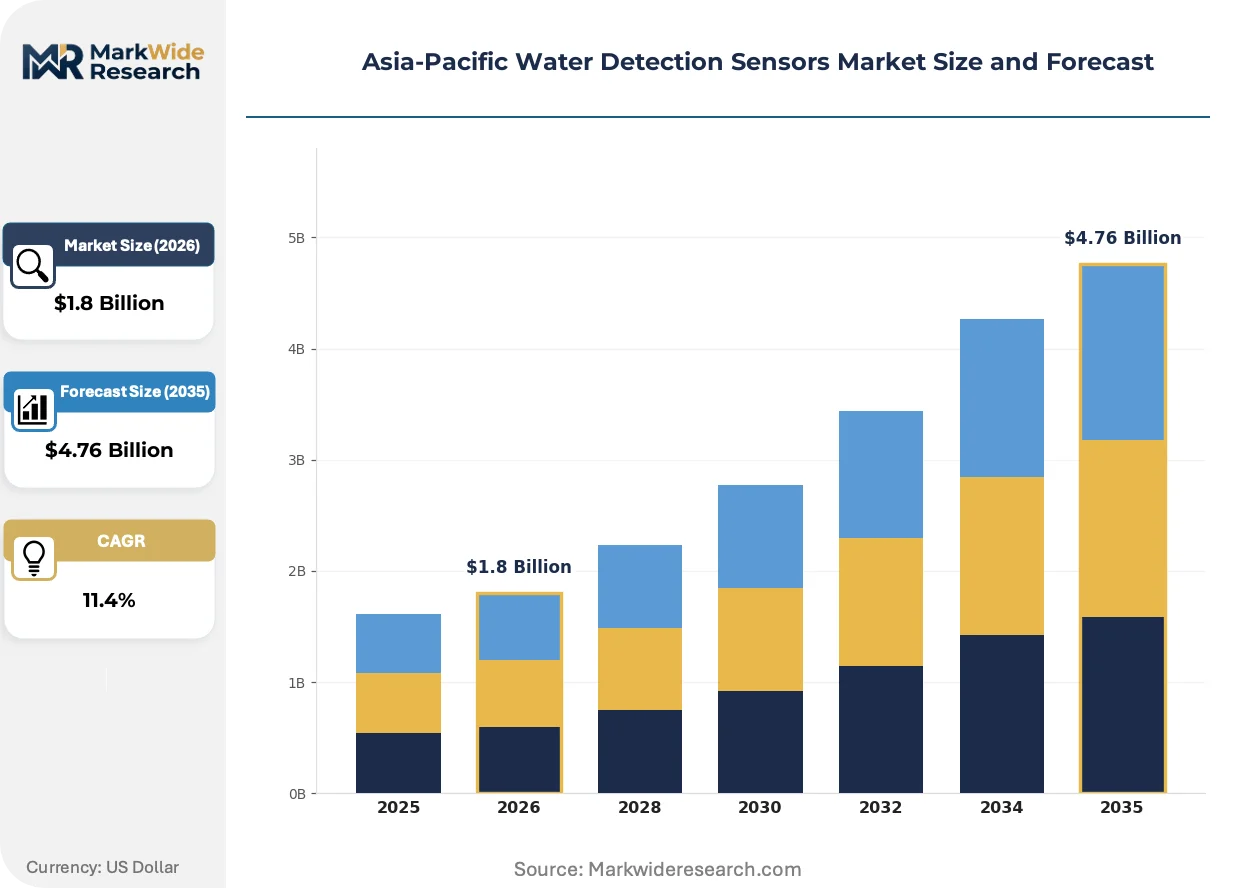
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Capacitive, Optical, Conductive, Ultrasonic Application: Leak Detection, Flood Monitoring, Industrial Applications, HVAC Systems End User: Residential, Commercial, Industrial, Municipal Technology: Wired, Wireless, IoT-enabled, Smart Systems |
| Companies Covered | Yokogawa Electric Corporation, Emerson Electric Co., Endress+Hauser Group Services AG, HORIBA, Ltd., Panasonic Corporation, Toshiba Corporation, TDK Corporation, Hach Co., Ltd., TTK - Leak Detection System, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Water Detection Sensors Market Strategic Shifts
Photonic and solid-state sensing modalities are compressing maintenance intervals while expanding detectable parameter ranges, with regional governments embedding technical specifications directly into procurement eligibility criteria.
Silicon photonics-based refractive index sensors is supplanting traditional float and pressure transducer architectures in high-purity water applications. Semiconductor fabs in South Korea and Taiwan are adopting these platforms for real-time TOC monitoring, eliminating sampling delays that previously required 30-45 minute laboratory turnaround. The shift is compressing sensor replacement cycles from seven-year electromechanical lifespans to three-year optical upgrade schedules.
Japan's METI IoT acceleration framework is channeling subsidy funding toward miniaturized, battery-operated detection nodes for agricultural irrigation networks. The program mandates interoperability with JIS-standard data formats, forcing sensor vendors to open proprietary communication protocols. Domestic rice cultivation cooperatives in Niigata and Akita prefectures are piloting soil-moisture-linked flood detection arrays under this scheme.
Asset-as-a-service contracting is displacing capital expenditure procurement in Australian mining water management. Rio Tinto and BHP are bundling sensor hardware, calibration labor, and cloud analytics into per-cubic-meter processed water fees. This model transfers obsolescence risk to vendors while locking buyers into multi-year data platform commitments, with Western Australian iron ore operations representing the most concentrated adoption geography.
Asia-Pacific Water Detection Sensors Market Segmentation
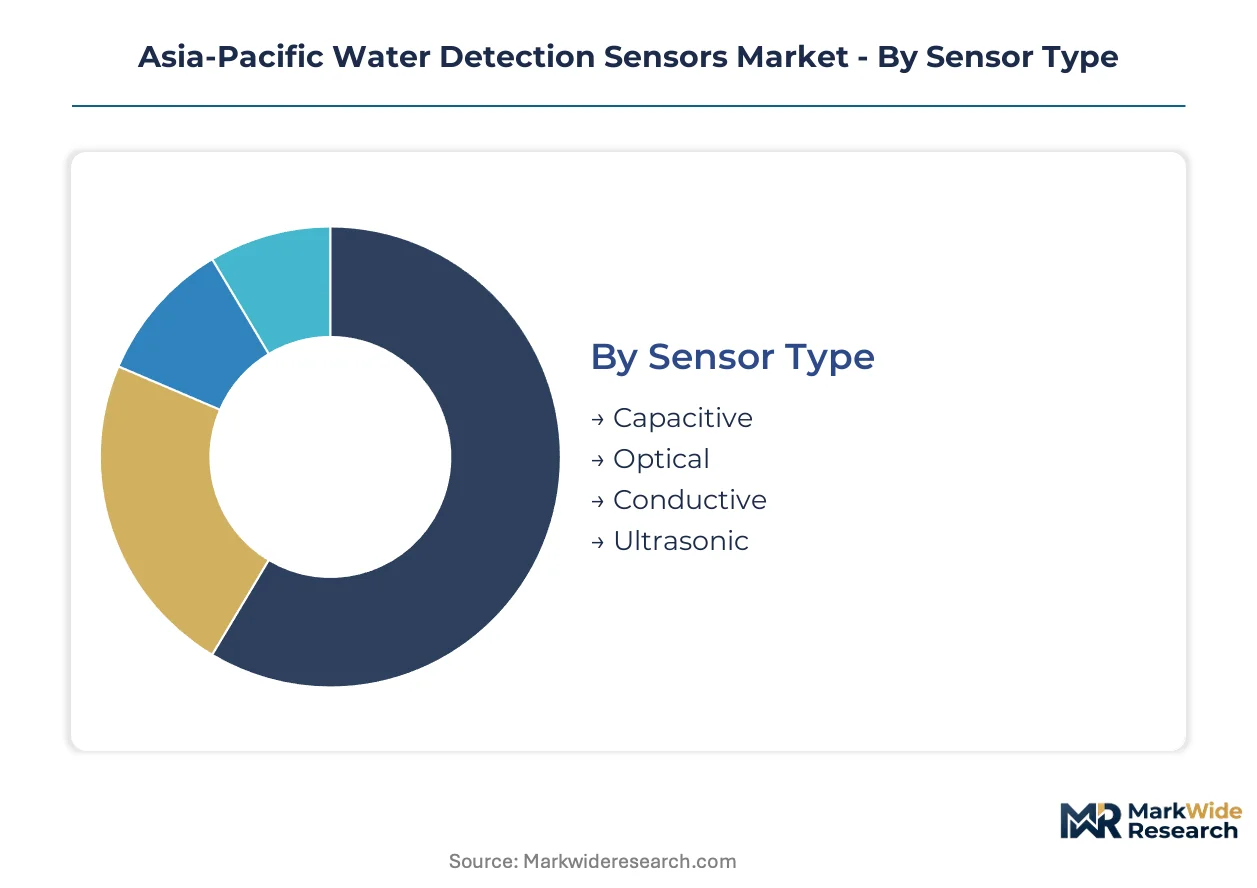
Sensor type, application architecture, and connectivity protocols segment the Asia-Pacific water detection sensors market into distinct procurement channels. Each dimension carries different certification burdens, replacement cycles, and margin structures that shape vendor positioning across municipal, industrial, and residential deployment contexts.
Sensor Type:
Domestic production concentrates on conductive and basic capacitive platforms for municipal tenders in India and Southeast Asia, while optical and precision capacitive sensors rely heavily on Japanese and South Korean component imports.
- Capacitive:Non-contact measurement eliminates electrode corrosion in chemical processing environments. Demand clusters in Japan's petrochemical corridors and Australia's mining water treatment facilities where maintenance access is costly and infrequent.
- Optical:Silicon photonics-based refractive index detection enables real-time TOC monitoring without sampling delays. Semiconductor fabs in South Korea and Taiwan drive replacement cycles compressed to three-year intervals versus seven-year electromechanical lifespans.
- Conductive:Simple two-electrode conductivity measurement dominates India's municipal AMR meter bundling tenders due to BIS certification feasibility and sub-dollar unit economics at volume.
- Ultrasonic:Time-of-flight level sensing penetrates flood monitoring networks in Indonesia's national water loss reduction program where battery-operated nodes must operate without line power.
Capacitive platforms command the established base. The steepest expansion runs through optical detection as semiconductor fabrication capacity multiplies across the region.
Application:
Cost tier stratification separates premium continuous-monitoring installations from economy-grade alert-only systems, with industrial applications capturing the highest per-node value and HVAC systems representing the most price-sensitive volume channel.
- Industrial Applications:Multi-parameter water quality monitoring for semiconductor and chemical plants integrates optical TOC, resistivity, and particle detection. China's MEE wastewater discharge permits mandate real-time certification, forcing facility-wide sensor retrofits.
- Leak Detection:Acoustic and pressure-based pipeline integrity systems anchor municipal procurement in Indonesia, Thailand, and Vietnam where non-revenue water targets approach 20% reduction mandates.
- Flood Monitoring:Battery-operated edge nodes with LoRaWAN backhaul deploy across agricultural irrigation networks in Japan's Niigata and Akita prefectures under METI subsidy frameworks.
- HVAC Systems:Condensate pan and cooling tower level sensors serve commercial building automation with lowest-common-denominator 4-20mA output, resisting digital protocol upgrades.
Industrial applications absorb the highest absolute spending. Flood monitoring is climbing fastest as climate adaptation funding channels into distributed sensor networks.
End User:
Customer type determines procurement modality, with municipal tenders favoring localized manufacturing compliance and industrial buyers prioritizing calibration service proximity over unit cost.
- Municipal:Water utilities in Delhi, Mumbai, and Bangalore bundle leak detection with smart meter deployments under urban renewal frameworks, requiring BIS electromagnetic compatibility and ingress protection certifications.
- Industrial:State-owned enterprises in China's industrial corridor cities retrofit aging pipeline networks with certified optical systems, transferring obsolescence risk through asset-as-a-service contracts modeled on Australian mining sector precedents.
- Commercial:Building automation integrators in Singapore and Sydney specify multi-sensor nodes combining leak, temperature, and humidity detection for data center cooling infrastructure.
- Residential:Smart home water shutoff valves with integrated leak detection penetrate premium housing developments in Tokyo and Melbourne, constrained by Wi-Fi reliability in concrete construction.
Municipal procurement represents the deepest installed base. Industrial end users are expanding most quickly as discharge monitoring mandates tighten across the region.
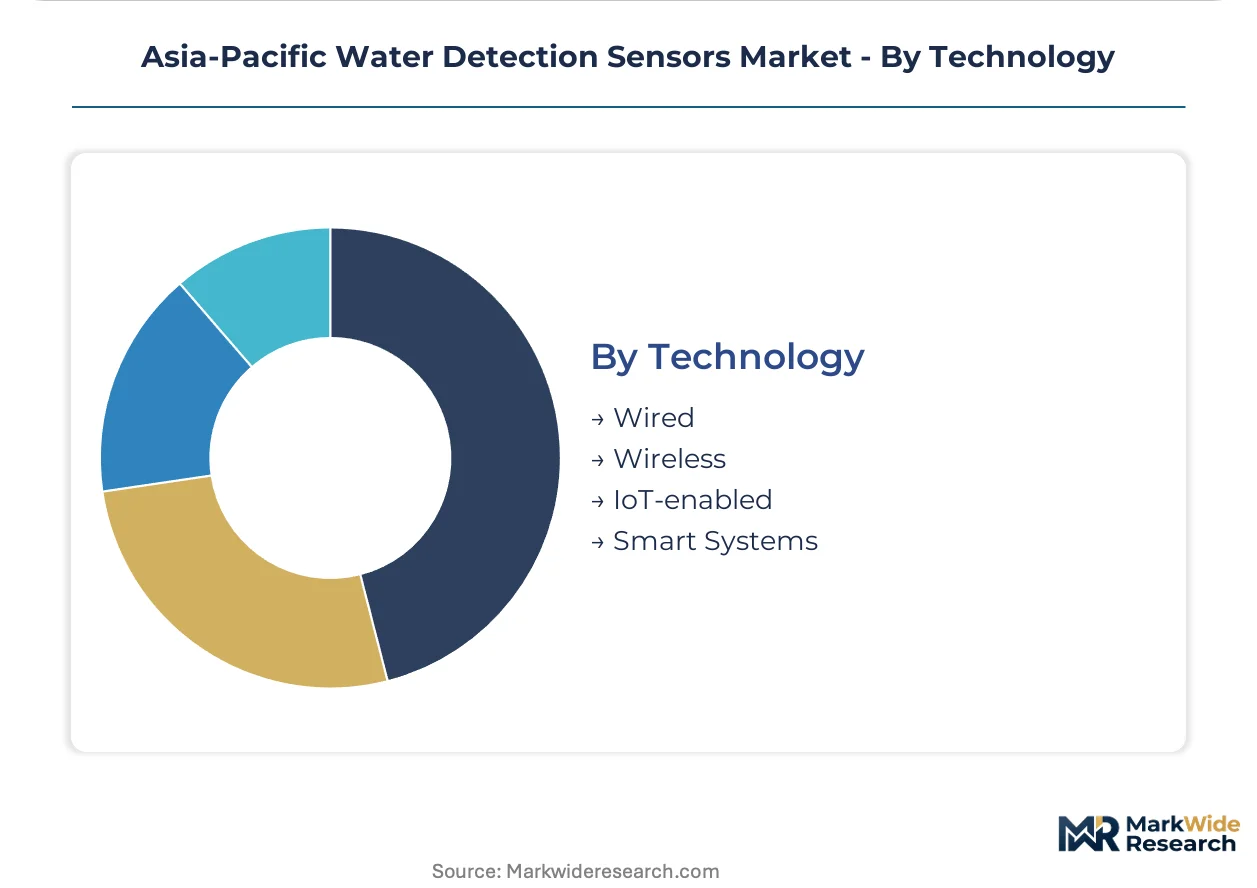
Technology:
Supply concentration for wireless chipsets and photonic components in East Asian contract manufacturers creates divergent availability timelines for wired versus connected platforms.
- IoT-enabled:Cloud-integrated analytics platforms with predictive maintenance algorithms compress replacement cycles for electromechanical sensors. Procurement concentrates in Australian mining water management where Rio Tinto and BHP bundle hardware, calibration, and analytics into per-cubic-meter fees.
- Smart Systems:Edge AI inference on-sensor enables anomaly detection without cloud dependency, critical for bandwidth-constrained deployments in Indonesia's outer islands and Philippine provincial utilities.
- Wireless:LoRaWAN and NB-IoT connectivity penetrates agricultural and flood monitoring applications where trenching for conduit is economically prohibitive.
- Wired:Legacy 4-20mA analog output persists in Southeast Asian SCADA infrastructure, resisting digital retrofit despite superior diagnostic capability of IO-Link alternatives.
Wired infrastructure retains the dominant installed base. IoT-enabled architectures are gaining share fastest as utilities abandon reactive maintenance schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers and municipal utilities across the Asia-Pacific region display divergent procurement priorities. State-owned enterprises in China's corridor cities prioritize certified optical systems for discharge compliance. Southeast Asian utilities favor cost-optimized acoustic and pressure-based leak detection networks. Australian mining operators transfer technology risk through service-integrated contracting models.
China
Semiconductor fabrication expansion in Shanghai and Hefei drives demand for ultrapure water monitoring with real-time TOC detection. The Ministry of Ecology and Environment ties wastewater discharge permits to continuous monitoring mandates, forcing facility-wide sensor retrofits. State-owned chemical enterprises in the Yangtze River Delta corridor cities are replacing aging pipeline infrastructure with certified optical detection systems.
Japan
Petrochemical corridors along the Keihin and Keiyo industrial zones require corrosion-resistant capacitive sensors for chemical processing environments. METI's national IoT acceleration framework channels subsidy funding toward miniaturized battery-operated detection nodes for agricultural irrigation networks. Rice cultivation cooperatives in Niigata and Akita prefectures pilot soil-moisture-linked flood detection arrays under this program.
India
Municipal corporations in Delhi, Mumbai, and Bangalore bundle leak detection sensors with AMR water meter deployments under smart city urban renewal frameworks. The Bureau of Indian Standards enforces electromagnetic compatibility and ingress protection certifications, with testing queues extending 14-18 weeks for smart water meter approvals. Domestic manufacturing concentrates on conductive sensor platforms for sub-dollar unit economics at municipal tender volume.
Australia
Mining water management operations in Western Australia's Pilbara region adopt asset-as-a-service contracting that bundles sensor hardware, calibration labor, and cloud analytics into per-cubic-meter processed water fees. Rio Tinto and BHP operations represent the most concentrated adoption geography for this model. The arrangement transfers obsolescence risk to vendors while locking buyers into multi-year data platform commitments.
Indonesia
Presidential directives targeting 20% non-revenue water reduction unlock municipal tender volume for acoustic and pressure-based leak detection networks. Battery-operated ultrasonic level sensors penetrate flood monitoring deployments where trenching for conduit is economically prohibitive. Northern Java corridor utilities face retrofit integration complexity with aging cast-iron distribution networks that resist standard sensor mounting configurations.
Asia-Pacific Water Detection Sensors Market Competitive Environment
Player mix skews toward diversified industrial automation conglomerates with process control heritage. The vendor base concentrates around three strategic archetypes: precision instrumentation specialists with optical detection platforms, integrated automation providers with calibration service networks, and component manufacturers leveraging MEMS fabrication scale. Competitive moves center on backward integration into sensor calibration capabilities and technology licensing partnerships for advanced photonic platforms.
Among Japanese-headquartered industrial automation providers, Yokogawa Electric Corporation and HORIBA, Ltd. occupy positions that exemplify the precision instrumentation archetype. Emerson Electric Co. represents the integrated automation model with service-network anchoring. Endress+Hauser Group Services AG sits within the European-origin specialist tier that competes on metrology traceability. Panasonic Corporation and TDK Corporation demonstrate the component-scale archetype with MEMS fabrication leverage.
| Leading Market Players |
|---|
| Yokogawa Electric Corporation |
| Emerson Electric Co. |
| Endress+Hauser Group Services AG |
| HORIBA, Ltd. |
| Panasonic Corporation |
| Toshiba Corporation |
| TDK Corporation |
| Hach Co., Ltd. |
| TTK - Leak Detection System |
| Others |
Value Chain & Pricing Dynamics
Silicon photonics-based refractive index sensors replacing electromechanical float architectures simultaneously relocates component sourcing to East Asian photonics foundries and compresses replacement cycle economics from seven-year to three-year intervals, redistributing pricing power toward optical subsystem vendors.
Pricing Analysis
Cost-plus contracts with photodiode and laser diode indexation dominate procurement for optical detection platforms in semiconductor fab applications. Pricing stratifies across premium optical TOC monitoring systems, standard capacitive chemical processing sensors, and economy conductive platforms for municipal AMR bundling. Cost compression in economy tiers intensifies as India's BIS certification queues extend commissioning timelines and freeze working capital. Municipal utilities in Southeast Asia exhibit highest price sensitivity, while Australian mining operators accept premium positioning for asset-as-a-service bundling.
Supply Chain Analysis
Japan and South Korea anchor precision optical component fabrication, while China concentrates MEMS conductive sensor die production and India assembles sub-dollar municipal meter bundles. Photodiode supply draws from East Asian contract manufacturers, with laser diodes and silicon photonics wafers feeding from Japanese and South Korean foundries. Single-source vulnerability concentrates in photonics-grade semiconductor substrates, exposing downstream assemblers to geopolitical logistics friction. Distribution runs through authorized calibration service networks anchored in Tokyo, Singapore, and Sydney, extending commissioning timelines for remote deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
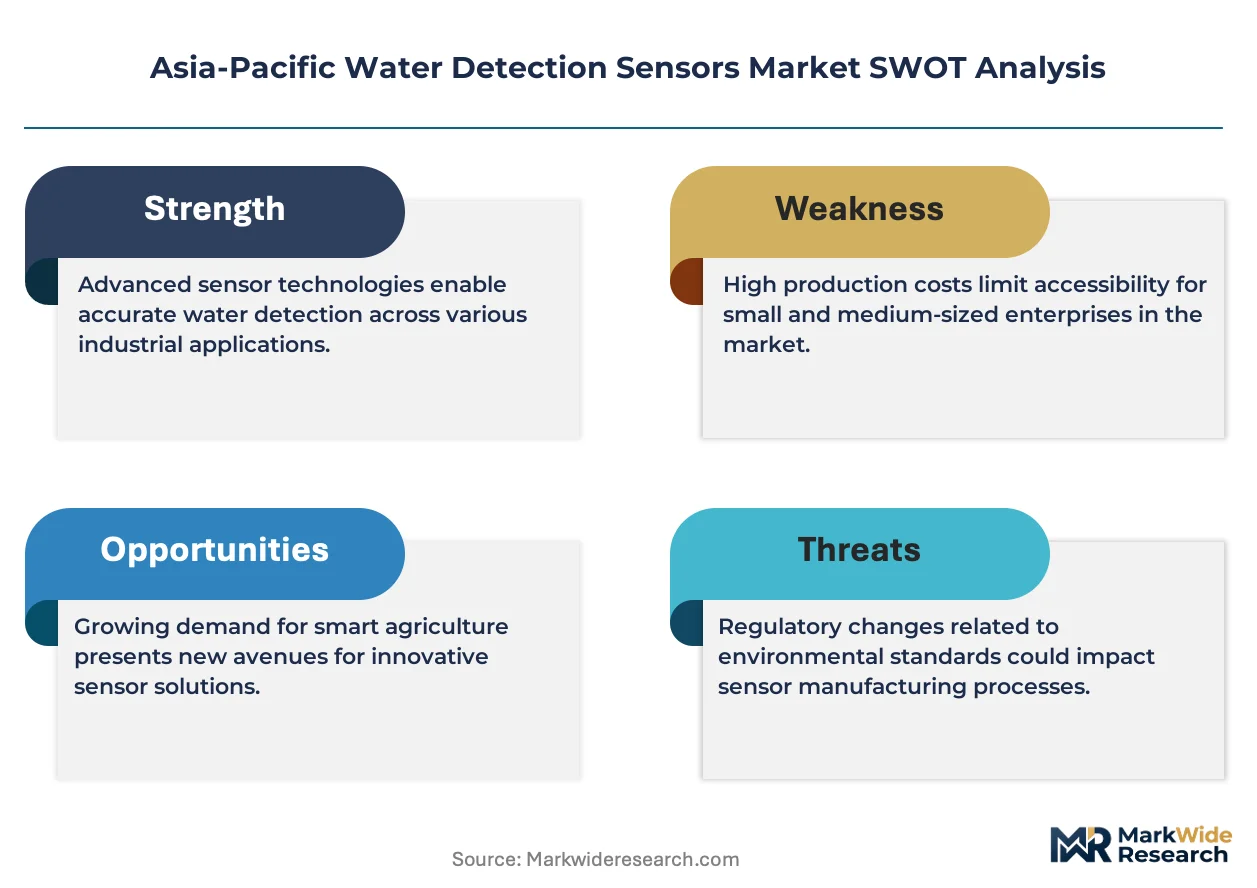
The Asia-Pacific water detection sensors market represents a high-growth disruption as China's MEE wastewater mandates force facility-wide retrofits and edge AI inference converges with low-power LoRaWAN transmission.
For Market Incumbents: Shield installed base relationships by backward integration into sensor calibration capabilities, countering the threat of asset-as-a-service contracting displacing capital expenditure procurement. Prioritize certification investment in India's BIS electromagnetic compatibility queue to defend municipal tender access against domestic manufacturing competitors.
For New Entrants and Emerging Players: Lead with edge AI inference integration for bandwidth-constrained deployments in Indonesia's outer islands and Philippine provincial utilities, where cloud dependency creates white-space vulnerability. Target Vietnam's northern industrial corridor expansion surrounding Hanoi for greenfield ultrapure water monitoring demand in foreign electronics manufacturing fabs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with precision instrumentation specialists holding optical detection platforms and established metrology traceability. Long-term viability over the coming decade hinges on technology licensing partnerships for silicon photonics architectures. Watch for MEE mandate expansion beyond semiconductor and chemical plants into food and beverage processing as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calibration Services | Emerson Electric's service-network anchoring compresses commissioning timelines for remote municipal deployments. |
| Technology Licensing Partnership | HORIBA's specialized optical platforms for semiconductor fabs enable premium positioning in South Korean and Taiwanese markets. |
| Edge AI Inference Development | On-sensor anomaly detection algorithms enable predictive maintenance without cloud dependency in Indonesian outer islands. |
| Asset-as-a-Service Contracting | Rio Tinto and BHP's per-cubic-meter fee structures transfer obsolescence risk while locking multi-year data commitments. |
| BIS Certification Fast-Track Investment | Domestic manufacturing concentration on conductive platforms accelerates municipal tender access in Delhi and Mumbai. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with municipal utility procurement directors, industrial plant engineers, sensor vendor product managers, and calibration laboratory metrologists; and secondary validation through China's MEE discharge permit databases, India's BIS certification records, Japan's METI IoT subsidy frameworks, and Australian mining water management contract disclosures. Bottom-up sensor shipment estimates triangulated against top-down municipal infrastructure spending allocations.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation dimensions spanning sensor type, application architecture, connectivity protocol, and end-user procurement modality. CAGRs derived from replacement cycle compression dynamics, regulatory mandate rollout velocity, and industrial capacity expansion trajectories. Semiconductor fab buildout schedules and non-revenue water reduction targets anchored regional demand projections.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of real-time monitoring mandates or accelerated photonics component supply diversification would require recalibration. Forecasts reflect assumptions on BIS certification queue durations, legacy SCADA retrofit resistance, and edge AI algorithm deployment timelines. Recalibration cycles align with material shifts in MEE mandate scope, METI subsidy program extensions, and Indonesia's presidential directive implementation progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Potentiometer Market
Sensors and Controls
MEMS Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Asia-Pacific Touch Sensor Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
US Smart Air Purifier Market
Sensors and Controls
Optical Chemical Sensor Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Distributed Fiber Optic Sensing Market