
 Piezoelectric Accelerometer Market | 2026-2036
Piezoelectric Accelerometer Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric Accelerometer Market Outlook
Asset-light leasing models for vibration test equipment is fragmenting competitive dynamics across the piezoelectric accelerometer landscape. PCB Piezotronics leverages extensive channel partnerships to sustain aftermarket calibration revenue streams. KISTLER anchors high-end quartz sensor production for European automotive powertrain testing. Bruel and Kjaer differentiates through integrated measurement chain solutions spanning transducers to analysis software.
A piezoelectric accelerometer converts mechanical vibration into an electrical charge via crystalline materials such as quartz or lead zirconate titanate, generating output proportional to acceleration with typical sensitivities ranging from 0.1 to 1000 mV/g. The device serves critical functions in structural health monitoring, engine diagnostics, and precision motion control where direct acceleration measurement determines system safety margins. Multi-axis configurations command premium positioning due to complexity in triaxial crystal stacking and cross-axis isolation engineering. Aerospace and automotive end-use segments absorb the majority of high-reliability units, with industrial automation representing an emerging volume tier where cost-optimized MEMS alternatives compete at lower performance thresholds.
FAA airworthiness directives mandate traceable calibration intervals for flight-critical vibration monitoring, compelling suppliers to maintain accredited laboratory networks. EASA implements parallel requirements through CS-25 certification standards, while REACH restricts certain piezoceramic compositions containing lead-based compounds. Stakeholders must evaluate material substitution roadmaps against performance degradation risks as regulatory timelines compress.
Market Dynamics
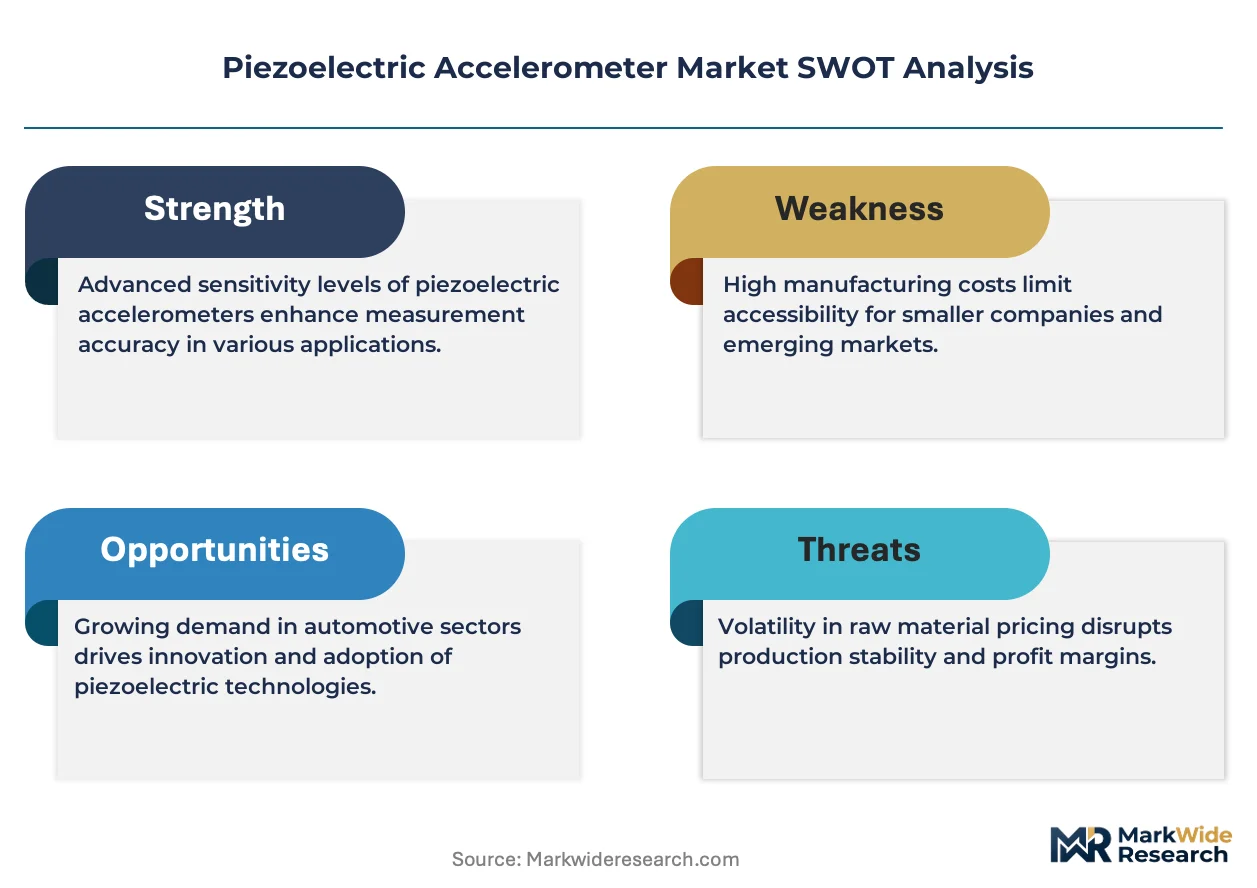
Calibration traceability mandates from FAA and EASA are compressing supplier qualification timelines while REACH material restrictions force crystalline composition redesigns, creating dual compliance pressure on piezoceramic manufacturers.
Growth Catalysts
- Airframe structural health monitoring:Aerospace OEMs in Germany and France are mandating continuous vibration sensing for predictive maintenance of composite wing structures and engine mounts.
- REACH substitution timelines:European ECHA deadlines for lead-free piezoceramics are accelerating R&D investment in potassium sodium niobate alternatives with comparable electromechanical coupling coefficients.
- Automotive powertrain electrification:Electric vehicle motor and inverter testing protocols in Japan and South Korea require triaxial accelerometers for NVH validation at rotational speeds exceeding internal combustion benchmarks.
Market Restraints
- Quartz crystal supply concentration:High-purity cultured quartz for reference-grade sensors concentrates among three Japanese and American suppliers, exposing procurement risk during geological or trade disruptions.
- MEMS price-floor competition:Capacitive MEMS accelerometers from semiconductor foundries satisfy 70% of industrial automation vibration monitoring at sensitivity thresholds below piezoelectric crossover points.
- Extended calibration infrastructure:ISO 17025-accredited laboratories require capital-intensive vibration exciters and laser interferometer reference systems that fragment service economics outside dense industrial clusters.
Strategic Opportunities
- India industrial automation penetration:BIS certification requirements for machinery safety are creating first-time demand for vibration monitoring in textile and metalworking SMEs across Gujarat and Tamil Nadu.
- Edge AI sensor fusion:Integration of piezoelectric transducers with onboard neural processing units enables real-time anomaly detection without external data acquisition hardware.
- CSRD reporting mandates:European corporate sustainability disclosure rules are expanding predictive maintenance budgets to reduce equipment replacement emissions, directly benefiting condition monitoring sensor deployment.
Industry Challenges
- Cross-axis isolation engineering:Triaxial accelerometer manufacturing demands sub-micron crystal alignment tolerances that strain metrology capabilities and yield rates.
- FAA calibration interval enforcement:Flight-critical applications require 12-month recertification cycles with documented traceability chains that burden aftermarket service capacity.
- Legacy analog infrastructure:Industrial facilities with 4-20 mA control systems face signal conditioning incompatibility with modern IEPE accelerometer outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric Accelerometer Market |
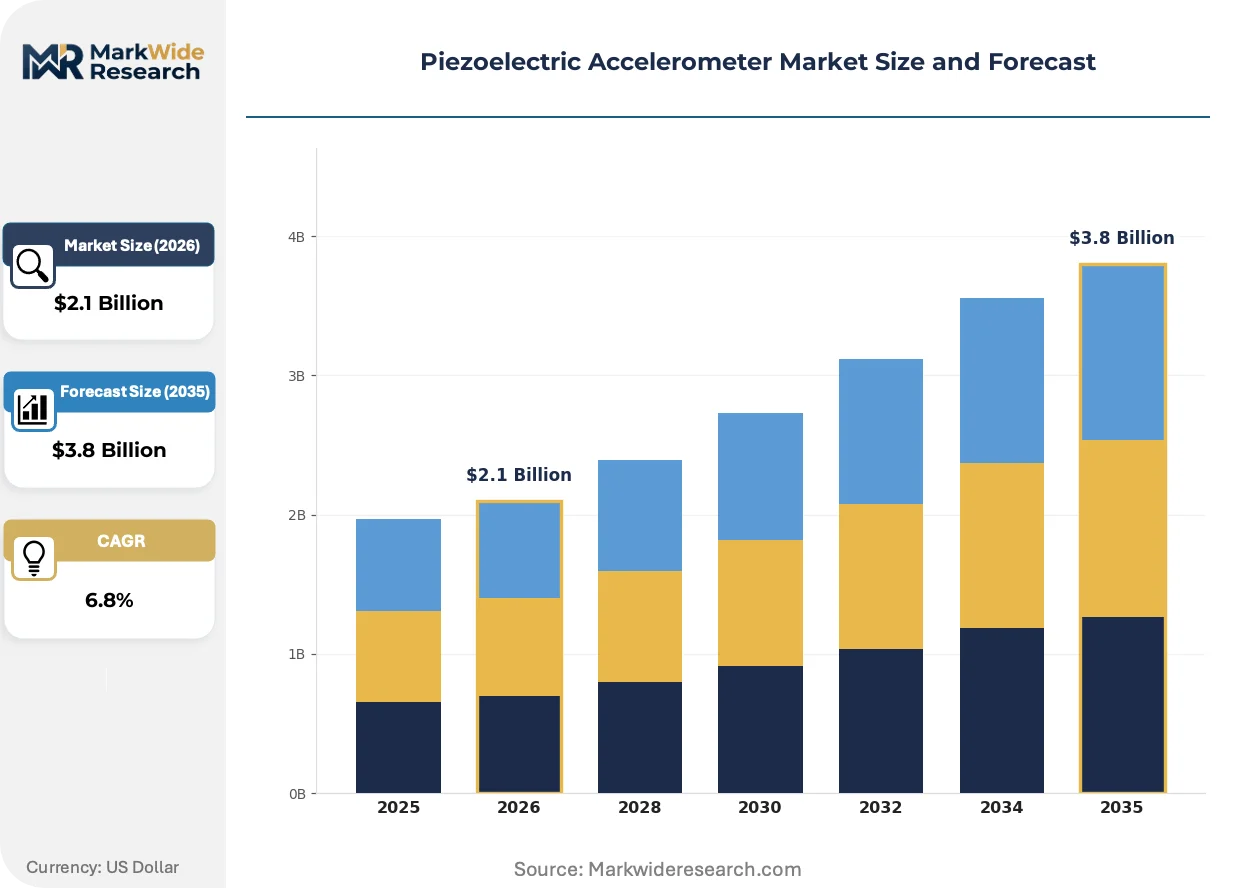
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Frequency, High-Frequency, Multi-Axis, Single-Axis End User: Aerospace, Automotive, Consumer Electronics, Industrial Automation Technology: MEMS, Quartz, PZT, Polymer-Based Application: Structural Health Monitoring, Vibration Testing, Motion Detection, Seismic Analysis |
| Companies Covered | PCB Piezotronics, Bruel and Kjaer, KISTLER, Meggitt Sensing Systems, Honeywell, TE Connectivity, Dytran Instruments, RION, Sinocera Piezotronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric Accelerometer Market Strategic Shifts
Silicon carbide substrate integration and wireless telemetry protocols are dissolving traditional boundaries between sensing elements and signal processing, compressing value chain capture points for established transducer specialists.
Thin-film piezoelectric deposition onto silicon wafers is rendering obsolete bulk ceramic machining for mid-sensitivity applications. Automotive tier-one suppliers in Germany and Japan are qualifying wafer-scale accelerometers for transmission and chassis modules. This manufacturing transition is compressing unit economics toward MEMS-like cost structures while retaining piezoelectric temperature stability.
EASA CS-25 certification standards now mandate digital twins for aircraft structural health data, forcing accelerometer suppliers to embed calibration coefficients in machine-readable formats. This regulatory architecture is fragmenting procurement between hardware-agnostic software platforms and integrated measurement chains. European MRO providers are consolidating sensor vendor lists to simplify data governance compliance.
Equipment-as-a-service contracts in vibration testing are unbundling capital expenditure into operational line items. Aerospace and automotive R&D departments in France and the United States are leasing shaker tables and data acquisition systems with embedded accelerometer refresh cycles. This financing restructuring is shortening replacement intervals and concentrating aftermarket revenue with lessors who control calibration scheduling.
Piezoelectric Accelerometer Market Segmentation
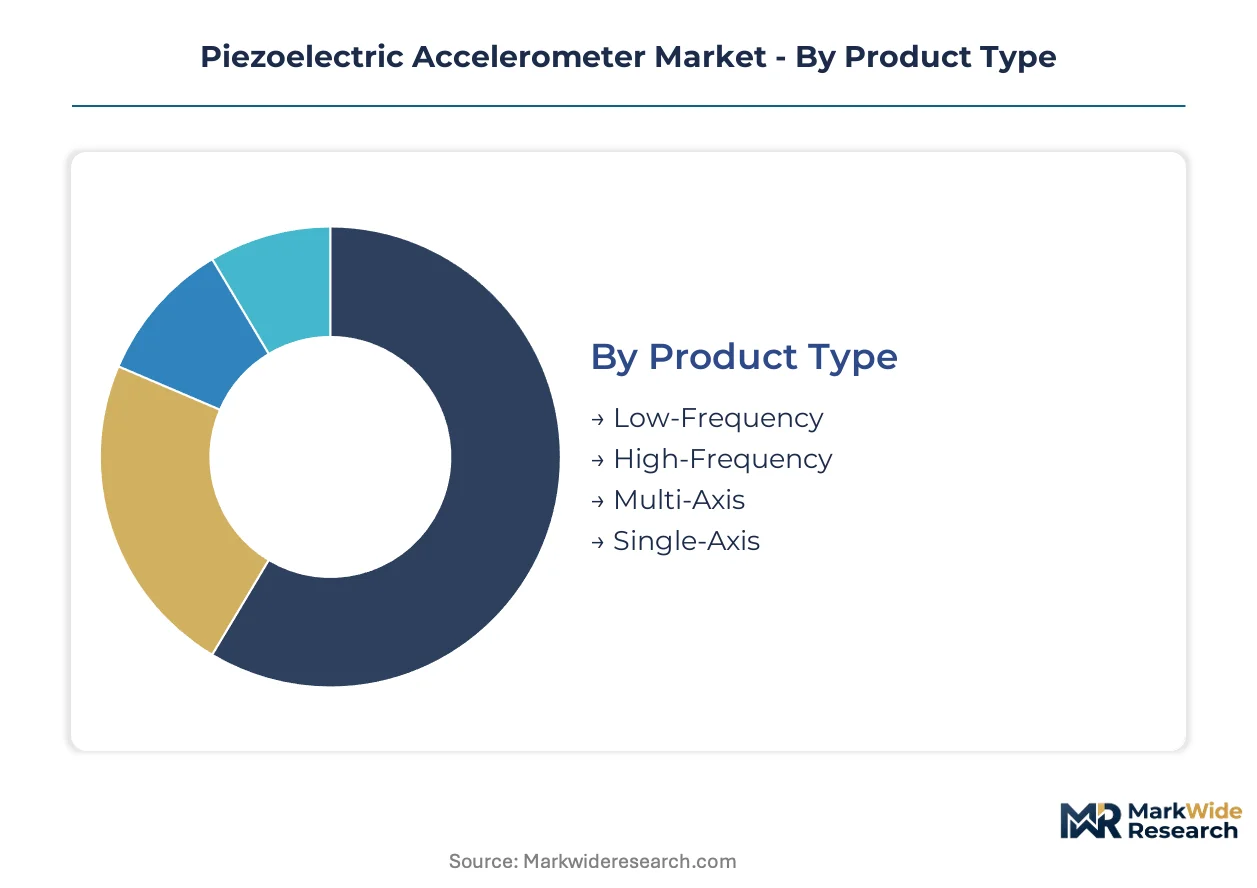
Piezoelectric accelerometer procurement patterns diverge sharply across frequency response requirements, end-use reliability thresholds, and crystalline material specifications. Understanding these segment boundaries clarifies why aerospace buyers reject MEMS alternatives while industrial automation gravitates toward cost-optimized configurations.
Product Type:
Frequency response requirements span seismic-grade motion capture to ultrasonic vibration diagnostics, with axis configuration determining mechanical integration complexity and unit economics.
- Multi-Axis:Triaxial crystal stacking with sub-micron alignment tolerances enables simultaneous X-Y-Z acceleration capture in a single housing. Aerospace OEMs in Germany and France specify these for engine mount monitoring where cross-axis vibration isolation determines safety margins. FAA calibration traceability mandates compress supplier qualification timelines for flight-critical deployments.
- High-Frequency:Resonant frequencies exceeding 50 kHz suit gearbox diagnostics and bearing defect detection in rotating machinery. Automotive powertrain electrification in Japan and South Korea is accelerating NVH validation protocols that demand ultrasonic-range sensitivity for electric motor testing.
- Low-Frequency:Sub-1 Hz response characteristics serve seismic monitoring and large civil structure applications.
- Single-Axis:Uniaxial designs dominate cost-sensitive industrial automation where directional vibration monitoring suffices.
Established volume favors single-axis configurations in factory automation; emerging adoption favors multi-axis units in aerospace predictive maintenance programs.
End User:
Reliability certification tiers and operational criticality separate price-insensitive aerospace procurement from volume-driven industrial segments.
- Aerospace:Flight-critical applications mandate EASA CS-25 and FAA airworthiness compliance with 12-month recalibration cycles and documented traceability chains. Composite airframe health monitoring in France and Germany absorbs premium quartz sensors for wing structure predictive maintenance. REACH material restrictions are forcing crystalline composition redesigns ahead of ECHA substitution deadlines.
- Automotive:Powertrain electrification protocols in Japan require triaxial accelerometers for inverter NVH validation at rotational speeds exceeding internal combustion benchmarks. Wafer-scale piezoelectric deposition is compressing unit economics toward MEMS-like cost structures while retaining temperature stability.
- Industrial Automation:Capacitive MEMS alternatives satisfy sensitivity thresholds below piezoelectric crossover points in 70% of machinery monitoring applications.
- Consumer Electronics:Miniaturization demands and extreme cost pressure relegate this segment to MEMS-dominated solutions with limited piezoelectric penetration.
Mature procurement patterns dominate automotive testing; steepest expansion trajectory appears in aerospace structural health monitoring mandates.
Technology:
Crystalline material selection governs temperature stability, electromechanical coupling efficiency, and regulatory compliance exposure across the technology stack.
- Quartz:Cultured synthetic crystals deliver exceptional thermal stability and low pyroelectric noise for reference-grade metrology. High-purity supply concentrates among Japanese and American producers, exposing procurement risk during geological or trade disruptions. European automotive powertrain testing anchors demand for KISTLER's quartz sensor production.
- PZT:Lead zirconate titanate compositions offer superior electromechanical coupling coefficients but face REACH restriction timelines. ECHA deadlines are accelerating potassium sodium niobate alternative development with comparable performance metrics.
- MEMS:Semiconductor foundry production enables volume economics that piezoelectric architectures cannot match at industrial automation sensitivity thresholds.
- Polymer-Based:Flexible substrate compatibility suits conformal wearable and biomedical applications with modest performance requirements.
Performance-critical applications favor quartz; regulatory pressure is displacing PZT toward lead-free alternatives fastest.
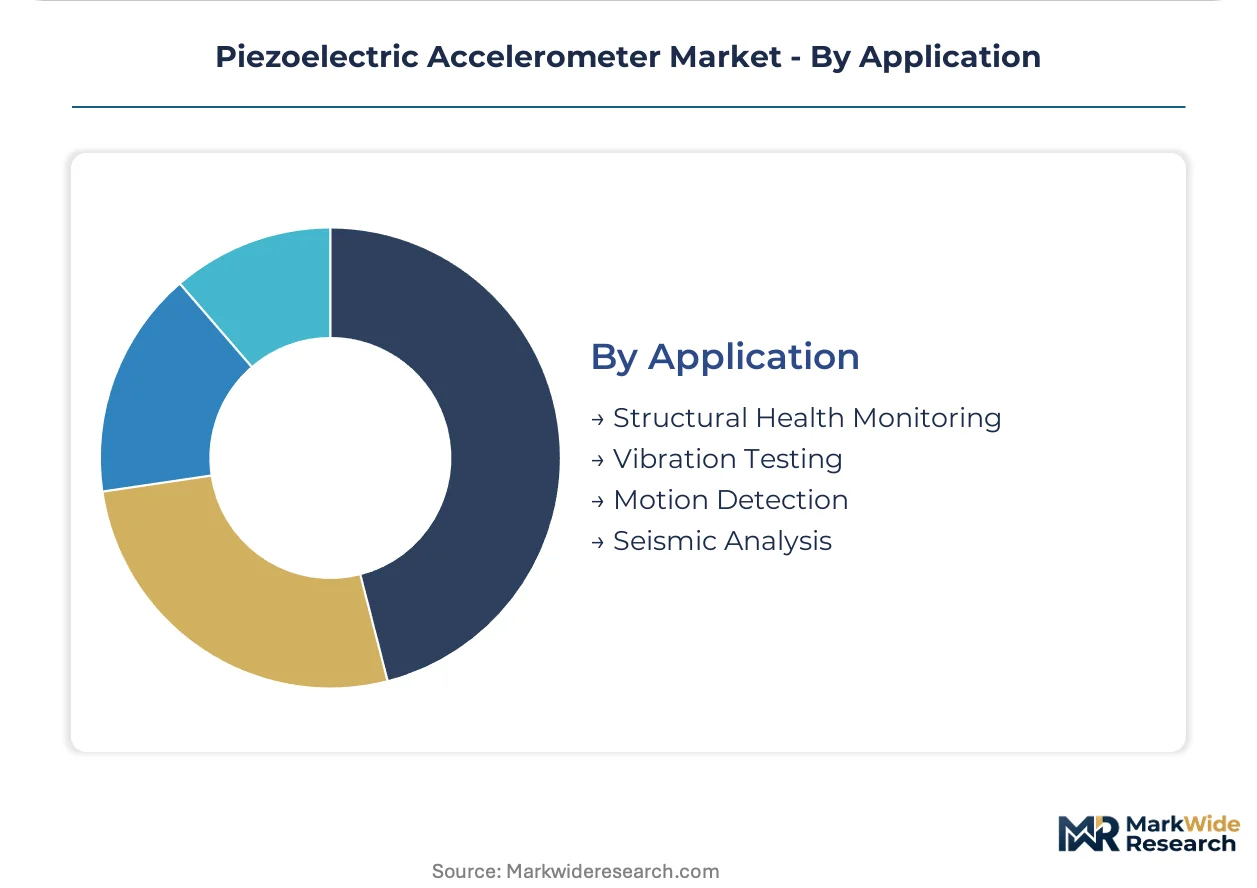
Application:
Use-case specificity determines signal conditioning requirements, environmental sealing grades, and integration with external analysis infrastructure.
- Structural Health Monitoring:Continuous vibration sensing for predictive maintenance of bridges, airframes, and wind turbine blades demands ruggedized packaging and long-term stability. CSRD reporting mandates in Europe are expanding predictive maintenance budgets to reduce equipment replacement emissions. EASA digital twin requirements now force embedded calibration coefficients in machine-readable formats.
- Vibration Testing:Laboratory and production-line shaker table applications require traceable calibration intervals with ISO 17025-accredited laboratory networks. Equipment-as-a-service contracts in France and the United States are unbundling capital expenditure into operational line items with embedded sensor refresh cycles.
- Motion Detection:Industrial robotics and precision positioning systems require high-frequency response with minimal phase distortion.
- Seismic Analysis:Geophysical exploration and earthquake monitoring demand ultra-low-frequency response with exceptional noise floors.
Regulatory compliance investment favors structural health monitoring; service model innovation favors vibration testing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-heavy economies in Germany and Japan supply precision quartz sensors to aerospace OEMs in France and the United States, while India and South Korea emerge as net importers of high-reliability units for automotive electrification programs.
Germany
Automotive powertrain testing and industrial automation clusters in Stuttgart and Munich drive procurement of triaxial quartz sensors. REACH compliance deadlines from ECHA are compressing substitution timelines for lead-free piezoceramics. Baden-Württemberg hosts concentrated R&D activity for potassium sodium niobate alternatives.
United States
FAA airworthiness directives mandate traceable calibration intervals for flight-critical vibration monitoring in commercial and defense aerospace. Boeing and Lockheed Martin supply chains in Washington State and Texas absorb premium multi-axis units. PCB Piezotronics leverages extensive channel partnerships to sustain aftermarket calibration revenue streams.
Japan
High-purity cultured quartz supply concentrates among domestic producers, exposing global procurement risk during trade disruptions. Automotive OEMs in Toyota City and Yokohama specify accelerometers for electric motor NVH validation. METI industrial standards anchor qualification protocols for powertrain electrification testing.
France
Airbus structural health monitoring mandates for composite wing assemblies drive demand for reference-grade sensors. EASA CS-25 certification standards require embedded calibration coefficients in machine-readable formats. Toulouse and Nantes aerospace clusters concentrate predictive maintenance sensor deployment.
India
BIS certification requirements for machinery safety are creating first-time demand for vibration monitoring in textile and metalworking SMEs. Gujarat and Tamil Nadu industrial zones represent emerging volume tiers where cost-optimized configurations compete with MEMS alternatives. Central government PLI schemes for manufacturing are accelerating automation adoption.
Piezoelectric Accelerometer Market Competitive Environment
On the supply side, the industry is structured around three tiers: premium quartz specialists, integrated measurement chain providers, and volume-oriented industrial suppliers. Strategic archetypes include calibration-service-anchored players, wafer-scale thin-film innovators, and MEMS-competing cost optimizers. Dominant competitive moves encompass backward integration into crystal cultivation and strategic partnerships with aerospace OEMs for digital twin integration.
Within the premium-tier vector, KISTLER anchors European quartz sensor production for automotive powertrain testing, while Bruel and Kjaer exemplifies the integrated measurement chain archetype spanning transducers to analysis software. PCB Piezotronics occupies a position as a calibration-service-anchored player with extensive channel partnerships. These three represent distinct strategic postures rather than direct substitutability.
| Leading Market Players |
|---|
| PCB Piezotronics |
| Bruel and Kjaer |
| KISTLER |
| Meggitt Sensing Systems |
| Honeywell |
| TE Connectivity |
| Dytran Instruments |
| RION |
| Sinocera Piezotronics |
| Others |
Value Chain & Pricing Dynamics
The Yokohama-Hamburg maritime corridor carries high-purity cultured quartz from Japanese suppliers to European automotive powertrain testing clusters, with freight cost volatility amplifying procurement risk for German OEMs while compressing margins on reference-grade sensor shipments. This logistics tension concentrates pricing power among three dominant crystal cultivators and forces tiered pricing stratification across certification-grade, industrial-grade, and cost-optimized MEMS-competing tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with aerospace procurement absorbing premium quartz sensors at price points insulated from MEMS competition by FAA calibration traceability mandates. Price differentiation rests on certification grade and volume scale, with flight-critical units commanding multiples over factory automation alternatives. Cost compression in the industrial tier is intensifying because semiconductor foundries are flooding the market with capacitive MEMS alternatives at sensitivity thresholds below piezoelectric crossover points. Automotive powertrain testing departments exhibit least price sensitivity due to electrification protocol mandates, while textile and metalworking SMEs in India represent the most price-constrained demand pool.
Supply Chain Analysis
High-purity cultured quartz feedstock concentrates among Japanese and American producers, with synthetic crystal cultivation drawing from mineral-grade silicon feedstocks and proprietary growth furnace technologies. Piezoceramic compositions rest on lead zirconate titanate and emerging potassium sodium niobate alternatives, while precision machining equipment for crystal alignment is anchored in German and Swiss manufacturing clusters. Single-source vulnerability runs through the Japanese quartz supply base, exposing downstream pricing to trade disruption or geological events. Distribution runs through authorized channel partners with embedded calibration service contracts, consolidating aftermarket revenue with regional specialists who control ISO 17025-accredited laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Piezoelectric accelerometer demand sits in early-cycle expansion as EASA digital twin mandates and CSRD predictive maintenance reporting obligations create first-time structural health monitoring procurement across European aerospace and industrial asset bases.
For Market Incumbents: Build calibration-service moats by expanding ISO 17025-accredited laboratory networks into underserved industrial clusters, capturing recurring revenue from FAA-mandated 12-month recertification cycles. Deepen backward integration into synthetic quartz cultivation to reduce exposure to Japanese supply concentration. MEMS price-floor competition threatens industrial automation volumes; defend by bundling edge AI sensor fusion capabilities that capacitive alternatives cannot replicate. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu industrial zones offer white-space penetration as BIS machinery safety certification creates first-time vibration monitoring demand among textile and metalworking SMEs. Wafer-scale thin-film piezoelectric deposition for automotive chassis modules represents a second penetrable entry point where MEMS temperature instability disqualifies semiconductor alternatives. A calibration-service-anchored go-to-market model, leasing equipment with embedded sensor refresh cycles, unbundles capital barriers for price-constrained buyers. For Investors and Strategic Acquirers: Specialist calibration-service providers with dense regional laboratory footprints represent the most defensible acquisition archetype, capturing recurring revenue from regulatory-mandated recertification cycles with limited substitution risk. Long-term viability over a multi-year horizon depends on positioning against REACH material substitution timelines and FAA-EASA calibration traceability enforcement expansion. Watch ECHA lead-free piezoceramic deadline acceleration as the critical inflection signal for potassium sodium niobate alternative qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Cultivation | Captive supply of high-purity quartz reduces Japanese procurement concentration risk for European automotive testing clusters. |
| Edge AI Sensor Fusion Development | Onboard neural processing units enable real-time anomaly detection without external data acquisition hardware, differentiating against MEMS alternatives. |
| Calibration Laboratory Network Expansion | ISO 17025-accredited facilities in industrial clusters capture recurring FAA-mandated recertification revenue from flight-critical applications. |
| Wafer-Scale Thin-Film Deposition Qualification | Automotive tier-one supplier adoption for transmission modules compresses unit economics toward MEMS-like cost structures. |
| Digital Twin Data Format Integration | EASA CS-25 embedded calibration coefficient mandates fragment procurement toward hardware-agnostic software platforms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aerospace procurement managers, automotive NVH validation engineers, industrial automation plant engineers, and aftermarket calibration service heads. Secondary validation drew from FAA airworthiness directive filings, EASA CS-25 certification standards documentation, ECHA REACH substitution timeline announcements, and customs trade data for high-purity quartz imports. Bottom-up segment sizing across product type, end user, technology, and application dimensions was triangulated against top-down macroeconomic indicators for industrial automation and aerospace capital expenditure.
Forecast calibration employed a multi-dimensional analytical framework spanning frequency response requirements, crystalline material specifications, and regional regulatory compliance clusters across the projection horizon. Segmentation modeling incorporated axis configuration complexity, reliability certification tiers, and calibration traceability enforcement intensity as structural drivers. CAGRs were derived from elasticity-adjusted demand curves calibrated to OEM procurement survey data and equipment-as-a-service contract penetration rates in vibration testing applications.
Practitioners should monitor ECHA lead-free piezoceramic deadline revisions, FAA calibration interval enforcement expansion, and MEMS sensitivity threshold advancement for early signals requiring forecast adjustment. Cross-checking against IHS Markit aerospace production databases and automotive powertrain electrification program announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Global Battery Free RFID Sensor Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Absolute Encoders Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Smart Haptic Devices Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Global Wireless Sensors Network Market