
 Europe Optical Sensors Market | 2026-2036
Europe Optical Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Optical Sensors Market Foresight
Industrial automation buyers is bifurcating from consumer electronics as the dominant demand archetype in Europe. Sick AG dominates factory-floor sensing with deep vertical integration into German automotive lines. ams-OSRAM AG leverages its photonics heritage to anchor premium image sensor supply for machine vision. STMicroelectronics competes through MEMS-integrated optical platforms that sustain design wins across Continental industrial OEMs.
Europe optical sensors are photoelectric devices that detect, measure, or convert light signals into electrical output using semiconductor junctions, fiber optic waveguides, or laser diodes, typically operating across ultraviolet to infrared spectra with response times in microseconds. Their primary commercial purpose is enabling non-contact precision measurement, object detection, and ambient sensing in environments where mechanical probes fail or contaminate processes. Image sensors command the largest value pool due to machine vision proliferation, while fiber optic sensors represent the fastest-expanding category as EU industrial operators replace electrical instrumentation in hazardous ATEX zones. Active optical technology leads volume deployment, though passive optical architectures gain share in energy-constrained safety applications.
EMA device standards, REACH substance restrictions, and CE marking under the EU Machinery Directive collectively shape product certification timelines and material selection for European optical sensor manufacturers. The EU AI Act introduces conformity requirements for autonomous sensing systems that process environmental data in critical infrastructure. Stakeholders must monitor how ECHA substance-of-very-high-concern listings affect specialty coating supply chains for sensor housings and optical windows.
Market Dynamics
EU Green Deal carbon targets and REACH substance phase-outs are forcing sensor manufacturers to redesign optical housings and eliminate mercury-based detection elements, compressing certification timelines while opening premium positioning for compliant suppliers.
Growth Catalysts
- Machine vision proliferation:German automotive OEMs are deploying high-resolution image sensors for defect detection at welding stations. Quality control mandates from KBA are accelerating factory-floor upgrades.
- Fiber optic sensor replacement:ATEX zone operators in France and Italy are swapping electrical instrumentation for passive optical architectures. REACH restrictions on spark-risk electrical components support this transition.
- EU AI Act conformity:Critical infrastructure operators must certify autonomous sensing systems processing environmental data. This creates certified product tiers that command pricing premiums.
Market Restraints
- Specialty coating supply concentration:ECHA substance-of-very-high-concern listings threaten supply chains for sensor optical windows and anti-reflective coatings. German and French coating specialists face reformulation costs.
- Indium phosphide wafer scarcity:Laser diode production depends on constrained III-V compound semiconductor substrates. European foundries lack captive supply of these wafers.
- Mercury-free technology gaps:UV-C detection applications still rely on mercury-vapor reference standards despite RoHS phase-out deadlines. Alternative solid-state UV sensors carry 40-60% cost premiums.
Strategic Opportunities
- Italian industrial automation corridors:Emilia-Romagna and Lombardy machinery clusters show underpenetrated demand for predictive maintenance sensors. Local system integrators seek photonics partners.
- MEMS-optical convergence:Combining microelectromechanical structures with photonic integrated circuits enables chip-scale spectrometers. This opens food safety and pharmaceutical process monitoring applications.
- CSRD disclosure mandates:Corporate sustainability reporting requirements drive demand for energy-efficient sensor networks. Suppliers offering consumption-transparent product lines capture ESG procurement budgets.
Industry Challenges
- Photonics packaging skill scarcity:European manufacturers compete for technicians skilled in hermetic sealing and fiber pigtailing. Technical universities in Germany and France have not scaled training programs to match demand.
- CE marking timeline compression:EU Machinery Directive conformity assessments now average 14-18 months for novel optical sensing architectures. This delays revenue recognition for product development cycles.
- Legacy PLC integration friction:Brownfield factory installations require protocol translation between modern optical sensor outputs and 1990s-era programmable logic controllers. System integrators bear integration cost overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Optical Sensors Market |
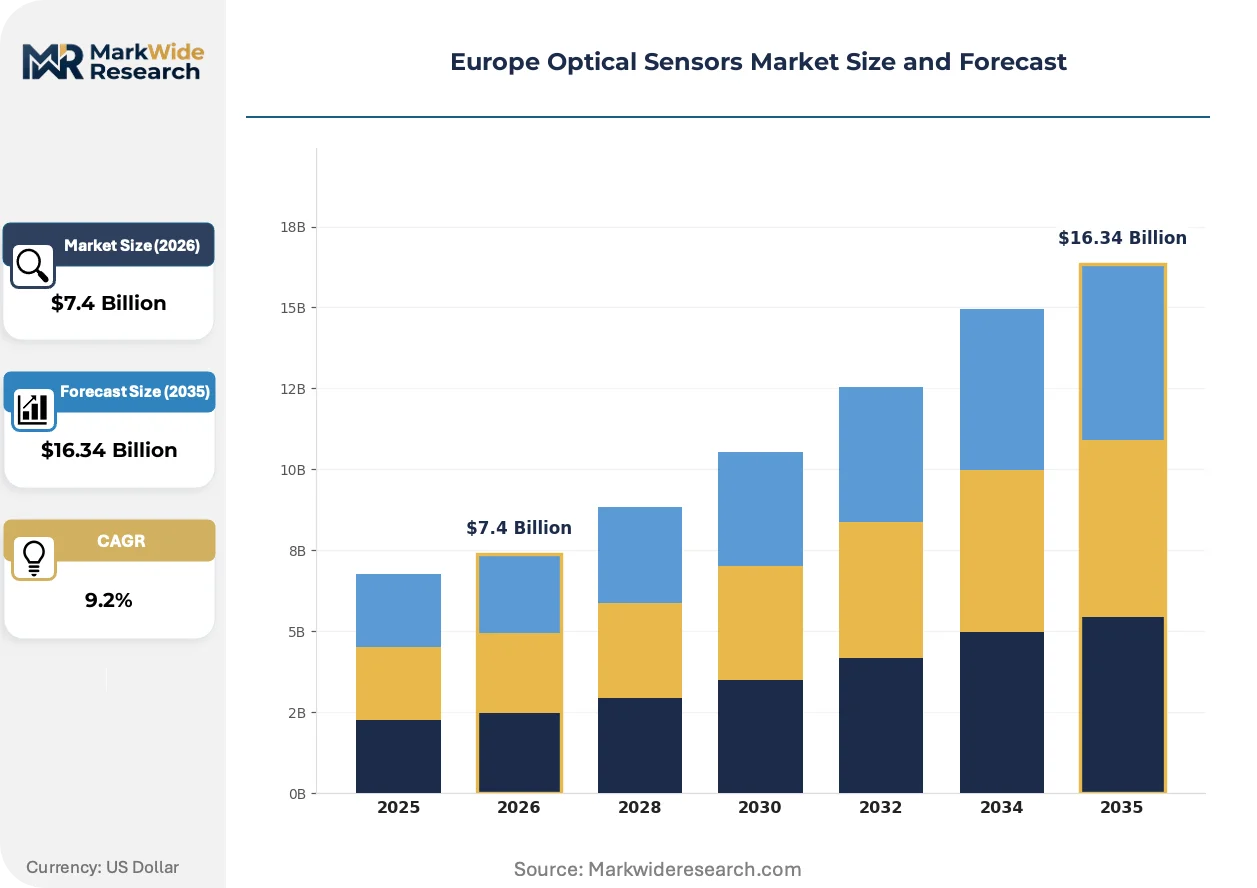
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $16.34 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Sensors, Image Sensors, Proximity Sensors, Fiber Optic Sensors Technology: Active Optical, Passive Optical, Digital Optical, Analog Optical End User: Consumer Electronics, Automotive OEMs, Aerospace, Industrial Automation Application: Motion Detection, Environmental Monitoring, Healthcare, Safety & Security |
| Companies Covered | Sick AG, Honeywell International Inc, Rockwell Automation, ams-OSRAM AG, STMicroelectronics, Bosch Sensortec GmbH, First Sensor AG, Turck, Hamamatsu Photonics K.K., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Optical Sensors Market Shifts & Advancements
Photonics integration and regulatory compliance are reshaping competitive positioning in European optical sensing. Three developments merit particular attention.
Solid-state LiDAR architectures are bifurcating from mechanical scanning systems in industrial distance measurement. German logistics operators are adopting MEMS-based beam steering for warehouse automation. This compression of moving parts is enabling maintenance-free deployment cycles exceeding 50,000 hours.
REACH authorization requirements for chromium trioxide in sensor housing coatings are forcing material transitions. ECHA sunset dates for these substances in 2024-2026 have triggered aluminum anodizing and PVD coating investments. Italian sensor housing suppliers are most exposed given their concentration in decorative chrome finishing.
Buying committees in French aerospace and German automotive are consolidating vendor relationships around full-stack sensing partners. Distributors with component-only catalogs are losing access to specification processes. This concentration is most visible in Munich and Toulouse engineering centers where multi-year framework agreements now predominate.
Europe Optical Sensors Market Segmentation
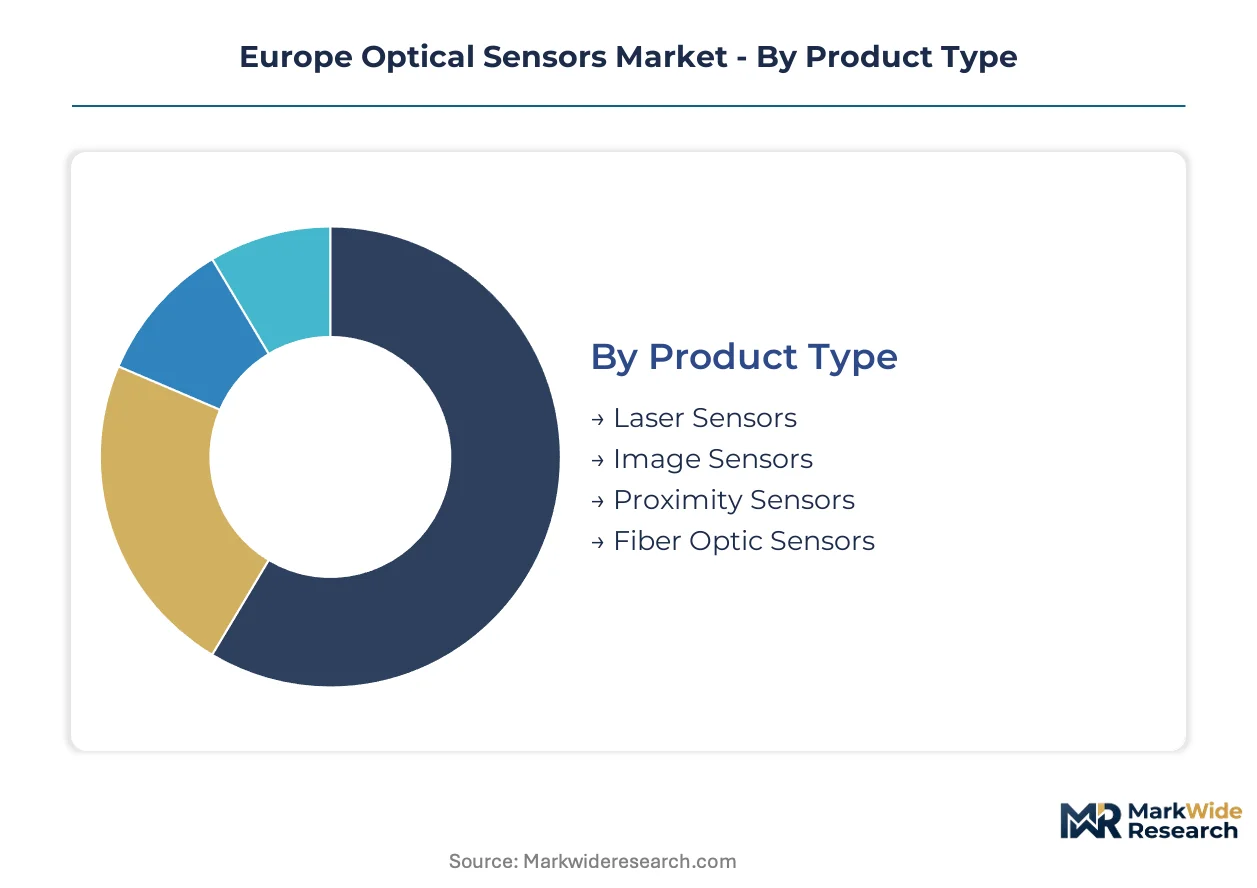
Optical sensor procurement in Europe flows through distinct channel architectures that vary by segment complexity and certification burden. Industrial buyers in Germany and France consolidate purchases through system integrators, while automotive OEMs engage directly with qualified tier-one suppliers.
Product Type:
Channel distribution varies sharply across product categories, with high-specification laser and image sensors moving through authorized distributor networks and fiber optic sensors increasingly sourced through specialized photonics integrators.
- Laser Sensors:These devices emit coherent light beams to measure distance, displacement, or surface characteristics with micrometer precision. German automotive OEMs at welding stations in Stuttgart and Munich clusters drive concentrated demand for time-of-flight variants. REACH compliance for housing materials compresses supplier qualification timelines.
- Image Sensors:Semiconductor arrays convert optical signals into digital image data, spanning CMOS and CCD architectures. Machine vision deployments in French aerospace manufacturing at Toulouse engineering centers anchor premium demand. KBA quality mandates accelerate factory-floor replacement cycles.
- Proximity Sensors:Photoelectric devices detect object presence without physical contact through reflected or interrupted light beams.
- Fiber Optic Sensors:Passive architectures transmit light through silica waveguides for measurement in explosive ATEX zones. Italian industrial corridors in Emilia-Romagna show accelerating replacement of electrical instrumentation.
By volume, Image Sensors leads. By growth pace, Fiber Optic Sensors is expanding most quickly.
Technology:
Cost tier differentiation separates these architectures, with active optical commanding premium positioning for precision applications and passive optical gaining share in cost-constrained safety deployments.
- Active Optical:Self-illuminated systems incorporating laser diodes or LEDs with onboard signal processing electronics. MEMS-integrated platforms from European foundries sustain design wins across Continental industrial OEMs. Indium phosphide wafer scarcity constrains laser diode production scaling.
- Passive Optical:Externally powered architectures relying on ambient light or fiber-coupled sources, eliminating electrical components at sensing points. ATEX zone operators in France prioritize these for intrinsic safety compliance.
- Digital Optical:Output interfaces communicate through standardized digital protocols enabling direct PLC integration.
- Analog Optical:Continuous voltage or current outputs require signal conditioning for modern control systems.
By installed base, Active Optical dominates. By share gain rate, Passive Optical is climbing the fastest.
End User:
Customer type determines specification authority, with automotive and aerospace buyers retaining direct vendor relationships while industrial automation channels through system integrators.
- Automotive OEMs:German manufacturers deploy high-resolution sensing at paint inspection and welding quality stations. Multi-year framework agreements now predominate in Munich engineering centers.
- Industrial Automation:Machinery clusters in Lombardy and Emilia-Romagna seek predictive maintenance sensor partners. Brownfield installations face protocol translation friction with legacy PLCs.
- Consumer Electronics:Smartphone and wearable manufacturers drive volume demand for compact ambient light and proximity modules.
- Aerospace:French airframe and engine manufacturers specify hermetic-grade sensors for flight-critical monitoring.
By procurement value, Automotive OEMs leads. By expansion trajectory, Industrial Automation shows steepest gains.
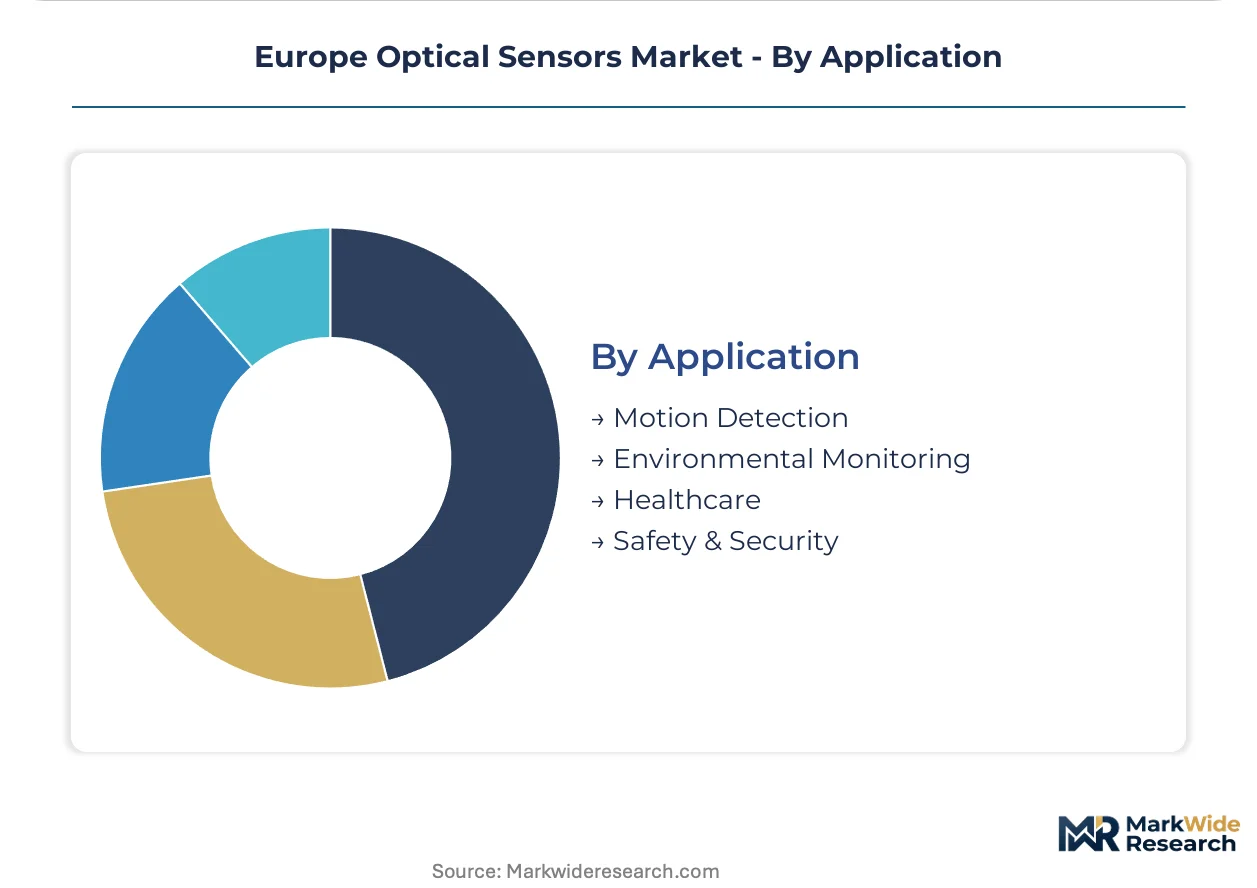
Application:
Margin profiles diverge across applications, with healthcare and aerospace sustaining premium pricing while motion detection commoditizes toward volume manufacturing economics.
- Safety & Security:Perimeter monitoring and machine safeguarding applications demand fail-safe optical architectures with SIL certification. EU Machinery Directive CE marking averages 14-18 months for novel sensing designs.
- Healthcare:Non-invasive diagnostic and patient monitoring applications require biocompatible housings and EMC compliance. EMA device standards shape product certification timelines.
- Motion Detection:Industrial automation and building automation systems deploy these for presence sensing and energy management.
- Environmental Monitoring:Air quality and emissions sensing applications face CSRD disclosure mandate tailwinds.
By average selling price, Safety & Security commands premium positioning. By demand acceleration, Healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube canal network and trans-European transport corridors position Central Europe as the primary logistics backbone for optical sensor distribution across the continent.
Germany
Machine vision deployments at welding stations and paint inspection lines drive concentrated procurement from Stuttgart and Munich automotive clusters. KBA quality mandates accelerate factory-floor sensor replacement cycles. Bavaria's engineering centers host multi-year framework agreements consolidating vendor relationships around full-stack sensing partners.
France
Aerospace manufacturers at Toulouse engineering centers specify hermetic-grade sensors for flight-critical monitoring applications. ANSM and CNIL data governance requirements shape conformity assessment timelines for autonomous sensing systems. The Provence-Alpes-Côte d'Azur corridor shows accelerating fiber optic sensor adoption for ATEX zone compliance.
Italy
Industrial automation corridors in Emilia-Romagna and Lombardy machinery clusters seek predictive maintenance sensor partnerships. REACH authorization deadlines for chromium trioxide trigger coating reformulation investments among sensor housing suppliers. Milan-based system integrators bridge brownfield PLC integration gaps for optical sensor deployments.
United Kingdom
London and Southeast research centers drive demand for MEMS-optical convergence platforms in pharmaceutical process monitoring. MHRA device standards and post-Brexit UKCA marking requirements extend certification timelines for novel sensing architectures. Midlands manufacturing hubs concentrate on safety-certified optical architectures for machinery safeguarding.
Netherlands
Eindhoven Region photonics clusters anchor chip-scale spectrometer development for food safety applications. CSRD disclosure mandates drive procurement of energy-efficient sensor networks from Rotterdam port logistics operators. Randstad distribution hubs manage cross-border sensor shipments to German and Belgian industrial customers.
Europe Optical Sensors Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth and vertical market focus. The vendor base stratifies into three tiers: diversified electronics conglomerates with captive sensor divisions, pure-play photonics specialists with deep application expertise, and regional system integrators with localization capabilities. Strategic moves concentrate on MEMS-optical convergence partnerships and REACH-compliant material transitions. M&A activity targets fiber optic sensing specialists with ATEX certification assets.
Within the factory-floor sensing tier, Sick AG exemplifies deep integration into German automotive production lines. ams-OSRAM AG occupies a position bridging photonics heritage with premium image sensor supply. STMicroelectronics represents the diversified semiconductor conglomerate archetype competing through MEMS-integrated platforms.
| Leading Market Players |
|---|
| Sick AG |
| Honeywell International Inc |
| Rockwell Automation |
| ams-OSRAM AG |
| STMicroelectronics |
| Bosch Sensortec GmbH |
| First Sensor AG |
| Turck |
| Hamamatsu Photonics K.K. |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon targets and REACH substance phase-outs simultaneously gate supplier qualification windows and compress price differentiation timelines. German automotive OEMs now demand mercury-free sensing architectures at 40-60% cost premiums, while Italian housing suppliers absorb coating reformulation investments that reshape competitive cost structures.
Pricing Analysis
Volume-discount tiering structures separate multi-year framework agreements from spot procurement across German and French industrial clusters. Premium positioning accrues to REACH-compliant suppliers with captive ATEX certification, while standard tiers compete on sensor output density and warranty terms. Cost compression in fiber optic sensor categories intensifies as Emilia-Romagna system integrators consolidate vendor panels. Automotive OEMs in Munich and Stuttgart engineering centers show least price sensitivity due to KBA quality mandate compliance requirements.
Supply Chain Analysis
Just-in-time inventory strategies dominate German automotive lines, while French aerospace operators maintain strategic stockpiles of hermetic-grade sensor components. Manufacturing concentration rests on Germany, France, and the Netherlands for final assembly, with indium phosphide wafer supply anchored in Asian foundries. Specialty coating feedstock dependencies on ECHA-authorized chromium trioxide create single-source vulnerability exposure. Distribution runs through Randstad logistics hubs and Munich-based system integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as EU AI Act conformity requirements splinter procurement authority across certified and uncertified product tiers. Machine vision proliferation in German welding stations and French aerospace manufacturing creates divergent specification niches.
For Market Incumbents: Consolidate around MEMS-optical convergence platforms to defend against emerging photonics specialists with chip-scale spectrometer capabilities. Deepen backward integration into indium phosphide wafer supply through foundry partnerships in Asian manufacturing clusters. Prioritize REACH-compliant coating qualification investments ahead of ECHA sunset deadlines.
For New Entrants and Emerging Players: Differentiate on ATEX-certified fiber optic sensor architectures targeting Italian industrial automation corridors in Lombardy and Emilia-Romagna. Emilia-Romagna machinery clusters represent the most penetrable geography given brownfield PLC integration friction burdening incumbent relationships. Pursue system integrator co-development partnerships rather than direct OEM sales cycles.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MEMS-integrated optical platforms as European foundries scale photonics packaging capacity. Five-to-ten year viability favors specialists with captive ATEX certification assets and REACH-compliant material portfolios. Watch ECHA substance-of-very-high-concern listing velocity as inflection indicator for coating supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS-Optical Convergence Partnership | Enables chip-scale spectrometers for pharmaceutical process monitoring in Dutch photonics clusters. |
| REACH-Compliant Coating Transition | Secures supplier qualification ahead of ECHA chromium trioxide sunset dates affecting Italian housing manufacturers. |
| ATEX Certification Asset Acquisition | Captures fiber optic sensor demand from French and Italian explosive zone operators replacing electrical instrumentation. |
| Multi-Year Framework Agreement Consolidation | Locks in Munich and Toulouse engineering center procurement relationships against distributor-only competitors. |
| Hermetic Sealing Skill Development | Addresses technician scarcity in German and French technical universities for photonics packaging operations. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings. Plant engineers, OEM procurement teams, aftermarket service heads, and photonics R&D directors provided operational context. Secondary sources include ECHA substance restriction databases, EU Machinery Directive conformity assessment records, SEC filings from listed sensor manufacturers, and customs trade data for III-V compound semiconductor substrates. Bottom-up sensor shipment estimates triangulate against top-down industrial automation capex projections.
Sensitivity analysis around REACH compliance timeline scenarios and indium phosphide wafer availability stress-tests the projection framework. Segmentation dimensions span product type, technology architecture, end-user industry, and application across the modeling period. CAGRs derive from segment-level demand elasticity modeling against German automotive production forecasts and French aerospace manufacturing indices. MEMS integration adoption curves and CSRD disclosure mandate implementation pace inform industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal implementation and REACH authorization schedules; material policy shifts would require re-modeling. Indium phosphide supply disruptions or ECHA substance listing accelerations constitute primary revision triggers. Revision becomes warranted when hermetic sealing technician training program scaling crosses demand absorption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
Light Detection and Ranging (Lidar) Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
APAC Occupancy Sensors Market
Sensors and Controls
Global Single Loop Controller Market
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Global Blind Spot Monitor Market