
 China Sensors Market | 2026-2036
China Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
China Sensors Market Insights
Domestic MEMS foundry capacity in Jiangsu and Zhejiang provinces is rebalancing toward automotive-grade production. Huawei Technologies Co., Ltd leverages its semiconductor design ecosystem to anchor high-end optical sensor development. Silan Microelectronics sustains captive wafer fabrication for pressure and inertial sensors. Mingshi Sensing specializes in industrial proximity modules for steel and chemical plant automation.
China sensors are transduction devices that convert physical or chemical stimuli into measurable electrical signals, typically operating across temperature ranges of minus forty to one hundred twenty-five degrees Celsius with millivolt-level output sensitivity. These components enable real-time process control, environmental surveillance, and machine-to-machine communication in connected infrastructure. MEMS sensors command premium positioning due to miniaturization requirements in consumer wearables and vehicle safety systems, while wireless sensor networks expand fastest in smart factory retrofits. Pressure sensors retain mature margins from HVAC and hydraulic equipment replacement cycles.
NMPA medical device registration rules and MIIT sensor performance standards shape product certification timelines for domestic manufacturers. GB national standards on electromagnetic compatibility constrain design architectures for industrial deployment. Stakeholders must monitor how SAMR enforcement of quality consistency rules affects component sourcing from second-tier domestic suppliers.
Market Dynamics
MIIT sensor performance standards and NMPA medical device registration rules are compressing certification timelines, forcing domestic manufacturers to accelerate testing infrastructure investment or cede share to certified incumbents.
Growth Catalysts
- Automotive electrification mandates:NEV safety regulations require multi-axis inertial sensors for battery management and collision avoidance systems, pulling MEMS capacity toward vehicle-grade fabrication.
- GB electromagnetic compatibility standards:Industrial automation buyers in Jiangsu province now specify certified proximity sensors for steel mill retrofits, filtering out uncertified suppliers.
- Shenzhen electronics corridor concentration:Consumer wearable OEMs cluster procurement of miniaturized pressure and optical sensors, creating demand density that justifies dedicated foundry lines.
Market Restraints
- Silicon wafer input volatility:200mm wafer spot prices fluctuate with memory chip demand cycles, squeezing MEMS foundry margins on fixed-price industrial contracts.
- Single-province foundry concentration:Jiangsu and Zhejiang provinces host over 70 percent of domestic MEMS capacity, exposing supply chains to regional power rationing or water restrictions.
- Optical sensor technical ceiling:Lidar-grade silicon photonics remains import-dependent as domestic fabs lack sub-100nm patterning for coherent detection arrays.
Strategic Opportunities
- Western province industrial retrofits:Sichuan and Shaanxi steel plants lag coastal automation penetration, creating sensor deployment gaps for certified proximity module suppliers.
- Dual carbon goals enforcement:MEE emissions monitoring mandates expand continuous air quality sensor networks, mandating new procurement beyond voluntary corporate sustainability programs.
- AI-edge convergence:On-device inference chips paired with inertial sensors enable predictive maintenance without cloud latency, opening premium pricing for integrated modules.
Industry Challenges
- MEMS design talent scarcity:Finite element modeling expertise for multi-physics sensor simulation concentrates in Shanghai and Beijing, forcing inland foundries to pay 40 percent salary premiums.
- SAMR quality consistency enforcement:Random factory inspections under 2023 market regulation rules delay shipments when traceability documentation fails spot audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Sensors Market |
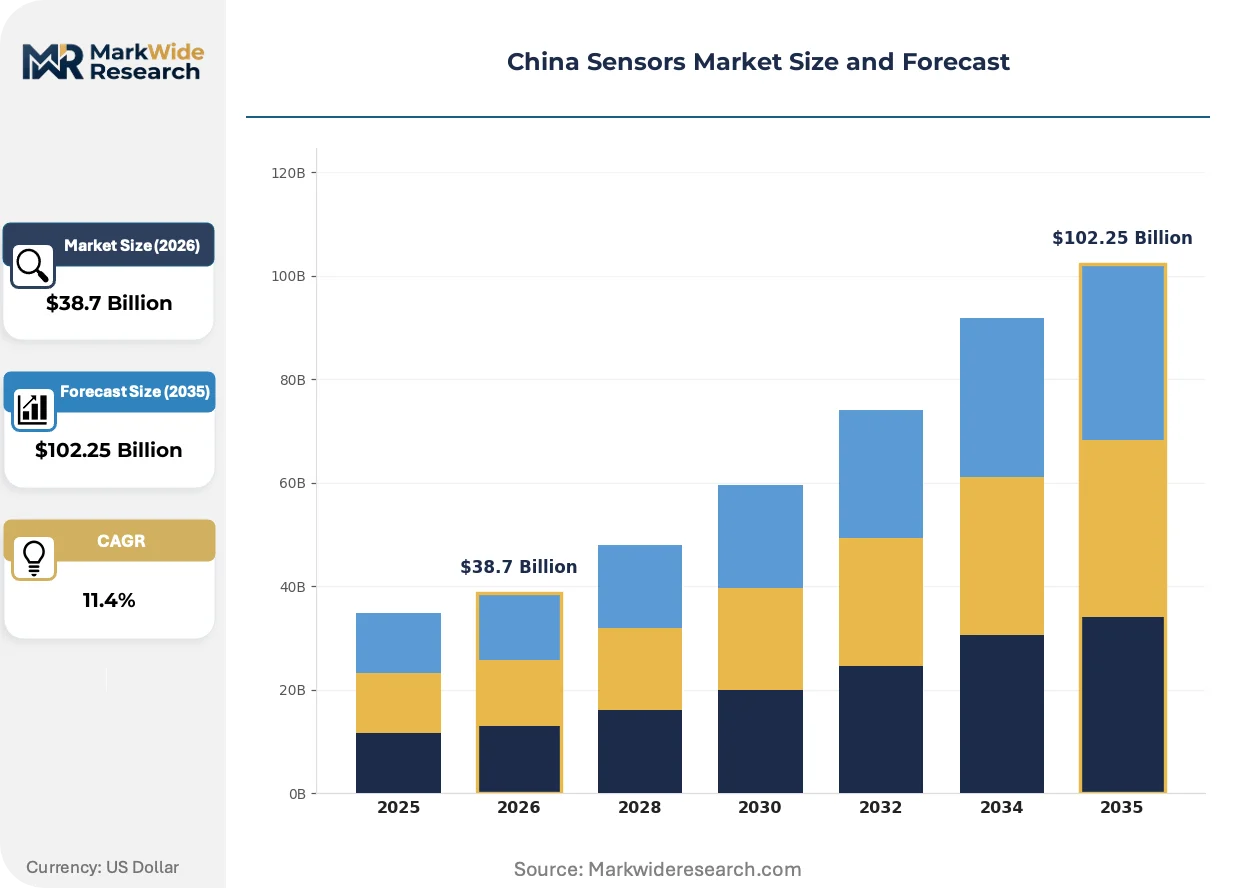
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Light Sensors Technology: Analog Sensors, Digital Sensors, Wireless Sensors, MEMS Sensors End User: Automotive, Healthcare, Industrial, Consumer Electronics Application: Automation, Environmental Monitoring, Smart Home, Wearable Devices |
| Companies Covered | Huawei Technologies Co., Ltd, Cheemi Technology Co., Ltd, HeYi Electronics Technology Co., Ltd, Novosense, Beijing Smart Technology Co., Ltd, Xiamen Hualian Technology Co., Ltd, Silan Microelectronics, Mingshi Sensing, Sodilon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Sensors Market Trends and Innovations
Silicon photonics integration and edge-AI inference are compressing sensor response latency while regulatory emissions mandates expand continuous monitoring networks beyond voluntary corporate adoption.
Multi-sensor fusion modules combining inertial measurement units with pressure transducers are automating real-time equipment health diagnostics in chemical plant automation. Mingshi Sensing and comparable industrial specialists deploy these integrated packages for predictive maintenance contracts. The technology is automating manual inspection rounds that previously required dedicated technician teams.
NMPA medical device registration rules now mandate electromagnetic compatibility testing for implantable sensors, extending certification timelines by six to nine months for domestic manufacturers. Cardiovascular monitoring wearable producers in Shenzhen must redesign antenna architectures to pass GB/T 17626 immunity tests. The regulatory friction most affects optical heart-rate sensor modules targeting hospital-grade accuracy claims.
Steel and chemical plant operators in Jiangsu province now specify outcome-based sensor service contracts tying payment to uptime guarantees rather than hardware procurement. System integrators absorb capital deployment risk while capturing recurring revenue streams. This procurement model shift is most visible in heavy industrial automation where unplanned downtime costs exceed sensor hardware value by orders of magnitude.
China Sensors Market Segmentation
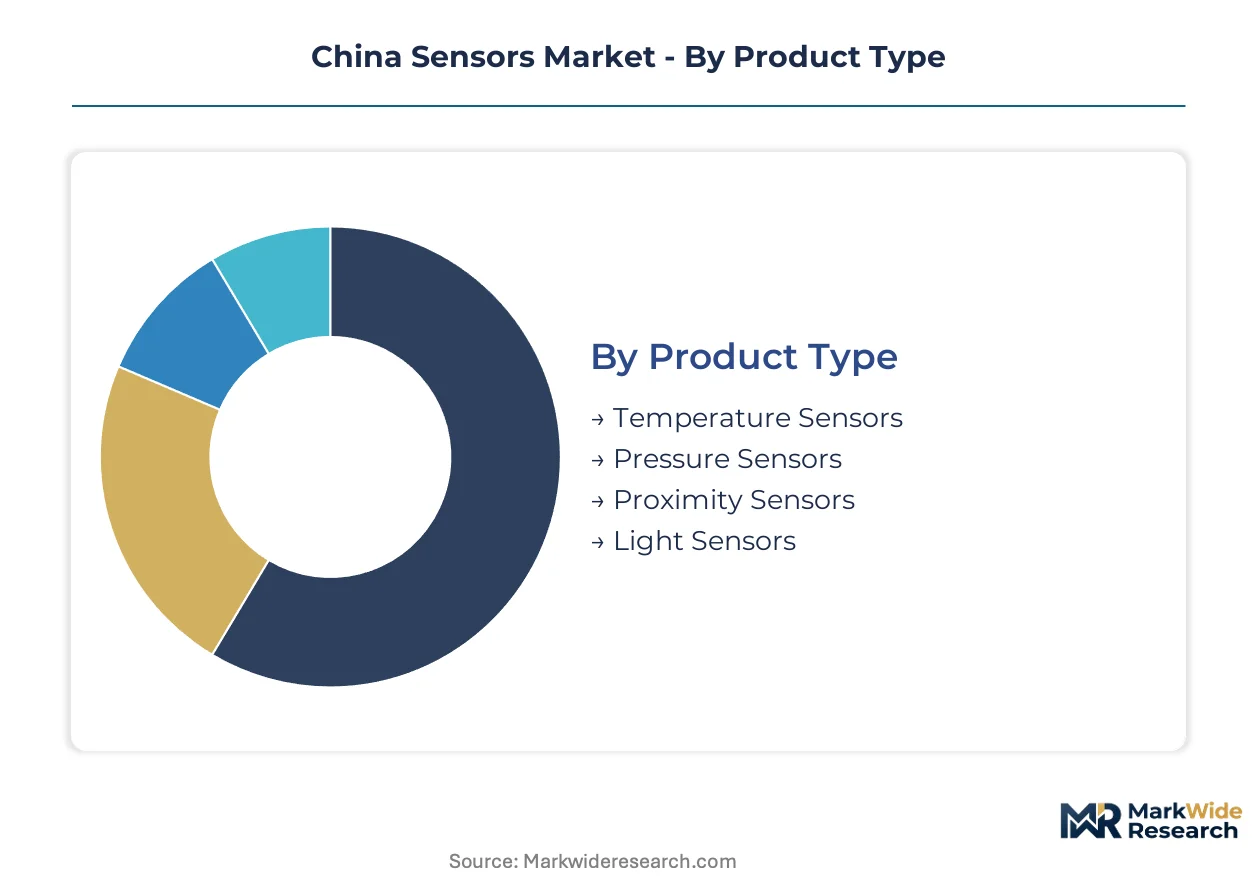
Segmentation in the China sensors market reveals how certification requirements fragment procurement patterns across industries. MIIT performance standards and NMPA medical device rules create divergent compliance burdens that reshape supplier selection criteria.
Product Type:
Pressure sensors and temperature sensors carry the heaviest NMPA certification loads for medical applications, while proximity sensors face GB electromagnetic compatibility mandates in industrial settings.
- Pressure Sensors:Piezoresistive and capacitive transduction elements dominate automotive and HVAC applications. Jiangsu province steel mills specify certified units for hydraulic equipment retrofits under tightening GB standards. MEMS miniaturization drives wearable blood pressure monitoring demand in Shenzhen.
- Temperature Sensors:Thermocouple and RTD variants span minus forty to one thousand two hundred degrees Celsius operating ranges. NEV battery management systems in automotive pull thermistor procurement toward vehicle-grade suppliers with MIIT certification. Industrial process control maintains steady replacement cycles in chemical plants.
- Proximity Sensors:Inductive and capacitive detection modules automate position sensing in factory automation. Mingshi Sensing and comparable specialists serve steel mill automation with outcome-based service contracts.
- Light Sensors:Photodiode and ambient light sensing elements enable display brightness adjustment and optical heart-rate monitoring. NMPA electromagnetic compatibility testing extends certification timelines for hospital-grade wearable applications.
Pressure sensors sit at the top of the volume ranking, with proximity sensors climbing the fastest as Jiangsu industrial retrofits accelerate.
Technology:
Cost tier differentiation separates high-volume analog production from premium digital and wireless modules requiring firmware development investment.
- MEMS Sensors:Micro-electromechanical systems integrate mechanical structures with CMOS electronics for miniaturized inertial and pressure measurement. Huawei's semiconductor ecosystem anchors domestic optical MEMS development while Silan Microelectronics maintains captive wafer fabrication. NEV safety mandates pull foundry capacity toward automotive-grade production lines.
- Wireless Sensors:Low-power radio protocols enable battery-operated deployment without cabling infrastructure. Smart factory retrofits in western provinces adopt Zigbee and LoRa modules for predictive maintenance networks where cloud latency is unacceptable.
- Digital Sensors:Integrated ADC and calibration logic reduce host processor burden in consumer electronics. Shenzhen wearable OEMs specify I2C and SPI interface standards for miniaturized module integration.
- Analog Sensors:Millivolt-level output signals require external signal conditioning but retain cost advantages in mature HVAC and hydraulic equipment replacement markets.
Analog sensors retain the largest installed base, with wireless sensors expanding most quickly as edge-AI convergence enables on-device inference without cloud dependency.
End User:
Application maturity determines margin structure, with automotive and healthcare commanding premium pricing against price-pressured consumer electronics.
- Automotive:NEV electrification mandates multi-axis inertial sensors for battery thermal management and collision avoidance. Domestic MEMS foundries in Jiangsu and Zhejiang rebalance capacity toward vehicle-grade fabrication with AEC-Q100 qualification.
- Healthcare:NMPA registration rules and GB/T 17626 electromagnetic compatibility testing filter suppliers for implantable and wearable cardiovascular monitoring. Certification timelines extend six to nine months for optical heart-rate modules targeting hospital-grade accuracy claims.
- Industrial:Steel and chemical plant automation in Jiangsu province specifies certified proximity sensors for mill retrofits. Outcome-based service contracts tie payment to uptime guarantees rather than hardware procurement.
- Consumer Electronics:Shenzhen electronics corridor concentration creates demand density for miniaturized pressure and optical sensors in wearables. Price competition intensifies as module integration commoditizes standalone component value.
Industrial end users generate the most stable revenue streams, with automotive climbing fastest as NEV penetration mandates expand sensor content per vehicle.
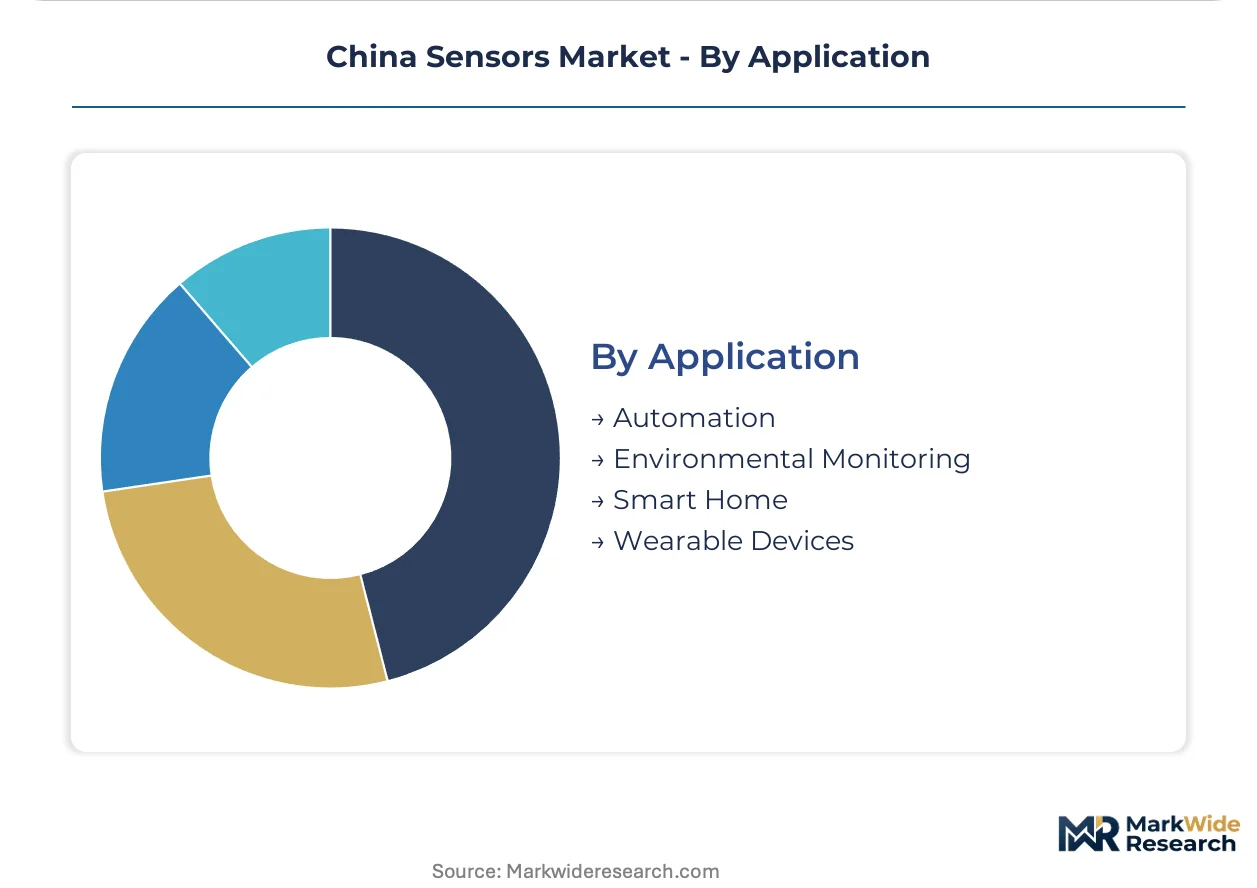
Application:
Geography-driven deployment patterns concentrate automation demand in coastal provinces while environmental monitoring expands inland under MEE enforcement.
- Automation:Real-time process control systems integrate multi-sensor fusion modules for equipment health diagnostics. Mingshi Sensing deploys combined inertial and pressure packages for predictive maintenance contracts in chemical plants.
- Environmental Monitoring:Continuous air quality sensor networks expand under dual carbon goals enforcement beyond voluntary corporate sustainability programs. MEE emissions mandates drive new procurement in Sichuan and Shaanxi industrial zones.
- Smart Home:Occupancy sensing and climate control automation integrate proximity and temperature sensors in residential construction. Wireless protocol standardization reduces installation cost for retrofit applications.
- Wearable Devices:Optical heart-rate and blood pressure monitoring modules target consumer fitness and medical-grade accuracy segments. NMPA certification separates hospital-grade suppliers from consumer-tier competitors.
Automation applications dominate current revenue contribution, with environmental monitoring gaining share fastest as regulatory enforcement tightens emission compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturers exploit compliance cost gaps between coastal certification hubs and inland production zones. MIIT sensor standards and NMPA medical device rules create divergent cost-of-compliance profiles across provincial boundaries. Foundry investment migrates toward regions with streamlined regulatory pathways.
Guangdong Province
Shenzhen electronics manufacturers cluster procurement of miniaturized optical and pressure sensors for wearable devices. NMPA electromagnetic compatibility testing extends certification timelines for hospital-grade accuracy claims. The Pearl River Delta corridor generates demand density that justifies dedicated MEMS foundry lines.
Jiangsu Province
Steel mill automation buyers specify GB-certified proximity sensors for hydraulic equipment retrofits. MIIT performance standards filter uncertified suppliers from industrial procurement shortlists. The Yangtze River Delta hosts concentrated MEMS fabrication capacity serving automotive and industrial end users.
Zhejiang Province
Automotive-grade MEMS foundries rebalance capacity toward NEV battery management and collision avoidance systems. Dual carbon goals enforcement drives emissions monitoring sensor procurement beyond voluntary adoption. Hangzhou-Ningbo industrial clusters anchor captive wafer fabrication for pressure and inertial devices.
Sichuan Province
Western steel plants lag coastal automation penetration, creating deployment gaps for certified proximity module suppliers. MEE emissions monitoring mandates expand continuous air quality sensor networks. The Chengdu-Chongqing economic zone attracts sensor integrators targeting industrial retrofit contracts.
Shaanxi Province
Chemical plant operators specify outcome-based sensor service contracts tying payment to uptime guarantees. SAMR quality consistency enforcement through random factory inspections affects component traceability documentation. Xi'an aerospace and defense clusters pull high-reliability sensor development inland.
China Sensors Market Competitive Landscape
Yangtze River Delta producers anchor one tier; Pearl River Delta specialists hold another. The vendor base splits between consolidated semiconductor conglomerates with captive fabrication and fragmented industrial sensor module assemblers. Three archetypes dominate: integrated device manufacturers with in-house wafer production, fabless design houses leveraging foundry partnerships, and application-specific system integrators bundling hardware with service contracts. Capacity expansion and certification infrastructure investment represent the dominant competitive moves.
Among domestic fabricators, Silan Microelectronics and Mingshi Sensing exemplify divergent strategic positions. Silan Microelectronics occupies the integrated manufacturer archetype with captive supply chain control. Mingshi Sensing represents the application-specialist tier focused on industrial automation outcomes. Huawei Technologies Co., Ltd anchors the technology-ecosystem tier, leveraging semiconductor design infrastructure to influence high-end optical sensor development. These three entities collectively illustrate how scale, specialization, and platform integration create distinct competitive vectors.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd |
| Cheemi Technology Co., Ltd |
| HeYi Electronics Technology Co., Ltd |
| Novosense |
| Beijing Smart Technology Co., Ltd |
| Xiamen Hualian Technology Co., Ltd |
| Silan Microelectronics |
| Mingshi Sensing |
| Sodilon |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between MIIT-qualified automotive sensors and uncertified industrial modules manifests in both margin structures and foundry allocation decisions. Premium-tier suppliers capture pricing power through AEC-Q100 qualification while commodity producers absorb wafer cost volatility on fixed-price contracts.
Pricing Analysis
Distributor margins on MEMS pressure sensors compress as Shenzhen wearable OEMs consolidate procurement through direct foundry relationships. Three-tier pricing structure across AEC-Q100 automotive, GB-certified industrial, and uncertified commodity levels reflects certification investment recovery timelines. Pricing pressure stems from 200mm silicon wafer spot price volatility squeezing fixed-price industrial contracts. Consumer electronics buyers exhibit highest price sensitivity while automotive Tier 1 suppliers accept premium pricing for traceability documentation.
Supply Chain Analysis
Refurbishment flows for industrial proximity modules remain underdeveloped as Mingshi Sensing and comparable specialists prioritize outcome-based service contracts over hardware recovery. Jiangsu and Zhejiang provinces anchor over 70 percent of domestic MEMS fabrication capacity. Raw material dependencies center on 200mm silicon wafers, specialty glass substrates for optical sensors, and rare-earth magnetic materials for inertial devices. Single-province concentration exposes supply chains to regional power rationing. Distribution runs through electronics component distributors in Shenzhen and direct OEM contracts for automotive qualified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China sensors market compounds steadily as NEV electrification mandates expand sensor content per vehicle regardless of macroeconomic cycles.
For Market Incumbents: Acquire MEMS design talent pools in Shanghai and Beijing to offset 40 percent salary premiums inland foundries currently pay. Silan Microelectronics should expand captive wafer fabrication capacity in Zhejiang before Jiangsu power constraints tighten. Huawei's semiconductor ecosystem must accelerate optical MEMS development before lidar-grade silicon photonics import dependency hardens into structural vulnerability. For New Entrants and Emerging Players: MEE emissions monitoring mandates in Sichuan and Shaanxi open a window for certified air quality sensor networks where coastal incumbents lack established service infrastructure. Western province steel plants lag coastal automation penetration by several years, creating deployment gaps for proximity module specialists. Target outcome-based service contracts rather than hardware procurement to absorb capital deployment risk while capturing recurring revenue. For Investors and Strategic Acquirers: Consolidation pressure builds where SAMR quality consistency enforcement raises documentation costs above what fragmented module assemblers can sustain. The 5-10 year viability window favors integrated device manufacturers with captive fabrication over fabless design houses exposed to foundry margin cycles. Monitor MIIT sensor performance standard revisions as inflection indicators for certification infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | MIIT and NMPA compliance timelines filter uncertified suppliers from procurement shortlists. |
| Automotive-Grade Foundry Conversion | Jiangsu and Zhejiang capacity rebalancing captures NEV battery management sensor demand. |
| Outcome-Based Service Contracting | Steel mill automation buyers shift payment models from hardware to uptime guarantees. |
| Western Province Geographic Expansion | Sichuan and Shaanxi industrial retrofits lag coastal penetration by measurable deployment gaps. |
| Multi-Sensor Fusion Module Development | Combined inertial and pressure packages automate predictive maintenance in chemical plants. |
Research Methodology
Coverage spans Guangdong, Jiangsu, Zhejiang, Sichuan, and Shaanxi provinces, with primary inputs from each regional cluster. The research combines interviews with MEMS foundry operations managers, automotive Tier 1 procurement directors, industrial automation system integrators, and NMPA regulatory consultants with secondary validation. Secondary sources include MIIT sensor performance standard filings, SAMR market regulation enforcement records, NEV production databases, and steel mill automation retrofit announcements. Bottom-up sensor unit demand estimates triangulate against top-down electronics component trade flow analysis.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. The analytical framework models product type, technology tier, end-user industry, and application dimensions alongside provincial regulatory cluster differentiation. CAGRs derive from segment-level growth trajectory synthesis. Forecast inputs include NEV penetration policy targets, dual carbon goals enforcement timelines, and MIIT certification backlog data.
Revisions become necessary when NMPA medical device registration rules extend timelines beyond modeled assumptions or when Jiangsu power rationing disrupts foundry output. Practitioners should monitor SAMR inspection frequency trends and 200mm wafer spot price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Hydrogen Monitor Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Europe Nano Radiation Sensors Market