
 Echo Sounder Market | 2026-2036
Echo Sounder Market Size, Share, and Industry Trends Forecast 2026-2036
Echo Sounder Market Analysis
Digital beamforming is rewriting echo sounder architecture, replacing analog signal chains with software-defined acoustic processing. Kongsberg leverages its seabed-mapping heritage to dominate deep-water survey contracts. Teledyne Technologies Incorporated sustains R&D intensity across multi-frequency sonar platforms for defense and scientific buyers. Exail anchors European market presence through specialized underwater robotics integration.
An echo sounder is an acoustic instrument that transmits pulses downward through water columns and measures return-time intervals to calculate depth, typically operating at frequencies between 12 kHz and 200 kHz depending on resolution requirements. The device serves as foundational equipment for hydrographic charting, fish stock assessment, and subsea infrastructure inspection. Multi-beam product types command premium positioning in offshore energy applications where swath coverage efficiency directly reduces vessel-day costs. Fixed installations lead in environmental monitoring deployments along permanent observation networks. Portable units compete hardest in small-scale aquaculture and recreational fishing segments where capital constraints shape purchasing patterns.
IMO safety standards and national hydrographic service mandates from bodies like NOAA and the UK Hydrographic Office shape equipment certification requirements and replacement cycles. The EU Marine Strategy Framework Directive drives habitat-mapping demand through mandated seabed monitoring protocols. Stakeholders must weigh beam-density specifications against vessel-integration costs when specifying systems for emerging offshore wind survey programs.
Market Dynamics
Digital beamforming architectures are compressing analog component counts while expanding software-defined acoustic processing capabilities across hydrographic survey fleets. This shift is redistributing value from hardware suppliers toward embedded software developers and system integrators.
Growth Catalysts
- EU Marine Strategy Framework Directive:Mandated seabed monitoring protocols across member states are accelerating replacement cycles for fixed-installation echo sounders in environmental observation networks.
- Offshore wind farm development:Pre-construction geophysical surveys in the North Sea and Southeast Asia are absorbing multi-beam systems at rates outpacing traditional oil and gas applications.
- Precision aquaculture standards:Japan's METI push for automated feeding and biomass monitoring is driving fixed-installation demand across coastal aquaculture zones.
Market Restraints
- Transducer ceramic supply concentration:Piezoelectric material processing capacity clusters in East Asian manufacturing hubs, creating single-source vulnerability for high-frequency array production.
- IMO certification timelines:Extended type-approval procedures for safety-of-navigation equipment delay fleet modernization programs and compress vendor cash conversion cycles.
- Laser bathymetry substitution:Airborne lidar systems are capturing near-shore charting contracts where water clarity permits, eroding shallow-water echo sounder volumes.
Strategic Opportunities
- Autonomous underwater vehicle integration:Convergence of compact multi-beam payloads with AUV platforms opens untapped demand for pipeline inspection in Norway's aging subsea infrastructure.
- Scientific research vessel retrofits:National oceanographic institutes in Germany and France are unbundling after-sales service contracts, creating openings for independent calibration and maintenance providers.
- Portable unit channel expansion:Direct-to-operator e-commerce penetration in recreational fishing segments bypasses traditional marine electronics distributors.
Industry Challenges
- Acoustic data scientist scarcity:Hydrographic processing expertise concentrates among aging surveyor cohorts, constraining fleet expansion for offshore contractors.
- Legacy system integration friction:Vessel retrofit projects face compatibility failures between new beamforming processors and existing motion reference units.
- Multi-frequency calibration complexity:Expanded transducer arrays require extended dockside commissioning periods that reduce vessel utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Echo Sounder Market |
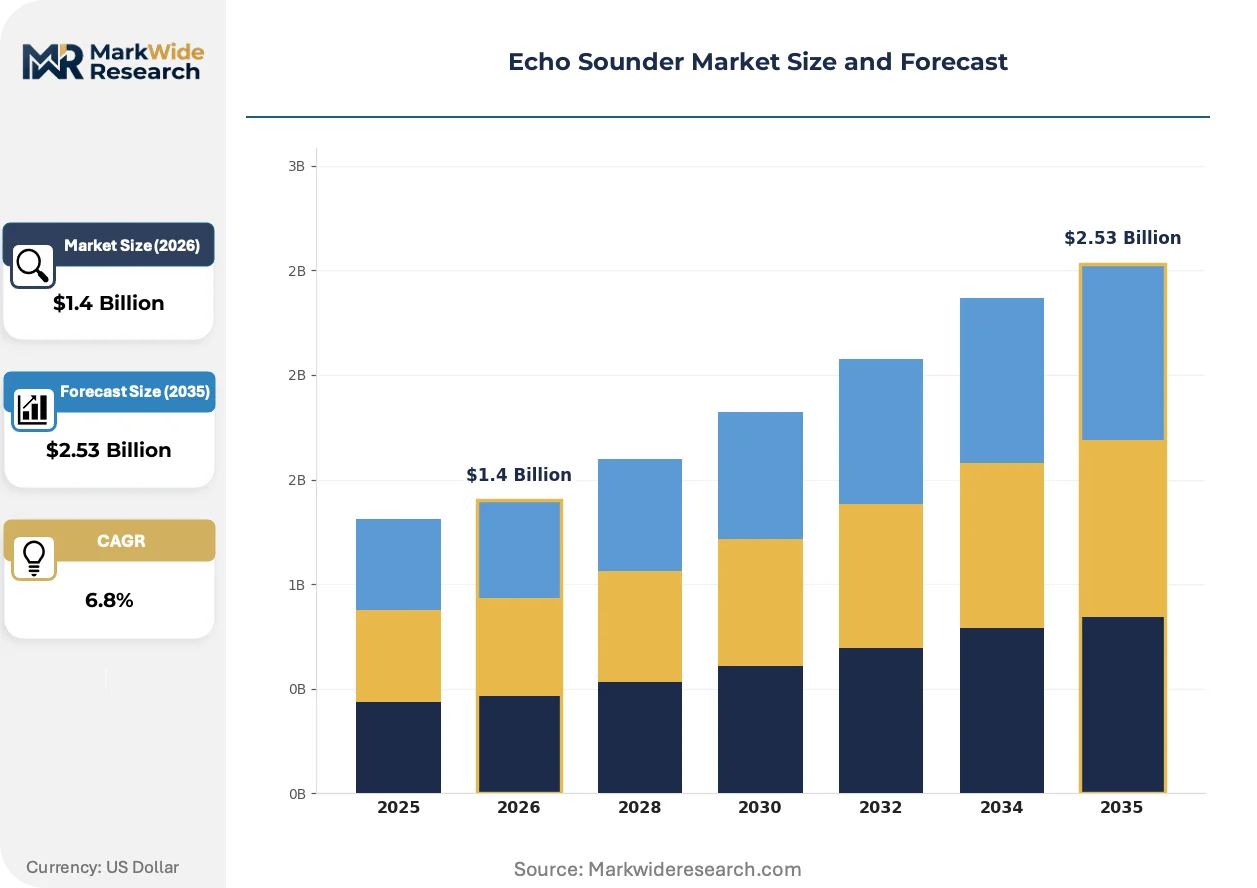
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Multi-Beam, Single-Beam End User: Marine, Research Institutions, Commercial Fishing, Oil & Gas Technology: Fish Finder, Sonar, Acoustic Imaging, Underwater Surveying Application: Navigation, Aquaculture, Habitat Mapping, Environmental Monitoring |
| Companies Covered | R2Sonic LLC, Imagenex Technology Corp, Kongsberg, EdgeTech Inc., Furuno Electric Co., Ltd., Teledyne Technologies Incorporated, Tritech International Limited, Exail, NORBIT ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Echo Sounder Market Emerging Trajectories
Acoustic processing hardware is flattening into software layers, enabling real-time beam steering without mechanical array rotation. This architectural shift is compressing system footprints while expanding swath coverage capabilities.
Multi-beam echo sounder technology is migrating from discrete analog front-ends toward field-programmable gate array-based digital signal chains. Offshore energy survey contractors in the North Sea are adopting these architectures fastest, driven by vessel-day cost pressures. The technology is migrating from hardware-defined to software-defined acoustic processing, compressing maintenance schedules and enabling over-the-air feature updates.
REACH restrictions on lead-based piezoelectric materials are forcing transducer manufacturers toward barium titanate and potassium sodium niobate alternatives. Industrial consequence includes reformulated ceramic curing protocols and extended qualification timelines for new array designs. High-frequency scientific instruments face the steepest compliance burden, with European manufacturers accelerating alternative material validation ahead of sunset dates.
Charter arrangements for survey equipment are displacing capital purchases among mid-size hydrographic service providers. Equipment-as-a-service models bundle maintenance, calibration, and software licensing into per-project fees. This shift is most visible in Southeast Asian markets where capital constraints intersect with irregular contract flows.
Echo Sounder Market Segmentation
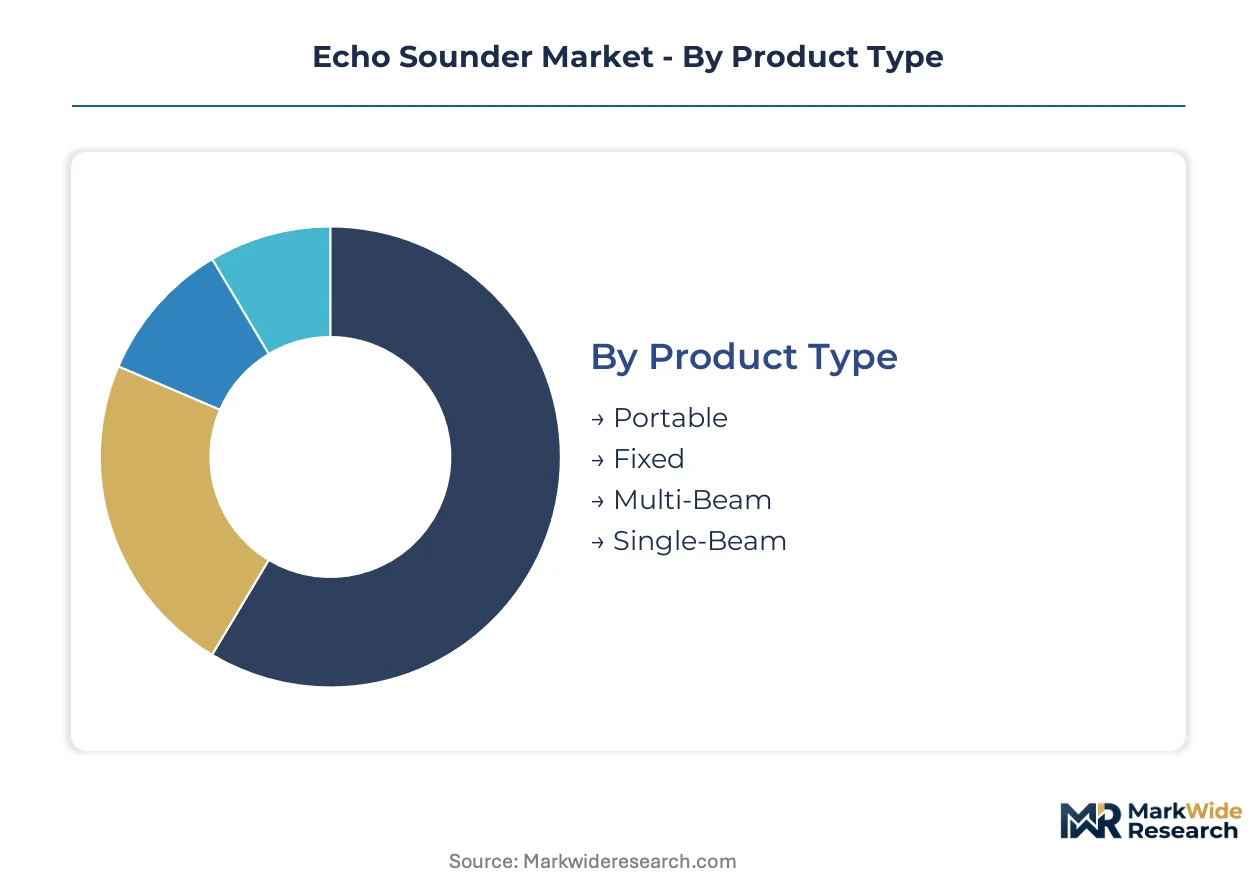
Echo sounder procurement patterns diverge sharply across vessel types and operational mandates. Equipment specifications cascade from regulatory certification requirements through to installation permanence and beam complexity.
Product Type:
After-sales service intensity escalates with system integration depth and calibration complexity.
- Multi-Beam:Swath-forming arrays generate dense point clouds across wide seabed corridors through electronically steered transmit-receive modules. Offshore wind survey contractors in the North Sea and Southeast Asia absorb these systems fastest as vessel-day economics favor coverage efficiency over single-beam methods.
- Fixed:Permanently mounted transducer arrays feed continuous data streams into vessel-wide navigation networks or coastal observation stations. Japan's coastal aquaculture zones under METI precision standards are accelerating installations for automated biomass monitoring and feeding system integration.
- Portable:Battery-powered units with clamp-on or pole-mounted transducers serve small-boat operators and recreational anglers.
- Single-Beam:Narrow-cone depth sounders with analog or basic digital processing dominate legacy fleet retrofits and cost-constrained hydrographic programs.
By volume, Single-Beam leads. By growth pace, Multi-Beam is ahead.
End User:
Capital deployment timelines stretch from seasonal fishing cycles through decadal research vessel programs.
- Oil & Gas:Subsea infrastructure inspection mandates drive multi-beam specifications for pipeline route surveys and as-laid verification. Norway's aging North Sea infrastructure and Southeast Asian deepwater developments sustain replacement demand despite energy transition pressures.
- Commercial Fishing:Sonar arrays integrate with net monitoring and fish-finding electronics aboard industrial trawlers. Norwegian fleet modernization ahead of stricter IMO emissions rules is compressing replacement cycles for integrated bridge systems.
- Research Institutions:National oceanographic programs specify calibrated scientific-grade systems with multi-frequency capability.
- Marine:Merchant vessel carriage requirements under SOLAS Chapter V mandate echo sounder presence on cargo ships and passenger vessels.
By installed base, Marine dominates. By specification advancement, Research Institutions set the pace.
Technology:
Signal processing migration from analog hardware to software-defined architectures is redistributing value across the technology stack.
- Underwater Surveying:Integrated positioning, motion sensing, and acoustic processing suites deliver hydrographic-grade bathymetric deliverables. EU Marine Strategy Framework Directive seabed monitoring protocols are mandating survey-grade specifications for member state habitat mapping programs.
- Sonar:Active acoustic systems spanning fish detection through obstacle avoidance serve dual-use defense and commercial markets.
- Acoustic Imaging:High-resolution seabed visualization through interferometric or synthetic aperture methods supports archaeological and engineering applications.
- Fish Finder:Simplified depth and target-strength displays target recreational and small-scale commercial operators.
By revenue concentration, Underwater Surveying commands premium positioning. By unit expansion, Sonar is gaining share fastest.
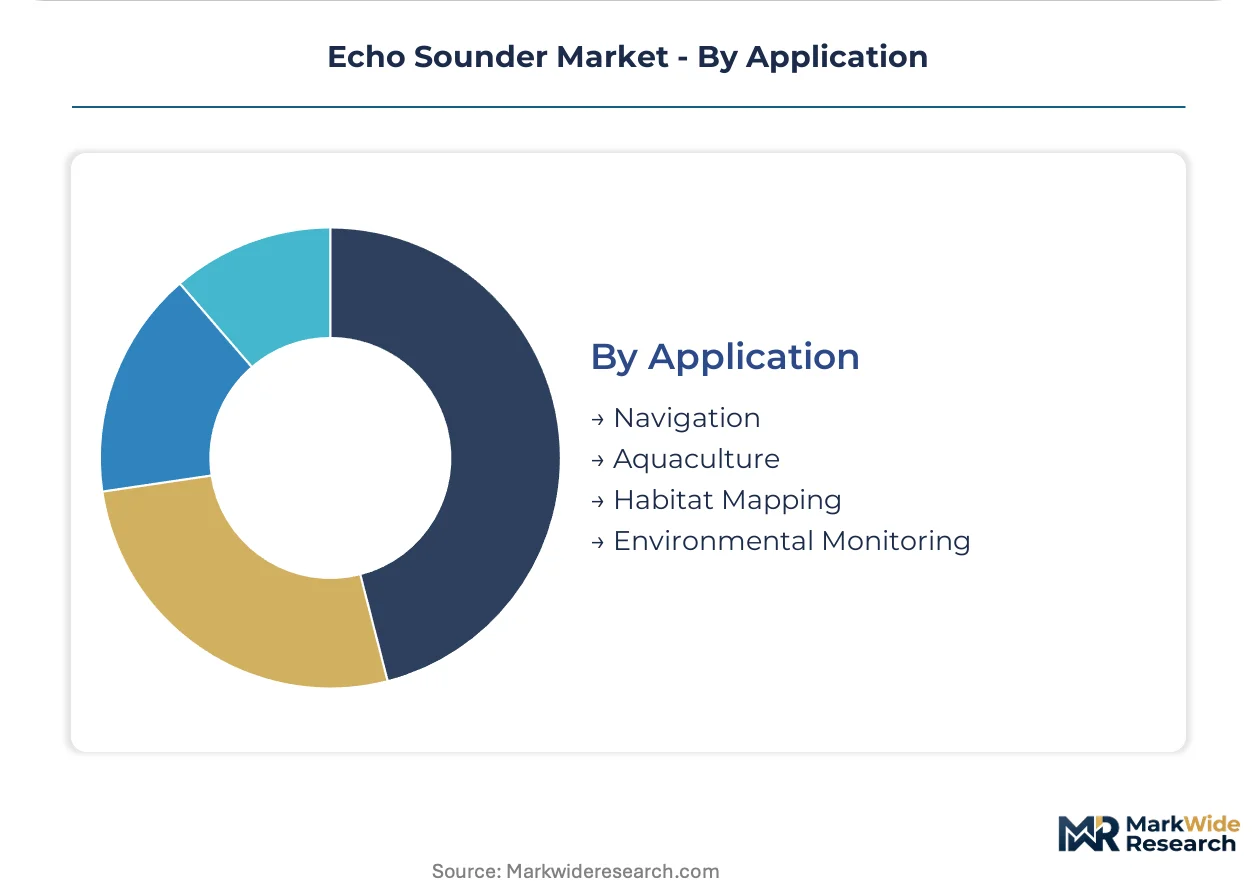
Application:
Regulatory mandate intensity varies from compulsory carriage rules through voluntary sustainability certifications.
- Habitat Mapping:Systematic seabed classification for marine protected area designation and benthic impact assessment. EU member states under Marine Strategy Framework Directive obligations are accelerating survey procurement to meet monitoring protocol deadlines.
- Environmental Monitoring:Fixed installations on moorings or cabled observatories track long-term acoustic conditions and biological activity.
- Aquaculture:Site selection, net inspection, and predator detection support farm operational efficiency.
- Navigation:Safety-of-navigation depth determination for chart compilation and real-time vessel operations.
By regulatory pull, Habitat Mapping faces the steepest compliance-driven demand. By operational expansion, Aquaculture shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep-water survey contractors and commercial fishing operators concentrate procurement authority in coastal economies with established maritime industrial bases. National hydrographic mandates and offshore energy licensing regimes shape equipment specification patterns across distinct regulatory environments.
Norway
North Sea decommissioning schedules and subsea infrastructure aging drive multi-beam system demand for pipeline inspection and as-laid verification. The Norwegian Maritime Authority enforces IMO emissions standards that compress fleet modernization cycles for integrated bridge electronics. Bergen and Stavanger host survey vessel operators upgrading sonar arrays ahead of stricter environmental compliance deadlines.
United States
NOAA hydrographic charting mandates and offshore wind lease rounds in the Atlantic absorb multi-beam survey capacity for pre-construction geophysical work. The Jones Act vessel requirements shape domestic fleet specifications for equipment carriage. Gulf Coast ports and Pacific Northwest shipyards handle retrofit installations for research and commercial fleets.
Japan
Coastal aquaculture automation and precision feeding systems accelerate fixed-installation echo sounder deployment across METI-regulated zones. The Fisheries Agency monitors biomass standards that require continuous acoustic monitoring infrastructure. Nagasaki and Hiroshima prefectures concentrate aquaculture technology adoption for oyster and yellowtail farm operations.
Germany
EU Marine Strategy Framework Directive seabed monitoring obligations drive habitat-mapping procurement through federal maritime agencies. The Federal Maritime and Hydrographic Agency enforces survey-grade certification for environmental observation networks. Hamburg and Bremerhaven anchor hydrographic service provider clusters serving North Sea and Baltic operations.
United Kingdom
Offshore wind development in the North Sea and Celtic Sea generates geophysical survey demand for multi-beam bathymetric coverage. The UK Hydrographic Office mandates equipment standards for safety-of-navigation carriage on merchant vessels. Southampton and Aberdeen harbor survey contractors and fishing fleet operators replacing legacy single-beam systems.
Echo Sounder Market Vendor Landscape
Channel-controlling players compete with product-specialist players for specification authority in fleet procurement decisions. The vendor base organizes around three tiers: diversified maritime electronics conglomerates, dedicated hydrographic instrumentation firms, and regional fishing electronics distributors. Consolidation pressure concentrates among mid-scale survey equipment suppliers facing R&D cost escalation. Dominant competitive moves include strategic partnerships for AUV payload integration and geographic expansion through local calibration service networks.
Within the diversified maritime technology tier, Kongsberg and Teledyne Technologies Incorporated occupy positions spanning defense, scientific, and commercial survey applications. Furuno Electric Co., Ltd. exemplifies the dedicated marine electronics specialist archetype with concentrated presence in commercial fishing and merchant vessel segments. Exail represents the European precision instrumentation cluster with robotics integration capabilities. These three anchors illustrate how competitive positioning fragments across end-use specialization rather than geographic coverage alone.
| Leading Market Players |
|---|
| R2Sonic LLC |
| Imagenex Technology Corp |
| Kongsberg |
| EdgeTech Inc. |
| Furuno Electric Co., Ltd. |
| Teledyne Technologies Incorporated |
| Tritech International Limited |
| Exail |
| NORBIT ASA |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam container corridor shapes cost dynamics for transducer ceramic shipments, compressing margins on high-frequency array production while amplifying price differentiation between integrated system vendors and component assemblers. Freight volatility feeds directly into procurement negotiations for Norwegian survey contractors and Japanese aquaculture operators, forcing tiered service bundling that separates calibration-inclusive packages from bare-hardware transactions.
Pricing Analysis
Cost-plus contracts with ceramic price indexation dominate multi-beam system procurement for North Sea offshore wind surveys, insulating vendors from piezoelectric material volatility while exposing buyers to pass-through clauses. Three-tier pricing structure across premium, standard, and economy levels separates IMO-certified navigation systems from scientific-grade calibrated instruments and portable recreational units. Cost compression in the portable segment is intensifying because direct-to-operator e-commerce channels bypass traditional distributor markups. Small-boat aquaculture operators in Southeast Asia exhibit the highest price sensitivity, whereas research institutions with decadel vessel programs absorb premium positioning for traceable calibration chains.
Supply Chain Analysis
Export-control restrictions on high-frequency sonar technology limit transducer array flows from US and European defense-qualified suppliers to certain offshore energy markets, fragmenting procurement channels for dual-use components. Manufacturing concentrates in Japan, Norway, and Germany for precision ceramic processing, precision machining, and system integration respectively. Supply chains draw from lead-free piezoelectric alternatives, FPGA processing modules, and motion reference units. Single-source vulnerability in barium titanate ceramic curing capacity creates bottleneck exposure for REACH-compliant array production. Distribution runs through authorized marine electronics distributors with dockside calibration capabilities, though equipment-as-a-service models are displacing capital sales among mid-size hydrographic providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of acoustic data scientists with hydrographic processing expertise constrains fleet expansion for offshore contractors, making human capital retention and automated beam-processing development decisive competitive variables. Vendors must weigh software-defined architecture investments against the risk of legacy integration failures that extend commissioning periods and reduce vessel utilization.
For Market Incumbents: Build switching-cost moats through embedded calibration service contracts that tether customers to proprietary beam-processing software ecosystems. Kongsberg and Teledyne Technologies should deepen backward integration into FPGA-based signal processing modules to reduce dependency on discrete component suppliers. Counter the threat of equipment-as-a-service challengers by unbundling maintenance offerings for national oceanographic institutes in Germany and France, creating captive revenue streams that resist price erosion.
For New Entrants and Emerging Players: Mid-market portable units for Southeast Asian aquaculture operators represent the most penetrable entry point, where capital constraints and irregular contract flows favor rental-over-purchase economics. Scientific research vessel retrofits in France and Germany offer second-mover advantage as legacy service contracts expire, creating openings for independent calibration specialists. Pursue direct-to-operator digital channels for recreational fishing segments, bypassing distributor networks that Furuno dominates.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified maritime conglomerates seeking to divest non-core hydrographic instrumentation divisions amid R&D cost escalation. The five-to-ten-year viability window favors vendors with AUV payload integration capabilities, as autonomous pipeline inspection demand accelerates in Norway's aging subsea infrastructure. Watch for inflection signals in METI precision aquaculture subsidy disbursements, which would validate fixed-installation demand trajectories across Japanese coastal zones.
| Strategic Initiative | Industry Significance |
|---|---|
| AUV Payload Integration | Compact multi-beam convergence with autonomous platforms unlocks pipeline inspection contracts in Norway's North Sea decommissioning programs. |
| Software-Defined Architecture Migration | FPGA-based digital beamforming compresses analog component counts while enabling over-the-air feature updates for offshore survey fleets. |
| Lead-Free Ceramic Qualification | Barium titanate and potassium sodium niobate validation ahead of REACH sunset dates secures European market access for high-frequency scientific instruments. |
| Equipment-as-a-Service Expansion | Per-project fee bundling in Southeast Asia addresses capital constraints while capturing recurring revenue from irregular contract flows. |
| Independent Calibration Network Buildout | Unbundled service contracts for German and French oceanographic institutes exploit incumbents' reluctance to customize maintenance offerings. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of IMO type-approval databases, EU Marine Strategy Framework Directive implementation reports, and national hydrographic service procurement records. The research combined structured interviews with hydrographic survey contractors, fleet managers at Norwegian fishing cooperatives, METI aquaculture technology officers, and calibration service technicians with validation against customs trade data, SEC filings from listed marine electronics vendors, and NOAA charting program budget disclosures. Bottom-up vessel fleet analysis and top-down market sizing triangulate volume estimates across the analysis window.
Forecast inputs span multi-beam versus single-beam penetration rates by vessel class, fixed-installation deployment timelines under precision aquaculture mandates, and portable unit channel shift toward direct e-commerce. Segmentation modeling covers product type, end-use sector, technology architecture, and application mandate intensity. CAGRs derive from regression against historical replacement cycles, regulatory compliance deadlines, and offshore energy licensing rounds. Industry-specific inputs include transducer ceramic supply capacity expansion and acoustic data scientist workforce growth trajectories.
Macroeconomic conditions sit as an overlay; deviation in offshore energy capital expenditure cycles, container freight rates, or yen-euro exchange volatility would shift the trajectory. Forecasts reflect documented assumptions on REACH compliance timelines and IMO emissions rule enforcement stringency. Material shifts in AUV platform adoption rates or laser bathymetry technical capabilities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Calibrator Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Europe Vibration Sensors Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
Magnetoresistive Sensors Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
South Korea Sensors Market