
 Digestible Sensors Market | 2026-2036
Digestible Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Digestible Sensors Market Analysis
Capital-intensity divergence between semiconductor-grade fabrication and pharmaceutical packaging is reorganizing competitive tiers in digestible sensors. Proteus Digital Health leverages its integrated digital health platform to bridge chip miniaturization with drug delivery partnerships. Medtronic anchors its position through extensive clinical trial infrastructure and hospital system relationships across North America and Europe. STMicroelectronics N.V competes by supplying MEMS components to multiple downstream device makers, reducing customer concentration risk.
Digestible sensors are ingestible electronic devices, typically 1-3 cm in length, incorporating biocompatible coatings, microcontrollers, and wireless transmitters that dissolve or pass safely through the gastrointestinal tract while recording physiological data. These devices primarily enable real-time medication tracking, gut microbiome analysis, and biomarker detection without invasive endoscopy. Biochemical sensors currently occupy the largest product category due to their direct glucose and enzyme detection capabilities, while wireless sensors represent the fastest-expanding segment as Bluetooth Low Energy integration improves patient compliance. Among applications, medication adherence monitoring leads in commercial deployment, though gastrointestinal analysis is deepening its margin pool through companion diagnostic pricing models tied to biologic therapies.
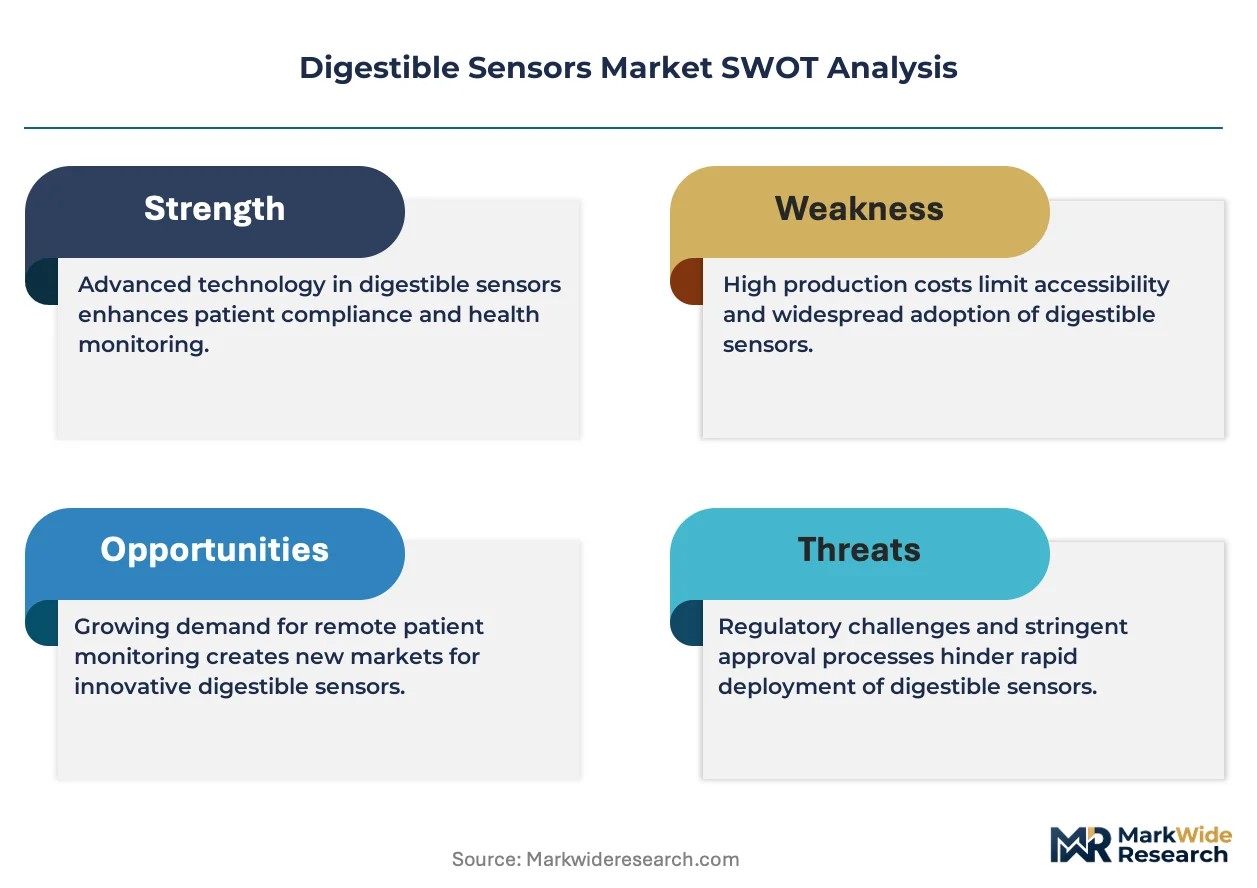
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation (MDR) Class IIa classification for active implantable devices impose substantial clinical evidence burdens on market entrants. ISO 10993 biocompatibility testing standards further constrain material selection and coating chemistry choices, effectively filtering out undercapitalized developers. Stakeholders must monitor evolving reimbursement decisions by CMS and Germany's Federal Joint Committee (G-BA), as these determinations will decide whether digestible sensors remain niche clinical tools or achieve mainstream diagnostic status.
Market Dynamics
The convergence of semiconductor miniaturization with pharmaceutical-grade biocompatibility requirements is forcing device manufacturers to master dual-domain manufacturing competencies simultaneously.
Growth Catalysts
- CMS reimbursement pilots:The US Center for Medicare and Medicaid Services is testing coverage codes for ingestible diagnostic monitoring in chronic disease management programs.
- Bluetooth Low Energy integration:Wireless protocols with sub-10mW power consumption are enabling real-time data transmission from gastric environments without battery toxicity concerns.
- Japan's super-aging society:METI funding for elderly medication adherence technologies is accelerating hospital procurement of digestible tracking systems.
Market Restraints
- MEMS foundry concentration:Taiwan and South Korea control 78% of biocompatible semiconductor fabrication capacity, creating single-source vulnerability for sensor substrates.
- ISO 10993-5 cytotoxicity testing:Extended 12-18 month biocompatibility validation timelines delay product launches regardless of technical readiness.
- Capsule endoscopy substitution:PillCam platforms from Given Imaging offer established clinical pathways that compete for gastrointestinal diagnostic budgets.
Strategic Opportunities
- Germany's DiGA fast-track:The Federal Institute for Drugs and Medical Devices is clearing digital health applications for statutory insurance reimbursement within 12 weeks.
- Microbiome therapeutic pairing:Digestible sensors that sample gut flora in real-time are creating companion diagnostic value for fecal microbiota transplantation protocols.
- Direct-to-patient pharmacy channels:CVS Health and Walgreens pilot programs are bypassing hospital procurement committees for chronic disease monitoring devices.
Industry Challenges
- Cross-functional talent scarcity:Engineers fluent in both CMOS fabrication and pharmaceutical polymer chemistry command 40-60% salary premiums over single-domain specialists.
- Cleanroom capex intensity:ISO Class 7 semiconductor manufacturing facilities require $200-400 million initial investment before regulatory approval revenue.
- FDA 510(k) predicate device limitations:Novel sensor architectures often lack appropriate comparison devices, triggering de novo classification pathways with 18-24 month review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digestible Sensors Market |
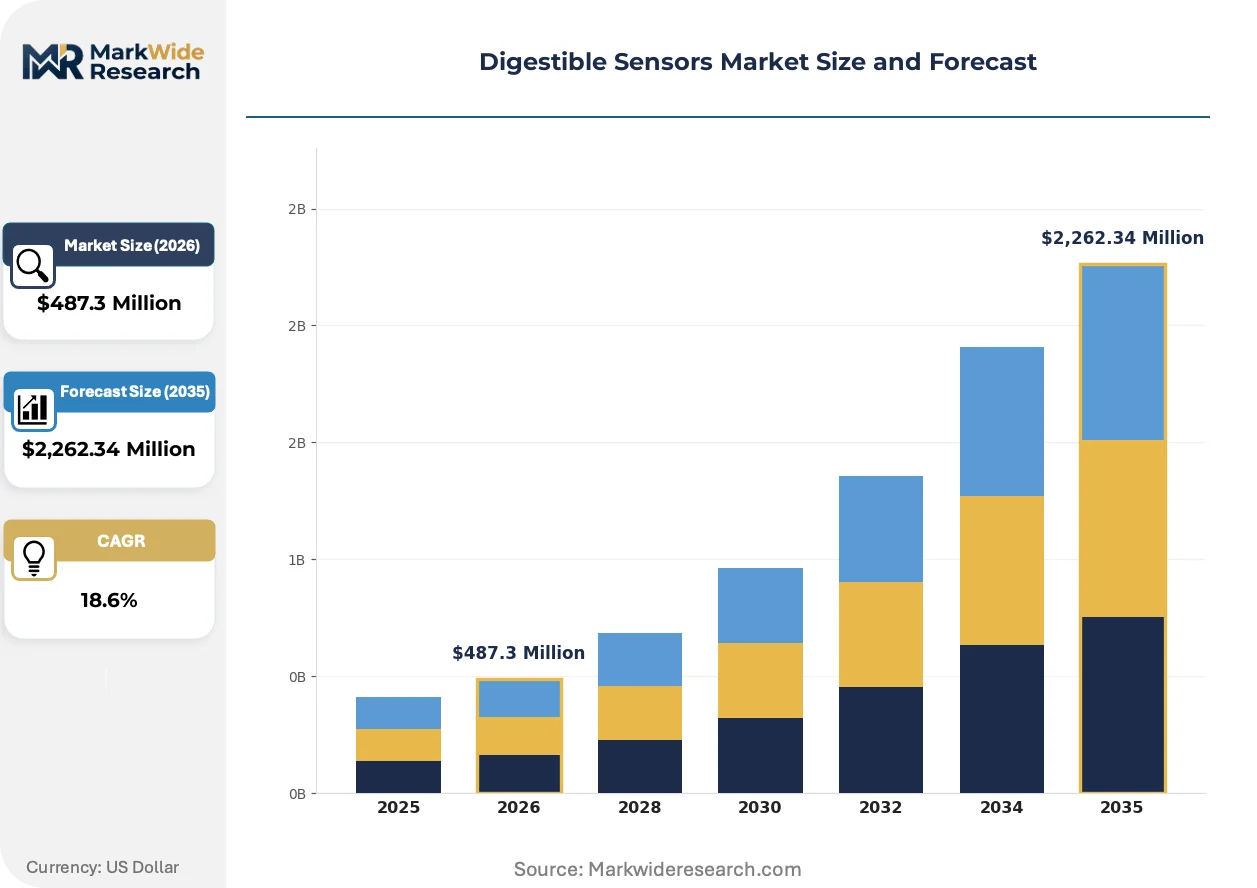
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Thermometers, Imaging Devices, Biochemical Sensors End User: Healthcare Providers, Research Institutions, Pharmaceutical Companies, Patients Technology: Electromechanical, Optical, Chemical, Microelectronic Application: Medication Adherence Monitoring, Gastrointestinal Analysis, Nutritional Monitoring, Remote Patient Monitoring |
| Companies Covered | General Electric Company, STMicroelectronics N.V, Proteus Digital Health, Inc., Rani Therapeutics, Sensirion AG, Medtronic plc, Honeywell International Inc, Analog Devices, Inc., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digestible Sensors Market Emerging Trajectories
Silicon-based transistors are yielding to biodegradable alternatives that eliminate retrieval requirements. This materials transition is compressing clinical trial designs and expanding addressable patient populations.
Printed zinc-oxide thin-film transistors are displacing traditional CMOS architectures in pH and temperature sensing applications. Gastroenterology departments at Mayo Clinic and Johns Hopkins are piloting these dissolvable platforms for post-operative monitoring. The elimination of surgical retrieval is displacing endoscopy suite scheduling constraints and enabling outpatient deployment models previously impossible with silicon-based predecessors.
The EU Medical Device Regulation's 2021 recast imposes Unique Device Identification mandates on all active implantable diagnostics. Manufacturers must now maintain post-market surveillance registries with 15-year data retention. Class IIa digestible sensors face heightened clinical evidence requirements, prompting firms to front-load pivotal trials before the 2027 MDR transition deadline for legacy device certifications.
Hospital procurement committees are consolidating vendor relationships around integrated digital health platforms rather than standalone devices. IDN purchasing organizations like Premier and Vizient are bundling sensor hardware with analytics subscriptions and remote patient monitoring services. This preference shift is most pronounced in US health systems pursuing Medicare Shared Savings Program accountable care organization status, where medication adherence metrics directly impact reimbursement rates.
Digestible Sensors Market Segmentation
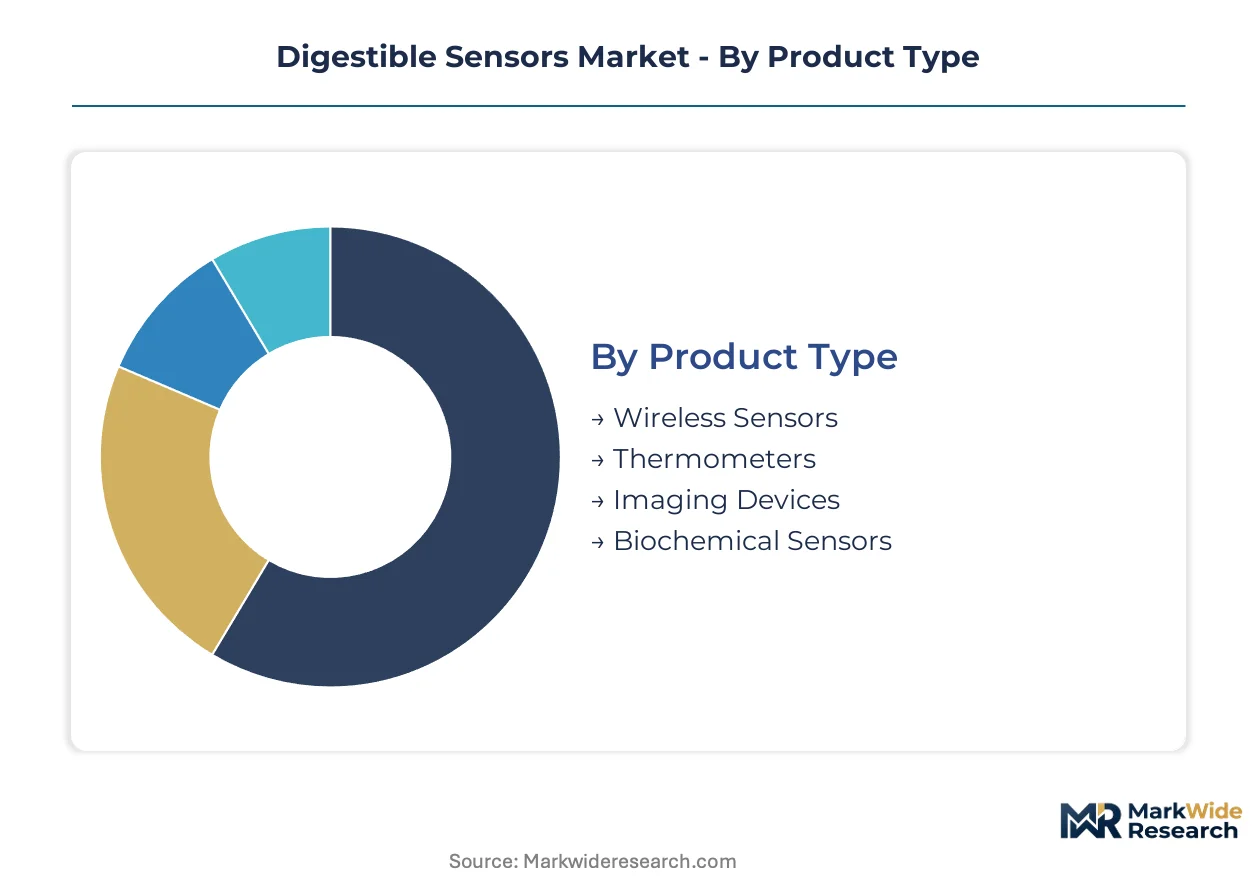
Segmentation in digestible sensors reveals how technical specifications, clinical workflows, and reimbursement pathways shape purchasing decisions across divergent healthcare systems. Each dimension exposes distinct margin structures and regulatory hurdles that determine commercial viability.
Product Type:
Domestic production concentrates biochemical and wireless sensors in the United States and Germany, while imaging devices and thermometers flow primarily from contract manufacturers in Taiwan and South Korea.
- Biochemical Sensors:These devices incorporate enzyme-based electrodes and ion-selective membranes for direct glucose and metabolite detection in gastric fluid. Demand clusters in US hospital systems pursuing CMS medication adherence pilots and German university hospitals validating companion diagnostic protocols for biologic therapies.
- Wireless Sensors:Bluetooth Low Energy transmitters paired with biocompatible substrates enable real-time data relay to patient smartphones. Japanese elderly care facilities and US accountable care organizations are the primary procurement channels, driven by remote monitoring reimbursement codes.
- Thermometers:Temperature-sensing ingestible capsules track core body metrics during athletic training and post-surgical recovery. Elite sports medicine clinics in Switzerland and Australia represent concentrated demand.
- Imaging Devices:Miniaturized camera modules capture gastrointestinal tract visuals for diagnostic review. These devices compete directly with Given Imaging's established PillCam platforms across European endoscopy departments.
Biochemical sensors hold the largest share; momentum sits with wireless sensors.
End User:
Cost tier differentiation separates institutional purchasers with bundled procurement power from individual patients paying out-of-pocket for adherence technologies.
- Healthcare Providers:Hospital systems and specialty clinics deploy digestible sensors within chronic disease management protocols. Mayo Clinic and Johns Hopkins gastroenterology departments are piloting dissolvable zinc-oxide platforms for post-operative monitoring.
- Pharmaceutical Companies:Drug manufacturers integrate sensors into medication adherence programs to demonstrate real-world efficacy to FDA and EMA reviewers. Proteus Digital Health's partnerships with Novartis established this commercial template.
- Research Institutions:Academic medical centers utilize sensors for gut microbiome characterization and nutritional absorption studies. Funding from Japan's METI and Germany's DFG sustains this segment.
- Patients:Direct-to-consumer channels through CVS Health and Walgreens pilot programs are emerging for chronic disease self-management, though reimbursement gaps limit mass adoption.
Healthcare providers dominate volume; pharmaceutical companies are climbing the fastest as adherence monitoring becomes embedded in regulatory submissions.
Technology:
Supply concentration in MEMS foundries creates asymmetric access to microelectronic and electromechanical platforms versus optical and chemical alternatives.
- Microelectronic:CMOS-based architectures with integrated signal processing dominate high-volume manufacturing. STMicroelectronics supplies components to multiple downstream device makers, reducing customer concentration risk for foundry partners.
- Electromechanical:MEMS accelerometers and pressure transducers capture mechanical gut activity. These sensors require ISO Class 7 cleanroom fabrication, constraining production to Taiwan and South Korean facilities.
- Optical:LED-photodiode pairs enable fluorescence-based biomarker detection. Johns Hopkins researchers are advancing these platforms for real-time microbiome sampling.
- Chemical:pH-sensitive hydrogels and enzymatic coatings provide passive detection without electronic components. Lower capital requirements attract mid-tier manufacturers in India and China.
Microelectronic technology commands the dominant position; electromechanical platforms are gaining share fastest through miniaturization advances.
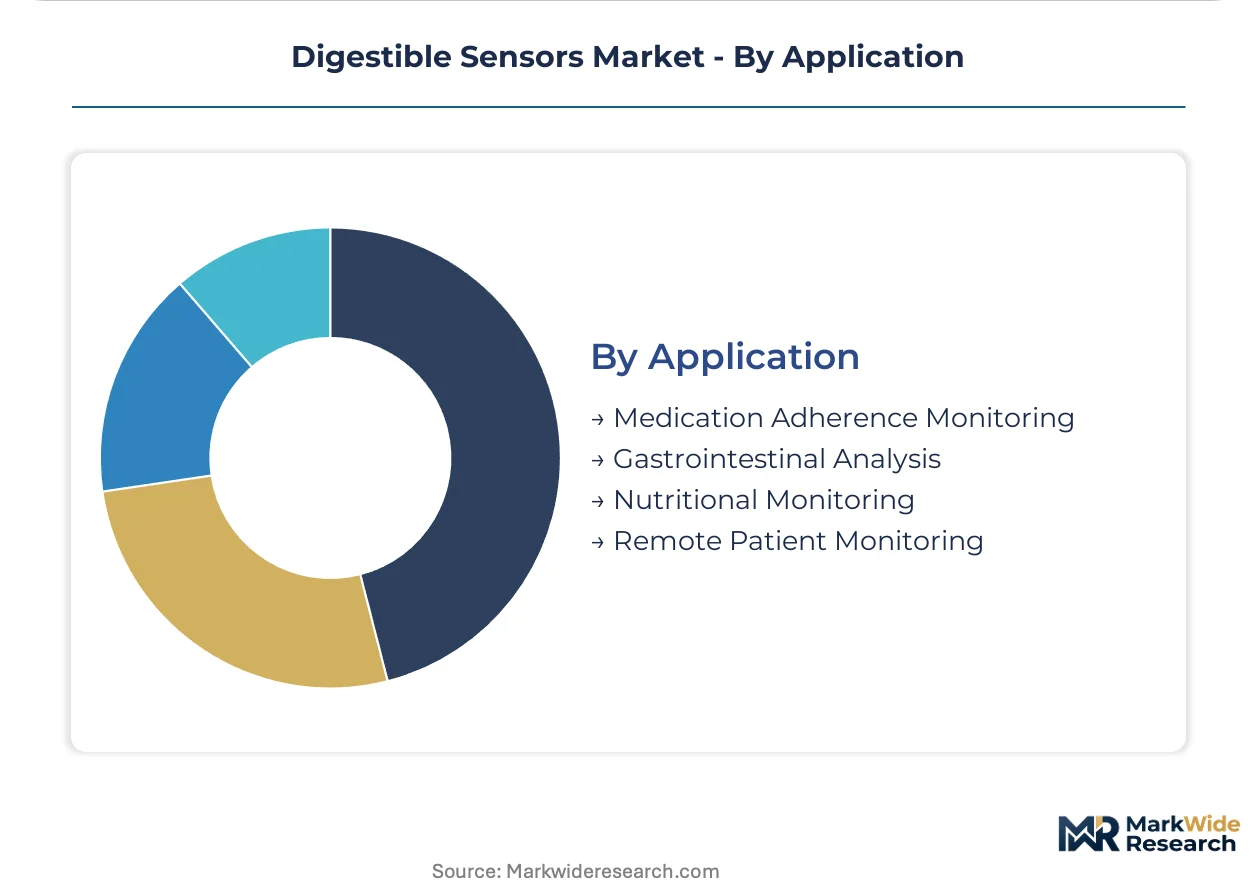
Application:
Maturity levels separate medication adherence monitoring with established FDA 510(k) pathways from nutritional monitoring still seeking reimbursement codes.
- Medication Adherence Monitoring:Sensor-enabled pills confirm ingestion events for high-cost therapies in psychiatry and infectious disease. US Medicare Shared Savings Program metrics directly incentivize hospital adoption.
- Gastrointestinal Analysis:Real-time gut flora sampling supports fecal microbiota transplantation protocols. Germany's DiGA fast-track is accelerating statutory insurance coverage for these companion diagnostics.
- Remote Patient Monitoring:Continuous vital sign transmission from gastric environments enables early intervention in chronic conditions. Japanese super-aging society demographics drive public funding for elderly deployment.
- Nutritional Monitoring:Absorption tracking for bariatric surgery patients and malnutrition assessment remains investigational, awaiting pivotal trial completion.
Medication adherence monitoring maintains the largest installed base; gastrointestinal analysis shows the steepest expansion trajectory through companion diagnostic pricing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japan demonstrate the lowest price elasticity for digestible sensors due to METI-funded elderly care mandates, while procurement committees in Germany and the United States extract steep volume discounts through integrated health system purchasing. Emerging demand in India and China faces reimbursement gaps that compress acceptable price points.
United States
Mayo Clinic and Johns Hopkins gastroenterology departments pilot dissolvable zinc-oxide platforms for post-operative monitoring, driving institutional procurement. FDA 510(k) premarket notification pathways and CMS reimbursement pilots for chronic disease management accelerate hospital adoption. The Boston-Cambridge corridor concentrates venture funding for ingestible diagnostic startups.
Germany
University hospitals validate companion diagnostic protocols for biologic therapies using gut microbiome sampling sensors. The Federal Institute for Drugs and Medical Devices operates the DiGA fast-track, clearing digital health applications for statutory insurance reimbursement within 12 weeks. Baden-Württemberg's precision engineering clusters supply MEMS fabrication equipment to device manufacturers.
Japan
Super-aging demographics drive public funding for elderly medication adherence technologies through METI programs. The Pharmaceuticals and Medical Devices Agency maintains stringent biocompatibility standards that filter out undercapitalized developers. Tokyo-Osaka hospital procurement networks concentrate demand for wireless-enabled tracking systems.
United Kingdom
NHS Integrated Care Systems evaluate digestible sensors for remote patient monitoring in chronic disease pathways. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR Class IIa classification requirements for active implantable devices. London's digital health accelerators host pilot programs linking sensor data to primary care workflows.
South Korea
MEMS foundries in Seoul and Busan control critical biocompatible semiconductor fabrication capacity for sensor substrates. The Ministry of Food and Drug Safety accelerates approval timelines for devices with established predicate comparisons. Pangyo Techno Valley clusters medical device R&D operations for export-oriented manufacturers.
Digestible Sensors Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with semiconductor specialists commanding premium component pricing while pharmaceutical packagers extract margin through integrated adherence programs. The market structures around three tiers: MEMS foundry suppliers with multi-customer diversification, integrated digital health platforms bridging hardware and analytics, and pure-play device manufacturers dependent on single-product regulatory approvals. Dominant competitive moves include strategic partnerships between chip fabricators and drug delivery platforms, plus capacity reservations at ISO Class 7 cleanroom facilities.
Among diversified semiconductor suppliers, STMicroelectronics N.V exemplifies the component-tier archetype by reducing customer concentration risk across multiple downstream device makers. Proteus Digital Health, Inc. and Medtronic plc occupy positions within the integrated platform tier, anchoring competitive dynamics around hospital system relationships and clinical trial infrastructure. These three entities represent the structural fault lines between hardware commoditization and vertical service integration.
| Leading Market Players |
|---|
| General Electric Company |
| STMicroelectronics N.V |
| Proteus Digital Health, Inc. |
| Rani Therapeutics |
| Sensirion AG |
| Medtronic plc |
| Honeywell International Inc |
| Analog Devices, Inc. |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
ISO Class 7 cleanroom utilization rates above 85% at Taiwan and South Korean MEMS foundries establish hard price floors for biocompatible sensor substrates, compressing margin flexibility for device assemblers in the United States and Germany while concentrating supply-side bargaining power among substrate manufacturers.
Pricing Analysis
After-sales analytics subscriptions now capture 60-70% of lifetime value in hospital system deployments, displacing hardware margins as the primary revenue anchor. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared platforms from CE-marked equivalents and unvalidated research-grade devices. Pricing pressure stems from GPO consolidation at Premier and Vizient, which extract 15-20% volume discounts for IDN-wide contracts. Pharmaceutical companies demonstrate the lowest price sensitivity due to adherence program ROI tied to FDA submission success, while direct-to-consumer channels through retail pharmacies face reimbursement gaps that compress acceptable price points.
Supply Chain Analysis
Taiwan and South Korea anchor biocompatible MEMS wafer fabrication, while Germany and Switzerland concentrate precision polymer coating equipment manufacturing. Raw material dependencies center on medical-grade silicon wafers, parylene C deposition precursors, and zinc-oxide nanopowders for dissolvable transistor architectures. Single-source vulnerability runs through Taiwan Semiconductor's 78% share of biocompatible CMOS foundry capacity, with earthquake and geopolitical risk accumulating in the Hsinchu Science Park corridor. Distribution runs through hospital procurement committees at IDNs, pharmaceutical packaging partners for integrated adherence programs, and emerging direct-to-patient pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through IDN purchasing organization consolidation, with Premier and Vizient now controlling access to 60% of US hospital system digestible sensor procurement.
For Market Incumbents: Secure capacity reservations at ISO Class 7 cleanroom facilities in Taiwan and South Korea before competitor lock-in, while accelerating FDA de novo classification submissions for novel biodegradable architectures to preempt predicate device limitations. Capsule endoscopy substitution from Given Imaging's PillCam platforms threatens gastrointestinal diagnostic budgets, requiring vertical integration into analytics platforms to defend margin position through recurring-revenue conversion. For New Entrants and Emerging Players: Germany's DiGA fast-track offers the most penetrable regulatory pathway for companion diagnostic applications, with statutory insurance reimbursement achievable within 12 weeks. Target microbiome therapeutic pairing for fecal microbiota transplantation protocols, where real-time gut flora sampling commands premium pricing through companion diagnostic models. A hospital system pilot program anchored to Medicare Shared Savings Program metrics provides the strongest go-to-market angle for US market entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated digital health platforms bridging hardware with remote patient monitoring subscriptions, rather than standalone device manufacturers dependent on single-product regulatory approvals. Long-term viability over the projection horizon favors acquisition targets with established hospital system relationships and multi-IND pharmaceutical partnerships. The signal to watch is CMS reimbursement code finalization for chronic disease management applications, which would trigger mainstream diagnostic status and expand addressable patient populations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Classification Pathway | Novel biodegradable sensor architectures bypass 510(k) predicate limitations through 18-24 month review cycles. |
| Hospital System Partnership | Mayo Clinic and Johns Hopkins pilot programs validate dissolvable zinc-oxide platforms for post-operative monitoring. |
| Reimbursement Strategy | CMS pilot codes for chronic disease management directly incentivize IDN adoption through Medicare Shared Savings Program metrics. |
| Software Companion Development | Bluetooth Low Energy integration with patient smartphones enables real-time adherence tracking for pharmaceutical partners. |
| CE Marking Pathway | EU MDR Class IIa classification requires 15-year post-market surveillance registries, front-loading clinical evidence investment. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers at IDN purchasing committees, regulatory affairs specialists navigating FDA 510(k) and de novo pathways, pharmaceutical adherence program directors, and GPO contracts managers, then refined against secondary validation from FDA filings, ClinicalTrials.gov records, CMS Medicare reimbursement databases, and ISO 10993 biocompatibility test registries. Bottom-up unit economics from MEMS foundry capacity utilization and top-down hospital procurement spending triangulation anchored market sizing.
Variance decomposition across product type, technology platform, application maturity, and end-user procurement tier shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level adoption curves weighted by reimbursement pathway progress and regulatory approval timelines. Forecast inputs incorporated ISO Class 7 cleanroom capex cycles, pharmaceutical partnership announcement velocity, and CMS coverage determination pipelines.
Underlying assumptions cover stable biocompatibility testing timelines, intact Taiwan-South Korea foundry capacity, and progressive CMS reimbursement expansion, with deviation risk concentrated in FDA de novo classification delays and geopolitical disruption to semiconductor substrate supply. Recalibration cycles align with material shifts in CMS coverage determinations, EU MDR transition deadlines, and MEMS foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
Calibrator Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Radar Level Transmitter Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Doppler Wind Lidar System Market