
 Global Linear Encoder Market | 2026-2036
Global Linear Encoder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Linear Encoder Market Outlook
Market Context
The EU F-Gas Regulation is restructuring capital equipment sourcing across European precision manufacturing, compelling encoder suppliers to certify thermal stability under fluorinated gas phase-outs. Heidenhain GmbH leverages its captive glass-grinding capacity to anchor premium optical encoder supply for semiconductor lithography. Renishaw plc competes through in-house photonics R&D, sustaining patent density in interferometric measurement subsystems. Nidec Corporation dominates magnetic encoder volumes by controlling ferrite sintering and magnetization processes in-house.
Technical Definition and Segment Structure
A linear encoder is a electromechanical position sensor that converts linear displacement into digital or analog signals, typically achieving resolutions below one micrometer through optical grating interference, magnetic pole pitch detection, or capacitive fringe-field modulation. Optical encoders maintain the highest precision tier for semiconductor lithography and CNC grinding, while magnetic encoders displace them in contaminated industrial environments where coolant mist degrades glass scales. Absolute encoders command margin premiums in safety-critical robotics and aerospace actuation, whereas incremental architectures retain cost advantages in material handling conveyors and 3D printing gantries.
Regulatory Frame and Outlook
Japan's METI enforces JIS B 6188 accuracy grades for machine tool feedback devices, while China's GB/T 17421.2 standard governs CNC positioning verification and SAMR certifies encoder interfaces for domestic industrial control systems. The EU Machinery Directive and CE marking requirements compel functional safety ratings in collaborative robotics, filtering encoder suppliers by ISO 13849 compliance. Stakeholders must monitor convergence between encoder cybersecurity protocols and IEC 62443 industrial network standards as factory digitization accelerates.
Market Dynamics
REACH substance restrictions on heavy metals in electronic components are forcing encoder manufacturers to abandon traditional glass-scale optical designs and requalify magnetic and capacitive sensing architectures for precision applications.
Growth Catalysts
- Semiconductor lithography expansion:Taiwan and South Korean fabrication equipment builders are scaling encoder procurement for wafer positioning stages, pulling high-resolution optical units into volume production.
- China's domestic CNC toolbuilding:SAMR-certified encoder interfaces are penetrating local machine tool supply chains, replacing imported feedback devices in five-axis machining centers.
- EU F-Gas Regulation phase-out:Thermal stability certification requirements are filtering encoder suppliers for European precision manufacturing, creating replacement demand for fluorinated-gas-compatible designs.
Market Restraints
- Glass substrate supply concentration:Premium optical encoder production depends on captive grinding capacity concentrated in Germany and Japan, creating input bottlenecks during demand surges.
- Magnetic encoder temperature drift:Ferrite magnetization instability above 80°C limits magnetic architectures in high-speed spindle feedback, constraining addressable applications.
- REACH compliance recertification costs:Heavy metal substitution in scale materials requires multi-year requalification cycles with machine tool OEMs, freezing supplier rotations.
Strategic Opportunities
- India's PLI scheme for machine tools:Production-linked incentives for domestic CNC manufacturing are opening encoder procurement channels previously locked to Japanese and European suppliers.
- Collaborative robotics safety integration:ISO 13849-compliant absolute encoders are penetrating collaborative robot joint actuation as functional safety mandates expand beyond automotive.
- Capacitive-optical hybrid architectures:Fringe-field modulation combined with interferometric verification is automating sub-micron calibration in semiconductor metrology equipment.
Industry Challenges
- Photonics assembly technician scarcity:Precision optical encoder manufacturing requires grating alignment specialists with interferometry expertise, constraining capacity expansion in Taiwan and South Korea.
- IEC 62443 cybersecurity integration:Factory digitization is forcing encoder suppliers to embed network security protocols into legacy incremental interfaces, extending development timelines.
Report Scope
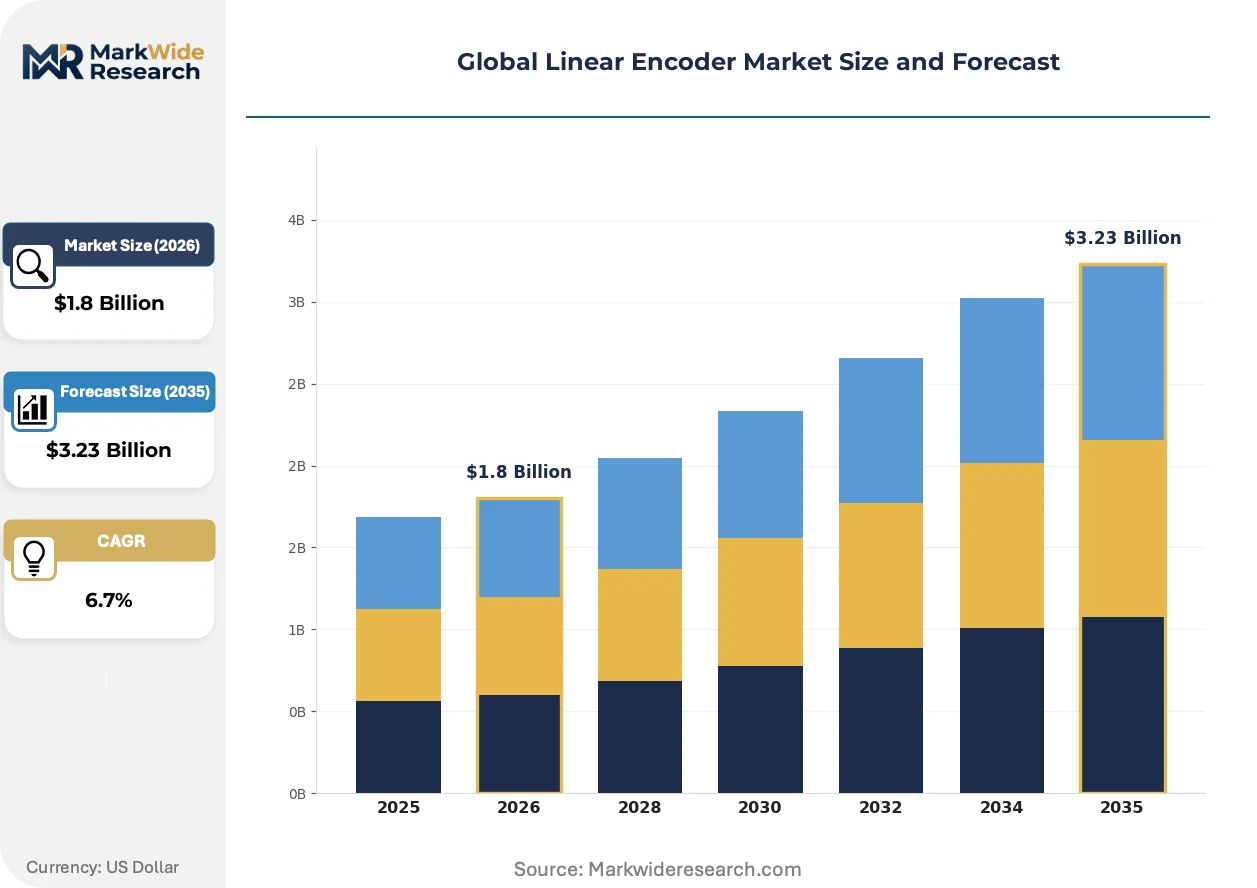
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Linear Encoder Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Encoders, Optical Encoders, Capacitive Encoders, Inductive Encoders Technology: Incremental, Absolute, Hybrid, Resonant End User: Automotive, Industrial Automation, Aerospace, Electronics Application: Robotics, CNC Machines, 3D Printing, Material Handling |
| Companies Covered | Heidenhain GmbH, Renishaw plc, Nidec Corporation, Baumer Group, Omron Corporation, Celera Motion Inc., Kübler Group, Magnescale Co. Ltd., Leine & Linde AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Linear Encoder Market Strategic Shifts
Encoder architectures are bifurcating between contamination-tolerant magnetic designs for shop-floor machinery and vacuum-compatible optical systems for semiconductor front-end equipment, with interface standardization lagging behind hardware evolution.
Capacitive fringe-field sensing is automating position feedback in medical imaging gantries and semiconductor wafer handling robots where optical contamination risks and magnetic field interference exclude competing technologies. Diagnostic equipment manufacturers in Germany and Japan are adopting these architectures for MRI-compatible motion stages. The technology is automating encoder integration into previously inaccessible cleanroom and shielded environments without resolution degradation.
Japan's METI is enforcing JIS B 6188 accuracy grade harmonization across machine tool feedback devices, compelling encoder suppliers to recalibrate certification documentation for cross-border equipment shipments. The regulation is compressing supplier qualification cycles from 18 months to 9 months for compliant architectures. South Korean and Taiwanese CNC builders are prioritizing JIS-certified encoders to streamline export documentation to Southeast Asian assembly plants.
Machine tool OEMs are unbundling encoder specification from bundled spindle packages, forcing component suppliers to establish direct technical relationships with end-user maintenance departments. This disintermediation is fragmenting procurement authority across original equipment manufacturers and aftermarket service channels. The pattern is most visible in China's domestic CNC sector, where state-owned automotive manufacturers now specify feedback devices independently of machine tool sourcing.
Global Linear Encoder Market Segmentation
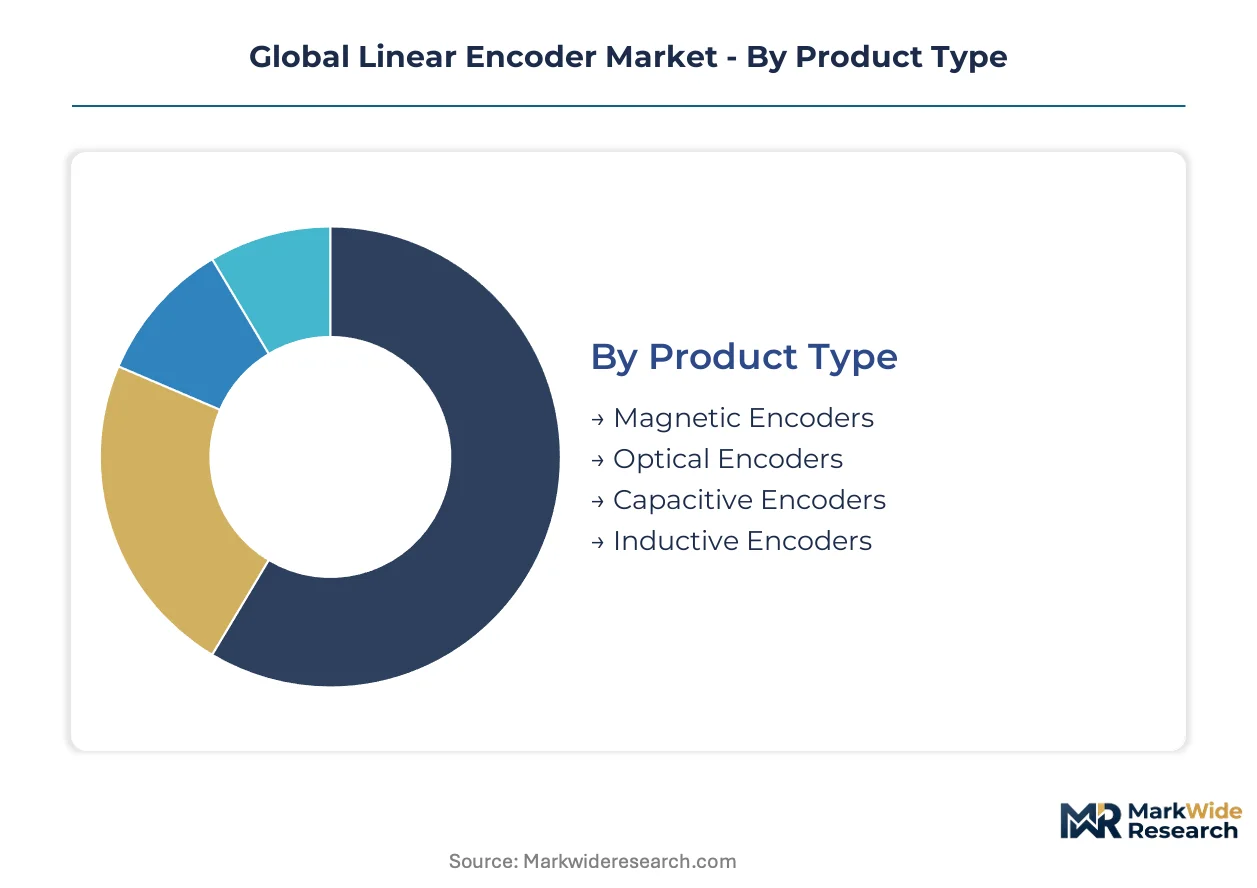
Encoder specification cascades through four interdependent dimensions: sensing physics determines environmental tolerance, interface architecture dictates system integration cost, end-use verticals impose certification requirements, and motion platform geometry fixes mechanical packaging constraints.
Product Type:
Buyers select sensing physics based on contamination exposure and precision requirements.
- Optical Encoders:Glass-scale gratings with interferometric readheads achieve sub-micron resolution for semiconductor lithography stages. Taiwan and South Korean fab equipment builders anchor procurement volumes as wafer positioning tolerances tighten below 10 nanometers.
- Magnetic Encoders:Ferrite pole tracks with Hall-effect or magnetoresistive sensing withstand coolant mist and metallic debris in CNC machining centers. China's domestic machine tool sector is displacing optical units in five-axis equipment where enclosure sealing costs outweigh precision trade-offs.
- Capacitive Encoders:Fringe-field modulation between etched electrodes eliminates particulate sensitivity and magnetic interference for MRI-compatible medical gantries.
- Inductive Encoders:Eddy-current position sensing operates through non-ferrous barriers in sealed aerospace actuators and submersible robotics.
Volume sits with magnetic architectures in general machinery; growth tilts toward capacitive designs in medical and semiconductor handling applications.
Technology:
Interface selection hinges on homing requirements, safety integrity levels, and controller compatibility.
- Incremental:Quadrature output with index pulse minimizes unit cost and controller overhead for velocity-controlled conveyors and printing systems. Material handling OEMs in Germany and Japan standardize on 5V differential line driver interfaces for noise immunity across long cable runs.
- Absolute:Multi-turn position retention via battery-backed or geartrain encoding eliminates homing cycles in collaborative robotics and aerospace flight controls. ISO 13849 compliance mandates are penetrating automotive assembly applications beyond traditional machine tool boundaries.
- Hybrid:Combined incremental track for motion with serial absolute channel for startup positioning bridges legacy controller upgrades.
- Resonant:Surface acoustic wave position sensing achieves vacuum compatibility and radiation hardness for satellite deployment mechanisms.
Incremental units dominate unit shipments; absolute architectures gain share fastest in safety-critical robotics.
End User:
Vertical-specific certification and operating environment dictate supplier qualification pathways.
- Industrial Automation:Machine tool builders and packaging system integrators constitute the core demand base. JIS B 6188 accuracy grade certification from Japan's METI filters supplier pools for cross-border equipment shipments to Southeast Asian assembly plants.
- Electronics:Semiconductor front-end and backend equipment manufacturers specify vacuum-compatible optical encoders with low outgassing materials. Taiwan's lithography stage builders are scaling encoder procurement as advanced node capacity expands.
- Automotive:Powertrain assembly and battery module production lines drive demand for contamination-tolerant magnetic feedback.
- Aerospace:Flight control surface actuation and landing gear positioning mandate DO-178C software assurance and extended temperature operation.
Electronics manufacturing concentrates premium optical volumes; automotive automation expands most quickly as electric vehicle retooling accelerates.
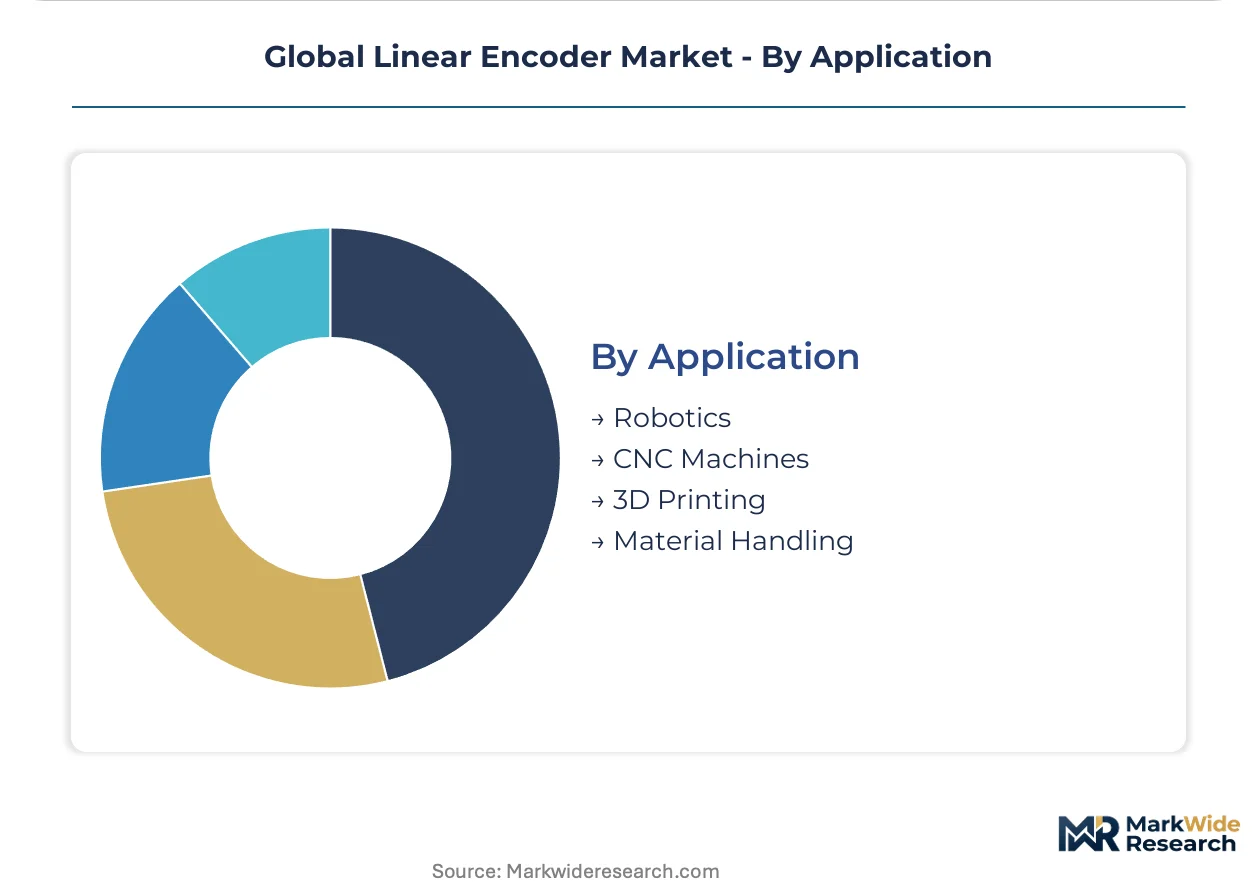
Application:
Motion platform geometry and duty cycle determine encoder mechanical packaging and thermal management.
- CNC Machines:Linear motor and ball-screw axes require sealed encoders with thermal expansion matching cast iron or granite machine bases. China's SAMR-certified encoder interfaces are penetrating domestic five-axis machining centers as import substitution policies tighten.
- Robotics:Articulated arm joints and linear seventh axes demand compact absolute encoders with functional safety ratings. Collaborative robot OEMs in Germany and Denmark specify SIL2/PLd feedback for human-robot interaction zones.
- Material Handling:Overhead gantry and automated storage retrieval systems prioritize encoder durability over precision in warehouse environments.
- 3D Printing:Fused deposition and powder bed fusion gantries use cost-optimized incremental encoders for layer positioning verification.
CNC machinery anchors current installed base; robotics applications climb the fastest as safety mandates expand beyond automotive into logistics and healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Southern Taiwan Science Park anchors semiconductor equipment clustering, concentrating lithography-stage encoder procurement for advanced node fabrication. South Korea's Yongin and Hwaseong corridors drive memory and logic fab expansion. China's Yangtze River Delta and Pearl River Delta manufacturing belts are displacing imported machine tool feedback devices under domestic certification mandates.
Taiwan
Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation are scaling lithography-stage encoder procurement as 3nm and 2nm process ramps accelerate. The National Science and Technology Council coordinates Science Park infrastructure subsidies that concentrate precision equipment vendors in Tainan and Taichung. Hsinchu Science Park hosts the densest cluster of semiconductor metrology equipment builders, pulling high-resolution optical encoder volumes from German and Japanese suppliers.
South Korea
Samsung Electronics and SK Hynix are expanding wafer positioning stage encoder specifications for EUV lithography adoption across Pyeongtaek and Yongin complexes. The Ministry of Trade, Industry and Energy administers K-Semiconductor Belt tax incentives that attract encoder suppliers to Gyeonggi Province. Pangyo Techno Valley has emerged as the primary hub for domestic semiconductor equipment R&D, compressing supplier qualification cycles for local encoder integration.
China
Domestic CNC toolbuilders in Jiangsu and Zhejiang provinces are replacing imported feedback devices with SAMR-certified encoder interfaces for five-axis machining centers. The State Administration for Market Regulation enforces GB/T 17421.2 positioning verification standards that filter supplier pools for state-owned automotive manufacturers. Suzhou and Shenzhen industrial zones concentrate the fastest-growing demand for magnetic encoder architectures in contamination-tolerant machine tool applications.
Germany
Heidenhain GmbH's captive glass-grinding capacity in Traunreut anchors premium optical encoder supply for European semiconductor lithography and CNC grinding equipment. The EU F-Gas Regulation is compelling thermal stability recertification for encoder designs deployed in precision manufacturing. Bavaria's Munich-Stuttgart corridor concentrates diagnostic equipment manufacturers adopting capacitive fringe-field architectures for MRI-compatible motion stages.
Japan
METI enforces JIS B 6188 accuracy grade harmonization across machine tool feedback devices, compressing supplier qualification documentation from 18 months to 9 months for compliant architectures. Nidec Corporation's ferrite sintering and magnetization processes in-house dominate magnetic encoder volumes for industrial automation. The Chubu and Kansai manufacturing belts host the densest concentrations of photonics assembly technicians with interferometry expertise for precision optical encoder production.
Global Linear Encoder Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where captive component capabilities anchor premium positioning while modular suppliers capture volume scale. The vendor base clusters around three strategic archetypes: integrated photonics manufacturers controlling glass substrate supply, magnetic sensing specialists commanding ferrite processing, and interface-agnostic module assemblers serving cost-optimized industrial segments. Competitive moves concentrate on backward integration into scale material production and geographic co-location with semiconductor equipment clusters in Taiwan and South Korea.
Among Germany-based precision equipment fabricators, Heidenhain GmbH exemplifies the integrated photonics archetype through captive glass-grinding operations. Renishaw plc occupies a comparable position within UK-based industrial measurement specialists. Nidec Corporation represents the diversified conglomerate model, leveraging magnetic materials expertise across multiple electromechanical product categories. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Heidenhain GmbH |
| Renishaw plc |
| Nidec Corporation |
| Baumer Group |
| Omron Corporation |
| Celera Motion Inc. |
| Kübler Group |
| Magnescale Co. Ltd. |
| Leine & Linde AB |
| Others |
Value Chain & Pricing Dynamics
Captive glass-grinding operations in Germany and Japan anchor premium optical encoder supply chains, concentrating pricing power among integrated photonics manufacturers while forcing modular suppliers toward magnetic architectures where ferrite processing costs dominate unit economics. REACH substance restrictions on heavy metals in electronic components are compressing margins across glass-scale optical designs as manufacturers absorb multi-year requalification cycles with machine tool OEMs.
Pricing Analysis
Lead-time premiums for short-delivery optical encoders command substantial markups over standard-contract pricing, while spot inventory of magnetic units trades at discounts reflecting China's domestic capacity expansion. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified absolute encoders for collaborative robotics from incremental units for material handling conveyors. Pricing pressure stems from SAMR-certified domestic alternatives displacing imported feedback devices in China's five-axis machining centers. Automotive powertrain assembly lines exhibit highest price sensitivity due to volume procurement mandates, whereas semiconductor lithography stage builders prioritize resolution specifications over unit cost.
Supply Chain Analysis
Freight costs for precision glass substrates from Traunreut to Taiwan's Southern Taiwan Science Park and Hsinchu clusters add substantial landed cost premiums for European optical encoder shipments. Supply concentration in Germany, Japan, and Taiwan draws from captive grinding capacity, specialized photonics assembly labor pools, and semiconductor equipment clustering respectively. Ferrite sintering magnetization instability above 80°C creates single-source vulnerability for high-speed spindle feedback applications. Distribution runs through machine tool OEM bundled packages and direct technical relationships with end-user maintenance departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH compliance recertification costs freeze supplier rotations and favor integrated photonics manufacturers with captive scale material production over modular assemblers.
For Market Incumbents: Extend backward integration into ferrite sintering operations to defend magnetic encoder margins against Nidec Corporation's in-house magnetization dominance. Extend JIS B 6188 certification coverage to compress qualification cycles from 18 months to 9 months for compliant architectures, blocking emerging capacitive specialists from cross-border equipment shipments to Southeast Asian assembly plants.
For New Entrants and Emerging Players: Launch via direct technical relationships with China's state-owned automotive manufacturers, who now specify feedback devices independently of machine tool sourcing. Target India's PLI scheme for machine tools as the most penetrable geography, where production-linked incentives for domestic CNC manufacturing are opening encoder procurement channels previously locked to Japanese and European suppliers. Pursue collaborative robotics safety integration as the primary go-to-market angle, where ISO 13849-compliant absolute encoders penetrate beyond traditional automotive boundaries.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified electromechanical conglomerates seeking magnetic sensing capabilities. Long-term viability favors vertically integrated specialists controlling either glass substrate supply or ferrite processing, with modular assemblers facing margin compression from domestic certification mandates in China. Watch convergence between encoder cybersecurity protocols and IEC 62443 industrial network standards as the signal indicating which suppliers can capture factory digitization spend.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Substrate Production | Heidenhain GmbH's captive Traunreut grinding capacity anchors premium optical encoder supply for semiconductor lithography. |
| JIS B 6188 Certification Investment | METI-enforced accuracy grade harmonization compresses supplier qualification documentation for cross-border equipment shipments. |
| Capacitive-Optical Hybrid Architecture Development | Fringe-field modulation combined with interferometric verification automates sub-micron calibration in semiconductor metrology equipment. |
| Geographic Co-location with Semiconductor Clusters | Taiwan's Southern Taiwan Science Park and South Korea's Yongin corridor concentrate lithography-stage encoder procurement volumes. |
| IEC 62443 Cybersecurity Protocol Integration | Factory digitization forces embedded network security into legacy incremental interfaces, extending development timelines for compliant suppliers. |
Study Parameters
Multi-period observation of encoder procurement patterns from Taiwan and South Korean fab equipment builders anchored the trend analysis, supplemented by interviews with semiconductor metrology equipment R&D directors, CNC toolbuilder procurement teams, machine tool OEM platform engineers, and aftermarket service heads. Secondary validation drew from JIS B 6188 certification databases, SAMR interface registration filings, EU F-Gas Regulation thermal stability documentation, and SEC disclosures from diversified electromechanical conglomerates. Bottom-up segment sizing triangulated against top-down industrial automation equipment production forecasts.
Segment-weighting across sensing physics, interface architecture, end-use vertical, and motion platform geometry dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from equipment installation base expansion rates, replacement cycle analysis, and technology substitution elasticities. Forecast inputs incorporated semiconductor capital expenditure trajectories from Taiwan's National Science and Technology Council infrastructure subsidies and South Korea's K-Semiconductor Belt tax incentive disbursements.
Semiconductor capital expenditure volatility, REACH substance restriction enforcement timing, and magnetic encoder temperature drift limitations are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Window Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Japan Digital Thermometer Market