
 3D Sensors Market | 2026-2036
3D Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
3D Sensors Market Analysis
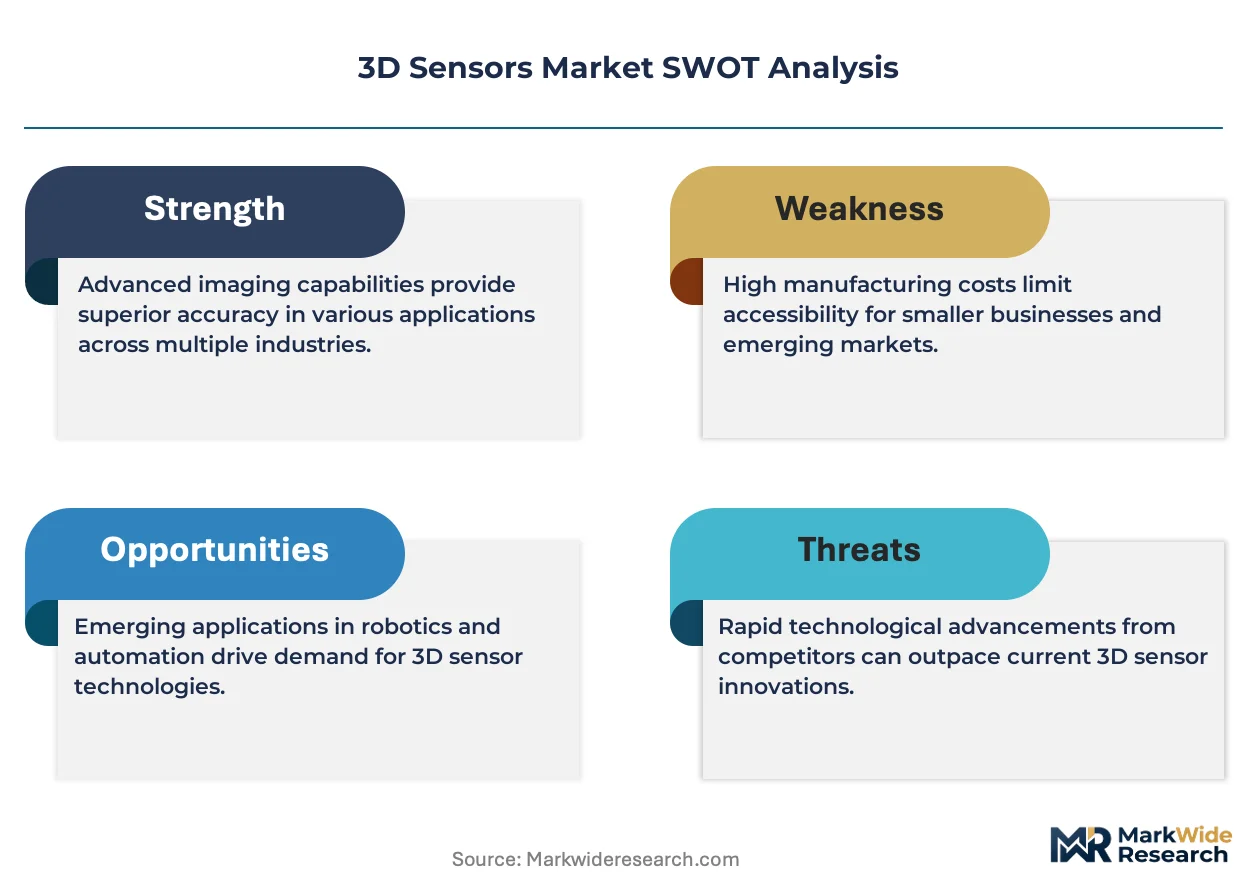
Silicon photonics is shifting the cost structure of 3D sensor modules by replacing traditional gallium arsenide substrates in time-of-flight receivers. Infineon Technologies AG leverages its foundry partnerships to sustain wafer-scale integration of photodetectors and readout circuits. Sony Corporation dominates image sensor supply for consumer and automotive depth cameras. STMicroelectronics specializes in MEMS-based scanning solutions for compact LiDAR modules.
3D sensors are optoelectronic devices that measure spatial depth by emitting structured light, laser pulses, or stereo image pairs and calculating return-time or parallax differentials, typically resolving distances from millimeters to hundreds of meters with frame rates exceeding 30 Hz for real-time applications. Their primary purpose is enabling machines to perceive volumetric geometry for navigation, quality inspection, or human-machine interaction. Time-of-flight cameras lead volume shipments in consumer electronics where slim form factors and low power dominate design priorities. LiDAR technology captures the fastest expansion in automotive and robotics applications requiring long-range precision under variable lighting. Industrial automation applications anchor premium pricing as manufacturers demand sub-millimeter accuracy and IP67 environmental sealing.
The FDA regulates 3D sensors used in surgical navigation and diagnostic imaging under device classification rules requiring clinical validation of spatial accuracy. The EU AI Act imposes conformity assessment obligations on autonomous systems integrating depth perception for safety-critical decisions. REACH restrictions on rare-earth phosphors and RoHS substance limits constrain emitter material choices and supply chain qualification. Stakeholders must monitor evolving harmonized standards for functional safety in automotive LiDAR as type-approval frameworks solidify across major economies.
Market Dynamics
Silicon photonics is compressing module costs by replacing gallium arsenide substrates in time-of-flight receivers, forcing incumbent supply chains to requalify wafer-scale integration processes or cede share to foundry partners.
Growth Catalysts
- EU AI Act conformity requirements:Safety-critical autonomous systems must validate depth perception accuracy under standardized test protocols, creating mandatory upgrade cycles for automotive LiDAR suppliers.
- Industrial automation in Germany:Smart manufacturing investments demand sub-millimeter 3D inspection for quality control, anchoring premium pricing for IP67-sealed sensor modules.
- Solid-state LiDAR beam steering:MEMS-based scanning eliminates mechanical rotating assemblies, reducing form factors and enabling integration into consumer electronics and compact robotics platforms.
Market Restraints
- Rare-earth phosphor supply concentration:REACH restrictions on europium and terbium compounds constrain emitter material choices, forcing suppliers to requalify alternative phosphor formulations.
- Wafer-level packaging bottlenecks:Advanced 3D sensor modules require through-silicon vias and hybrid bonding capabilities concentrated among a limited set of OSAT providers.
- Indoor time-of-flight limitations:Multi-path interference in reflective environments degrades depth accuracy, restricting deployment in warehouse automation and retail analytics applications.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract module assembly and testing operations, creating a secondary supply hub outside East Asian concentration.
- Surgical navigation systems:FDA device classification rules for AI-enabled medical devices create a validated channel for 3D sensors in orthopedic and neurosurgical guidance platforms.
- Edge AI convergence with depth sensing:On-device neural processing units enable real-time point cloud analysis without cloud dependency, opening battery-powered mobile robotics applications.
Industry Challenges
- Functional safety certification timelines:Automotive LiDAR type-approval under evolving ISO 26262 and UN ECE frameworks extends product qualification cycles by 18-24 months.
- Optomechanical assembly skill scarcity:Precision alignment of laser emitters and photodetector arrays requires specialized technicians, constraining manufacturing scale-up.
- Legacy industrial protocol integration:EtherCAT and PROFINET compatibility requirements force sensor vendors to maintain multiple firmware branches, fragmenting R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Sensors Market |
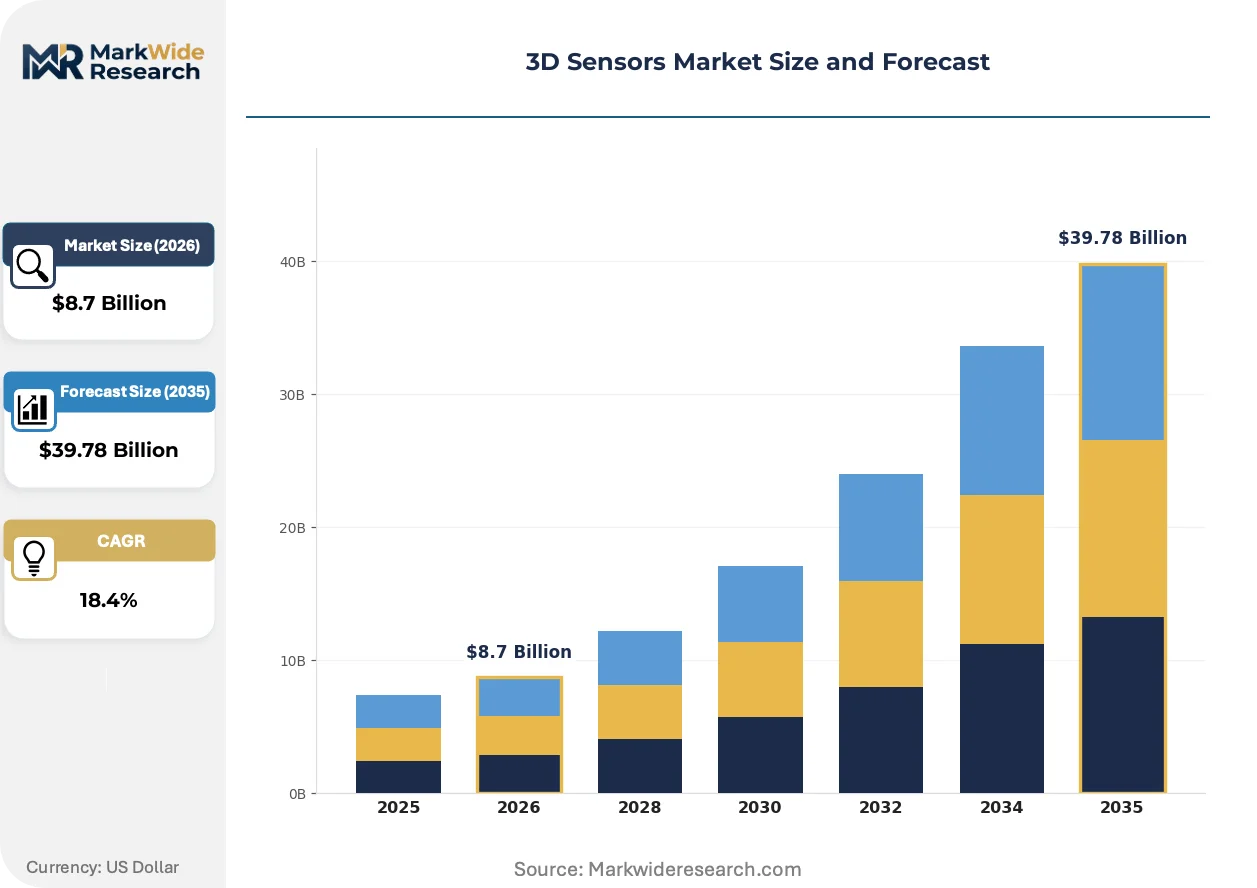
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
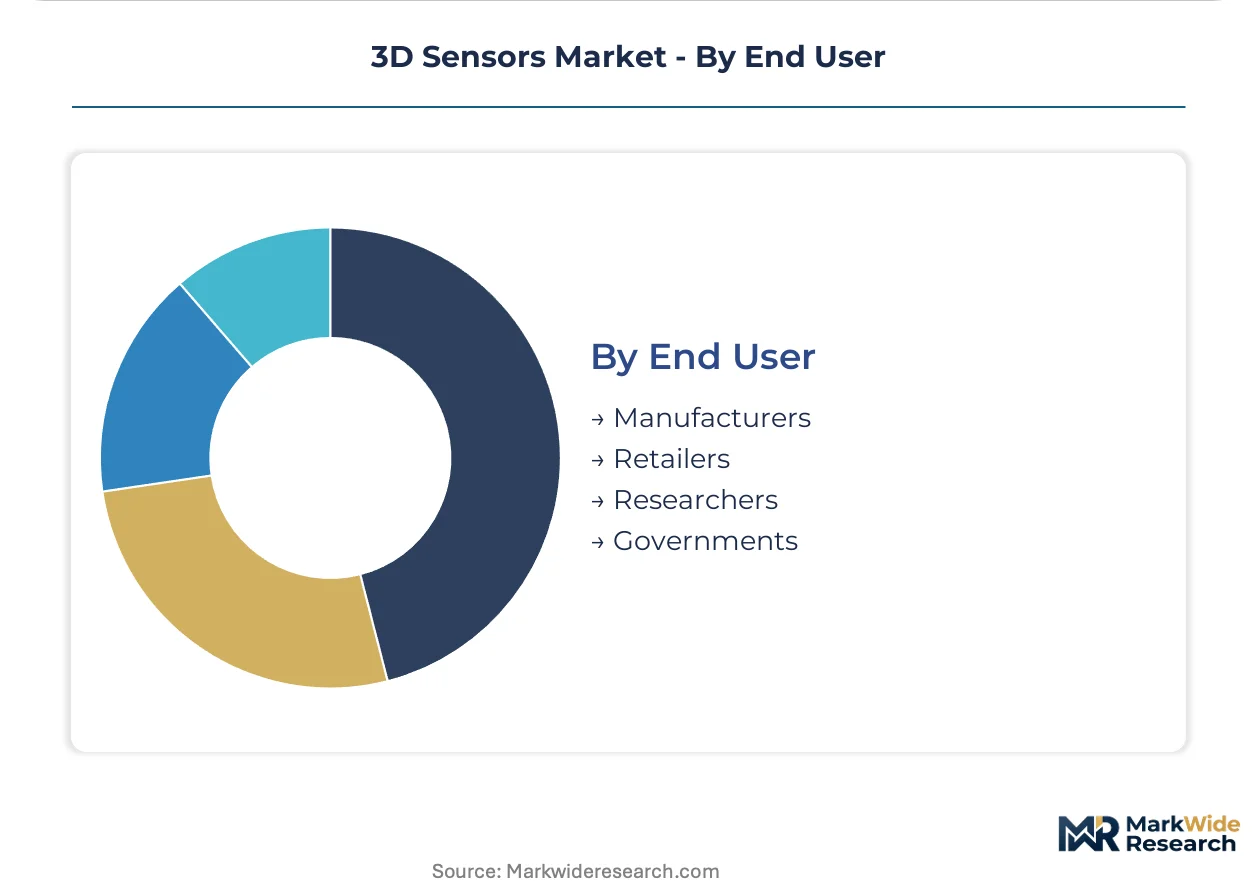
| Segmentation | Product Type: Laser Scanners, Time-of-Flight Cameras, Structured Light Sensors, Depth Cameras Technology: LiDAR, Stereo Vision, Ultrasonic, Photogrammetry Application: Robotics, Automotive, Industrial Automation, Healthcare End User: Manufacturers, Retailers, Researchers, Governments |
| Companies Covered | Infineon Technologies AG, Microchip Technology Inc., Sony Corporation, STMicroelectronics, Cognex Corporation, OmniVision Technologies Inc., Keyence Corporation, Qualcomm Technologies Inc., ifm electronic GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Sensors Market Emerging Trajectories
Photonic integration and regulatory harmonization are restructuring competitive advantage around foundry access and pre-certified module platforms rather than discrete component expertise.
Solid-state silicon photonics is integrating indium phosphide lasers with silicon nitride waveguides on single substrates. Automotive tier-1 suppliers are adopting these platforms for next-generation LiDAR transceivers. The technology is integrating emitter and detector functions at wafer scale, collapsing the traditional multi-chip module supply chain into monolithic foundry outputs.
REACH and RoHS substance restrictions are tightening allowable materials in emitter phosphors and solder alloys. Manufacturers must requalify supply chains under ECHA substance of very high concern listings. Consumer electronics and automotive exterior applications face the steepest compliance costs as they source from high-volume Asian assembly operations.
Buyers in industrial automation are consolidating vendor relationships around pre-certified sensor platforms. System integrators now specify modules with embedded functional safety documentation rather than assembling discrete components. This preference shift concentrates procurement among vendors with in-house regulatory affairs capabilities, visible most acutely in German and Japanese manufacturing equipment markets.
3D Sensors Market Segmentation
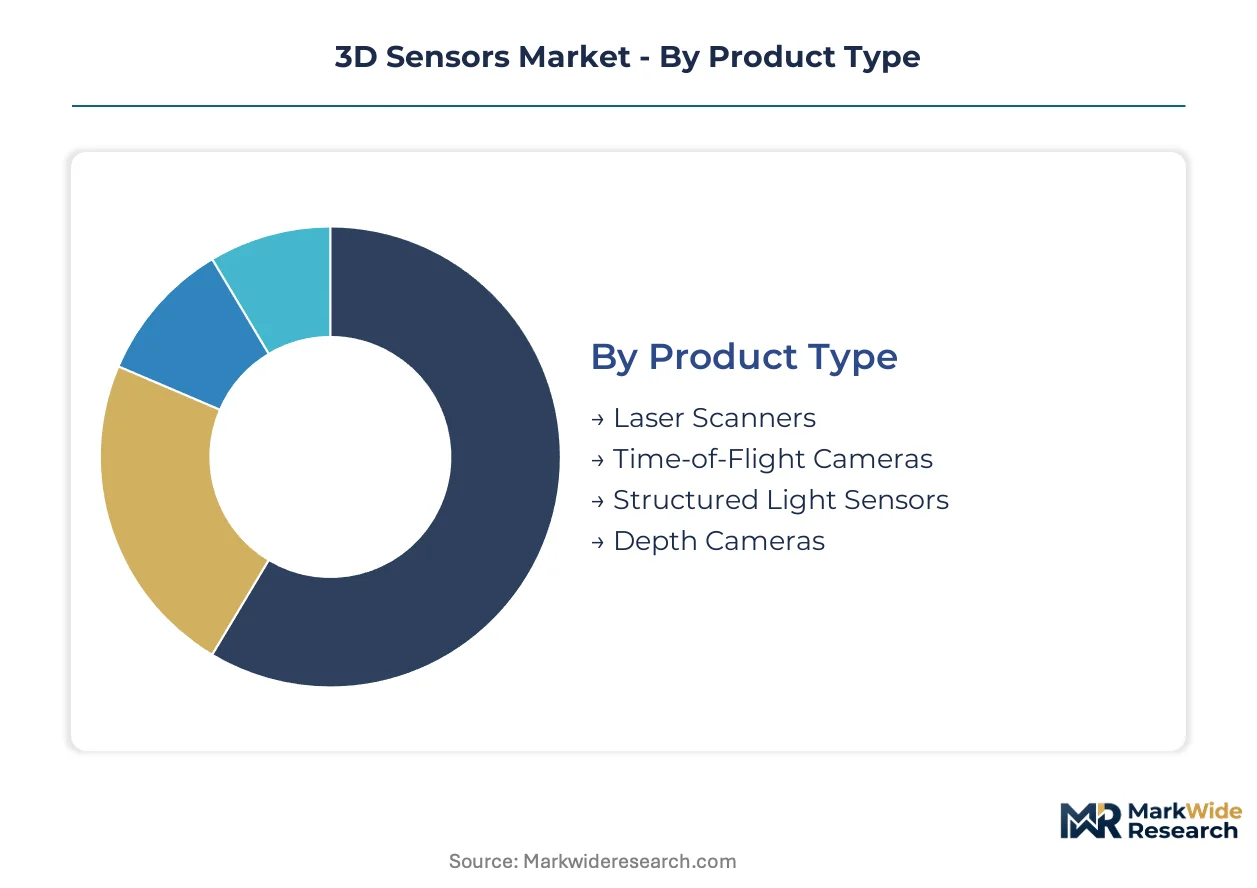
3D sensor procurement decisions hinge on certification pathways that vary dramatically across product architectures. Manufacturers must map segment-specific validation requirements against application criticality before committing to module designs.
Product Type:
FDA 510(k) clearance governs depth cameras deployed in surgical navigation, while automotive LiDAR modules face UN ECE type-approval under evolving functional safety frameworks. Time-of-flight cameras in consumer electronics bypass medical-grade validation but must satisfy FCC emission limits for laser products.
- Time-of-Flight Cameras:These sensors measure depth by calculating photon travel time between emitter and receiver, achieving sub-centimeter accuracy at ranges under 10 meters. Demand clusters in Chinese smartphone assembly lines where slim z-height requirements dominate design specifications. Solid-state silicon photonics is compressing module costs by replacing gallium arsenide substrates.
- Structured Light Sensors:Projecting known geometric patterns onto surfaces enables high-fidelity surface reconstruction for facial authentication and industrial metrology. German automotive manufacturers specify these for interior cabin monitoring where eye-tracking precision exceeds radar capabilities. IP67 sealing requirements anchor premium pricing for industrial variants.
- Laser Scanners:Rotating or solid-state beam steering captures millimeter-accurate point clouds for surveying and autonomous vehicle perception. Long-range precision requirements in robotics applications drive specification differentiation.
- Depth Cameras:Integrated RGB-D modules combine color imaging with spatial mapping for augmented reality and human-machine interaction. Consumer electronics volume shipments concentrate in East Asian assembly operations.
Leading the category by volume: Time-of-Flight Cameras. Growing fastest: Structured Light Sensors.
Technology:
Cost tiers separate premium photonic integration from commodity ultrasonic alternatives, with LiDAR transceivers commanding 10-20x unit economics of depth-sensing arrays in white goods.
- LiDAR:Pulsed or continuous-wave laser ranging achieves hundred-meter detection with centimetric precision under variable lighting. Automotive tier-1 suppliers in Germany and the United States specify solid-state MEMS scanning for next-generation advanced driver-assistance systems. Silicon photonics foundry partnerships are collapsing multi-chip module supply chains into monolithic outputs.
- Stereo Vision:Dual-camera parallax calculation requires no active emission, enabling passive depth perception in battery-constrained applications. Warehouse automation in the United States deploys these for pallet dimensioning where regulatory laser classification adds compliance burden.
- Ultrasonic:Piezoelectric transducer arrays measure time-of-flight through air or liquid media, limited to short-range proximity detection. Parking assistance systems in mass-market vehicles anchor volume demand.
- Photogrammetry:Multi-view geometric reconstruction from calibrated camera arrays enables cultural heritage digitization and construction progress monitoring. Research institutions and government survey agencies sustain niche procurement.
Highest margin concentration: LiDAR. Steepest expansion trajectory: Stereo Vision.
Application:
Customer maturity varies sharply—automotive buyers demand pre-certified modules with embedded ISO 26262 documentation, while robotics startups accept development kits requiring integration validation.
- Automotive:Autonomous driving and cabin monitoring systems require depth perception validated under UN ECE R157 and impending AI Act conformity assessment. German and United States manufacturers specify automotive-grade LiDAR with -40°C to 85°C operating ranges.
- Industrial Automation:Sub-millimeter accuracy requirements for quality inspection and robotic guidance anchor premium pricing. Smart manufacturing investments in Germany concentrate demand for IP67-sealed sensor modules with EtherCAT protocol compatibility.
- Robotics:Mobile platforms integrate depth sensing for simultaneous localization and mapping in unstructured environments. Edge AI convergence enables real-time point cloud analysis without cloud dependency.
- Healthcare:FDA device classification rules for AI-enabled medical devices create validated channels for surgical navigation and diagnostic imaging. Orthopedic and neurosurgical guidance platforms require clinical validation of spatial accuracy.
Deepest certification requirements: Automotive. Fastest qualification cycles: Healthcare.
End User:
Procurement scale separates volume manufacturers from project-based research acquisitions, with government tenders specifying domestic content thresholds that reshape supplier eligibility.
- Manufacturers:Tier-1 automotive suppliers and industrial equipment OEMs consolidate vendor relationships around pre-certified sensor platforms. Multi-year supply agreements with foundry partners secure wafer-scale photonic integration capacity.
- Retailers:Inventory management and customer analytics applications deploy depth sensing for automated dimensioning and footfall tracking. Multi-path interference in reflective warehouse environments constrains time-of-flight deployment.
- Researchers:Academic and corporate R&D laboratories procure development kits for algorithm validation and prototype integration. Funding agency requirements increasingly mandate open-source software compatibility.
- Governments:Defense, surveying, and infrastructure inspection applications specify ruggedized modules with export-controlled performance thresholds. India's PLI scheme for electronics manufacturing attracts module assembly operations outside East Asian concentration.
Dominant procurement volume: Manufacturers. Fastest budget growth: Governments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in manufacturing corridors where automotive and industrial automation investments intersect with tightening regulatory frameworks for autonomous systems and AI-enabled devices.
China
Smartphone assembly lines in Shenzhen and Dongguan drive volume procurement of time-of-flight cameras with aggressive z-height specifications. NMPA and MIIT coordinate device classification rules for medical and automotive depth sensors under evolving GB standards. The Yangtze River Delta hosts module testing operations serving domestic EV manufacturers integrating solid-state LiDAR.
Germany
Automotive tier-1 suppliers in Stuttgart and Munich specify automotive-grade LiDAR modules with embedded ISO 26262 documentation for advanced driver-assistance systems. The EU AI Act imposes conformity assessment obligations on autonomous perception systems, extending qualification timelines. Industrial automation clusters in Bavaria anchor premium pricing for IP67-sealed sensors with EtherCAT protocol compatibility.
United States
Warehouse automation deployments in California and Texas deploy stereo vision systems for pallet dimensioning where laser classification adds compliance burden. FDA device classification rules create validated channels for surgical navigation systems requiring clinical validation of spatial accuracy. The Pacific Northwest hosts development operations for edge AI convergence with depth sensing in mobile robotics.
Japan
MEMS-based scanning LiDAR for compact robotics platforms concentrates manufacturing in Nagoya and Osaka industrial corridors. METI coordinates national standards alignment with ISO functional safety frameworks for automotive perception systems. Kanto region precision equipment vendors supply optomechanical alignment systems for photodetector array assembly.
India
PLI scheme incentives attract module assembly and testing operations to Tamil Nadu and Karnataka, creating secondary supply capacity outside East Asian concentration. CDSCO medical device regulations create pathways for surgical navigation sensor validation. Telangana's electronics manufacturing clusters host calibration operations for time-of-flight receivers.
3D Sensors Market Vendor Landscape
Wafer-scale photonic integration dominates the current landscape as foundry partnerships displace traditional multi-chip module supply chains. The vendor base stratifies across three tiers: integrated device manufacturers with captive foundry access, fabless specialists licensing silicon photonics IP, and module assemblers dependent on external component sourcing. Competitive moves concentrate on securing foundry capacity commitments and pre-certifying module platforms under automotive functional safety frameworks.
Among European integrated device manufacturers, Infineon Technologies AG and STMicroelectronics exemplify the foundry-anchored archetype with wafer-scale integration capabilities. Sony Corporation occupies a position representing the image sensor supply concentration for consumer and automotive depth cameras. These three entities anchor the premium tier where regulatory pre-certification and photonic integration capabilities determine procurement eligibility.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Microchip Technology Inc. |
| Sony Corporation |
| STMicroelectronics |
| Cognex Corporation |
| OmniVision Technologies Inc. |
| Keyence Corporation |
| Qualcomm Technologies Inc. |
| ifm electronic GmbH |
| Others |
Supply Flow & Price Mechanics
Precision optomechanical alignment specialists in Japan's Kanto region command wage premiums that propagate through sensor module assembly costs, widening spreads between IP67-sealed industrial tiers and consumer-grade alternatives. Labor-cost differentials between German automotive-tier calibration technicians and Tamil Nadu assembly operators create pricing-tier spreads that favor foundry-integrated incumbents over module assemblers.
Pricing Analysis
Volume shipments concentrate in time-of-flight cameras for Chinese smartphone assembly, while automotive LiDAR modules capture margin premiums. Three-tier pricing structure across premium, standard, and economy levels separates IP67-sealed industrial sensors with EtherCAT compatibility from development kits lacking certification documentation. Pricing pressure stems from silicon photonics cost compression as gallium arsenide substrates face displacement. Robotics startups exhibit highest price sensitivity, while German automotive tier-1 suppliers prioritize pre-certified platforms over unit economics.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and Japan coordinate photonic component flows to module assembly hubs. Wafer-scale integration draws from indium phosphide laser foundries, silicon nitride waveguide fabricators, and through-silicon via packaging operations concentrated among limited OSAT providers. Single-source vulnerability in europium and terbium phosphor supply constrains emitter material choices under REACH restrictions. Distribution runs through automotive tier-1 supplier consolidation channels and direct industrial equipment OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act imposes conformity assessment obligations that extend qualification timelines, erecting compliance-cost barriers that favor incumbents with embedded regulatory affairs capabilities over capital-constrained entrants.
For Market Incumbents: Hedge against silicon photonics disruption by securing captive foundry capacity commitments in Taiwan and Japan before multi-chip module supply chains collapse. Accelerate ISO 26262 pre-certification investments to capture automotive tier-1 procurement consolidation around documented safety platforms. Defensive positioning requires backward integration into wafer-scale photodetector array production. For New Entrants and Emerging Players: System integrators in India's PLI scheme electronics manufacturing clusters represent the most penetrable channel partner type for module assembly and testing operations. Target surgical navigation platforms requiring FDA 510(k) clearance where validation timelines deter commodity competitors. White-space capture demands edge AI convergence partnerships with mobile robotics developers seeking battery-powered depth perception. For Investors and Strategic Acquirers: Re-rating potential sits with fabless silicon photonics IP licensors given automotive LiDAR foundry partnership announcements as catalyst. Long-term viability over the next decade hinges on regulatory pre-certification asset accumulation rather than discrete component expertise. Monitor UN ECE R157 type-approval acceleration as inflection signal for automotive perception system procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Securement | Wafer-scale photonic integration collapses multi-chip module supply chains into monolithic outputs at TSMC and GlobalFoundries. |
| Functional Safety Pre-Certification | Embedded ISO 26262 documentation accelerates automotive tier-1 procurement cycles under EU AI Act conformity requirements. |
| Silicon Photonics IP Licensing | Indium phosphide laser integration with silicon nitride waveguides displaces gallium arsenide substrates in time-of-flight receivers. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Karnataka module assembly operations diversify supply concentration outside East Asian hubs. |
| Surgical Navigation Platform Validation | FDA 510(k) clearance creates protected channels for orthopedic and neurosurgical guidance system depth sensors. |
Methodological Framework
Document review covered SEC 10-K filings, EU regulatory impact assessments, and photonics industry trade publications, complemented by interviews with automotive tier-1 supplier procurement directors, industrial automation OEM platform engineers, MEMS foundry operations managers, and FDA regulatory affairs specialists. Secondary validation drew from NMPA device classification databases, UN ECE working party submissions, and REACH substance restriction updates. Bottom-up sensor shipment estimates triangulated against top-down automotive LiDAR content-per-vehicle projections.
Cross-reference between historical silicon photonics adoption curves and expert panel input on solid-state LiDAR beam steering maturity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, certification pathway, end-use criticality, and regional regulatory cluster. CAGRs derived from wafer-scale integration cost compression trajectories and automotive functional safety certification velocity assumptions.
Caveats apply where UN ECE R157 amendment timelines or ECHA substance of very high concern listing expansions could materially shift the outlook for emitter material availability and automotive type-approval pathways. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Active Sensor Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Infrared Gas Sensor Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Refrigeration Gauge Market