
 Robotic Sensors Market | 2026-2036
Robotic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Sensors Market Intelligence
Aftermarket sensor calibration and predictive maintenance revenue is fragmenting across regional service networks. Infineon Technologies AG leverages its MEMS fabrication depth to dominate automotive-grade inertial sensing modules. FANUC Corporation anchors its installed base through proprietary force sensor integration on its LR Mate robot series. SICK AG competes in optical safety scanners with channel control through certified system integrator partnerships.
Robotic sensors are electromechanical transducers that convert physical stimuli—displacement, force, electromagnetic radiation, or thermal gradients—into processable electrical signals, typically with response times below one millisecond and resolution thresholds measured in micrometers or millinewtons. Their primary industrial purpose is closed-loop feedback control, enabling autonomous robots to adapt trajectories and grip forces in real time without human intervention. Vision sensors now lead capital deployment in electronics manufacturing, while force-torque sensing exhibits the fastest structural expansion as collaborative robots proliferate in pharmaceutical packaging lines. Temperature and ultrasonic modalities remain mature segments with margin pools concentrated in hazardous environment certifications for chemical processing applications.
The EU Machinery Directive and ISO 10218 standards mandate redundant force-limiting architectures on collaborative robots, directly shaping product design requirements for European deployments. In the United States, OSHA technical guidance on robot system safety influences liability frameworks and insurance premiums for sensor-equipped installations. China's GB standards for industrial robot safety, administered by SAMR, create market access conditions distinct from Western certification paths. Stakeholders must monitor divergence between regional safety certification regimes when configuring sensor portfolios for multinational robot OEM supply contracts.
Market Dynamics
Collaborative robot safety mandates across major manufacturing jurisdictions are compressing sensor deployment timelines and forcing redundant force-torque architectures into standard product configurations. This regulatory pull is restructuring supplier qualification criteria and OEM procurement specifications simultaneously.
Growth Catalysts
- ISO 10218 compliance mandates:European machinery safety standards now require dual-channel force-limiting verification on cobot installations, creating captive demand for certified sensor modules.
- Pharmaceutical packaging automation:Sterile fill-finish lines in Germany and Japan are integrating six-axis force-torque sensors for delicate vial handling without human intervention.
- MEMS fabrication scale:Wafer-level integration of accelerometer and gyroscope functions is collapsing unit costs for automotive-grade inertial sensing.
Market Restraints
- Silicon wafer input volatility:MEMS die production depends on 300mm silicon supply concentrated in Taiwan and South Korea, exposing sensor fabs to geopolitical disruption.
- Functional safety certification bottlenecks:TÜV and UL testing queues for SIL-2/PLe rated force sensors extend lead times by 8-14 months.
- Optical encoder substitution:Magnetic position sensing is displacing optical solutions in dust-heavy automotive welding cells, eroding margin pools for legacy photoelectric suppliers.
Strategic Opportunities
- India's electronics manufacturing corridor:PLI scheme incentives for mobile phone assembly are attracting cobot deployments without entrenched sensor supplier relationships.
- Thermal sensor fusion:Combining infrared arrays with vision systems enables predictive maintenance on injection molding equipment before surface defects appear.
- SAMR GB standard harmonization:China's industrial robot safety certification pathway is diverging from ISO frameworks, creating first-mover advantage for domestic-qualified component vendors.
Industry Challenges
- Safety systems integration expertise:End users lack in-house capability to validate force-torque sensor thresholds against ISO/TS 15066 collision parameters, creating dependency on scarce certified integrators.
- Legacy PLC architecture incompatibility:EtherCAT and PROFINET real-time protocols require gateway hardware that adds latency to sub-millisecond sensor feedback loops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Sensors Market |
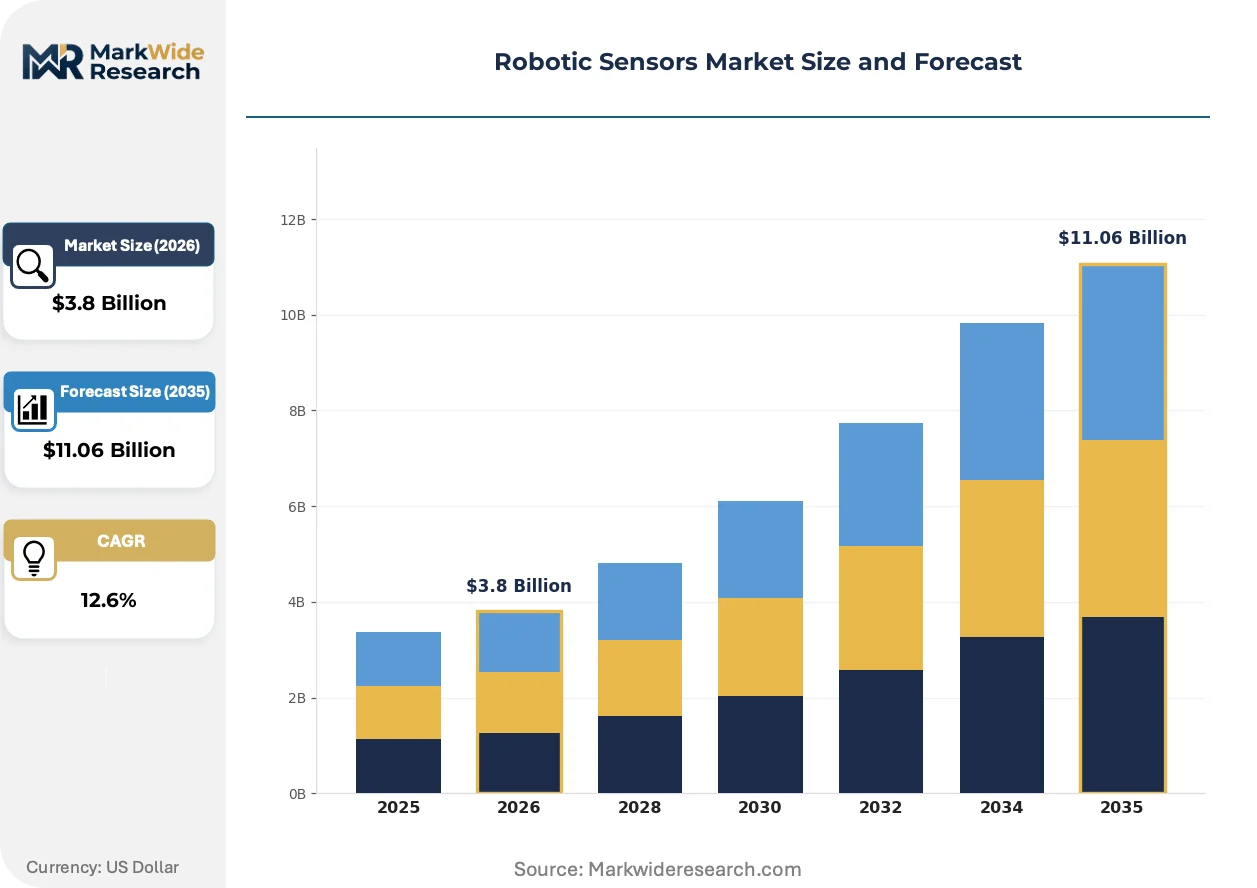
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Proximity Sensors, Vision Sensors, Force Sensors, Temperature Sensors, Ultrasonic Sensors, Gyroscopic Sensors Technology: Infrared, Capacitive, Inductive, Lidar, Piezoelectric, Optical Application: Material Handling, Quality Control, Assembly Automation, Packaging, Hazardous Environment Monitoring, Precision Machining End User: Electronics Manufacturers, Aerospace OEMs, Food Processing, Consumer Appliances, Pharmaceutical Producers, Semiconductor Fabricators |
| Companies Covered | Infineon Technologies AG, FANUC Corporation, Honeywell International Inc., SICK AG, OMRON Corporation, TE Connectivity Ltd., Keyence Corporation, ATI Industrial Automation, Cognex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Sensors Market Strategic Shifts & Innovations
Sensor modality convergence is collapsing the traditional separation between tactile, visual, and thermal feedback channels. This integration is enabling context-aware robot behavior without centralized processing bottlenecks.
Multi-spectral imaging is hybridizing visible-light and short-wave infrared detection into single-package vision modules. Electronics manufacturers in China's Yangtze River Delta are adopting these fused sensors for solder joint inspection at line speeds exceeding 500 parts per minute. The technology is hybridizing quality control workflows that previously required sequential station handoffs.
REACH restrictions on perfluorinated compounds are forcing sensor manufacturers to reformulate potting compounds and conformal coatings used in washdown-rated encoders. Industrial washing equipment OEMs in Germany face compliance deadlines that compress reformulation validation cycles. Food-grade force-torque sensors with revised chemistries are entering qualification at Swiss packaging machinery builders ahead of enforcement dates.
Buying organizations are consolidating sensor procurement under centralized technical specifications rather than plant-level discretion. Automotive Tier-1 suppliers in Japan are mandating common force-torque interfaces across their robot supplier base to reduce spare inventory. This specification tightening is squeezing regional distributors who previously captured margin through application engineering services.
Robotic Sensors Market Segmentation
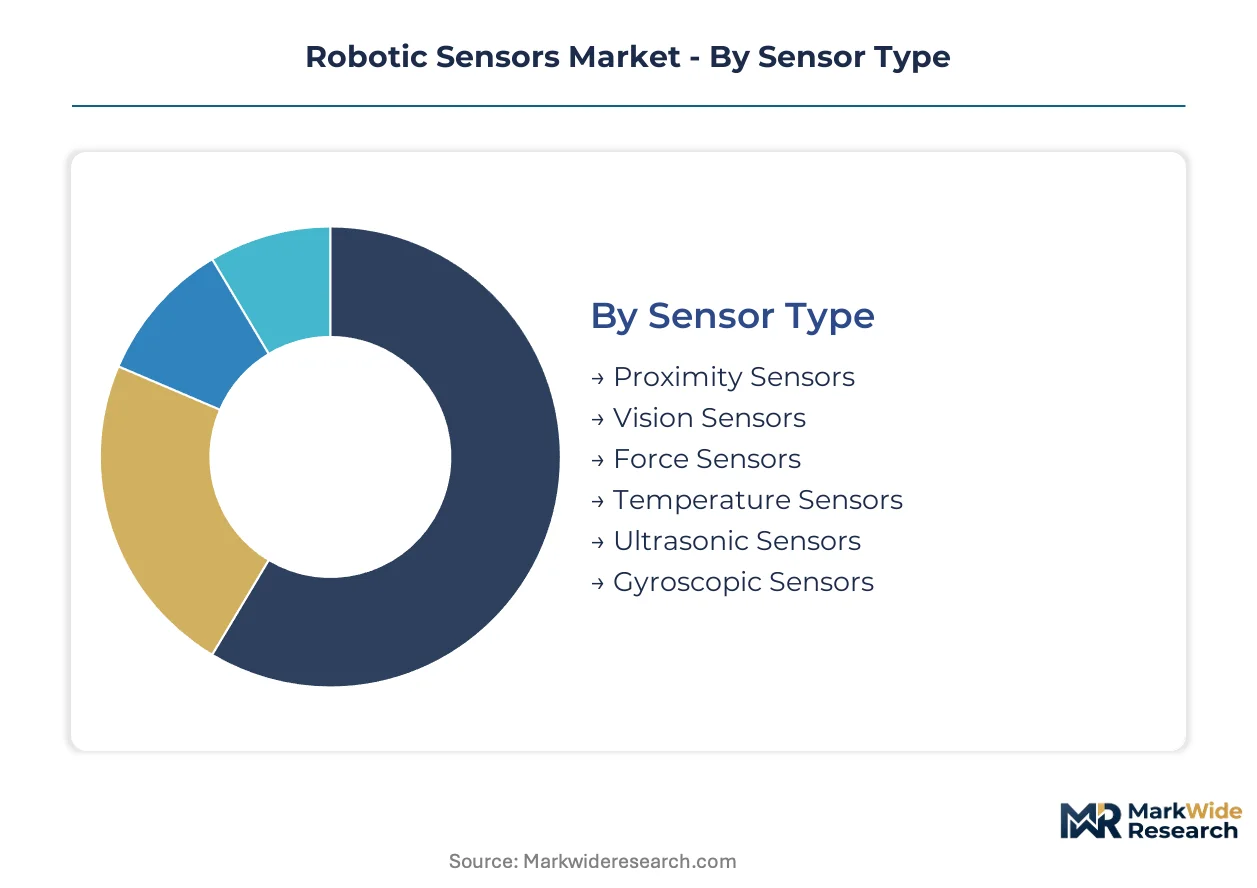
Sensor modality selection in robotics hinges on response time thresholds, environmental resilience, and integration complexity with existing control architectures. Procurement decisions increasingly favor multi-functional packages that collapse sensing layers into unified feedback loops.
Sensor Type:
Application requirements dictate which physical stimulus—electromagnetic fields, mechanical strain, or thermal gradients—warrants dedicated transduction hardware.
- Vision Sensors:Multi-spectral imaging modules now fuse visible-light and short-wave infrared detection for solder joint inspection at line speeds exceeding 500 parts per minute. Electronics manufacturers in China's Yangtze River Delta corridor are absorbing these fused sensors to collapse sequential quality control station handoffs.
- Force Sensors:Six-axis force-torque transducers enable real-time grip adjustment for delicate vial handling in sterile pharmaceutical packaging lines across Germany and Japan. ISO 10218 compliance mandates for collaborative robot safety are compressing deployment timelines for redundant force-limiting architectures.
- Proximity Sensors:Inductive and capacitive variants provide collision avoidance feedback without physical contact in high-speed material handling cells.
- Temperature Sensors:Thermocouple and RTD-based modules monitor thermal gradients in hazardous chemical processing environments requiring explosion-proof certifications.
- Ultrasonic Sensors:Time-of-flight acoustic ranging supports level detection and obstacle mapping in dust-heavy conditions where optical solutions degrade.
- Gyroscopic Sensors:MEMS-based inertial measurement units supply orientation data for mobile robot navigation and stabilization control.
Vision sensors command the established base in capital deployment. The steepest expansion runs through force sensors as collaborative robot safety mandates proliferate across pharmaceutical and electronics assembly lines.
Technology:
Transduction physics determines resolution limits, environmental immunity, and unit economics at volume scale.
- Optical:Photoelectric encoders and fiber-based systems deliver sub-micrometer position resolution for precision machining applications. Magnetic encoder substitution in automotive welding cells is eroding margin pools for legacy photoelectric suppliers.
- Piezoelectric:Ceramic crystal transducers convert mechanical strain into electrical charge with response times below one millisecond for dynamic force measurement. Wafer-level MEMS integration is collapsing fabrication costs for automotive-grade inertial sensing modules.
- Infrared:Thermal imaging arrays enable predictive maintenance on injection molding equipment before surface defects become visible.
- Capacitive:Electric field disturbance detection supports non-contact proximity sensing in cleanroom semiconductor fabrication environments.
- Inductive:Eddy-current principles provide robust position feedback in metallic debris conditions common to machining operations.
- Lidar:Time-of-flight laser ranging generates three-dimensional point clouds for mobile robot navigation and obstacle mapping.
Optical technologies retain the largest installed footprint. Piezoelectric architectures are climbing the fastest as force-torque sensing requirements intensify across collaborative robot deployments.
Application:
Process stage determines sensor modality mix, with upstream operations favoring environmental monitoring and downstream stages requiring precision manipulation feedback.
- Assembly Automation:Coordinated vision and force feedback enables adaptive part mating without rigid fixture requirements. Automotive assembly lines in Germany and Japan are expanding sensor deployment for collaborative robot safety systems.
- Quality Control:Multi-spectral imaging hybridizes visible and infrared detection for defect identification at production line speeds. China's Yangtze River Delta electronics manufacturing corridor is absorbing these fused sensors for solder joint verification.
- Material Handling:Proximity and vision sensors coordinate pallet detection and grip verification in high-throughput distribution environments.
- Packaging:Force-torque sensing supports delicate product handling in pharmaceutical and food-grade applications requiring contamination prevention.
- Hazardous Environment Monitoring:Temperature and gas sensors with explosion-proof certifications protect personnel in chemical processing operations.
- Precision Machining:Optical encoders and tactile probes maintain dimensional tolerances in subtractive manufacturing processes.
Assembly automation anchors current sensor deployment volume. Quality control applications are expanding most quickly as vision system costs decline and inspection speed requirements intensify.
End User:
Industry-specific regulatory frameworks and contamination control standards shape sensor specification requirements and certification pathways.
- Electronics Manufacturers:Miniaturization trends and high-mix production demand vision systems with sub-millimeter resolution and rapid reconfiguration capability. The Yangtze River Delta corridor concentrates demand for multi-spectral inspection modules.
- Pharmaceutical Producers:Sterile fill-finish operations require force-torque sensors with food-grade chemistries and washdown-rated enclosures. Swiss packaging machinery builders are qualifying revised sensor formulations ahead of REACH enforcement deadlines.
- Semiconductor Fabricators:Cleanroom-compatible sensors with minimal particulate generation support wafer handling and lithography positioning.
- Aerospace OEMs:High-reliability inertial sensing and precision measurement systems support composite manufacturing and assembly verification.
- Food Processing:Hygienic design standards mandate stainless steel enclosures and crevice-free surfaces for sensors in washdown environments.
- Consumer Appliances:Cost-optimized proximity and touch sensors enable automation in high-volume white goods assembly.
Electronics manufacturers represent the dominant demand concentration. Pharmaceutical producers are gaining share fastest as sterile automation requirements intensify across European and Japanese packaging lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate low price elasticity for force-torque sensors with SIL-2/PLe certification, while procurement teams in India's emerging electronics corridor negotiate aggressively on unit costs for vision modules.
United States
Automotive Tier-1 suppliers in Detroit mandate common force-torque interfaces across robot supplier bases to consolidate spare inventory. OSHA technical guidance on robot system safety shapes liability frameworks and insurance premiums for sensor-equipped installations. The Southeast manufacturing belt is absorbing collaborative robot deployments for electric vehicle battery assembly.
Germany
Automotive assembly lines in Bavaria and Baden-Württemberg are expanding sensor deployment for collaborative robot safety systems. The EU Machinery Directive and ISO 10218 standards mandate redundant force-limiting architectures, directly shaping product design requirements. Stuttgart's industrial automation cluster concentrates demand for certified force-torque modules in precision manufacturing cells.
China
The Yangtze River Delta electronics manufacturing corridor concentrates demand for multi-spectral vision sensors performing solder joint inspection. SAMR administers GB standards for industrial robot safety, creating certification pathways distinct from Western frameworks. Shenzhen and Suzhou are absorbing fused vision-infrared modules at line speeds exceeding 500 parts per minute.
Japan
Sterile fill-finish lines in the Kansai and Kanto regions integrate six-axis force-torque sensors for delicate pharmaceutical vial handling. METI industrial policy supports domestic sensor fabrication for strategic autonomy in robotics supply chains. Nagoya's automotive manufacturing hub anchors demand for MEMS-based inertial sensing in precision assembly applications.
India
PLI scheme incentives for mobile phone assembly in Karnataka and Tamil Nadu are attracting cobot deployments without entrenched sensor supplier relationships. The country's national electronics regulator is harmonizing safety certification timelines with production subsidy disbursement schedules. The Delhi-Mumbai Industrial Corridor is emerging as a testing ground for cost-optimized proximity sensing in high-volume material handling.
Robotic Sensors Market Key Industry Players
Capability concentration sits with specialized force-torque fabricators holding TÜV and UL certifications; scale advantage sits with semiconductor houses leveraging MEMS wafer-level integration. The market structure divides between premium-tier safety-certified specialists and volume-driven component suppliers serving cost-sensitive automation projects. Three archetypes dominate: MEMS-integrated semiconductor manufacturers, safety-certified force-torque specialists, and vision system integrators with channel control through certified partnerships. Competitive moves center on backward integration into MEMS fabrication and geographic expansion into India's PLI-subsidized manufacturing corridors.
Within the MEMS-integrated tier, Infineon Technologies AG exemplifies capability depth in automotive-grade inertial sensing, while FANUC Corporation anchors proprietary force sensor integration through its installed robot base. SICK AG occupies a position in optical safety scanning with distribution control through certified system integrator networks. These three represent the dominant competitive archetypes: semiconductor-scale MEMS integration, captive sensor-robot bundling, and channel-controlled optical safety systems.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| FANUC Corporation |
| Honeywell International Inc. |
| SICK AG |
| OMRON Corporation |
| TE Connectivity Ltd. |
| Keyence Corporation |
| ATI Industrial Automation |
| Cognex Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Taiwan's 300mm MEMS foundries is compressing wafer pricing and forcing sensor fabricators toward long-term offtake contracts that lock in volume commitments from automotive OEMs. This utilization dynamic simultaneously erodes spot-market leverage for tier-two suppliers and rewards tier-one vendors with backward integration into captive wafer supply.
Pricing Analysis
Aftermarket calibration service contracts now drive lifetime value capture, with sensor OEMs bundling predictive maintenance subscriptions at three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on SIL-2/PLe certification tier and geographic proximity to certified integrator networks. Cost compression in vision modules is intensifying because magnetic encoder substitution in automotive welding cells erodes legacy photoelectric margins. Electronics manufacturers in India's PLI corridor demonstrate highest price sensitivity, while German pharmaceutical packers accept premium force-torque pricing for TÜV-validated safety architectures.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for sensor distributors serving multinational robot OEMs. Wafer fabrication concentrates in Taiwan and South Korea, with final assembly anchored in China and Germany. MEMS die production draws from 300mm silicon supply, ceramic crystal substrates, and rare-earth magnetic materials. Single-source vulnerability in EUV lithography equipment for advanced node MEMS creates chokepoint risk. Distribution runs through certified system integrator partnerships rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where EtherCAT/PROFINET interoperability standards are collapsing proprietary sensor interface moats and enabling modular substitution across robot OEM installed bases.
For Market Incumbents: Build certification moats by accelerating TÜV and UL queue placement for SIL-2/PLe force-torque modules before ISO 10218 compliance deadlines tighten. Magnetic encoder substitution in automotive welding cells threatens legacy photoelectric revenue streams; backward integration into MEMS wafer supply secures cost position against Taiwanese foundry volatility. Channel control through certified integrator partnerships defends against price-transparent direct procurement platforms. For New Entrants and Emerging Players: Build out white-space positions in India's PLI-subsidized electronics corridor where entrenched sensor supplier relationships remain unformed. Karnataka and Tamil Nadu mobile phone assembly lines offer penetrable entry points for cost-optimized proximity sensing modules. SAMR GB standard harmonization creates regulatory arbitrage opportunity for domestic-qualified vendors ahead of Western certification divergence. Target system integrator bypass models that compress deployment timelines for mid-market automation projects. For Investors and Strategic Acquirers: Long-term, this sits as a safety-certification scarcity play because force-torque specialists with TÜV/UL validated architectures command irreplaceable positions in European pharmaceutical and automotive cobot deployments. Acquisition target archetype: mid-cap fabricators holding dual-channel force-limiting IP with unexploited geographic expansion capability. The signal to watch is SAMR's GB standard divergence timeline, which will bifurcate certification pathways and strand non-compliant Western vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Fabrication | Infineon's wafer-level integration anchors automotive-grade inertial sensing cost leadership against foundry volatility. |
| Certified System Integrator Channel Control | SICK's optical safety scanner distribution through TÜV-certified partners blocks price-transparent direct procurement. |
| SAMR GB Standard Pre-Qualification | First-mover domestic certification in Shenzhen and Suzhou captures divergent China safety pathway before Western vendors adapt. |
| Force-Torque Sensor-Robot Bundling | FANUC's proprietary LR Mate integration locks pharmaceutical packers into captive spare and calibration revenue streams. |
| Multi-Spectral Vision Module Launch | Fused visible-infrared sensors at 500+ parts per minute collapse sequential inspection stations in Yangtze River Delta electronics corridors. |
Research Approach
Cross-validation between regulatory filing analysis and supply chain participant interviews anchors the qualitative findings in this study. Primary fieldwork engaged robot OEM procurement directors, certified system integrator technical leads, MEMS foundry operations managers, and pharmaceutical packaging automation engineers across Germany, Japan, China, and India. Secondary validation drew from SAMR GB standard publications, TÜV certification databases, SEC 10-K sensor segment disclosures, and Taiwan semiconductor trade association capacity reports. Bottom-up demand modeling from end-user installation data and top-down supply-side capacity analysis were reconciled through iterative triangulation.
Calibration against historical MEMS pricing cycles and force-torque certification queue lengths refined the analytical framework across the projection horizon. Segmentation dimensions modeled include sensor modality, transduction physics, application process stage, and end-user regulatory framework cluster. CAGRs were derived from installed base expansion rates and replacement cycle compression in collaborative robot deployments. Industry-specific forecast inputs incorporated ISO 10218 compliance deadline phasing and PLI scheme subsidy disbursement schedules in India's electronics manufacturing corridor.
Stress conditions across silicon wafer supply disruption, TÜV/UL certification queue extension, and EtherCAT/PROFINET protocol adoption timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization trajectories and MEMS fabrication scale economics. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Latin America Lidar Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
Laser Scanner Market