
 Asia Pacific Industrial Computed Tomography Market | 2026-2036
Asia Pacific Industrial Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Industrial Computed Tomography Market Outlook
Equipment leasing and managed-service contracts is reconfiguring competitive access across the Asia Pacific industrial CT landscape. Nikon Corporation leverages its precision optics heritage to dominate high-resolution metrology systems for Japanese automotive suppliers. Waygate Technologies sustains broad regional coverage through calibrated service networks and localized maintenance contracts. Zeiss International anchors premium positioning with multi-sensor integration platforms that command technical specification adherence from semiconductor fabs in South Korea and Taiwan.
Industrial computed tomography deploys X-ray or neutron radiography to generate three-dimensional volumetric reconstructions of internal component structures, typically achieving spatial resolution below one micrometer for materials characterization and defect detection. Cone beam systems and flat panel detector architectures now lead technology adoption due to faster scan cycles and reduced footprint requirements for in-line quality control. Non-destructive testing and failure analysis applications capture expanding share as aerospace and electronics end users mandate 100% inspection protocols for safety-critical and miniaturized assemblies. Custom solutions and calibration services within the service type dimension concentrate margin pools where vendor technical credibility determines contract renewal rates.
Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS standards that mandate traceable dimensional verification for exported precision components, directly shaping CT equipment procurement specifications. China's State Administration for Market Regulation (SAMR) administers GB standards for industrial radiography safety and measurement uncertainty, while South Korea's MFDS aligns medical-adjacent manufacturing quality rules with international IEC frameworks. Stakeholders must monitor divergence between national certification requirements and emerging cross-border mutual recognition agreements that could alter equipment qualification costs and service localization strategies.
Market Dynamics
Equipment leasing models and managed-service contracts are compressing capital barriers for precision manufacturers across the Asia Pacific, while METI's tightening JIS traceability mandates force CT system upgrades at Japanese automotive and aerospace suppliers.
Growth Catalysts
- GB Standard Tightening:China's SAMR enforcement of industrial radiography safety protocols mandates CT-based inspection for high-value exports from the Yangtze River Delta cluster.
- Miniaturization Demands:South Korean semiconductor fabs require sub-micron resolution CT for 3D packaging validation of advanced memory modules.
- Aerospace NDT Expansion:Japanese and South Korean airframe manufacturers deploy cone-beam CT for 100% inspection of turbine blade castings under airworthiness directives.
Market Restraints
- X-Ray Source Concentration:Vacuum tube and microfocus source supply concentrates among German and Japanese specialty component houses, creating procurement bottlenecks.
- Calibration Infrastructure Gaps:Traceable artifact standards for dimensional CT remain limited outside Japan's NMIJ metrology network, raising measurement uncertainty disputes.
- Neutron CT Substitution:Synchrotron and neutron radiography facilities in Australia and Japan capture high-value failure analysis contracts from conventional CT vendors.
Strategic Opportunities
- Southeast Asia Penetration:Vietnam and Thailand's electronics contract manufacturing expansion lacks indigenous high-resolution CT capacity, creating service outsourcing demand.
- Multi-Sensor Convergence:Integration of optical, tactile, and CT measurement modalities on unified platforms addresses semiconductor metrology complexity.
- MFDS Alignment:South Korea's medical device manufacturing quality rules extend CT inspection mandates to adjacent precision component suppliers.
Industry Challenges
- Reconstruction Algorithm Expertise:Sparse availability of computed tomography physicists capable of optimizing artifact correction for composite materials limits deployment velocity.
- Legacy CMM Integration:Shop-floor CT systems require middleware development to feed dimensional data into existing quality management software at automotive tier-one suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Industrial Computed Tomography Market |
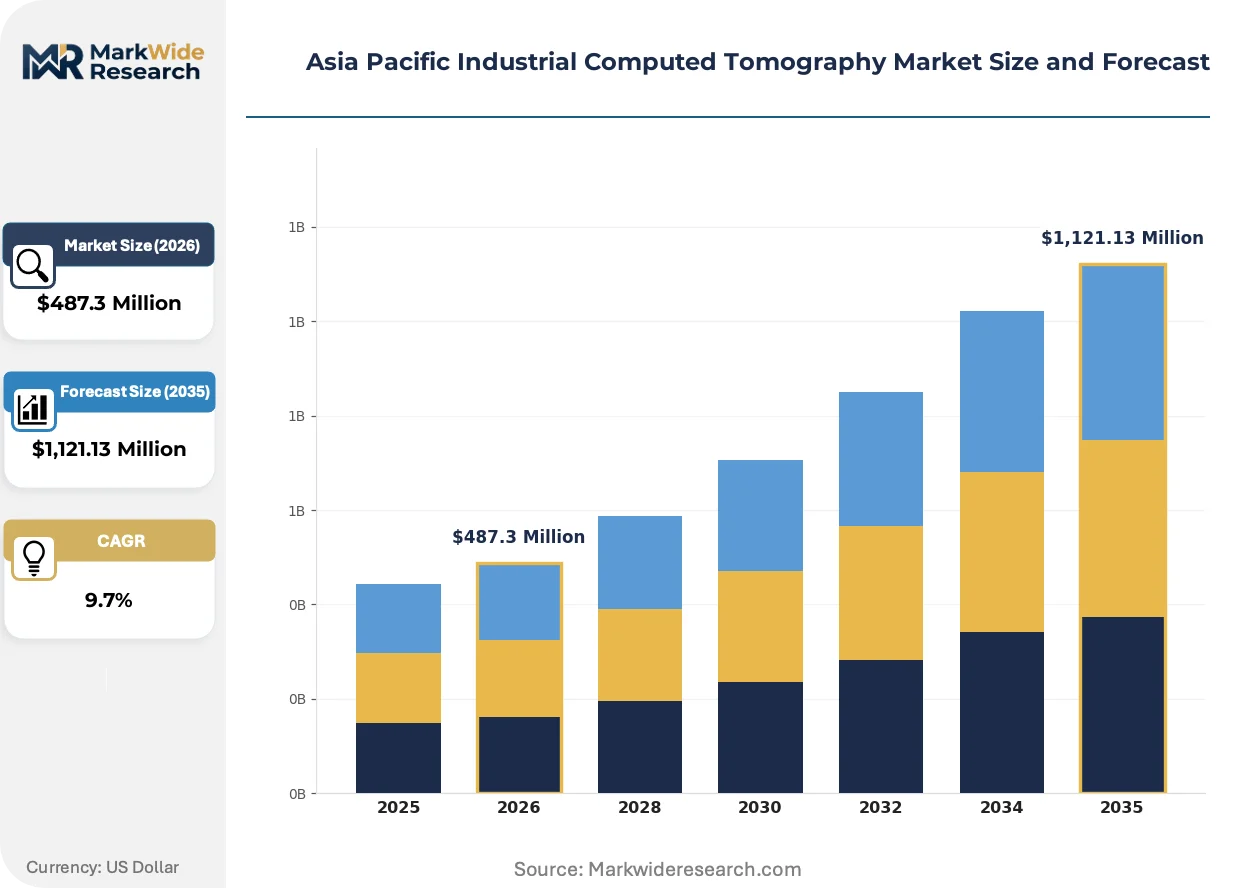
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: X-ray, Neutron Radiography, Cone Beam, Flat Panel Detector Application: Quality Control, Research & Development, Non-Destructive Testing, Failure Analysis End User: Aerospace, Automotive, Electronics, Manufacturing Service Type: Custom Solutions, Calibration Services, Equipment Rental, Maintenance |
| Companies Covered | Shimadzu Corporation, Omron Corporation, Nikon Corporation, Bruker Corporation, Waygate Technologies, Zeiss International, Comet Group Limited, Thermo Fisher Scientific Inc, Hitachi Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Industrial Computed Tomography Market Strategic Shifts
Scanner architectures and service delivery models are undergoing parallel transformation as flat-panel detector costs decline and regulatory traceability requirements harden across precision manufacturing verticals.
Flat-panel detector technology is migrating from offline laboratory configurations toward in-line production environments. Japanese automotive suppliers now embed cone-beam CT stations directly adjacent to machining centers for real-time first-article inspection. This proximity deployment compresses feedback loops from hours to minutes, eliminating batch quarantine inventory.
METI's 2023 revision to JIS B 7440 dimensional measurement standards mandates documented uncertainty budgets for CT-based coordinate measurements. Japanese precision component exporters must now maintain calibrated reference artifacts traceable to NMIJ national standards. Aerospace and medical device subcontractors face the steepest compliance costs, driving consolidation toward vendors with embedded metrology service capabilities.
Buying patterns among electronics manufacturers now favor performance-based service agreements over equipment ownership. South Korean and Taiwanese semiconductor fabs contract for guaranteed throughput and uptime rather than capitalizing scanner assets. This preference shift concentrates margin pools with vendors capable of remote diagnostics and predictive maintenance across distributed manufacturing footprints.
Asia Pacific Industrial Computed Tomography Market Segmentation
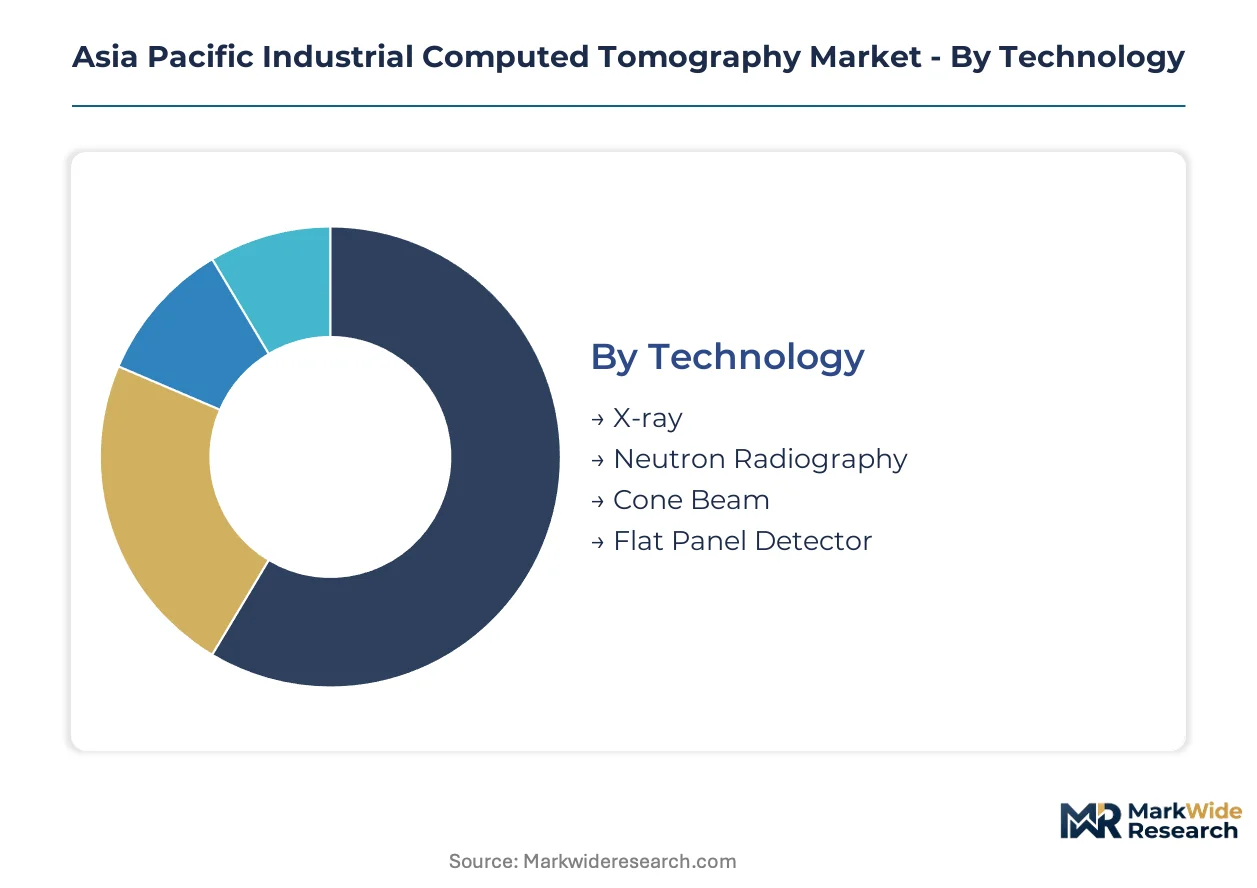
Industrial CT procurement patterns diverge sharply across technology architectures and service delivery models. Segment boundaries matter because equipment refresh cycles, margin structures, and regulatory compliance burdens vary by category in ways that reshape vendor positioning across the Asia Pacific precision manufacturing corridor.
Technology:
Cycle times for detector and source technologies range from eighteen-month refresh rates for commodity flat panels to seven-year stability for specialized neutron radiography installations.
- X-ray:Penetrating radiation systems deploy microfocus and nanofocus tubes for metallic component inspection. Japanese automotive suppliers in Nagoya's precision engineering corridor specify these for turbine blade porosity detection under METI-mandated JIS traceability protocols.
- Cone Beam:Circular trajectory scanning with area detectors enables rapid volumetric reconstruction. South Korean semiconductor fabs in Gyeonggi Province deploy cone-beam architectures for 3D packaging validation where throughput requirements exceed linear array capabilities.
- Flat Panel Detector:Amorphous silicon and CMOS sensor arrays dominate new installations. China's Yangtze River Delta electronics contract manufacturers favor these for footprint-constrained shop-floor deployment.
- Neutron Radiography:Thermal and cold neutron beams penetrate high-density materials opaque to X-ray. Australian and Japanese synchrotron facilities capture failure analysis contracts for aerospace composite delamination studies.
Cone Beam anchors the volume base while Flat Panel Detector gains share at the steepest rate.
Application:
Margin concentration follows inspection criticality, with aerospace airworthiness mandates commanding premium pricing against production-line quality gates.
- Non-Destructive Testing:Volumetric inspection without component destruction serves safety-critical applications. Japanese and South Korean airframe manufacturers deploy CT-based NDT for 100% turbine blade inspection under civil aviation authority directives.
- Quality Control:In-process dimensional verification replaces destructive sampling. Chinese automotive tier-one suppliers embed CT stations adjacent to machining centers for real-time first-article inspection.
- Failure Analysis:Root-cause investigation of component fractures and delaminations. Electronics manufacturers in Taiwan's Hsinchu Science Park contract third-party labs for advanced packaging defect characterization.
- Research & Development:Materials characterization and process development support. Japanese university-industry partnerships leverage CT for additive manufacturing parameter optimization.
Quality Control generates the highest equipment shipment volumes whereas Non-Destructive Testing commands the steepest service contract premiums.
End User:
Customer concentration patterns reflect regional manufacturing specialization, with electronics demand clustering in South Korea and Taiwan against aerospace procurement centered on Japan.
- Electronics:Semiconductor packaging, printed circuit board, and consumer device manufacturers require sub-micron resolution. South Korean memory fabs and Taiwanese foundries drive specification tightening for 3D integration validation.
- Aerospace:Airframe, engine, and landing gear producers mandate traceable inspection records. Japanese and South Korean manufacturers face airworthiness directive compliance for turbine casting porosity limits.
- Automotive:Powertrain, chassis, and electric vehicle battery suppliers deploy CT for lightweighting validation. China's new energy vehicle producers in the Yangtze River Delta specify CT for battery cell weld inspection.
- Manufacturing:General industrial and precision component producers across diverse sectors. Thailand and Vietnam's expanding electronics contract manufacturing bases lack indigenous high-resolution capacity.
Electronics anchors installed base value while Aerospace expands most quickly on regulatory mandate intensity.
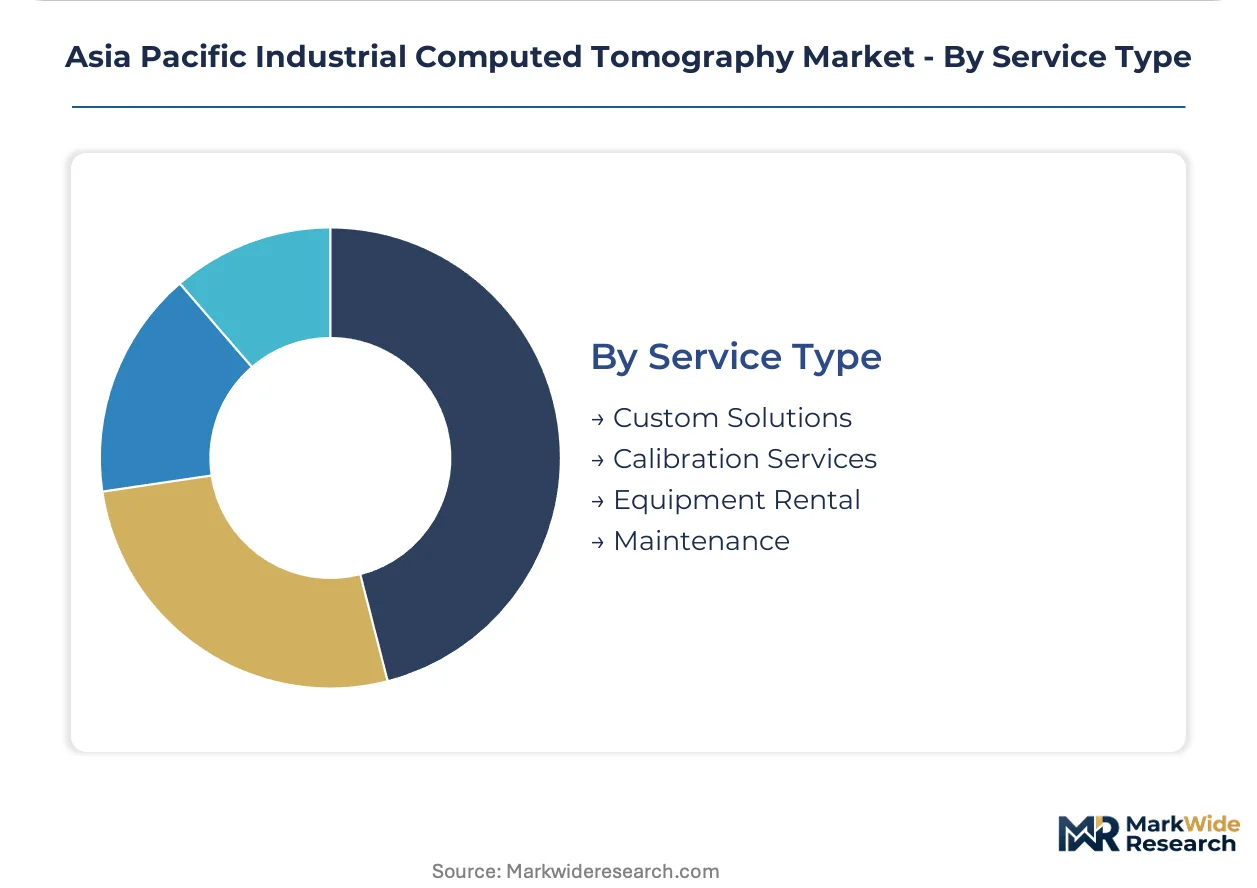
Service Type:
Revenue stability varies by contract structure, with performance-based agreements reducing customer capital commitment while concentrating vendor risk.
- Equipment Rental:Operating lease structures preserve customer liquidity. Southeast Asian electronics contract manufacturers in Vietnam and Thailand favor rental for capacity flexibility amid demand volatility.
- Calibration Services:Traceable artifact verification and measurement uncertainty documentation. Japanese precision exporters require NMIJ-traceable calibration under revised JIS B 7440 mandates.
- Custom Solutions:Application-specific scanner configurations and software integration. South Korean semiconductor fabs commission multi-sensor platforms combining CT with optical and tactile modalities.
- Maintenance:Preventive service contracts and remote diagnostics capability. Taiwanese electronics manufacturers prioritize uptime guarantees over ownership for distributed fabrication footprints.
Calibration Services anchors recurring revenue stability while Equipment Rental climbs the fastest on capital barrier reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-administered quality mandates across the Asia Pacific are accelerating CT equipment procurement timelines. Japan's METI enforces JIS traceability protocols for precision exporters. China's SAMR tightens GB standards for industrial radiography safety. South Korea's MFDS extends medical-grade quality rules to adjacent component manufacturing.
Japan
Automotive and aerospace suppliers in Nagoya's precision engineering corridor drive cone-beam CT deployment for real-time first-article inspection. METI's 2023 revision to JIS B 7440 mandates documented uncertainty budgets for coordinate measurements, forcing system upgrades among tier-one exporters. Japanese manufacturers now embed CT stations adjacent to machining centers to compress feedback loops from hours to minutes.
China
New energy vehicle producers in the Yangtze River Delta specify CT systems for battery cell weld inspection and lightweighting validation. SAMR enforcement of industrial radiography safety protocols mandates CT-based inspection for high-value exports from electronics contract manufacturers. Shanghai and Suzhou manufacturing clusters concentrate demand for flat-panel detector architectures in footprint-constrained shop-floor environments.
South Korea
Semiconductor fabs in Gyeonggi Province require sub-micron resolution CT for 3D packaging validation of advanced memory modules. MFDS alignment of medical device manufacturing quality rules extends CT inspection mandates to adjacent precision component suppliers. Samsung and SK Hynix supply chain partners drive specification tightening for multi-sensor integration platforms.
Taiwan
Foundries and advanced packaging houses in Hsinchu Science Park contract third-party labs for defect characterization of miniaturized assemblies. Electronics manufacturers prioritize performance-based service agreements with guaranteed throughput over equipment ownership. Distributed fabrication footprints across the island create demand for vendors with remote diagnostics and predictive maintenance capabilities.
Vietnam
Electronics contract manufacturing expansion in Bac Ninh and Hai Phong industrial zones lacks indigenous high-resolution CT capacity. Foreign-owned assembly plants favor equipment rental structures for capital flexibility amid demand volatility. Japanese and South Korean component suppliers impose incoming inspection protocols that outsource CT verification to regional service providers.
Asia Pacific Industrial Computed Tomography Market Competitive Environment
On the supply side, the industry is consolidating around precision optics heritage, calibrated service networks, and multi-sensor integration platforms. Three strategic archetypes dominate: Japanese precision equipment houses leveraging metrology credibility, German-Japanese component specialists controlling X-ray source supply, and diversified technology conglomerates offering bundled analytical solutions. Competitive moves concentrate on strategic partnerships for localized maintenance contracts and technology licensing for flat-panel detector architectures.
Within the precision optics tier, Nikon Corporation and Zeiss International exemplify vendors anchoring premium positioning through heritage technical credibility. Waygate Technologies represents the service-network archetype, sustaining regional coverage through calibrated maintenance infrastructure. Among diversified technology conglomerates, Shimadzu Corporation and Hitachi Ltd occupy positions spanning analytical instrumentation and industrial systems. These groupings illustrate how vendor selection criteria vary by end-user sophistication: aerospace mandates traceable metrology chains, while electronics manufacturers prioritize uptime guarantees and throughput commitments.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Omron Corporation |
| Nikon Corporation |
| Bruker Corporation |
| Waygate Technologies |
| Zeiss International |
| Comet Group Limited |
| Thermo Fisher Scientific Inc |
| Hitachi Ltd |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Southeast Asian electronics contract manufacturing is compressing lead times for flat-panel detector systems while simultaneously elevating pricing leverage among Japanese and German component suppliers serving precision metrology markets.
Pricing Analysis
Certification level creates the primary spread across the Asia Pacific industrial CT market, with JIS-traceable systems commanding substantial premiums over non-certified alternatives for Japanese automotive and aerospace exporters. Three-tier pricing structure across premium, standard, and economy levels reflects resolution specifications, software integration depth, and bundled calibration service commitments. Cost compression in economy-tier cone-beam systems is intensifying because Chinese domestic manufacturers are expanding detector assembly capacity in the Yangtze River Delta. Electronics contract manufacturers in Vietnam and Thailand exhibit the highest price sensitivity due to capital constraint pressures, while Japanese precision component exporters demonstrate the lowest sensitivity given regulatory compliance mandates.
Supply Chain Analysis
Electronics contract manufacturers including Foxconn, Luxshare, and Goertek hold substantial assembly capacity across Vietnam, Thailand, and southern China, creating concentrated demand nodes for in-line CT inspection systems. Vacuum tube and microfocus X-ray sources draw from German and Japanese specialty component houses, while amorphous silicon detector arrays rest on Taiwanese and South Korean semiconductor foundry output. Single-source vulnerability in high-voltage X-ray generator supply creates exposure for system integrators dependent on specific Japanese component vendors. Distribution runs through authorized regional service partners who bundle installation, calibration, and maintenance contracts to capture recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific industrial CT market is navigating a cyclical recovery anchored to semiconductor capital expenditure normalization and aerospace production rate restorations following supply chain dislocations.
For Market Incumbents: Harden defensive positioning by embedding NMIJ-traceable calibration capabilities directly into equipment platforms, addressing the regulatory compliance burden that Japanese precision exporters face under revised JIS B 7440 mandates. Deepen backward integration into flat-panel detector architectures to reduce exposure to single-source component bottlenecks from Taiwanese and South Korean sensor suppliers. Prioritize capacity expansion in Vietnam and Thailand to capture electronics contract manufacturing demand without incurring Japanese labor cost structures. For New Entrants and Emerging Players: Vietnam's electronics manufacturing zones present the most penetrable geography for CT service outsourcing, given indigenous high-resolution inspection capacity gaps and Japanese supplier incoming inspection mandates. Target performance-based service agreements with guaranteed uptime commitments rather than equipment sales, mirroring the preference shift observed among Taiwanese semiconductor fabs. Position through partnerships with established regional maintenance networks to overcome credibility barriers in calibration services. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment rental and managed-service contract segments as vendor financing structures proliferate. Long-term viability over the next decade rests on recurring revenue stability from calibration and maintenance contracts rather than cyclical equipment shipment volumes. Acquisition targets should demonstrate embedded metrology service capabilities with established NMIJ or equivalent national standards traceability. Monitor semiconductor fab capital expenditure announcements from Samsung and SK Hynix as the primary inflection indicator for South Korean CT demand. Quarterly review of JIS standard revision timelines and SAMR enforcement intensity is advised to detect regulatory-driven equipment upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Platform Integration | Addresses semiconductor metrology complexity for Samsung and SK Hynix packaging validation requirements. |
| Regional Calibration Center Expansion | Captures recurring revenue from Japanese precision exporters facing JIS B 7440 uncertainty documentation mandates. |
| Equipment Leasing Program Launch | Reduces capital barriers for Vietnamese and Thai electronics contract manufacturers amid demand volatility. |
| Neutron CT Capability Acquisition | Defends against Australian and Japanese synchrotron facilities capturing high-value aerospace failure analysis contracts. |
| Remote Diagnostics Infrastructure Deployment | Supports Taiwanese electronics manufacturers with distributed fabrication footprints requiring predictive maintenance guarantees. |
Study Parameters
A standing panel of metrology service directors, precision manufacturing quality managers, semiconductor fab equipment procurement leads, and aerospace NDT supervisors provided ongoing calibration for demand assumptions and technology adoption timelines. Primary interview intelligence combined with secondary validation from METI regulatory filings, SAMR standard revision notices, semiconductor industry capital expenditure disclosures, and customs trade data for CT system imports. Bottom-up equipment shipment estimates triangulated against top-down manufacturing value-added projections across the Asia Pacific precision engineering corridor.
Scenario-bracketing framed the analytical approach, with volume and value outputs stress-tested against alternative semiconductor capex trajectories and aerospace production rate assumptions across the projection horizon. Segmentation dimensions modeled include technology architecture, application criticality, end-user vertical, and service delivery structure, with particular attention to electronics versus aerospace procurement pattern divergence. CAGRs were derived from installed base growth rates and replacement cycle compression rather than simple trend extrapolation, incorporating METI-mandated JIS upgrade timelines and MFDS alignment effects on medical-adjacent manufacturing.
Practitioners should monitor semiconductor memory pricing cycles, JIS standard revision announcements, and SAMR enforcement intensity for early signals of forecast deviation. Forecasts reflect documented assumptions regarding detector technology cost curves and regional regulatory harmonization progress. Quarterly review of NMIJ calibration backlog indicators and Chinese new energy vehicle production rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Macroscopic Imaging Systems Market
Imaging
Europe Image Sensors Market
Imaging
Camera Technology Market
Imaging
Thermal Imaging Systems Market
Imaging
Chemiluminescence Imaging Market
Imaging
Hyperspectral Imaging Market
Imaging
Photography Equipment Market
Imaging
IP Camera Market
Imaging
Camera Lens Market
Imaging
Holotomographic Imaging Market
Imaging
PET Scanners Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
EUV Mask Inspection System Market
Imaging
Industrial Camera Market
Imaging
Global Trail Camera Market
Imaging
Document Imaging Market