
 Audio Power Amplifier IC Market | 2026-2036
Audio Power Amplifier IC Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Power Amplifier IC Market Outlook
Automotive infotainment is broadening the end-use mix for audio power amplifier ICs beyond traditional consumer electronics. Texas Instruments leverages its analog portfolio to dominate automotive-grade Class D solutions. Infineon Technologies AG anchors European supply through its silicon and silicon germanium expertise. STMicroelectronics N.V. competes across multiple amplifier classes with integrated manufacturing scale.
An audio power amplifier IC is a monolithic or multi-chip semiconductor device that boosts low-power audio signals to levels suitable for driving loudspeakers or headphones, typically operating across frequency ranges from 20 Hz to 20 kHz with total harmonic distortion below 1%. Class D amplifiers lead in portable and automotive applications due to efficiencies exceeding 90%, while CMOS technology occupies the highest volume tier for cost-sensitive consumer electronics. GaN-based designs represent the fastest-growing technology segment for high-end audiophile equipment where thermal performance and power density command premium positioning.
The EPA guides energy-efficiency standards for consumer electronics in the United States, while the EU Green Deal and REACH framework restrict hazardous substances and mandate lifecycle transparency across European supply chains. The FCC regulates electromagnetic emissions from wireless-enabled audio systems, shaping product certification requirements for OEMs targeting North American distribution. Stakeholders must monitor how evolving efficiency mandates and material restrictions redefine amplifier architecture roadmaps and foundry partnerships.
Market Dynamics
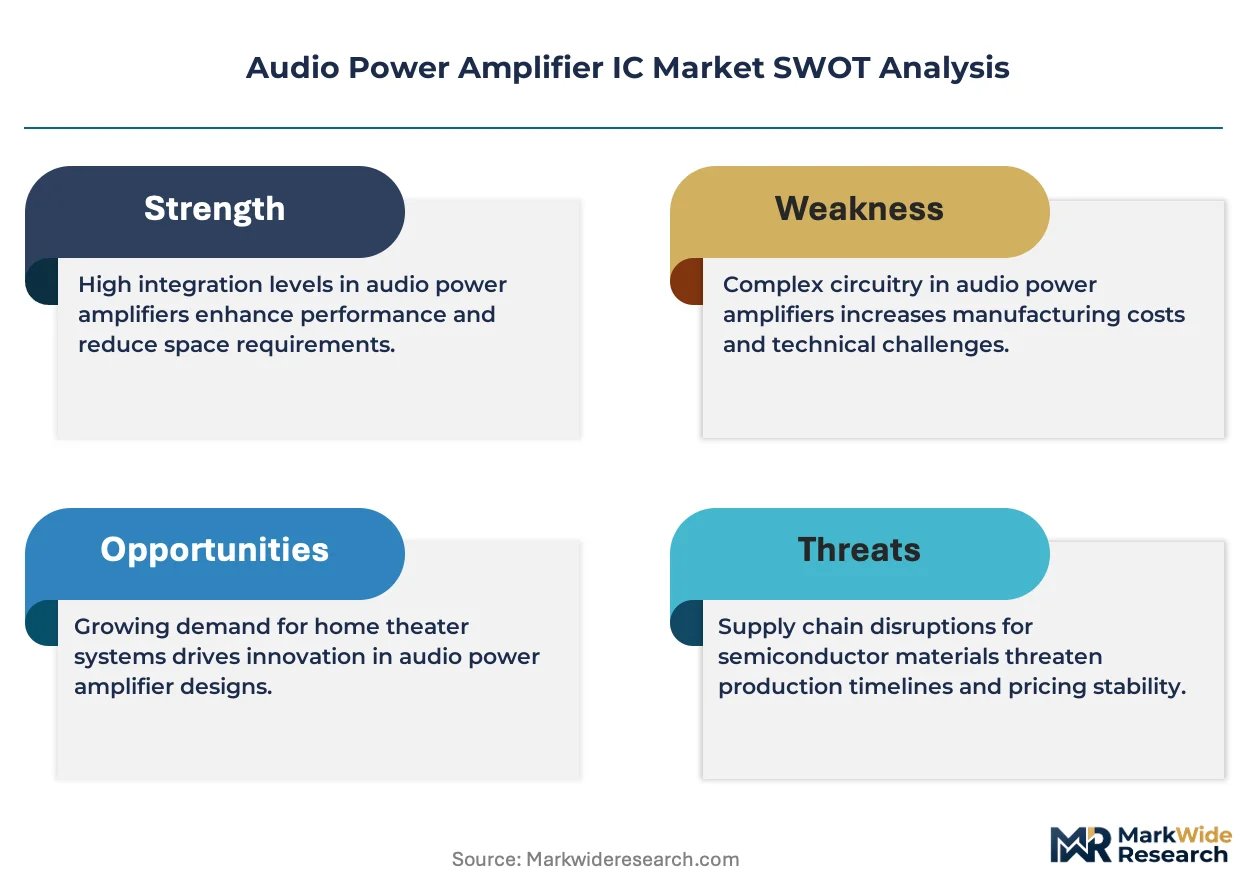
GaN-on-silicon technology is compressing thermal management requirements for high-power audio stages, forcing incumbent CMOS foundries to retool process nodes or cede premium amplifier segments to specialized compound semiconductor suppliers.
Growth Catalysts
- EU F-Gas Regulation:Efficiency mandates for consumer electronics components are accelerating Class D amplifier adoption across European white-goods and portable audio OEMs.
- Automotive infotainment integration:Dashboard audio modules now require multiple amplifier channels per vehicle, expanding addressable silicon content in Germany, China, and South Korea manufacturing clusters.
- GaN substrate availability:Improved 6-inch and 8-inch gallium nitride wafer supply is reducing cost premiums for high-efficiency amplifier designs targeting audiophile and professional sound reinforcement segments.
Market Restraints
- Silicon wafer price volatility:200mm and 300mm substrate costs fluctuate with memory chip demand cycles, compressing gross margins for high-volume Class AB amplifier producers.
- Packaging substrate concentration:ABF and BT resin substrate supply concentrates in Taiwan and Japan, creating single-source vulnerability for multi-chip audio amplifier modules.
- Electromagnetic compatibility thresholds:FCC Part 15 emissions limits impose costly shielding and filtering requirements on wireless-enabled smart speaker amplifiers.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component-level incentives are attracting audio amplifier IC packaging and testing investments to Uttar Pradesh and Tamil Nadu corridors.
- Spatial audio rendering in AR/VR headsets:Multi-channel amplifier arrays for head-tracked binaural synthesis represent uncontracted demand from metaverse hardware developers.
- REACH substance transparency:Lifecycle documentation requirements are creating service revenue streams for semiconductor firms offering certified conflict-free and halogen-free amplifier portfolios.
Industry Challenges
- Analog-mixed-signal design talent scarcity:Experienced IC architects capable of optimizing noise-floor and distortion specifications command compensation premiums that inflate R&D overhead.
- AEC-Q100 certification timelines:Automotive-grade qualification cycles extending 18-24 months delay revenue recognition for new amplifier designs targeting infotainment platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Power Amplifier IC Market |
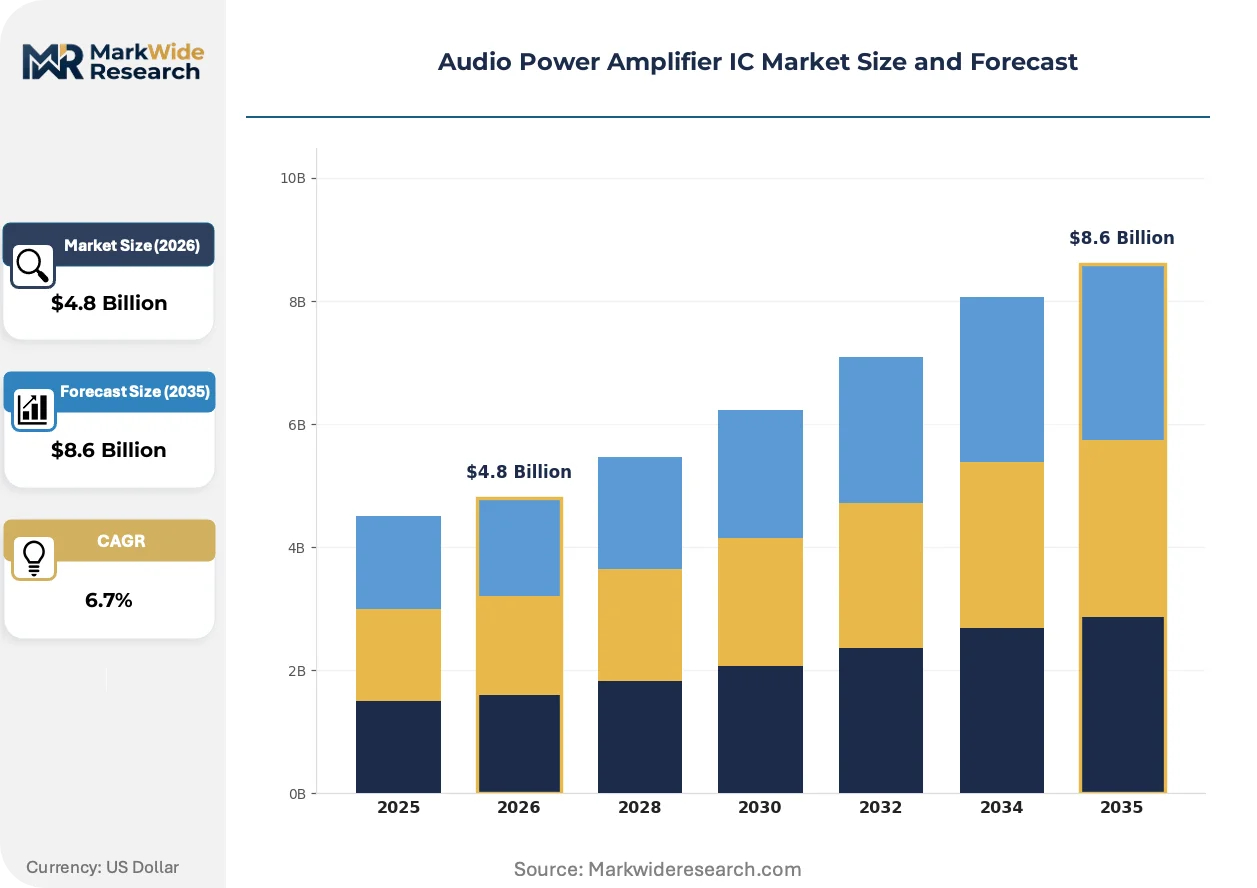
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class A, Class B, Class AB, Class D, Class G, Class H Technology: CMOS, Bipolar Junction Transistor, BiCMOS, GaN, SiGe Application: Portable Speakers, Soundbars, Home Theater Systems, Audiophile Equipment, Automotive Infotainment, Public Address Systems End User: Consumer Electronics Manufacturers, Audio Equipment OEMs, Tier-1 Suppliers, Aftermarket Providers |
| Companies Covered | Texas Instruments, Analog Devices, Infineon Technologies AG, STMicroelectronics N.V., NXP Semiconductors N.V., ON Semiconductor Corporation, Cirrus Logic, Inc., ROHM Semiconductor, Monolithic Power Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Power Amplifier IC Market Strategic Shifts
Integration of digital signal processing cores with analog output stages is collapsing board-level component counts, while regulatory pressure on standby power consumption is redefining efficiency benchmarks across all amplifier classes.
GaN HEMT devices are unifying switching amplification and power conditioning functions in single-die architectures. High-end sound reinforcement OEMs in North America and Western Europe are adopting these designs for touring rigs and installed venue systems. This unification is compressing the addressable market for discrete Class D controller ICs by absorbing timing and protection circuitry into the power transistor die.
The EU Green Deal's ecodesign requirements are mandating sub-0.5-watt standby power for networked audio equipment. Manufacturers serving European distribution channels must redesign power supply and amplifier standby logic to meet 2027 implementation deadlines. Consumer electronics brands with EU market exposure are prioritizing integrated PFC and standby control to avoid product delisting.
Direct procurement from foundries is displacing traditional semiconductor distribution for mid-tier audio amplifier buyers. Tier-two OEMs in South Korea and Taiwan now negotiate wafer starts and test services directly with 200mm analog foundries, bypassing authorized distributors. This channel compression is most visible in the portable Bluetooth speaker segment where annual volumes exceed 10 million units per SKU.
Audio Power Amplifier IC Market Segmentation
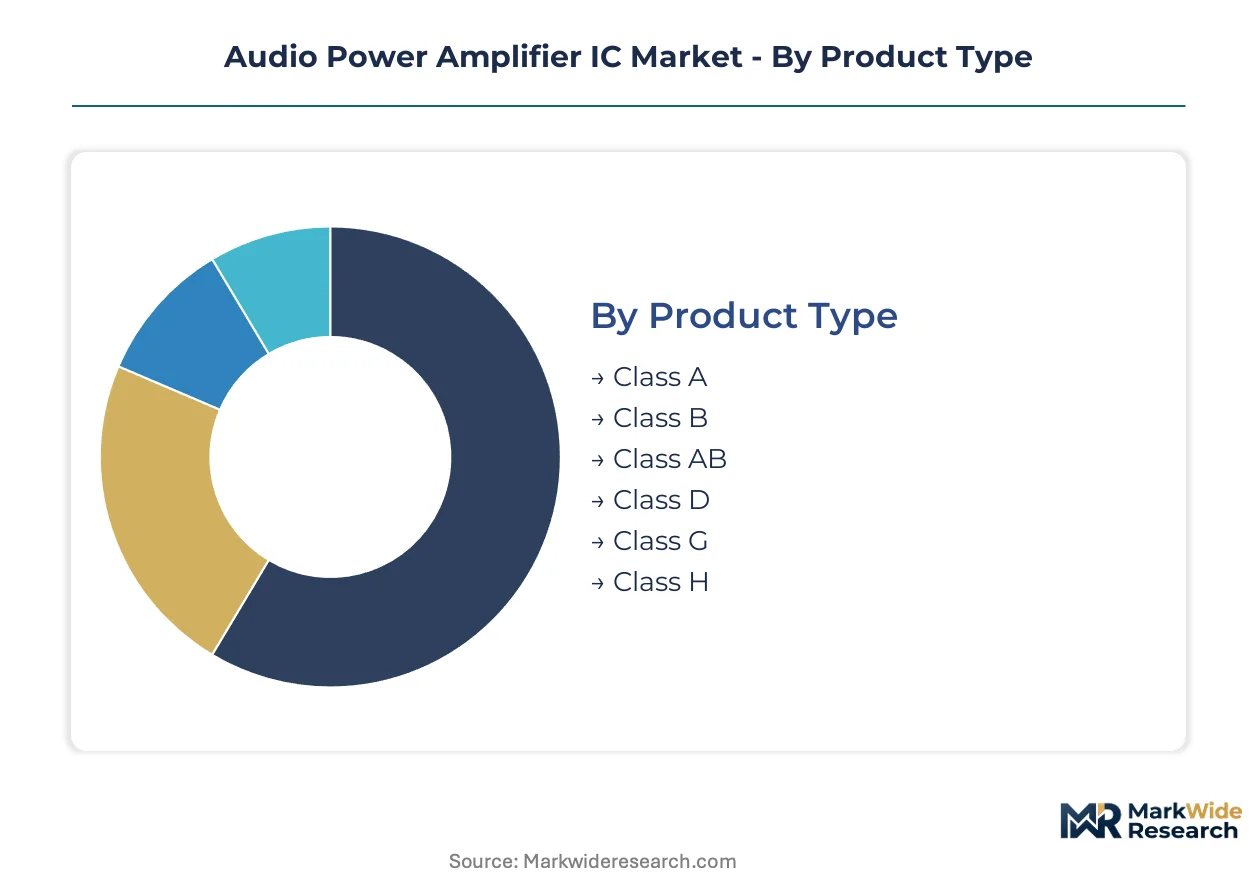
Audio power amplifier IC segmentation reveals distinct performance-cost tradeoffs across amplifier topologies and semiconductor processes. Technology selection directly constrains thermal budgets, electromagnetic profiles, and foundry sourcing strategies for OEMs.
Product Type:
Amplifier class selection hinges on efficiency mandates and linearity requirements.
- Class D:Switching amplification achieves efficiencies exceeding 90% through pulse-width modulation, minimizing heat sinking in portable and automotive applications. EU F-Gas Regulation efficiency benchmarks accelerate adoption across German and South Korean white-goods OEMs.
- Class AB:Hybrid linear-switching operation delivers sub-0.1% total harmonic distortion for mid-tier home audio, though 60% peak efficiency demands larger thermal packages. China-based consumer electronics manufacturers maintain volume demand for cost-optimized Class AB silicon.
- Class A:Continuous conduction delivers maximum linearity for studio monitoring and high-end audiophile equipment, with 25% efficiency limiting deployment to thermally managed rack systems.
- Class B:Push-pull complementary symmetry halves conduction losses versus Class A, though crossover distortion restricts use to budget public address systems where fidelity thresholds are relaxed.
- Class G:Rail-switching architectures dynamically adjust supply voltage to track signal amplitude, improving efficiency over Class AB in professional sound reinforcement without Class D's filtering complexity.
- Class H:Modulated rail voltage achieves similar efficiency gains to Class G through alternative topology, finding niche adoption in touring audio amplifiers where weight reduction justifies design complexity.
Mature deployment sits with Class AB. Newer deployment is concentrated in Class D.
Technology:
Process node selection determines power density, switching speed, and unit economics.
- CMOS:Complementary metal-oxide-semiconductor dominates volume production through mature 180nm and 130nm analog foundry nodes, enabling sub-dollar amplifier ICs for Bluetooth speaker OEMs. Taiwan and China foundry concentration keeps CMOS the default for cost-sensitive consumer electronics.
- GaN:Gallium nitride HEMT devices enable megahertz-range switching frequencies with minimal switching losses, collapsing magnetic component sizes in high-power professional audio. GaN substrate availability from 6-inch and 8-inch wafer supply is reducing cost premiums for audiophile and sound reinforcement segments.
- Bipolar Junction Transistor:Discrete and integrated bipolar processes deliver superior transconductance for low-noise preamplification stages, though power dissipation limits output stage integration.
- BiCMOS:Bipolar-CMOS integration combines analog precision with digital control logic, serving mid-tier automotive infotainment modules requiring integrated diagnostics.
- SiGe:Silicon germanium extends bipolar performance to microwave frequencies, supporting RF-integrated audio amplifiers in wireless-enabled smart speakers where Bluetooth coexistence filtering is required.
Volume concentration rests with CMOS. Technology transition is accelerating in GaN.
Application:
End-use environments dictate channel count, thermal envelope, and regulatory exposure.
- Automotive Infotainment:Dashboard audio modules require 4-12 amplifier channels per vehicle with AEC-Q100 Grade 2 temperature tolerance, expanding silicon content in Germany, China, and South Korean manufacturing clusters. Tier-1 suppliers specify integrated Class D solutions with load dump protection.
- Portable Speakers:Battery-powered operation mandates sub-100mW standby consumption and 90%+ efficiency, with annual volumes exceeding 10 million units per SKU enabling direct foundry procurement from mid-tier OEMs.
- Soundbars:Slim form factors drive multi-channel Class D integration with wireless subwoofer connectivity, subject to FCC Part 15 emissions certification for North American distribution.
- Home Theater Systems:5.1 and 7.1 channel configurations demand matched amplifier arrays with thermal synchronization, favoring integrated multi-channel ICs over discrete implementations.
- Audiophile Equipment:Ultra-low noise floors below -120dBV and sub-0.001% distortion specifications justify discrete component premium pricing and GaN-based output stages.
- Public Address Systems:70V and 100V line distribution requires high-voltage output stages with extended thermal cycling tolerance for installed venue and transportation applications.
Channel expansion is steepest in automotive infotainment. Efficiency pressure is most acute in portable speakers.
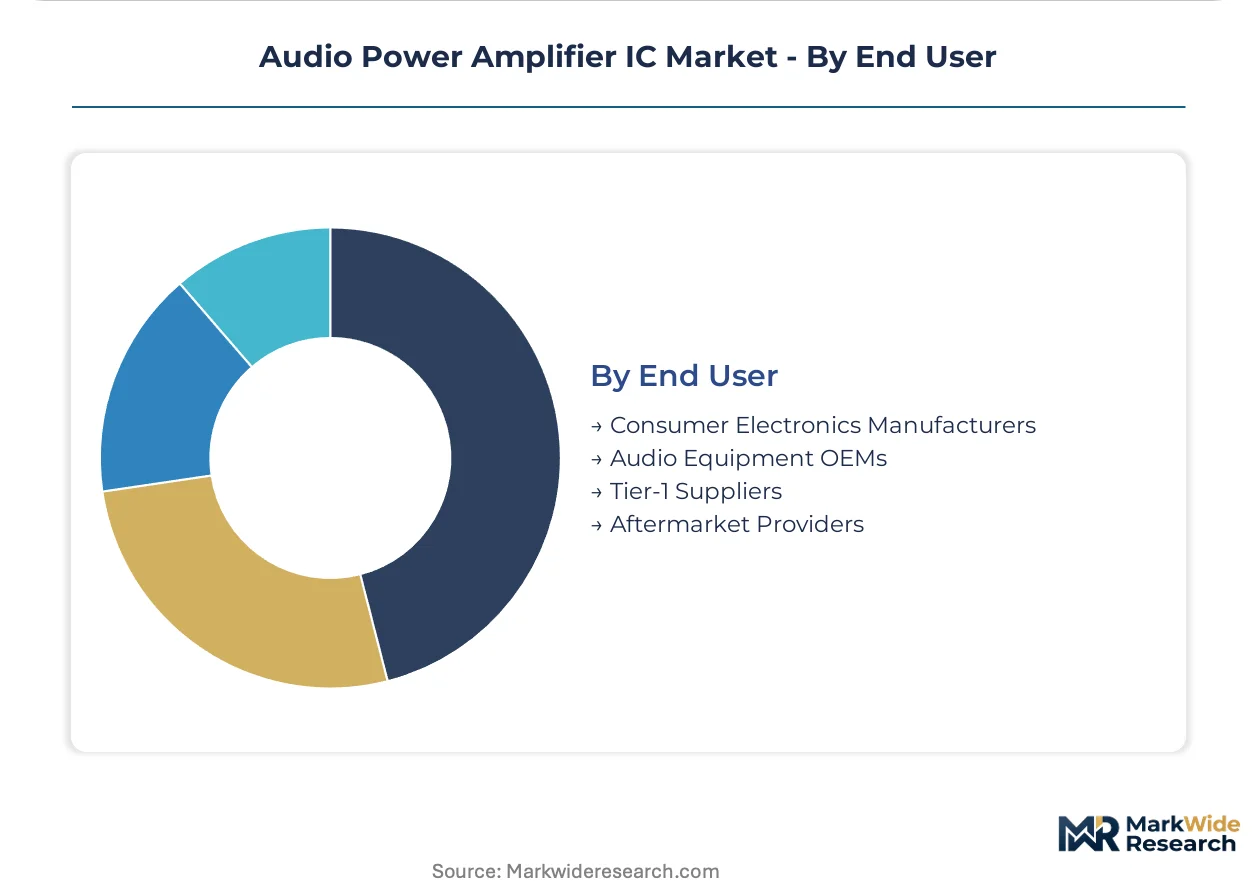
End User:
Procurement authority and technical integration depth vary sharply across buyer categories.
- Tier-1 Suppliers:Automotive electronics integrators specify amplifier ICs with 18-24 month AEC-Q100 qualification cycles, locking foundry capacity through long-term supply agreements. German and South Korean Tier-1s dominate infotainment platform design wins.
- Consumer Electronics Manufacturers:Smartphone and white-goods OEMs prioritize CMOS cost curves and packaging standardization, with annual volume commitments driving wafer-level negotiation leverage.
- Audio Equipment OEMs:Specialized speaker and amplifier brands differentiate through discrete component selection and custom thermal design, accepting higher BOM costs for performance segmentation.
- Aftermarket Providers:Vehicle audio upgrade and replacement channels demand pin-compatible drop-in solutions with minimal redesign, favoring established Class AB and Class D platforms over emerging GaN architectures.
Design authority concentrates with Tier-1 suppliers. Volume aggregation favors consumer electronics manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China, South Korea, and Germany concentrate audio power amplifier IC manufacturing through tax incentives and infrastructure subsidies. These zones anchor wafer fabrication, packaging, and automotive module assembly for global distribution.
China
MIIT dual carbon goals accelerate Class D amplifier adoption in Shenzhen and Dongguan consumer electronics clusters. GB standards on standby power consumption tighten efficiency benchmarks for white-goods OEMs. Yangtze River Delta foundries supply CMOS amplifier wafers to portable speaker manufacturers at sub-dollar unit economics.
Germany
KBA automotive certification requirements drive AEC-Q100 Grade 2 amplifier demand for infotainment platforms. EU F-Gas Regulation efficiency mandates reshape component sourcing for Berlin and Munich audio equipment brands. Bavaria anchors Continental and Bosch Tier-1 supplier design centers specifying integrated Class D solutions.
South Korea
MFDS electromagnetic compatibility rules intersect with FCC Part 15 alignment for Samsung and LG smart speaker exports. Seoul Capital Area fabless houses negotiate direct foundry contracts for 10-million-unit annual amplifier volumes. Busan-Ulsan packaging corridors assemble multi-chip modules for automotive dashboard integration.
United States
EPA energy-efficiency guidance shapes consumer electronics amplifier roadmaps for Amazon and Google smart speaker procurement. FCC emissions limits impose shielding costs on wireless-enabled audio systems targeting North American retail. Austin and Dallas analog design centers compete for automotive-grade Class D silicon talent.
India
PLI scheme component-level incentives attract amplifier IC testing investments to Uttar Pradesh and Tamil Nadu corridors. BIS certification requirements phase in for imported semiconductor modules. Bengaluru and Hyderabad EMS providers assemble soundbars for European export markets under REACH substance documentation rules.
Audio Power Amplifier IC Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with IDM-heavy portfolios dominating automotive-grade supply and fabless competitors capturing portable audio volumes. Consolidation concentrates around analog-mixed-signal design capabilities and AEC-Q100 qualification infrastructure. Three archetypes define positioning: integrated device manufacturers with captive fabs, fabless specialists licensing process technology, and diversified semiconductor conglomerates cross-selling amplifier blocks. Competitive moves center on foundry partnership exclusives and backward integration into gallium nitride substrate supply.
Among diversified semiconductor conglomerates, Texas Instruments and Infineon Technologies AG exemplify scale-driven IDM archetypes with automotive certification depth. STMicroelectronics N.V. occupies a position bridging consumer and automotive segments through integrated manufacturing scale. These three entities represent the dominant competitive anchors shaping foundry allocation and Tier-1 supplier design wins across German, Chinese, and South Korean manufacturing clusters.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Infineon Technologies AG |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| ON Semiconductor Corporation |
| Cirrus Logic, Inc. |
| ROHM Semiconductor |
| Monolithic Power Systems, Inc. |
| Others |
Value Chain & Pricing Dynamics
Analog-mixed-signal design talent concentration in Taiwan and South Korea creates labor-cost differentials that spread pricing tiers across premium automotive-grade, standard industrial, and economy consumer segments.
Pricing Analysis
Lead-time-driven pricing premiums reward expedited delivery of AEC-Q100 certified Class D amplifiers for automotive platform launches, while spot-market CMOS inventory trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates GaN-based audiophile modules from mid-tier BiCMOS automotive solutions and sub-dollar CMOS portable speaker chips. Pricing pressure stems from silicon wafer cost volatility compressing margins for high-volume Class AB producers. Consumer electronics manufacturers exhibit highest price sensitivity due to annual volume commitments exceeding 10 million units per SKU, whereas Tier-1 automotive suppliers accept premiums for guaranteed qualification documentation.
Supply Chain Analysis
Returns and refurbishment flows for professional sound reinforcement amplifiers create secondary supply channels that compete with new production in North American and Western European markets. Taiwan, South Korea, and China anchor wafer fabrication for CMOS and BiCMOS amplifier dies, while Japan and Malaysia concentrate ABF substrate production for multi-chip modules. Raw material dependencies include 200mm and 300mm silicon wafers, gallium nitride substrates from 6-inch and 8-inch wafer supply, and BT resin laminates for packaging. Single-source vulnerability in Taiwan-Japan packaging substrate corridors threatens module assembly continuity. Distribution runs through direct foundry contracts for mid-tier OEMs and authorized semiconductor distributors for smaller volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The audio power amplifier IC market sits in a technology-transition phase where GaN HEMT architectures displace legacy CMOS and bipolar solutions in high-power professional and audiophile segments.
For Market Incumbents: Extend AEC-Q100 qualification infrastructure to capture dashboard audio module expansion in German and South Korean automotive clusters. Secure long-term gallium nitride substrate offtake agreements to defend premium amplifier positioning against compound semiconductor specialists. Backward integration into 6-inch and 8-inch GaN wafer supply represents the critical lever for margin protection as silicon foundries retool for efficiency mandates. For New Entrants and Emerging Players: Direct-to-OEM digital procurement channels bypass established distributor relationships and unlock portable Bluetooth speaker volumes exceeding 10 million units annually. Spatial audio rendering hardware for AR/VR headsets offers the most penetrable white-space target, with uncontracted demand from metaverse developers seeking multi-channel amplifier arrays. Lead with reference designs emphasizing sub-0.5-watt standby compliance for EU Green Deal alignment. For Investors and Strategic Acquirers: Re-rating potential sits with GaN substrate suppliers given improved 6-inch and 8-inch wafer availability reducing cost premiums for high-efficiency amplifier designs. Long-term viability favors compound semiconductor specialists with captive epitaxy capabilities over fabless competitors tethered to foundry allocation cycles. Monitor AEC-Q100 certification backlog durations as an inflection indicator for automotive-grade supply tightness.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Substrate Supply Agreement | Secures 6-inch and 8-inch wafer access for high-efficiency amplifier cost reduction. |
| AEC-Q100 Certification Investment | Unlocks Tier-1 automotive infotainment design wins in German and South Korean clusters. |
| Direct Foundry Procurement Channel | Bypasses distributor markups for portable speaker OEMs with 10-million-unit annual volumes. |
| REACH Compliance Documentation Service | Captures service revenue from lifecycle transparency mandates under EU substance regulations. |
| Spatial Audio Reference Design Launch | Targets uncontracted AR/VR headset demand for head-tracked binaural synthesis hardware. |
Study Parameters
Document review covered SEC 10-K filings, customs and trade databases, and foundry capacity disclosures, complemented by interviews with analog IC design directors, Tier-1 automotive procurement managers, and consumer electronics supply chain planners. Secondary validation drew from MIIT dual carbon goal documentation, EU F-Gas Regulation implementation guidance, and EPA energy-efficiency standards. Bottom-up amplifier shipment modeling triangulated against top-down semiconductor consumption estimates across the analysis window.
Segmented outputs by amplifier class, semiconductor process technology, and end-use application combined with regional production cluster analysis to generate volume and value trajectories. CAGRs derived from historical foundry utilization trends, automotive platform production schedules, and efficiency regulation phase-in timelines. Forecast inputs incorporated GaN substrate supply expansion curves and AEC-Q100 certification pipeline durations.
The model holds under stable foundry allocation and regulatory implementation schedules; deviation in silicon wafer pricing volatility or EU ecodesign deadline acceleration would shift amplifier class adoption curves. Practitioners should monitor gallium nitride wafer supply announcements and automotive platform launch delays for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Global Interface IC Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Memory Integrated Circuits (IC) Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Communication Special Purpose Logic IC Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market
IC (Integrated Circuits)
Digital Potentiometer IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Japan Analog IC Market
IC (Integrated Circuits)
Computer and Peripherals Standard Logic IC Market
IC (Integrated Circuits)
Battery Fuel Gauge IC Market
IC (Integrated Circuits)
Semiconductor Integrated Circuit Chip Market
IC (Integrated Circuits)
United States Analog Integrated Circuits Market
IC (Integrated Circuits)
NFC Tag Ics Market
IC (Integrated Circuits)
3D IC and 2.5D IC Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market