
 Thermal Flow Meter Market | 2026-2036
Thermal Flow Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Flow Meter Market Outlook
Asian sensor foundries are decoupling from legacy calibration dependencies, building in-house thermal reference labs to shorten lead times for high-precision flow elements. Emerson Electric leverages its Rosemount instrumentation franchise to anchor North American petrochemical retrofit cycles. Siemens competes through its Sitrans portfolio, dominating digital integration architectures across European process industries. Yokogawa Electric Corporation specializes in explosion-proof thermal designs for offshore platform applications.
Thermal flow meters measure mass flow rate by detecting temperature differential across a heated sensor element, typically operating with platinum resistance temperature detectors paired with constant-power or constant-temperature Wheatstone bridge circuits to achieve accuracies within one percent of reading in gas applications. Their primary industrial purpose centers on direct mass flow measurement without density compensation, eliminating the need for separate pressure and temperature correction in compressed gas and flare monitoring systems. Inline thermal configurations sustain premium positioning in custody transfer applications where pipeline integrity demands full-bore measurement, while insertion types occupy mid-range process control installations requiring hot-tap retrofit capability. Smart technology variants with HART and Foundation Fieldbus protocols are capturing margin pools as facilities prioritize predictive diagnostics over analog signal outputs.
The EPA enforces Mandatory Greenhouse Gas Reporting Rule protocols that specify thermal meter performance standards for flare gas quantification, while the EU F-Gas Regulation drives replacement demand through phased restrictions on fluorinated greenhouse gas emissions in industrial cooling circuits. IEC 61508 functional safety standards shape product development roadmaps as end-users demand SIL-rated thermal instruments for safety instrumented systems. Stakeholders must monitor evolving methane emissions accounting rules across multiple jurisdictions to anticipate specification shifts in next-generation procurement cycles.
Market Dynamics
EPA greenhouse gas reporting mandates are compressing specification cycles for flare gas monitoring equipment, forcing instrumentation vendors to accelerate SIL-rated product certifications ahead of procurement deadlines.
Growth Catalysts
- EU F-Gas Regulation:Phased restrictions on fluorinated greenhouse gas emissions in industrial cooling circuits are accelerating replacement demand for thermal meters with leak-detection integration.
- Offshore platform electrification:North Sea operators are specifying explosion-proof thermal designs for flare gas quantification on unmanned installations.
- Platinum resistance temperature detectors:Asian sensor foundries are scaling in-house thermal reference lab capacity to shorten lead times for high-precision flow elements.
Market Restraints
- Platinum price volatility:Wheatstone bridge circuits depend on platinum RTD elements, exposing manufacturers to precious metal commodity swings.
- Inline configuration cost premium:Full-bore custody transfer meters require pipeline shutdown for installation, limiting retrofit applicability.
- Coriolis meter substitution:Liquid-phase applications increasingly favor Coriolis mass flow technology where density compensation is already available.
Strategic Opportunities
- India PLI scheme:Process instrumentation localization incentives are opening procurement channels for domestic thermal meter assembly.
- HART protocol convergence:Smart transmitters with predictive diagnostics are capturing margin pools from analog signal installations in German chemical clusters.
- Biogas upgrading facilities:Methane purity verification requirements are creating specification demand for thermal mass flow in anaerobic digestion plants.
Industry Challenges
- SIL certification timelines:IEC 61508 functional safety assessments for safety instrumented systems extend product development cycles by 12-18 months.
- Legacy system integration:Foundation Fieldbus deployment requires specialized commissioning expertise that mid-sized process operators struggle to source.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Flow Meter Market |
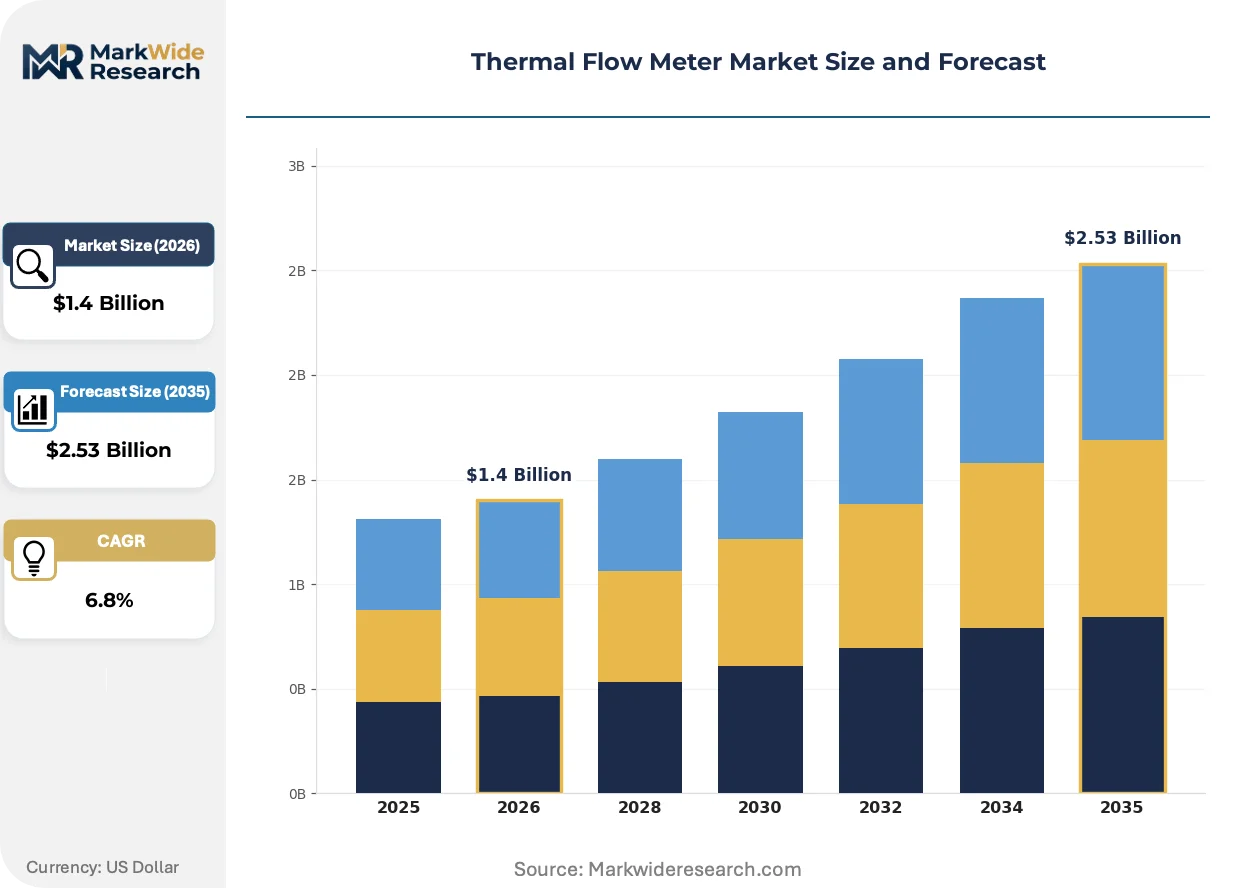
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insertion Type, Inline Type, Portable Type, Microthermal Type End User: Oil & Gas, Water & Wastewater Treatment, Chemicals, HVAC Technology: Analog, Digital, Smart, Ultrasonic Application: Flow Measurement, Energy Monitoring, Process Control, Volume Measurement |
| Companies Covered | SICK, Sierra Instruments, Emerson Electric, ABB, FCI (Fluid Components International), Siemens, Bronkhorst, Yokogawa Electric Corporation, Endress+Hauser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Flow Meter Market Strategic Shifts
Digital integration architectures are displacing analog signal infrastructures across process industries, compressing the window between sensor specification and predictive maintenance deployment.
Multi-variable thermal transmitters is consolidating discrete temperature and flow measurement functions into single housing units. Petrochemical operators in the US Gulf Coast are specifying these integrated designs for new build projects. This consolidation is compressing vendor qualification lists as procurement teams reduce supplier management overhead.
The EPA's Mandatory Greenhouse Gas Reporting Rule is tightening flare gas quantification accuracy thresholds for petroleum refineries. Refinery operators must now demonstrate continuous monitoring capability with documented calibration traceability. This pressure is accelerating specification shifts toward smart thermal meters with embedded diagnostic logging in Texas and Louisiana process complexes.
After-sales service unbundling is fragmenting traditional full-service contracts into separate hardware, calibration, and software subscription components. German automotive manufacturing clusters are driving this decomposition through competitive tendering for meter verification services. This pattern is most visible in Baden-Württemberg precision instrumentation procurement, where end-users now source calibration from third-party metrology laboratories.
Thermal Flow Meter Market Segmentation
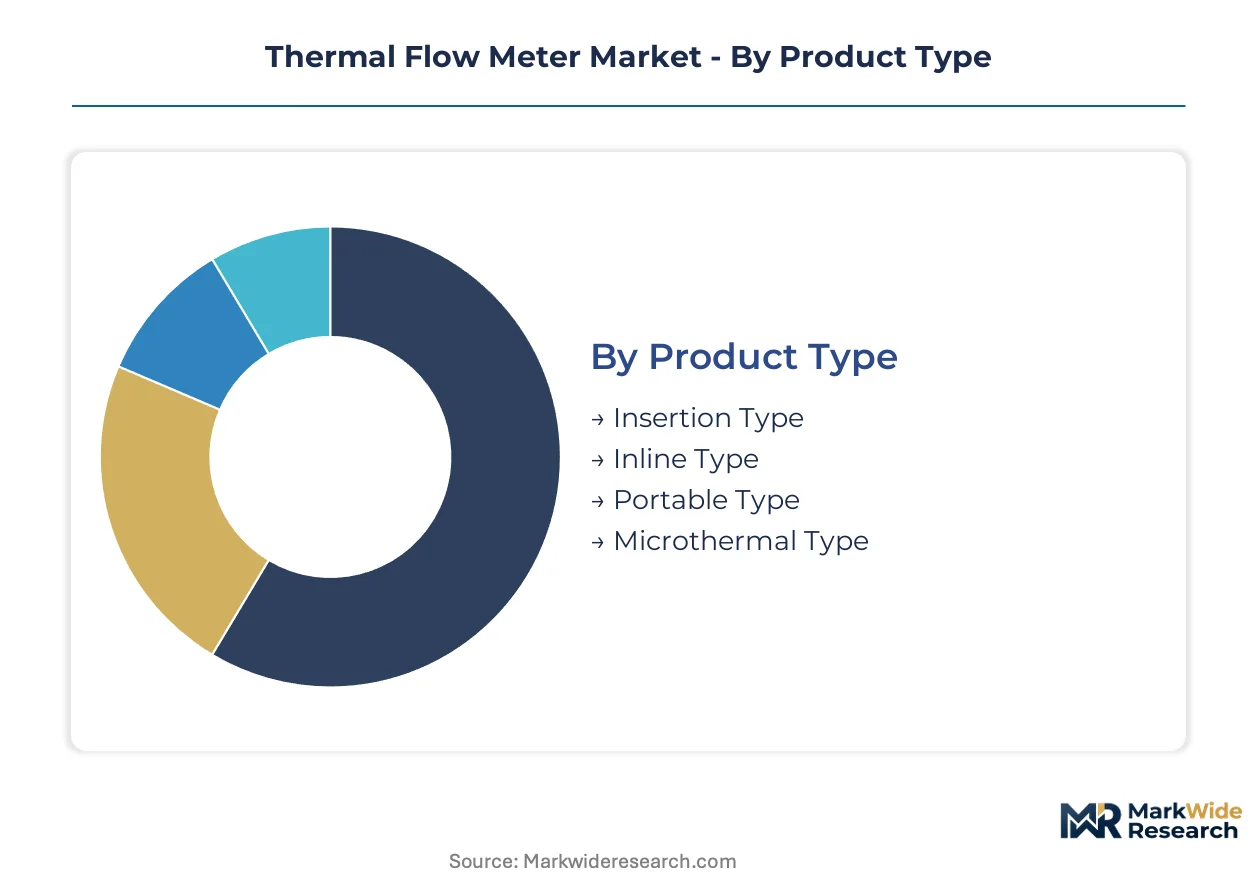
Thermal flow meter segmentation reveals distinct capital requirements across configuration types, with inline installations demanding pipeline shutdowns and insertion variants enabling hot-tap retrofits. End-use concentration in oil and gas custody transfer drives premium specification cycles, while technology tiers separate legacy analog infrastructure from predictive diagnostic platforms.
Product Type:
Capital intensity varies sharply across physical configurations, with full-bore inline meters requiring the highest upfront investment for pipeline integration and flanged connections.
- Inline Type:Full-bore designs integrate directly into pipeline infrastructure with flanged or welded connections, achieving custody-transfer-grade accuracy through complete flow profile capture. Demand concentrates in Texas and Louisiana refinery complexes where EPA flare gas quantification mandates enforce continuous monitoring with documented calibration traceability.
- Insertion Type:Probe-based configurations deploy through hot-tap fittings without process interruption, sacrificing some accuracy for retrofit accessibility. German chemical clusters in Baden-Württemberg specify these for mid-range process control installations where predictive diagnostics outweigh absolute precision requirements.
- Portable Type:Battery-powered verification units serve calibration audit and temporary measurement needs.
- Microthermal Type:Compact chip-scale designs address laboratory and semiconductor process gas applications.
Most installed capacity flows through Inline Type configurations. Expansion is steepest in Insertion Type segments.
End User:
Application environments dictate specification rigor, with explosive atmosphere certifications and SIL ratings separating oil and gas procurement from general industrial demand.
- Oil & Gas:Upstream, midstream, and downstream operators deploy thermal meters for custody transfer, flare gas monitoring, and emissions quantification. North Sea platform electrification programs specify explosion-proof designs for unmanned installations.
- Chemicals:Process control and reactor feed measurement drive demand for corrosion-resistant wetted materials. German automotive manufacturing clusters pair thermal meters with leak-detection integration for fluorinated gas compliance.
- Water & Wastewater Treatment:Aeration basin airflow and biogas recovery applications favor cost-optimized insertion designs.
- HVAC:Building automation systems specify thermal meters for chilled water and combustion air monitoring.
Procurement volume concentrates in Oil & Gas. Chemicals is climbing the fastest.
Technology:
Signal processing architectures determine lifecycle economics, with smart platforms capturing margin through predictive maintenance subscriptions while analog installations face replacement pressure.
- Smart:HART and Foundation Fieldbus-enabled transmitters embed diagnostic logging and remote calibration capabilities. US Gulf Coast petrochemical operators specify these for EPA greenhouse gas reporting compliance with continuous monitoring documentation.
- Digital:Microprocessor-based designs offer intermediate functionality between analog and fully smart platforms. Indian process industries under PLI localization incentives specify these for domestic assembly qualification.
- Analog:4-20 mA signal outputs persist in legacy installations with limited upgrade budgets.
- Ultrasonic:Non-thermal measurement principle competes in specific gas applications requiring no pressure drop.
Deployment share remains largest in Analog. Smart platforms are gaining share fastest.
Application:
Measurement purpose determines accuracy requirements and calibration protocols, with custody transfer demanding full-bore configurations and process control tolerating insertion probes.
- Flow Measurement:Direct mass flow quantification without density compensation represents the core thermal meter value proposition. Biogas upgrading facilities in Germany specify these for methane purity verification in anaerobic digestion plants.
- Energy Monitoring:Thermal mass flow enables BTU calculation for combustion optimization and carbon accounting. US refinery operators deploy these for EPA Mandatory Greenhouse Gas Reporting Rule compliance.
- Process Control:Feedback loop integration for reactor feed and burner management tolerates moderate accuracy.
- Volume Measurement:Derived calculations require pressure and temperature compensation, reducing thermal meter competitiveness.
Installed base concentrates in Flow Measurement. Energy Monitoring shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping thermal flow meter procurement as manufacturers relocate assembly to jurisdictions with streamlined SIL certification pathways. Cost-of-compliance gaps between EPA-mandated US specifications and EU F-Gas Regulation frameworks are accelerating cross-border sourcing decisions.
United States
EPA Mandatory Greenhouse Gas Reporting Rule enforcement drives flare gas monitoring upgrades across Texas and Louisiana refinery complexes. The agency's documented calibration traceability requirements compress procurement cycles for smart transmitters with embedded diagnostic logging. US Gulf Coast petrochemical operators specify HART-enabled designs for continuous emissions verification.
Germany
EU F-Gas Regulation phased restrictions accelerate replacement demand for leak-detection-integrated thermal meters in automotive cooling circuits. Baden-Württemberg precision instrumentation clusters drive competitive tendering for meter verification services. German chemical manufacturers unbundle after-sales contracts into separate hardware, calibration, and software subscription components.
China
Dual carbon goals under MEE oversight tighten methane emissions accounting standards for industrial facilities. Yangtze River Delta sensor foundries build in-house thermal reference labs to shorten lead times for high-precision platinum RTD elements. Domestic process industries scale assembly capacity for cost-optimized insertion designs.
India
PLI scheme localization incentives open procurement channels for domestic thermal meter assembly in process instrumentation. Maharashtra and Gujarat industrial corridors specify microprocessor-based digital transmitters for qualification under domestic content requirements. Indian chemical operators prioritize hot-tap retrofit capability to minimize pipeline shutdown costs.
United Kingdom
North Sea platform electrification programs specify explosion-proof thermal designs for unmanned flare gas quantification installations. UK regulators align offshore emissions monitoring with EU F-Gas Regulation transition timelines. Aberdeen energy services clusters source SIL-rated instruments for safety instrumented systems on decommissioning-delayed assets.
Thermal Flow Meter Market Competitive Environment
German and Swiss producers anchor the premium-tier instrumentation segment; US and Japanese specialists hold positions in explosion-proof and offshore applications. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with full instrumentation portfolios, mid-cap sensor specialists with focused thermal expertise, and regional fabricators serving cost-sensitive retrofit markets. Dominant competitive moves include geographic expansion through localized assembly partnerships and technology licensing for smart transmitter protocol integration.
Among diversified industrial conglomerates, Emerson Electric and Siemens exemplify scale-driven positioning across petrochemical and process industry verticals. Yokogawa Electric Corporation occupies a specialist tier focused on hazardous environment certifications. These three anchors represent distinct competitive vectors: North American retrofit cycle capture, European digital integration architecture dominance, and Asia-Pacific offshore platform specialization.
| Leading Market Players |
|---|
| SICK |
| Sierra Instruments |
| Emerson Electric |
| ABB |
| FCI (Fluid Components International) |
| Siemens |
| Bronkhorst |
| Yokogawa Electric Corporation |
| Endress+Hauser |
| Others |
Value Chain & Pricing Dynamics
Platinum price volatility cascades through Wheatstone bridge manufacturing costs into tiered instrument pricing, with precious metal commodity swings compressing margins on high-accuracy custody transfer meters while forcing recalibration of insertion-type positioning for process control buyers.
Pricing Analysis
Distributor margins on smart transmitters with HART protocol integration absorb certification cost premiums before reaching refinery procurement teams in Texas and Louisiana. Three-tier pricing structure across SIL-rated premium, standard digital, and legacy analog levels segments buyer archetypes by compliance urgency and calibration traceability requirements. Cost compression in mid-range insertion configurations is intensifying because Asian foundries are scaling domestic assembly capacity. Water and wastewater treatment operators exhibit highest price sensitivity, while oil and gas custody transfer buyers prioritize measurement accuracy over unit cost.
Supply Chain Analysis
Freight cost differentials between German precision instrumentation clusters and Yangtze River Delta sensor foundries influence sourcing decisions for European process industries. Manufacturing concentrates in Germany, China, and the United States, with platinum RTD elements drawing from South African and Russian mining outputs. Single-source vulnerability in high-purity platinum supply creates exposure for Wheatstone bridge circuit producers. Distribution runs through authorized instrumentation distributors serving petrochemical complexes, with direct OEM relationships dominating large-scale refinery retrofit contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal flow meter demand compounds through successive regulatory tightening cycles, with EPA greenhouse gas reporting mandates and EU F-Gas Regulation phased restrictions creating overlapping procurement windows that sustain replacement velocity across industrial verticals.
For Market Incumbents: To counter Coriolis meter substitution in liquid-phase applications, anchor retrofit capture through predictive diagnostics subscription bundling and deepen backward integration into platinum RTD element production to insulate margin from commodity swings. Accelerate SIL certification pipelines for safety instrumented system specifications before procurement deadlines compress. For New Entrants and Emerging Players: Launch via third-party metrology laboratory partnerships targeting German automotive manufacturing clusters where after-sales service unbundling has fragmented incumbent full-service contracts. White-space concentrates in Indian process instrumentation localization under PLI scheme incentives and biogas upgrading facility specifications for methane purity verification. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap sensor specialists with captive thermal reference lab capacity because certification backlog creates acquisition currency for faster SIL-rated product market entry. Target platform consolidation around smart transmitter protocol integration capabilities. Watch EPA methane emissions accounting rule evolution as inflection signal for specification shift velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum RTD Production | Captive supply of Wheatstone bridge elements insulates margin from South African commodity volatility. |
| Smart Transmitter Protocol Integration | HART and Foundation Fieldbus certification opens procurement channels at US Gulf Coast petrochemical operators. |
| Explosion-Proof Design Certification | IECEx and ATEX compliance qualifies vendors for North Sea platform electrification programs. |
| After-Sales Service Unbundling | Separate calibration and software subscription components match German automotive cluster tendering patterns. |
| Domestic Assembly Partnership | Indian PLI scheme localization meets government procurement domestic content requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with instrumentation procurement managers at petrochemical operators, maintenance directors at refinery complexes, OEM engineering teams specifying custody transfer systems, and aftermarket service heads at distributor networks with secondary validation against EPA enforcement databases, EU ETS transaction records, SEC filings from listed industrial conglomerates, and customs trade data for platinum-containing instrument imports. Bottom-up segment sizing and top-down macro anchoring were cross-checked for convergence.
Historical reference periods anchored the projection horizon through documented retrofit cycle timing and regulatory compliance deadline clustering. Segmentation dimensions modeled include product configuration type, end-use industry vertical, technology tier, and regional regulatory framework. CAGRs were derived from fitted growth curves applied to disclosed shipment volumes and disclosed order backlog trajectories. Forecast inputs incorporated EPA greenhouse gas reporting rule enforcement intensity and EU F-Gas Regulation phase-out schedules.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions, platinum price spike events exceeding historical volatility bands, and breakthrough sensor technologies displacing thermal measurement principles. Forecasts reflect assumptions about continued enforcement continuity and technology adoption pacing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Smart Parking Sensor Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Thermometer Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
Inline Quality Control Sensors Market