
 Nano Dentistry Market | 2026-2036
Nano Dentistry Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Dentistry Market Intelligence
Multi-source procurement of nano-ceramic precursors is expanding as dental manufacturers diversify supply risk across Asian and European chemical suppliers. DENTSPLY Sirona leverages captive R&D facilities in Switzerland to sustain formulation control for its nano-composite resin portfolio. Institut Straumann anchors its competitive position through precision milling partnerships that secure CAD/CAM system integration. Zimmer Biomet competes via orthopedic-to-dental technology transfer, applying surface nanotopography expertise from joint implants to dental screw designs.
Nano dentistry applies engineered nanomaterials—typically 1-100 nm particles of silica, zirconia, or hydroxyapatite—into restorative and preventive formulations to enhance mechanical strength, wear resistance, and bioactive interaction with dental tissues. These materials are synthesized through sol-gel processing or mechanochemical milling, then dispersed into resin matrices or ceramic slurries for chairside or laboratory fabrication of crowns, fillings, and implant coatings. Nano-composite resins command the largest revenue pool due to direct restoration volume, while bioprinting represents the fastest-expanding technology segment as tissue-engineered periodontal scaffolds advance from research to clinical validation. Preventive care applications show accelerating uptake as nano-suspended fluoride and antimicrobial solutions gain reimbursement traction in European dental practices.
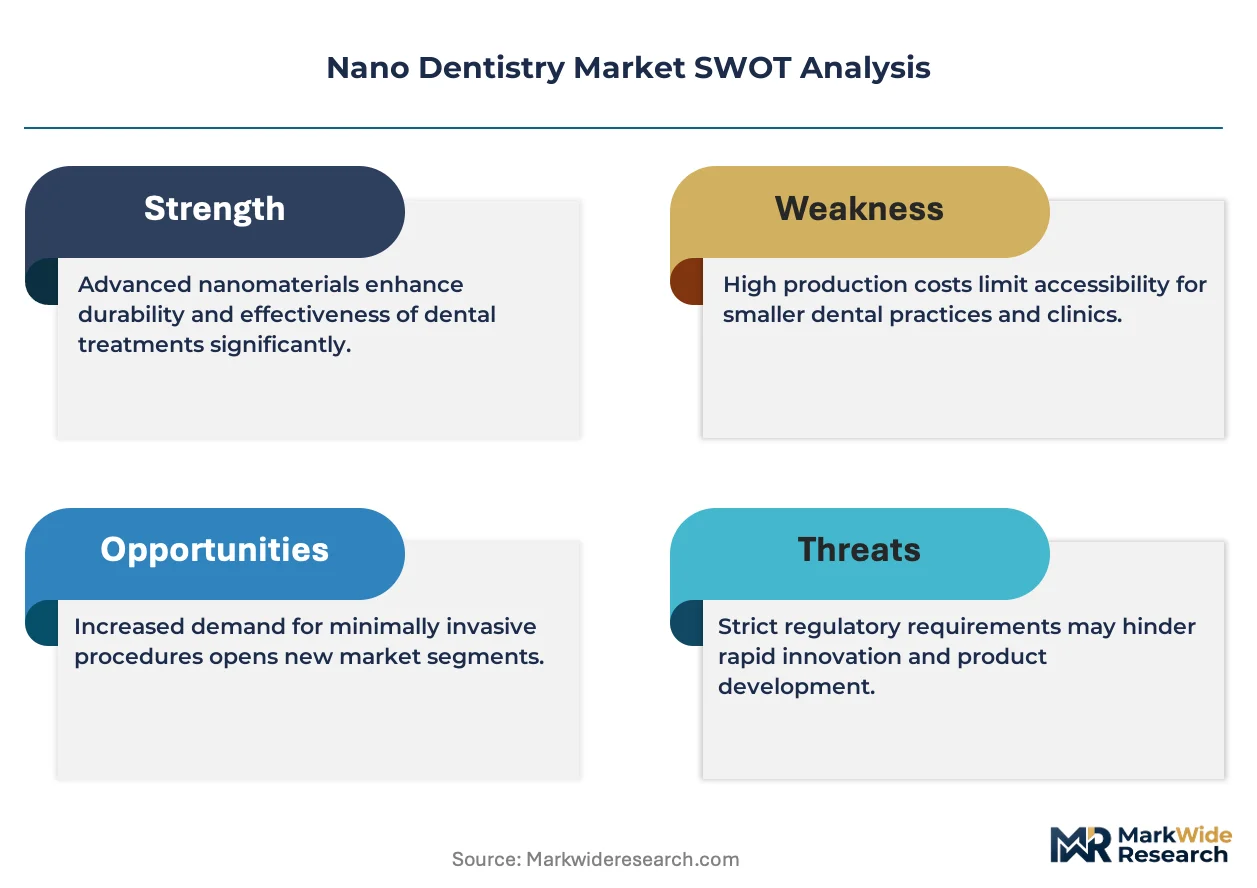
FDA 510(k) pathways govern nanomaterial device clearance in the United States, while EMA and national competent authorities apply evolving nano-specific guidance under EU MDR for risk classification of permanent implantable dental products. REACH registration requirements for nanoparticle raw materials constrain European formulation flexibility and elevate compliance costs for imported nano-ceramic powders. Stakeholders must monitor regulatory divergence between FDA's case-by-case nanotechnology approach and Europe's emerging horizontal nano-framework, as this gap will determine manufacturing location decisions and clinical trial investment priorities.
Market Dynamics
Chairside CAD/CAM fabrication is compressing restoration turnaround times from weeks to hours, forcing dental laboratories to reposition toward complex implant prosthetics and aesthetic layering services that resist commoditization.
Growth Catalysts
- EU MDR nano-specific guidance:EMA's evolving classification framework for permanent implantable dental products is creating regulatory clarity that accelerates clinical trial investment and product registration timelines.
- Silica nanoparticle dispersion:Advances in sol-gel processing enable uniform particle distribution within resin matrices, improving mechanical strength thresholds for posterior restorations.
- Multi-location dental service organizations:Consolidated procurement by United States-based DSOs creates volume commitments that justify manufacturing scale-up for nano-composite formulations.
Market Restraints
- Zirconia precursor concentration:Asian chemical suppliers dominate nano-ceramic powder production, creating single-source vulnerability for European formulators dependent on REACH-registered imports.
- Mechanochemical milling capex:Sub-50 nm particle production requires specialized attritor systems that smaller dental material manufacturers cannot finance without strategic partnerships.
- Conventional glass ionomer substitution:Fluoride-releasing traditional materials retain reimbursement advantages in pediatric and geriatric segments where nano-premium pricing faces resistance.
Strategic Opportunities
- Bioprinted periodontal scaffolds:Tissue-engineered solutions for alveolar bone regeneration represent whitespace beyond traditional restoration, with Switzerland and Germany hosting early clinical validation cohorts.
- Japan METI nanomaterial safety standards:Alignment with PMDA's nano-device pathway creates a regulatory bridge for products seeking simultaneous East Asian market entry.
- Direct-to-clinic nano-fluoride distribution:Subscription models for preventive nano-suspensions bypass dental laboratory intermediaries, capturing margin in European preventive care practices.
Industry Challenges
- Formulation chemist scarcity:Interdisciplinary expertise spanning colloidal chemistry, polymer science, and dental biomaterials concentrates in Swiss and German research clusters, constraining R&D expansion elsewhere.
- FDA 510(k) nanotechnology case-by-case review:Unpredictable clearance timelines for novel particle architectures delay commercialization and compress effective patent life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Dentistry Market |
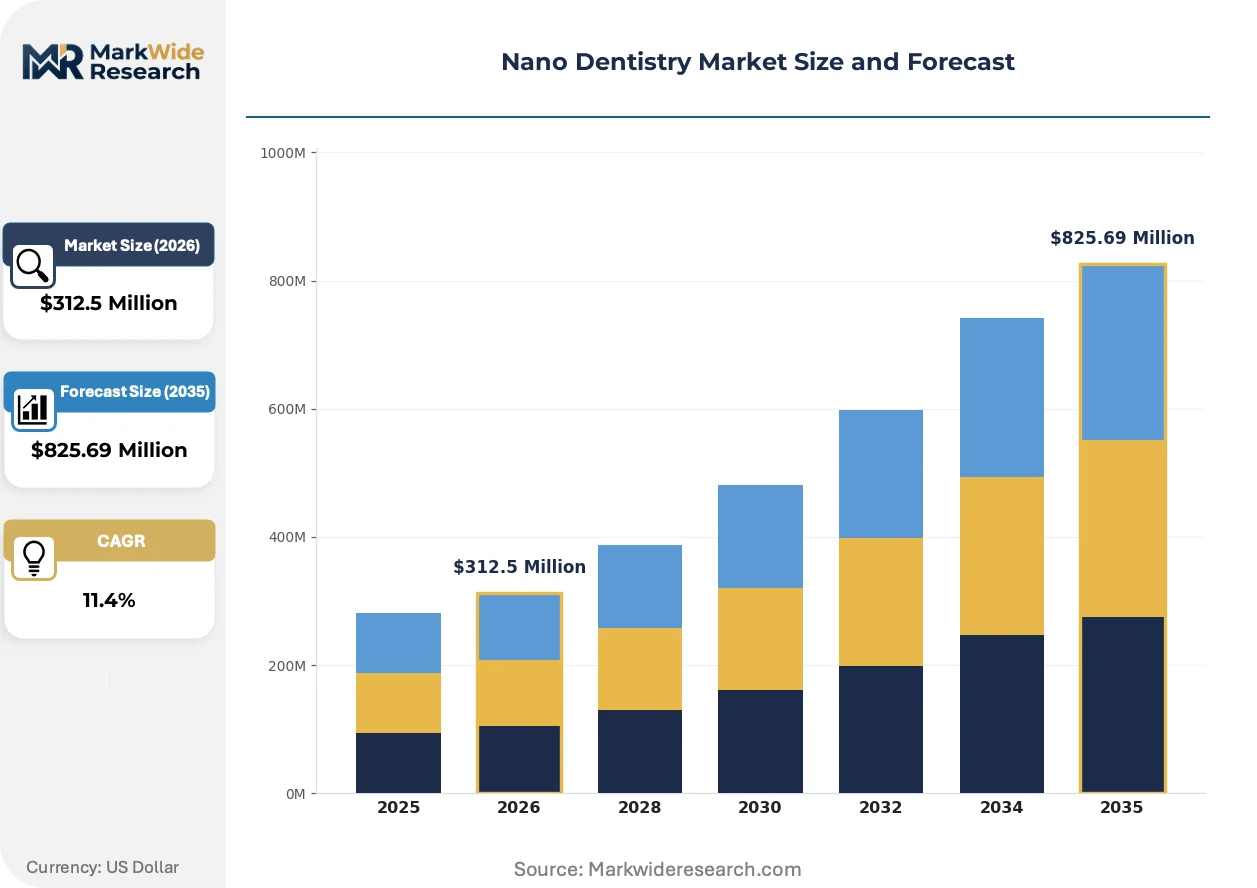
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nano-Composite Resins, Nanoparticles, Nano-Ceramics, Nano-Suspended Solutions Application: Restorative Dentistry, Preventive Care, Orthodontics, Periodontics Technology: Laser Technology, Ultrasonic Treatment, CAD/CAM Systems, Bioprinting End User: Dental Clinics, Hospitals, Research Laboratories, Academic Institutions |
| Companies Covered | DENTSPLY Sirona, Institut Straumann, Zimmer Biomet, Ivoclar Vivadent, aap Implantate AG, Heraeus Kulzer, BioHorizons IPH, 3M, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Dentistry Market Strategic Shifts & Innovations
Digital workflow integration and bioactive material science are converging to redefine value capture in restorative dentistry, shifting competitive advantage from material properties alone to system-level clinical outcomes.
Nano-hydroxyapatite surface coatings for titanium implants are expanding into osseointegration acceleration applications, with German and Swiss implant manufacturers adopting the technology to differentiate premium screw designs. The structural consequence is compression of healing timelines that previously justified extended temporary restoration contracts.
REACH registration requirements for nanoparticle raw materials are tightening European formulation flexibility, elevating compliance costs for imported nano-ceramic powders and incentivizing backward integration into captive precursor synthesis. German manufacturers are responding by relocating milling operations to Switzerland to leverage Swissmedic's parallel regulatory pathway.
DSO procurement centralization is consolidating supplier relationships around vendors offering validated CAD/CAM block compatibility, with United States multi-location operators demanding seamless integration with existing chairside milling investments. This pattern is most visible in Texas and Florida metropolitan corridors where dental practice consolidation has advanced furthest.
Nano Dentistry Market Segmentation
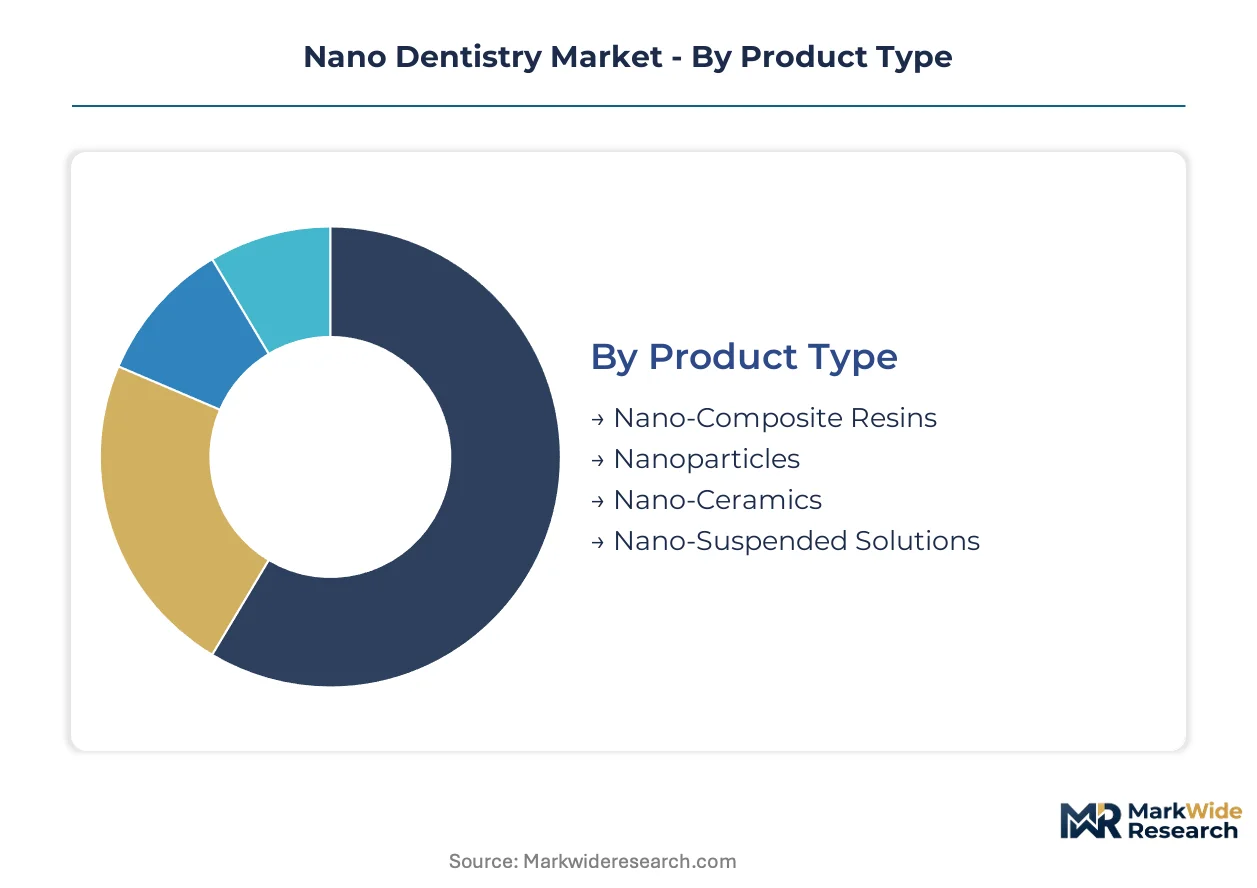
Segmentation in nano dentistry reveals how material science specialization and clinical workflow integration determine competitive positioning. Product categories cluster around manufacturing scale and regulatory pathway complexity, while application and technology segments reflect diverging investment priorities across preventive versus restorative care models.
Product Type:
Supply concentration for engineered nanomaterials tilts toward European and Asian chemical processors with REACH-registered precursor capabilities.
- Nano-Composite Resins:Silica and zirconia nanoparticles dispersed in photopolymerizable resin matrices deliver wear resistance exceeding conventional composites. Dental clinics in Texas and Florida metropolitan corridors drive procurement volume through consolidated DSO purchasing agreements.
- Nanoparticles:Discrete hydroxyapatite or silver nanoparticles serve as additives for antimicrobial and remineralization applications. German and Swiss formulators dominate sol-gel synthesis capacity, constraining supply elasticity for North American compounders.
- Nano-Ceramics:Yttria-stabilized zirconia and alumina nanopowders feed CAD/CAM block production and implant coating applications.
- Nano-Suspended Solutions:Colloidal dispersions for topical fluoride delivery and enamel remineralization target preventive care reimbursement pathways in European dental practices.
Nano-composite resins absorb the bulk of installed capacity; nano-suspended solutions are expanding most quickly.
Application:
Cost tier stratification separates premium implantology from commoditized preventive formulations, with reimbursement differentials determining margin capture.
- Restorative Dentistry:Direct and indirect restorations utilizing nano-filled composites and ceramic hybrids account for procedural volume concentration. FDA 510(k) clearance pathways govern device entry, with unpredictable timelines compressing effective commercialization windows for novel particle architectures.
- Preventive Care:Nano-fluoride varnishes and antimicrobial rinses target caries inhibition and biofilm management. European practices in Germany and Switzerland lead adoption as statutory reimbursement frameworks expand coverage for prophylactic nano-interventions.
- Orthodontics:Nano-coated brackets and archwires reduce friction and accelerate treatment mechanics.
- Periodontics:Tissue-engineered scaffolds and localized drug delivery systems address alveolar bone regeneration.
Restorative dentistry commands dominant revenue share; periodontics demonstrates steepest expansion trajectory.
Technology:
Volume concentration in chairside fabrication is displacing traditional laboratory workflows, compressing turnaround times from weeks to hours.
- CAD/CAM Systems:Computer-aided design and milling of nano-ceramic blocks enables same-day crown and veneer production. United States multi-location dental service organizations demand seamless integration with existing chairside investments, consolidating supplier relationships around validated block compatibility.
- Bioprinting:Extrusion-based and stereolithographic fabrication of cell-laden constructs advances periodontal tissue engineering. Switzerland and Germany host early clinical validation cohorts for alveolar bone regeneration scaffolds.
- Laser Technology:Hard and soft tissue applications leverage photothermal effects for caries removal and periodontal therapy.
- Ultrasonic Treatment:Piezoelectric devices enhance scaling efficiency and nanoparticle dispersion in therapeutic formulations.
CAD/CAM systems anchor current installed base; bioprinting is gaining share fastest.
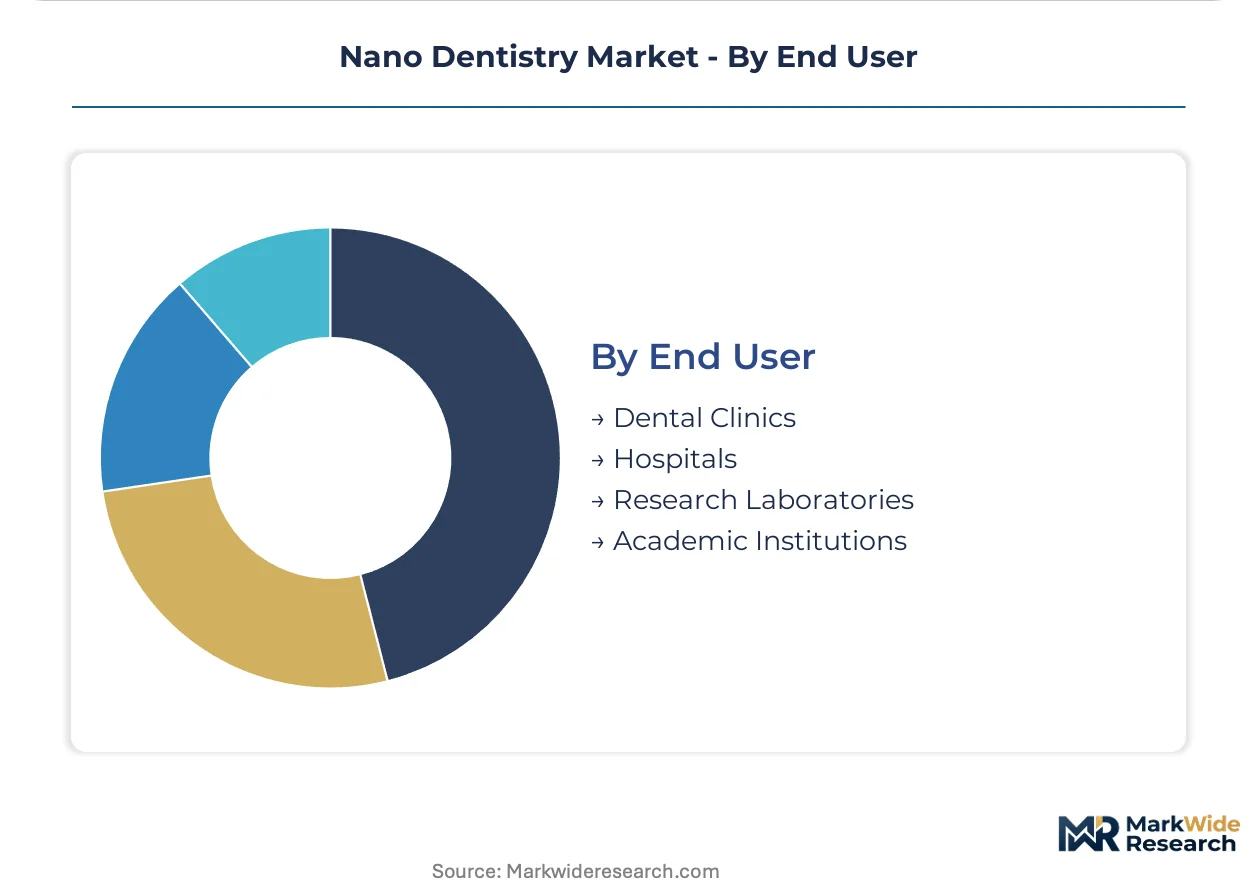
End User:
Customer type segmentation reflects diverging procurement authority, with consolidated DSOs extracting volume discounts unavailable to independent practitioners.
- Dental Clinics:Private and group practices represent primary demand concentration for chairside restorative materials and preventive formulations. Metropolitan consolidation in Texas and Florida corridors accelerates centralized purchasing standardization.
- Hospitals:Academic medical centers and community hospitals handle complex oral surgery and trauma reconstruction requiring implant-grade nano-ceramics.
- Research Laboratories:Preclinical and translational facilities drive demand for experimental nanoparticle formulations and bioprinting platforms.
- Academic Institutions:Dental schools integrate nano-material curricula and clinical training, generating captive demand for educational product lines.
Dental clinics absorb the bulk of installed capacity; research laboratories are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sol-gel synthesis capacity clusters in Swiss and German chemical corridors anchor European nano-ceramic precursor supply. DSO procurement centralization in Texas and Florida metropolitan areas drives North American demand concentration for chairside restorative materials.
United States
FDA 510(k) clearance pathways govern nanomaterial device entry, with unpredictable timelines compressing commercialization windows for novel particle architectures. Multi-location dental service organizations in Texas and Florida metropolitan corridors extract volume discounts through consolidated procurement agreements. Dallas-based DSOs standardize nano-composite formulations across chairside CAD/CAM investments.
Germany
EMA's evolving nano-specific guidance under EU MDR accelerates clinical trial investment for permanent implantable dental products. REACH registration requirements for nanoparticle raw materials elevate compliance costs for imported nano-ceramic powders. Stuttgart and Munich host precision milling partnerships securing CAD/CAM system integration for premium implant manufacturers.
Switzerland
Swissmedic's parallel regulatory pathway attracts German manufacturers relocating milling operations to circumvent REACH constraints. Basel and Zurich research clusters concentrate interdisciplinary expertise spanning colloidal chemistry, polymer science, and dental biomaterials. Early clinical validation cohorts for bioprinted periodontal scaffolds operate from Swiss university hospitals.
Japan
METI nanomaterial safety standards align with PMDA's nano-device pathway, creating regulatory bridges for East Asian market entry. Tokyo and Osaka dental schools integrate nano-material curricula generating captive demand for educational product lines. Japanese implant manufacturers adopt nano-hydroxyapatite surface coatings to differentiate premium screw designs.
China
NMPA governs nanomaterial medical device registration with evolving classification frameworks for dental implants. Shanghai and Shenzhen chemical processors expand sol-gel synthesis capacity for nano-ceramic precursors serving domestic formulators. Local manufacturers develop cost-optimized nano-composite resins targeting price-sensitive dental clinic segments.
Nano Dentistry Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers scale sol-gel synthesis and mechanochemical milling operations to serve DSO procurement commitments. The vendor base organizes around three strategic archetypes: Swiss-German precision formulators with captive R&D facilities, diversified orthopedic-to-dental technology transfer specialists, and Asian chemical processors supplying REACH-registered nano-ceramic precursors. M&A activity concentrates on CAD/CAM block compatibility validation, while strategic partnerships secure bioprinting platform access for periodontal scaffold development.
Among diversified dental technology conglomerates, DENTSPLY Sirona and Danaher Corporation exemplify scale-driven archetypes with broad restorative portfolio coverage. Swiss precision specialists Institut Straumann and Zimmer Biomet occupy positions within the premium implantology tier, leveraging surface nanotopography expertise from adjacent orthopedic applications. German-Japanese materials science hybrids including Heraeus Kulzer and 3M represent technology-transfer archetypes applying industrial nanoparticle dispersion capabilities to dental resin matrices.
| Leading Market Players |
|---|
| DENTSPLY Sirona |
| Institut Straumann |
| Zimmer Biomet |
| Ivoclar Vivadent |
| aap Implantate AG |
| Heraeus Kulzer |
| BioHorizons IPH |
| 3M |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Zirconia nanopowder spot indices in Asian chemical markets cascade through nano-composite resin pricing tiers, compressing margins for European formulators dependent on REACH-registered imports while DSO volume commitments in Texas and Florida corridors sustain premium tier stability.
Pricing Analysis
Warranty-bundled CAD/CAM block compatibility guarantees separate premium nano-ceramic suppliers from unbundled commodity resin vendors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence between FDA-cleared implant coatings and conventional restorative formulations. Cost compression in economy-tier nano-composites is intensifying because Asian manufacturers are scaling sol-gel synthesis capacity for domestic dental clinic segments. Pediatric and geriatric practices exhibit highest price sensitivity due to glass ionomer reimbursement advantages, while multi-location DSOs extract volume discounts that insulate premium tier pricing.
Supply Chain Analysis
REACH registration and Swissmedic parallel pathway qualifications gate European supply participation, constraining nano-ceramic precursor sourcing to German, Swiss, and select Asian chemical processors. Mechanochemical milling equipment and yttria-stabilized zirconia feedstock draw from Japanese and South Korean precision manufacturing clusters. Single-source vulnerability concentrates in Asian nano-ceramic powder production, where tariff exposure on REACH-registered imports elevates compliance costs for North American compounders. Distribution runs through dental laboratory intermediaries for CAD/CAM blocks, while direct-to-clinic models emerge for preventive nano-suspension formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanochemical milling capacity scarcity props nano-composite resin pricing, creating supply-constrained conditions that favor incumbents with captive synthesis operations.
For Market Incumbents: Extend formulation control through backward integration into sol-gel precursor synthesis in Swiss chemical corridors, countering REACH registration cost pressures. Anchor CAD/CAM block compatibility validation against chairside milling investments by Texas and Florida DSOs to defend against Asian cost-optimized entrants. For New Entrants and Emerging Players: Bioprinted periodontal scaffold platforms offer technology-first wedge opportunities beyond commoditized restoration, with Switzerland and Germany clinical validation cohorts providing regulatory credibility pathway. Target European preventive care reimbursement expansion for nano-fluoride suspensions, leveraging direct-to-clinic subscription models that bypass laboratory intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor Swiss-German precision formulators with captive R&D facilities and validated CAD/CAM integration, as REACH compliance costs pressure smaller European compounders. Monitor FDA 510(k) nanotechnology case-by-case review timeline compression as inflection signal for patent life extension and commercialization window expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | German manufacturers relocating milling to Switzerland circumvent REACH constraints and secure formulation control. |
| Bioprinting Platform Partnership | Swiss university hospital clinical validation cohorts accelerate periodontal scaffold regulatory credibility. |
| CAD/CAM Block Compatibility Validation | Texas and Florida DSO procurement centralization demands seamless chairside milling integration. |
| Direct-to-Clinic Distribution Model | European preventive care practices bypass laboratory intermediaries for nano-fluoride margin capture. |
| Dual Regulatory Pathway Registration | Japan METI alignment with PMDA creates bridge for simultaneous East Asian market entry. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning dental material formulators, DSO procurement directors, CAD/CAM system engineers, and REACH compliance specialists. FDA 510(k) clearance databases, EMA nano-specific guidance documents, Swissmedic parallel pathway records, and German chemical industry association reports supplied validation benchmarks. Bottom-up nano-composite resin volume estimates triangulated against top-down dental restoration procedure counts across the analysis window.
Granularity-level modeling applied product type splits at the nanoparticle dispersion technology level, application segments at the reimbursement pathway tier, and end-user categories at the procurement authority cluster. CAGRs derived from procedure volume elasticity against nano-material price indices, with segmentation dimensions including sol-gel versus mechanochemical synthesis routes, chairside versus laboratory fabrication workflows, and statutory versus private reimbursement coverage patterns.
Several conditions sit outside the modeled scope, including speculative bioprinting regulatory approvals, unforeseen REACH nanoparticle registration amendments, and macroeconomic shocks to dental service organization consolidation financing. Forecasts reflect assumptions about DSO procurement standardization velocity and bioprinting clinical validation progression. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Asia Pacific Dental Market
Dental Devices
North America Dental Lab Market
Dental Devices
Dental Needle Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Europe Dental Lab Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Dental Caries Market
Dental Devices
Global Dental Burs Market
Dental Devices
Periodontal Scalers and Curettes Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Splints Market
Dental Devices
Lights for Dental Healthcare Market
Dental Devices
Global Periodontal Market
Dental Devices
Dental Air Abrasion Market