
 Global Dental Burs Market | 2026-2036
Global Dental Burs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Burs Market Foresight
Digital dentistry integration is fragmenting traditional bur procurement channels as CAD/CAM workflows and 3D-printed surgical guides alter chairside material requirements. Dentsply Sirona, Inc. leverages its end-to-end digital ecosystem to bundle consumable sales with equipment leases. Komet Dental anchors European manufacturing with precision-ground carbide geometries for high-speed handpieces. MANI, Inc. competes on cost-efficient diamond plating for Asian dental clinic networks.
Dental burs are rotary cutting instruments, typically manufactured from tungsten carbide, diamond grit, or ceramic composites, with shank diameters standardized at 1.6 mm or 2.35 mm to fit ISO-compliant dental handpieces operating at 200,000–400,000 RPM; they perform hard-tissue cutting, cavity preparation, and prosthetic finishing in restorative and surgical dentistry. Diamond burs command premium positioning in crown preparation due to superior cutting efficiency on enamel and zirconia restorations. Tungsten carbide dominates cavity preparation volumes where cross-cut fissure designs optimize debris clearance. Ceramic burs represent the fastest-growing material category as heat-sensitive procedures and polymer-based restorative work expand in pediatric and cosmetic segments.
FDA 510(k) clearance requirements govern bur biocompatibility and structural integrity for US market entry, while EU MDR and CE marking enforce sterility validation and traceability across European distribution channels. ISO 1797 and ISO 8325 standards define dimensional tolerances and performance testing protocols that manufacturers must satisfy for international commercialization. Stakeholders should monitor regulatory divergence between FDA's device classification approach and EU MDR's enhanced clinical evidence requirements when allocating certification budgets across geographic portfolios.
Market Dynamics
Digital dentistry workflows are fragmenting traditional bur procurement channels as CAD/CAM systems and 3D-printed surgical guides alter chairside material specifications and reorder supplier relationships across dental practices.
Growth Catalysts
- India's National Oral Health Programme:Government dental health initiatives and private clinic chains are scaling instrument procurement volumes in tier-2 and tier-3 cities.
- ISO 7785 handpiece compatibility standards:Tightening material specifications for shank diameters and torque transmission are driving replacement cycles for legacy inventory.
- Zirconia restoration proliferation:CAD/CAM-milled zirconia crowns require diamond grit burs for precision finishing, expanding premium consumable attach rates.
Market Restraints
- Tungsten carbide supply concentration:Powder metallurgy feedstock for carbide blanks concentrates in Chinese and German supplier networks, exposing buyers to input cost volatility.
- FDA 510(k) clearance timelines:Biocompatibility and structural integrity testing for US market entry extends certification cycles by 12-18 months for novel geometries.
- Ceramic composite brittleness:Fracture resistance limitations in high-torque handpiece applications restrict ceramic burs to low-speed finishing procedures.
Strategic Opportunities
- Brazil's underserved interior markets:ANVISA regulatory harmonization with ISO standards enables streamlined entry into state-funded dental expansion programs.
- Polymer-based restorative convergence:Heat-sensitive pediatric and cosmetic procedures are creating demand for ceramic bur alternatives to carbide thermal transfer.
- Direct-to-clinic e-procurement platforms:Digital marketplaces are disintermediating traditional dental distributor networks in Southeast Asian clinic chains.
Industry Challenges
- Precision grinding technician scarcity:Carbide flute geometry expertise concentrates in aging European and Japanese workforces with limited apprenticeship pipelines.
- Legacy handpiece integration friction:ISO 1797 dimensional tolerances for new bur designs must accommodate installed bases of non-compliant vintage equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Burs Market |
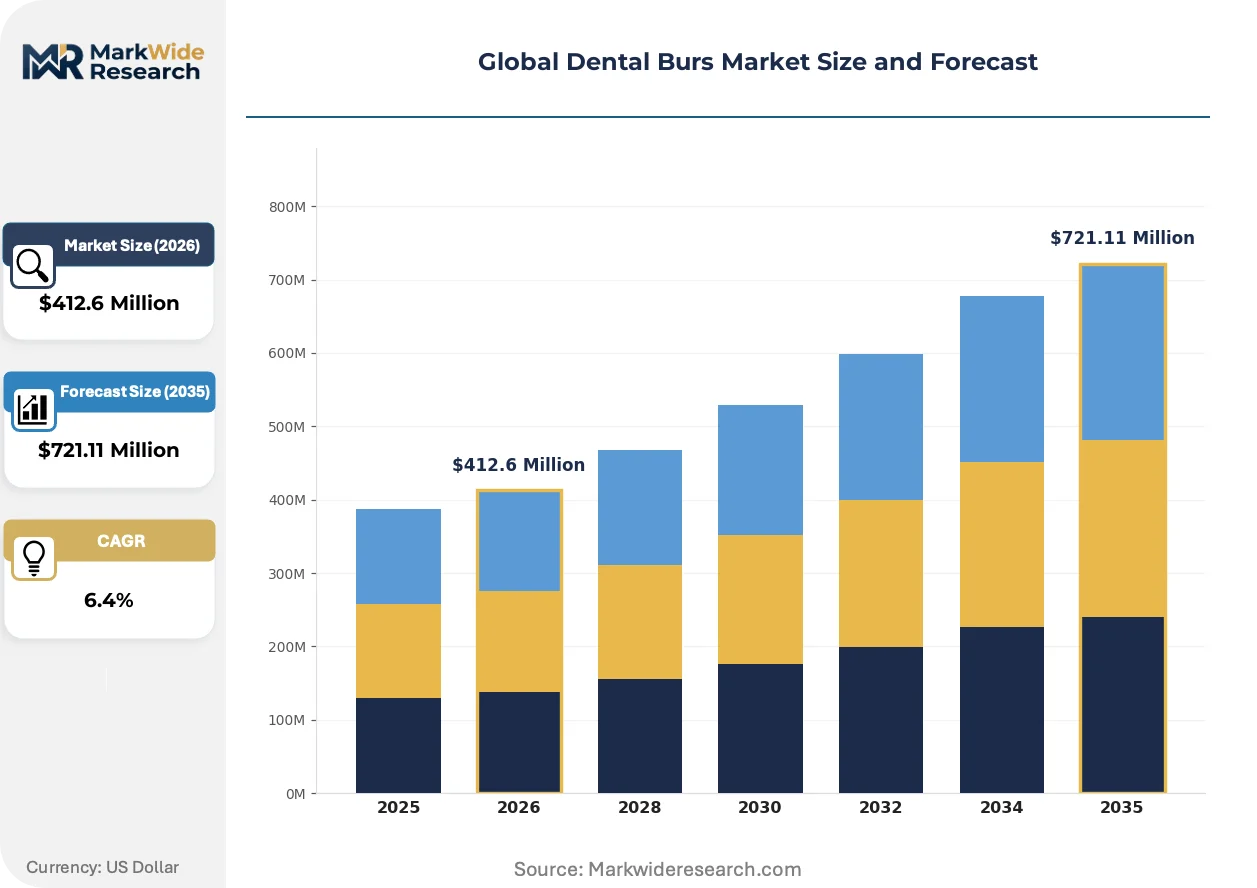
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $721.11 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tungsten Carbide, Steel, Diamond, Ceramic, Composite Shape: Round, Pear, Flame, Needle, Tapered Application: Cavity Preparation, Crown Preparation, Endodontics, Orthodontics, Prosthodontics End User: Dental Clinics, Dental Laboratories, Academic Institutions, Mobile Dental Units |
| Companies Covered | Dentsply Sirona, Inc., Kerr Corporation, Komet Dental, MANI, Inc., COLTENE Holding AG, Brasseler USA, Prima Dental Group, Shofu Dental GmbH, Diatech Dental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Burs Market Shifts & Advancements
Chairside digital workflows are reordering material requirements and supplier relationships as real-time milling and printing compress the traditional lab-to-practice value chain.
Multi-layer diamond plating technology is digitizing crown preparation efficiency by enabling single-bur completion of zirconia and lithium disilicate restorations. High-volume cosmetic practices in South Korea and the UAE are adopting these geometries to reduce chair time per unit. The technology is digitizing procedure economics by collapsing the instrument count per case and simplifying inventory management.
EU MDR enhanced clinical evidence requirements are extending sterility validation and traceability obligations across European distribution channels. Manufacturers must now maintain post-market surveillance systems and unique device identifiers for diamond and carbide rotary instruments. German and Swiss precision manufacturers are responding by consolidating CE marking responsibilities in-house rather than relying on notified body intermediation.
Subscription-based consumable bundling is displacing spot purchasing in corporate dental chains as equipment lessors integrate bur replenishment into monthly service agreements. DSOs in the United States and Spain are negotiating multi-year supply contracts tied to CAD/CAM system utilization rates. This shift is most visible in markets where private equity consolidation has created multi-site procurement leverage.
Global Dental Burs Market Segmentation
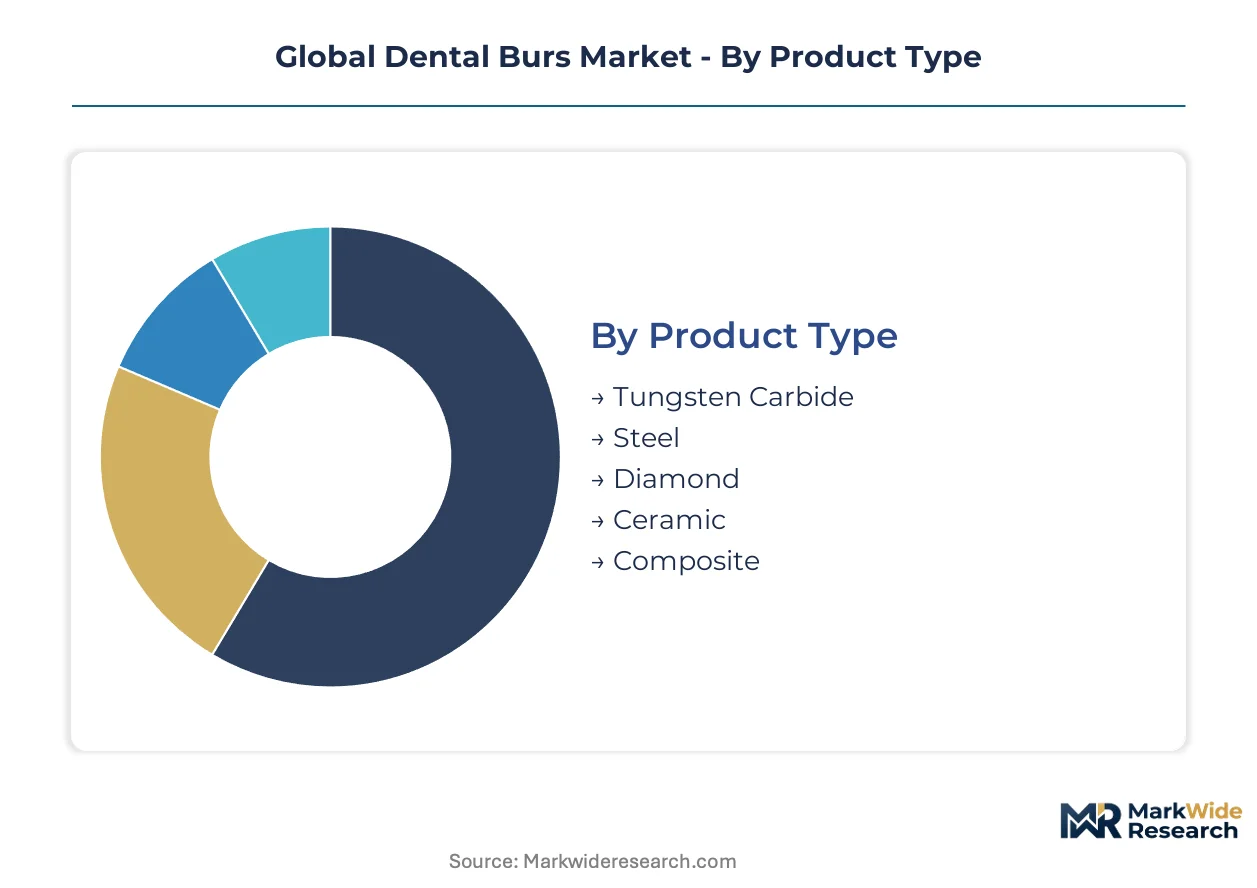
Dental burs serve distinct functional niches across restorative workflows, with material composition, geometry, and end-use environment each driving procurement specifications. Segmentation reveals how premium diamond plating for zirconia finishing commands different pricing logic than bulk carbide purchases for high-volume cavity preparation.
Product Type:
Material composition determines thermal behavior, cutting efficiency, and replacement frequency across handpiece applications.
- Tungsten Carbide:Cross-cut fissure geometries optimize debris clearance in high-speed cavity preparation. Indian dental clinic chains in tier-2 cities are scaling bulk procurement of carbide round burs under government oral health program tenders.
- Diamond:Multi-layer grit plating bonded to stainless steel shanks delivers precision cutting on enamel and zirconia restorations. South Korean cosmetic practices are driving attach rates for single-bur crown completion systems to compress chair time.
- Steel:Legacy low-speed applications in provisional crown trimming and acrylic adjustment persist where cost minimization outweighs durability requirements.
- Ceramic:Zirconia-based composites minimize thermal transfer in pediatric and polymer-based restorative work where heat sensitivity constrains carbide or diamond use.
- Composite:Hybrid resin-ceramic matrices target specialized finishing procedures in aesthetic dentistry with controlled abrasion characteristics.
Tungsten carbide commands the established base across high-volume restorative markets. The steepest expansion runs through ceramic formulations as heat-sensitive procedure volumes climb.
Shape:
Geometric profiles align with specific tooth surface contours and access requirements in operative dentistry.
- Round:Spherical cutting heads excel in initial caries removal and cavity entry with minimal adjacent tooth contact. German precision manufacturers maintain tight dimensional tolerances for ISO 1797 compliance in high-torque handpiece interfaces.
- Pear:Converging sidewalls with rounded apex suit Class II proximal box preparations and occlusal anatomy refinement. UAE-based cosmetic dental groups specify pear geometries for premium crown preparation workflows.
- Flame:Elongated tapering profiles access subgingival margins and interproximal spaces in periodontal and prosthodontic procedures.
- Needle:Fine cylindrical points enable pit and fissure exploration with minimal enamel sacrifice in preventive resin restorations.
- Tapered:Conical geometries with defined cutting angles standardize axial wall reduction for full-coverage crown preparations across CAD/CAM milling workflows.
Round burs retain the highest shipment volumes across general practice procurement. Pear configurations are gaining share fastest in cosmetic-focused clinic networks.
Application:
Clinical use case determines rotational speed requirements, cutting load, and sterility protocols.
- Cavity Preparation:High-speed carbide and diamond burs remove infected dentin and shape retention form for amalgam and composite restorations. Brazil's ANVISA-regulated state dental programs are expanding instrument kits for basic operative care in interior municipalities.
- Crown Preparation:Precision taper and shoulder formation for fixed prosthodontics demands multi-grit diamond sequences. Spanish DSOs are bundling crown preparation bur sets with CAD/CAM system leases to standardize margin quality across clinic networks.
- Endodontics:Specialized gates-glidden and orifice-shaping geometries facilitate root canal access and coronal flaring with controlled cutting depth.
- Orthodontics:Low-speed finishing burs debond adhesive residue and adjust bracket positioning without enamel damage.
- Prosthodontics:Laboratory-grade carbide cutters trim die stone, adjust metal frameworks, and finish acrylic denture bases on dental lathes.
Cavity preparation anchors procurement volume in emerging market expansion. Crown preparation is expanding most quickly as CAD/CAM restoration adoption accelerates.
End User:
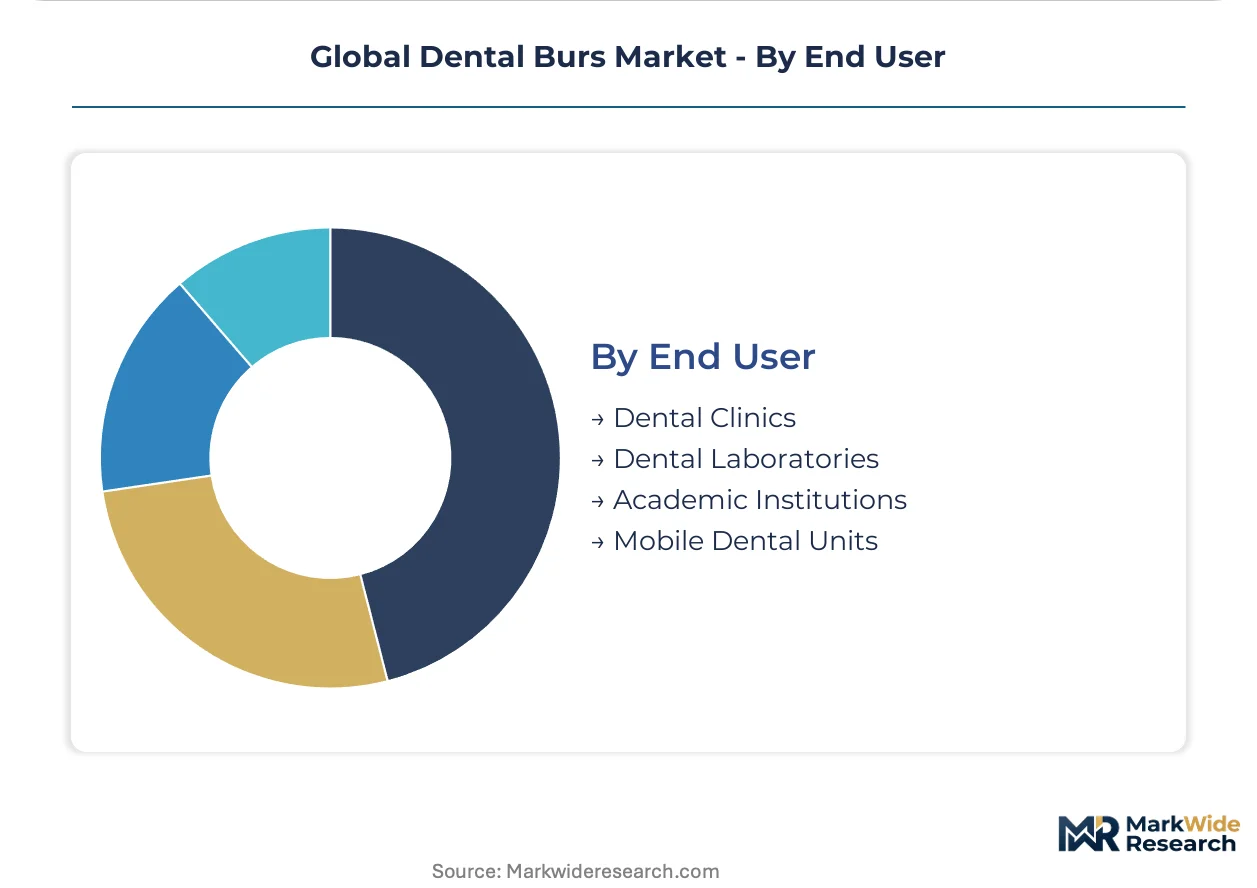
Procurement scale, sterility infrastructure, and reimbursement environment differentiate customer segments.
- Dental Clinics:Chairside single-patient-use disposables dominate in infection-controlled private practice settings. India's National Oral Health Programme is channeling bulk instrument procurement through accredited clinic chains in tier-3 cities.
- Dental Laboratories:Reusable carbide cutters and grinding stones for model work and prosthesis finishing operate on multi-year replacement cycles with lower per-unit sensitivity.
- Academic Institutions:Training programs in Japan and South Korea require standardized bur kits for preclinical simulation labs with high student throughput and consumable budget constraints.
- Mobile Dental Units:Field-based screening and basic restorative services in rural India and Brazil's interior rely on compact, sterilizable instrument sets with minimal equipment dependency.
Dental clinics command the established base through high-frequency disposable consumption. Mobile dental units are climbing the fastest as government outreach programs scale rural access infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from German and Swiss precision manufacturers balance against import dependence for carbide feedstock and diamond grit across Asian manufacturing hubs. The United States maintains a net importer position for finished rotary instruments while exporting specialized carbide blanks to European grinding facilities. India's government procurement programs are redirecting trade flows toward domestic assembly partnerships with Japanese and German technology licensors.
United States
FDA 510(k) clearance requirements govern biocompatibility testing for rotary cutting instruments entering the US market. Private equity-backed dental service organizations in Texas and Florida are consolidating procurement leverage across multi-site clinic networks. The FDA's device classification approach for handpiece-compatible instruments creates extended certification timelines for novel geometries.
Germany
EU MDR enhanced clinical evidence requirements enforce sterility validation and unique device identifiers across distribution channels. Precision grinding expertise concentrates in Solingen and Tuttlingen industrial clusters where carbide flute geometry knowledge resides in specialized workforces. German manufacturers are consolidating CE marking responsibilities in-house rather than relying on notified body intermediation.
India
The National Oral Health Programme channels bulk instrument procurement through accredited clinic chains in tier-2 and tier-3 cities. Central Drugs Standard Control Organization regulations align with ISO 1797 dimensional tolerance standards for handpiece compatibility. Manufacturing partnerships in Gujarat and Maharashtra are scaling domestic assembly of diamond-plated instruments under technology transfer agreements with Japanese licensors.
Japan
Ministry of Health, Labour and Welfare pharmaceutical and medical device regulations govern biocompatibility standards for rotary instruments. Precision carbide blank production concentrates in Aichi Prefecture industrial corridors serving domestic and export markets. Japanese manufacturers supply plating technology and quality control systems to Indian assembly joint ventures.
Brazil
ANVISA regulatory harmonization with ISO standards enables streamlined market entry for instrument manufacturers. State-funded dental expansion programs in interior municipalities are scaling basic operative care infrastructure. São Paulo-based distributor networks are consolidating procurement for clinic chains across the Southeast region.
Global Dental Burs Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers. Precision grinding expertise for carbide geometries concentrates in German and Japanese manufacturing clusters with limited workforce replenishment pipelines. Strategic archetypes include integrated dental equipment-consumable bundlers, specialized carbide precision manufacturers, and cost-optimized diamond plating specialists. Dominant competitive moves center on subscription-based consumable contracts tied to equipment leases and backward integration into carbide blank production.
Among integrated equipment-consumable bundlers, Dentsply Sirona, Inc. exemplifies the end-to-end ecosystem approach where rotary instrument sales attach to digital workflow hardware. Komet Dental occupies a position within the European precision manufacturing tier, representing specialized carbide geometry capabilities for high-speed handpiece applications. MANI, Inc. sits within the Asia-Pacific cost-optimization archetype, anchoring diamond plating efficiency for high-volume clinic network procurement.
| Leading Market Players |
|---|
| Dentsply Sirona, Inc. |
| Kerr Corporation |
| Komet Dental |
| MANI, Inc. |
| COLTENE Holding AG |
| Brasseler USA |
| Prima Dental Group |
| Shofu Dental GmbH |
| Diatech Dental AG |
| Others |
Supply & Pricing Matrix
Freight corridors connecting Shanghai Port to Hamburg anchor cost dynamics across the dental burs trade, with container rate volatility amplifying price differentiation between German precision manufacturers and Asian plating specialists while compressing margins for mid-tier carbide distributors caught between feedstock concentration and clinic procurement consolidation.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium diamond plating, standard carbide geometries, and economy steel alternatives. Price differentiation hinges on ISO 13485 certification grade and volume scale, with Brazilian state dental programs extracting maximum discount leverage through multi-year tenders. Pricing pressure intensifies as Indian domestic assembly partnerships undercut Japanese import premiums. Corporate dental chains exhibit lowest price sensitivity due to bundled equipment leases, while independent tier-3 clinics drive hardest bargain on spot carbide purchases.
Supply Chain Analysis
Contract manufacturing capacity concentrates in Solingen industrial clusters, Aichi Prefecture precision corridors, and Gujarat assembly zones under technology transfer arrangements. Tungsten carbide powder metallurgy feeds from Chinese and German supplier networks, diamond grit plating chemistry hinges on Japanese process licensing, and stainless steel shank stock draws from Indian mill capacity. Single-source vulnerability in carbide blank supply exposes manufacturers to input cost volatility. Distribution runs through consolidated dental distributor networks in developed markets and direct-to-clinic e-procurement platforms in Southeast Asian expansion zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR enhanced clinical evidence requirements constitute a regulatory inflection compressing vendor viability windows and rewarding consolidated certification capabilities across the dental burs competitive set.
For Market Incumbents: Entrench precision grinding expertise through captive apprenticeship pipelines in Solingen and Tuttlingen clusters before workforce attrition erodes flute geometry capabilities. Secure backward integration into carbide blank production to insulate margin structures from Chinese feedstock volatility. Prioritize in-house CE marking consolidation to capture regulatory compliance premiums as notified body bottlenecks extend market access timelines for competitors. For New Entrants and Emerging Players: Brazil's interior municipalities present the most penetrable geographic white space, where ANVISA harmonization enables streamlined state tender participation without legacy distributor entanglements. Polymer-based restorative procedures in pediatric dentistry offer application entry with lower carbide expertise barriers. Pursue direct-to-clinic e-procurement partnerships with Southeast Asian clinic chains to circumvent entrenched distributor relationships. For Investors and Strategic Acquirers: EU MDR's post-market surveillance obligations reshape the acquisition landscape toward targets with established unique device identifier infrastructure and clinical evidence repositories. Five-to-ten year viability favors precision manufacturers with integrated grinding-plating-certification capabilities over pure-play distributors. Monitor FDA 510(k) clearance velocity as signal for US market access competitiveness among European precision targets.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Consolidation | In-house notified body relationships accelerate EU MDR compliance for German precision manufacturers. |
| Backward Integration into Carbide Blanks | Captive powder metallurgy supply insulates margin structures from Chinese feedstock price volatility. |
| Direct-to-Clinic E-Procurement Launch | Digital marketplace entry disintermediates traditional distributor networks in Indian tier-3 cities. |
| Multi-layer Diamond Plating R&D | Single-bur crown completion technology compresses chair time for South Korean cosmetic practices. |
| Hospital System Partnership | Spanish DSO equipment lease bundling locks in multi-year consumable attach rates across clinic networks. |
Research Methodology
A spread of perspectives from dental equipment procurement managers, precision grinding technicians, GPO contracts administrators, and CAD/CAM workflow specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body registries, CDSCO device approval records, and Indian National Oral Health Programme tender documentation. Bottom-up clinic procurement modeling triangulated against top-down manufacturer shipment estimates.
Demand-supply balance dynamics across material composition segments, geometric profile categories, clinical application workflows, and end-user procurement scales structured the analytical framework throughout the projection horizon. CAGRs derived from segmented volume trajectories weighted by replacement frequency differentials and CAD/CAM adoption curves. Forecast inputs incorporated ISO 7785 handpiece compatibility upgrade cycles and zirconia restoration proliferation rates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese carbide feedstock suppliers or accelerated FDA clearance pathways for novel ceramic geometries would shift outcomes. Quarterly review of EU MDR notified body queue lengths and Indian domestic assembly capacity announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Implant Motors Market
Dental Devices
Dental Radiometer Market
Dental Devices
Dental Calipers Market
Dental Devices
Dental Diagnostic and Surgical Market
Dental Devices
Glenoid Fossa Prosthesis Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Dental Implants Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Composite Filling Market
Dental Devices
Dental CAD Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Global Dental Labs Market
Dental Devices
Global Dental Lasers Market