
 Dental Diagnostic and Surgical Market | 2026-2036
Dental Diagnostic and Surgical Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Diagnostic and Surgical Market Outlook
Dental laboratories is pivoting toward chairside manufacturing, pulling capital equipment demand away from centralized production models. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to control workflow software-to-hardware transitions. Straumann Group anchors implantology with precision-milled surgical guides that tie diagnostic imaging to guided surgery protocols. Danaher Corporation competes through diagnostic platform density, bundling intraoral scanners with consumable workflows.
Dental diagnostic and surgical equipment encompasses imaging systems, surgical instruments, and computer-aided fabrication tools designed for oral cavity intervention, typically operating at 60-90 kVp for intraoral radiography and sub-millimeter voxel resolution for cone beam tomography. Its primary purpose is to enable accurate pathology detection, treatment planning, and minimally invasive surgical execution across dental specialties. Cone beam CT and 3D imaging command premium positioning as orthodontists and maxillofacial surgeons require sub-millimeter anatomical fidelity for implant placement and airway analysis. Digital imaging sustains volume leadership across dentist offices where retrofit compatibility and lower per-scan cost preserve installed base loyalty.
FDA 510(k) pathways and EU MDR conformity requirements shape product development cycles, with MDR's heightened clinical evidence demands extending certification timelines for cone beam systems and surgical lasers. ISO 13485 quality management and HIPAA data security standards further constrain software-integrated imaging platforms that store patient records. Stakeholders must monitor how FDA's evolving AI-enabled device framework reclassifies radiological decision-support tools and whether EU MDR notified body capacity bottlenecks persist for novel surgical instrument categories.
Market Dynamics
Digital workflow integration is compressing diagnostic-to-surgical timelines as chairside CAD/CAM systems displace laboratory-centric production models, forcing capital reallocation across dental service organizations and independent practices.
Growth Catalysts
- FDA AI-enabled device framework:Accelerated 510(k) clearance pathways for radiological decision-support tools reduce product development cycles for imaging software developers targeting US dental clinics.
- Orthodontic digital treatment planning:Sub-millimeter cone beam CT fidelity requirements from aligner therapy protocols drive replacement demand for legacy panoramic systems in orthodontic practices.
- Germany KBA-aligned quality protocols:Dense dental clinic networks and stringent medical device certification standards create concentrated procurement clusters for precision-milled surgical guides.
Market Restraints
- Zirconium oxide supply concentration:Raw material sourcing for CAD/CAM milling blocks depends on limited high-purity ceramic suppliers, exposing manufacturers to input cost volatility.
- EU MDR notified body capacity:Heightened clinical evidence demands for cone beam systems and surgical lasers extend certification timelines, delaying product launches across European markets.
- Intraoral scanner substitution:Direct digital impression capture threatens traditional alginate and PVS material volumes, compressing consumable revenue streams for distributors.
Strategic Opportunities
- Brazil ANVISA regulatory alignment:Underpenetrated digital imaging adoption in Latin America's largest dental market creates whitespace for cone beam CT vendors establishing local service infrastructure.
- AI-radiology convergence:Machine learning algorithms paired with intraoral sensors enable automated caries detection, opening subscription revenue models for software-integrated hardware platforms.
- Direct-to-clinic distribution:E-commerce procurement portals bypass traditional dental dealer networks, capturing margin compression benefits for manufacturers with logistics scale.
Industry Challenges
- CAD/CAM technician training deficits:Shortage of digitally fluent dental laboratory professionals constrains chairside manufacturing adoption rates among small-to-mid-sized practices.
- HIPAA data architecture complexity:Cloud-based imaging platforms storing patient records face multi-jurisdictional compliance burdens, lengthening vendor security audit timelines.
- Legacy equipment integration friction:Retrofitting digital workflows into practices with depreciated panoramic units requires costly middleware solutions, slowing upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Diagnostic and Surgical Market |
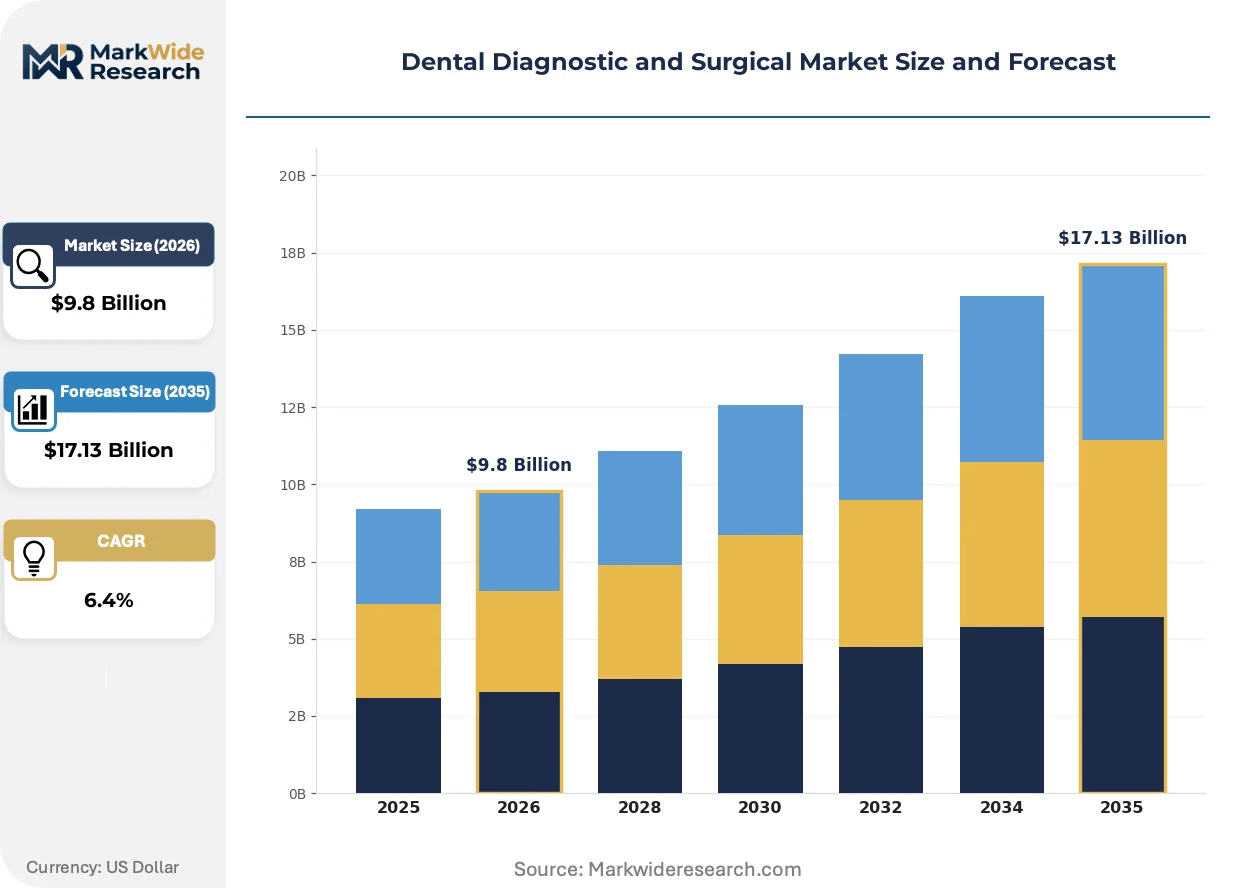
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray Systems, Intraoral Cameras, Cone Beam CT, Surgical Instruments Application: Orthodontics, Periodontics, Endodontics, Maxillofacial Surgery End User: Dentist Offices, Hospitals, Dental Laboratories, Research Institutions Technology: Digital Imaging, 3D Imaging, CAD/CAM, Laser Technology |
| Companies Covered | Dentsply Sirona, Carestream Health, Danaher Corporation, Envista Holdings Corporation, Planmeca, Henry Schein, Straumann Group, 3M Company, Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Diagnostic and Surgical Market Strategic Shifts
Workflow automation and regulatory recalibration are restructuring how diagnostic data translates into surgical execution, with software-hardware integration becoming the primary axis of vendor differentiation.
Intraoral photogrammetry systems capture full-arch implant positions without physical impression materials. Prosthodontists and implantologists in high-volume surgical centers adopt these systems to compress appointment sequences. The technology is expanding into guided surgery protocols by enabling real-time surgical guide fabrication without laboratory intermediation.
EU MDR Article 10 clinical evidence requirements now mandate post-market surveillance for Class IIa and above dental imaging equipment. Manufacturers must maintain systematic data collection on device safety and performance, increasing regulatory affairs staffing levels. Cone beam CT vendors with existing European installed bases face retrospective clinical evaluation obligations that smaller competitors cannot resource.
Subscription-based software licensing displaces perpetual purchase models for treatment planning platforms. Dental service organizations negotiating enterprise agreements extract per-seat pricing concessions that independent practices cannot match. This concentration is most visible in US metropolitan markets where DSOs control 25-30% of chair positions and demand unified imaging ecosystems across acquired practices.
Dental Diagnostic and Surgical Market Segmentation
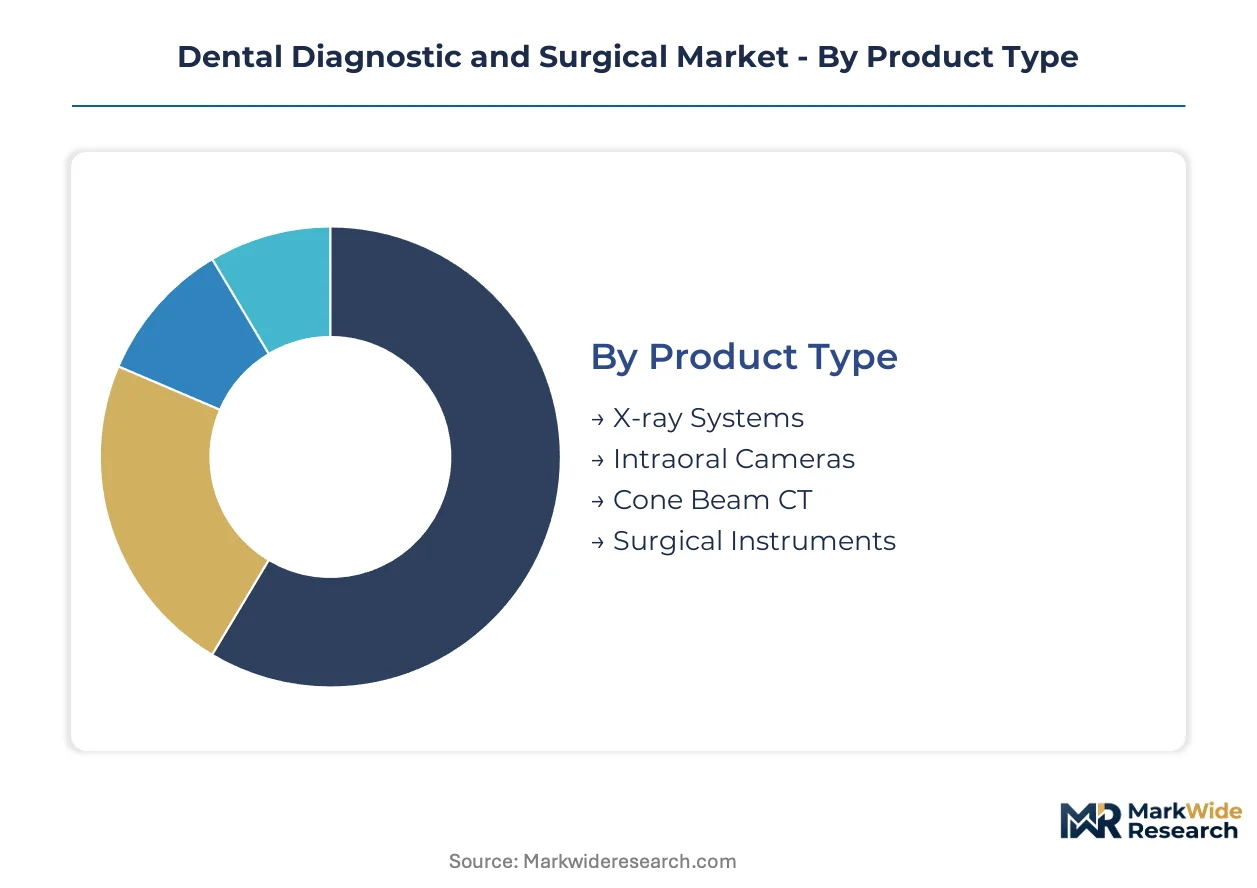
Segmentation in dental diagnostics and surgical equipment reveals how capital flows concentrate around imaging fidelity requirements and workflow integration points. Equipment specifications vary sharply across orthodontic aligner planning, implantology, and chairside restoration protocols.
Product Type:
Supply concentration for high-precision imaging components favors vendors with captive sensor fabrication and tube head manufacturing capabilities.
- Cone Beam CT:Sub-millimeter voxel resolution systems dominate orthodontic and maxillofacial surgical planning. Demand concentrates in Germany where KBA-aligned quality protocols and dense specialist clinic networks drive replacement of legacy panoramic units.
- X-ray Systems:Intraoral radiography operating at 60-90 kVp retains volume leadership through retrofit compatibility and lower per-scan operational costs. Dentist offices in the US preserve installed base loyalty as FDA 510(k) pathways streamline upgrade certifications.
- Intraoral Cameras:Direct digital impression capture devices threaten traditional alginate workflows.
- Surgical Instruments:Precision-milled guides and motorized handpieces tie diagnostic imaging to guided surgery protocols.
Today's leader: X-ray Systems. Tomorrow's challenger: Cone Beam CT.
Application:
Cost tier differentiation separates high-volume aligner therapy from specialized surgical interventions requiring anatomical fidelity.
- Orthodontics:Aligner therapy protocols demand sub-millimeter cone beam CT fidelity for treatment planning software integration. Practices in metropolitan US markets where dental service organizations control 25-30% of chair positions negotiate enterprise imaging ecosystem agreements.
- Maxillofacial Surgery:Airway analysis and implant placement require sub-millimeter anatomical mapping. German maxillofacial centers drive concentrated procurement for precision-milled surgical guides under stringent medical device certification standards.
- Periodontics:Soft tissue management and bone regeneration planning utilize digital periodontal charting.
- Endodontics:Root canal morphology visualization depends on high-resolution intraoral sensors.
Orthodontics captures current volume. Maxillofacial Surgery climbs the fastest on procedural complexity premiums.
End User:
Customer type determines procurement scale, with dental service organizations extracting pricing concessions unavailable to independent practices.
- Dentist Offices:Independent and group practices represent the primary volume channel for intraoral scanners and digital radiography. US metropolitan markets show DSO-driven consolidation demanding unified imaging ecosystems across acquired locations.
- Dental Laboratories:Centralized production facilities face capital reallocation pressure as chairside CAD/CAM systems displace laboratory-centric workflows. Technician training deficits constrain adoption among small-to-mid-sized practices.
- Hospitals:Academic medical centers and trauma units require cone beam CT for complex craniofacial reconstruction.
- Research Institutions:Clinical evidence generation for EU MDR post-market surveillance obligations drives imaging equipment procurement.
Dentist Offices anchor current demand. Dental Laboratories face structural compression from chairside manufacturing adoption.
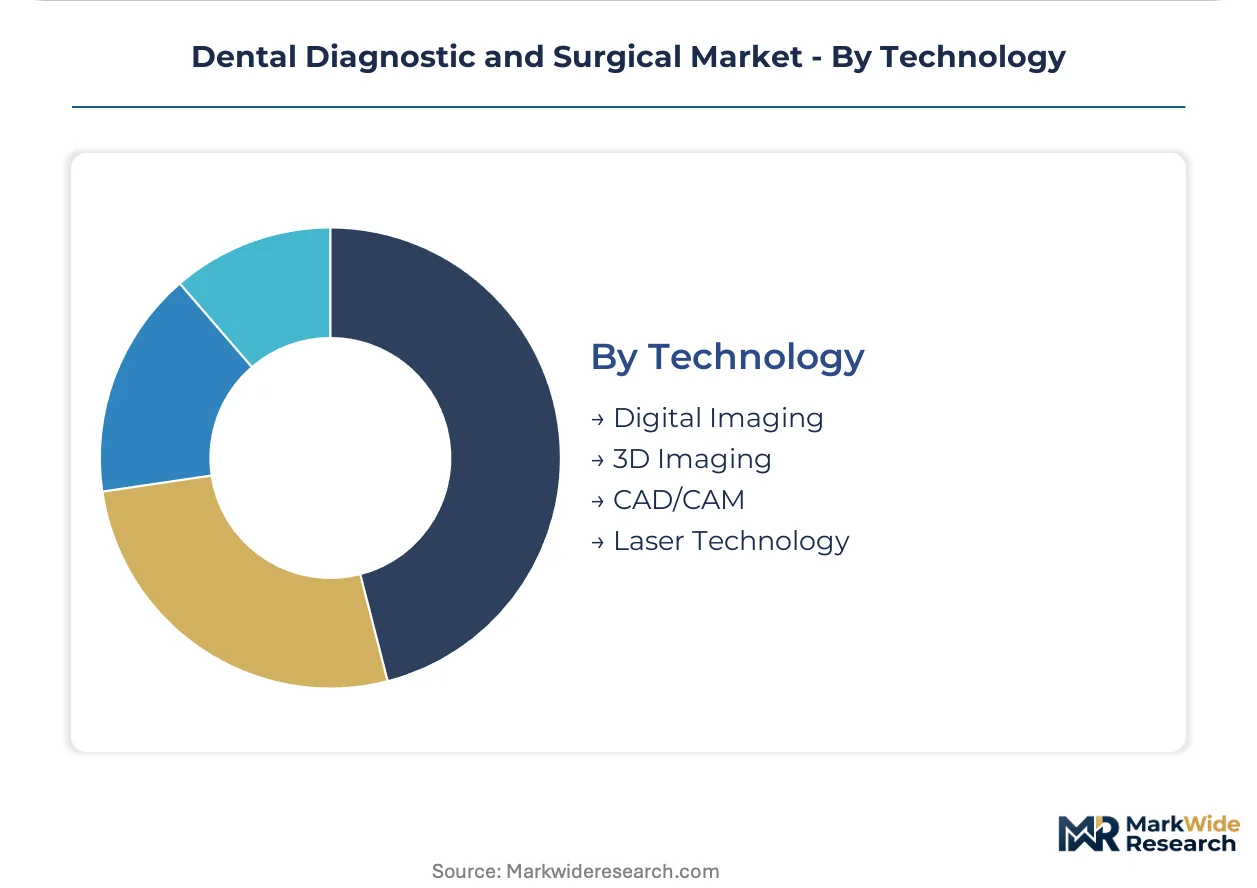
Technology:
Margin structures favor integrated software-hardware platforms over standalone device sales.
- Digital Imaging:Intraoral sensors and phosphor plate systems sustain volume leadership through lower per-scan costs and HIPAA-compliant cloud architecture. Retrofit compatibility with depreciated panoramic units slows upgrade cycles in cost-constrained practices.
- CAD/CAM:Chairside milling and 3D printing systems compress diagnostic-to-restoration timelines. Zirconium oxide supply concentration for milling blocks exposes manufacturers to input cost volatility from limited high-purity ceramic suppliers.
- 3D Imaging:Cone beam CT and intraoral photogrammetry enable full-arch implant positioning without physical impression materials.
- Laser Technology:Soft tissue surgical lasers face extended EU MDR certification timelines from heightened clinical evidence demands.
Digital Imaging holds installed base dominance. CAD/CAM gains share fastest on workflow integration premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly to jurisdictions with streamlined medical device certification timelines. Cost-of-compliance gaps between FDA 510(k) pathways and EU MDR obligations drive capital toward North American and select Asian markets.
United States
Orthodontic digital treatment planning and dental service organization consolidation fuel imaging equipment procurement. FDA's AI-enabled device framework accelerates clearance pathways for radiological decision-support tools. Metropolitan markets in Texas and Florida show concentrated DSO-driven demand for unified imaging ecosystems.
Germany
KBA-aligned medical device quality protocols and dense specialist clinic networks sustain premium positioning for precision-milled surgical guides. EU MDR Article 10 clinical evidence requirements mandate post-market surveillance for Class IIa imaging equipment. Bavarian dental technology clusters around Munich and Nuremberg anchor precision manufacturing for cone beam CT components.
China
Domestic manufacturing scale and NMPA regulatory harmonization efforts attract foreign joint ventures for intraoral scanner assembly. National healthcare infrastructure investments expand dental clinic networks in tier-2 cities. Yangtze River Delta production bases near Shanghai supply CAD/CAM milling blocks to Southeast Asian markets.
Brazil
Underpenetrated digital imaging adoption in Latin America's largest dental market creates whitespace for cone beam CT vendors. ANVISA regulatory alignment with international standards reduces import friction for US and European equipment manufacturers. São Paulo state concentrates private dental clinic investment and specialist training institutions.
Japan
Aging demographic profiles and universal health coverage sustain replacement demand for digital radiography systems. PMDA streamlined review pathways for software-integrated imaging platforms compress product launch timelines. Osaka-Kobe industrial corridor hosts precision component fabricators serving intraoral sensor manufacturers.
Dental Diagnostic and Surgical Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors bundle hardware, software, and consumable workflows into integrated ecosystems. The market structure concentrates around three to five diversified multinationals controlling imaging-to-surgery platforms, with mid-tier specialists competing on application-specific fidelity. Two strategic archetypes prevail: integrated CAD/CAM ecosystem providers and diagnostic platform bundlers. M&A activity and technology licensing agreements represent the dominant competitive moves, with manufacturers acquiring software capabilities to close workflow gaps.
Within the integrated ecosystem tier, Dentsply Sirona and Straumann Group exemplify vertically consolidated positioning across software-to-hardware transitions. Danaher Corporation occupies a position among diagnostic platform bundlers, leveraging consumable workflow density to anchor intraoral scanner deployments. These three entities represent contrasting approaches to capturing value from digital workflow compression.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Carestream Health |
| Danaher Corporation |
| Envista Holdings Corporation |
| Planmeca |
| Henry Schein |
| Straumann Group |
| 3M Company |
| Ivoclar Vivadent |
| Others |
Value Chain & Pricing Dynamics
Dental service organizations controlling 25-30% of US metropolitan chair positions negotiate enterprise-wide imaging ecosystem contracts that compress channel margins and force manufacturers toward subscription-based software licensing models. This buyer concentration reshapes how equipment vendors structure pricing across hardware, software, and consumable bundles.
Pricing Analysis
Distributor margins of 15-25% on capital equipment face compression as direct-to-clinic e-commerce portals capture procurement volume from traditional dental dealer networks. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI-enabled radiology platforms from basic intraoral sensors and refurbished panoramic units. Cost compression in economy-tier digital radiography intensifies because of intraoral scanner substitution threatening legacy sensor volumes. Independent dentist offices show highest price sensitivity, while German maxillofacial centers under KBA-aligned protocols accept premium positioning for sub-millimeter cone beam CT fidelity.
Supply Chain Analysis
Single-source vulnerability sits with high-purity zirconium oxide suppliers concentrated in Japan and Germany for CAD/CAM milling block production. Tube head fabrication for intraoral radiography draws from German and Japanese precision component clusters, while CMOS sensor wafers feed from Taiwanese semiconductor foundries. Tariff exposure on ceramic raw materials threatens margin stability for chairside milling system manufacturers. Distribution runs through authorized dental equipment dealers with regional service infrastructure, though direct manufacturer-to-clinic logistics partnerships are displacing legacy channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as orthodontic aligner therapy protocols and guided implantology drive replacement demand toward sub-millimeter imaging fidelity specifications.
For Market Incumbents: Cement ecosystem control by acquiring AI-enabled radiology software capabilities to close workflow gaps in diagnostic-to-surgical timelines. Expand captive zirconium oxide sourcing through backward integration into high-purity ceramic suppliers, defending against input cost volatility that threatens CAD/CAM milling block margins. For New Entrants and Emerging Players: Dental service organization procurement committees represent the most accessible channel entry point for unified imaging ecosystem vendors lacking established dealer relationships. Target Brazil's underpenetrated cone beam CT market through ANVISA-aligned regulatory partnerships with local service infrastructure providers, bypassing saturated US and German procurement clusters. For Investors and Strategic Acquirers: Dental technology multinationals with integrated CAD/CAM-to-implantology platforms are the most active acquirer in this space, seeking software capabilities that compress diagnostic-to-restoration workflows. Capability scarcity centers on AI-radiology convergence assets and intraoral photogrammetry patents. Watch FDA's evolving AI-enabled device framework as the signal for reclassification risk that could extend 510(k) timelines for radiological decision-support tools.| Strategic Initiative | Industry Significance |
|---|---|
| FDA AI-Enabled Device Submission | Accelerated 510(k) pathways for radiological decision-support tools reduce product development cycles for imaging software targeting US dental clinics. |
| EU MDR Post-Market Surveillance Investment | Systematic clinical data collection on Class IIa imaging equipment satisfies Article 10 obligations and creates retrospective evaluation barriers for smaller competitors. |
| Direct-to-Clinic Distribution Partnership | E-commerce procurement portals bypass traditional dental dealer networks, capturing margin compression benefits for manufacturers with logistics scale. |
| Chairside CAD/CAM Ecosystem Integration | Software-hardware bundling compresses diagnostic-to-restoration timelines and locks independent practices into proprietary milling block consumables. |
| Brazil ANVISA Regulatory Alignment | Underpenetrated digital imaging adoption in Latin America's largest dental market creates whitespace for cone beam CT vendors establishing local service infrastructure. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental laboratory technicians, orthodontic practice managers, hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR notified body decisions, hospital procurement databases, and dental equipment customs records. Bottom-up equipment shipment estimates triangulated against top-down dental clinic network expansion data across the analysis window.
Segment-weighting approaches applied differential growth assumptions across cone beam CT, intraoral scanners, and CAD/CAM milling systems based on orthodontic aligner therapy penetration rates, dental service organization consolidation trajectories, and EU MDR certification timeline impacts. CAGRs derived from equipment replacement cycle analysis, technology substitution elasticities, and regional regulatory pathway efficiency differentials. Forecast inputs incorporated zirconium oxide supply concentration risk and AI-radiology software adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints, FDA AI device reclassification decisions, and dental service organization acquisition velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Dental Veneers Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
Dental Sealants Market
Dental Devices
Dental Aligners Market
Dental Devices
Dental Floss Market
Dental Devices
Saudi Arabia Dental Devices Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Lights for Dental Healthcare Market
Dental Devices
Single Tooth Implants and Dental Bridges Market
Dental Devices
Malocclusion Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Dental Impression System Market
Dental Devices
Teeth Whitening Pen Market