
 Europe Dental Lab Market | 2026-2036
Europe Dental Lab Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dental Lab Market Foresight
Digital CAD/CAM workflows is reshaping how dental laboratories fabricate crowns, bridges, and implant-supported prostheses across Europe. Straumann Group leverages its integrated scanner-to-milling ecosystem to control high-margin restorative workflows. Dentsply Sirona sustains broad geographic coverage through its open-architecture design software that interoperates with third-party hardware. BEGO GmbH & Co. KG anchors premium cobalt-chrome and zirconia production from its Bremen headquarters, dominating German-speaking markets.
Europe dental labs manufacture custom oral prostheses using biocompatible ceramics, metals, and polymers to precise micrometer tolerances for individual patient anatomy. Crown and bridge segments generate the largest revenue share due to recurring replacement cycles and aging demographics across Italy and Spain. CAD/CAM technology captures the fastest expansion as laboratories phase out conventional wax-and-cast methods for same-day milling and 3D printing of surgical guides. Metal ceramics retains volume leadership in price-sensitive Southern European markets while zirconia displaces porcelain-fused-to-metal in premium Northern European practices.
EU Medical Device Regulation and CE marking requirements enforce traceability, biocompatibility testing, and post-market surveillance for all custom-made dental devices distributed within member states. EMA-aligned notified bodies in Germany and the Netherlands conduct conformity assessments that determine market access for novel biomaterials and digital manufacturing platforms. France's ANSM maintains additional vigilance on acrylic resin monomer emissions in laboratory environments. Stakeholders must monitor evolving harmonized standards under the EU AI Act as machine-learning algorithms enter automated crown design and quality inspection workflows.
Market Dynamics
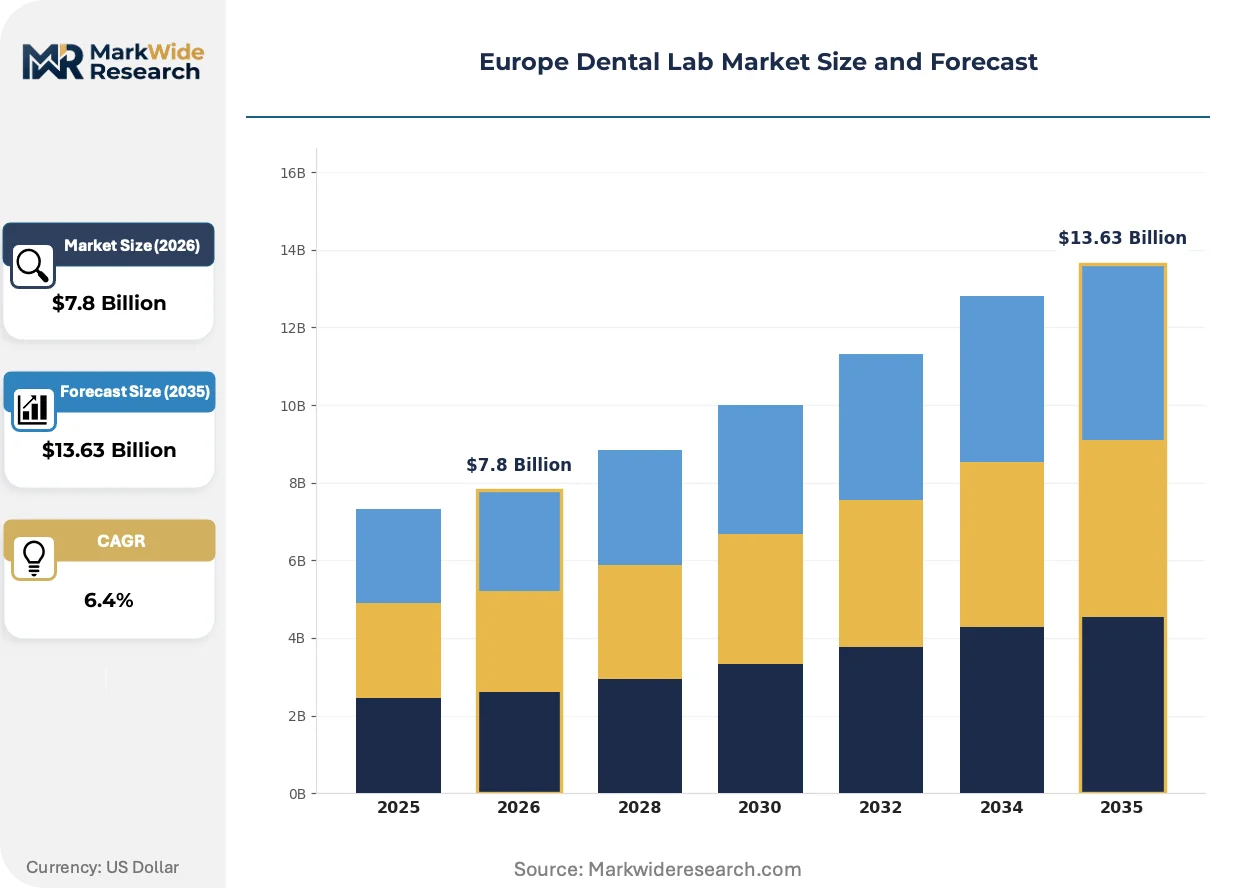
EU Medical Device Regulation enforcement is compressing laboratory certification timelines while CAD/CAM adoption accelerates workflow consolidation across German and French prosthodontic networks.
Growth Catalysts
- MDR traceability mandates:CE marking requirements under EU Medical Device Regulation force laboratories to digitize production records, expanding scanner and milling equipment procurement across notified body jurisdictions in Germany and the Netherlands.
- Aging demographics in Southern Europe:Italy and Spain exhibit elevated crown replacement cycles as patient populations over 65 drive recurring demand for fixed prosthodontic restorations.
- Zirconia sintering automation:High-speed furnace integration with CAD/CAM workflows reduces chairside turnaround from weeks to days, attracting private dental clinic chains in Bavaria and Baden-Württemberg.
Market Restraints
- Precious metal volatility:Palladium and gold price swings destabilize cost structures for laboratories maintaining conventional porcelain-fused-to-metal production lines.
- German equipment supplier concentration:Scanner and milling hardware sourcing clusters around Bremen and Stuttgart manufacturing corridors, exposing buyers to extended lead times during component shortages.
- Acrylic resin monomer restrictions:France's ANSM emission caps constrain traditional denture base fabrication methods, requiring capital outlays for closed-system polymerization equipment.
Strategic Opportunities
- Poland and Czech Republic laboratory networks:Underpenetrated digital fabrication capacity in Central European dental markets offers first-mover positioning for CAD/CAM workflow providers.
- EU AI Act algorithmic design:Automated crown anatomy generation using machine-learning tools creates regulatory-compliant pathways for quality inspection automation under forthcoming harmonized standards.
- Direct-to-clinic 3D printing:Chairside surgical guide production bypasses traditional laboratory intermediaries, opening subscription-based material supply contracts with implantology practices.
Industry Challenges
- Dental technician specialization gaps:Cross-training requirements for digital design software and subtractive manufacturing programming outpace vocational education output in Italy and Spain.
- Notified body backlog congestion:EMA-aligned conformity assessment queues in Germany and the Netherlands delay novel biomaterial market entry by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dental Lab Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crown, Bridge, Denture, Orthodontic Appliance Technology: CAD/CAM, 3D Printing, Milling, Wax Printing End User: Dental Clinics, Hospitals, Specialty Practices, Research Institutions Material: Metal Ceramics, Zirconia, Acrylic, Composite |
| Companies Covered | Zimmer Biomet Holdings, BEGO GmbH & Co. KG, Dentsply Sirona, Henry Schein, Corus Dental, Straumann Group, 3Shape A/S, VOCO GmbH, Ivoclar Vivadent, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dental Lab Market Shifts & Advancements
Digital fabrication methods are compressing traditional laboratory business models while regulatory algorithms reshape quality assurance protocols across European notified body jurisdictions.
Intraoral scanning hardware is migrating from specialist prosthodontic clinics toward general practitioner adoption in France and Germany. General dental practices in the Île-de-France region now deploy chairside scanners for single-unit crown workflows, reducing conventional impression material consumption by half. This shift is compressing the geographic radius of laboratory service areas as digital files replace physical model transport.
EU AI Act framework requirements for machine-learning medical devices are mandating algorithmic transparency documentation for automated crown design platforms. Laboratory software vendors must now submit training data provenance and bias assessment protocols to EMA-aligned notified bodies before CE marking approval. German laboratories employing AI-assisted anatomy generation face the steepest compliance documentation burdens under this emerging harmonized standard.
Subscription-based material procurement is displacing spot-market purchasing among high-volume dental clinic chains. Large practice groups in Bavaria negotiate multi-year zirconia block supply agreements with fixed per-unit pricing, transferring inventory risk upstream to laboratory suppliers. This concentration of purchasing power is most visible in corporate dental platforms operating across Baden-Württemberg and North Rhine-Westphalia.
Europe Dental Lab Market Segmentation
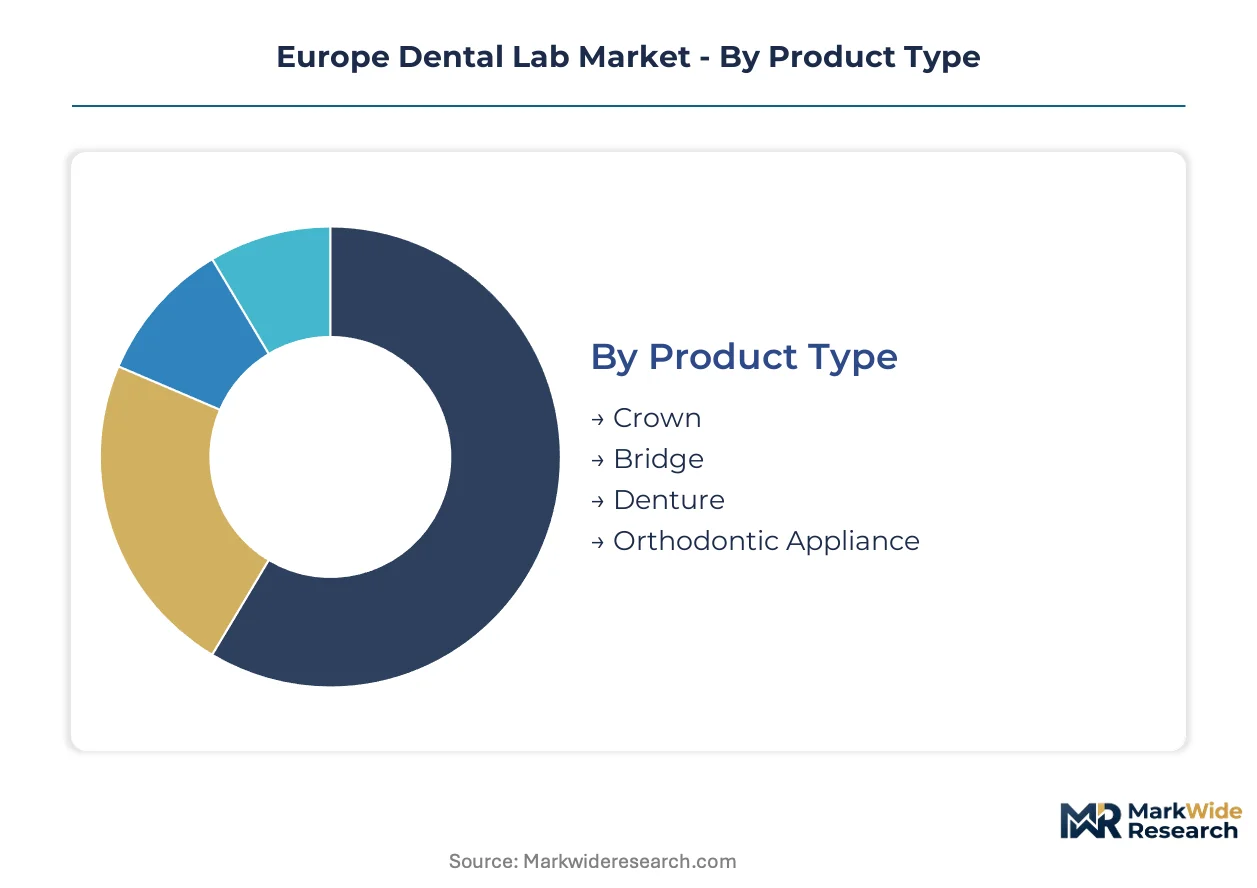
Segmentation in the Europe Dental Lab Market reveals distinct service intensity profiles across product categories. Laboratories supporting high-turnover crown workflows demand rapid technical response capabilities, while denture and orthodontic segments require sustained patient-specific consultation support.
Product Type:
After-sales service intensity varies dramatically across prosthetic categories, with implant-supported restorations requiring multi-year technical support commitments.
- Crown:Single-unit ceramic or metal-ceramic restorations fabricated to micrometer tolerances for individual tooth replacement. Demand concentrates in Bavaria and Baden-Württemberg where dense prosthodontic clinic networks drive same-day milling expectations.
- Bridge:Multi-unit fixed prostheses spanning edentulous spaces using cantilever or pontic designs. Italian and Spanish laboratories report elevated replacement cycles as aging patient populations over 65 require recurrent interventions.
- Denture:Removable acrylic or metal-frame prostheses replacing full or partial dental arches. France's ANSM emission caps on acrylic resin monomers constrain traditional fabrication methods.
- Orthodontic Appliance:Removable aligners and fixed brackets manufactured to patient-specific treatment plans. Central European markets show underpenetrated digital fabrication capacity.
Crown holds the largest share; momentum sits with Orthodontic Appliance.
Technology:
Capital deployment patterns distinguish high-investment digital platforms from legacy equipment categories.
- CAD/CAM:Computer-aided design and manufacturing workflows integrating intraoral scans with subtractive milling. German laboratories phase out conventional wax-and-cast methods for Bavaria and Baden-Württemberg clinic chains.
- 3D Printing:Additive fabrication of surgical guides, models, and provisional restorations using photopolymer resins. Direct-to-clinic production bypasses traditional laboratory intermediaries in implantology practices.
- Milling:Subtractive machining of zirconia blocks and pre-sintered ceramics into final prosthetic forms. Zirconia sintering automation reduces chairside turnaround from weeks to days.
- Wax Printing:Solid inkjet deposition of casting patterns for conventional lost-wax metal frameworks. Southern European price-sensitive markets retain volume for porcelain-fused-to-metal production.
Milling dominates current installed base; 3D Printing is climbing the fastest.
End User:
Procurement sophistication separates high-volume clinic chains from fragmented independent practitioner demand.
- Dental Clinics:General and specialist practices generating the majority of laboratory prescription volume. Corporate platforms across North Rhine-Westphalia negotiate multi-year material supply agreements.
- Hospitals:Academic medical centers and public health institutions requiring complex maxillofacial prostheses. EMA-aligned notified bodies enforce extended conformity assessment timelines for novel biomaterials.
- Specialty Practices:Prosthodontic, periodontic, and implantology clinics demanding premium restoration quality. Île-de-France region general practitioners now deploy chairside scanners for single-unit workflows.
- Research Institutions:University dental schools and biomaterials laboratories evaluating next-generation fabrication protocols. EU AI Act documentation burdens apply to algorithmic design validation studies.
Dental Clinics command the largest share; Specialty Practices show steepest expansion trajectory.
Material:
Price volatility exposure differentiates precious metal-dependent categories from ceramic alternatives.
- Metal Ceramics:Porcelain-fused-to-metal restorations combining cobalt-chrome or precious alloy substructures with veneering ceramics. Palladium and gold price swings destabilize cost structures for conventional production lines.
- Zirconia:High-strength yttria-stabilized tetragonal zirconia polycrystal for anterior and posterior crowns. Northern European premium practices displace porcelain-fused-to-metal with monolithic zirconia.
- Acrylic:Polymethyl methacrylate resins for denture bases and temporary restorations. French emission regulations require closed-system polymerization equipment capital outlays.
- Composite:Particle-reinforced resin materials for provisional restorations and orthodontic devices. BEGO GmbH & Co. KG anchors premium production from Bremen headquarters.
Metal Ceramics retains volume leadership; Zirconia is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prosthodontic clinic chains and independent dental practices concentrate demand across Northern and Western Europe, while Southern European markets exhibit higher price sensitivity and longer replacement cycles for fixed restorations.
Germany
Bavaria and Baden-Württemberg host dense networks of prosthodontic specialists driving same-day milling expectations. The EU Medical Device Regulation enforcement through German notified bodies compresses laboratory certification timelines for digital workflows. Stuttgart and Bremen manufacturing corridors anchor scanner and milling hardware production, exposing buyers to extended lead times during component shortages.
France
Île-de-France general practitioners deploy chairside scanners for single-unit crown workflows, reducing conventional impression material consumption. ANSM emission caps on acrylic resin monomers constrain traditional denture base fabrication methods in Parisian laboratories. The Provence-Alpes-Côte d'Azur region shows emerging adoption of closed-system polymerization equipment to meet regulatory requirements.
Italy
Aging patient populations over 65 drive elevated crown replacement cycles across Lombardy and Emilia-Romagna. CE marking requirements under MDR force digitization of production records among notified body jurisdictions. Dental technician specialization gaps in vocational education output lag behind cross-training requirements for digital design software.
Spain
Price-sensitive Southern European markets retain volume leadership for porcelain-fused-to-metal restorations despite zirconia displacement trends elsewhere. Metal ceramics production lines face cost structure destabilization from palladium and gold price volatility. Madrid and Barcelona laboratory networks report underpenetrated digital fabrication capacity relative to Northern European benchmarks.
Poland
Central European dental markets offer first-mover positioning for CAD/CAM workflow providers seeking expansion beyond saturated Western markets. EMA-aligned conformity assessment standards apply equally to Polish laboratories accessing EU-wide distribution. Warsaw and Krakow metropolitan areas concentrate emerging private dental clinic chains negotiating multi-year material supply agreements.
Europe Dental Lab Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that segments into integrated platform providers, regional fabrication specialists, and equipment-agnostic material suppliers. The vendor base clusters around three strategic archetypes: scanner-to-milling ecosystem owners, premium biomaterial anchors, and open-architecture software licensors. M&A activity concentrates on digital workflow consolidation, while strategic partnerships target direct-to-clinic 3D printing subscriptions.
Among Germany-based fabricators, BEGO GmbH & Co. KG anchors premium cobalt-chrome and zirconia production from its Bremen headquarters, exemplifying the regional specialist archetype. Straumann Group and Dentsply Sirona occupy positions on opposing ends of the integration spectrum, with the former representing closed-ecosystem control and the latter embodying open-architecture interoperability. These three entities collectively illustrate the competitive tension between captive supply chains and interoperable platforms reshaping procurement patterns across European prosthodontic networks.
| Leading Market Players |
|---|
| Zimmer Biomet Holdings |
| BEGO GmbH & Co. KG |
| Dentsply Sirona |
| Henry Schein |
| Corus Dental |
| Straumann Group |
| 3Shape A/S |
| VOCO GmbH |
| Ivoclar Vivadent |
| Others |
Supply & Pricing Matrix
Bremen and Stuttgart manufacturing corridors anchor scanner and milling hardware production, concentrating upstream capacity in German industrial clusters that transfer pricing power to equipment suppliers during component shortages. Bavarian prosthodontic clinic chains negotiate multi-year zirconia block supply agreements with fixed per-unit pricing, transferring inventory risk upstream while compressing margins for independent laboratories.
Pricing Analysis
Cost-plus contracts with palladium and gold indexation dominate porcelain-fused-to-metal production lines, exposing Southern European laboratories to precious metal volatility. Price differentiation hinges on CE marking tier under EU Medical Device Regulation and volume scale, with corporate dental platforms commanding standard-tier rates while independent practitioners absorb premium pricing for small-batch customization. Cost compression in metal ceramics is intensifying because zirconia displacement trends in Northern Europe force price-matching. Corporate clinic chains in Baden-Württemberg exhibit lowest price sensitivity due to captive patient volumes, whereas Madrid and Barcelona independent laboratories face acute margin pressure.
Supply Chain Analysis
Contract manufacturing concentrates with BEGO GmbH & Co. KG in Bremen and Straumann Group's Swiss production facilities holding premium cobalt-chrome and zirconia capacity. Geographic supply concentration clusters in Germany, Switzerland, and the Netherlands, with scanner hardware drawing from Stuttgart precision engineering ecosystems. Raw material dependencies rest on yttria-stabilized zirconia powder, cobalt-chrome alloy feedstock, and photopolymer resin monomers. Single-source vulnerability from German equipment supplier concentration exposes buyers to extended lead times. Distribution runs through regional laboratory networks serving prosthodontic clinics within compressed geographic radii as digital files replace physical model transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act algorithmic transparency mandates constitute a regulatory inflection that will bifurcate competitive positioning between documentation-compliant laboratories and legacy operators. This high-growth disruption favors first-movers in automated crown design and quality inspection workflows.
For Market Incumbents: Pre-empt notified body backlog congestion by accelerating CE marking submissions for machine-learning medical devices before harmonized standards crystallize. Consolidate backward integration into zirconia sintering automation to defend margin position against direct-to-clinic 3D printing entrants. Channel control through subscription-based material procurement contracts with Bavarian corporate platforms anchors recurring revenue against spot-market volatility. For New Entrants and Emerging Players: Pursue underpenetrated digital fabrication capacity in Poland and Czech Republic laboratory networks where EMA-aligned standards apply but competition remains sparse. Target orthodontic appliance segments in Central European markets where clear aligner demand outpaces local production capability. A direct-to-clinic 3D printing subscription model bypassing traditional laboratory intermediaries offers the most penetrable go-to-market angle for implantology practices. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MDR compliance burdens and AI Act documentation requirements will force sub-scale laboratory exits, concentrating market share among platform-integrated operators. Acquisition targets should display vertical integration into scanner-to-milling ecosystems or premium biomaterial production anchored in German-speaking markets. The signal to watch is notified body approval velocity for novel biomaterials, as 12-18 month assessment queues indicate regulatory capacity constraints that favor incumbent laboratories with established conformity assessment relationships.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EMA-aligned notified body pre-submission reduces time-to-market for AI-assisted crown design platforms in Germany. |
| Backward Integration into Zirconia Production | In-house sintering automation captures margin from equipment suppliers and reduces chairside turnaround for Bavarian clinic chains. |
| Direct-to-Clinic 3D Printing Subscription | Chairside surgical guide production bypasses traditional laboratory intermediaries in Île-de-France implantology practices. |
| Strategic Partnership with Corporate Dental Platforms | Multi-year material supply agreements with North Rhine-Westphalia chains transfer inventory risk and lock in volume commitments. |
| Acquisition of Central European Laboratory Networks | Polish and Czech digital fabrication capacity offers first-mover positioning before MDR compliance costs force consolidation. |
Research Methodology
Initial hypotheses were tested against primary input from dental laboratory directors, prosthodontic clinic procurement managers, biomedical engineers at notified bodies, and GPO contracts specialists, then refined against secondary validation from EMA device registration databases, EU Medical Device Regulation harmonized standards filings, customs trade data on zirconia powder imports, and SEC disclosures from listed dental equipment manufacturers. Bottom-up laboratory capacity surveys and top-down prosthodontic clinic prescription volume estimates were triangulated to anchor market sizing.
Demand-supply balance framing anchored the analytical framework across the projection horizon, modeling crown, bridge, denture, and orthodontic appliance segments alongside technology adoption curves for CAD/CAM, 3D printing, milling, and wax printing workflows. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic dental expenditure trends. Industry-specific forecast inputs incorporated MDR compliance cost pass-through assumptions and AI Act algorithmic transparency implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in eurozone dental reimbursement rates or precious metal commodity indices would shift the trajectory. Forecasts reflect documented assumptions on technology substitution elasticities and regulatory implementation pacing. Quarterly review of notified body approval queues and zirconia block pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
China Dental Devices Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Italy Dental Devices Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Middle East and Africa Dental Lab Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Orthodontics Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Global Dentures Market
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Dental Laboratories Market
Dental Devices
Europe Dental Implants Market