
 Asia-Pacific Digital Dentistry Market | 2026-2036
Asia-Pacific Digital Dentistry Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Dentistry Market Analysis
Zirconia is pivoting from lab-fabricated monolithic crowns to chairside-milled multilayer formulations, compressing per-unit production costs for same-day restorative procedures. 3Shape leverages its open-architecture scanning ecosystem to sustain interoperability leadership across third-party milling systems. Dentsply Sirona anchors premium chairside CAD/CAM installations through its vertically integrated hardware-software bundles. Align Technology competes in orthodontics via proprietary intraoral scanner-to-clear-aligner pipelines that lock specialists into closed digital workflows.
Digital dentistry encompasses the computer-aided design, computer-aided manufacture, and three-dimensional imaging technologies that replace conventional mechanical and analog methods in oral healthcare, with intraoral scanners achieving accuracy thresholds of 5-15 micrometers for full-arch digital impressions. Its primary commercial purpose centers on compressing restorative and orthodontic treatment timelines while standardizing output precision across decentralized clinical settings. Intraoral scanners occupy the dominant revenue position within product type categories, though 3D printers represent the fastest-expanding margin pool as resin formulations mature for surgical guide and provisional crown applications. Among end users, dental clinics absorb the majority of capital expenditure, while laboratories defend entrenched positions in complex implant-supported prosthodontics where multi-unit accuracy requirements exceed current chairside milling tolerances.
Japan's PMDA governs software-as-medical-device classifications for AI-assisted treatment planning platforms, while China's NMPA enforces GB standards on electromagnetic compatibility for intraoral scanning hardware, and Australia's TGA mandates ISO 13485 quality system certification for imported CAD/CAM components. These frameworks collectively elevate compliance costs for new entrants while privileging incumbents with established regulatory dossiers across multiple Asia-Pacific jurisdictions. Stakeholders must monitor harmonization gaps between national medical device software pathways that currently fragment product registration strategies and delay cross-border deployment timelines.
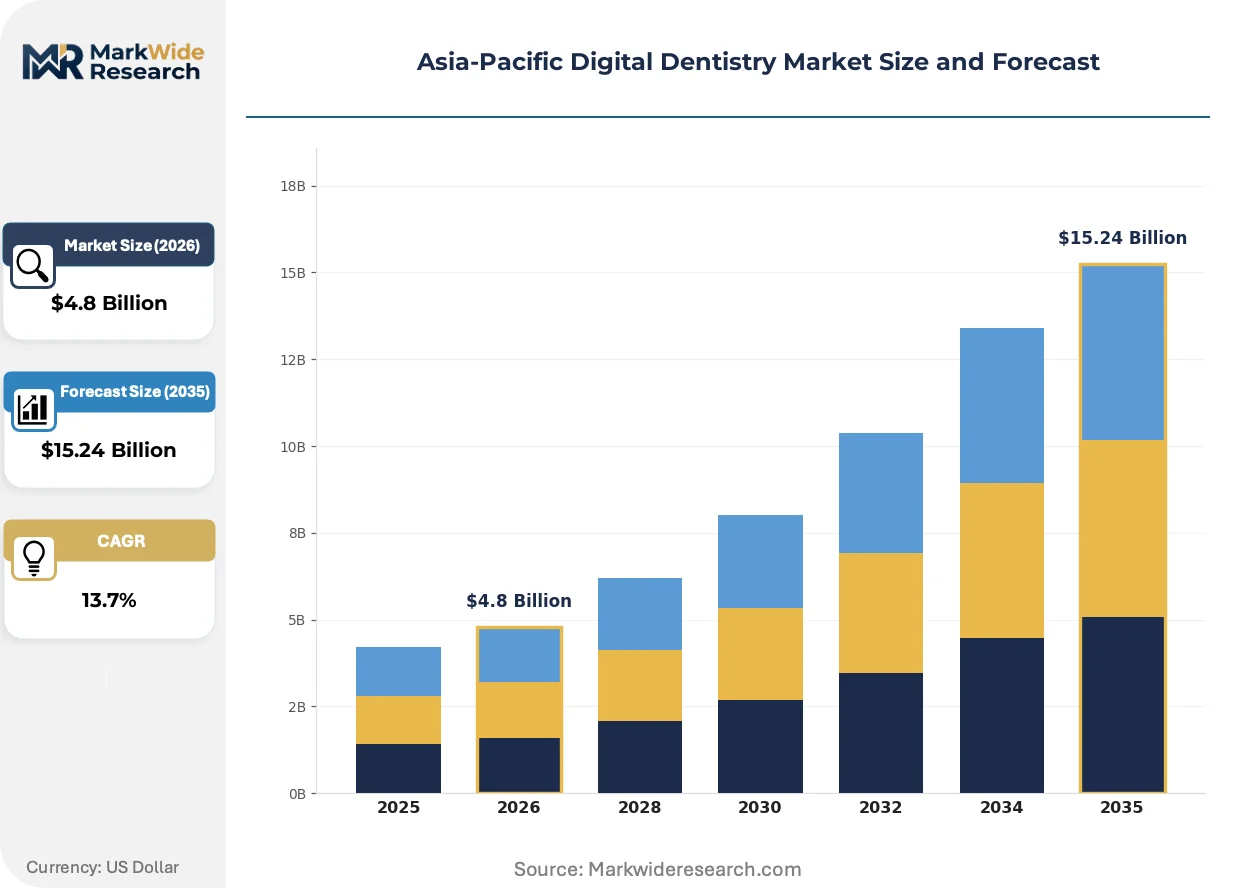
Market Dynamics
Chairside CAD/CAM workflows are compressing restorative timelines across Asia-Pacific dental clinics, forcing laboratories to defend complex prosthodontic niches where multi-unit accuracy requirements exceed current milling tolerances. This technological shift is redistributing value capture between clinical and lab-based service providers.
Growth Catalysts
- Streamlined software-as-medical-device pathways:Japan's PMDA has accelerated regulatory clearance for AI-assisted treatment planning platforms, reducing time-to-market for virtual surgical planning tools.
- Private dental chain consolidation:China's tier-one cities are witnessing purchasing power concentration among multi-clinic operators capable of standardizing digital workflows across branch networks.
- Multilayer zirconia formulations:Chairside-milled gradient ceramics are displacing lab-fabricated monolithic crowns by delivering aesthetic depth without outsourcing delays.
Market Restraints
- Capital intensity threshold:Chairside milling units and intraoral scanner bundles require substantial upfront investment that filters out independent solo practitioners.
- Electromagnetic compliance costs:China's NMPA enforces GB standards on intraoral scanning hardware, elevating certification expenses for imported equipment.
- Accuracy ceiling in complex cases:Full-arch implant-supported prosthodontics still demands laboratory-grade multi-unit precision beyond current chairside milling capabilities.
Strategic Opportunities
- Resin formulation maturation:3D printing materials are advancing for surgical guide and provisional crown applications, opening margin pools in same-day dentistry.
- Australian TGA harmonization potential:ISO 13485 quality system certification requirements for CAD/CAM components could align with broader Asia-Pacific regulatory convergence initiatives.
- Tier-two city penetration in China:Digital dentistry adoption remains concentrated in Beijing, Shanghai, Guangzhou and Shenzhen, leaving significant whitespace in provincial capitals.
Industry Challenges
- Interoperability friction:Closed digital workflows from proprietary scanner-to-aligner pipelines lock specialists into single-vendor ecosystems, complicating multi-equipment integration.
- Regulatory dossier fragmentation:Harmonization gaps between national medical device software pathways delay cross-border deployment timelines and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Dentistry Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD/CAM Systems, Intraoral Scanners, 3D Printers, Imaging Software End User: Dental Clinics, Research Institutions, Hospitals, Laboratories Technology: Digital Impressions, Virtual Treatment Planning, Cone Beam Imaging, Computer-Aided Design Application: Orthodontics, Restorative Dentistry, Cosmetic Dentistry, Prosthodontics |
| Companies Covered | 3Shape, Ivoclar Vivadent, Align Technology, Dentsply Sirona, Planmeca, Vatech, Osstem Implant, Medit Corporation, J. Morita Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Dentistry Market Emerging Trajectories
Digital impression technologies are displacing conventional mechanical methods across restorative and orthodontic workflows, with accuracy thresholds now matching clinical requirements for full-arch rehabilitation. This technological maturation is enabling same-day treatment protocols that compress patient visit frequency.
Artificial intelligence-assisted treatment planning is expanding into virtual orthodontic simulation and implant positioning, with algorithms now automating landmark detection and collision avoidance. Specialist practices in Japan and South Korea are adopting these platforms at accelerating rates. This capability expansion is compressing the planning phase of complex cases from days to hours while standardizing output consistency across less experienced operators.
Japan's PMDA has clarified software-as-medical-device classification criteria for AI-driven diagnostic aids, creating predictable registration pathways that reduce regulatory uncertainty for developers. The industrial consequence is a pipeline of regionally developed planning tools competing with imported platforms. Orthodontic applications are most affected, with domestic vendors accelerating localization strategies to capture specialist practice demand.
Buying patterns among Asia-Pacific dental clinics are pivoting toward bundled hardware-software service contracts that unbundle traditional capital expenditure into operationalized subscription models. Equipment distributors in Australia and Singapore are restructuring their offerings around per-procedure fees rather than upfront purchase. This shift is most visible among private dental chains in China's eastern seaboard cities, where standardized multi-branch deployments favor predictable recurring costs over lumpy capital outlays.
Asia-Pacific Digital Dentistry Market Segmentation
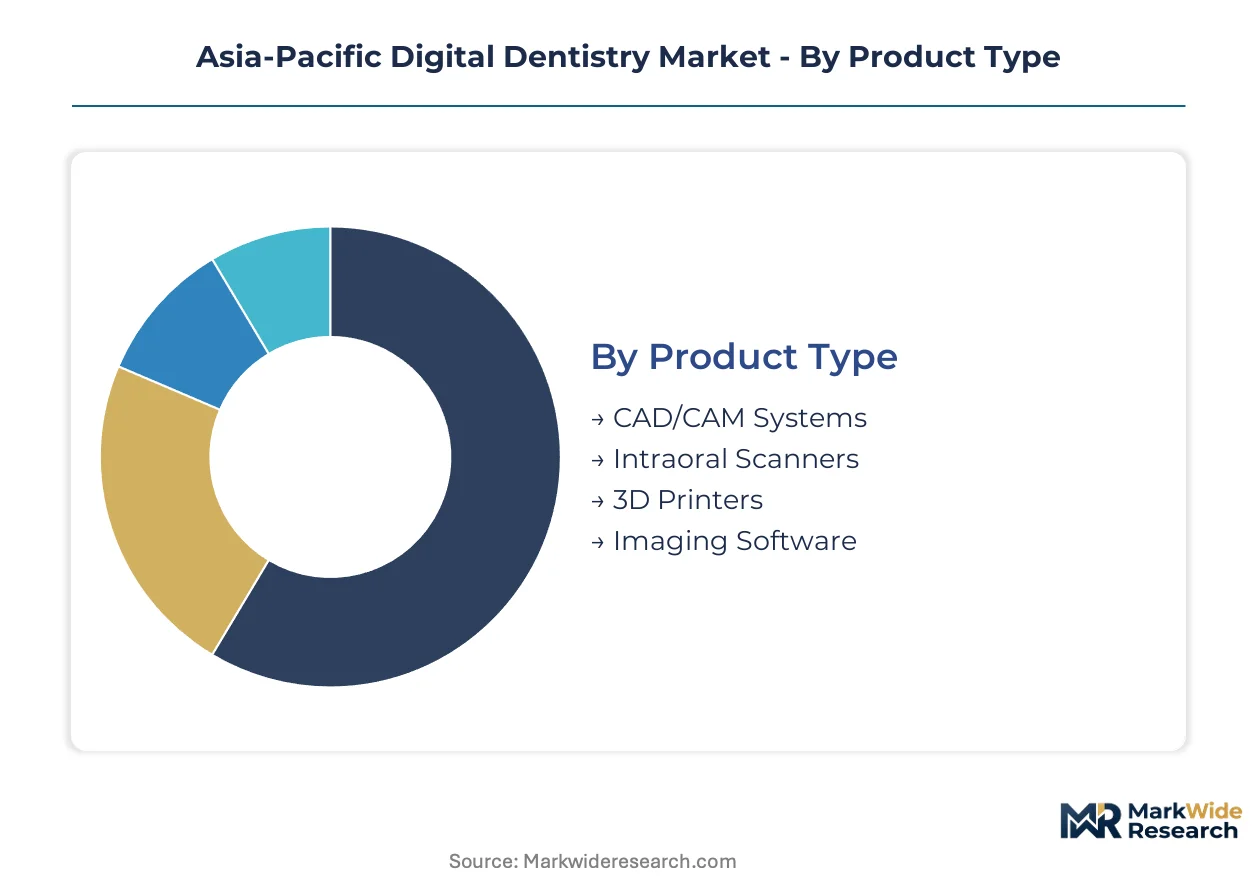
Digital dentistry markets fragment across hardware, software, and service layers that command distinct margin profiles and capital deployment cycles. Understanding these segment boundaries clarifies where value concentrates versus where growth accelerates.
Product Type:
Technology sophistication and workflow integration depth separate equipment categories.
- Intraoral Scanners:Optical triangulation and confocal microscopy systems achieve 5-15 micrometer accuracy thresholds for full-arch digital impressions. China's tier-one private dental chains are standardizing these across branch networks to compress patient visit frequency.
- CAD/CAM Systems:Chairside milling units integrate design software with subtractive manufacturing hardware for same-day crown production. Japan's PMDA streamlined software-as-medical-device pathways for the virtual planning components bundled with these systems.
- 3D Printers:Stereolithography and digital light processing hardware for surgical guide and provisional crown fabrication.
- Imaging Software:Treatment planning platforms and AI-assisted diagnostic tools requiring regulatory clearance.
Intraoral scanners lead on scale; 3D printers lead on momentum.
End User:
Capital intensity and case complexity dictate purchasing patterns across provider types.
- Dental Clinics:Private practices and multi-clinic chains absorb the majority of chairside equipment expenditure, with China's consolidated operators leveraging standardized procurement across branch networks.
- Laboratories:Centralized fabrication facilities defend complex prosthodontic niches where multi-unit implant accuracy exceeds current chairside milling tolerances.
- Hospitals:Academic medical centers and tertiary facilities with integrated oral surgery departments.
- Research Institutions:Universities and clinical trial sites developing next-generation materials and protocols.
Dental clinics dominate volume; laboratories defend premium positioning.
Technology:
Digital workflow stages map to distinct hardware-software combinations.
- Digital Impressions:Intraoral scanning protocols displacing conventional mechanical methods across restorative and orthodontic workflows.
- Virtual Treatment Planning:AI-assisted platforms automating landmark detection and collision avoidance for implant positioning, with specialist practices in Japan and South Korea adopting at accelerated rates.
- Cone Beam Imaging:Three-dimensional radiographic systems providing sub-millimeter anatomical detail for surgical planning.
- Computer-Aided Design:Software environments for prosthetic geometry optimization and material-specific milling parameter selection.
Digital impressions anchor current deployment; virtual treatment planning is climbing the fastest.
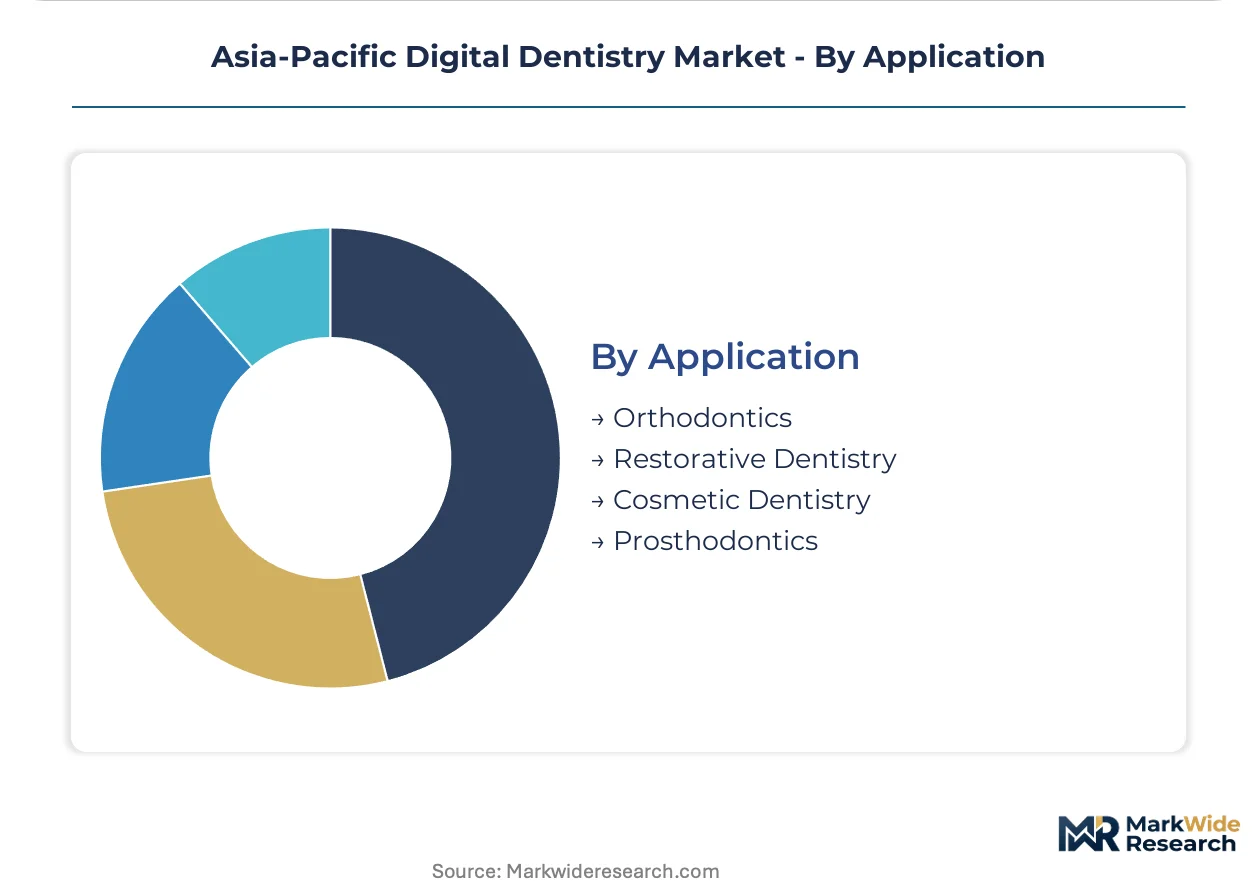
Application:
Clinical specialty requirements drive specification differentiation.
- Restorative Dentistry:Crown, bridge, and inlay fabrication workflows where chairside CAD/CAM compresses production timelines from weeks to hours.
- Orthodontics:Clear aligner therapy pipelines requiring intraoral scanner-to-manufacturing integration, with proprietary closed workflows locking specialists into single-vendor ecosystems.
- Prosthodontics:Complex implant-supported reconstructions demanding laboratory-grade multi-unit precision.
- Cosmetic Dentistry:Veneer and aesthetic restoration planning with enhanced visualization tools.
Restorative dentistry captures the largest equipment footprint; orthodontics shows the steepest software attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta dental manufacturing cluster generates the dominant share of regional equipment procurement, with Shanghai-based private chains standardizing chairside CAD/CAM deployments across branch networks.
China
Private dental chains in Beijing, Shanghai, Guangzhou and Shenzhen are consolidating purchasing power for intraoral scanner bundles. NMPA enforces GB standards on electromagnetic compatibility for imported scanning hardware. Hangzhou and Chengdu are emerging as tier-two city hubs where digital adoption lags tier-one penetration by three to five years.
Japan
Specialist orthodontic practices in Tokyo and Osaka are adopting AI-assisted treatment planning platforms at accelerated rates. PMDA streamlined software-as-medical-device pathways for virtual surgical planning tools. Nagoya's dental equipment distributors are restructuring offerings around per-procedure subscription models rather than capital sales.
South Korea
Seoul Capital Area clinics are deploying cone beam imaging systems for implant positioning workflows. MFDS regulates AI-driven diagnostic aids under medical device software classifications. Busan-Ulsan manufacturing corridors host domestic 3D printer assembly operations serving export markets.
Australia
Sydney and Melbourne private practices absorb premium chairside milling installations through bundled service contracts. TGA mandates ISO 13485 quality system certification for imported CAD/CAM components. Queensland's regional dental networks remain underpenetrated relative to southeastern metro concentration.
India
Maharashtra and Karnataka dental laboratories are defending complex prosthodontic niches where multi-unit precision exceeds chairside capabilities. CDSCO regulates imported intraoral scanners under medical device licensing requirements. Delhi-NCR academic medical centers pilot AI-assisted landmark detection for implant planning.
Asia-Pacific Digital Dentistry Market Vendor Landscape
Global majors compete with regional champions across regulatory dossier depth and software-hardware integration. The vendor base stratifies into three tiers: vertically integrated conglomerates with full-stack CAD/CAM portfolios, open-architecture scanning specialists sustaining interoperability across third-party systems, and closed-loop orthodontics platforms locking specialists into proprietary pipelines. Dominant competitive moves include strategic partnerships between equipment distributors and private dental chains, plus geographic expansion into China's tier-two provincial capitals.
Within the vertically integrated tier, Dentsply Sirona and Planmeca exemplify hardware-software bundling strategies that anchor premium chairside installations. 3Shape occupies a position as the open-architecture scanning archetype, while Align Technology represents the closed-loop orthodontics model. These three entities collectively illustrate the strategic divergence between interoperability-focused and ecosystem-locking approaches that define competitive positioning across Asia-Pacific digital dentistry procurement.
| Leading Market Players |
|---|
| 3Shape |
| Ivoclar Vivadent |
| Align Technology |
| Dentsply Sirona |
| Planmeca |
| Vatech |
| Osstem Implant |
| Medit Corporation |
| J. Morita Corporation |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of zirconia blanks and optical scanning modules anchors both supply security and pricing power for premium chairside CAD/CAM vendors operating across Asia-Pacific dental markets. This backward integration shields hardware manufacturers from resin and ceramic input volatility while enabling subscription-based pricing models that compress customer acquisition costs.
Pricing Analysis
Input-cost pass-through from zirconia blank suppliers and precision optical component manufacturers shapes equipment pricing across tiered hardware bundles. Three-tier pricing structure across premium, standard, and economy levels separates Dentsply Sirona's vertically integrated chairside systems from open-architecture scanning alternatives. Pricing pressure stems from China's NMPA electromagnetic compliance costs elevating certification expenses for imported intraoral scanners. Solo practitioners in tier-two Indian cities exhibit highest price sensitivity, while Japanese specialist orthodontic chains absorb premium AI-assisted planning platform subscriptions with minimal negotiation.
Supply Chain Analysis
Direct-to-clinic distribution channels handle hyperscale demand from China's consolidating private dental chains, while laboratory-focused distributors manage complex prosthodontic equipment procurement. Manufacturing concentrates in Germany, Japan, and South Korea for precision milling spindles and optical triangulation sensors. Supply chains draw from Taiwanese semiconductor foundries for scanning processor chips and Belgian ceramic suppliers for multilayer zirconia formulations. Single-source vulnerability concentrates in Japanese confocal microscopy component suppliers serving Tier 1 scanner manufacturers. Distribution runs through authorized dealer networks in Australia and Singapore, with direct sales teams penetrating China's tier-one metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific digital dentistry represents a late-cycle quality story as specialist practices pivot toward AI-assisted treatment planning platforms demanding premium software attach rates and validated clinical outputs.
For Market Incumbents: Acquire regulatory dossier portfolios across multiple Asia-Pacific jurisdictions to defend against emerging domestic challengers leveraging streamlined PMDA and NMPA pathways. Deepen backward integration into zirconia blank manufacturing to capture margin pools eroding at the equipment layer. Prioritize ISO 13485 certification maintenance for Australian TGA compliance as harmonization initiatives converge quality system requirements. For New Entrants and Emerging Players: Enter via tier-two Chinese provincial capitals where digital adoption lags tier-one penetration by three to five years, exploiting whitespace in Hangzhou and Chengdu dental markets. Target provisional crown resin formulation niches where 3D printing material science advances faster than incumbent R&D cycles. Deploy per-procedure subscription pricing to bypass capital expenditure barriers filtering solo practitioners. For Investors and Strategic Acquirers: Roll-up economics work for regional equipment distributors with established clinic relationships because purchasing power consolidation among multi-branch operators favors standardized procurement platforms. Five-to-ten year viability hinges on software-as-medical-device revenue streams displacing hardware transaction dependency. Monitor PMDA software classification harmonization signals as inflection indicators for cross-border platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Registration | PMDA streamlined pathways reduce time-to-market for AI-assisted orthodontic planning platforms competing with imported alternatives. |
| Chairside CAD/CAM Bundle Expansion | Vertically integrated hardware-software deployments anchor premium positioning in China's consolidating private dental chain networks. |
| Open-Architecture Scanning Ecosystem | Interoperability leadership across third-party milling systems sustains 3Shape's competitive moat against closed-loop alternatives. |
| Resin Formulation Maturation | Advanced 3D printing materials for surgical guides open margin pools in same-day dentistry workflows beyond traditional crown fabrication. |
| Tier-Two City Penetration | Underpenetrated provincial capitals in China offer whitespace acquisition targets before domestic competitors establish regulatory dossiers. |
Methodological Framework
Multiple input streams — primary interviews with dental equipment procurement managers, regulatory affairs specialists at NMPA and PMDA, and orthodontic practice owners — were reconciled against secondary validation from hospital procurement databases, medical device registration filings, and GPO contract repositories. Bottom-up equipment shipment data from distributors across China, Japan, and Australia were triangulated with top-down market sizing derived from capital expenditure disclosures of listed private dental chains.
Data-stream reconciliation across product type, end-user category, technology layer, and clinical application dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of intraoral scanner adoption curves and 3D printer installation growth rates. Industry-specific forecast inputs included NMPA electromagnetic compliance cost trajectories and PMDA software-as-medical-device clearance timelines.
Inputs from regulatory filing databases and distributor shipment records were available through the study window; gaps in tier-two Chinese city penetration data introduce uncertainty bands around provincial market sizing. Forecasts reflect documented assumptions regarding private dental chain consolidation velocity and AI-assisted planning platform adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contraceptive Rings Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Medical Oxygen Sensors Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Liposuction Devices Market
Medical Devices
EMG Biosensors Market
Medical Devices
Cryoballoon Ablation System Market
Medical Devices
Breast Localization System Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market
Medical Devices
Smart Patches Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Hearing Aid Dehumidifier Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Laparoscopic Electrodes Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market