
 Asia Pacific Dental Market | 2026-2036
Asia Pacific Dental Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Dental Market Insights
Market Context with Strategic Players
Private dental clinic chains is redrawing procurement priorities across the Asia Pacific region, shifting volume away from hospital-based purchasing committees toward decentralized inventory decisions. Dentsply Sirona leverages its CAD/CAM equipment portfolio to dominate chairside workflows in Australian and Japanese practices. Align Technology sustains premium positioning through direct-to-practitioner digital scanning networks. GC Corporation anchors its competitiveness with fluoride-releasing restorative materials tailored to caries-prevalent populations in Indonesia and Vietnam.
Technical Definition and Structural Segments
Dental care encompasses the diagnosis, prevention, and treatment of oral diseases using instruments ranging from high-speed handpieces operating at 300,000–400,000 RPM to biocompatible titanium implants with osseointegration surfaces. The industry serves therapeutic restoration, aesthetic enhancement, and chronic disease management functions across ambulatory and institutional settings. Consumables and dental implants command the deepest margin pools due to repeat-purchase dynamics and specialized manufacturing requirements, while digital dentistry and 3D printing represent the fastest-expanding technology categories as chairside production displaces centralized laboratory workflows. Orthodontics competes intensely between clear aligner platforms and conventional bracket systems, with application demand tilting toward cosmetic dentistry as middle-class patients prioritize aesthetic outcomes.
Regulatory Framework and Forward Outlook
Japan's PMDA, Australia's TGA, and India's CDSCO collectively enforce medical device registration, sterilization validation, and clinical evidence standards that determine market access timelines and product qualification costs. Japan's QMS ordinance and India's 2017 Medical Device Rules impose quality system audits on foreign manufacturers, filtering supplier participation. Stakeholders must monitor divergence between national regulatory databases and harmonized ASEAN medical device directives as the region moves toward unified conformity assessment pathways.
Market Dynamics
Private dental clinic chains across Southeast Asia are decentralizing procurement authority from hospital purchasing committees to individual practice managers, fragmenting vendor relationships and compressing decision cycles for equipment and consumables.
Growth Catalysts
- India's CDSCO Import Rules:Tightened medical device registration requirements redirect procurement toward locally registered suppliers, accelerating domestic manufacturing capacity expansion.
- Chairside CAD/CAM Adoption:Digital scanning and milling systems enable same-day crown production, reducing laboratory turnaround from two weeks to under two hours.
- Tier-Two City Disposable Income:China's secondary urban centers exhibit faster income growth than saturated metros, creating new patient pools for aesthetic and restorative procedures.
Market Restraints
- Titanium Implant Raw Material Concentration:Sponge titanium supply concentrates among a limited set of metallurgical processors, exposing manufacturers to input cost volatility.
- PMDA Quality System Audits:Japan's QMS ordinance imposes multi-year compliance timelines on foreign manufacturers, filtering market participation.
- Conventional Bracket Substitution Pressure:Clear aligner platforms capture orthodontic cases previously served by fixed appliances, compressing bracket system volumes.
Strategic Opportunities
- Vietnam's Underpenetrated Clinic Network:Dental chair density remains below regional averages, creating whitespace for equipment suppliers and consumables distributors.
- 3D Printing Convergence with Biocompatible Resins:Chairside production of surgical guides and temporary restorations merges additive manufacturing with regulatory-compliant materials.
- ASEAN Medical Device Directive Harmonization:Unified conformity assessment pathways reduce registration duplication across member states.
Industry Challenges
- CAD/CAM Technician Skill Scarcity:Digital workflow adoption outpaces training pipeline output, creating bottlenecks in scanner operation and design software proficiency.
- Osseointegration Surface Certification Timelines:Implant manufacturers face extended clinical evidence requirements for modified surface topographies.
- Legacy Practice Management System Integration:New digital platforms require middleware development to interface with entrenched electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Dental Market |
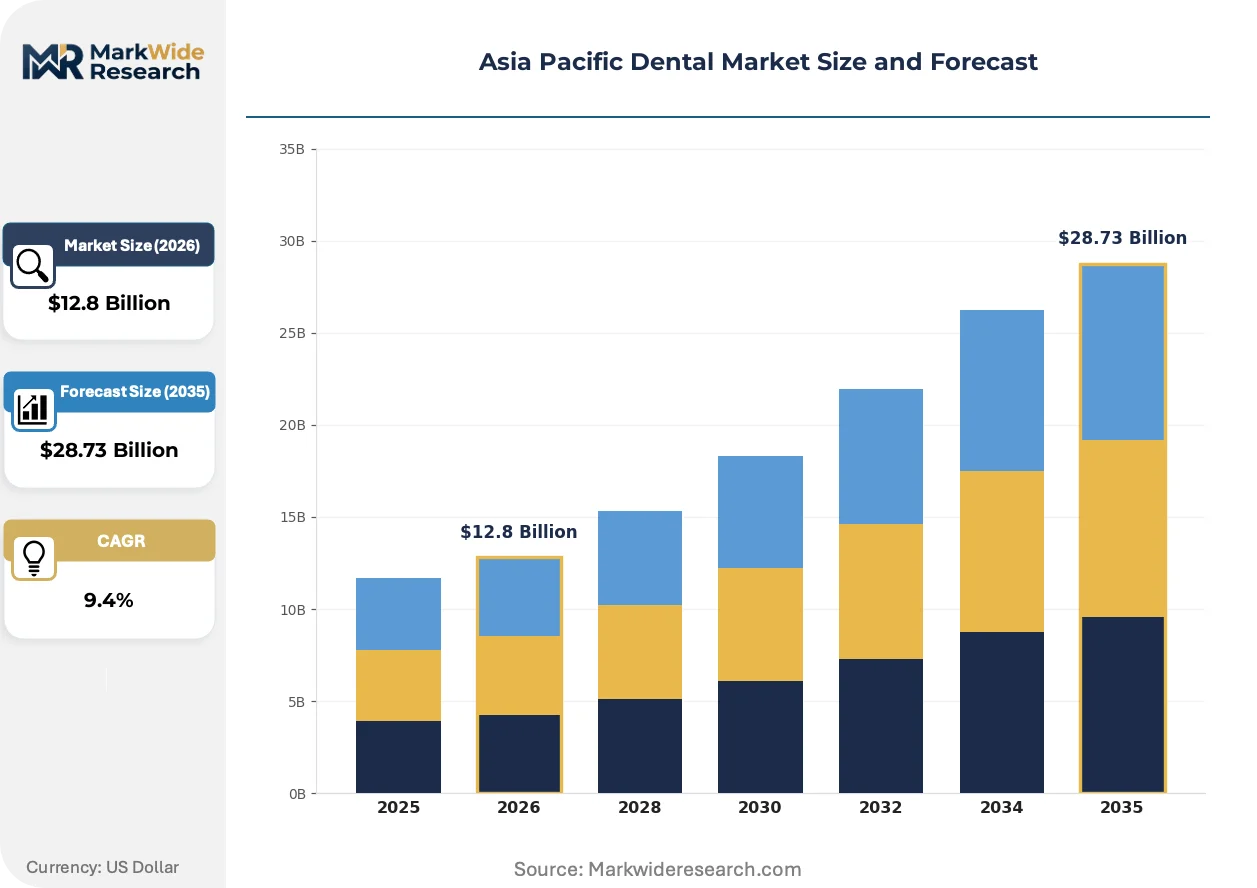
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Equipment, Dental Implants, Orthodontics End User: Hospitals, Dental Clinics, Academic Institutions, Research Laboratories Technology: CAD/CAM, Digital Dentistry, Laser Dentistry, 3D Printing Application: Cosmetic Dentistry, Preventive Care, Restorative Treatment, Periodontology |
| Companies Covered | Dentsply Sirona, Align Technology, Envista Holdings Corporation, Institut Straumann AG, Henry Schein, 3M, Ivoclar Vivadent, GC Corporation, Planmeca, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Dental Market Trends and Innovations
Digital dentistry infrastructure is compressing traditional laboratory intermediaries while regulatory harmonization efforts reshape cross-border equipment flows across Southeast Asian markets.
Intraoral scanning hardware is miniaturizing from cart-mounted units to handheld wireless devices weighing under 300 grams. Solo practitioners and small group practices in Thailand and Malaysia are adopting these portable systems at replacement-cycle pace. This form-factor reduction is miniaturizing capital requirements and enabling mobile dentistry deployments in remote provincial markets previously unreachable by fixed-chair infrastructure.
Japan's PMDA revised its medical device software guidance to classify AI-assisted radiographic interpretation tools as Class II devices requiring clinical validation. Manufacturers must submit algorithm training datasets and performance benchmarks against expert reader panels. Dental imaging OEMs targeting the Japanese market are restructuring R&D roadmaps to accommodate pre-market clinical trial obligations.
Direct-to-practitioner digital scanning networks are displacing distributor-mediated equipment sales in Australian and South Korean markets. Manufacturers now deploy field clinical specialists to train chairside staff, capturing recurring consumables revenue through proprietary material lock-in. This channel restructuring concentrates margin capture with equipment vendors while reducing independent dental laboratory influence over restoration material selection.
Asia Pacific Dental Market Segmentation
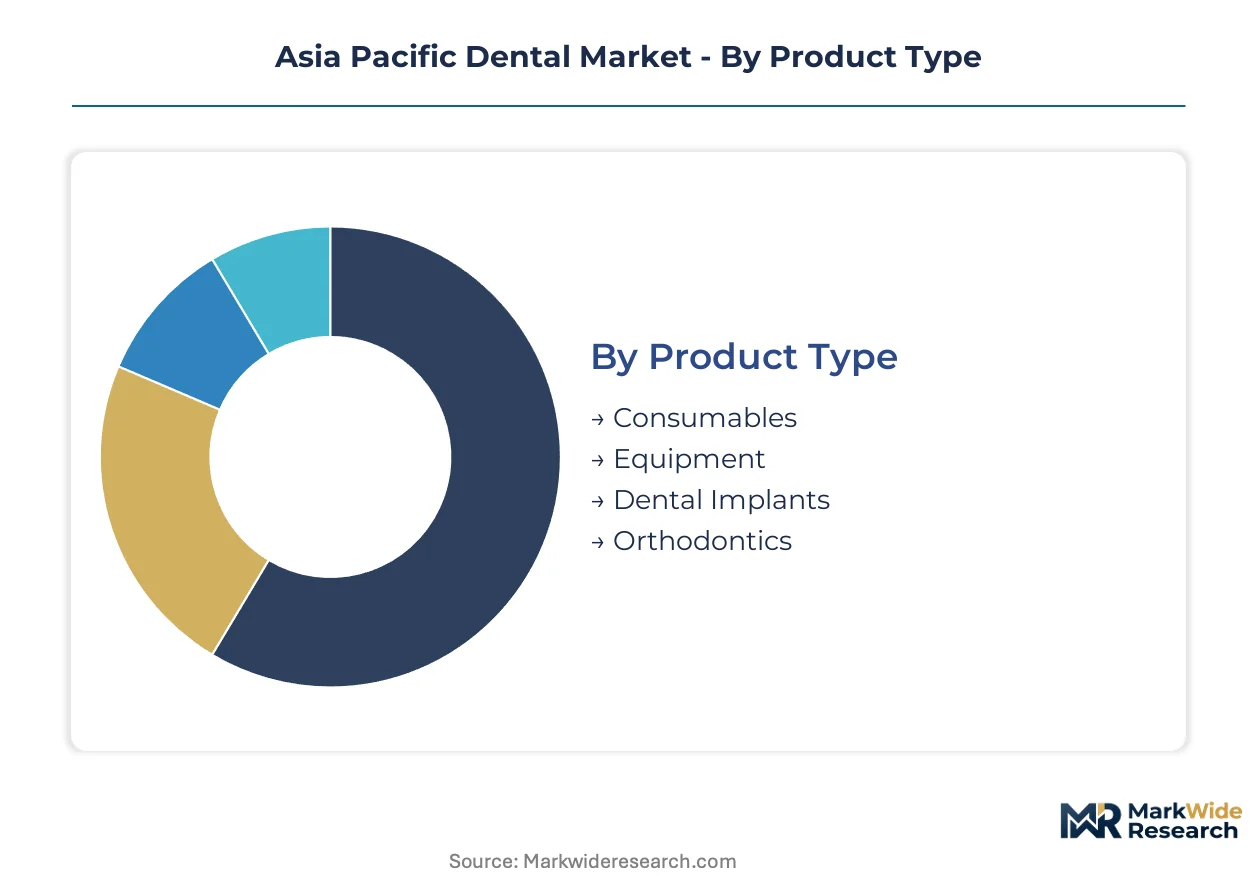
Segmentation in the Asia Pacific dental market reveals divergent channel economics and procurement behaviors. Product type determines margin structure, while technology adoption separates high-investment private chains from cost-constrained public institutions.
Product Type:
Consumables and implants flow through high-frequency distributor networks, while capital equipment concentrates through direct manufacturer relationships with clinic chains.
- Consumables:Fluoride-releasing composites, bonding agents, and impression materials constitute recurring purchase cycles with 60-90 day inventory turns. Demand clusters in Indonesian and Vietnamese private clinics where chair expansion outpaces supply chain maturation, compressing distributor margins.
- Equipment:High-speed handpieces, autoclaves, and imaging systems require technical installation and maintenance contracts. Australian and Japanese practices prioritize chairside CAD/CAM integration, while Southeast Asian markets still expand basic chair and compressor capacity.
- Dental Implants:Titanium fixtures with surface-modified osseointegration properties command premium positioning. China's tier-two cities and South Korea's aesthetic-focused practices drive volume, though raw material concentration in sponge titanium suppliers creates cost volatility.
- Orthodontics:Clear aligner platforms and conventional bracket systems compete for case volume. Aligner adoption accelerates in South Korea and urban China, while fixed appliances retain cost-sensitive segments in India and the Philippines.
Consumables dominate installed base. Dental implants are where expansion concentrates.
End User:
Procurement authority decentralization is fragmenting vendor relationships across customer types, with private clinics compressing decision cycles versus hospital committees.
- Hospitals:Public institutions in India and Thailand maintain centralized purchasing with multi-year tender cycles. CDSCO registration requirements and extended validation timelines filter supplier participation toward established multinationals with local manufacturing.
- Dental Clinics:Private chains across Malaysia and Indonesia delegate procurement to practice managers, enabling rapid equipment replacement and consumables switching. This decentralization rewards distributors with localized inventory and technical service capabilities.
- Academic Institutions:Dental schools in Japan and Australia drive training-equipment specifications that cascade into graduate practice preferences. Research partnerships with imaging and CAD/CAM manufacturers shape curriculum-aligned purchasing.
- Research Laboratories:Biomaterials testing and surface characterization facilities support implant and regenerative product development. Concentrated in Singapore and South Korea, these end users demand precision instrumentation with validation documentation.
Hospitals anchor legacy installed base. Dental clinics are gaining share fastest.
Technology:
Technology segmentation separates capital-intensive digital workflows from established mechanical techniques, with adoption pacing varying sharply by market maturity.
- CAD/CAM:Chairside scanning and milling systems enable same-day crown production. Japanese and Australian practices lead adoption, while Thai and Malaysian clinics accelerate replacement of cart-mounted units with handheld wireless scanners.
- Digital Dentistry:Intraoral imaging, electronic health records, and practice management software integration. South Korean chains prioritize seamless platform connectivity, creating demand for middleware development.
- Laser Dentistry:Soft-tissue and hard-tissue laser systems for periodontal and surgical applications. Penetration remains limited to premium-positioned practices in Singapore and Hong Kong due to capital cost and training requirements.
- 3D Printing:Additive manufacturing of surgical guides, temporary restorations, and orthodontic models. Biocompatible resin certification under PMDA and TGA frameworks shapes vendor qualification in Japan and Australia.
CAD/CAM dominates current capital deployment. 3D printing represents the steepest expansion trajectory.
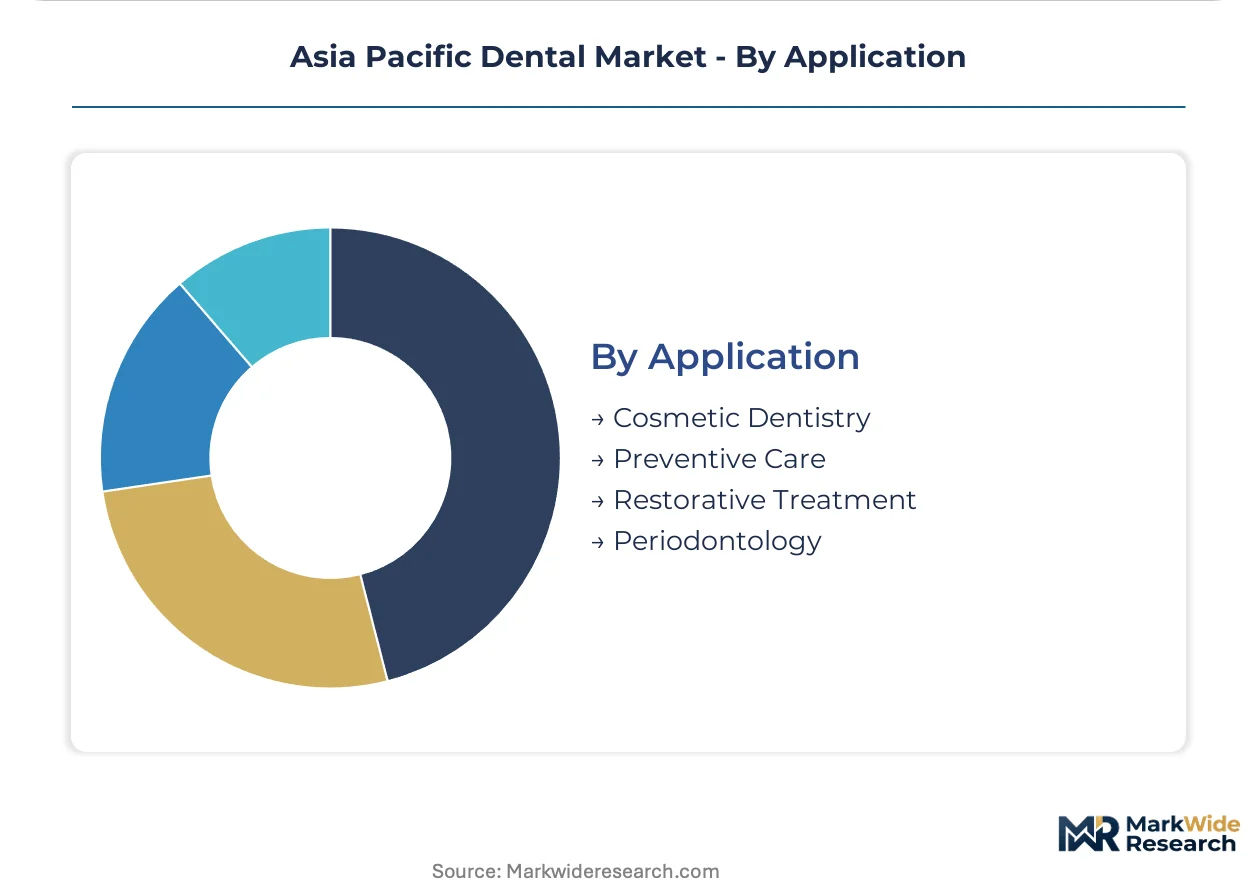
Application:
Application segmentation tracks patient payment capacity, with cosmetic and restorative procedures concentrated in private-pay markets and preventive care tied to insurance reimbursement structures.
- Cosmetic Dentistry:Veneers, whitening, and aesthetic orthodontics. China's tier-two cities and South Korea's urban centers exhibit fastest demand growth as disposable income outpaces metro saturation.
- Preventive Care:Fluoride treatments, sealants, and prophylaxis. Indonesian and Vietnamese government programs expand access, though equipment and consumables procurement remains price-sensitive.
- Restorative Treatment:Crowns, bridges, and direct fillings. Indian private clinics drive volume for cost-optimized materials, while Australian practices prioritize premium ceramic and composite systems.
- Periodontology:Gum disease management through scaling, root planing, and regenerative procedures. Japan's aging population sustains demand, with laser and ultrasonic technologies displacing manual instrumentation.
Restorative treatment commands largest procedure volume. Cosmetic dentistry is where premium positioning concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports precision dental equipment to Australian specialist practices, while South Korean clear aligner manufacturers supply orthodontic chains across Southeast Asia. This trade-flow pattern shapes competitive positioning across the region's fragmented procurement landscape.
China
Tier-two cities including Chengdu, Wuhan, and Xi'an drive demand for aesthetic procedures as disposable income growth outpaces saturated coastal metros. NMPA registration requirements for imported implants filter supplier participation toward locally registered entities. The Yangtze River Delta cluster around Shanghai anchors domestic manufacturing of CAD/CAM components and biocompatible resins.
Japan
Aging demographics sustain periodontology and implant procedure volumes in Kanto and Kansai metropolitan areas. PMDA QMS ordinance imposes multi-year compliance timelines on foreign manufacturers, concentrating market access among established multinationals with local quality system audits. Tokyo and Osaka dental schools cascade training-equipment specifications into graduate practice preferences.
India
Private clinic chains in Maharashtra and Karnataka expand chair capacity faster than public hospital procurement cycles. CDSCO's 2017 Medical Device Rules and tightened import registration redirect procurement toward locally registered suppliers, accelerating domestic manufacturing capacity. The Delhi-NCR corridor clusters dental laboratory services and implant distributors serving North Indian markets.
Australia
Direct-to-practitioner digital scanning networks displace distributor-mediated equipment sales in Sydney and Melbourne specialist practices. TGA medical device registration and sterilization validation standards determine product qualification timelines. The Melbourne-Brisbane corridor concentrates premium-positioned practices adopting chairside CAD/CAM and 3D printing workflows.
Vietnam
Dental chair density in Ho Chi Minh City and Hanoi remains below regional averages, creating whitespace for equipment suppliers and consumables distributors. Government preventive care programs expand access in provincial markets previously unreachable by fixed-chair infrastructure. The Southern Key Economic Zone clusters foreign-invested manufacturing facilities serving ASEAN export markets.
Asia Pacific Dental Market Competitive Landscape
Player mix skews toward multinational equipment specialists with direct clinical training capabilities and regional consumables distributors with localized inventory networks. Market structure concentrates around three strategic archetypes: integrated digital workflow vendors, implant system specialists with surface-modification IP, and distributor-led consumables suppliers. Competitive moves center on direct-to-practitioner channel restructuring and chairside technology licensing arrangements that lock in recurring material revenue.
Within the integrated digital workflow tier, Dentsply Sirona and Align Technology exemplify archetypes combining equipment hardware with proprietary consumables ecosystems. Institut Straumann AG occupies a position among implant system specialists with metallurgical and surface-engineering competencies. These three anchors represent distinct competitive vectors: chairside production integration, direct clinical network deployment, and osseointegration technology specialization.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Align Technology |
| Envista Holdings Corporation |
| Institut Straumann AG |
| Henry Schein |
| 3M |
| Ivoclar Vivadent |
| GC Corporation |
| Planmeca |
| Others |
Pricing and Supply Chain Analysis
Japan's PMDA QMS ordinance gates both supplier qualification and price tiering simultaneously, as foreign manufacturers face multi-year audit timelines that filter participation toward established players with localized quality systems while compressing margin pools for unregistered competitors. This regulatory barrier creates a dual effect: it protects premium pricing for compliant incumbents and forces cost-optimized tiers toward domestic manufacturing partnerships.
Pricing Analysis
Next-generation handheld wireless intraoral scanners command three-to-four-fold premiums over prior-generation cart-mounted units, while legacy mechanical handpieces trade at commodity levels in Southeast Asian procurement tenders. Three-tier pricing structure across premium, standard, and economy levels separates Japanese and Australian practices seeking chairside CAD/CAM integration from Indian clinics prioritizing cost-optimized consumables and Vietnamese entrants expanding basic chair capacity. Pricing pressure stems from clear aligner platforms capturing orthodontic cases previously served by fixed appliances, compressing bracket system volumes and forcing conventional manufacturers toward volume discounting. Hospital purchasing committees in Thailand and India exhibit highest price sensitivity due to multi-year tender cycles, while Australian specialist practices show lowest sensitivity when bundled with direct clinical training and proprietary material lock-in.
Supply Chain Analysis
Port congestion along the Shanghai-Singapore trade lane elevates inbound logistics costs for titanium sponge shipments originating from Japanese and Chinese metallurgical processors, compressing working capital cycles for implant manufacturers dependent on just-in-time raw material flows. Sponge titanium supply concentrates among limited processors in Japan, China, and Russia, while biocompatible resin formulations for 3D printing draw from German and Japanese specialty chemical houses. Single-source vulnerability runs through surface-modified implant substrate suppliers, where osseointegration coating intellectual property anchors in concentrated facilities. Distribution runs through high-frequency distributor networks for consumables in Indonesia and Vietnam, contrasting with direct manufacturer relationships dominating Australian and Japanese equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clear aligner substitution threatens conventional bracket and laboratory-mediated restoration workflows, forcing incumbents to defend integrated digital positions while new entrants exploit whitespace in underpenetrated provincial networks.
For Market Incumbents: Secure proprietary consumables lock-in through chairside technology licensing arrangements that capture recurring material revenue, while accelerating backward integration into biocompatible resin production to offset supply concentration risk from Japanese and German specialty chemical suppliers. Defend against direct-to-practitioner digital scanning networks by embedding field clinical specialists within Australian and South Korean practices to tighten switching costs. For New Entrants and Emerging Players: Differentiate on regulatory agility by securing early CDSCO registration ahead of tightened import rules, targeting Maharashtra and Karnataka private clinic chains with localized inventory partnerships. Exploit Vietnam's underpenetrated chair density in Ho Chi Minh City and Hanoi through mobile dentistry deployments enabled by handheld wireless scanner miniaturization, bypassing fixed-chair infrastructure requirements. For Investors and Strategic Acquirers: ASEAN Medical Device Directive harmonization reshapes the acquisition landscape by reducing registration duplication costs across member states, improving scalability of regional platform investments. Target mid-cap consumables distributors with established Vietnamese and Indonesian inventory networks and technical service capabilities, as these assets compound value under unified conformity assessment pathways. Monitor divergence between national regulatory databases and harmonized directives as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Practitioner Channel Restructuring | Align Technology's clinical specialist deployment in Australia captures margin concentration previously held by independent dental laboratories. |
| Chairside CAD/CAM Integration | Dentsply Sirona's same-day crown production systems displace two-week laboratory turnaround in Japanese and Australian practices. |
| Biocompatible Resin Certification Investment | 3D printing surgical guide manufacturers securing PMDA Class II validation unlock Japanese market access ahead of unregistered competitors. |
| CDSCO Registration Pre-positioning | Domestic manufacturing capacity expansion in India accelerates as tightened import rules redirect procurement toward locally registered suppliers. |
| Mobile Dentistry Infrastructure Deployment | Handheld wireless scanner adoption enables provincial Vietnamese market penetration previously unreachable by fixed-chair networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dental equipment procurement managers, private clinic chain operators, biomedical engineers, and GPO contracts managers across Japan, Australia, India, and Vietnam; and secondary validation through PMDA medical device registration databases, CDSCO import compliance filings, hospital procurement tender records, and ASEAN medical device directive harmonization documents. Bottom-up installation base modeling for CAD/CAM units and implant procedure volumes triangulated against top-down market sizing from trade flow data and distributor revenue disclosures.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product type, end user, technology generation, and application, with regional regulatory clusters treated as distinct adoption pacing variables. CAGRs derived from procedure volume elasticity to disposable income growth in China's tier-two cities, chair expansion rates in Vietnamese private clinics, and substitution coefficients between clear aligner and fixed appliance orthodontic cases. Industry-specific forecast inputs incorporated sponge titanium price volatility indices and intraoral scanner replacement cycle compression from cart-mounted to handheld wireless form factors.
The analysis sits within stated boundaries; outcomes outside sustained CDSCO enforcement rigor, PMDA audit timeline stability, or ASEAN directive harmonization progress would require recalibration. Forecasts reflect documented assumptions regarding raw material supply concentration, regulatory pathway divergence, and technology adoption S-curves across market maturity tiers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental 3D Printing Market
Dental Devices
Surgical Dental Loupes and Camera Market
Dental Devices
Prophylaxis Pastes Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental Veneers Market
Dental Devices
Dental Sealants Market
Dental Devices
China Dental Devices Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Dental Braces Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Dental Autoclave Market
Dental Devices
Dental Implants and Abutment Systems Market