
 Global Restorative Dentistry Market | 2026-2036
Global Restorative Dentistry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Restorative Dentistry Market Foresight
Private clinics is unwinding volume concentration from academic institutes as chairside CAD/CAM adoption accelerates among independent practitioners. DENTSPLY SIRONA leverages its integrated imaging-to-milling ecosystem to dominate digital workflow installations across North America and Europe. Institut Straumann anchors the premium implant-abutment segment with its proprietary connection geometries and surgical protocol standardization. GC Corporation specializes in glass ionomer chemistry for pediatric and geriatric indications where moisture tolerance outweighs aesthetic demands.
Restorative dentistry encompasses the clinical discipline and material science of reconstructing damaged, decayed, or missing tooth structure through direct placement or laboratory-fabricated prostheses, requiring precise bond strength exceeding 20 MPa for posterior load-bearing applications and color stability within 2 Delta E units over service life. The field serves the dual purpose of restoring masticatory function and preventing secondary caries propagation at the restoration-tooth interface. Composite resin formulations command the largest product type revenue pool due to universal shade-matching versatility and incremental curing techniques, while dental ceramics segments capture disproportionate margin contribution from monolithic zirconia crown demand in anterior and posterior applications. CAD/CAM restorations within delivery mode represent the fastest structural expansion as intraoral scanner penetration crosses critical adoption thresholds in mid-sized practices.
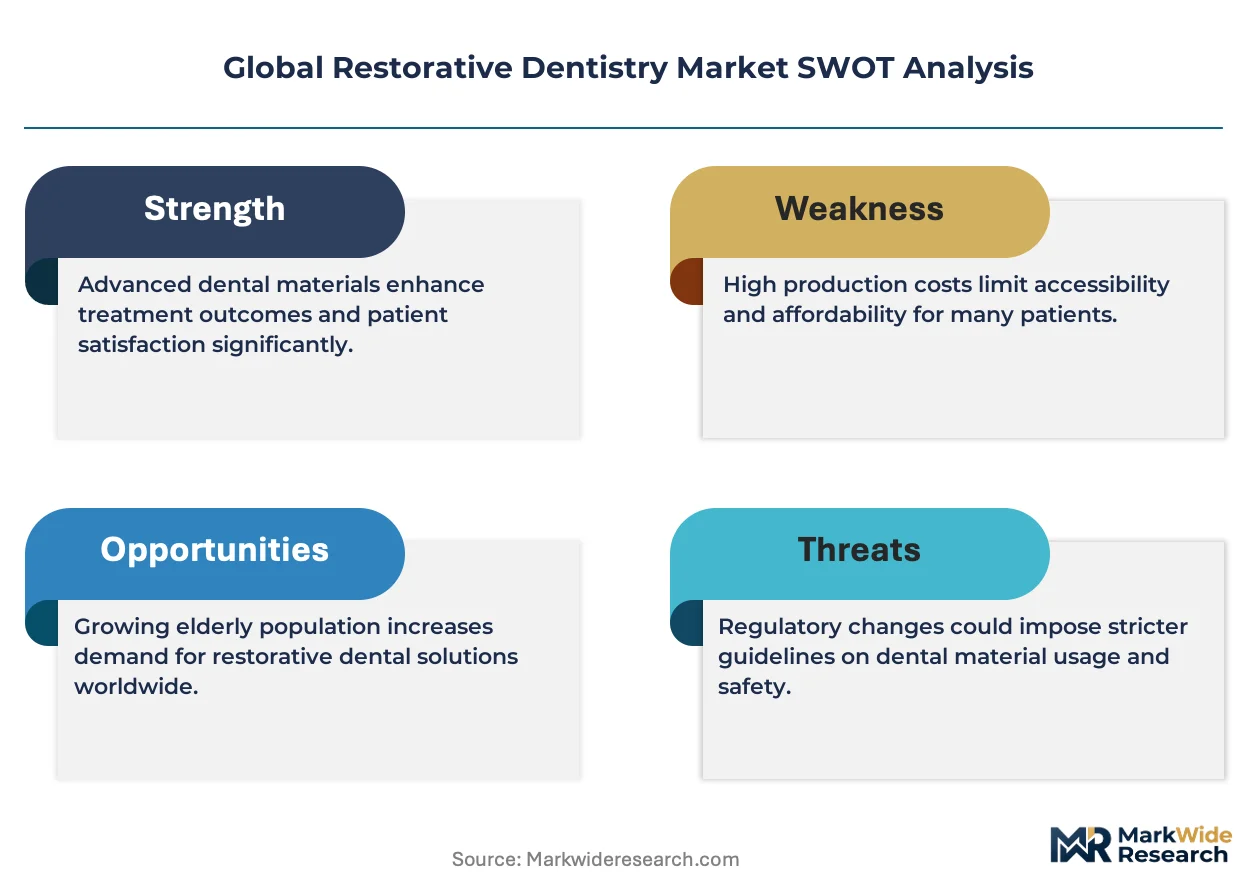
FDA 510(k) premarket notification requirements and EU MDR Class IIa reclassification for permanent filling materials are elevating biocompatibility testing burdens and clinical evidence thresholds for market authorization. ISO 10993 biological evaluation protocols and REACH substance restrictions on mercury-containing amalgam formulations are reshaping material portfolios toward resin-based and ceramic alternatives across manufacturing supply chains. Stakeholders must weigh capital deployment between chairside milling hardware and centralized laboratory networks as reimbursement polarization between public and private payers intensifies geographic profitability variance.
Market Dynamics
Chairside CAD/CAM adoption is compressing turnaround times from weeks to hours, forcing dental laboratories to recalibrate service models around same-day fabrication while manufacturers restructure hardware-software bundles for independent practitioners.
Growth Catalysts
- EU MDR Class IIa reclassification:Biocompatibility testing mandates for permanent filling materials are accelerating resin-based and ceramic formulation R&D across manufacturing supply chains.
- East Asia's aging patient base:Japan and South Korea's geriatric demographic concentration is expanding demand for moisture-tolerant glass ionomer restorations in institutional settings.
- Intraoral scanner penetration:Digital impression capture is displacing polyvinyl siloxane workflows in mid-sized North American practices, reducing remakes and patient chair time.
Market Restraints
- Capital intensity barrier:Chairside milling units and associated sintering ovens require six-figure USD deployment, constraining solo practitioner adoption outside fee-for-service markets.
- REACH substance restrictions:Mercury-containing amalgam phase-down timelines are forcing inventory write-downs and material substitution costs for laboratories with legacy stockpiles.
- Zirconia supply concentration:Sintered ceramic blank production clusters in Germany and Japan create geographic vulnerability to energy cost volatility and export licensing delays.
Strategic Opportunities
- Brazil's laboratory consolidation:São Paulo and Curitiba dental lab networks remain fragmented, creating acquisition targets for digital workflow integrators seeking Latin American scale.
- AI-powered shade matching:Machine learning algorithms paired with spectrophotometry are converging to reduce technician subjectivity in anterior ceramic fabrication.
- India's PLI scheme extension:Medical device manufacturing incentives cover precision milling burs and implant components, attracting contract manufacturers from Shenzhen and Seoul.
Industry Challenges
- CAD/CAM technician scarcity:Digital design proficiency with exocad and 3Shape platforms outpaces vocational training pipeline output in Germany and the United States.
- ISO 10993 certification timelines:Biological evaluation protocols for novel nano-hybrid composites extend regulatory approval cycles by 18-24 months versus legacy materials.
- Legacy PMS integration:Chairside scanners and mills require API connectivity with practice management software from Dentrix, Eaglesoft, and Open Dental, creating IT deployment friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Restorative Dentistry Market |
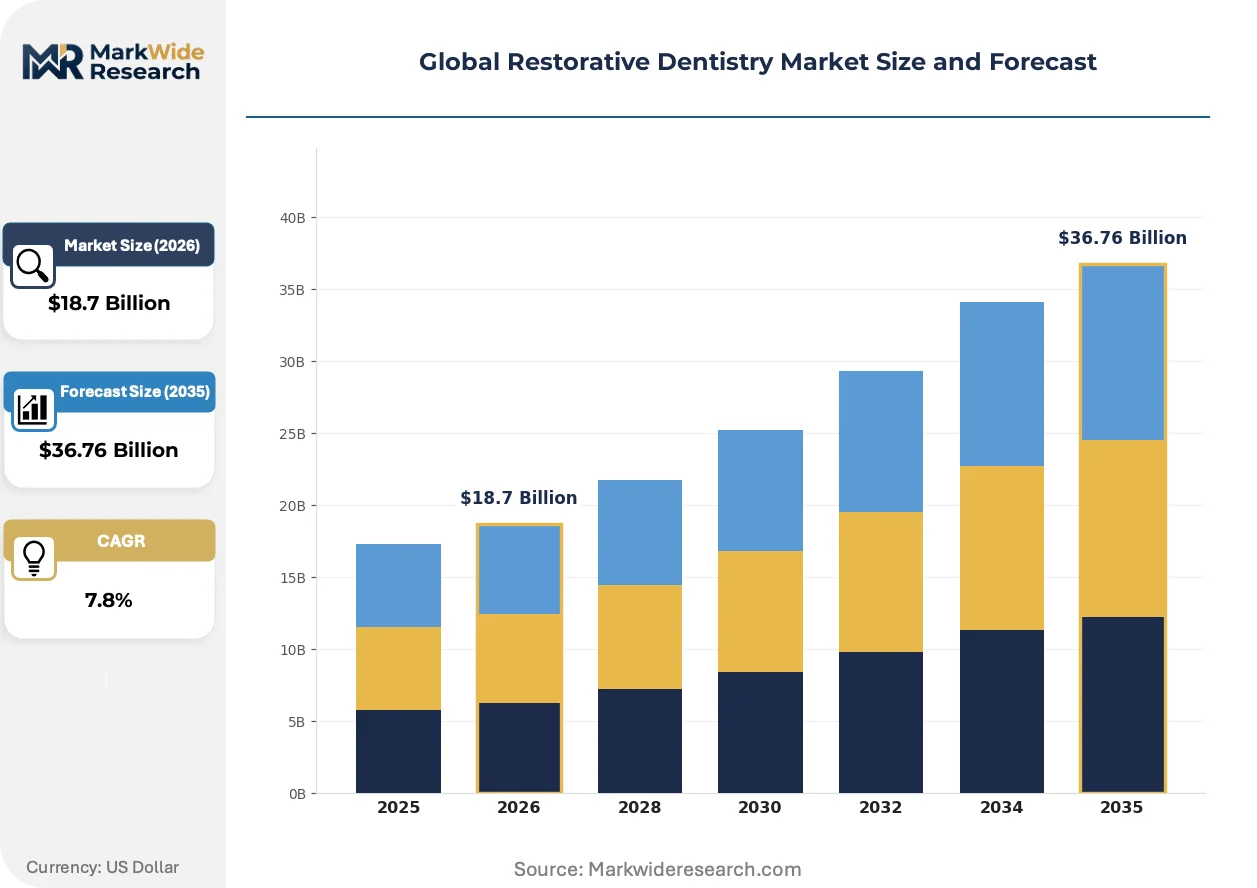
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Resin, Amalgam, Glass Ionomer Cement, Dental Ceramics, Resin-modified Glass Ionomer Application: Class I Restoration, Class II Restoration, Class III Restoration, Temporary Fillings, Core Build-up End User: Private Clinics, Dental Laboratories, Academic Institutes, Specialty Dental Centers, Community Health Centers Delivery Mode: Direct Restorations, Indirect Restorations, CAD/CAM Restorations, Shade Matching Systems, 3D Printing Solutions |
| Companies Covered | DENTSPLY SIRONA Inc., Envista Holdings Corporation, 3M Company, Ivoclar Vivadent AG, Institut Straumann, GC Corporation, Mitsui Chemicals, Septodont Holding, COLTENE Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Restorative Dentistry Market Shifts & Advancements
Workflow digitization is collapsing the traditional separation between clinical capture and laboratory fabrication, creating new competitive terrain around software ecosystems rather than standalone hardware.
Monolithic zirconia is decomposing the metal-ceramic crown segment through simplified fabrication protocols and reduced technician labor intensity. Independent practices in Texas and Florida are adopting these restorations at the fastest clip, compressing laboratory outsourcing volumes for posterior single units. The technology is decomposing margin structures for traditional porcelain-fused-to-metal suppliers while expanding addressable volume for chairside mills.
Japan's PMDA has tightened biocompatibility documentation requirements for imported dental ceramics, forcing foreign manufacturers to establish local clinical testing partnerships or cede shelf space to domestic suppliers. The industrial consequence is a bifurcation between premium global brands with regulatory infrastructure and mid-tier competitors exiting the market. German and Swiss ceramic houses are responding by acquiring Tokyo-based distributor networks to maintain compliance velocity.
Subscription-based software licensing is displacing perpetual purchase models for CAD design modules and milling control systems. Dental laboratories in Ontario and British Columbia are shifting from capital expenditure to operating expenditure accounting, reducing barrier-to-entry for smaller shops. This pattern is most visible in Canada's private-practice-heavy provinces where laboratory profit margins face pressure from in-office milling adoption.
Global Restorative Dentistry Market Segmentation
Segmentation in restorative dentistry tracks how material properties, clinical workflows, and reimbursement environments reshape procurement patterns. Each dimension reveals distinct margin pressures and technology adoption curves that manufacturers must navigate.
Product Type:
Margin pools concentrate in ceramic and nano-hybrid resin formulations where proprietary chemistry commands price premiums over commodity alternatives.
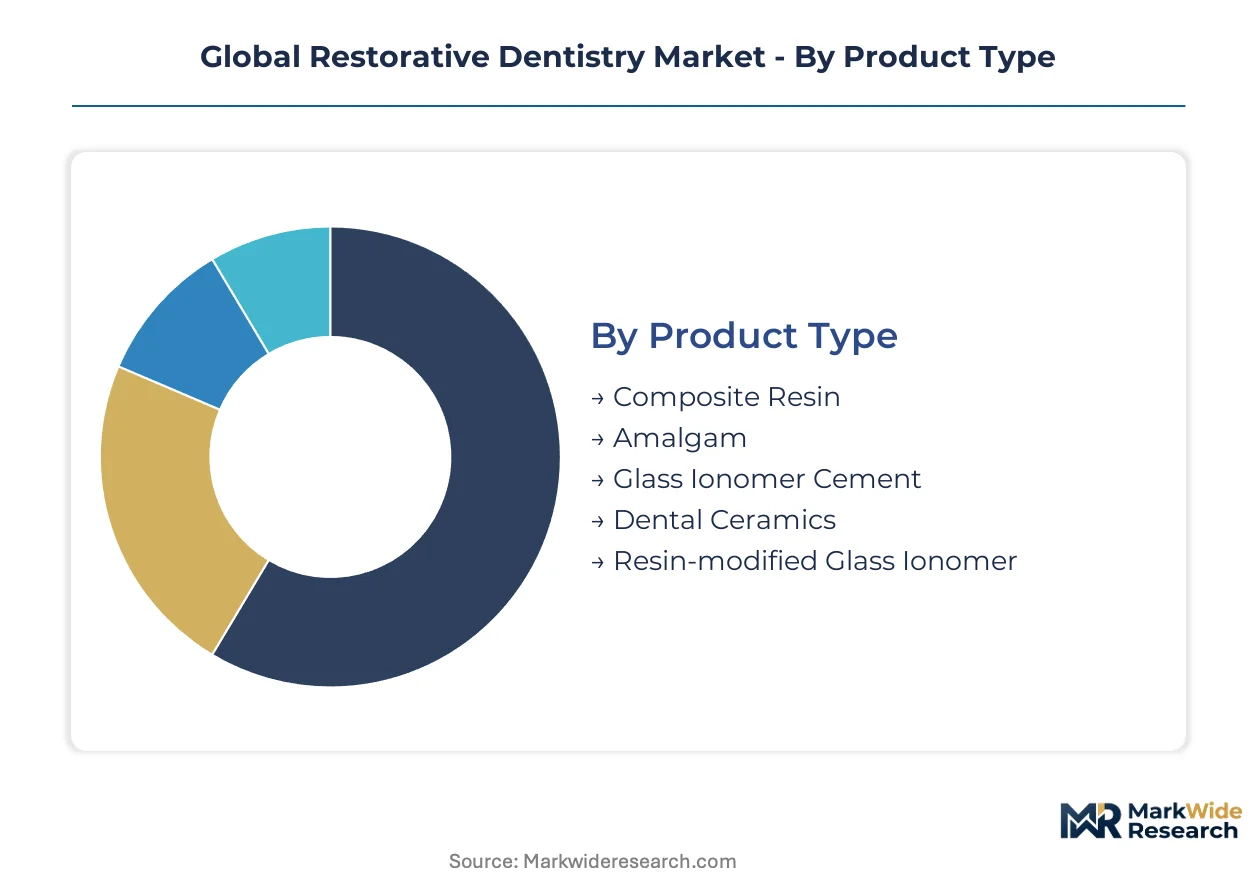
- Composite Resin:Nano-hybrid and bulk-fill formulations dominate anterior and posterior direct placements through incremental curing protocols and universal shade systems. Demand clusters in North American fee-for-service practices where chairside efficiency justifies material cost premiums over amalgam.
- Dental Ceramics:Monolithic zirconia and lithium disilicate blocks serve crown and bridge applications requiring flexural strength above 900 MPa and optical translucency matching natural dentition. German and Japanese milling centers are expanding sintered blank production to supply chairside CAD/CAM adoption in Texas and Florida.
- Amalgam:Mercury-containing alloy mixtures face REACH phase-down mandates across EU member states, forcing inventory transitions toward resin alternatives in institutional settings.
- Glass Ionomer Cement:Fluoroaluminosilicate chemistry provides moisture-tolerant adhesion for pediatric and geriatric indications in Japan's long-term care facilities.
- Resin-modified Glass Ionomer:Hybrid chemistry bridges aesthetic demands with chemical cure reliability for core build-up and provisional restorations.
The dominant share belongs to composite resin, while dental ceramics is closing the gap fastest.
Application:
Procedure volume distributes unevenly across cavity classifications, with posterior load-bearing applications driving material performance specifications.
- Class II Restoration:Proximal box preparations in posterior teeth require materials with compressive strength exceeding 300 MPa and marginal seal integrity against recurrent caries. North American private practices specify nano-hybrid composites or ceramic inlays depending on payer reimbursement differentials.
- Core Build-up:Foundation restorations for crown placement demand rapid set times and bond strengths compatible with subsequent adhesive cementation. Brazilian dental laboratories are expanding centralized fabrication of composite and glass ionomer cores for outsourced clinic delivery.
- Class I Restoration:Occlusal pit and fissure defects utilize flowable composites and sealants in pediatric and adolescent populations.
- Class III Restoration:Anterior proximal lesions prioritize aesthetic integration through microfilled composites and shade-matching protocols.
- Temporary Fillings:Interim zinc oxide-eugenol and temporary resin materials serve emergency and transitional care in community health settings.
Class II restoration commands procedure volume leadership, though core build-up is expanding most quickly through crown-and-bridge demand.
End User:
Capital deployment capacity separates customer tiers, with technology adoption rates diverging sharply between institutional and independent practice settings.
- Private Clinics:Independent practitioners in Ontario and British Columbia are acquiring intraoral scanners and chairside mills to compress restoration turnaround from laboratory outsourcing. Subscription software licensing is reducing capital barriers for CAD/CAM adoption among solo operators.
- Dental Laboratories:Centralized fabrication facilities in São Paulo and Curitiba are consolidating digital workflows around exocad and 3Shape design platforms to defend against in-office milling displacement.
- Academic Institutes:University clinics in Germany and Japan train operators on conventional techniques while gradually integrating digital impression systems into curricula.
- Specialty Dental Centers:Prosthodontic and aesthetic-focused practices concentrate ceramic and implant restoration volume requiring advanced shade-matching infrastructure.
- Community Health Centers:Publicly funded facilities prioritize cost-efficient glass ionomer and amalgam alternatives where reimbursement constraints limit material selection.
Private clinics hold installed base dominance, while dental laboratories are restructuring fastest to retain fabrication volume.
Delivery Mode:
Workflow digitization is collapsing traditional boundaries between clinical capture and laboratory production, creating new competitive terrain around software ecosystems.
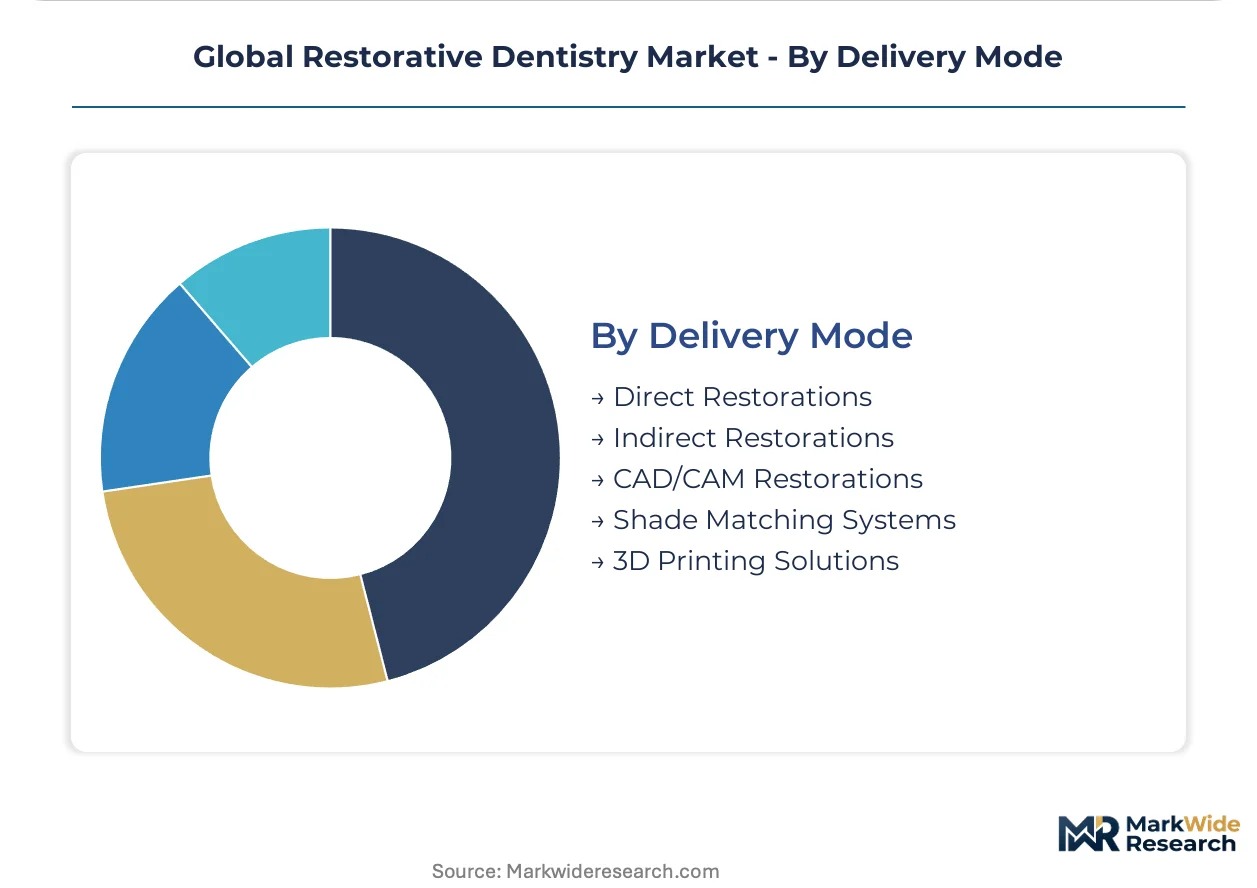
- CAD/CAM Restorations:Computer-aided design and milling systems integrate intraoral scanning, digital design, and automated fabrication into same-day delivery protocols. DENTSPLY SIRONA's imaging-to-milling ecosystem dominates North American and European installations among mid-sized practices crossing critical adoption thresholds.
- Direct Restorations:Chairside composite and amalgam placement remains volume-heavy in pediatric, emergency, and resource-constrained settings where capital equipment is unavailable.
- Indirect Restorations:Laboratory-fabricated crowns and inlays persist in complex aesthetic cases requiring technician artistry beyond current automated milling capabilities.
- Shade Matching Systems:Spectrophotometry and machine learning algorithms are reducing technician subjectivity in anterior ceramic fabrication.
- 3D Printing Solutions:Resin-based additive manufacturing is emerging for surgical guides, temporary restorations, and denture frameworks in specialized laboratory applications.
Direct restoration maintains procedure volume leadership, though CAD/CAM restorations are climbing the fastest as scanner penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fee-for-service private practices in the United States generate the highest per-procedure revenue for chairside CAD/CAM systems, while East Asian institutional settings prioritize moisture-tolerant materials for aging populations. Regulatory divergence between FDA 510(k) pathways and EU MDR compliance timelines is fragmenting product launch sequences across major markets.
United States
Independent practitioners in Texas and Florida are deploying intraoral scanners at the fastest clip, compressing laboratory outsourcing volumes for posterior single units. FDA 510(k) premarket notification requirements for biocompatible ceramics are elevating clinical evidence thresholds for market authorization. The Dallas-Fort Worth metroplex is emerging as a hub for same-day crown delivery, with mid-sized practices crossing critical digital adoption thresholds.
Germany
Dental laboratories in North Rhine-Westphalia are consolidating around exocad and 3Shape design platforms to defend fabrication volume against in-office milling displacement. EU MDR Class IIa reclassification for permanent filling materials is accelerating resin-based formulation R&D across manufacturing supply chains. The sintered ceramic blank production cluster around Stuttgart faces energy cost volatility pressures.
Japan
Long-term care facilities in the Kanto region are expanding glass ionomer procurement for geriatric indications where moisture tolerance outweighs aesthetic demands. PMDA has tightened biocompatibility documentation requirements for imported dental ceramics, forcing foreign manufacturers to establish local clinical testing partnerships. Tokyo-based distributor acquisitions by German ceramic houses are accelerating to maintain compliance velocity.
Brazil
Dental laboratory networks in São Paulo and Curitiba remain fragmented, creating acquisition targets for digital workflow integrators seeking Latin American scale. ANVISA regulatory frameworks for medical device manufacturing are aligning with international ISO standards to attract foreign capital. Brazilian dental laboratories are expanding centralized fabrication of composite cores for outsourced clinic delivery.
India
Medical device manufacturing incentives under the PLI scheme extension cover precision milling burs and implant components, attracting contract manufacturers from Shenzhen and Seoul. CDSCO is streamlining import licensing for intraoral scanners to accelerate digital adoption among urban private practitioners. The Maharashtra-Gujarat industrial corridor is seeing concentrated investment in dental consumables production.
Global Restorative Dentistry Market Competitive Landscape
Player mix skews toward diversified dental conglomerates with imaging-to-milling ecosystem control alongside specialized ceramic and implant-focused houses. Market structure concentrates around three strategic archetypes: integrated workflow providers bundling hardware-software-service, premium implant-abutment specialists with proprietary connection geometries, and regional material chemists dominating niche indications. Competitive dynamics center on M&A activity targeting laboratory network consolidation and strategic partnerships bridging chairside scanner penetration with centralized fabrication capacity.
Within the integrated workflow tier, DENTSPLY SIRONA Inc. and Envista Holdings Corporation represent the dominant imaging-to-milling ecosystem architects. Among specialized material houses, Ivoclar Vivadent AG exemplifies the premium ceramic segment, while Institut Straumann occupies a position anchoring the implant-abutment premium tier. GC Corporation sits within the regional chemistry specialist archetype, with its moisture-tolerant formulations serving pediatric and geriatric institutional demand clusters.
| Leading Market Players |
|---|
| DENTSPLY SIRONA Inc. |
| Envista Holdings Corporation |
| 3M Company |
| Ivoclar Vivadent AG |
| Institut Straumann |
| GC Corporation |
| Mitsui Chemicals |
| Septodont Holding |
| COLTENE Holding AG |
| Others |
Supply & Pricing Matrix
Capacity utilization at sintered ceramic blank facilities in Germany and Japan creates scale economies that simultaneously concentrate upstream supply and establish price floors for monolithic zirconia restorations. This dynamic forces mid-sized dental laboratories to absorb margin compression or exit posterior crown fabrication entirely.
Pricing Analysis
Cost-plus contracts with zirconia blank suppliers index to energy and rare earth oxide benchmarks, creating pass-through volatility that laboratories hedge through inventory pre-buying. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared biocompatible ceramics from CE-marked alternatives and unbranded commodity blanks. Pricing pressure stems from chairside CAD/CAM adoption compressing laboratory outsourcing volumes for single-unit posterior restorations. Fee-for-service private practices in Texas and Florida exhibit lowest price sensitivity due to reimbursement premiums, while community health centers in Ontario face severe material budget constraints.
Supply Chain Analysis
Inventory lead times for lithium disilicate and zirconia blanks extend 8-12 weeks from German and Japanese manufacturing clusters, creating working capital intensity for North American laboratories. Raw material dependencies center on yttria-stabilized zirconia powders, high-purity silica precursors, and precision-milled tungsten carbide burs. Single-source vulnerability concentrates in sintered ceramic blank production around Stuttgart and Nagoya, where energy cost volatility threatens supply continuity. Distribution runs through authorized dealer networks and direct laboratory relationships, with DENTSPLY SIRONA and Ivoclar Vivadent maintaining captive channel control over premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workflow digitization fragments competitive terrain into software ecosystems, hardware bundles, and pure-material supply, creating niche entry points for specialized players. The demand-side shift toward same-day delivery protocols splinters procurement authority between clinicians and laboratory technicians.
For Market Incumbents: Consolidate laboratory network acquisitions in São Paulo and Curitiba to defend fabrication volume against Brazilian chairside milling penetration. Deepen backward integration into sintered ceramic blank production to offset energy cost volatility and supply concentration risk in Germany and Japan. For New Entrants and Emerging Players: Differentiate on AI-powered shade matching algorithms that reduce technician subjectivity in anterior ceramic fabrication. Target India's PLI scheme corridor for precision milling bur contract manufacturing, leveraging medical device incentives to undercut established East Asian suppliers on implant component costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CAD/CAM software licensors with subscription pricing models, offering superior cash flow predictability versus capital equipment vendors. Over the projection horizon, acquisition targets should prioritize dental laboratories with exocad and 3Shape design proficiency in fragmented Latin American markets. The signal to watch is PMDA biocompatibility documentation tightening, which will force foreign ceramic manufacturers to establish local clinical testing partnerships or exit Japan entirely.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Network Consolidation | Acquisition of São Paulo and Curitiba facilities defends fabrication volume against chairside displacement. |
| Backward Integration into Ceramic Blanks | In-house sintered zirconia production insulates margin from German and Japanese energy cost volatility. |
| AI Shade Matching Development | Spectrophotometry algorithms reduce technician subjectivity in anterior ceramic fabrication workflows. |
| PLI Scheme Manufacturing Entry | India's medical device incentives attract precision milling bur production from Shenzhen and Seoul. |
| PMDA Compliance Infrastructure | Tokyo-based clinical testing partnerships maintain market access under tightened biocompatibility requirements. |
Research Methodology
A standing panel of prosthodontists, dental laboratory technicians, GPO contracts managers, and CAD/CAM platform engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, PMDA approval registries, and dental laboratory trade association procurement surveys. Bottom-up procedure volume estimates triangulated against top-down material consumption data from German and Japanese ceramic blank manufacturers.
Consistency checks validated volume and value outputs against intraoral scanner installation disclosures from DENTSPLY SIRONA and Envista Holdings, as well as reimbursement schedule filings from CMS and provincial health authorities across the analysis window. Segmentation modeling incorporated product type chemistry tiers, delivery mode workflow categories, end-user capital deployment capacity, and regional regulatory cluster divergence. CAGRs derived from logistic diffusion curves for digital adoption thresholds, calibrated to historical penetration patterns in Texas and Florida private practices.
Material uncertainties — EU MDR enforcement variance, REACH mercury amalgam phase-down acceleration, and zirconia supply disruption from energy cost shocks — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding scanner penetration rates and laboratory consolidation velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Dentures Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
CBCT Dental Imaging Market
Dental Devices
Global Periodontal Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Global Dental Turbine Market
Dental Devices
Dental Composite Resin Filling Market
Dental Devices
RFID-Enabled Dental Printing Market
Dental Devices
Dental Hand Tools Market