
 Global Dental Microscope Market | 2026-2036
Global Dental Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Microscope Market Foresight
Equipment leasing and pay-per-use financing is reconfiguring capital deployment across dental practices, enabling mid-tier clinics to access surgical-grade optics without upfront purchase burdens. Carl Zeiss AG leverages its precision optics heritage to dominate high-end trinocular configurations. Leica Microsystems anchors its position through integrated fluorescence modules for complex oral surgery workflows. Zumax Medical Co., Ltd. competes aggressively on cost-engineered binocular systems for emerging market clinics.
A dental microscope is a precision optical instrument employing apochromatic lens systems with magnification ranges typically spanning 2x to 30x, designed to provide stereoscopic visualization of oral structures during diagnostic and surgical procedures. LED illumination modules with color temperatures near 5600K now replace halogen sources, reducing thermal load on tissue while maintaining natural color rendering for accurate margin identification. Trinocular configurations command premium positioning due to integrated camera ports enabling real-time patient education and documentation. Digital zoom technology represents the fastest-expanding segment as practices adopt 4K video capture for teledentistry and training protocols.
FDA 510(k) clearance pathways govern surgical microscope marketing in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements on Class IIa optical devices. Japan's PMDA enforces JIS optical performance standards that effectively filter lower-grade imports from the Japanese market. China's NMPA has accelerated review timelines for domestically manufactured dental optics under innovation channel designations. Stakeholders must monitor regulatory divergence between major jurisdictions when configuring product portfolios and certification strategies.
Market Dynamics
Equipment leasing and pay-per-use financing is reconfiguring capital deployment across dental practices, enabling mid-tier clinics to access surgical-grade optics without upfront purchase burdens.
Growth Catalysts
- EU MDR Classification Pressure:Tighter clinical evidence requirements on Class IIa optical devices are accelerating replacement cycles as practices preempt compliance-driven obsolescence.
- Teledentistry Infrastructure:4K video capture protocols are expanding addressable demand beyond procedural suites into remote consultation and specialist referral networks.
- China's Tier-One City Concentration:Private dental chains in Shanghai, Beijing, and Guangzhou are standardizing magnification systems across multi-site portfolios.
Market Restraints
- Apochromatic Lens Input Costs:Precision optical glass and rare-earth coatings expose manufacturers to supply volatility from concentrated German and Japanese substrate suppliers.
- PMDA JIS Standards:Japan's optical performance requirements effectively filter lower-grade imports, compressing accessible market volume for cost-engineered entrants.
- LED Module Thermal Management:Color temperature stability near 5600K demands sophisticated heat dissipation engineering that elevates bill-of-materials complexity.
Strategic Opportunities
- India's Private Clinic Expansion:Metro and tier-two cities present underpenetrated demand for binocular configurations as disposable income rises and oral health awareness spreads.
- Fluorescence-Assisted Surgery Convergence:Integration of narrow-band imaging with standard magnification workflows opens premium positioning in oncologic and reconstructive oral procedures.
- NMPA Innovation Channel:China's accelerated review timelines for domestically manufactured optics reward localized production with faster market access versus import registration.
Industry Challenges
- Stereoscopic Calibration Expertise:Shortage of technicians trained in apochromatic lens alignment and coaxial illumination adjustment extends installation timelines and elevates service costs.
- FDA 510(k) Documentation Burden:Surgical microscope marketing clearance requires substantial predicate device analysis and clinical equivalence data that stretches regulatory timelines.
- Legacy Halogen System Integration:Practices with existing microscope infrastructure face compatibility friction when upgrading to LED illumination modules without full platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Microscope Market |
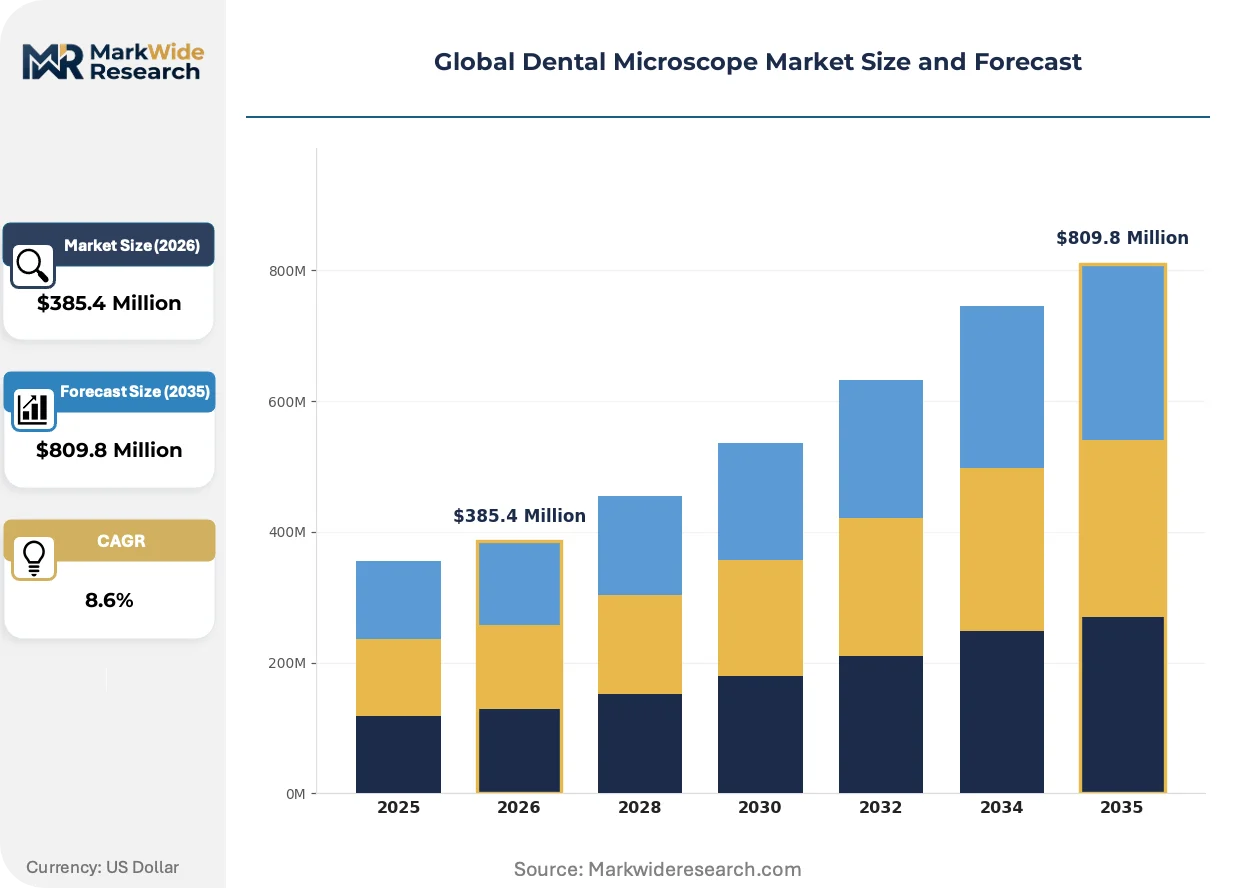
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $809.8 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Binocular, Trinocular, Quadruple, Wireless Technology: Optical Zoom, Digital Zoom, LED Illumination, Autofocus Application: Endodontics, Periodontics, Oral Surgery, Prosthodontics, Orthodontics End User: Private Clinics, Dental Laboratories, Academic Institutions, Specialty Centers |
| Companies Covered | Carl Zeiss AG, Leica Microsystems, Zumax Medical Co., Ltd., Global Surgical Corporation, Seiler Instrument, Karl Kaps GmbH & Co. KG, ARI Medical Technology Co., Ltd., Alltion (Wuzhou) Co., Ltd., Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Microscope Market Shifts & Advancements
Digital zoom technology is virtualizing traditional optical magnification architectures, compressing hardware differentiation while expanding software-defined feature sets across price tiers.
4K video capture systems with integrated camera ports are virtualizing the documentation function previously served by standalone intraoral cameras and external imaging rigs. Specialty dental clinics in Germany and private chains across China's eastern seaboard are adopting these trinocular configurations at replacement-cycle velocity. The technology is virtualizing hardware boundaries between diagnostic and surgical workflows, enabling single-platform standardization that reduces capital duplication.
The EU Medical Device Regulation imposes stricter clinical evidence requirements on Class IIa optical devices than predecessor directives, elevating documentation burdens for manufacturers seeking CE marking. This regulatory friction is compressing vendor margins and extending product development timelines by twelve to eighteen months across European launch schedules. Surgical-grade configurations with integrated fluorescence modules face the steepest compliance costs, pushing vendors to concentrate MDR investment on premium SKUs while maintaining legacy certifications for standard binocular systems.
Service unbundling is fragmenting traditional capital-equipment procurement into componentized financing, maintenance, and upgrade subscriptions. Mid-tier clinics in the United States and United Kingdom are displacing upfront purchase models with operating-lease structures that bundle LED module refresh cycles and software updates. This behavioral shift is most visible among dental service organizations managing multi-site portfolios, where standardization and predictable cash flow outweigh ownership economics.
Global Dental Microscope Market Segmentation
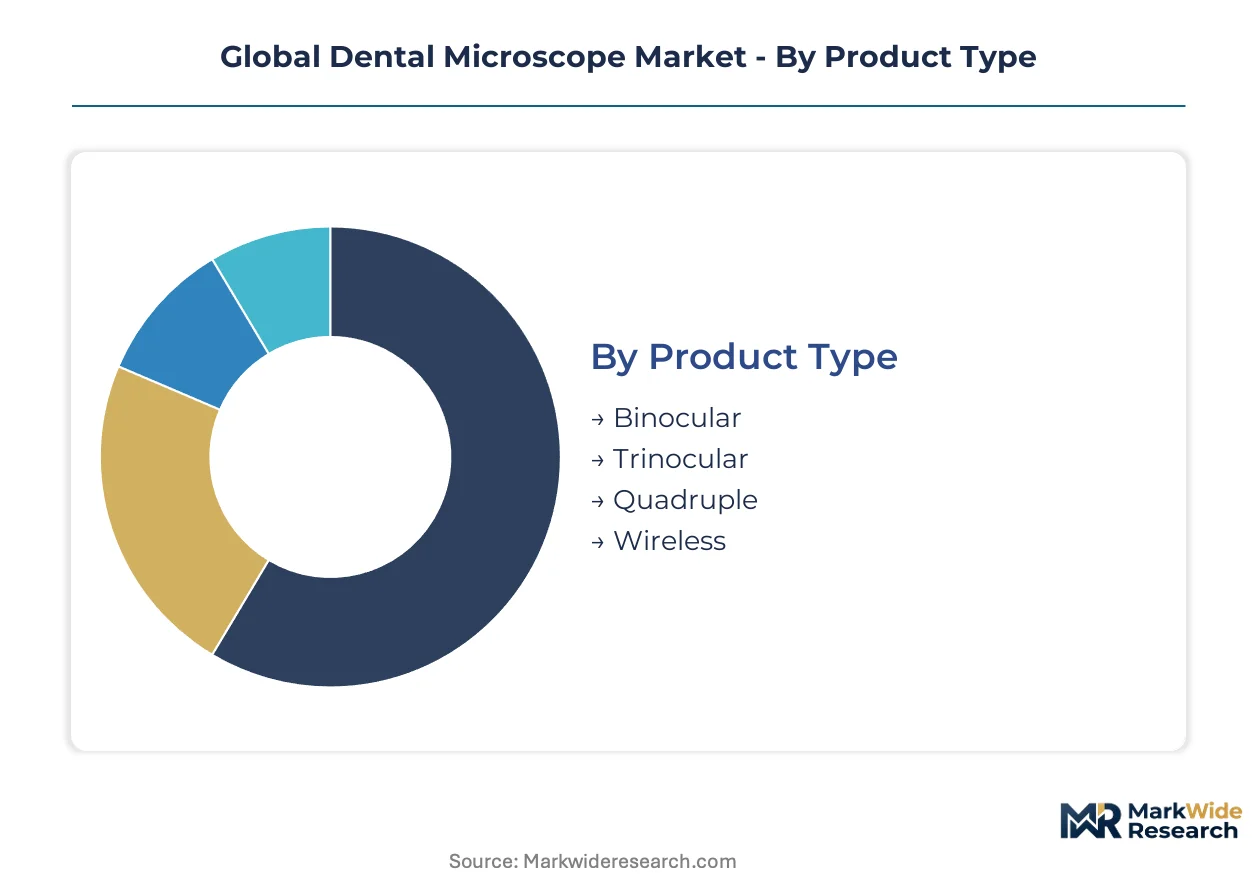
Product architecture and clinical workflow requirements fragment the dental microscope landscape into distinct purchasing cohorts. Trinocular configurations command premium positioning through integrated imaging, while digital zoom technology is virtualizing traditional optical architectures. Understanding segment boundaries illuminates where capital deployment concentrates and which specifications drive replacement cycles.
Product Type:
Cost tier stratification separates entry-level binocular systems from surgical-grade configurations with integrated documentation ports.
- Binocular:Dual-eyepiece optical paths with fixed or variable magnification from 2x to 20x serve routine diagnostic and basic restorative procedures. Demand concentrates in India's tier-two cities and Southeast Asian private clinics where capital constraints favor proven optical architectures over documentation capability.
- Trinocular:Three-port designs incorporating a dedicated camera channel enable 4K video capture for teledentistry and patient education workflows. Germany's specialty endodontic clinics and China's Shanghai-Beijing-Guangzhou private chains are standardizing these configurations across multi-site portfolios.
- Quadruple:Four-port architectures support simultaneous assistant observation and dual-camera documentation for complex surgical workflows.
- Wireless:Battery-powered mobility variants with reduced cable management target field dentistry and temporary clinic setups.
Trinocular systems hold installed capacity in developed markets. Binocular configurations are rotating up the share rankings in emerging economies.
Technology:
Application intensity varies by procedural complexity, with autofocus and fluorescence integration commanding surgical premiums.
- Optical Zoom:Mechanical lens systems with apochromatic correction maintain image fidelity across magnification ranges. Japan's PMDA JIS standards filter lower-grade imports, preserving market access for precision-engineered German and Japanese optical assemblies.
- Digital Zoom:Sensor-based magnification with software interpolation compresses hardware differentiation while expanding feature configurability. China's NMPA innovation channel is accelerating domestic manufacturer access for these virtualized architectures.
- LED Illumination:Solid-state sources near 5600K color temperature reduce thermal tissue load versus legacy halogen.
- Autofocus:Motorized lens positioning with depth-tracking algorithms maintains focal plane during dynamic surgical manipulation.
Optical zoom maintains procedural reliability in critical applications. Digital zoom is climbing the fastest in replacement-cycle velocity.
Application:
Customer type alignment maps magnification requirements to procedural reimbursement economics and litigation exposure.
- Endodontics:Canal negotiation and apex location demand 10x to 25x magnification with coaxial illumination for visualization of calcified anatomy. Germany's statutory insurance reimbursement for microscope-assisted retreatment is standardizing adoption across specialty clinics.
- Oral Surgery:Oncologic and reconstructive procedures require fluorescence module integration for margin assessment. China's tier-one private chains are deploying these configurations for implantology and soft-tissue management.
- Periodontics:Subgingival defect visualization drives demand for periodontal pocket illumination systems.
- Prosthodontics:Margin identification and occlusal adjustment utilize moderate magnification with natural color rendering.
- Orthodontics:Indirect bonding and bracket positioning employ lower magnification ranges with wide field-of-view optics.
Endodontics anchors installed base concentration. Oral surgery is gaining share fastest through fluorescence convergence.
End User:
Volume concentration and procurement sophistication separate institutional purchasers from individual practice owners.
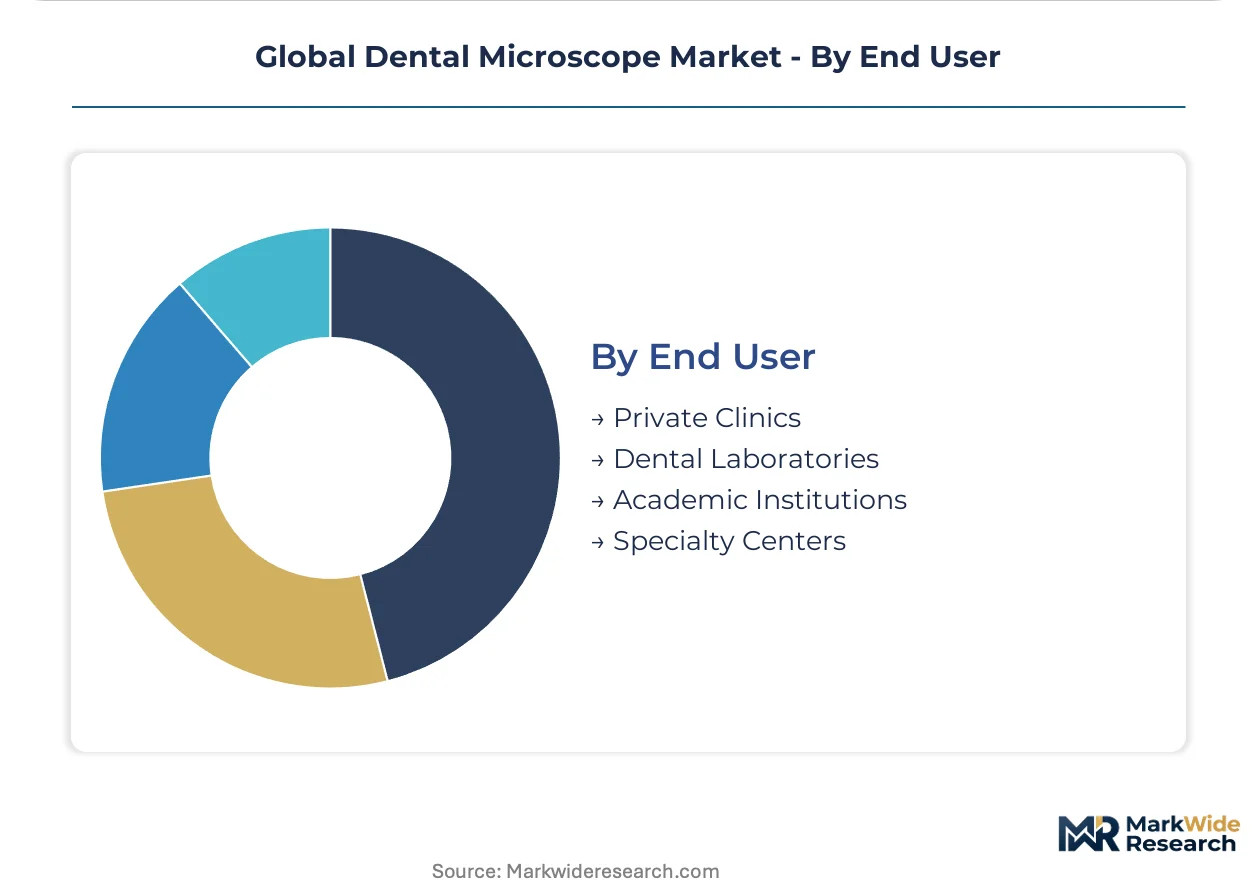
- Private Clinics:Solo and group practices drive replacement-cycle velocity through equipment leasing and pay-per-use financing structures. The United Kingdom's dental service organizations are standardizing LED-illuminated trinocular systems across multi-site portfolios.
- Specialty Centers:Concentrated endodontic and oral surgery facilities demand surgical-grade configurations with integrated documentation. Japan's university-affiliated specialty hospitals enforce JIS optical performance standards that elevate procurement specifications.
- Dental Laboratories:Benchtop magnification for prosthetic fabrication employs cost-optimized binocular systems with reduced illumination requirements.
- Academic Institutions:Training programs require multiple student observation ports and video distribution infrastructure.
Private clinics hold installed capacity concentration. Specialty centers are rotating up the share rankings through procedure volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory insurance reimbursement for microscope-assisted endodontic retreatment is accelerating specialty clinic adoption across the country. China's NMPA innovation channel is compressing review timelines for domestically manufactured optics. Japan's PMDA enforces optical performance standards that preserve market access for precision-engineered assemblies.
United States
Dental service organizations are standardizing LED-illuminated trinocular systems across multi-site portfolios through operating-lease structures. FDA 510(k) clearance pathways govern surgical microscope marketing with substantial predicate device analysis requirements. The Southeast region, particularly Florida and Georgia, is witnessing concentrated private equity investment in dental practice consolidation that drives equipment standardization.
Germany
Specialty endodontic clinics are expanding magnification capabilities as statutory insurance reimbursement validates procedural economics. The EU Medical Device Regulation imposes stricter clinical evidence requirements on Class IIa optical devices than predecessor directives. Bavaria's university-affiliated dental hospitals are enforcing elevated procurement specifications that filter lower-grade optical imports.
China
Private dental chains in Shanghai, Beijing, and Guangzhou are standardizing magnification systems across multi-site portfolios as disposable income rises. The NMPA has accelerated review timelines for domestically manufactured dental optics under innovation channel designations. The Yangtze River Delta region is concentrating domestic manufacturing capacity for cost-engineered binocular configurations targeting tier-two city expansion.
Japan
University-affiliated specialty hospitals are enforcing JIS optical performance standards that effectively filter lower-grade imports from the market. The PMDA maintains rigorous enforcement of substrate quality and apochromatic correction specifications. The Kanto region surrounding Tokyo anchors premium-tier demand concentration for surgical-grade configurations with integrated documentation capability.
India
Metro and tier-two cities present underpenetrated demand for binocular configurations as oral health awareness spreads and private clinic investment accelerates. The country's national medical device regulator is harmonizing quality standards with international frameworks to facilitate import access while protecting domestic manufacturers. Maharashtra's Mumbai-Pune corridor is emerging as the primary concentration for dental equipment distribution and specialty training infrastructure.
Global Dental Microscope Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price bands defined by optical certification grade and documentation capability. The vendor base stratifies between precision-optics heritage firms, integrated-device conglomerates, and cost-engineered emerging-market specialists. Three archetypes dominate: apochromatic lens heritage players, fluorescence-integrated surgical platform builders, and volume-scale binocular manufacturers. M&A activity concentrates on fluorescence module technology access, while geographic expansion targets China's tier-one city private chains.
Within the precision-optics heritage tier, Carl Zeiss AG and Leica Microsystems occupy positions defined by trinocular configuration dominance and integrated fluorescence workflows. Zumax Medical Co., Ltd. exemplifies the cost-engineered specialist archetype competing on price-accessible binocular systems. These three companies collectively represent the strategic positioning spectrum: heritage premium positioning, integrated surgical platform depth, and emerging-market volume penetration.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Leica Microsystems |
| Zumax Medical Co., Ltd. |
| Global Surgical Corporation |
| Seiler Instrument |
| Karl Kaps GmbH & Co. KG |
| ARI Medical Technology Co., Ltd. |
| Alltion (Wuzhou) Co., Ltd. |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
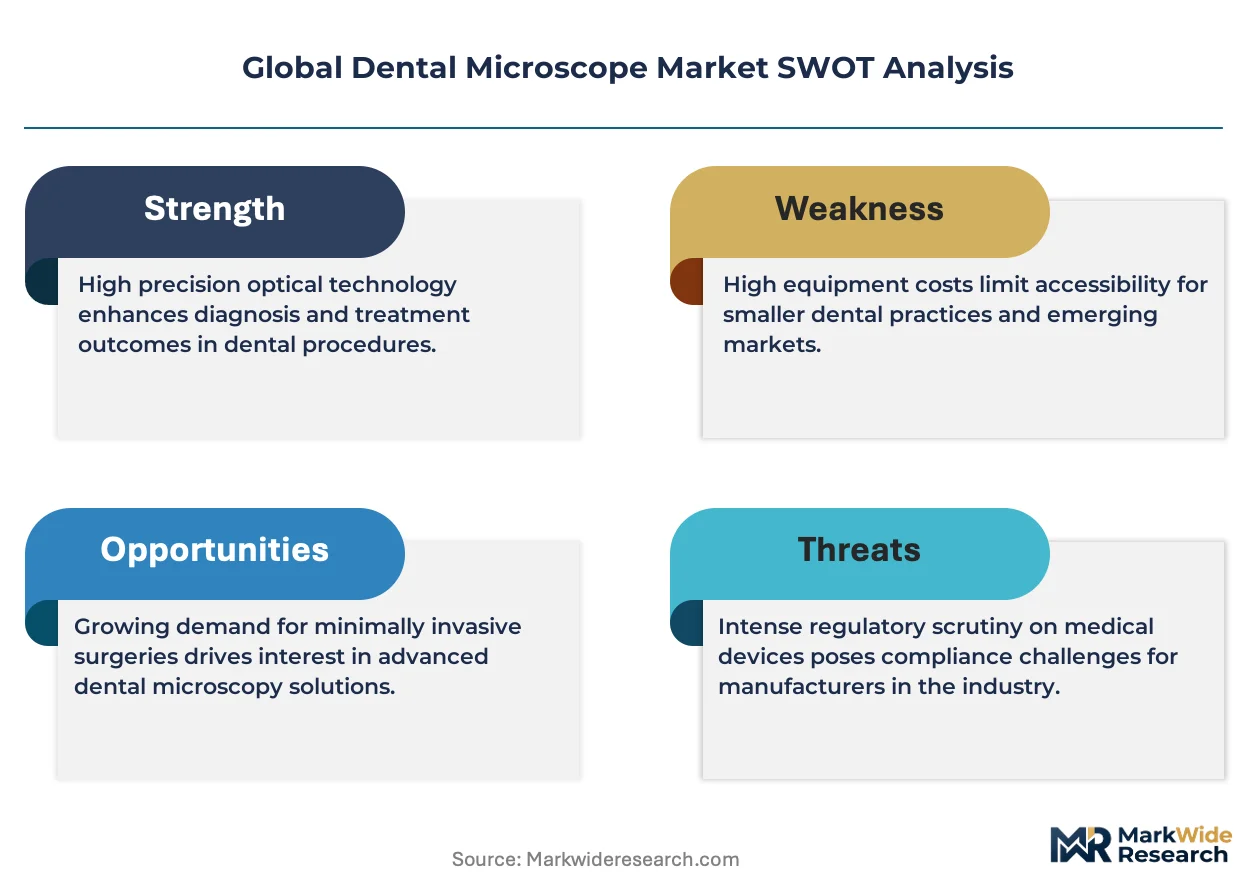
Single-source dependency on German and Japanese optical glass suppliers concentrates margin risk across all pricing tiers while compressing procurement flexibility for LED module manufacturers. This substrate bottleneck simultaneously widens spreads between CE-marked surgical-grade configurations and standard binocular systems while forcing assemblers to maintain dual-qualified vendor rosters.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between trinocular surgical platforms and entry-level binocular configurations. Three-tier pricing structure across premium, standard, and economy levels reflects apochromatic lens grade, fluorescence module integration, and bundled service intensity. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers exploit NMPA innovation channel accelerations. Price-sensitive tier-two clinics in India and Southeast Asia drive volume procurement of uncertified or self-certified alternatives, while Japanese university hospitals exhibit minimal price elasticity due to JIS-mandated performance floors.
Supply Chain Analysis
Precision optical glass feedstock concentrates in Germany and Japan, with rare-earth coating substrates sourced through concentrated Japanese chemical processors. LED die fabrication rests on Taiwanese and South Korean semiconductor foundries, while mechanical chassis components draw from China's Yangtze River Delta machining clusters. Single-source vulnerability in apochromatic lens blanks exposes assemblers to allocation risk during demand surges. Distribution runs through dental equipment distributors with regional service capabilities, though direct-to-clinic leasing platforms are fragmenting traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental microscope category is approaching a platform-economics inflection where software-defined digital zoom architectures decouple hardware value from optical heritage. Interoperability with teledentistry infrastructure and electronic health record systems is becoming the primary lock-in mechanism.
For Market Incumbents: Pre-empt fluorescence module commoditization by embedding narrow-band imaging algorithms into software-upgrade subscriptions rather than hardware SKUs. Deepen backward integration into LED thermal management subsystems to defend margin position against Chinese cost-engineered entrants. Anchor channel control through multi-site DSO leasing partnerships that bundle installation calibration and refresh cycles.
For New Entrants and Emerging Players: India's tier-two city private clinic expansion offers the most penetrable white-space for cost-optimized binocular configurations with localized service partnerships. Target China's NMPA innovation channel with domestic manufacturing joint ventures to compress regulatory timelines versus import registration. Deploy pay-per-use financing instruments to bypass capital-constrained clinic procurement committees.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fluorescence-integrated surgical platform builders with installed base density in German specialty clinics. Long-term viability hinges on software recurring revenue attachment rates rather than hardware shipment volumes. Monitor teledentistry reimbursement policy shifts as the primary inflection signal for documentation-capable trinocular demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Fluorescence Module Integration | Narrow-band imaging convergence opens premium positioning in oncologic oral surgery workflows. |
| Digital Zoom Platform Development | Software-defined architectures compress hardware differentiation while expanding feature configurability. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements filter lower-grade competitors from European market access. |
| Hospital System Partnership | DSO multi-site standardization agreements lock in replacement-cycle velocity and service revenue. |
| Reimbursement Strategy | Germany's statutory insurance validation for microscope-assisted retreatment anchors procedural economics. |
Research Methodology
A standing panel of endodontic specialists, oral surgeons, biomedical equipment procurement managers, and dental service organization operations directors provided ongoing calibration against clinical workflow realities. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, NMPA innovation channel designations, EU MDR notified body documentation, and hospital procurement database extracts. Bottom-up shipment modeling and top-down equipment spending allocation were triangulated against distributor inventory and leasing portfolio disclosures.
Scenario-bracketing around regulatory timeline uncertainty and LED substrate supply volatility framed the projection horizon. Segmentation dimensions spanned product architecture, illumination technology, procedural application, and end-user procurement sophistication. CAGRs were derived from installed base rotation rates and replacement-cycle compression observed across German specialty clinics and Chinese private chains. Forecast inputs incorporated teledentistry infrastructure buildout assumptions and reimbursement policy trajectories in key markets.
Practitioners should monitor NMPA review timeline announcements, EU MDR notified body capacity constraints, and LED thermal management patent litigation for early signals of forecast revision triggers. Cross-checking against dental equipment distributor inventory reports and DSO capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Microsurgery Market
Dental Devices
Dental Scalers Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Europe Dental Implants Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
North America Dental Lab Market
Dental Devices
Root Canal Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Orthodontic Wax Market
Dental Devices
Canada Dental Devices Market
Dental Devices
Malocclusion Market
Dental Devices
Dental Orthodontic Wax Market
Dental Devices
Dental Laboratories Market