
 Lights for Dental Healthcare Market | 2026-2036
Lights for Dental Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Lights for Dental Healthcare Market Foresight
Market Context
Germany is tilting toward higher-specification dental light production as regional precision engineering clusters deepen their medical device capabilities. A-dec Inc. leverages its vertically integrated manufacturing base in the Pacific Northwest to sustain consistent delivery of adjustable-intensity systems. Planmeca Oy anchors its competitive stance through R&D intensity focused on wireless-integrated dental operatory environments. Dentsply Sirona dominates the replacement parts and upgrade channel, controlling aftermarket revenue streams across mature installed bases.
Technical Definition and Segment Structure
Lights for dental healthcare are purpose-built illumination systems engineered to deliver color temperatures between 5000K and 6000K with color-rendering indices exceeding 90, enabling accurate shade matching and tissue differentiation during clinical procedures. These systems employ LED, halogen, or fiber-optic sources mounted on ceiling, wall, or mobile arm configurations to eliminate shadowing and reduce operator eye strain across extended treatment sessions. LED lights command the largest revenue share due to energy efficiency mandates and lumen maintenance advantages, while surgical lights represent the fastest-expanding category as outpatient oral surgery volumes rise. Fiber optic technology retains niche dominance in academic and research institutions where electromagnetic interference sensitivity dictates source separation.
Regulatory Environment and Outlook
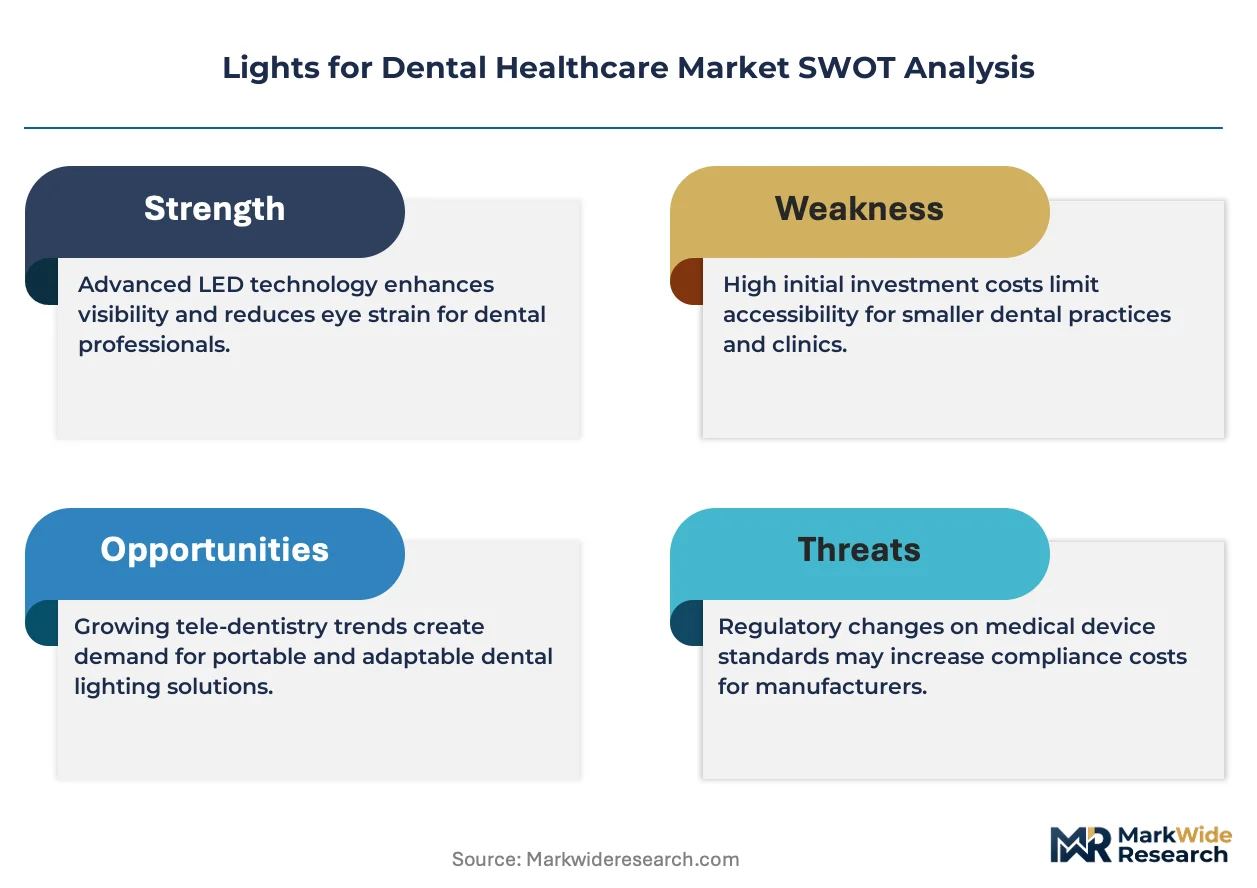
The FDA classifies dental operating lights as Class II medical devices under 21 CFR 892.1900, requiring 510(k) premarket notification for substantial equivalence demonstrations that shape product development timelines and design freeze decisions. CE marking under the EU Medical Device Regulation imposes additional biocompatibility and electrical safety testing burdens that filter smaller manufacturers from European market access. Stakeholders must monitor evolving IEC 60601-1-3 general lighting safety standards and national energy efficiency directives as these frameworks increasingly specify minimum luminous efficacy thresholds that could obsolete halogen product lines before natural replacement cycles conclude.
Market Dynamics
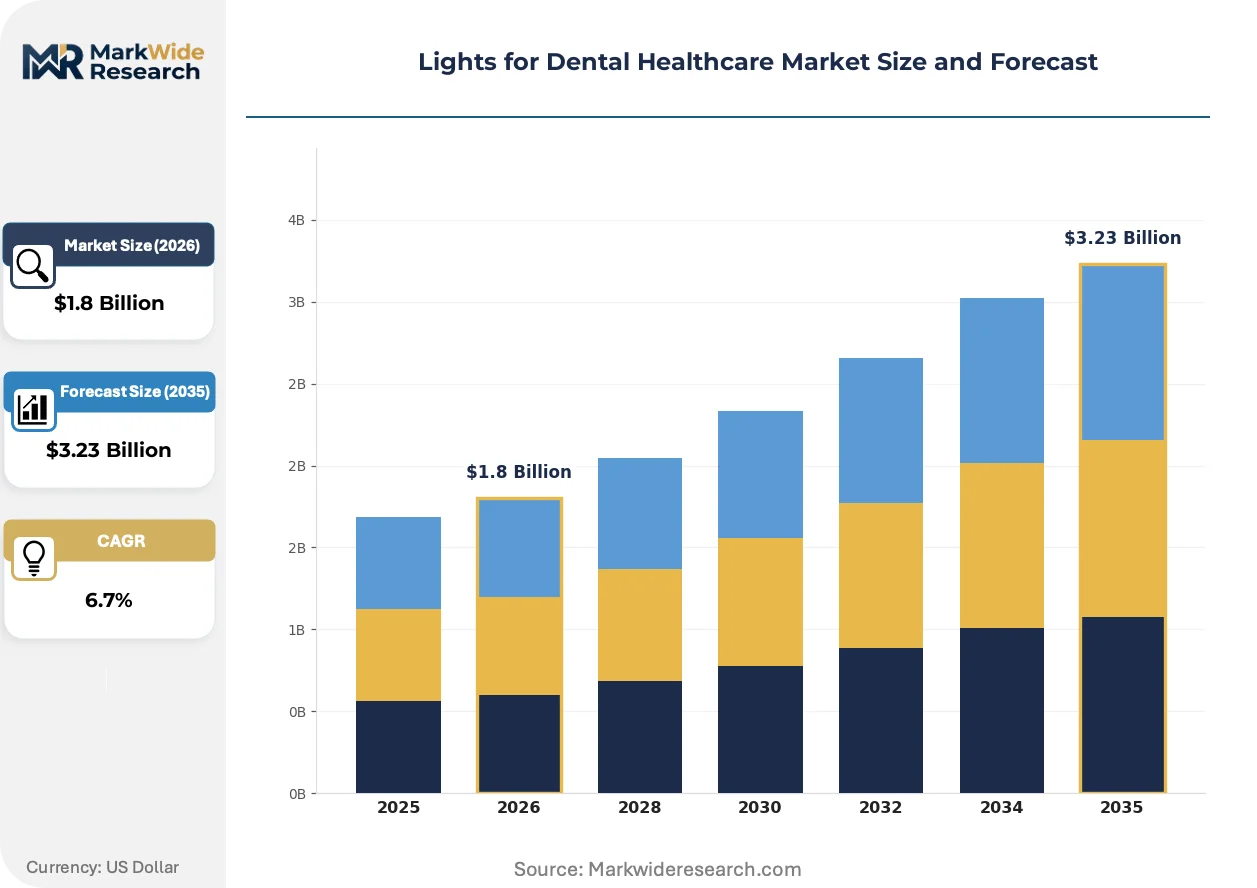
The LED transition is compressing replacement cycles as energy efficiency mandates and lumen degradation profiles reshape capital allocation across dental operatory construction and refurbishment projects.
Growth Catalysts
- FDA 510(k) pathway clarity:Streamlined substantial equivalence reviews for LED-based systems accelerate product introduction timelines. Manufacturers leverage predicate device databases to reduce regulatory friction.
- Outpatient oral surgery expansion:Ambulatory surgical centers in the United States deploy high-CRI surgical lights to support procedure migration from hospital settings. Facility accreditation standards drive specification upgrades.
- German precision manufacturing clusters:Concentrated supplier ecosystems around Stuttgart and Munich enable rapid prototyping of adjustable-arm configurations. Regional engineering talent pools shorten development cycles.
Market Restraints
- LED driver component concentration:Sourcing of high-reliability power electronics depends on limited Asian semiconductor foundry capacity. Supply disruptions propagate through finished goods lead times.
- Halogen obsolescence risk:National energy efficiency directives in multiple European markets mandate minimum luminous efficacy thresholds. Existing installed bases face premature replacement pressure.
- Biocompatibility testing burdens:EU MDR requirements for material safety documentation filter smaller manufacturers from CE marking access. Compliance costs concentrate market participation.
Strategic Opportunities
- Wireless-integrated operatory environments:Convergence of Bluetooth-enabled light controls with practice management software creates premium positioning. Early adopters in Nordic markets demonstrate workflow integration value.
- Academic research institution channel:Electromagnetic interference sensitivity in university dental schools sustains fiber optic niche demand. Specialized configurations command margin premiums.
- Aftermarket upgrade services:Unbundled retrofit kits for legacy armature systems address replacement part demand. Service contracts capture recurring revenue from mature installed bases.
Industry Challenges
- Color calibration technician scarcity:Accurate shade-matching system maintenance requires specialized optical training. Workforce gaps delay service response times in distributed markets.
- Legacy armature incompatibility:Mounting standard variations across decades of installed equipment complicate LED head retrofits. Integration engineering consumes development resources.
- 510(k) design freeze timelines:FDA notification review periods extend product launch windows. Competitive positioning erodes during regulatory hold periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lights for Dental Healthcare Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Halogen Lights, Surgical Lights, Exam Lights Technology: Wireless Technology, Fiber Optic, Battery-Operated, Adjustable Intensity Application: Orthodontics, Periodontics, Oral Surgery, General Dentistry End User: Dental Clinics, Hospitals, Research Institutions, Educational Institutions |
| Companies Covered | A-dec Inc., Planmeca Oy, Dentsply Sirona, DentalEZ, Midmark Corporation, Danaher Corporation, Flight Dental Systems, Dr. Mach GmbH, TPC Advanced Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lights for Dental Healthcare Market Shifts & Advancements
Illumination control architectures are fragmenting as wireless protocols and embedded sensors enable procedure-specific lighting profiles that override manual adjustment conventions.
Adaptive ambient compensation technology is migrating from high-end surgical suites to mid-market dental operatories. Hospital-affiliated dental departments in Germany and the United States pilot systems that automatically adjust intensity based on room luminance sensors. This capability compresses the specification gap between premium and standard product tiers.
EU MDR biocompatibility requirements are extending material documentation obligations to light housing polymers and cable sheathing. Manufacturers reformulate compound selections to satisfy cytotoxicity testing protocols. German notified bodies process the bulk of conformity assessments, creating geographic concentration in certification capacity.
Buying committees at dental service organizations now centralize equipment specification decisions across multi-site networks. Individual practitioner autonomy in light selection diminishes as procurement functions consolidate. This pattern is most visible in United States roll-up dentistry platforms where standardization reduces maintenance inventory complexity.
Lights for Dental Healthcare Market Segmentation
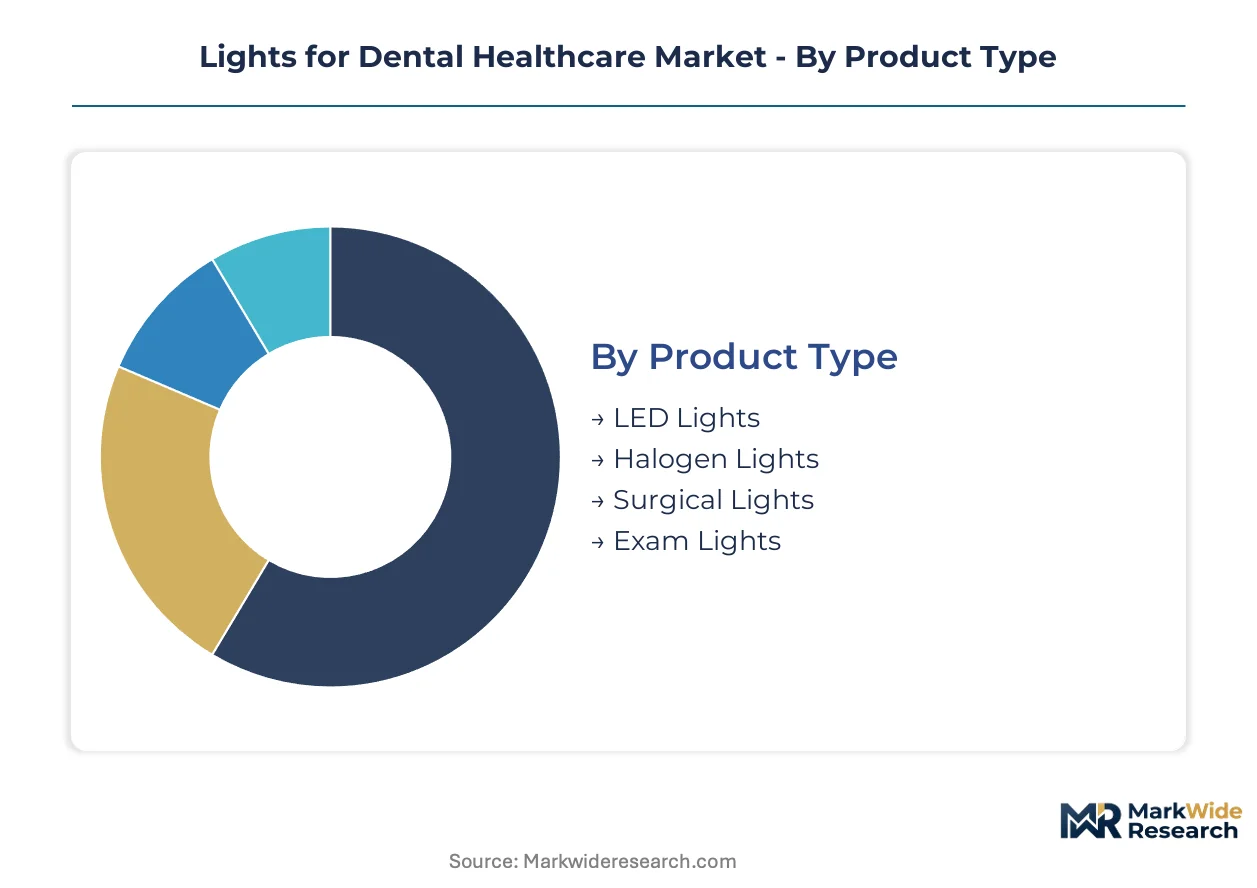
Segmentation in dental illumination reveals how clinical specialization, energy mandates, and procurement consolidation reshape product requirements. Each dimension exposes distinct specification pressures and channel access patterns.
Product Type:
Cost tier differentiation separates commodity replacements from premium surgical installations, with energy economics and procedure complexity driving specification divergence.
- LED Lights:Solid-state arrays deliver 5000K-6000K color temperature with CRI exceeding 90 and 50,000-hour operational lifespans. Dental clinics in Germany prioritize these systems as national efficiency directives accelerate halogen phase-outs.
- Halogen Lights:Tungsten-halogen sources maintain 3200K-3700K output with lower capital cost but higher energy draw and 2,000-hour lamp replacement cycles. Budget-constrained refurbishment projects in Eastern European markets sustain residual demand despite regulatory pressure.
- Surgical Lights:High-intensity configurations support oral surgery suites with shadow-free illumination fields exceeding 100,000 lux. Ambulatory surgical centers in the United States deploy these for procedure migration from hospital settings.
- Exam Lights:Compact mobile units serve diagnostic and hygiene appointments with adjustable gooseneck arms. Primary care dental networks standardize these for operatory flexibility.
LED lights command the established base. The steepest expansion runs through surgical lights.
Technology:
Application context determines which technical architecture delivers acceptable performance, with electromagnetic sensitivity and mobility requirements filtering viable options.
- Wireless Technology:Bluetooth-enabled control modules integrate with practice management software for preset procedure profiles. Nordic dental service organizations pilot these systems to reduce cable clutter and enable central equipment monitoring.
- Fiber Optic:Remote light source separation eliminates electromagnetic interference for MRI-compatible environments and sensitive research instrumentation. University dental schools in Germany and Japan retain this architecture for specialty research applications.
- Battery-Operated:Lithium-ion power systems support mobile field dentistry and temporary clinic setups without fixed electrical infrastructure. Humanitarian dental missions and military field hospitals specify these for deployment flexibility.
- Adjustable Intensity:Dimming circuits with 10%-100% range accommodate tissue photography, patient comfort, and operator eye strain reduction. Multi-disciplinary practices value this versatility across procedure types.
Fiber optic retains niche dominance in academic channels. Wireless integration gains share fastest among consolidated practice networks.
Application:
Procedure-specific optical demands create divergent requirements for color accuracy, intensity range, and shadow management across dental specialties.
- Oral Surgery:Deep-cavity illumination and hemostasis visibility demand surgical-grade intensity with coaxial lighting geometry. Hospital-affiliated dental departments in the United States expand dedicated surgical suite installations.
- General Dentistry:Restorative and preventive procedures require balanced CRI for shade matching without excessive capital outlay. Independent practitioners drive volume through replacement cycles.
- Orthodontics:Extended appointment durations and photographic documentation needs prioritize flicker-free output and consistent color temperature. Teen-focused practices invest in patient comfort features.
- Periodontics:Subgingival visibility and soft tissue differentiation demand precise angulation and high CRI. Specialized periodontal clinics specify premium armature systems.
General dentistry commands the established base. The steepest expansion runs through oral surgery.
End User:
Customer type determines procurement authority, specification sophistication, and service contract expectations across the installation base.
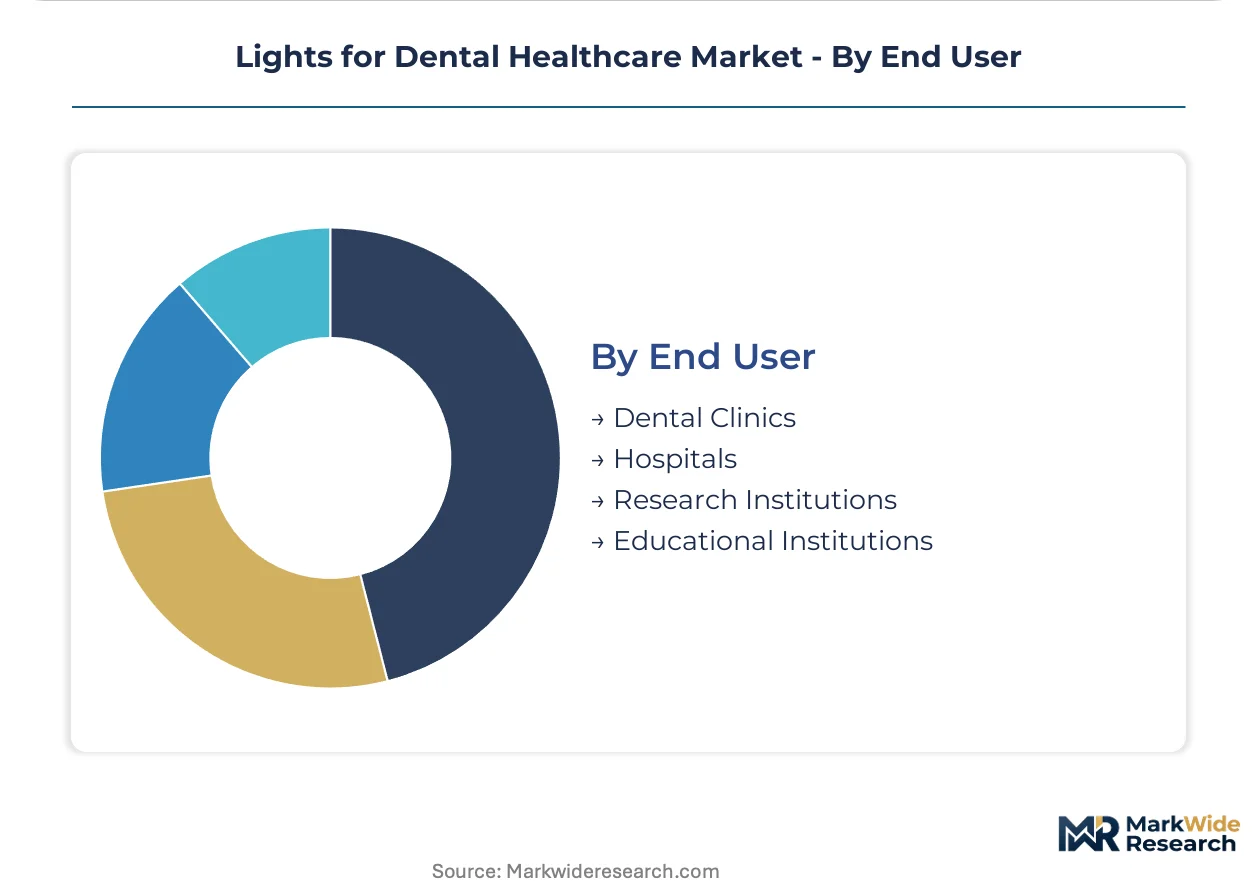
- Dental Clinics:Private practices and group practices balance capital constraints with clinical requirements. United States dental service organizations centralize purchasing across multi-site networks, reducing individual practitioner autonomy.
- Hospitals:Integrated health systems impose standardized specifications and preventive maintenance protocols. German hospital procurement departments favor CE-marked systems with established notified body relationships.
- Research Institutions:Electromagnetic compatibility and optical precision requirements override cost considerations. Fiber optic configurations command margin premiums in this channel.
- Educational Institutions:Dental schools require durable systems withstand intensive student use and curriculum rotation. Training programs prioritize adjustability and standardized controls across simulation laboratories.
Dental clinics command the established base. The steepest expansion runs through hospital-affiliated dental departments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision manufacturing clusters in southern Germany and the Pacific Northwest anchor supply capacity for high-specification dental illumination systems. Demand fragmentation across regulatory jurisdictions shapes divergent product requirements and certification strategies.
United States
Ambulatory surgical centers drive surgical light procurement as oral surgery migrates from hospital settings. The FDA's 510(k) pathway for Class II medical devices under 21 CFR 892.1900 governs market entry timelines. Newberg, Oregon hosts vertically integrated manufacturing for adjustable-intensity systems serving North American dental service organizations.
Germany
Replacement cycles in dental equipment and precision engineering capabilities concentrate demand for premium LED systems. EU MDR biocompatibility requirements filter smaller manufacturers from CE marking access. Stuttgart and Munich clusters enable rapid prototyping of adjustable-arm configurations through concentrated supplier ecosystems.
Japan
University dental schools sustain fiber optic niche demand for electromagnetic interference-sensitive research environments. METI energy efficiency directives accelerate halogen phase-outs in clinical settings. Tokyo and Osaka metropolitan areas concentrate procurement authority for multi-site dental chains.
China
Domestic dental clinic expansion drives volume demand for mid-tier LED operatory lighting. NMPA medical device registration requirements shape product localization strategies. Yangtze River Delta manufacturing bases supply LED driver components to finished goods assemblers.
United Kingdom
Consolidated dental service organizations centralize equipment specification decisions across multi-site networks. MHRA post-Brexit regulatory alignment with EU MDR standards maintains market access continuity. London and Southeast England procurement hubs standardize maintenance inventory for national roll-up platforms.
Lights for Dental Healthcare Market Competitive Landscape
Vertically integrated manufacturers and specialized dental equipment houses split the market between scale efficiency and clinical application depth. The vendor base concentrates around three strategic archetypes: Pacific Northwest-based integrated producers, Nordic wireless-technology specialists, and diversified dental consumables conglomerates with aftermarket service arms. Dominant competitive moves include backward integration into LED driver supply chains and geographic expansion through dental service organization procurement contracts.
Among North American integrated manufacturers, A-dec Inc. exemplifies the vertically integrated archetype through its Oregon-based production base. Planmeca Oy represents Nordic specialization in wireless-integrated operatory environments. Dentsply Sirona occupies a position as the diversified conglomerate archetype with established aftermarket revenue streams.
| Leading Market Players |
|---|
| A-dec Inc. |
| Planmeca Oy |
| Dentsply Sirona |
| DentalEZ |
| Midmark Corporation |
| Danaher Corporation |
| Flight Dental Systems |
| Dr. Mach GmbH |
| TPC Advanced Technology, Inc. |
| Others |
Supply & Pricing Matrix
Yangtze River Delta port congestion during LED driver component peak seasons amplifies cost differentials between premium German-engineered systems and mid-tier Asian assemblies. Freight volatility feeds directly into hospital procurement committee decisions that separate CE-marked surgical suites from budget clinic retrofits.
Pricing Analysis
The FDA's 510(k) substantial equivalence pathway dictates the pricing tier structure across North American dental illumination procurement. Three-tier pricing separates FDA-cleared surgical systems from standard operatory LEDs and economy-grade halogen replacements. Certification-grade differentiation and after-sales service bundling create the widest spreads. Pricing pressure stems from EU MDR biocompatibility testing cost pass-throughs. Budget-constrained Eastern European refurbishment projects show highest price sensitivity; German hospital-affiliated dental departments show lowest.
Supply Chain Analysis
Export control restrictions on high-reliability semiconductor manufacturing equipment limit LED driver foundry capacity expansion in China, Taiwan, and South Korea. German precision engineering clusters draw from captive aluminum extrusion and optical polymer compounding capabilities. Single-source vulnerability concentrates in Asian power electronics foundries. Distribution runs through dental equipment distributors with GPO contract relationships and direct hospital system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized optical calibration technician shortages constrain service response times across distributed markets, creating defendable advantage for firms with training infrastructure. This capability gap separates premium positioning from commodity competition.
For Market Incumbents: Build regulatory moats through FDA 510(k) predicate device libraries that accelerate competitor design freeze timelines. Deepen backward integration into LED driver supply chains to buffer Asian foundry concentration risks. Capture emerging entrant vulnerability to EU MDR biocompatibility documentation burdens by accelerating CE marking throughput at German notified bodies.
For New Entrants and Emerging Players: Build out wireless-integrated operatory environments for Nordic dental service organization pilot programs where cable clutter reduction commands premium positioning. Academic research institutions in Japan present the most penetrable fiber optic niche. Lead with Bluetooth-enabled control modules that integrate with practice management software workflows.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified dental equipment houses with established aftermarket service arms over pure-play illumination specialists. Five-to-ten year viability hinges on LED transition completion and halogen obsolescence capture. Watch fiber optic demand signals from university dental school capital expenditure cycles as inflection indicator for electromagnetic interference-sensitive research channel premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens design freeze timelines for LED surgical systems against predicate device databases. |
| CE Marking Pathway Investment | Secures German notified body relationships ahead of EU MDR biocompatibility documentation expansions. |
| Hospital System Partnership | Locks in ambulatory surgical center procurement for oral surgery migration from hospital settings. |
| Software Companion Development | Enables Bluetooth-enabled light control integration with practice management platforms. |
| Reimbursement Strategy | Aligns surgical light specifications with facility accreditation standards driving procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR conformity assessment records, and hospital procurement committee documentation. Clinicians, biomedical engineers, GPO contracts managers, and dental equipment distributors provided structured input. Bottom-up installation base modeling triangulates against top-down energy efficiency mandate impact assessments.
Forecast inputs span LED transition velocity, halogen replacement cycle compression, and outpatient oral surgery volume migration. Segmentation dimensions include product type, technology architecture, application specialty, and end-user procurement authority. CAGRs derive from replacement cycle analysis and capital expenditure pattern correlation across the projection horizon. German precision manufacturing cluster capacity and Asian semiconductor foundry utilization feed directly into supply-constrained scenario testing.
Stress conditions across LED driver component availability, EU MDR documentation timeline extensions, and ambulatory surgical center accreditation standard revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding energy efficiency directive enforcement intensity and wireless protocol adoption curves. Material shifts in FDA 510(k) review period duration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Dental Units Market
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
Dental Liners and Bases Market
Dental Devices
Dental Caries Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Dental Calipers Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Acrylic Teeth Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Malocclusion Market
Dental Devices
Asia-Pacific Dental Lab Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Chile Dental Market
Dental Devices
Endodontics and Orthodontics Market
Dental Devices
Dental Apex Locator Market