
 CBCT Dental Imaging Market | 2026-2036
CBCT Dental Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
CBCT Dental Imaging Market Analysis
The EU Medical Device Regulation is repositioning compliance burdens across European dental equipment procurement. Vatech Network leverages its manufacturing scale to maintain cost competitiveness in premium scanner categories. Dentsply Sirona Inc. anchors its position through deep software integration with chairside CAD/CAM workflows. J. Morita Mfg. Corp. specializes in compact-footprint systems tailored for urban clinic density in East Asian markets.
Cone beam computed tomography systems generate three-dimensional volumetric reconstructions from a rotating X-ray source and flat-panel detector, typically operating at 5-15 second scan times with voxel resolutions below 200 micrometers for osseous detail. The technology serves implant planning, orthodontic evaluation, and maxillofacial pathology examination through sub-millimeter accuracy in bone height and width measurement. Imaging Devices dominate capital expenditure flows while Software Solutions capture recurring revenue from treatment planning modules and cloud-based archival. Cone Beam Technology leads unit shipments among technology categories though Digital Radiography retains installed-base density in price-sensitive clinic tiers.
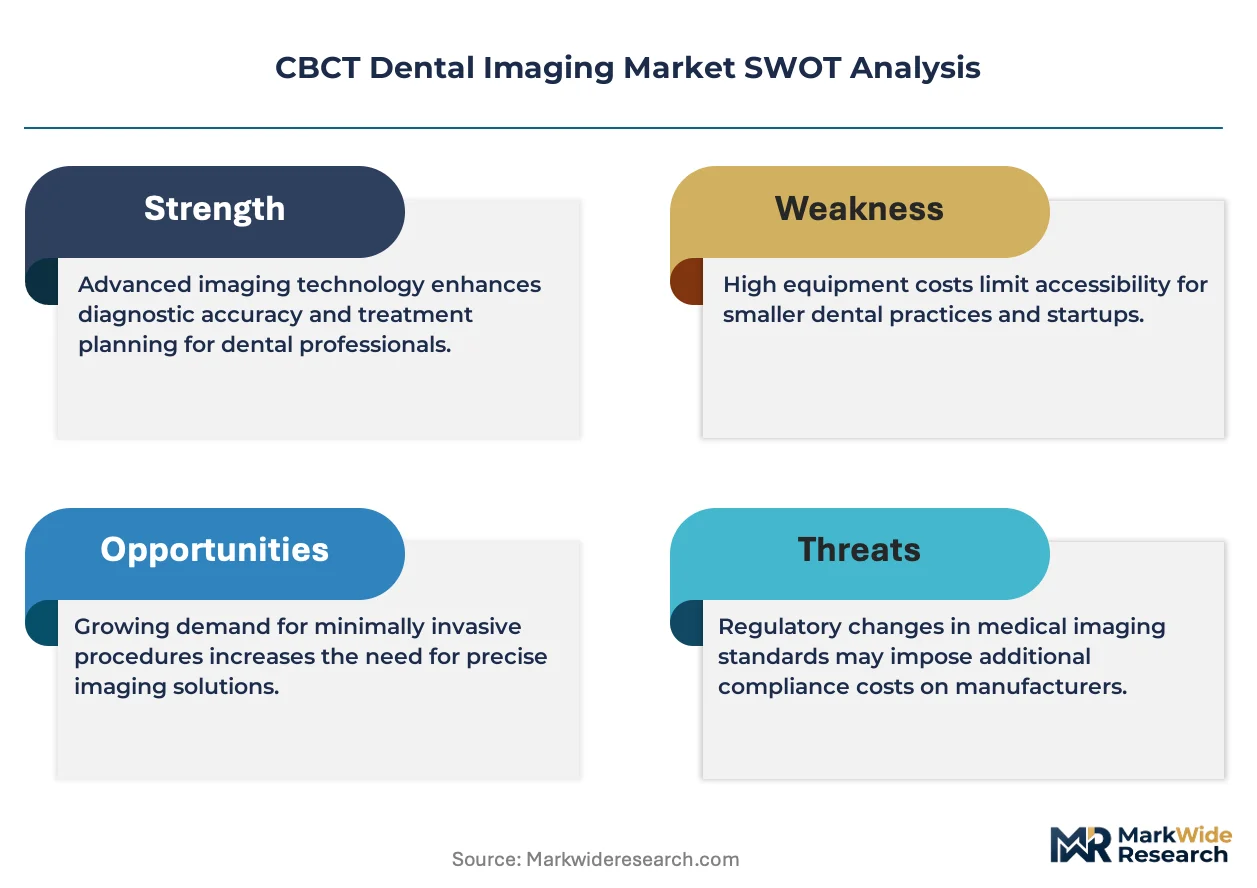
The FDA Center for Devices and Radiological Health enforces performance standards under 21 CFR 1020.32 for dental fluoroscopic equipment, shaping product design and submission pathways for US market access. CE marking under the EU MDR requires clinical evidence documentation that extends timelines for European commercialization. ISO 13485 quality management certification operates as a baseline procurement filter across OECD hospital systems and large dental service organizations. Stakeholders must weigh regulatory capital requirements against software subscription attach rates when evaluating platform economics.
Market Dynamics
Oral surgeons in Germany and the United States are driving capital rotation toward 3D volumetric systems as implant procedure complexity demands sub-millimeter bone mapping accuracy.
Growth Catalysts
- EU MDR Clinical Evidence Mandate:Device manufacturers must now compile robust clinical documentation for CE marking, elevating quality thresholds and filtering out marginal competitors across European procurement channels.
- Flat-Panel Detector Advances:Solid-state sensor technology is compressing scan times below 10 seconds while preserving voxel resolution under 200 micrometers for osseous detail.
- Urban Clinic Density:East Asian metropolitan markets favor compact-footprint systems that maximize floor-space efficiency in high-rent dental districts.
Market Restraints
- X-Ray Tube Supply Concentration:Specialty vacuum tube manufacturing clusters in Germany and Japan, creating single-source vulnerability for rotating anode assemblies.
- FDA 21 CFR 1020.32 Compliance Costs:Premarket notification pathways for fluoroscopic equipment require extensive performance testing that extends development timelines.
- Digital Radiography Substitute:Two-dimensional panoramic systems retain installed-base dominance in price-sensitive clinic tiers, delaying CBCT replacement cycles.
Strategic Opportunities
- Cloud-Based Archival Convergence:Treatment planning software is integrating with remote storage infrastructure to enable multi-site practice coordination and recurring subscription revenue.
- Orthodontic Evaluation Expansion:Clear aligner therapy workflows are creating demand for cephalometric analysis capabilities in general dentistry practices.
- India PLI Scheme:Production-linked incentives for medical device manufacturing are attracting assembly investment to serve South Asian price-optimized segments.
Industry Challenges
- ISO 13485 Certification Timeline:Quality management system audits for dental radiological equipment require 12-18 month implementation periods that delay market entry.
- CAD/CAM Integration Complexity:Chairside milling workflows demand seamless DICOM data exchange that legacy practice management systems struggle to accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBCT Dental Imaging Market |
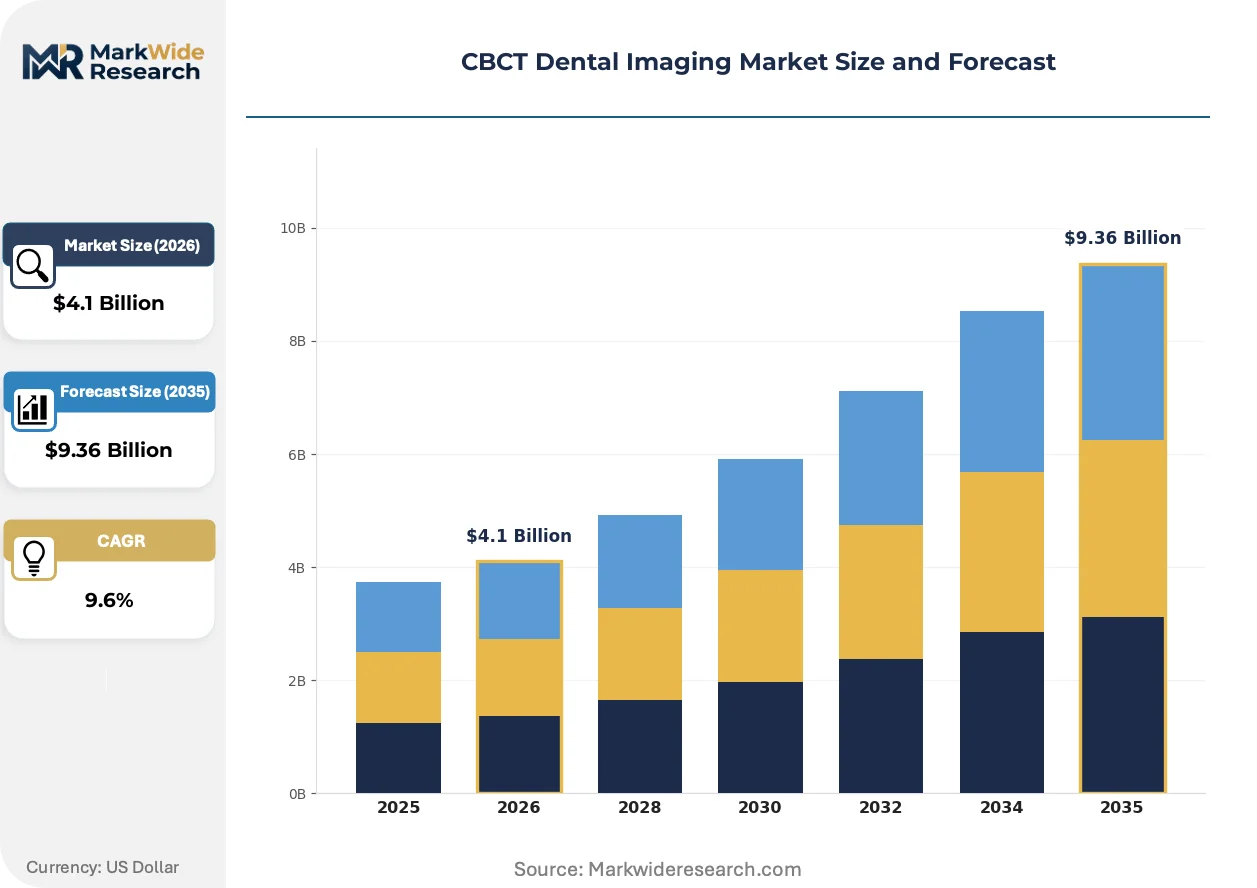
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $9.36 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Tomography, Software Solutions, Accessories, Imaging Devices End User: Dentists, Oral Surgeons, Orthodontists, Dental Clinics Technology: 2D Imaging, 3D Imaging, Digital Radiography, Cone Beam Technology Application: Implant Planning, Orthodontic Evaluation, Pathology Examination, Surgical Guide |
| Companies Covered | Vatech Network, Acteon Group, Dentsply Sirona Inc., J. Morita Mfg. Corp., Genoray Co Ltd, Carestream Health, KaVo Dental GmbH, Cefla s.c., Planmeca Oy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBCT Dental Imaging Market Emerging Trajectories
Software-defined imaging architectures are compressing hardware differentiation cycles while elevating algorithmic reconstruction as the primary value determinant in scanner procurement decisions.
Artificial intelligence reconstruction engines are integrating with raw projection data to reduce metal artifact interference and enhance soft-tissue contrast without dose escalation. Large dental service organizations in Germany are deploying these systems across consolidated clinic networks to standardize diagnostic output. The technology is integrating treatment planning modules directly into acquisition workflows, collapsing the traditional separation between imaging and case presentation software.
CE marking under the EU MDR is extending clinical evidence requirements to legacy device modifications that previously qualified for simplified review. Manufacturers must now compile post-market surveillance data and clinical evaluation reports for substantial equivalent determinations. Premium scanner categories face the longest documentation timelines, compressing European commercialization windows relative to FDA 510(k) pathways.
After-sales service contracts are unbundling from capital equipment sales as independent service organizations capture calibration and maintenance revenue. German dental clinic consolidations favor multi-year service agreements with guaranteed uptime clauses over traditional warranty structures. This shift concentrates recurring revenue with platform-agnostic service providers rather than original equipment manufacturers.
CBCT Dental Imaging Market Segmentation
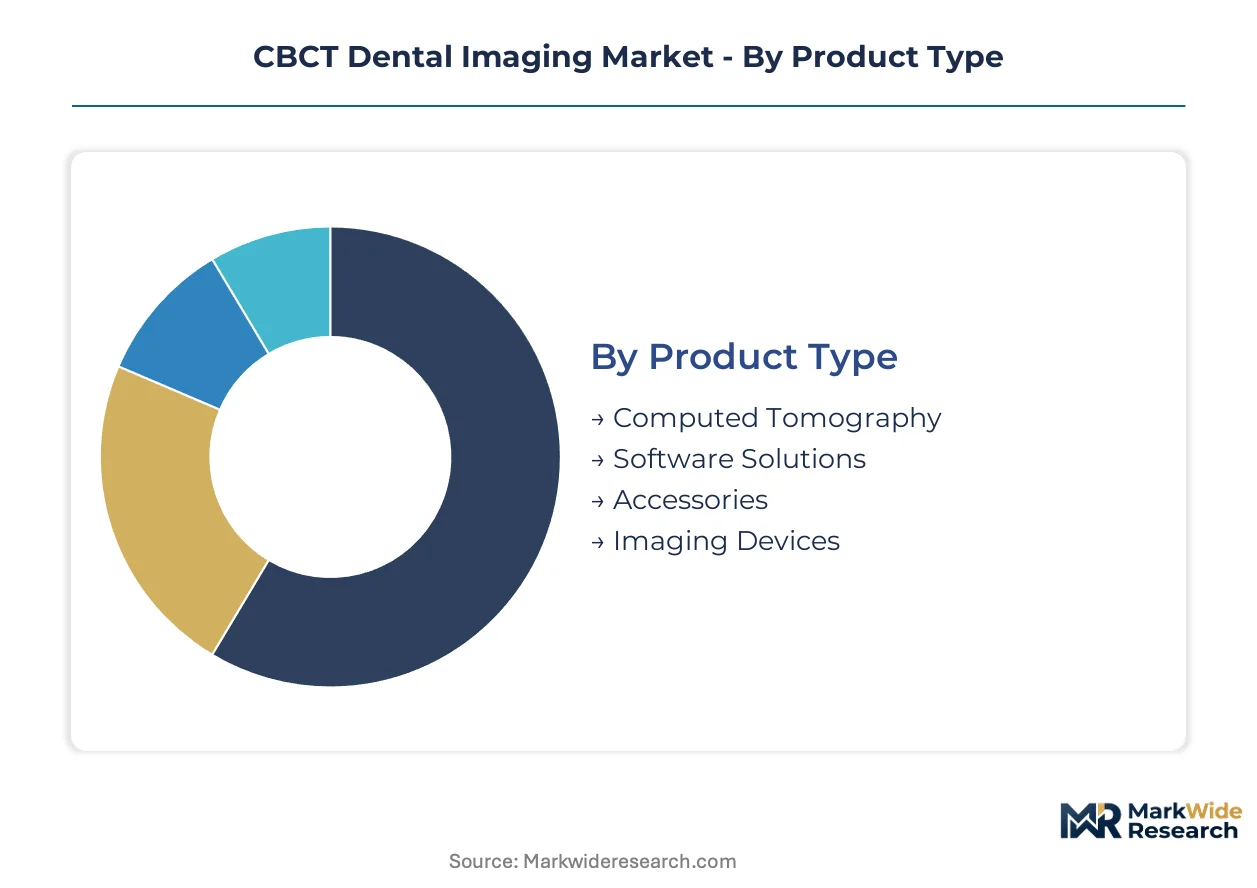
CBCT dental imaging segmentation reflects divergent capital deployment strategies across clinic tiers. Equipment manufacturers calibrate product portfolios across premium volumetric systems and price-accessible software modules. Procurement patterns split between large dental service organizations pursuing standardization and independent practices prioritizing flexible financing.
Product Type:
Customization intensity varies sharply across this category, from configurable software platforms to fixed-specification hardware units.
- Imaging Devices:Cone beam systems integrate rotating X-ray sources with flat-panel detectors for sub-200-micrometer voxel resolution. Oral surgeons in Germany and the United States drive replacement cycles as implant complexity demands three-dimensional bone mapping accuracy.
- Software Solutions:Treatment planning modules and cloud-based archival systems generate recurring subscription revenue through DICOM data management. Large dental service organizations favor multi-site coordination capabilities that collapse traditional gaps between acquisition and case presentation workflows.
- Computed Tomography:Hospital-grade systems with extended field-of-view capabilities serve maxillofacial pathology examination.
- Accessories:Positioning aids and bite indexes standardize patient alignment across repeated scans.
Leading the category by volume: Imaging Devices. Expanding most quickly: Software Solutions.
End User:
Customer concentration tilts toward procedure volume and reimbursement scale rather than clinic count.
- Oral Surgeons:Complex implant and maxillofacial procedures command the highest imaging specifications and capital budgets. German clinic consolidation accelerates equipment standardization across acquired practices.
- Dental Clinics:General dentistry settings balance cost constraints against clear aligner therapy workflows that now require cephalometric analysis capabilities.
- Dentists:Independent practitioners favor compact-footprint systems for urban floor-space efficiency.
- Orthodontists:Specialized practices prioritize low-dose protocols for repeated pediatric imaging.
Dental Clinics dominate unit shipments. Oral Surgeons capture the steepest equipment value per installation.
Technology:
Maturity gradients separate legacy installed bases from next-generation replacement cycles.
- Cone Beam Technology:Rotating gantry architectures with solid-state detectors compress scan times below 10 seconds while preserving diagnostic resolution. FDA 21 CFR 1020.32 compliance requirements shape submission pathways for US market access.
- Digital Radiography:Two-dimensional panoramic systems retain dominance in price-sensitive clinic tiers, delaying full CBCT replacement cycles despite inferior bone mapping precision.
- 3D Imaging:Volumetric reconstruction algorithms now integrate AI engines to reduce metal artifact interference without dose escalation.
- 2D Imaging:Legacy film and phosphor plate systems persist in emerging market segments with constrained capital availability.
Cone Beam Technology leads current unit shipments. 3D Imaging gains share fastest as algorithmic reconstruction elevates software-defined value.
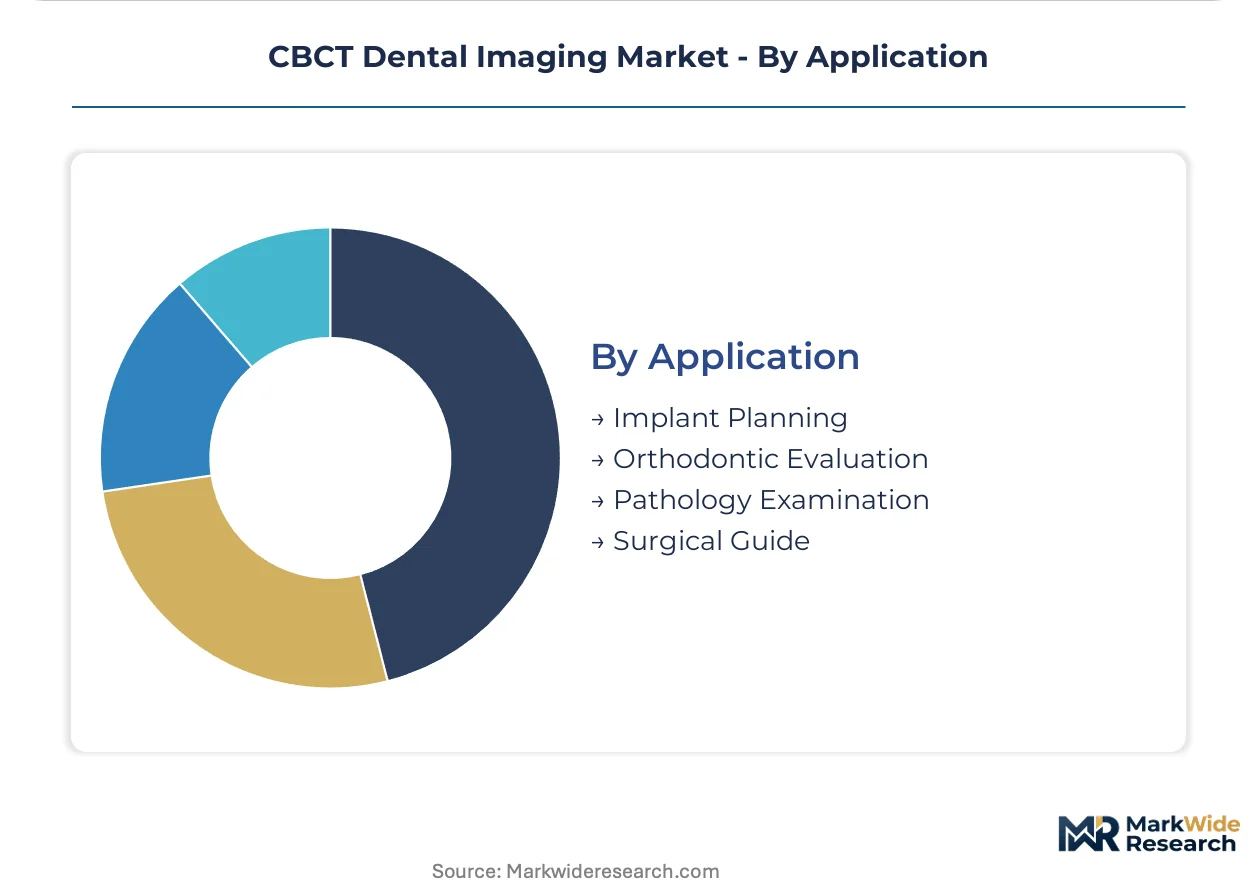
Application:
Reimbursement differentiation and procedure complexity stratify demand across use cases.
- Implant Planning:Sub-millimeter accuracy requirements for bone height and width measurement drive premium scanner specifications. CE marking under EU MDR extends clinical evidence timelines for European commercialization relative to FDA pathways.
- Orthodontic Evaluation:Clear aligner therapy expansion creates demand for cephalometric analysis in general dentistry settings previously served by 2D systems.
- Pathology Examination:Maxillofacial diagnostic workflows require extended field-of-view capabilities for tumor and trauma assessment.
- Surgical Guide:Chairside CAD/CAM integration demands seamless data exchange that legacy practice management systems struggle to accommodate.
Implant Planning commands the highest equipment value per procedure. Orthodontic Evaluation shows the fastest volume expansion as aligner therapy penetrates general practice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of CBCT systems concentrates in South Korea and Japan, while consumption tilts toward Germany and the United States where dental clinic consolidation accelerates equipment replacement cycles.
Germany
Dental clinic consolidation in Bavaria and North Rhine-Westphalia drives standardized equipment procurement across multi-site networks. The EU Medical Device Regulation extends clinical evidence timelines for CE marking, filtering marginal competitors from European commercialization. Stuttgart and Munich host precision manufacturing clusters for rotating anode assemblies used in premium scanner categories.
United States
Oral surgeons in Texas and Florida command premium capital budgets for complex implant procedures requiring sub-millimeter bone mapping accuracy. The FDA Center for Devices and Radiological Health enforces 21 CFR 1020.32 performance standards that shape submission pathways for fluoroscopic equipment. Greater Boston and the Research Triangle concentrate software development for AI reconstruction engines.
Japan
Urban clinic density in Tokyo and Osaka favors compact-footprint systems maximizing floor-space efficiency in high-rent dental districts. The Ministry of Economy, Trade and Industry (METI) supports medical device export promotion through JIS standards alignment. Nagoya and Kyoto house specialty vacuum tube manufacturing for rotating gantry architectures.
South Korea
Clear aligner therapy expansion in Seoul Capital Area creates demand for cephalometric analysis capabilities in general dentistry practices. The Ministry of Food and Drug Safety (MFDS) maintains streamlined approval pathways for software-defined imaging upgrades. Busan-Ulsan corridor concentrates flat-panel detector assembly operations serving export markets.
India
Price-optimized segments in Maharashtra and Gujarat attract assembly investment under the Production-Linked Incentive scheme for medical device manufacturing. The Central Drugs Standard Control Organization (CDSCO) harmonizes quality benchmarks with ISO 13485 certification requirements. Delhi-NCR emerges as a hub for cloud-based archival infrastructure serving multi-site practice coordination.
CBCT Dental Imaging Market Vendor Landscape
The competitive structure tilts toward diversified dental equipment conglomerates with software integration capabilities. Tiered positioning separates premium volumetric system manufacturers from price-accessible hardware specialists. Three archetypes dominate: full-platform integrators with CAD/CAM workflows, compact-footprint specialists for urban density, and component-scale manufacturers leveraging detector technology. Geographic expansion and strategic partnerships constitute the primary competitive moves, with M&A activity concentrating in software-defined imaging architectures.
Within the full-platform integrator tier, Dentsply Sirona Inc. and Planmeca Oy represent archetypal positioning through deep software-hardware convergence. KaVo Dental GmbH exemplifies German-engineered precision manufacturing for premium scanner categories. Vatech Network anchors the scale-driven segment with manufacturing breadth across detector and tube technologies. J. Morita Mfg. Corp. occupies a specialist position in compact-system design for East Asian metropolitan markets.
| Leading Market Players |
|---|
| Vatech Network |
| Acteon Group |
| Dentsply Sirona Inc. |
| J. Morita Mfg. Corp. |
| Genoray Co Ltd |
| Carestream Health |
| KaVo Dental GmbH |
| Cefla s.c. |
| Planmeca Oy |
| Others |
Supply Flow & Price Mechanics
Large dental service organizations in Germany and the United States concentrate procurement volumes and negotiate multi-year service agreements with guaranteed uptime clauses, shifting pricing power toward buyers who standardize across consolidated clinic networks.
Pricing Analysis
Pricing pressure intensifies in premium scanner categories as CE marking under the EU MDR extends clinical evidence timelines and elevates compliance costs that manufacturers must absorb or pass through. Three-tier pricing structure across premium, standard, and economy levels differentiates by field-of-view capability and software integration depth, with ISO 13485 certification grade serving as a procurement filter. Cost-down pressure on economy-tier systems accelerates because Indian assembly operations under the PLI scheme introduce price-optimized alternatives. Independent dental clinics in urban East Asian markets exhibit highest price sensitivity, while oral surgeons in Germany demonstrate lowest sensitivity due to reimbursement scale for complex implant procedures.
Supply Chain Analysis
Single-source vulnerability sits with rotating anode X-ray tube manufacturing concentrated in Germany and Japan, where specialty vacuum tube production clusters create bottlenecks for premium scanner assembly. Flat-panel detector fabrication draws from South Korean and Japanese component operations, with solid-state sensor wafer processing tethered to East Asian semiconductor infrastructure. Supply chain risk centers on tariff exposure for detector assemblies crossing from Busan-Ulsan corridor into European and North American final assembly locations. Distribution runs through dental equipment distributors with regional service capabilities, though independent service organizations increasingly capture aftermarket calibration and maintenance revenue unbundled from original equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CBCT dental imaging market functions as a consolidation play where EU MDR clinical evidence mandates filter marginal competitors and concentrate share with diversified platforms possessing software integration depth.
For Market Incumbents: Lock in multi-year service agreements with large dental service organizations before independent service organizations capture recurring calibration revenue. Deepen backward integration into flat-panel detector technology to reduce exposure to South Korean and Japanese component supply concentration. The threat of software-defined imaging architectures compressing hardware differentiation cycles demands accelerated R&D investment in AI reconstruction engines. For New Entrants and Emerging Players: Capture price-optimized segments in India and Southeast Asia where PLI scheme incentives lower assembly cost structures and local regulatory pathways remain streamlined. The most penetrable white-space sits in compact-footprint systems for East Asian urban clinic density. A software-first go-to-market angle—leading with cloud-based archival and treatment planning modules—sidesteps capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: The window for entry favors diversified dental equipment conglomerates with existing CAD/CAM workflow integration and ISO 13485 certification infrastructure already in place. Long-term viability rests on platforms that collapse the traditional separation between imaging acquisition and case presentation software. Watch for inflection signals in orthodontic evaluation adoption rates as clear aligner therapy penetrates general dentistry practices beyond specialist orthodontists.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend timelines and elevate quality thresholds for European commercialization. |
| Software Companion Development | AI reconstruction engines integrated with raw projection data reduce metal artifact interference without dose escalation. |
| Hospital System Partnership | Large dental service organizations in Germany standardize equipment procurement across multi-site consolidated networks. |
| FDA Submission | 21 CFR 1020.32 performance standards shape submission pathways for fluoroscopic equipment in the United States. |
| Reimbursement Strategy | Oral surgeon procedure scale in Texas and Florida commands premium capital budgets for complex implant imaging. |
Methodological Framework
Multi-period observation of equipment replacement cycles, regulatory submission timelines, and software subscription attach rates anchored the trend analysis, supplemented by interviews with oral surgeons, dental clinic procurement managers, biomedical engineers at large service organizations, and flat-panel detector manufacturing specialists. Secondary validation drew from FDA 510(k) and CE marking databases, ISO 13485 certification registries, hospital procurement contract disclosures, and dental equipment trade flow records. Bottom-up clinic census data triangulated against top-down manufacturer shipment reports.
Input-output matrices mapped cone beam unit shipments, software license activations, and service contract renewals across product type, end user specialty, technology generation, and application use case to generate volume and value estimates throughout the forecast period. CAGRs derived from logistic adoption curves fitted to historical replacement patterns and projected regulatory compliance cost trajectories. Industry-specific forecast inputs included EU MDR implementation pace and clear aligner therapy penetration rates in general dentistry.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to X-ray tube supply disruptions, FDA enforcement shifts, and cloud-based archival adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Global Endodontics Market
Dental Devices
Dental Healing Caps Market
Dental Devices
Global Orthodontic Product Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
China Dental Implants Market
Dental Devices
Dental Suction Mirror Market
Dental Devices
Europe CBCT Dental Imaging Market
Dental Devices
Argentina Dental Devices Market
Dental Devices
Dental Impression System Market
Dental Devices
Orthodontics Market
Dental Devices
Dental Etching Liquid Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Dental Inlays and Onlays Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Dental Units Market