
 Dental Air Abrasion Market | 2026-2036
Dental Air Abrasion Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Air Abrasion Market Analysis
Market Context
Micro-particle delivery technology is tilting dental air abrasion toward precision-controlled minimally invasive procedures, replacing conventional high-speed turbine dependence. Dentsply Sirona leverages its integrated digital workflow ecosystem to anchor premium positioning across chairside systems. KaVo Dental sustains manufacturing scale advantages through its German production footprint and established distribution into North American and European dental schools. NSK NAKANISHI INC. differentiates via compact handpiece engineering that targets space-constrained Asian clinic layouts.
Technical Definition and Segment Structure
Dental air abrasion is a kinetic cutting process that propels aluminum oxide or bioactive glass particles through a narrow nozzle via compressed air or gas, operating at pressures typically between 40 and 160 psi to selectively remove carious enamel and dentin without thermal damage. The technology serves primary industrial purposes in conservative cavity preparation, surface cleaning prior to bonding, and enamel microabrasion for aesthetic remediation. Wall-mounted systems dominate installed base value due to higher capital commitments and plumbing integration, while portable systems represent the fastest-expanding product category as mobile dentistry and teledentistry satellite operations multiply. Consumables concentrate margin pools through recurring abrasive particle, nozzle, and filter replacement cycles that lock in annuity revenue streams.
Regulatory Environment and Outlook
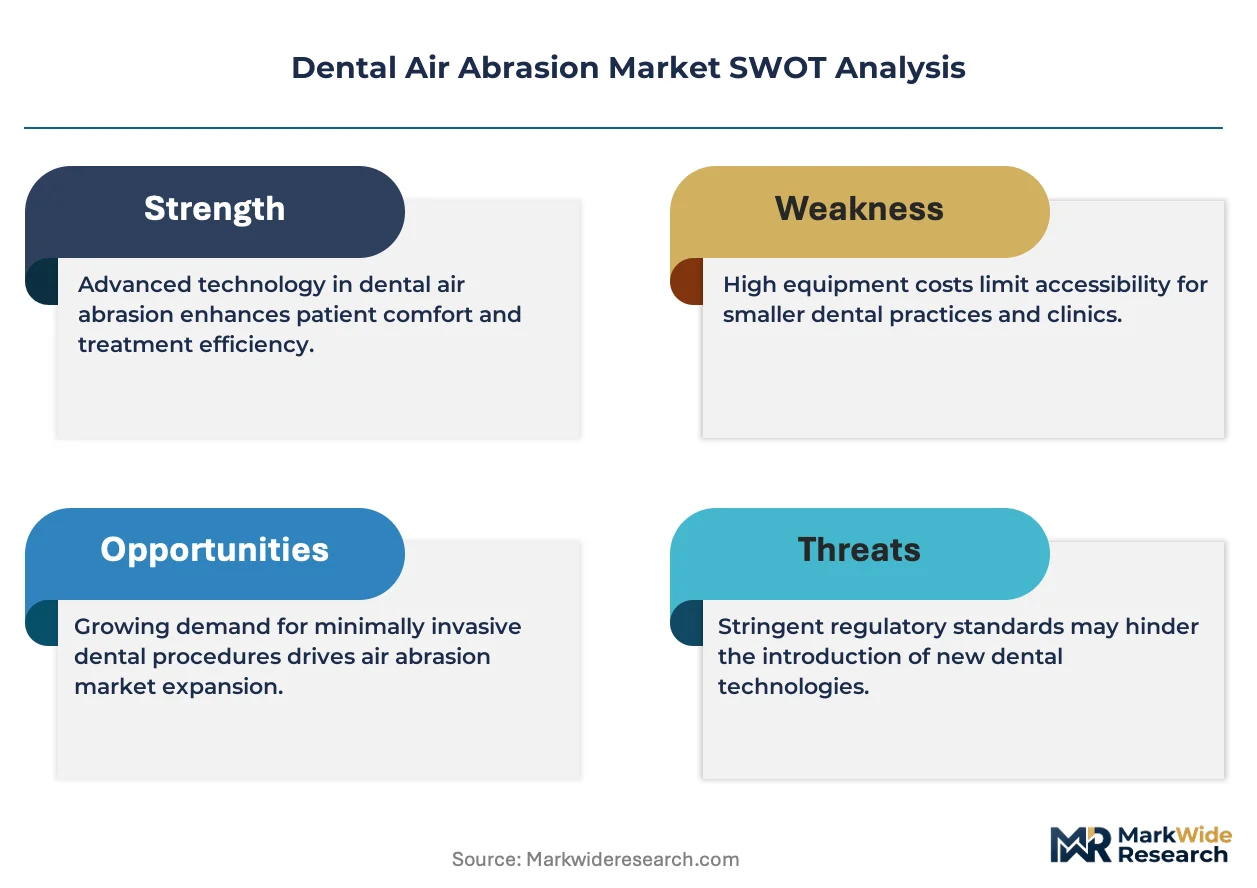
FDA 510(k) premarket notification requirements govern device classification for dental air abrasion units sold in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards on manufacturers seeking CE marking for European market access. ISO 13485 quality management certification functions as a baseline procurement filter for institutional buyers and group purchasing organizations evaluating vendor qualification. Stakeholders must monitor evolving EPA particulate emission standards for abrasive dust capture systems, as environmental compliance costs threaten to reshape total cost of ownership calculations and vendor selection criteria.
Market Dynamics
Compressed air particle delivery is displacing high-speed turbine dependence in conservative caries management, as practitioners and parents prioritize enamel preservation over traditional drilling protocols.
Growth Catalysts
- Minimally Invasive Protocol Adoption:Pediatric dental clinics are accelerating uptake of kinetic cutting techniques that reduce patient anxiety and eliminate thermal damage risks associated with conventional burs.
- FDA 510(k) Pathway Compression:Streamlined premarket notification timelines for new abrasive particle compositions are compressing product development cycles and accelerating commercialization.
- Reimbursement Framework Realignment:United States dental benefit structures increasingly favor conservative caries management over traditional restoration, directing procedure volume toward air abrasion systems.
Market Restraints
- Aluminum Oxide Supply Concentration:Abrasive particle sourcing depends on limited specialty chemical suppliers concentrated in industrial clusters, exposing manufacturers to input cost volatility.
- EU MDR Clinical Evidence Burden:Stricter clinical evidence standards for CE marking under the Medical Device Regulation are extending European market access timelines and elevating compliance expenditures.
- High-Speed Turbine Incumbency:Established rotary instrument installed bases and practitioner familiarity create switching friction that slows displacement rates in mature dental markets.
Strategic Opportunities
- Teledentistry Satellite Expansion:Portable air abrasion systems enable mobile dentistry deployments in rural United States communities currently underserved by fixed clinic infrastructure.
- Bioactive Glass Particle Innovation:Therapeutic abrasive compositions that release fluoride and support remineralization open restorative-adjacent revenue streams beyond purely mechanical cutting.
- EPA Particulate Capture Mandates:Evolving environmental compliance requirements for abrasive dust filtration create vendor differentiation opportunities through integrated capture system engineering.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management system audits and documentation requirements create extended vendor qualification periods that delay institutional procurement cycles.
- Digital Workflow Integration Complexity:Chairside air abrasion units must interface with intraoral scanning and CAD/CAM systems, requiring software compatibility investment that strains mid-tier manufacturer R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Air Abrasion Market |
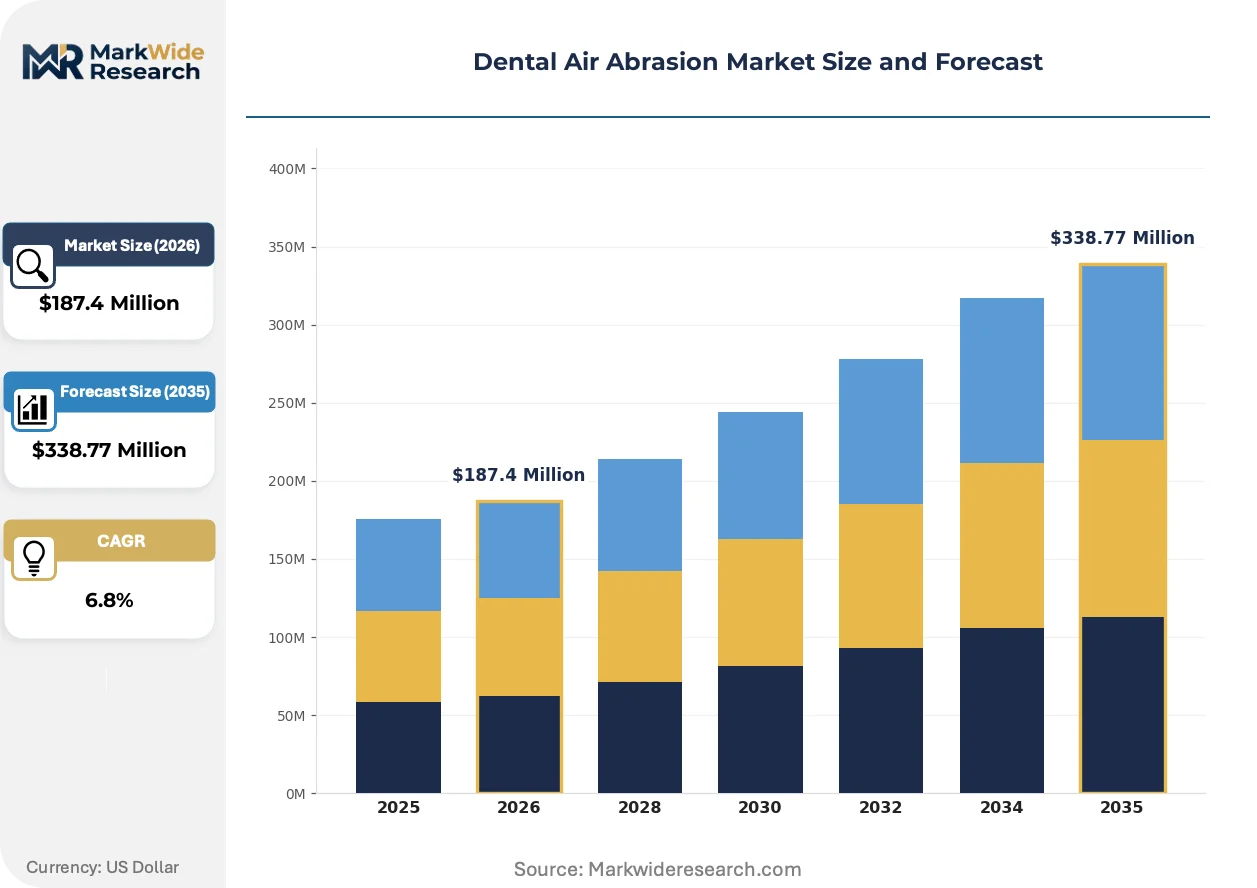
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Wall-Mounted Systems, Accessories, Consumables End User: Dental Clinics, Hospitals, Research Institutions, Universities Application: Cavity Preparation, Surface Cleaning, Enamel Microabrasion, Restorative Dentistry Technology: Micro-Particle Delivery, Air-Powder Technology, Laser Integration, Digital Interfaces |
| Companies Covered | Danville Material, Inc., ACTEON Group, KaVo Dental, Crystalmark Dental Systems, Inc., NSK NAKANISHI INC., Dentsply Sirona, Velopex International, Bio-Art, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Air Abrasion Market Emerging Trajectories
Digital integration and environmental compliance are compressing product development cycles while reshaping how abrasive delivery systems connect to broader restorative workflows.
Micro-particle beam control software is virtualizing the precision of cavity preparation by enabling real-time pressure modulation and automated depth limiting. Chairside systems in premium United States dental practices are adopting these modules fastest, with pediatric specialists leading implementation. This capability is virtualizing the boundary between manual operator skill and algorithmically controlled tissue removal, compressing training curves while elevating procedure consistency.
EPA particulate emission standards for abrasive dust capture are tightening environmental compliance obligations on dental equipment manufacturers. The regulatory pressure is forcing redesign of vacuum integration and filtration architecture in wall-mounted systems. United States vendors are responding fastest, with European manufacturers trailing by approximately one product generation due to fragmented national implementation timelines.
Parents and young adult patients are demanding anesthesia-free caries management, compressing switching cycles away from rotary instruments. Pediatric dental clinics in suburban United States markets are unbundling air abrasion procedures as standalone billable services distinct from comprehensive restoration packages. This behavioral shift concentrates in metropolitan corridors where dental benefit literacy and consumer review platforms accelerate technique awareness.
Dental Air Abrasion Market Segmentation
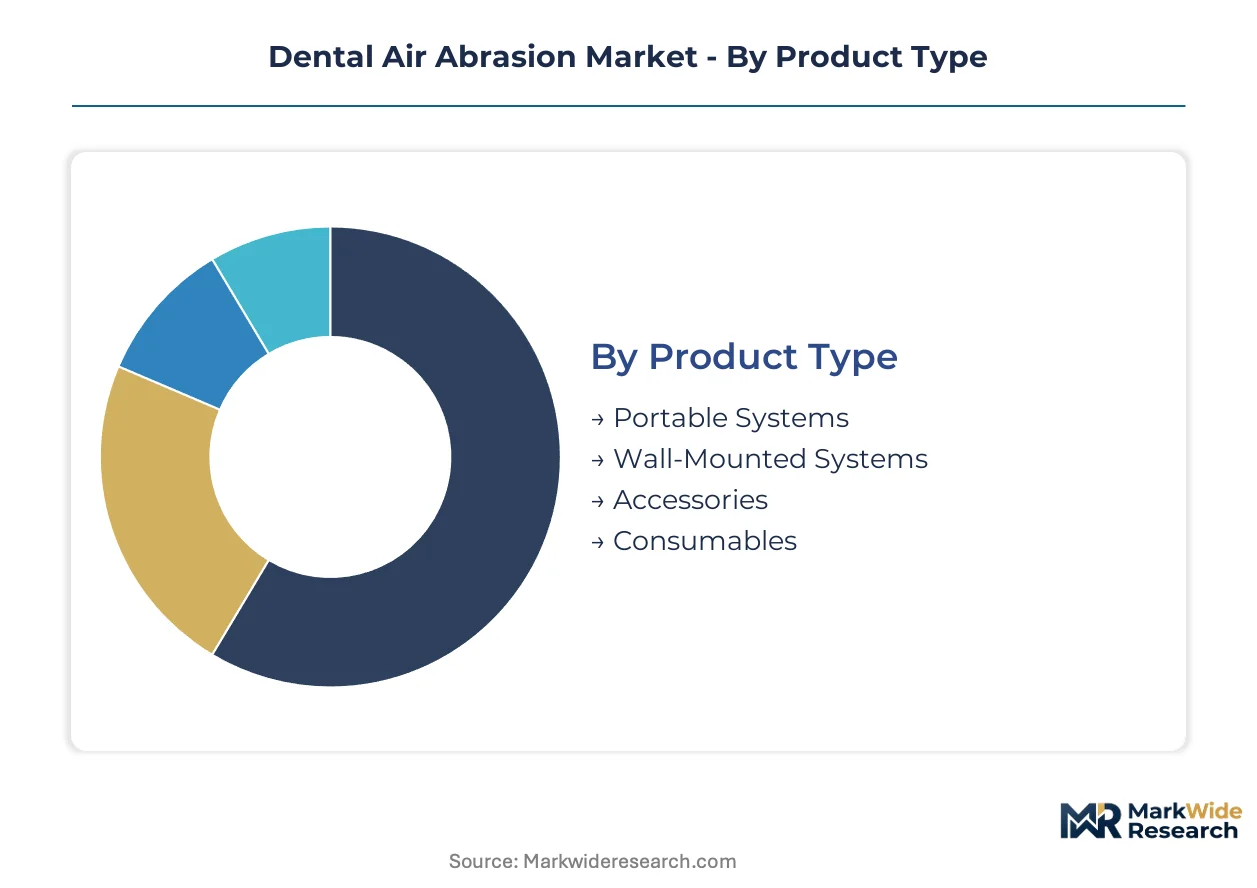
Segmentation in dental air abrasion reveals how equipment configuration, clinical setting, and procedural application shape procurement priorities and vendor positioning. Understanding these dimensions clarifies why portable systems and pediatric clinics are pulling ahead of legacy installed bases.
Product Type:
Mature wall-mounted installations dominate capital deployment, while emerging portable formats are capturing new clinical contexts.
- Wall-Mounted Systems:These units integrate with fixed plumbing and central vacuum infrastructure, delivering consistent pressure regulation for high-volume practices. Demand concentrates in established United States suburban dental clinics where renovation cycles and equipment depreciation schedules favor permanent installations. The category benefits from higher average selling prices and recurring service contract attachment rates.
- Portable Systems:Compact, self-contained units with internal compressors and battery power options enable deployment outside traditional clinic footprints. Teledentistry satellite operations and mobile dentistry fleets in rural United States communities are driving uptake fastest, as these systems bypass infrastructure constraints that wall-mounted alternatives require.
- Accessories:Nozzle assemblies, handpiece connectors, and vacuum adapters extend system functionality and compatibility across manufacturer ecosystems.
- Consumables:Abrasive particle cartridges, replacement nozzles, and filtration media generate recurring revenue through scheduled replacement cycles tied to procedure volume.
Wall-mounted systems handle the majority of throughput; portable systems are gaining share fastest as care delivery decentralizes.
End User:
Customer type segmentation tracks how procurement authority and reimbursement structure alter equipment specification priorities.
- Dental Clinics:Private and group practices with direct patient revenue streams prioritize chairside efficiency and patient experience metrics. Pediatric dental clinics within this segment are expanding air abrasion adoption fastest, driven by parental demand for minimally invasive protocols and anesthesia-free caries management.
- Hospitals:Academic medical centers and integrated health systems emphasize vendor credentialing, ISO 13485 certification, and group purchasing organization compliance over individual unit features.
- Research Institutions:Specialized centers investigating particle composition, pressure dynamics, and tissue interaction patterns require customizable systems with data logging capabilities.
- Universities:Dental schools in Germany, Japan, and the United States train incoming practitioners on air abrasion technique, creating early preference formation that influences later career equipment selection.
Dental clinics absorb the largest equipment volume; pediatric-focused practices within this segment are expanding most quickly.
Application:
Procedural use case determines abrasive particle selection, pressure parameters, and billing code alignment.
- Cavity Preparation:Selective caries removal using kinetic cutting at 40-160 psi preserves healthy enamel and dentin structure. United States reimbursement codes for conservative caries management are redirecting procedure volume toward this application.
- Surface Cleaning:Pre-bonding enamel conditioning and orthodontic bracket preparation demand controlled particle delivery without substrate damage.
- Enamel Microabrasion:Aesthetic remediation of fluorosis and superficial stains requires precise depth control and bioactive glass particle formulations that support remineralization.
- Restorative Dentistry:Adjunctive use alongside composite placement and ceramic bonding integrates air abrasion into broader digital workflow sequences.
Cavity preparation commands the largest procedure share; enamel microabrasion is climbing fastest as cosmetic dental demand rises.
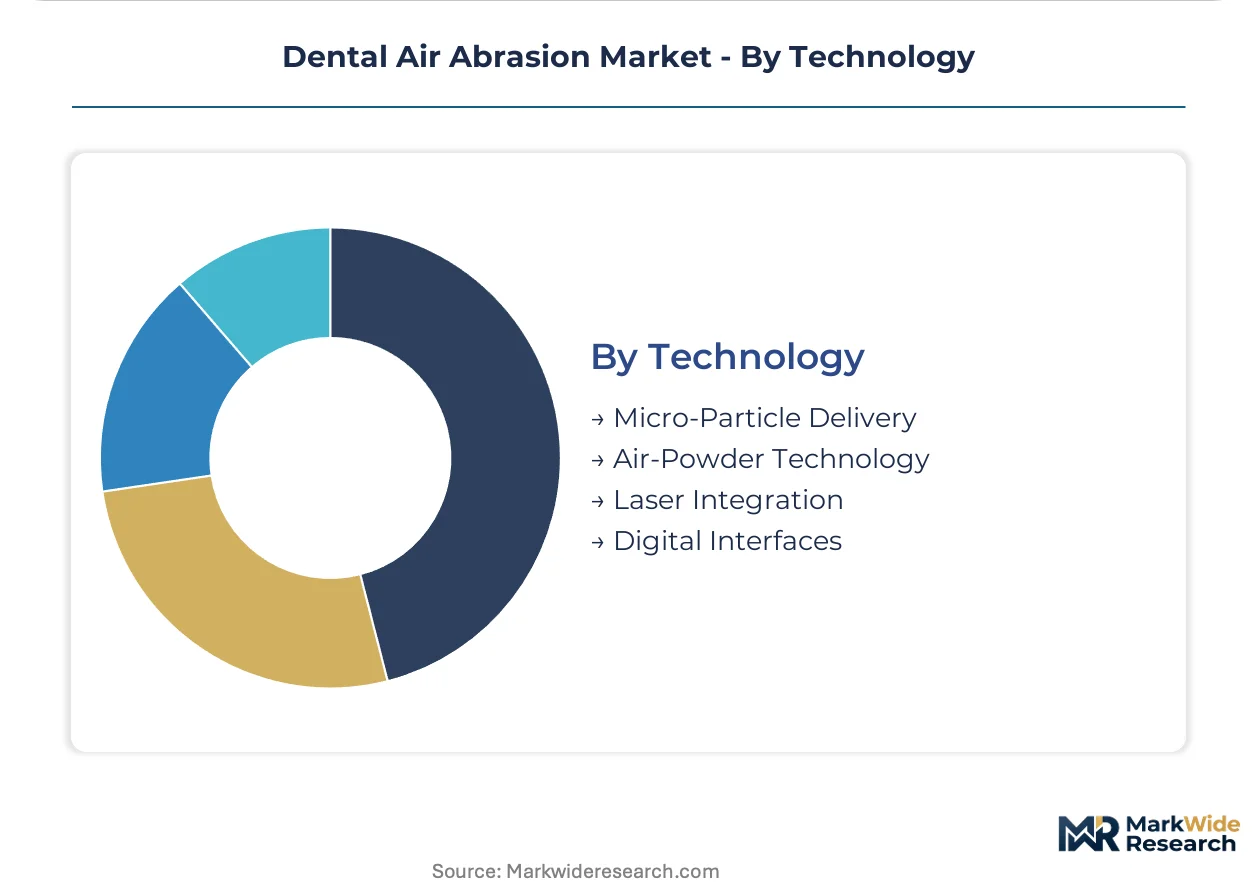
Technology:
Technical architecture segmentation captures the shift from mechanical precision toward software-mediated control and multimodal integration.
- Micro-Particle Delivery:Real-time pressure modulation and automated depth limiting software virtualize operator skill, compressing training curves while elevating procedure consistency. Premium United States practices are adopting these modules fastest.
- Air-Powder Technology:Conventional compressed air and particle propulsion systems remain the installed base standard, with cost advantages in price-sensitive procurement contexts.
- Laser Integration:Hybrid systems combining kinetic abrasion with soft tissue laser capability consolidate equipment footprints in space-constrained operatories.
- Digital Interfaces:CAD/CAM connectivity and intraoral scanning integration enable seamless workflow progression from preparation to restoration design.
Air-powder technology retains the largest installed base; micro-particle delivery systems are expanding most rapidly on new equipment sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric dental clinics and mobile dentistry operators concentrate procurement authority across developed markets, with reimbursement frameworks and environmental regulations shaping geographic deployment priorities.
United States
Suburban pediatric practices and teledentistry satellite operations drive equipment demand fastest. FDA 510(k) premarket notification pathways for new abrasive particle compositions compress development timelines. Dallas-Fort Worth and Atlanta metropolitan corridors anchor pediatric clinic expansion, with group purchasing organizations consolidating procurement volume.
Germany
Dental schools and academic medical centers emphasize ISO 13485 certification and vendor credentialing in procurement decisions. EU Medical Device Regulation clinical evidence requirements extend market access timelines. Stuttgart and Munich industrial clusters concentrate precision manufacturing for handpiece components and nozzle assemblies.
Japan
Space-constrained urban clinic layouts favor compact portable system configurations. METI industrial standards govern medical device quality management systems. Osaka-based manufacturing operations supply precision-engineered handpieces to domestic and export markets.
China
Rising cosmetic dental demand accelerates enamel microabrasion procedure volume in tier-one cities. NMPA medical device registration requirements structure market entry protocols. Shanghai and Beijing dental clinic chains pilot digital workflow integration with chairside air abrasion units.
Brazil
Mobile dentistry fleets serving rural communities expand portable system deployment. ANVISA medical device regulations govern import and commercialization pathways. São Paulo state concentrates dental equipment distribution infrastructure and specialist training institutions.
Dental Air Abrasion Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement contexts, with integrated dental equipment conglomerates anchoring premium positioning while mid-scale manufacturers capture price-sensitive volume. The vendor base stratifies around three archetypes: full-workflow integrators with digital ecosystem control, component specialists with manufacturing scale advantages, and regional fabricators serving localized procurement channels. Dominant competitive moves include strategic partnerships with group purchasing organizations and technology licensing arrangements for micro-particle delivery software.
Within the full-workflow integrator tier, Dentsply Sirona and KaVo Dental exemplify channel-control strategies through established distribution into dental schools and integrated health systems. NSK NAKANISHI INC. occupies a specialist position, with compact handpiece engineering addressing space-constrained Asian clinic layouts. Among diversified industrial conglomerates, 3M Company represents materials-science anchoring in abrasive particle and consumables supply.
| Leading Market Players |
|---|
| Danville Material, Inc. |
| ACTEON Group |
| KaVo Dental |
| Crystalmark Dental Systems, Inc. |
| NSK NAKANISHI INC. |
| Dentsply Sirona |
| Velopex International |
| Bio-Art |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors govern abrasive particle landed costs, compressing margin structures for European manufacturers while amplifying price differentiation between integrated conglomerates and component specialists sourcing from Asian chemical clusters.
Pricing Analysis
Cost-plus contracts indexed to specialty aluminum oxide spot markets dominate OEM supply agreements, with pass-through clauses activating quarterly. Three-tier pricing structure across premium, standard, and economy levels separates Dentsply Sirona's integrated digital workflows from mid-tier portable systems and unbranded consumables. Pricing pressure stems from EPA particulate capture mandates forcing filtration architecture redesigns. Pediatric dental clinics exhibit highest price sensitivity due to reimbursement code misalignment, while academic medical centers prioritize ISO 13485 certification over unit cost.
Supply Chain Analysis
Upstream feedstock concentration in Chinese and German specialty chemical clusters anchors abrasive particle supply, with aluminum oxide refining capacity tethered to industrial ceramics and metallurgy co-production. Precision nozzle machining rests on Japanese and Swiss micromanufacturing capabilities. Single-source vulnerability runs through Brazilian bioactive glass suppliers serving therapeutic particle formulations. Distribution runs through dental equipment distributors with GPO contracts in the United States, direct hospital sales in Germany, and clinic-level procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental air abrasion is approaching a platform-economics inflection where CAD/CAM interoperability and chairside software integration determine vendor lock-in, compressing standalone equipment margins while expanding ecosystem subscription value pools.
For Market Incumbents: Entrench digital workflow dominance through backward integration into intraoral scanning software and exclusive nozzle-cartridge pairing protocols that raise switching costs. KaVo Dental's German manufacturing scale and Dentsply Sirona's GPO channel control represent defensible moats against portable system disruptors. Prioritize FDA 510(k) clearance velocity for bioactive glass particle compositions to preempt therapeutic positioning by materials entrants. For New Entrants and Emerging Players: Rural United States teledentistry satellites and mobile dentistry fleets in Brazil's São Paulo state interior represent the most penetrable entry points, as infrastructure-light portable configurations bypass incumbent wall-mounted installed bases. Price-sensitive procurement in Southeast Asian clinic chains offers secondary expansion terrain. Go-to-market should emphasize anesthesia-free procedure bundling and pediatric parental education content over clinical specification sheets. For Investors and Strategic Acquirers: FDA clearance pathway compression for new abrasive compositions reshapes the acquisition landscape, elevating targets with pre-submission documentation and established 510(k) track records. Five-to-ten-year viability favors consumables-anchored revenue models with scheduled replacement cycles over capital equipment exposure. Monitor EPA particulate emission standard finalization timelines as the critical inflection signal for filtration technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed premarket timelines for bioactive glass particles reward early regulatory investment with commercialization lead time. |
| CAD/CAM Platform Integration | Seamless intraoral scanning connectivity locks chairside systems into premium digital workflow ecosystems. |
| Portable System Manufacturing Scale-Up | Battery-powered compact configurations capture mobile dentistry and teledentistry satellite deployment growth. |
| EPA-Compliant Filtration Development | Integrated abrasive dust capture systems differentiate wall-mounted offerings as environmental mandates tighten. |
| Group Purchasing Organization Partnership | GPO contract penetration in United States suburban pediatric clinics consolidates procurement volume and reduces customer acquisition cost. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with dental equipment procurement managers, pediatric practice administrators, biomedical engineers at academic medical centers, and GPO contracts specialists; and secondary validation against FDA 510(k) premarket notification databases, EPA emission standard dockets, hospital procurement records, and dental school curriculum documentation. Bottom-up equipment shipment estimates and top-down procedure volume modeling were triangulated against reimbursement code utilization patterns.
Forecast inputs incorporated product type segmentation across wall-mounted and portable configurations, end-user stratification by dental clinics versus hospitals versus universities, application splits between cavity preparation and enamel microabrasion, and technology tiers from air-powder to micro-particle delivery systems. CAGRs were derived from procedure volume elasticity to reimbursement framework changes and pediatric clinic expansion rates. Industry-specific inputs included aluminum oxide price indices and EPA regulatory implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in dental benefit reimbursement rates, specialty chemical input costs, or medical device regulatory staffing levels would shift the trajectory. Cross-checking against CMS Medicare Advantage dental rider enrollment data and ADA procedure survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Gingivitis Treatment Market
Dental Devices
Dental Caries Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
India Dental Devices Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Air Polishers Market
Dental Devices
China Dental Devices Market
Dental Devices
Global Dental Restorative Market
Dental Devices
China Dental Implants Market
Dental Devices
Dental 3D Scanners Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Asia Pacific Acrylic Teeth Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Carpule Market
Dental Devices
Endodontics and Orthodontics Market