
 Computer-Aided Drug Discovery Market | 2026-2036
Computer-Aided Drug Discovery Market Size, Share, and Industry Trends Forecast 2026-2036
Computer-Aided Drug Discovery Market Analysis
Structure-based design precision is redrawing competitive boundaries in molecular screening. Schrödinger, Inc. leverages physics-based simulation platforms to anchor its position in target identification workflows. Exscientia sustains differentiation through autonomous chemistry engines that compress discovery timelines. Insilico Medicine, Inc. competes via generative biology platforms trained on multimodal omics datasets.
Computer-aided drug discovery encompasses computational platforms that model protein-ligand interactions, predict pharmacokinetic profiles, and optimize molecular scaffolds through iterative in silico screening. These systems typically process billions of compound conformations against validated disease targets using cloud-scale GPU clusters, replacing portions of traditional high-throughput screening infrastructure. Machine learning applications now dominate lead optimization workflows, where neural architectures predict ADMET properties from molecular graphs. Structure-based design retains margin concentration among large pharmaceutical buyers requiring atomic-resolution binding predictions for regulatory submissions. Cloud-based deployment models expand fastest among mid-cap biotechnology firms seeking elastic compute without capital-intensive server farms.
FDA's emerging guidance on AI-enabled drug development shapes validation standards for computational predictions submitted in IND packages. EMA's qualification opinion pathway for novel methodologies creates parallel compliance obligations for sponsors pursuing transatlantic trials. The OECD's principles on trustworthy AI extend to pharmaceutical algorithm auditing, pressuring vendors to document training data provenance and model drift. Stakeholders must now weigh regulatory acceptance timelines against platform interoperability investments when selecting computational partners.
Market Dynamics
Machine learning platforms are compressing discovery timelines from years to months, forcing pharmaceutical buyers to restructure their R&D vendor portfolios around computational validation capabilities rather than traditional screening throughput.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's emerging guidance on AI-enabled drug development validates computational predictions for IND submissions, reducing regulatory risk for sponsors adopting in silico methods.
- Cloud GPU Elasticity:Mid-cap biotechnology firms in Boston and San Francisco now access billion-scale molecular simulations without capital-intensive server infrastructure, expanding addressable demand.
- Generative Biology Convergence:Multimodal omics training datasets enable de novo molecular design, opening target classes previously intractable to structure-based approaches.
Market Restraints
- Training Data Provenance Requirements:OECD principles on trustworthy AI mandate documented model drift tracking, raising compliance costs for algorithm vendors.
- Atomic-Resolution Validation Bottlenecks:Large pharmaceutical buyers still require experimental binding confirmation for regulatory submissions, limiting full displacement of physical screening.
- Specialized Talent Scarcity:The intersection of computational chemistry and machine learning engineering concentrates in Cambridge, Massachusetts and Basel, Switzerland, creating recruitment bottlenecks.
Strategic Opportunities
- EMA Qualification Opinion Pathway:Sponsors pursuing transatlantic trials can secure parallel validation for novel methodologies, creating first-mover advantage in European markets.
- Antibody-Drug Conjugate Design:Generative platforms trained on linker-payload pharmacokinetics address a high-value application with limited computational competition.
- Contract Research Organization Integration:Computational vendors embedding directly into CRO workflows capture recurring revenue from biotech clusters without standalone platform sales cycles.
Industry Challenges
- Cross-Functional Team Assembly:Effective deployment requires rare combinations of medicinal chemists, cloud infrastructure engineers, and regulatory affairs specialists.
- Legacy High-Throughput Screening Depreciation:Pharmaceutical buyers face stranded asset risk from automated liquid-handling robotics and compound library physical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer-Aided Drug Discovery Market |
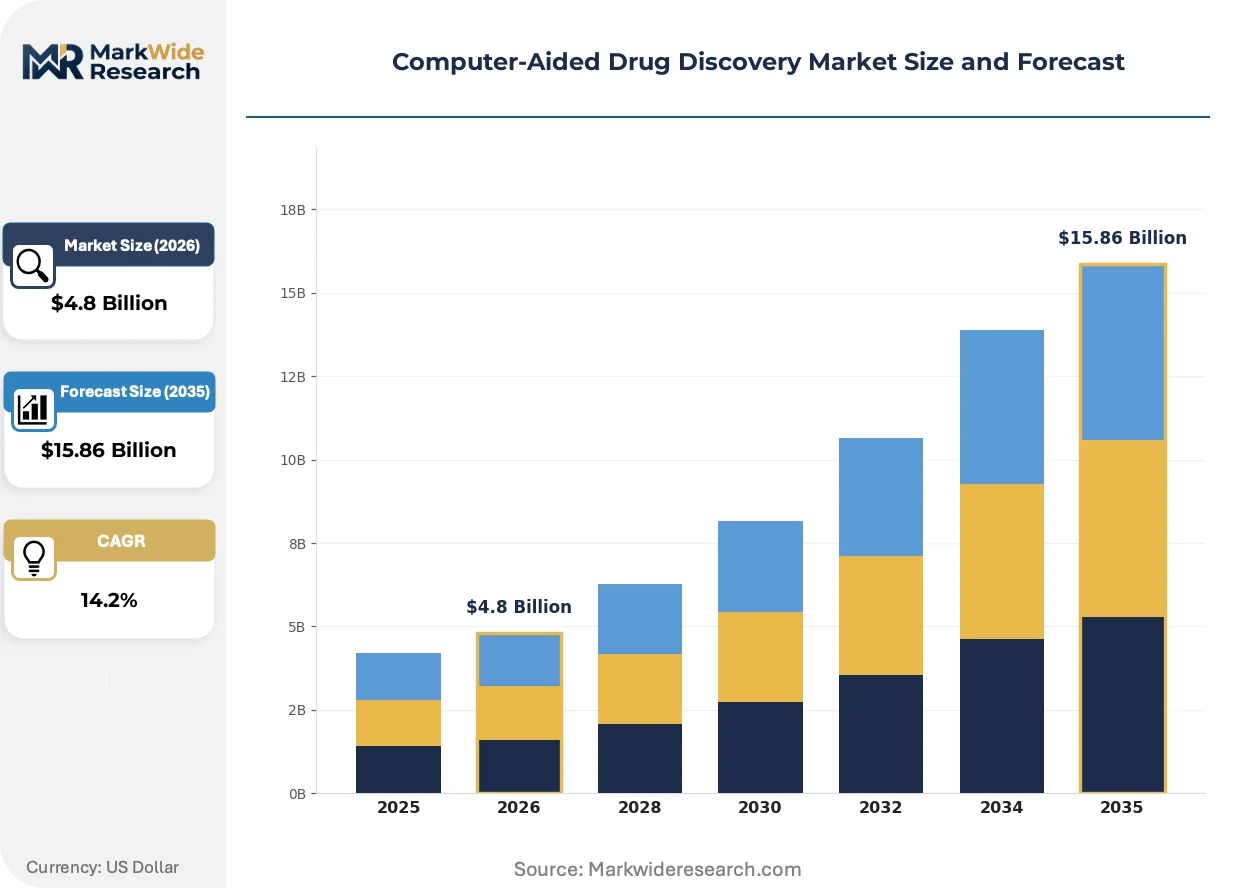
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Lead Discovery, Lead Optimization, Preclinical Development, Clinical Trials Technology: Machine Learning, Molecular Docking, Virtual Screening, Structure-Based Design End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutes, Contract Research Organizations Deployment: On-premises, Cloud-based, Hybrid, Software-as-a-Service |
| Companies Covered | Exscientia, Insilico Medicine, Inc., Schrödinger, Inc., Bayer AG, AstraZeneca, Dassault Systèmes, Atomwise, Inc., Charles River Laboratories, Certara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer-Aided Drug Discovery Market Emerging Trajectories
Physics-based simulation engines are merging with generative architectures, creating hybrid platforms that trade off computational cost against prediction accuracy in real-time during lead optimization campaigns.
Quantum chemistry approximations embedded in molecular dynamics workflows are miniaturizing the hardware footprint required for accurate protein-ligand binding predictions. Mid-cap biotechnology firms now deploy these methods on single-GPU workstations rather than cloud clusters. This compression is enabling decentralized discovery teams to iterate compounds without centralized IT approval cycles.
REACH registration requirements for novel chemical entities are expanding data obligations for computational predictions submitted in European regulatory packages. The European Chemicals Agency now expects documented training set coverage for any AI-predicted toxicity endpoint. Contract research organizations serving EU markets are retrofitting validation protocols to satisfy these documentation standards.
Biotechnology procurement officers now unbundle software licensing from professional services, demanding API-first platforms that integrate with existing electronic laboratory notebook systems. This shift displaces traditional enterprise software sales models predicated on multi-year implementation contracts. The pattern is most visible among Series B and C funded firms in South San Francisco seeking rapid workflow deployment without vendor lock-in.
Computer-Aided Drug Discovery Market Segmentation
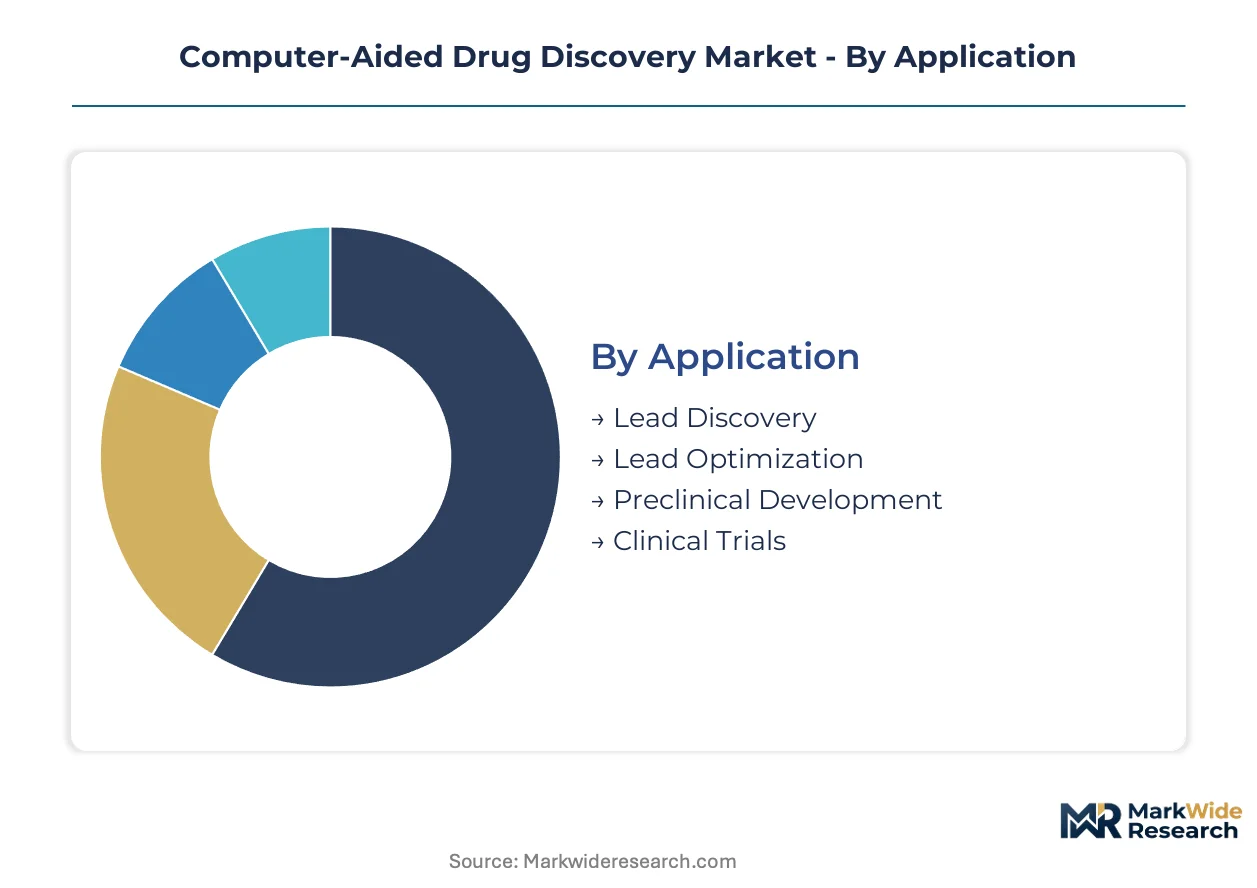
Computational drug discovery platforms serve heterogeneous workflows with divergent technical requirements and procurement patterns. Segmentation reveals where machine learning substitutes legacy methods versus where physics-based approaches retain irreplaceable value.
Application:
Lead optimization faces the most acute substitution pressure as neural architectures displace iterative medicinal chemistry cycles, while preclinical development maintains higher experimental validation barriers.
- Lead Discovery:Computational platforms screen billions of virtual compounds against target structures, compressing hit identification timelines. Demand concentrates among mid-cap biotechnology firms in Boston and San Francisco seeking to bypass capital-intensive high-throughput screening infrastructure.
- Lead Optimization:Machine learning predicts ADMET properties from molecular graphs, enabling rapid scaffold refinement. Large pharmaceutical buyers in Basel and Cambridge, Massachusetts anchor spending here, driven by FDA pressure for accelerated IND submissions with computational validation packages.
- Preclinical Development:Toxicity prediction and pharmacokinetic modeling require experimental confirmation.
- Clinical Trials:Patient stratification and biomarker discovery applications remain nascent.
Lead discovery anchors the volume base while lead optimization gains share at the steepest rate.
Technology:
Cost tier differentiation separates enterprise-grade physics engines from accessible cloud machine learning tools.
- Machine Learning:Neural architectures trained on multimodal omics datasets enable de novo molecular generation. Cloud GPU elasticity has democratized access, with Series B and C funded firms in South San Francisco driving fastest adoption.
- Structure-Based Design:Atomic-resolution binding predictions require specialized hardware and expertise. Large pharmaceutical buyers in Switzerland and the United States sustain premium pricing for regulatory-grade simulations.
- Molecular Docking:Established algorithms for pose prediction face margin compression.
- Virtual Screening:Library enumeration against target structures remains workflow-embedded.
Machine learning commands the broadest user base while structure-based design retains the highest contract values.
End User:
Customer type determines deployment complexity and integration requirements across the value chain.
- Pharmaceutical Companies:Integrated R&D organizations demand validated platforms with regulatory documentation. Spending concentrates among top-20 global firms restructuring vendor portfolios around computational capabilities rather than screening throughput.
- Biotechnology Firms:Capital-constrained innovators prioritize API-first platforms with rapid implementation. Procurement officers now unbundle software licensing from professional services to avoid vendor lock-in.
- Academic Research Institutes:Grant-funded access to shared national supercomputing resources.
- Contract Research Organizations:Computational vendors embedding into CRO workflows capture recurring revenue without standalone sales cycles.
Pharmaceutical companies provide the revenue foundation while biotechnology firms expand the addressable market most aggressively.
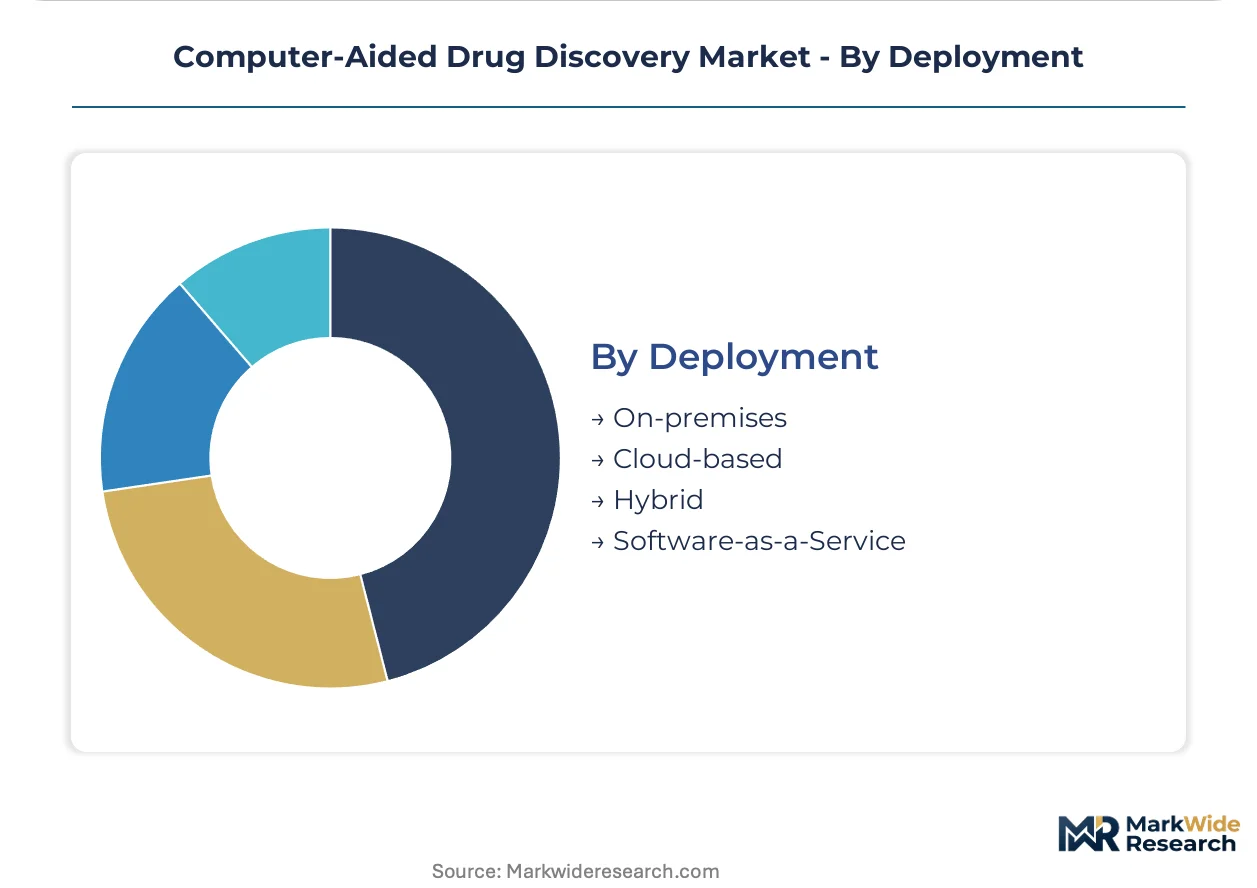
Deployment:
Supply concentration in cloud infrastructure is reshaping how computational chemistry scales.
- Cloud-based:Elastic GPU access eliminates capital expenditure for molecular dynamics simulations. Mid-cap biotechnology firms in Boston and San Francisco anchor demand, driven by OECD principles pressuring documented model drift tracking.
- Software-as-a-Service:Subscription models with API integration displace perpetual licenses. Series B and C funded firms prioritize rapid workflow deployment without multi-year implementation contracts.
- On-premises:Security-sensitive large pharmaceutical buyers retain controlled environments.
- Hybrid:Mixed architectures balance sensitive data handling with burst compute needs.
Cloud-based deployment anchors current adoption while software-as-a-service models are climbing the fastest among new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Physics-based simulation clusters concentrate in Switzerland and Massachusetts, while machine learning talent pools anchor in Cambridge, Basel, and South San Francisco. Cloud infrastructure democratizes access across mid-cap biotechnology hubs.
United States
FDA accelerated approval pathways for AI-designed molecules drive pharmaceutical procurement restructuring. The agency's emerging guidance on computational validation reduces regulatory risk for IND submissions incorporating in silico predictions. Boston and San Francisco biotech clusters anchor contract research organization spending on elastic GPU infrastructure.
Switzerland
Large pharmaceutical buyers in Basel sustain premium pricing for atomic-resolution binding predictions required for regulatory submissions. Swissmedic maintains stringent validation standards for computational predictions in drug approval packages. The Basel-Land region concentrates structure-based design expertise serving transatlantic trial sponsors.
United Kingdom
OECD principles on trustworthy AI pressure vendors to document training data provenance for algorithm auditing. The Medicines and Healthcare products Regulatory Agency aligns with FDA guidance on AI-enabled development pathways. Cambridge, England hosts concentrated computational chemistry and machine learning engineering intersections.
China
NMPA regulatory frameworks for AI-assisted drug discovery mature alongside domestic biotechnology scaling. National multimodal omics datasets enable generative biology platform training for de novo molecular design. Shanghai and Beijing anchor cloud-based deployment adoption among Series B and C funded firms.
Germany
REACH registration requirements expand data obligations for computational predictions in European regulatory packages. The Federal Institute for Drugs and Medical Devices expects documented training set coverage for AI-predicted toxicity endpoints. Munich and Heidelberg clusters integrate quantum chemistry approximations into decentralized discovery workflows.
Computer-Aided Drug Discovery Market Vendor Landscape
Concentration sits with physics-based simulation specialists and autonomous chemistry engine developers. The vendor base separates into three tiers: enterprise-grade platform providers serving top-20 pharmaceutical firms, API-first SaaS vendors targeting mid-cap biotechnology, and embedded CRO integration specialists. Strategic moves center on regulatory validation partnerships and cloud infrastructure alliances rather than horizontal consolidation.
Within the physics-based simulation tier, Schrödinger, Inc. and Dassault Systèmes occupy positions defined by atomic-resolution prediction capabilities. Exscientia exemplifies the autonomous chemistry engine archetype compressing discovery timelines through generative approaches. Insilico Medicine, Inc. anchors the generative biology segment with multimodal omics-trained platforms. These three represent distinct competitive vectors—simulation precision, chemistry automation, and biological data integration—rather than overlapping substitution threats.
| Leading Market Players |
|---|
| Exscientia |
| Insilico Medicine, Inc. |
| Schrödinger, Inc. |
| Bayer AG |
| AstraZeneca |
| Dassault Systèmes |
| Atomwise, Inc. |
| Charles River Laboratories |
| Certara |
| Others |
Supply Flow & Price Mechanics
GPU-based molecular simulation clusters displacing on-premises server farms simultaneously concentrate supply geography in cloud infrastructure hubs and compress pricing economics for mid-cap biotechnology procurement officers. Elastic compute access eliminates capital expenditure barriers while forcing perpetual-license vendors toward subscription recapture models.
Pricing Analysis
FDA accelerated approval pathways for AI-enabled drug development dictate the pricing tier structure across computational validation platforms. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade physics engines with regulatory documentation from API-first SaaS tools and open-source alternatives. Price differentiation hinges on certification grade for EMA qualification opinions and after-sales integration support. Cost compression in the standard tier is intensifying because cloud GPU providers commoditize baseline machine learning inference. Biotechnology procurement officers in Series B and C funded firms exhibit highest price sensitivity, while top-20 pharmaceutical buyers prioritize validation depth over licensing cost.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Taiwan and South Korea intermittently disrupt GPU hardware delivery schedules for cloud infrastructure expansion. The supply chain draws from specialized semiconductor fabrication in Taiwan, cloud data center concentration in the United States and Ireland, and algorithm development talent pools in Switzerland and Massachusetts. Raw material dependencies include NVIDIA A100/H100 accelerators, high-bandwidth memory modules, and proprietary molecular force field datasets. Single-source vulnerability sits with TSMC's advanced node production for training-optimized chips. Distribution runs through hyperscaler marketplaces and direct enterprise licensing agreements with computational chemistry vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
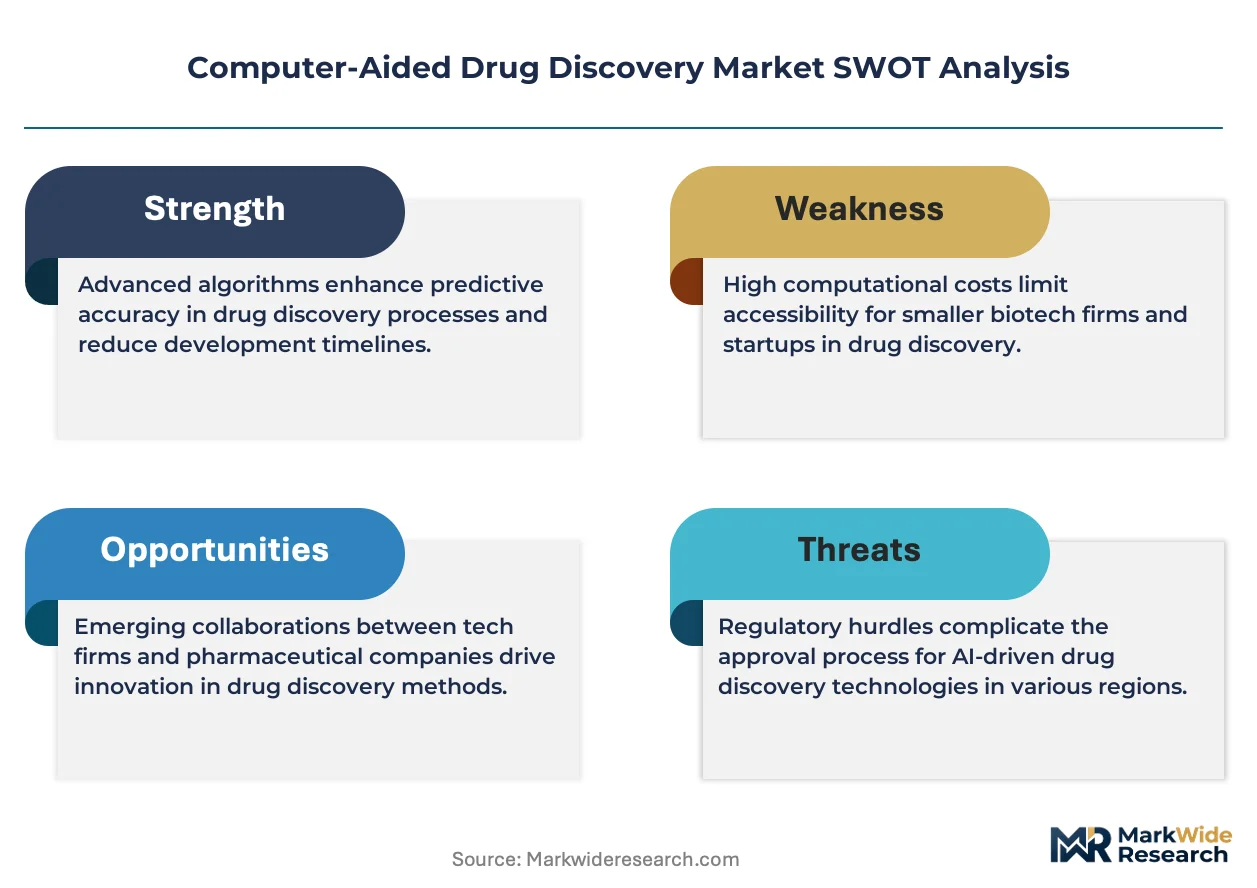
Platform fragmentation across machine learning, structure-based design, and generative biology architectures creates specialization niches as pharmaceutical buyers unbundle monolithic vendor relationships. Autonomous chemistry engines and physics simulation specialists now compete for distinct workflow slots rather than direct substitution.
For Market Incumbents: Fortify regulatory validation partnerships with FDA and EMA to lock in enterprise procurement criteria before emerging entrants achieve qualification opinion status. Deepen backward integration into cloud GPU infrastructure through reserved capacity agreements with hyperscalers, securing cost advantages against SaaS-native challengers. Structure-based design specialists face displacement threat from generative platforms trained on multimodal omics datasets. For New Entrants and Emerging Players: Anchor in antibody-drug conjugate design workflows where linker-payload pharmacokinetics training data remains scarce and computational competition limited. The most penetrable segment sits with mid-cap biotechnology firms in South San Francisco seeking API-first platforms without multi-year implementation contracts. Pursue CRO embedding strategies that capture recurring revenue from Boston and Basel biotech clusters without standalone enterprise sales cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed autonomous chemistry engine developers facing timeline compression pressure from generative biology platforms. Long-term viability over the next decade hinges on regulatory documentation depth rather than algorithmic sophistication alone. Watch for EMA qualification opinion pathway milestones as inflection indicators for platform consolidation appetite among top-20 pharmaceutical buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Partnership | EMA qualification opinion pathway secures first-mover validation for novel AI methodologies in European trials. |
| Cloud Infrastructure Alliance | Reserved GPU capacity agreements with AWS and Azure lock in elastic compute pricing for molecular dynamics workloads. |
| CRO Workflow Embedding | Direct integration into Charles River Laboratories and WuXi AppTec pipelines captures recurring revenue without standalone sales. |
| Multimodal Omics Data Licensing | Exclusive training dataset access from national biobanks differentiates generative biology platforms from structure-based competitors. |
| API-First Platform Launch | Electronic laboratory notebook integration meets Series B biotechnology procurement demands for rapid deployment without vendor lock-in. |
Methodological Framework
Cross-validation between primary interviews with computational chemistry directors and secondary analysis of FDA IND submissions anchors the qualitative findings in documented regulatory acceptance patterns. Drug development executives, regulatory affairs leads at top-20 pharmaceutical firms, cloud procurement officers at mid-cap biotechnology companies, and CRO scientific directors contributed structured input. Secondary sources include ClinicalTrials.gov AI-assisted trial registrations, EMA qualification opinion pathway documentation, SEC 10-K R&D expenditure disclosures, and OECD AI principle implementation reports. Bottom-up platform deployment estimates triangulate against top-down pharmaceutical IT spending benchmarks.
Sensitivity analysis across technology adoption curves, regulatory timeline scenarios, and cloud infrastructure cost trajectories shapes the analytical framework. Segmentation dimensions modeled include application workflow, deployment architecture, end-user organization scale, and regional regulatory cluster. CAGRs derive from iterative convergence between historical platform penetration rates and pharmaceutical R&D restructuring patterns across the projection horizon. Quantum chemistry hardware miniaturization timelines and FDA guidance finalization schedules constitute industry-specific forecast inputs.
Material uncertainties — NMPA regulatory framework maturation delays, REACH registration requirement expansions, and hyperscaler GPU export restriction changes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding OECD AI principle enforcement intensity and EMA-FDA guidance alignment velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Capecitabine Market
Pharmaceuticals
Pharmaceutical Grade Lactose Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Cortisone Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Topical Corticosteroids Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Global Opioid Induced Constipation Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market