
 Drug Eruptions Treatment Market | 2026-2036
Drug Eruptions Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Eruptions Treatment Market Foresight
ISO 13485 certification for medical device and pharmaceutical quality management is reorganizing competitive entry in drug eruptions therapeutics, raising compliance costs for new entrants. Pfizer Inc. leverages its global manufacturing scale to sustain corticosteroid supply across multiple delivery modes. Novartis AG anchors its position through biologics specialization in immunology-driven skin reactions. Johnson & Johnson competes via integrated dermatology channels that extend from hospital formulary access to outpatient clinic dispensing.
Drug eruptions treatment encompasses pharmacological interventions targeting immune-mediated cutaneous adverse reactions, including corticosteroids that modulate inflammatory cytokine cascades and biologics engineered to interrupt specific T-cell activation pathways, with primary purpose of halting disease progression and preventing systemic complications like Stevens-Johnson syndrome. Corticosteroids remain the dominant product category due to established efficacy in acute hypersensitivity presentations, while biologics represent the fastest-expanding segment as targeted IL-4 and IL-13 inhibitors demonstrate superior outcomes in refractory cases. The oral delivery mode occupies the largest volume share through patient convenience, though infusion channels capture disproportionate margin pools in hospital-based severe adverse event management.
FDA safety labeling requirements and EMA pharmacovigilance frameworks collectively shape development priorities, with both agencies intensifying post-market surveillance for immunosuppressant-associated infection risks. The EU MDR and REACH compliance obligations further constrain formulation chemistry choices for topical preparations entering European markets. Stakeholders must monitor evolving payer criteria for biologic step therapy protocols, as prior authorization requirements increasingly determine product access before clinical efficacy differentiates winners.
Market Dynamics
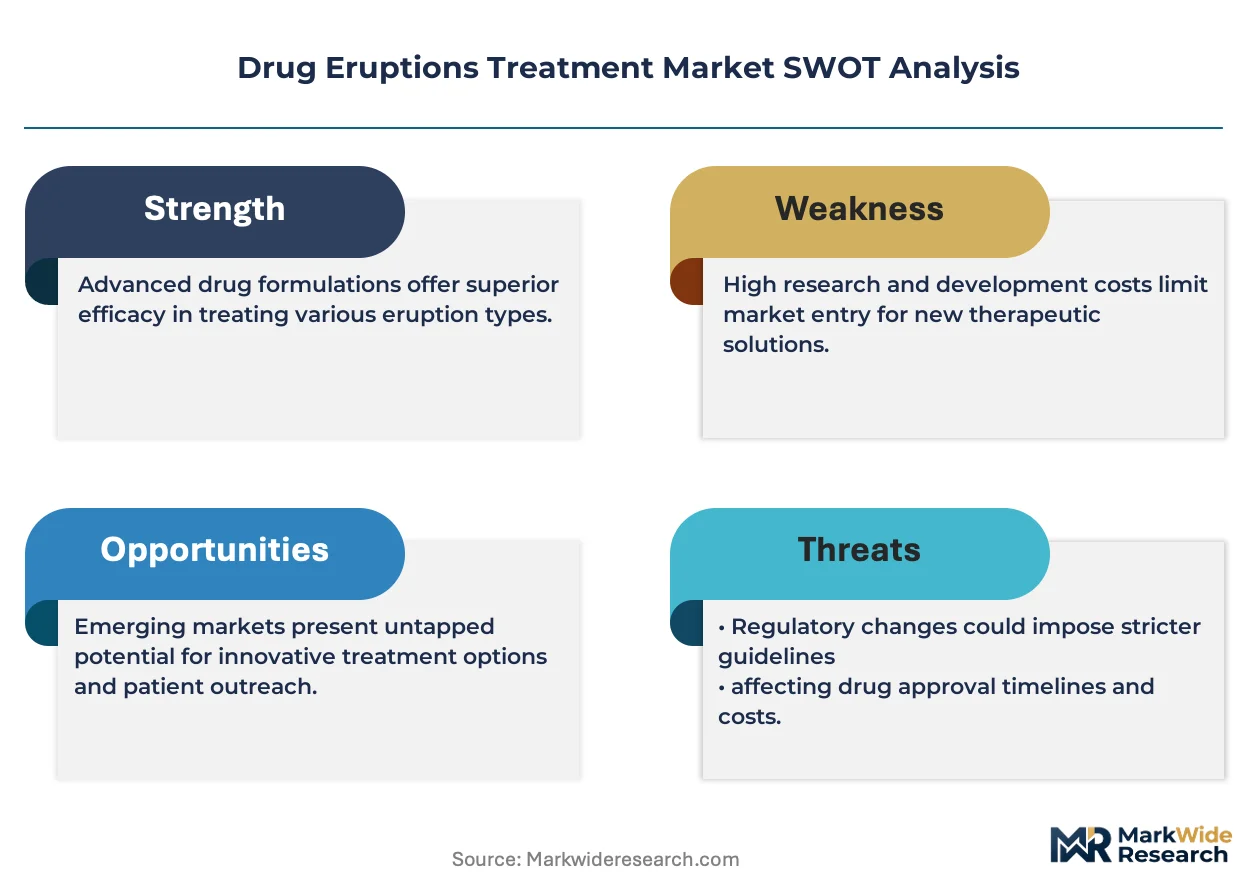
Biologics specialization is fragmenting competitive positioning in drug eruptions therapeutics, as targeted IL-4 and IL-13 inhibitors force legacy corticosteroid suppliers to defend formulary access through combination protocols and hospital contracting.
Growth Catalysts
- EMA pharmacovigilance frameworks:Intensified post-market surveillance for immunosuppressant-associated infection risks is accelerating biologics development investment by mandating superior safety profiles.
- Hospital-based severe adverse event management:Academic medical centers are expanding dedicated cutaneous adverse reaction units, creating concentrated demand for infusion-capable therapies.
- Specialty pharmacy networks:United States distribution infrastructure for temperature-sensitive biologics is deepening reach into outpatient dermatology clinics.
Market Restraints
- ISO 13485 certification costs:Quality management system compliance for pharmaceutical manufacturing is raising capital barriers for new entrants in biologics production.
- Active pharmaceutical ingredient concentration:Corticosteroid precursor supply chains cluster in specific manufacturing regions, exposing formulation chemistry to single-source disruption risk.
- Topical formulation limitations:Skin penetration barriers for large-molecule biologics restrict delivery mode options, constraining patient convenience in mild-to-moderate presentations.
Strategic Opportunities
- Prior authorization automation:Payer step therapy protocols are creating openings for real-world evidence platforms that accelerate biologics access decisions.
- Pediatric indication expansion:Underpenetrated age-specific dosing regimens present white space for pharmacokinetic studies in Stevens-Johnson syndrome prophylaxis.
- EU MDR compliance services:REACH formulation chemistry consulting for topical preparations entering European markets represents a high-margin adjacency.
Industry Challenges
- Immunology-trained dermatology workforce:Shortage of specialists capable of managing cytokine cascade modulation is bottlenecking biologics adoption in community hospital settings.
- Cold chain infrastructure capex:Biologics stability requirements demand continuous temperature monitoring systems, compressing margins for regional distributors.
- FDA label expansion timelines:Supplemental indication approvals for existing immunosuppressants face extended review cycles, delaying revenue diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Eruptions Treatment Market |
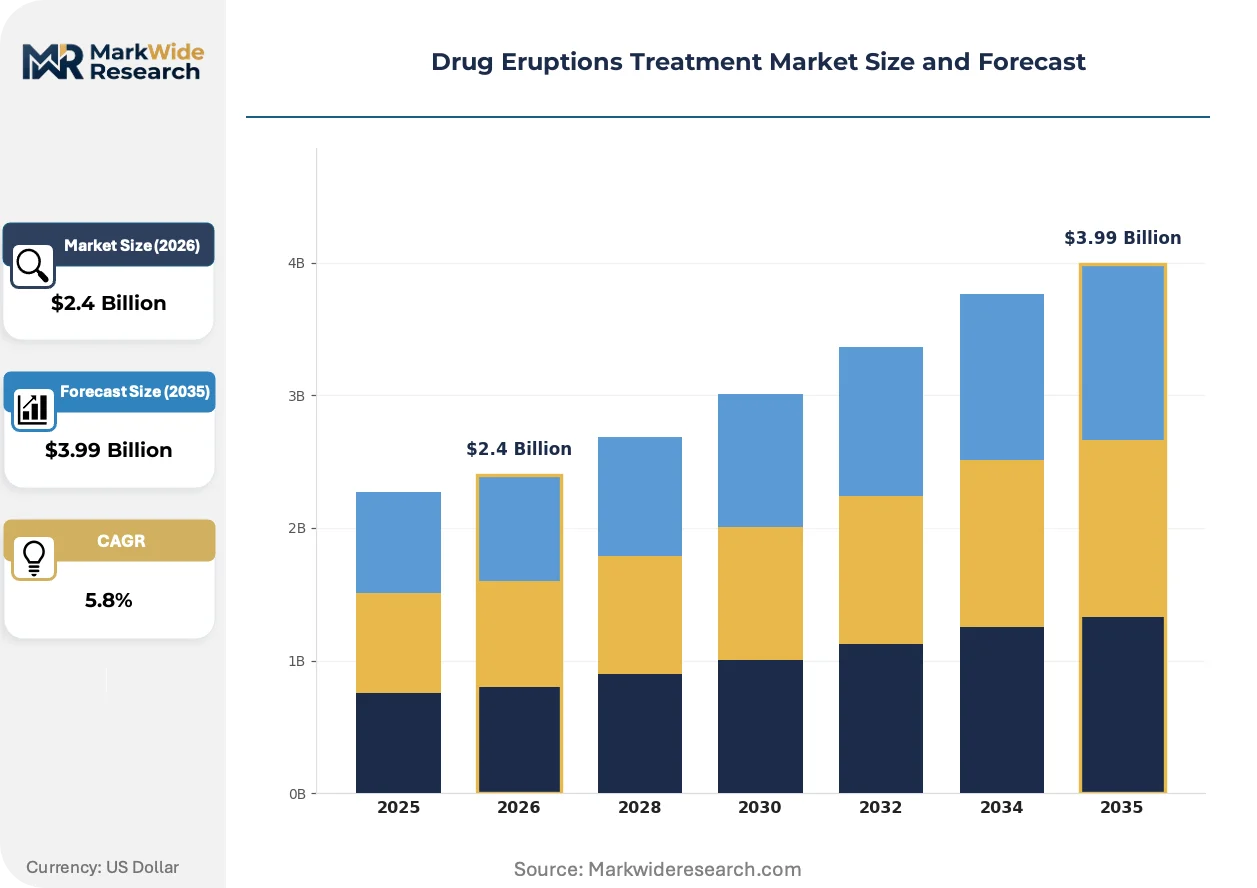
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Antihistamines, Immunosuppressants, Biologics Delivery Mode: Topical, Injectable, Oral, Infusion Care Setting: Outpatient Clinics, Hospitals, Home Care, Specialty Pharmacies End User: Dermatologists, General Practitioners, Allergists, Patients |
| Companies Covered | Johnson & Johnson, Pfizer Inc., Novartis AG, Bausch Health Companies Inc., Anuh Pharma Ltd., Avik Pharma, Hovione, Merck & Co., Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Eruptions Treatment Market Shifts & Advancements
Targeted delivery mechanisms are compressing the boundary between systemic and localized therapy, while regulatory agencies recalibrate safety surveillance for increasingly potent immunomodulators. These forces are reshaping how manufacturers prioritize development pipelines.
Subcutaneous biologics delivery systems are miniaturizing injection volumes through concentrated protein formulations, enabling self-administration outside infusion centers. Hospital-based dermatology departments are adopting these devices for step-down protocols following acute Stevens-Johnson syndrome stabilization. The technology is miniaturizing the acute care footprint required for severe cutaneous adverse reaction management, shifting margin capture toward outpatient channels.
REACH compliance obligations for topical corticosteroid formulations are constraining excipient choices in European markets, forcing reformulation of established products. EMA's evolving guidance on percutaneous absorption thresholds is compressing development timelines for new topical entrants. Manufacturers serving Germany and France are responding by consolidating formulation chemistry expertise within dedicated regulatory affairs divisions.
Academic medical centers are unbundling after-sales clinical support from product procurement, purchasing biologics through centralized pharmacy while contracting separately for patient monitoring services. This decoupling is displacing traditional vendor-managed inventory models in United States hospital systems. The pattern is most visible in Massachusetts and California, where integrated delivery networks are piloting outcomes-based contracting for IL-4 inhibitor therapy.
Drug Eruptions Treatment Market Segmentation
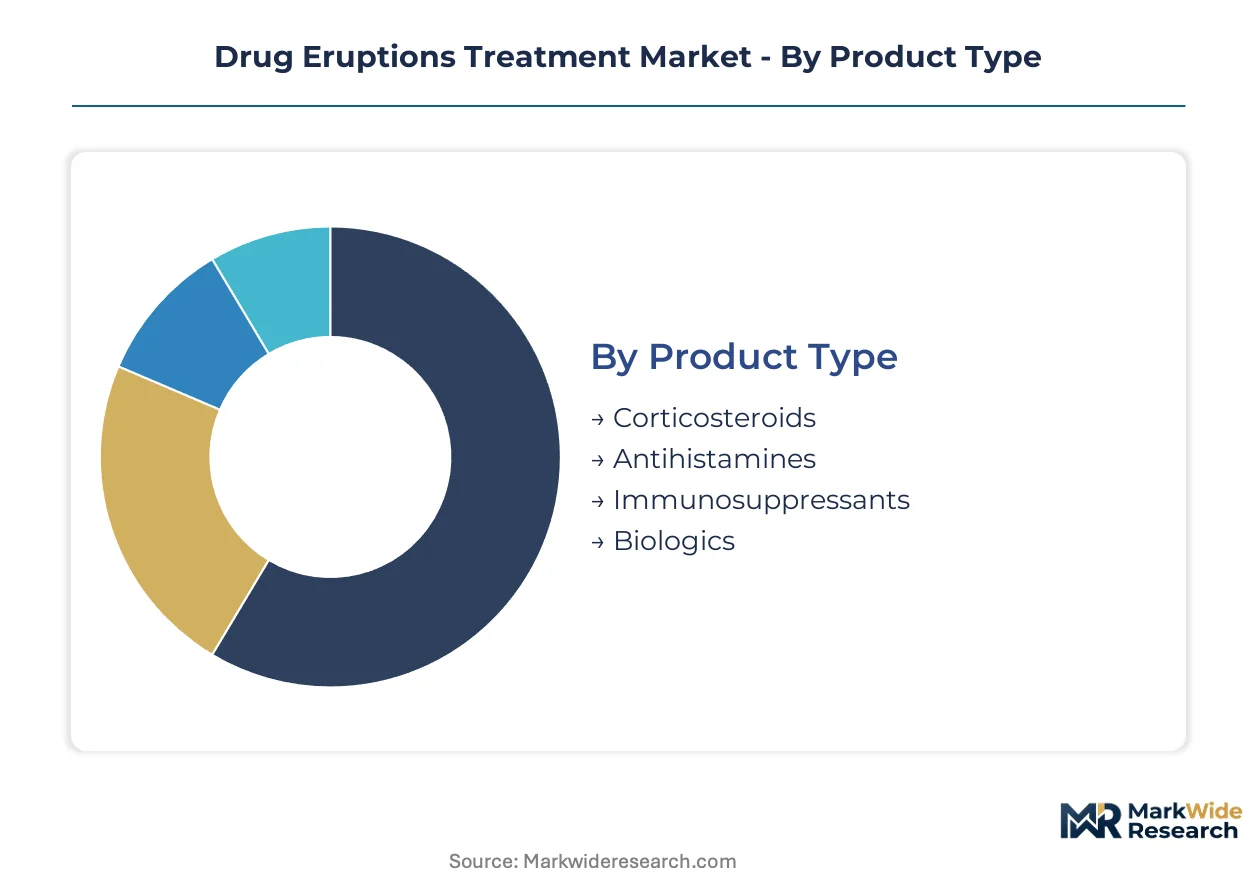
Segmentation in drug eruptions therapeutics reveals how treatment intensity, distribution infrastructure, and prescriber specialization allocate revenue across distinct channel configurations. Each dimension carries implications for cold chain investment, formulary negotiation leverage, and patient monitoring requirements.
Product Type:
Domestic formulation dominates corticosteroid supply chains, while biologics production clusters in FDA-inspected facilities serving export markets through specialty pharmacy networks.
- Corticosteroids:Synthetic glucocorticoid formulations modulate inflammatory cytokine cascades through genomic and non-genomic pathways. Demand concentrates in United States hospital emergency departments managing acute hypersensitivity presentations, constrained by EMA pharmacovigilance frameworks intensifying surveillance for infection risks.
- Biologics:Engineered monoclonal antibodies target IL-4 and IL-13 signaling pathways in refractory cutaneous adverse reactions. Massachusetts and California academic medical centers drive adoption through dedicated cutaneous adverse reaction units, requiring continuous temperature monitoring infrastructure.
- Antihistamines:H1-receptor antagonists block histamine-mediated vascular permeability in mild urticarial eruptions.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites serve as corticosteroid-sparing alternatives in chronic presentations.
Corticosteroids hold the largest share; momentum sits with biologics.
Delivery Mode:
Cost tier stratification separates premium infusion channels from economy oral generics, with margin capture inversely correlated with patient convenience.
- Oral:Systemic absorption through gastrointestinal tract enables outpatient self-administration for mild-to-moderate presentations. Volume concentrates in United States retail pharmacy chains, driven by prior authorization automation reducing access friction for step therapy protocols.
- Infusion:Intravenous delivery achieves rapid therapeutic levels in Stevens-Johnson syndrome stabilization. Academic medical centers in Germany and France capture disproportionate margin pools through centralized pharmacy procurement decoupled from clinical monitoring services.
- Topical:Percutaneous application targets localized inflammation with minimized systemic exposure.
- Injectable:Subcutaneous biologics delivery systems miniaturize injection volumes for step-down protocols.
Oral delivery commands volume leadership; infusion channels claim premium positioning.
Care Setting:
Application severity determines site of care, with hospital-based management reserved for systemic involvement and mucosal detachment risk.
- Hospitals:Inpatient dermatology departments manage cytokine storm presentations requiring intensive monitoring. Demand clusters in United States academic medical centers expanding dedicated cutaneous adverse reaction units, constrained by immunology-trained workforce shortages.
- Specialty Pharmacies:Temperature-controlled distribution networks handle biologics dispensing with integrated patient support programs. United States infrastructure deepens reach into outpatient dermatology clinics through continuous temperature monitoring systems.
- Outpatient Clinics:Community dermatology practices manage mild-to-moderate presentations with oral and topical regimens.
- Home Care:Self-administration protocols extend therapy beyond acute care settings for maintenance phases.
Hospitals anchor acute revenue; specialty pharmacies are climbing the fastest.
End User:
Customer type stratification reflects prescriber specialization depth, with dermatologists commanding biologics access decisions and general practitioners handling first-line presentations.
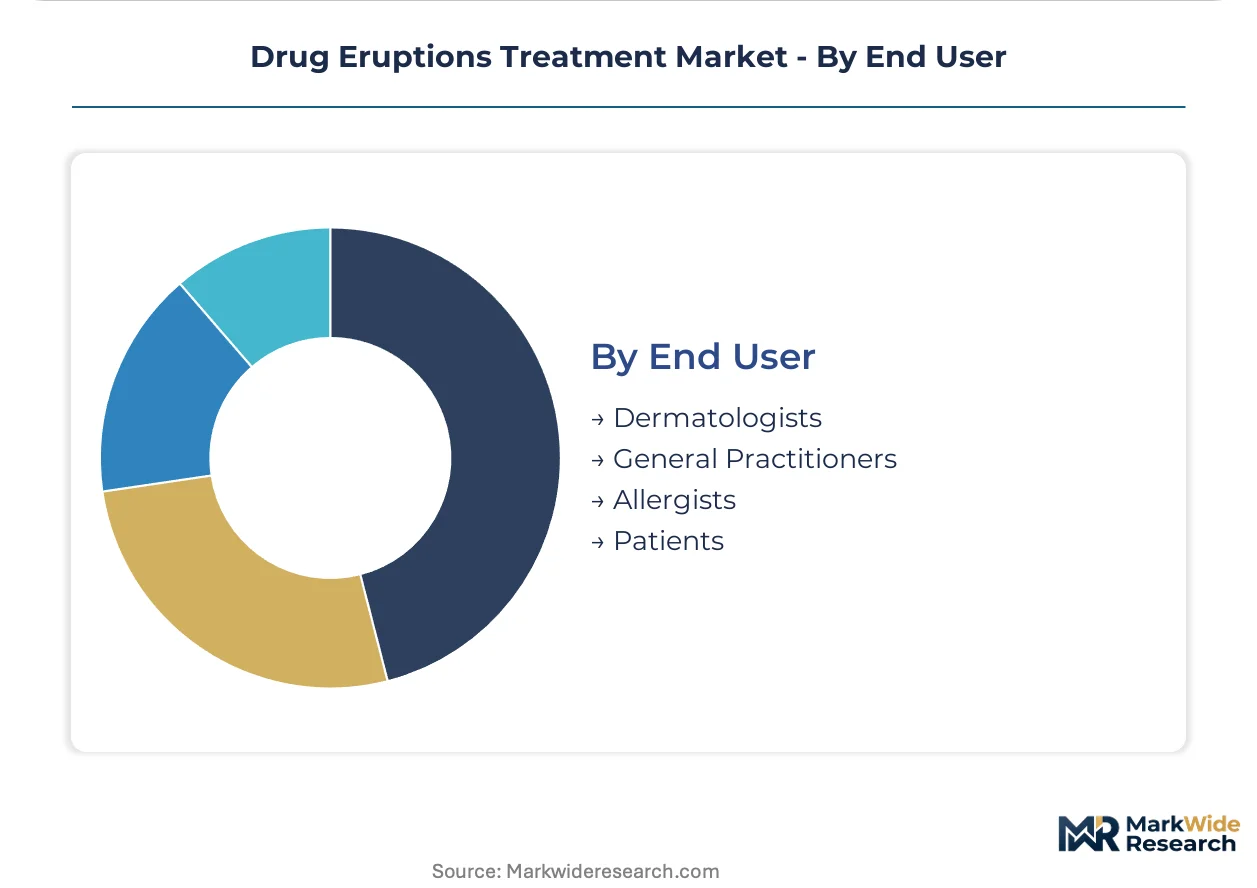
- Dermatologists:Board-certified specialists direct biologics prescribing through hospital formulary committees and prior authorization pathways. Concentration in Massachusetts and California integrated delivery networks pilots outcomes-based contracting for IL-4 inhibitor therapy.
- Patients:Direct access channels expand through subcutaneous self-administration devices enabling home-based maintenance. United States specialty pharmacy networks deepen reach through real-world evidence platforms accelerating access decisions.
- General Practitioners:Primary care gatekeepers initiate corticosteroid therapy for uncomplicated presentations.
- Allergists:Immunology specialists manage hypersensitivity-mediated eruptions with targeted testing protocols.
Dermatologists control premium access; patient-directed channels show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA safety labeling revisions and EMA pharmacovigilance intensification are redirecting investment flows toward markets with mature biologics infrastructure. Hospital formulary expansion for severe cutaneous adverse reaction management concentrates in jurisdictions with established specialty pharmacy networks and academic medical center density.
United States
Massachusetts and California integrated delivery networks pilot outcomes-based contracting for IL-4 inhibitor therapy. FDA post-market surveillance mandates for immunosuppressant-associated infection risks accelerate biologics development prioritization. Academic medical centers in Boston and San Francisco expand dedicated cutaneous adverse reaction units requiring continuous temperature monitoring infrastructure.
Germany
EMA pharmacovigilance frameworks intensify post-market surveillance obligations for topical corticosteroid formulations. REACH compliance constraints on excipient chemistry force reformulation of established products entering German markets. Concentrated demand in Bavaria and North Rhine-Westphalia flows through centralized hospital pharmacy procurement decoupled from clinical monitoring services.
France
ANSM guidance on percutaneous absorption thresholds compresses development timelines for new topical entrants. Hospital-based dermatology departments in Île-de-France and Auvergne-Rhône-Alpes manage cytokine storm presentations requiring intensive monitoring. French academic centers anchor EU-wide adoption patterns for biologics in Stevens-Johnson syndrome stabilization protocols.
Japan
PMDA review cycles for supplemental immunosuppressant indications face extended timelines delaying revenue diversification. METI incentives for cold chain infrastructure investment support biologics stability requirements in community hospital settings. Osaka and Tokyo metropolitan clusters concentrate dermatology specialist training programs for cytokine cascade modulation.
India
CDSCO accelerated approval pathways for biosimilars create entry opportunities in corticosteroid-sparing therapy segments. Maharashtra and Gujarat manufacturing clusters supply active pharmaceutical ingredient precursors to global formulation networks. Domestic specialty pharmacy infrastructure remains underdeveloped, constraining biologics reach beyond tertiary hospital centers.
Drug Eruptions Treatment Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with immunology portfolios and mid-scale generic specialists with corticosteroid manufacturing depth. Market structure exhibits tiered consolidation with three to five dominant positions in biologics and fragmented supply in oral generics. Strategic archetypes include global immunology platforms, hospital-focused injectable suppliers, and regional topical formulators. Competitive moves center on formulary contracting leverage and cold chain infrastructure partnerships.
Among diversified pharmaceutical conglomerates, Johnson & Johnson, Pfizer Inc., and Novartis AG occupy positions reflecting distinct capability emphases. Johnson & Johnson exemplifies integrated dermatology channel control spanning hospital formulary access to outpatient dispensing. Pfizer Inc. anchors scale-driven corticosteroid supply across multiple delivery modes through global manufacturing footprint. Novartis AG represents biologics specialization in immunology-driven skin reactions, with positioning shaped by targeted IL pathway expertise.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| Novartis AG |
| Bausch Health Companies Inc. |
| Anuh Pharma Ltd. |
| Avik Pharma |
| Hovione |
| Merck & Co., Inc. |
| Sanofi |
| Others |
Supply & Pricing Matrix
Capacity utilization at FDA-inspected biologics facilities shapes both supply concentration and price floors for drug eruptions therapeutics, with Massachusetts and California academic medical centers absorbing premium infusion pricing while oral corticosteroid volumes concentrate in retail pharmacy chains operating on thinner margins.
Pricing Analysis
Certification level creates the primary spread between premium biologics and economy oral generics. Three-tier pricing structure across premium infusion, standard injectable, and economy oral levels reflects ISO 13485 compliance costs and cold chain infrastructure requirements. Pricing pressure stems from payer step therapy protocols demanding real-world evidence for biologics access. General practitioners exhibit highest price sensitivity, while hospital formulary committees prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate biologics distribution through United States specialty pharmacy networks, while strategic stockpiling of corticosteroid active pharmaceutical ingredients concentrates in Maharashtra and Gujarat manufacturing clusters. Formulation chemistry depends on precursor supply chains anchored in India and China, with REACH compliance constraining European excipient sourcing. Single-source vulnerability for IL-4 inhibitor cell lines creates concentration risk. Distribution runs through temperature-controlled networks serving academic medical centers and outpatient dermatology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drug eruptions therapeutics present a defensive-moat market structure where regulatory entrenchment through FDA label expansions and EMA pharmacovigilance compliance creates durable barriers against generic substitution.
For Market Incumbents: Consolidate formulary access through outcomes-based contracting with Massachusetts and California integrated delivery networks. Acquire cold chain infrastructure partnerships to defend margin position against biosimilar entrants in corticosteroid-sparing segments. Prioritize ISO 13485 certification maintenance as a competitive filter. For New Entrants and Emerging Players: CDSCO accelerated approval pathways for biosimilars offer the fastest certification fast-track into corticosteroid-sparing therapy segments. Target pediatric indication expansion in Stevens-Johnson syndrome prophylaxis as underpenetrated white space. Deploy real-world evidence platforms as the primary go-to-market angle for prior authorization automation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biologics specialists with IL-4 and IL-13 pathway expertise over legacy corticosteroid manufacturers facing commoditization pressure. Long-term viability rests on regulatory navigation capabilities and academic medical center relationships. Watch immunology-trained dermatology workforce expansion rates as the inflection indicator for biologics adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biologics Manufacturing Scale-Up | Expands capacity at FDA-inspected facilities serving Massachusetts and California academic medical centers. |
| Prior Authorization Automation Platform | Accelerates payer access decisions for IL-4 inhibitor therapy through real-world evidence integration. |
| Pediatric Indication Expansion | Captures white space in age-specific Stevens-Johnson syndrome prophylaxis dosing regimens. |
| Cold Chain Infrastructure Partnership | Secures continuous temperature monitoring systems for biologics stability requirements. |
| EU MDR Compliance Services | Delivers REACH formulation chemistry consulting for topical preparations entering German and French markets. |
Research Methodology
Initial hypotheses were tested against primary input from hospital formulary directors, dermatology department heads, specialty pharmacy procurement managers, and payer access specialists and refined through secondary validation against FDA filings, EMA pharmacovigilance databases, ClinicalTrials.gov records, and hospital procurement contracts. Bottom-up patient-volume estimates and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Variance decomposition across product type, delivery mode, care setting, and prescriber specialization dimensions structured the analytical framework. CAGRs were derived from modeled patient population growth, treatment penetration rates, and pricing trajectory assumptions. Forecast inputs incorporated biologics adoption curves in academic medical centers and corticosteroid volume trends in retail pharmacy channels.
Decision-makers should treat outputs as directional under stable regulatory enforcement and payer policy continuity; material deviation would warrant model refresh. Revision becomes warranted when FDA label expansion timelines or EMA pharmacovigilance intensity crosses thresholds that alter competitive positioning dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
Apixaban Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Ketoprofen API Market
Pharmacology
Prescription Narcotic Cough Preparations and Expectorants Market
Pharmacology
Semaglutide API Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Ibuprofen API Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Propranolol Drug Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Medication Adherence Market
Pharmacology
Hypertension Drug Market