
 Dental Composite Filling Market | 2026-2036
Dental Composite Filling Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Composite Filling Market Insights
Buyer concentration among dental clinics is shifting toward multi-site practice networks and dental service organizations that negotiate centralized supply contracts. Dentsply Sirona leverages its integrated equipment-consumables platform to lock in recurring composite orders across these expanding networks. GC Corporation anchors its position through proprietary nano-ceramic filler technology that commands preference in Japanese and Southeast Asian markets. Envista Holdings competes by extending its Kerr brand portfolio across price tiers while sustaining direct sales relationships with high-volume clinic chains.
Dental composite filling denotes a tooth-colored restorative material comprising a resin matrix—typically Bis-GMA, UDMA, or TEGDMA—loaded with inorganic filler particles such as silica or barium glass, cured via visible-light photoinitiation to achieve compressive strength exceeding 300 MPa. Its primary purpose is to restore carious lesions and fracture defects while matching natural tooth aesthetics, displacing amalgam in anterior and visible posterior applications. Nanohybrid composites now dominate premium positioning due to superior polish retention and wear resistance, while flowable formulations capture fastest-growing share in pediatric and minimally invasive cavity preparations. Universal composites occupy the volume core as clinicians prioritize single-shade simplicity over layered aesthetic techniques.
The FDA regulates dental composites as Class II medical devices under 21 CFR 872, requiring substantial equivalence demonstrations for new formulations, while the EU MDR imposes stricter clinical evaluation and post-market surveillance obligations through notified body review. ISO 4049 sets international benchmarks for physical and chemical properties, including water sorption and radiopacity thresholds that manufacturers must document for market access. Stakeholders should monitor evolving biocompatibility testing standards and recyclability mandates that will reshape material selection criteria and supplier qualification protocols.
Market Dynamics
Dental service organizations now command procurement decisions for thousands of North American practices, compressing supplier margins while locking in multi-year volume commitments for nanohybrid and universal composite formulations.
Growth Catalysts
- EU MDR reclassification:Permanent filling substances now face stricter biocompatibility documentation, accelerating replacement cycles for older resin formulations as clinics preempt compliance deadlines.
- Pediatric dentistry expansion:Flowable composites capture rising cavity preparation volumes in children's dental segments due to simplified placement protocols and reduced chair time requirements.
- Tokyo polymer cluster:Precision filler synthesis capabilities concentrated in the greater Tokyo metropolitan area enable rapid iteration of nano-ceramic particle architectures for premium restorative lines.
Market Restraints
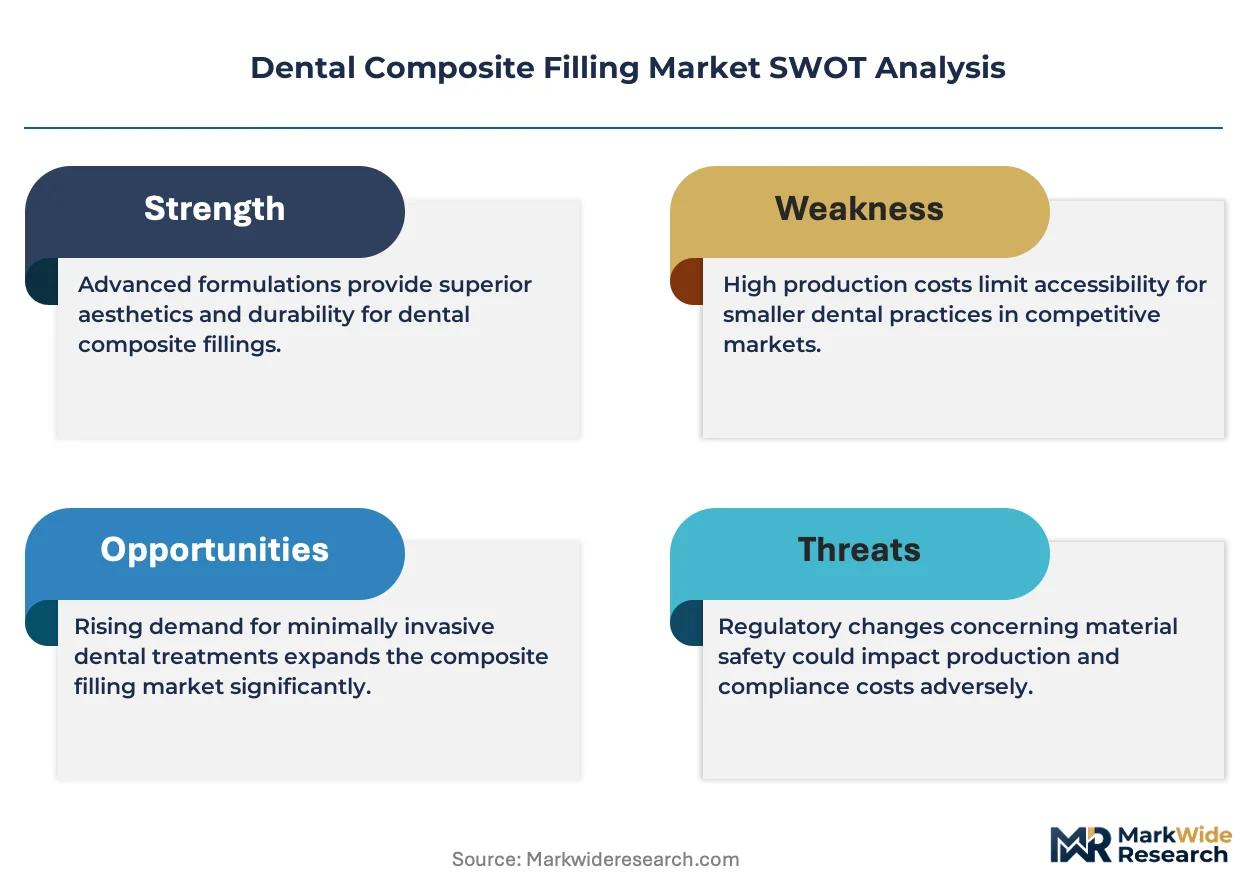
- Bis-GMA monomer cost volatility:Petrochemical feedstock fluctuations for bisphenol A derivatives compress gross margins for mid-tier composite manufacturers without captive resin production.
- Photoinitiator supply concentration:German and Japanese specialty chemical houses control 90% of camphorquinone and TPO supply, creating single-source vulnerability for light-cure formulation lines.
- Amalgam substitution ceiling:Posterior load-bearing applications in molar restorations retain metallic alloy preference where insurance reimbursement differentials persist.
Strategic Opportunities
- Indian dental manufacturing:Domestic production incentives under the PLI scheme attract composite resin assembly for price-sensitive Asian and African export markets.
- Chairside 3D printing convergence:Photopolymerizable composite inks compatible with dental CAD/CAM workflows open same-day permanent restoration fabrication in high-volume clinic chains.
- California biomonitoring mandates:State-level restrictions on bisphenol A release create first-mover advantage for Bis-GMA-free alternative resin platforms.
Industry Challenges
- Color-matching technician scarcity:Layered aesthetic techniques requiring shade selection expertise face training pipeline constraints as dental schools emphasize single-shade universal placement.
- ISO 4049 certification timelines:Water sorption and radiopacity testing protocols extend new product introduction cycles by 18-24 months for reformulated filler loadings.
- Legacy amalgam waste handling:EPA mercury separation requirements impose capital equipment burdens on practices transitioning composite-dominant workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Composite Filling Market |
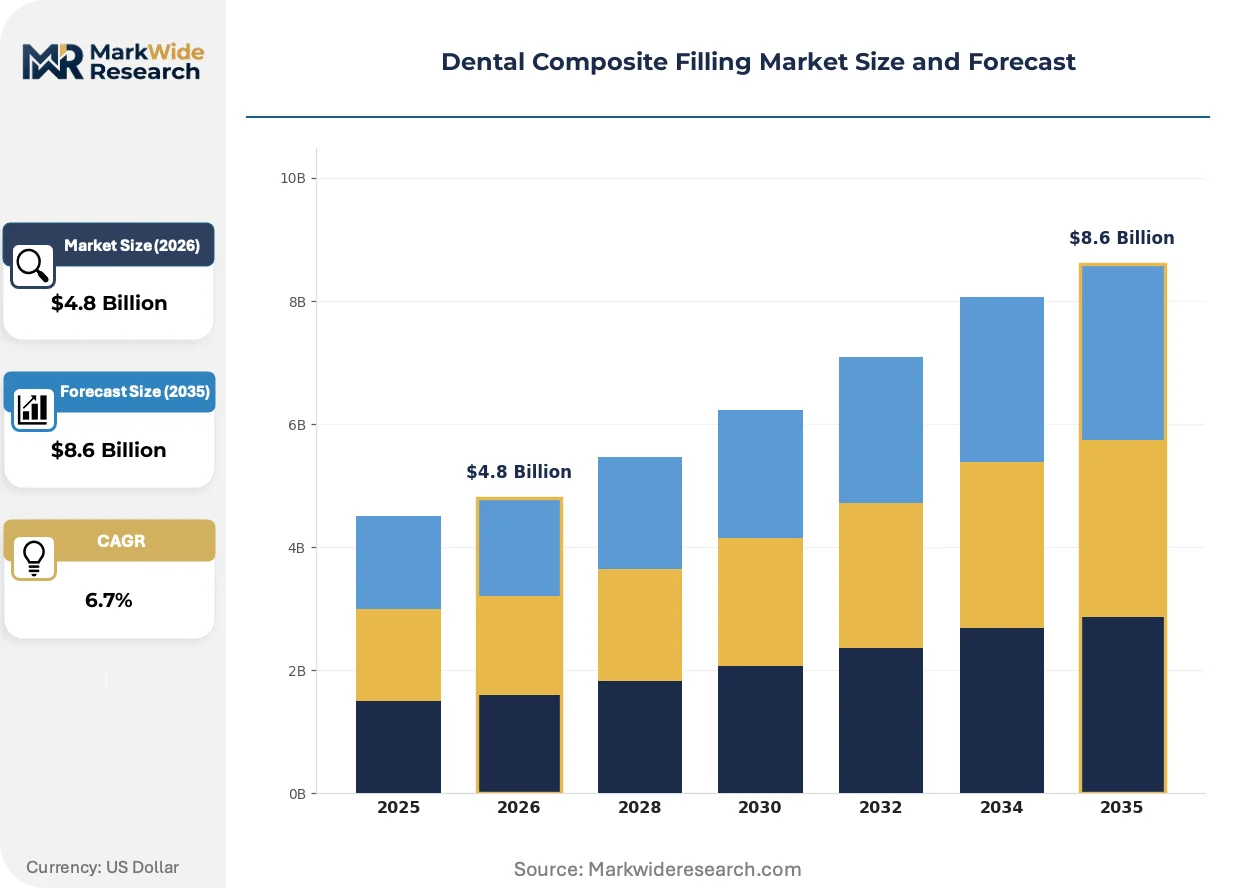
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Composites, Microhybrid Composites, Nanohybrid Composites, Flowable Composites End User: Dental Clinics, Hospitals, Private Practices, Academic Institutions Application: Restorative Procedures, Aesthetic Treatments, Preventive Care, Emergency Dental Services Distribution Channel: Direct Sales, Online Retailers, Wholesalers, Distributors |
| Companies Covered | Envista Holdings, Mitsui Chemicals, Dentsply Sirona, Kuraray Noritake Dental, VOCO GmbH, 3M Company, GC Corporation, Ultradent Products Inc., Ivoclar Vivadent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Composite Filling Market Trends and Innovations
Bulk-fill composite technology is compressing restoration placement protocols while regulatory chemistry restrictions are forcing resin matrix reformulation across major manufacturing clusters.
Bulk-fill composites with modified photoinitiator systems and increased translucency permit 4-6 mm incremental placement, eliminating traditional layering steps. Multi-site dental service organizations in the United States and Germany are standardizing these formulations to reduce chair time per restoration. This technology is expanding into pediatric and geriatric segments where patient compliance and saliva control challenge conventional incremental techniques.
REACH restrictions on methacrylate monomer classifications are compelling European manufacturers to document toxicological profiles for UDMA and TEGDMA constituents. The European Chemicals Agency's 2023-2025 substance evaluation roadmap targets residual monomer leaching thresholds. German dental material producers in Baden-Württemberg are responding with accelerated bio-based resin platform development to preempt regulatory exclusion.
Group purchasing organizations now aggregate demand across 500-2,000 practice locations, extracting price concessions previously available only to hospital systems. Independent dental distributors in Western Europe face disintermediation as these buying consortia establish direct manufacturer relationships. This consolidation is most visible in France and the United Kingdom where dental corporate chains approach 35% of operative procedure volume.
Dental Composite Filling Market Segmentation
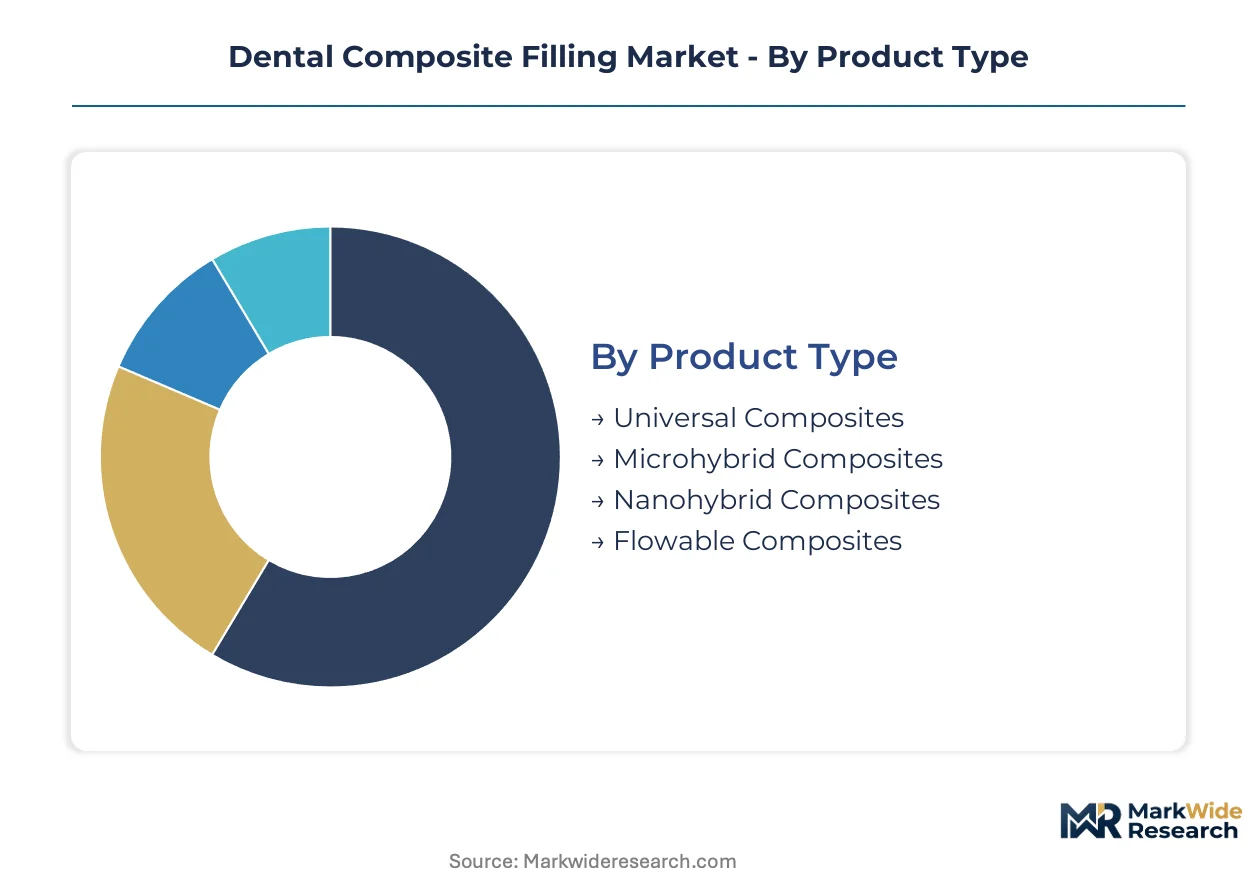
Dental composite filling procurement divides sharply across clinical settings and procedural requirements, with ISO 4049 compliance thresholds and FDA 510(k) pathways creating divergent qualification burdens for each segment. Understanding these fault lines exposes where formulation investments concentrate and which distribution channels capture margin.
Product Type:
FDA Class II device classification applies uniformly across all resin formulations, yet ISO 4049 water sorption and radiopacity testing intensity varies with filler particle architecture and matrix chemistry.
- Nanohybrid Composites:Silica-zirconia filler clusters below 100 nanometers deliver superior polish retention and wear resistance for anterior aesthetic zones. German dental clinics in Baden-Württemberg command premium positioning here, driven by patient willingness to pay for shade-matched restorations.
- Universal Composites:Single-shade formulations with simplified photoinitiator systems reduce chair time and technician training requirements. Multi-site dental service organizations in the United States consolidate procurement around these lines to standardize inventory across hundreds of locations.
- Flowable Composites:Low-viscosity resin matrices with reduced filler loading adapt to minimally invasive cavity preparations. Pediatric dentistry segments favor these for simplified placement protocols.
- Microhybrid Composites:Mid-range filler distribution balances strength and handling characteristics for general restorative applications. Price-sensitive private practices retain these for posterior load-bearing restorations.
Universal composites sit at the top of the volume ranking, with flowable formulations climbing the fastest.
End User:
Procurement scale and contract structure diverge dramatically between institutional buyers and independent operators, reshaping which distribution channels retain relevance.
- Dental Clinics:Corporate chains and dental service organizations negotiate multi-year supply agreements with direct manufacturer relationships. These buyers extract volume pricing on nanohybrid and universal formulations while disintermediating traditional distributors.
- Private Practices:Independent operators rely on group purchasing organizations to aggregate demand across hundreds of locations. French and British practice networks increasingly consolidate procurement through these consortia.
- Hospitals:Integrated health systems apply capital equipment procurement discipline to consumable purchasing, favoring single-source contracts with integrated equipment-consumables platforms.
- Academic Institutions:Dental schools and research hospitals prioritize training compatibility and bulk pricing over aesthetic performance, sustaining demand for mid-tier microhybrid lines.
Dental clinics capture the dominant procurement volume, with hospitals expanding most quickly as health systems integrate dental services.
Application:
Clinical indication determines restoration durability requirements and drives formulation selection toward specific compressive strength and polish retention profiles.
- Restorative Procedures:Caries excavation and defect repair command the largest material volumes, with bulk-fill technology compressing placement protocols in high-throughput settings. German and Japanese manufacturers lead incremental cure system innovation.
- Aesthetic Treatments:Layered shade-matching techniques for anterior restorations require premium nanohybrid formulations with superior optical properties. Tokyo-area polymer clusters supply precision filler synthesis for these applications.
- Preventive Care:Resin-modified glass ionomer hybrids and pit-and-fissure sealants occupy this segment, with flowable composites capturing share in pediatric applications.
- Emergency Dental Services:Rapid-setting formulations with simplified handling characteristics serve urgent care settings where moisture control and patient compliance challenge conventional techniques.
Restorative procedures anchor volume demand, with aesthetic treatments gaining share fastest as patient expectations rise.
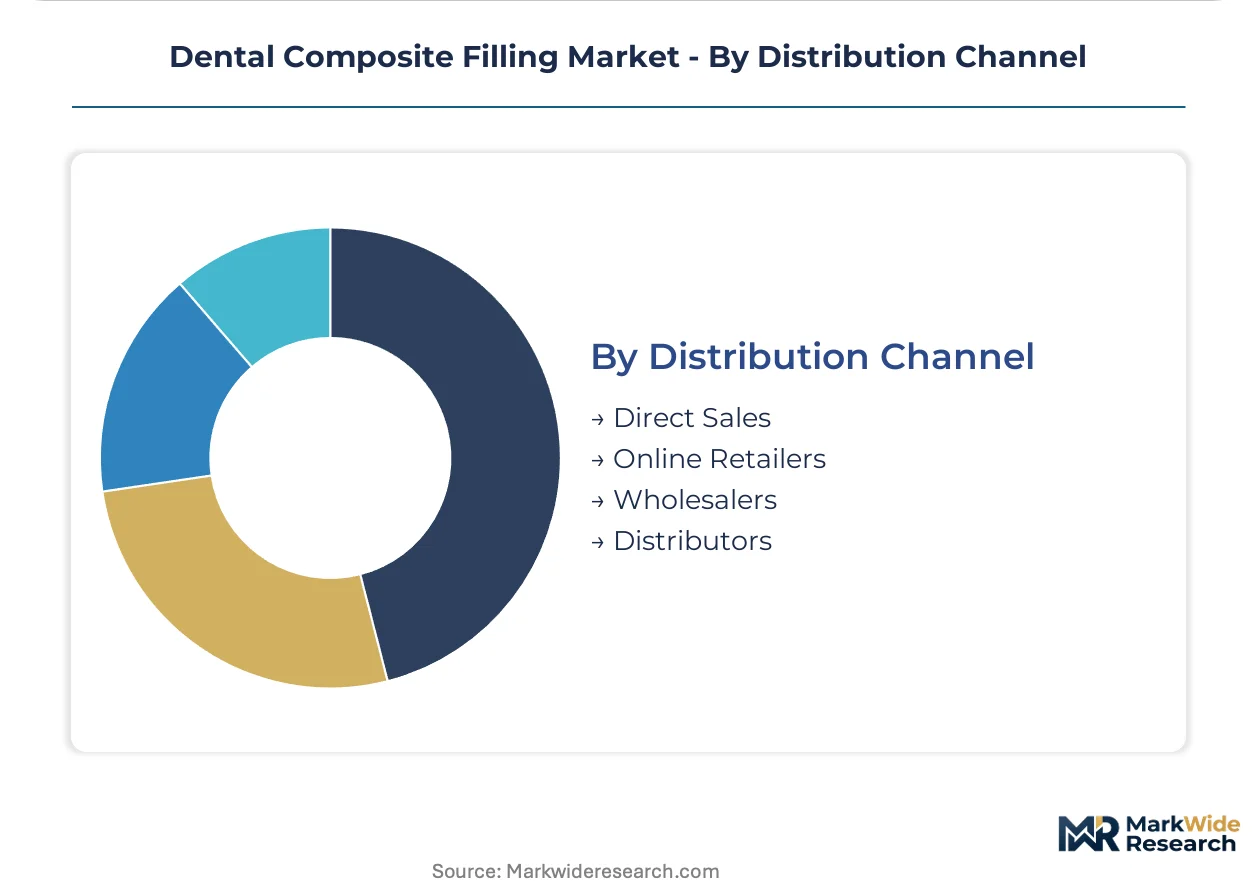
Distribution Channel:
Channel selection tracks buyer scale and geographic concentration, with direct manufacturer relationships displacing traditional intermediaries in consolidated markets.
- Direct Sales:Manufacturers maintain dedicated field forces for dental service organizations and hospital systems, locking in multi-year contracts with volume commitments and technical support bundling.
- Distributors:Regional wholesalers retain relevance in fragmented markets where independent practices predominate, though margin compression accelerates consolidation.
- Online Retailers:E-commerce platforms capture growing share among small practices seeking price transparency and just-in-time inventory management.
- Wholesalers:Traditional dental supply houses face disintermediation as group purchasing organizations establish direct manufacturer relationships, compressing their role to logistics fulfillment.
Direct sales command the largest revenue share, with online retailers expanding most quickly among smaller practice segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dental manufacturing cluster commands premium formulation capabilities, while Japan's precision polymer synthesis anchors supply advantages for nano-ceramic architectures across Asian markets.
United States
Dental service organizations now consolidate procurement for thousands of practices, extracting multi-year volume commitments on nanohybrid and universal composite lines. The FDA's 510(k) premarket notification pathway for Class II dental devices under 21 CFR 872 requires substantial equivalence demonstrations that extend new product introduction timelines. Private practice networks in California face state-level biomonitoring mandates on bisphenol A release, accelerating demand for alternative resin platforms.
Germany
Baden-Württemberg's dental material producers drive premium nanohybrid development for shade-matched anterior restorations. The EU Medical Device Regulation reclassification of permanent filling substances imposes stricter biocompatibility documentation through notified body review. REACH restrictions on methacrylate monomer classifications compel manufacturers to accelerate bio-based resin platform development in the Stuttgart-Karlsruhe corridor.
Japan
The greater Tokyo metropolitan area concentrates precision filler synthesis capabilities for rapid iteration of nano-ceramic particle architectures. METI oversight of medical device quality management systems aligns with international harmonization efforts under the IMDRF framework. GC Corporation anchors regional supply chains through proprietary nano-ceramic technology that commands preference across domestic and Southeast Asian markets.
India
Domestic production incentives under the PLI scheme attract composite resin assembly operations targeting price-sensitive Asian and African export markets. CDSCO medical device regulations impose import licensing requirements that favor local manufacturing partnerships. Maharashtra and Gujarat industrial zones host emerging dental material facilities serving regional distribution networks.
China
Rising dental clinic chains in Shanghai and Beijing drive volume procurement of flowable composites for pediatric and minimally invasive applications. NMPA medical device registration requirements for dental materials align with international standards while maintaining domestic testing protocols. The Yangtze River Delta region hosts contract manufacturing operations for multinational resin formulation brands.
Dental Composite Filling Market Competitive Landscape
German producers anchor the premium formulation tier; Japanese specialists hold supply advantages in precision filler synthesis. The vendor structure concentrates around integrated equipment-consumables platforms and dedicated resin compounders. Three archetypes dominate: multinational dental conglomerates with bundled offerings, regional specialists in nano-ceramic technology, and mid-tier compounders serving price-sensitive markets. Competitive moves center on direct sales relationships with dental service organizations and accelerated bio-based resin development to preempt regulatory chemistry restrictions.
Within the integrated platform tier, Dentsply Sirona exemplifies the equipment-consumables bundling strategy that locks in recurring composite orders across expanding clinic networks. GC Corporation represents the regional specialist archetype, anchoring its position through proprietary technology concentration in the Japanese market. Envista Holdings occupies the multi-brand portfolio position, extending its Kerr brand lines across price tiers while sustaining direct sales relationships with high-volume clinic chains.
| Leading Market Players |
|---|
| Envista Holdings |
| Mitsui Chemicals |
| Dentsply Sirona |
| Kuraray Noritake Dental |
| VOCO GmbH |
| 3M Company |
| GC Corporation |
| Ultradent Products Inc. |
| Ivoclar Vivadent |
| Others |
Pricing and Supply Chain Analysis
EU REACH restrictions on methacrylate monomer classifications gate qualified supply access and premium-tier pricing power for dental composite manufacturers, forcing reformulation investments that stratify market positions between compliant premium lines and legacy economy formulations.
Pricing Analysis
Capacity additions in India under the PLI scheme are reshaping price floors for economy-tier universal composites, compressing margins for mid-tier compounders without captive resin production. Three-tier pricing structure across premium nanohybrid, standard universal, and economy microhybrid levels dominates procurement, with ISO 4049 certification grade and volume scale driving price differentiation. Cost compression in the standard tier is intensifying because dental service organizations extract multi-year volume commitments with technical support bundling. Pediatric dentistry segments show highest price sensitivity due to reimbursement differentials, while German aesthetic clinics demonstrate lowest sensitivity for shade-matched anterior formulations.
Supply Chain Analysis
Photoinitiator supply rests on German and Japanese specialty chemical houses controlling camphorquinone and TPO production, creating single-source vulnerability for light-cure formulation lines. Raw material dependencies center on bisphenol A derivatives for Bis-GMA synthesis, nano-ceramic fillers from Tokyo-area precision polymer clusters, and barium glass radiopaque additives from Baden-Württemberg processors. Tariff exposure on Chinese-sourced silica fillers threatens margin stability for price-sensitive Asian export markets. Distribution runs through direct manufacturer relationships with dental service organizations, disintermediating traditional wholesalers in consolidated North American and Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where patient willingness to pay for aesthetic outcomes is shifting procurement toward nanohybrid formulations with superior polish retention and shade-matching capabilities.
For Market Incumbents: Anchor defensive positioning through backward integration into photoinitiator supply chains and accelerated bio-based resin platform development to preempt EU MDR compliance deadlines. Consolidate procurement relationships with expanding dental service organizations by bundling equipment-consumables platforms, while investing in ISO 4049 certification capacity to maintain premium-tier access against emerging Indian compounders.
For New Entrants and Emerging Players: Capture white-space opportunity in price-sensitive African and Southeast Asian markets where domestic production incentives under India's PLI scheme enable cost-competitive export positioning. Target flowable composite segments in pediatric dentistry where simplified placement protocols reduce barrier to entry, and pursue direct online retail channels among small independent practices seeking price transparency.
For Investors and Strategic Acquirers: Roll-up economics work for regional nano-ceramic specialists because proprietary filler synthesis capabilities command durable preference in aesthetic restoration segments with limited substitution threat. Over the medium-term horizon, acquisition focus should center on Baden-Württemberg and Tokyo-area compounders with established notified body relationships. The signal to watch is California biomonitoring mandate expansion to additional states, which would accelerate demand inflection for Bis-GMA-free alternative platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Resin Platform Development | REACH compliance investment preempts regulatory exclusion for European manufacturing operations. |
| Direct Sales Force Expansion | Dental service organization relationships lock in multi-year volume commitments with technical support bundling. |
| Photoinitiator Backward Integration | Captive camphorquinone supply mitigates single-source vulnerability from German and Japanese specialty houses. |
| Bulk-Fill Technology Line Extension | Modified photoinitiator systems reduce chair time per restoration in high-throughput pediatric and geriatric segments. |
| Online Retail Channel Development | E-commerce platforms capture growing share among small practices seeking just-in-time inventory management. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental materials procurement managers, biomedical engineers at hospital systems, GPO contracts specialists, and regulatory affairs leads at notified bodies with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, ISO 4049 certification records, and dental school curriculum databases. Bottom-up demand modeling across clinic types and top-down supply verification across manufacturing clusters were triangulated for consistency.
The forecast window anchored historical reference periods to procedural volume trends across restorative, aesthetic, and pediatric application segments, with CAGR derivation reflecting modeled interactions between product type, end-user procurement scale, and regional regulatory cluster evolution. Segmentation dimensions included filler particle architecture, clinic ownership structure, clinical indication, and distribution channel complexity. Industry-specific inputs incorporated dental service organization expansion rates and biomonitoring mandate adoption patterns.
Feedstock cost volatility, regulatory chemistry reclassification, and photoinitiator supply disruption are the dominant revision risks that could alter trajectory assumptions across the projection horizon. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Sealants Market
Dental Devices
Dental Suction Mirror Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Digital Facebow Market
Dental Devices
Global Dental Restorative Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Global Digital Dentistry Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Dental Hand Tools Market
Dental Devices
Dental Chair Market
Dental Devices
Global Periodontal Market
Dental Devices
Dental Aligners Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
Dental Needle Market
Dental Devices
Malocclusion Market