
 Dental Splints Market | 2026-2036
Dental Splints Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Splints Market Intelligence
Digital intraoral scanning and chairside milling is fragmenting traditional dental laboratory workflows for splint production. Glidewell Dental leverages its vertically integrated milling centers to sustain cost advantages across high-volume occlusal guard manufacturing. Dentsply Sirona anchors its position through proprietary CAD software that locks clinicians into closed-architecture design ecosystems. Henry Schein competes by controlling distribution density, placing splint materials and fabrication services within reach of solo-practice dentists.
Dental splints are removable intraoral devices fabricated from thermoplastic, acrylic, or polycarbonate substrates, designed to redistribute occlusal forces and protect dentition from parafunctional loading. Their primary commercial purpose spans bruxism management, post-surgical stabilization, and temporomandibular joint therapy, with thickness tolerances typically ranging from 1.5 mm to 4.0 mm depending on indication. Occlusal splints occupy the dominant share of product-type revenue, while thermoplastic materials command expanding preference due to biocompatibility certifications and repeatability in injection molding. Among end users, dental clinics capture the steepest growth trajectory as chairside production eliminates laboratory turnaround delays.
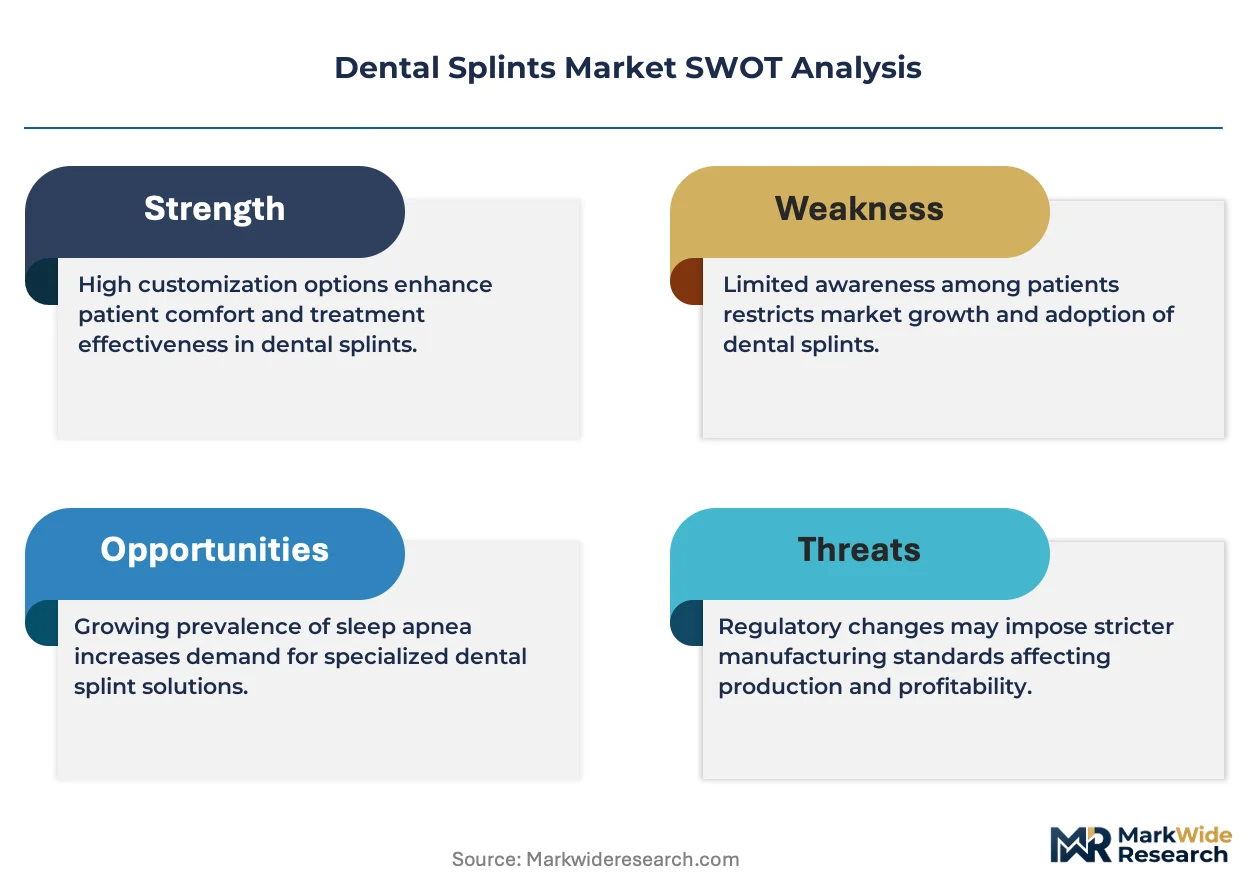
FDA 510(k) premarket notification requirements shape product entry timelines for domestic manufacturers, while ISO 13485 quality management standards govern export eligibility into European and Asia-Pacific territories. The EU Medical Device Regulation imposes stricter clinical evidence thresholds on custom-made dental appliances, elevating compliance costs for smaller laboratories. Stakeholders must monitor how FDA draft guidance on 3D-printed patient-matched devices resolves material validation protocols, as this determination will either accelerate or constrain additive manufacturing adoption across splint fabrication.
Market Dynamics
Chairside CAD/CAM fabrication is compressing traditional dental laboratory workflows, forcing incumbents to retool toward digital design services or risk disintermediation by clinic-direct manufacturing.
Growth Catalysts
- FDA 510(k) streamlining:Expedited premarket notification pathways for CAD/CAM-manufactured devices compress domestic production timelines and accelerate clinic adoption of in-house fabrication.
- Thermoplastic biocompatibility certifications:ISO 10993-compliant injection-moldable polymers enable repeatable, scalable production of occlusal appliances with reduced remanufacture rates.
- Temporomandibular disorder reimbursement clarity:United States private payer coding refinements strengthen specialist willingness to prescribe custom-fabricated splints over generic alternatives.
Market Restraints
- EU MDR clinical evidence thresholds:Stricter documentation requirements for custom-made appliances elevate compliance costs and extend market access timelines for smaller European laboratories.
- Acrylic monomer price volatility:Petrochemical feedstock fluctuations compress margin stability for conventional heat-cure splint manufacturers dependent on methyl methacrylate supply.
- Intraoral scanner hardware concentration:Proprietary scanner ecosystems lock clinics into single-vendor software workflows, constraining interoperability and supplier switching.
Strategic Opportunities
- Underpenetrated Southeast Asian dental clinics:Rapid private practice expansion in Vietnam and Indonesia creates first-mover potential for chairside milling service partnerships.
- Additive manufacturing material validation:FDA draft guidance resolution on 3D-printed patient-matched devices will either unlock or constrain photopolymer adoption across splint fabrication.
- Direct-to-patient subscription models:Tele-dentistry platforms in the United States are piloting remote impression kits and mail-order occlusal guard replacements, bypassing traditional clinic channels.
Industry Challenges
- CAD design technician scarcity:Dental laboratories face recruiting friction for operators proficient in 3Shape, Exocad, and proprietary chairside design modules.
- Legacy plaster cast integration:Hybrid workflows requiring physical model verification create bottlenecks and quality variance in practices transitioning to fully digital pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Splints Market |
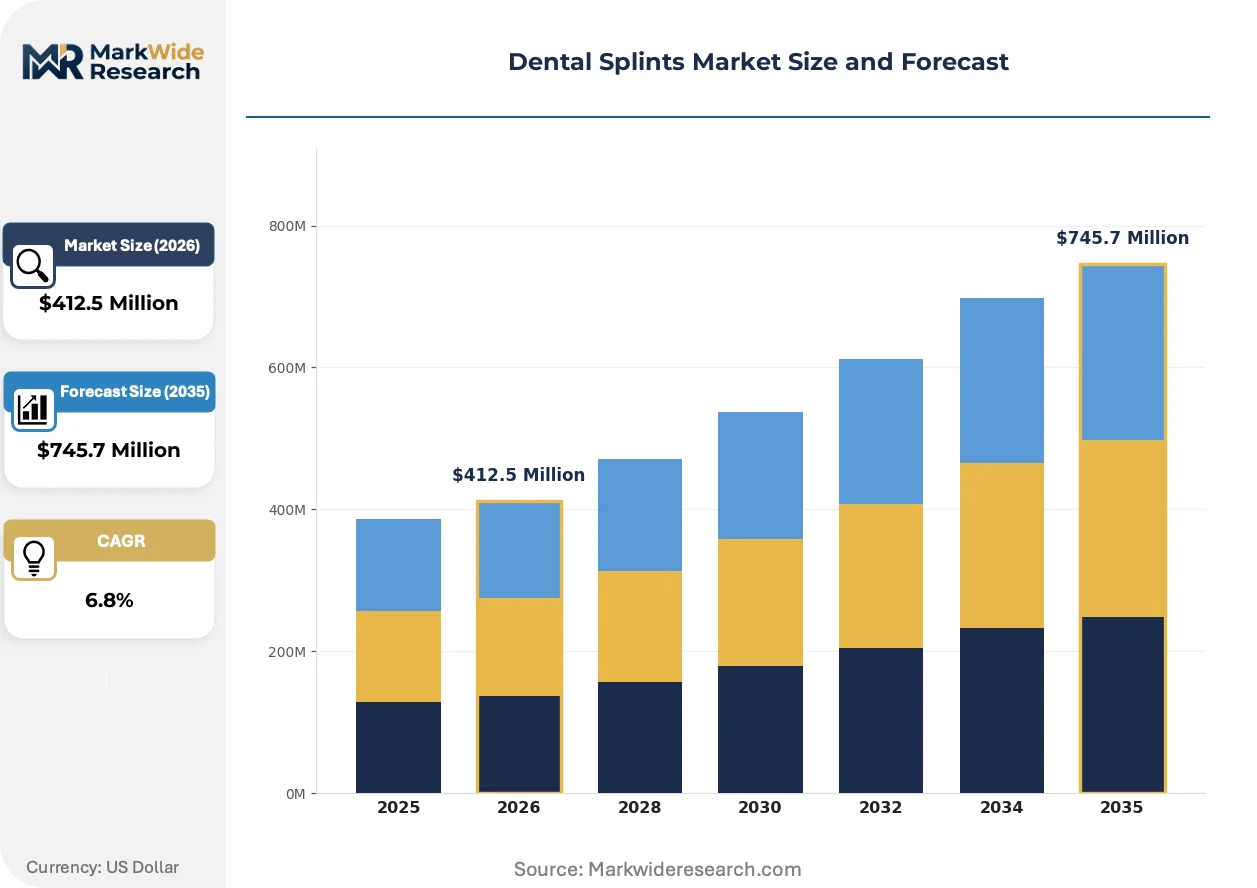
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Occlusal Splints, Interocclusal Splints, Retainers, Stabilization Splints Material: Polycarbonate, Acrylic, Thermoplastic, Silicone End User: Dentists, Orthodontists, Hospitals, Dental Clinics Application: Treatment of Bruxism, Post-Operative Care, Tooth Alignment, Jaw Discomfort |
| Companies Covered | Glidewell Dental, Keystone Industries, Dentsply Sirona, Ultradent Products, Henry Schein, 3M, 3D Systems, Septodont, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Splints Market Strategic Shifts & Innovations
Digital intraoral capture and automated fabrication are collapsing the traditional separation between diagnosis, design, and delivery in occlusal appliance therapy.
Intraoral scanning hardware is digitizing patient data capture at the point of care. Solo-practice dentists and group dental service organizations are deploying tabletop scanners from Dentsply Sirona and 3Shape at accelerating rates. This technology is digitizing the upstream workflow, eliminating alginate impressions and compressing case initiation from days to minutes.
The EU Medical Device Regulation is tightening clinical evidence requirements for custom-made dental appliances. Manufacturers must now compile systematic biological safety and performance documentation previously exempt under the Medical Device Directive. Smaller European laboratories are responding by consolidating or outsourcing regulatory affairs functions to specialized consultancies.
Subscription-based occlusal guard replacement is displacing single-transaction procurement in United States direct-to-consumer channels. Tele-dentistry platforms are bundling remote monitoring with quarterly splint refresh deliveries. This model concentrates most visibly in sleep medicine adjacent bruxism management, where patient compliance monitoring justifies ongoing engagement fees.
Dental Splints Market Segmentation
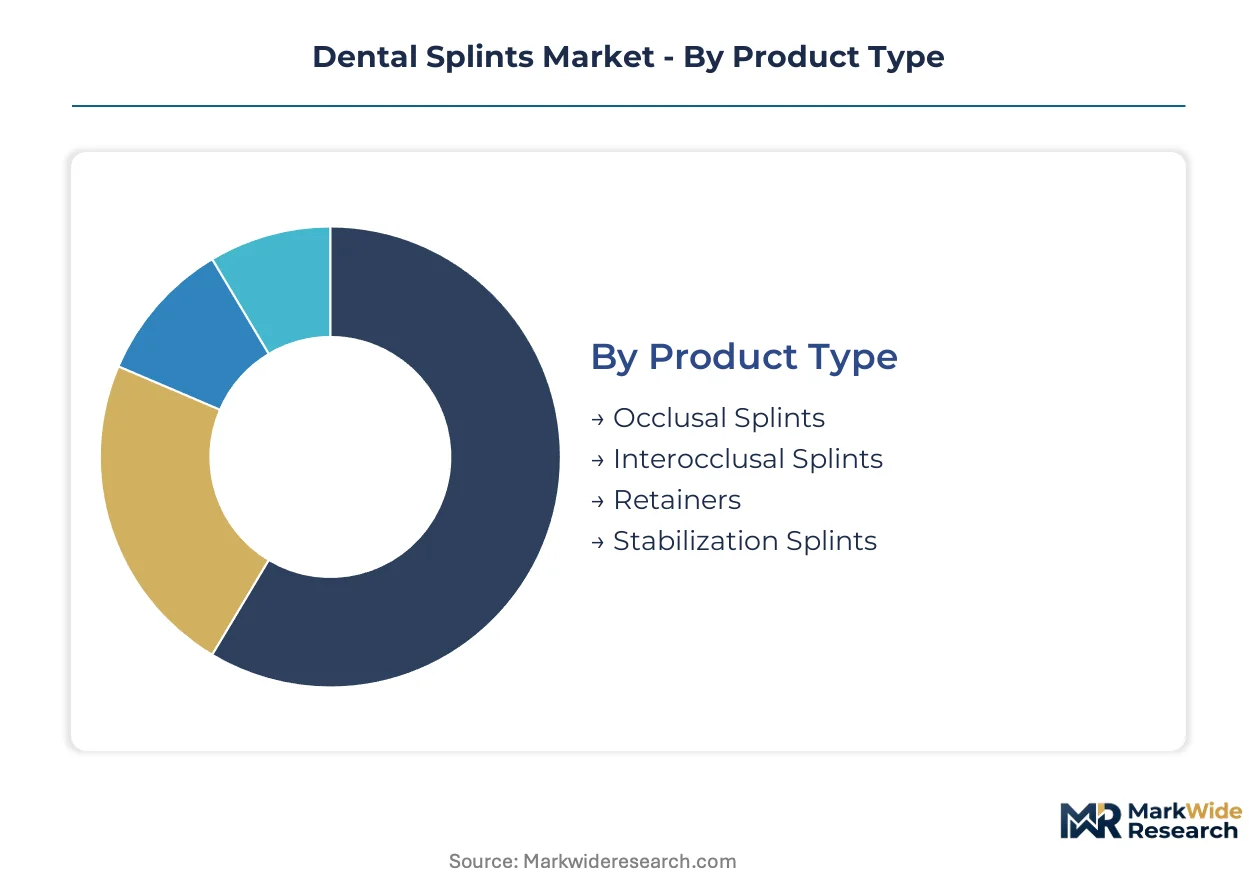
Product differentiation in dental splints hinges on material biocompatibility, fabrication precision, and indication-specific mechanical properties. Segmentation reveals how chairside digital workflows are redistributing value across traditional laboratory and clinic-direct channels.
Product Type:
Mature categories dominate revenue concentration while emerging formats exploit digital fabrication flexibility.
- Occlusal Splints:Fabricated from thermoplastic or acrylic substrates ranging 1.5-4.0 mm thickness, these appliances redistribute masticatory forces across the full dental arch. Demand concentrates in United States dental clinics where FDA 510(k) streamlining accelerates chairside production adoption.
- Interocclusal Splints:Anterior repositioning designs with adjustable ramp mechanisms guide condylar position for temporomandibular joint therapy. Orthodontists in Germany and Switzerland prescribe these for complex disc displacement protocols, though EU MDR documentation burdens constrain smaller laboratory suppliers.
- Retainers:Post-orthodontic appliances prevent relapse through passive mechanical retention.
- Stabilization Splints:Rigid designs immobilize segments following trauma or surgical intervention.
Occlusal Splints retain volume leadership; Interocclusal Splints hold the steepest expansion curve.
Material:
Cost tiers separate injection-moldable polymers from conventional heat-cure systems, with biocompatibility certification driving procurement decisions.
- Thermoplastic:ISO 10993-compliant polyesters and copolymers enable repeatable injection molding with sub-0.1 mm thickness tolerance. Dental clinics in the United States and Japan favor these for same-day fabrication workflows, eliminating laboratory turnaround.
- Acrylic:Heat-cured polymethyl methacrylate systems deliver optical clarity and repairability but expose manufacturers to methyl methacrylate feedstock volatility. European laboratories retain acrylic dominance for complex cantilever designs requiring manual characterization.
- Polycarbonate:High-impact resistance suits athletic mouthguard applications and pediatric indications.
- Silicone:Soft durometer formulations accommodate patients with gingival sensitivity or implant-protected occlusion.
Thermoplastic materials command the premium tier; Acrylic maintains installed-base dominance across legacy laboratory networks.
End User:
Customer type determines whether procurement flows through institutional purchasing or direct clinic fabrication investment.
- Dental Clinics:Solo and group practices deploying intraoral scanners and tabletop mills capture the steepest growth trajectory. Chairside CAD/CAM integration eliminates impression shipping and enables same-day delivery, compressing case economics.
- Dentists:General practitioners without milling capability outsource to commercial laboratories, sustaining traditional workflow volumes.
- Orthodontists:Specialists concentrate demand for complex interocclusal and repositioning designs.
- Hospitals:Oral surgery departments procure stabilization splints for acute trauma and post-surgical protocols.
Dental Clinics are expanding most quickly; Dentists retain the broadest addressable base.
Application:
Volume distribution tracks reimbursement clarity and patient-reported outcome measurement adoption.
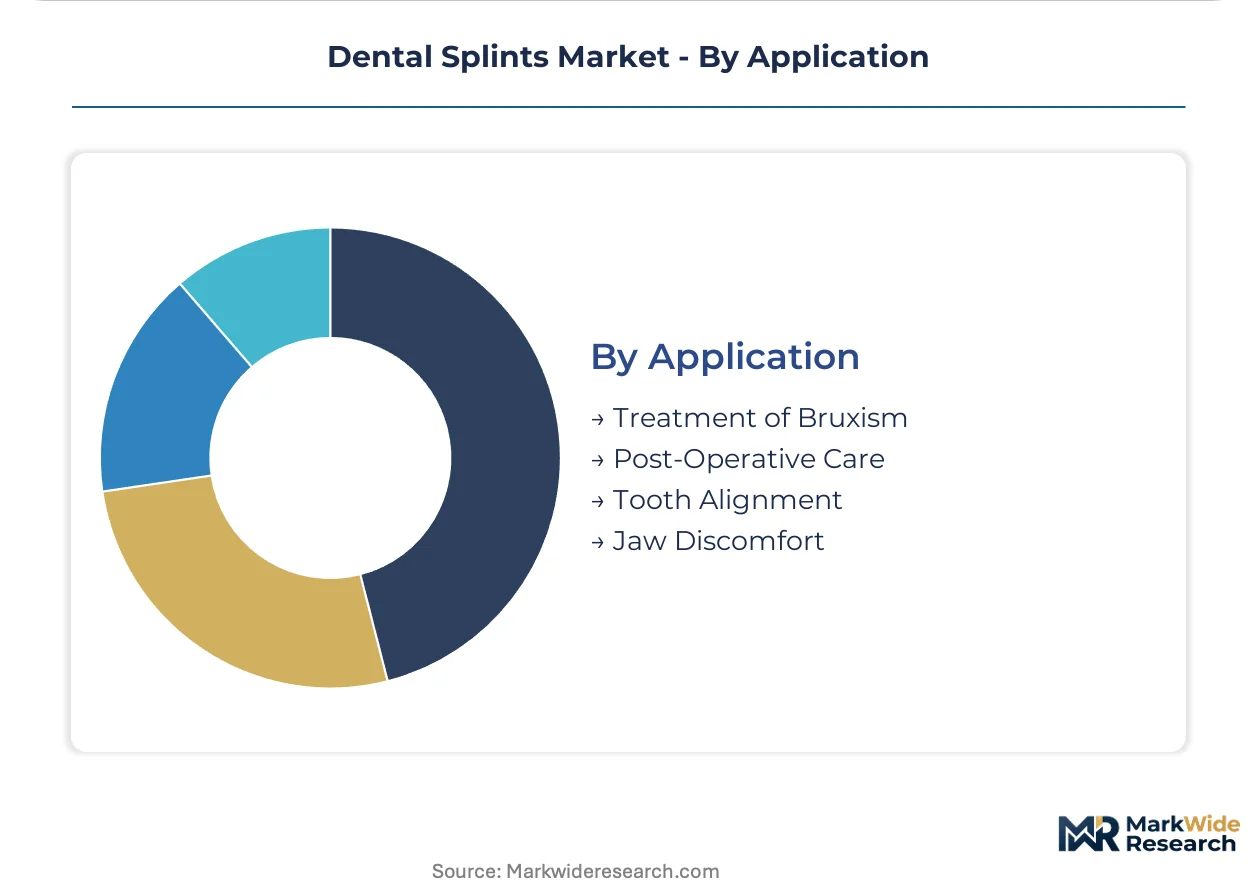
- Treatment of Bruxism:Sleep medicine crossover drives direct-to-consumer subscription pilots in the United States, though diagnostic coding variations complicate insurance predetermination.
- Post-Operative Care:Surgical stabilization protocols generate predictable demand cycles tied to orthognathic and implant procedure volumes.
- Tooth Alignment:Retention-phase compliance monitoring creates recurring revenue potential through replacement scheduling.
- Jaw Discomfort:Temporomandibular disorder management concentrates in United States specialist practices where private payer coding refinements strengthen custom-fabricated splint preference over boil-and-bite alternatives.
Bruxism management spans the widest patient population; Jaw Discomfort applications climb fastest on reimbursement tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist dental clinics in the United States purchase the majority of chairside-fabricated occlusal appliances. Reimbursement clarity for temporomandibular disorder management concentrates procurement authority among insured patient populations.
United States
Private payer coding refinements for temporomandibular disorder management strengthen specialist willingness to prescribe custom-fabricated splints over boil-and-bite alternatives. FDA 510(k) clearance pathways compress production timelines for domestic CAD/CAM manufacturers. Los Angeles and New York metro dental service organizations deploy intraoral scanners at accelerating rates, eliminating traditional laboratory intermediaries.
Germany
Orthodontists in Bavaria and North Rhine-Westphalia prescribe complex interocclusal repositioning designs for disc displacement protocols. EU Medical Device Regulation documentation burdens constrain smaller laboratory suppliers, elevating compliance costs. The Stuttgart industrial corridor hosts precision milling centers serving chairside fabrication networks across Central Europe.
Japan
Dental clinics in Tokyo and Osaka favor ISO 10993-compliant thermoplastic polymers for same-day fabrication workflows. METI standards for medical device quality management govern domestic manufacturing certification. The Nagoya medical technology cluster concentrates injection-molding capacity for occlusal appliance substrates.
Switzerland
Swissmedic oversight of custom-made dental appliances maintains stringent clinical evidence requirements for high-value occlusal designs. Private dental practices in Zurich and Geneva invest in proprietary CAD software ecosystems for in-house splint production. The Basel pharmaceutical-medical device corridor influences biocompatibility testing protocols adopted across Alpine laboratories.
Australia
TGA registration requirements for custom dental devices shape import eligibility for thermoplastic and acrylic substrates. Dental clinics in Sydney and Melbourne adopt chairside milling to reduce laboratory turnaround for bruxism management. The Melbourne biomedical precinct develops additive manufacturing validation protocols for patient-matched appliances.
Dental Splints Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Distribution density and software ecosystem lock-in determine pricing power more than manufacturing scale alone. Two strategic archetypes dominate: vertically integrated milling networks and closed-architecture CAD platform owners. Competitive moves concentrate on geographic expansion of chairside service partnerships and regulatory compliance outsourcing for EU market access.
Among United States-based fabricators, Glidewell Dental represents the scale-driven archetype through captive milling center networks. Dentsply Sirona anchors the proprietary ecosystem tier with software-hardware integration strategies. Henry Schein occupies a position bridging distribution control with clinic-direct material supply, exemplifying channel-density competition.
| Leading Market Players |
|---|
| Glidewell Dental |
| Keystone Industries |
| Dentsply Sirona |
| Ultradent Products |
| Henry Schein |
| 3M |
| 3D Systems |
| Septodont |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Los Angeles-to-Tokyo air freight corridors carry thermoplastic polymer resins and precision-milled occlusal substrates, with fuel surcharge volatility compressing margin buffers for mid-sized dental laboratories while amplifying price differentiation between ISO-certified premium tiers and uncertified economy alternatives.
Pricing Analysis
Cost-plus contracts indexed to methyl methacrylate spot pricing dominate acrylic splint procurement between European laboratories and German chemical suppliers. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared chairside systems from laboratory-fabricated appliances and boil-and-bite retail alternatives. Cost compression in economy tiers is intensifying because Asian injection-molding capacity expansion floods commodity thermoplastic segments. Solo-practice dentists exhibit highest price sensitivity, while dental service organizations prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Methyl methacrylate monomer production concentrates in Germany, China, and Saudi Arabia, with petrochemical feedstock drawing from regional naphtha crackers and propane dehydrogenation facilities. Polymer-grade thermoplastic pellets, CAD/CAM milling burs, and intraoral scanner calibration standards constitute critical input dependencies. Single-source vulnerability pervades proprietary scanner ecosystems that lock clinics into vendor-specific material validation protocols. Distribution runs through dental laboratory networks for custom-fabricated appliances and direct manufacturer-to-clinic channels for chairside production systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through FDA 510(k) clearance and ISO 13485 certification creates prohibitive switching costs for incumbent laboratories and established CAD/CAM platform owners.
For Market Incumbents: Insulate core revenue streams by deepening captive supply of ISO 10993-compliant thermoplastic substrates and securing exclusive chairside service partnerships with expanding dental service organizations in California and Texas. Threat substitution from direct-to-consumer tele-dentistry platforms demands preemptive investment in remote monitoring software companions that extend patient engagement beyond single-transaction splint delivery. For New Entrants and Emerging Players: Vietnamese private dental clinics represent the most penetrable geographic frontier, with chairside milling penetration below regional peers and local laboratory capacity constrained by EU MDR documentation burdens on imported appliances. Target white-space expansion through same-day fabrication service partnerships that eliminate traditional laboratory intermediaries, coupled with subscription-based replacement programs for bruxism management patients. For Investors and Strategic Acquirers: Regional CAD/CAM design boutiques with established FDA 510(k) submission track records and proprietary patient-matched fabrication protocols present optimal acquisition archetypes for platform consolidation plays. Long-term viability hinges on additive manufacturing material validation resolution by FDA draft guidance, with photopolymer biocompatibility certification serving as the critical inflection signal for portfolio reweighting toward 3D-printed appliance specialists.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates domestic manufacturing timelines for CAD/CAM-fabricated occlusal appliances. |
| ISO 13485 Certification Investment | Unlocks European Union market access for custom-made dental device exporters. |
| Chairside Service Partnership | Captures dental clinic volume by eliminating laboratory turnaround delays. |
| Software Companion Development | Enables remote patient monitoring and subscription-based splint replacement revenue. |
| Reimbursement Strategy | Secures private payer coding clarity for temporomandibular disorder management protocols. |
Research Approach
Cross-validation between primary interviews with dental laboratory owners, CAD/CAM design technicians, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, ISO certification registries, and dental school procurement databases. Bottom-up demand modeling triangulates with top-down market sizing across thermoplastic material consumption and intraoral scanner installation data.
Calibration against historical adoption curves for chairside milling technology and reimbursement coding refinements for temporomandibular disorder management shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, material certification tier, end-user channel, and application indication. CAGRs derive from spline-interpolated penetration rates and price elasticity estimates for custom-fabricated versus retail alternatives. Forecast inputs incorporate dental clinic density projections and private payer policy evolution.
Macroeconomic conditions sit as an overlay; deviation in petrochemical feedstock pricing and air freight fuel surcharges would shift the trajectory for acrylic-dependent manufacturers. Forecasts reflect documented assumptions about regulatory timeline resolution and material validation protocols. Cross-checking against dental school curriculum adoption rates for digital workflow training is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Dental Scalers Market
Dental Devices
Global Dental Crowns and Bridges Market
Dental Devices
Dental CAD/CAM Market
Dental Devices
Mexico Dental Devices Market
Dental Devices
Dental Air Polishers Market
Dental Devices
Dental Sealants Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Dental Devices and Consumables Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Irrigation Devices Market